
 Bio-Based Aromatics Market | 2026-2036
Bio-Based Aromatics Market Size, Share, and Industry Trends Forecast 2026-2036
Bio-Based Aromatics Market Outlook
Platform licensing revenue from catalytic pyrolysis technologies is reshaping margin pools away from commodity aromatics trading. BASF SE leverages its integrated Verbund sites to secure feedstock flexibility across phenol and styrene derivatives. Neste anchors European supply through its Singapore and Rotterdam renewable refineries, converting waste oils into bio-based chemical precursors. Braskem specializes in sugarcane-derived aromatics from its Brazilian operations, controlling a vertically integrated path from agricultural feedstock to polymer-grade outputs.
Bio-based aromatics comprise benzene, toluene, xylene (BTX) and substituted derivatives synthesized from renewable feedstocks such as lignin, sugars, or waste biomass rather than petroleum naphtha, typically achieving purity thresholds of 99.5% for polymerization-grade applications. These molecules serve as drop-in replacements in polyethylene terephthalate, polystyrene, phenolic resins, and synthetic rubber formulations. Terephthalic acid dominates value capture due to its irreplaceable role in polyester supply chains, while vanillin extracted through ferulic acid bioconversion commands premium pricing in food-grade and fragrance segments. Pharmaceutical-grade phenol remains the smallest volume category but carries the highest per-kilogram margins, reflecting stringent USP and EP certification requirements.
EPA renewable fuel standards and the EU Green Deal's Fit for 55 framework are tightening carbon intensity thresholds for petrochemical imports, forcing reformulation strategies among coatings and adhesives manufacturers. REACH registration deadlines for novel bio-based substances are creating compliance bottlenecks that favor pre-registered incumbent suppliers with established dossiers. FDA and EMA guidelines on pharmaceutical-grade excipient sourcing are beginning to recognize mass-balance certified bio-aromatics as acceptable alternatives to fossil-derived equivalents. Stakeholders must monitor how the EU AI Act and impending digital product passport requirements will alter traceability costs across multi-tier bio-aromatic supply chains.
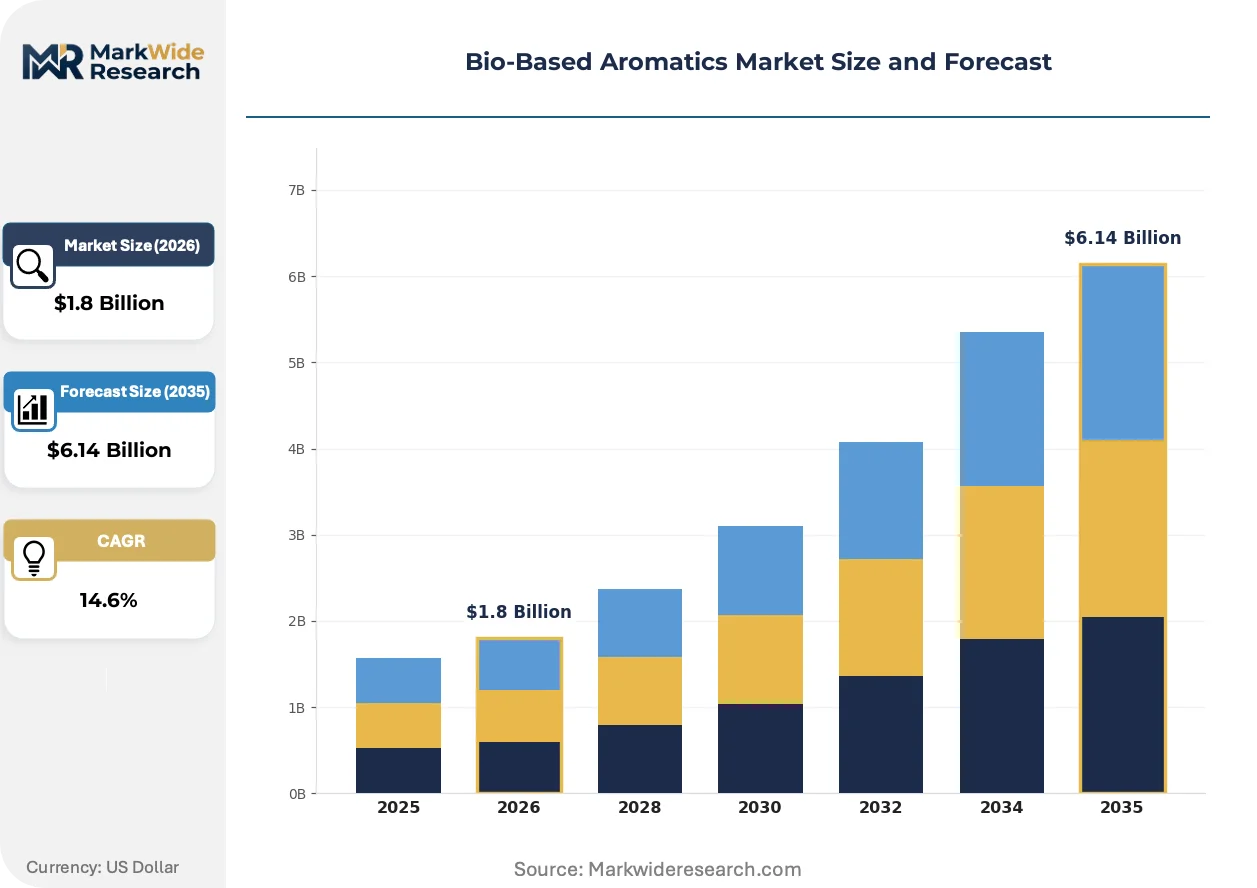
Market Dynamics
Fermentation technology advances are redirecting capital from fossil-based BTX streams toward lignocellulosic conversion platforms, compressing the cost gap between petroleum-derived and bio-based aromatic precursors.
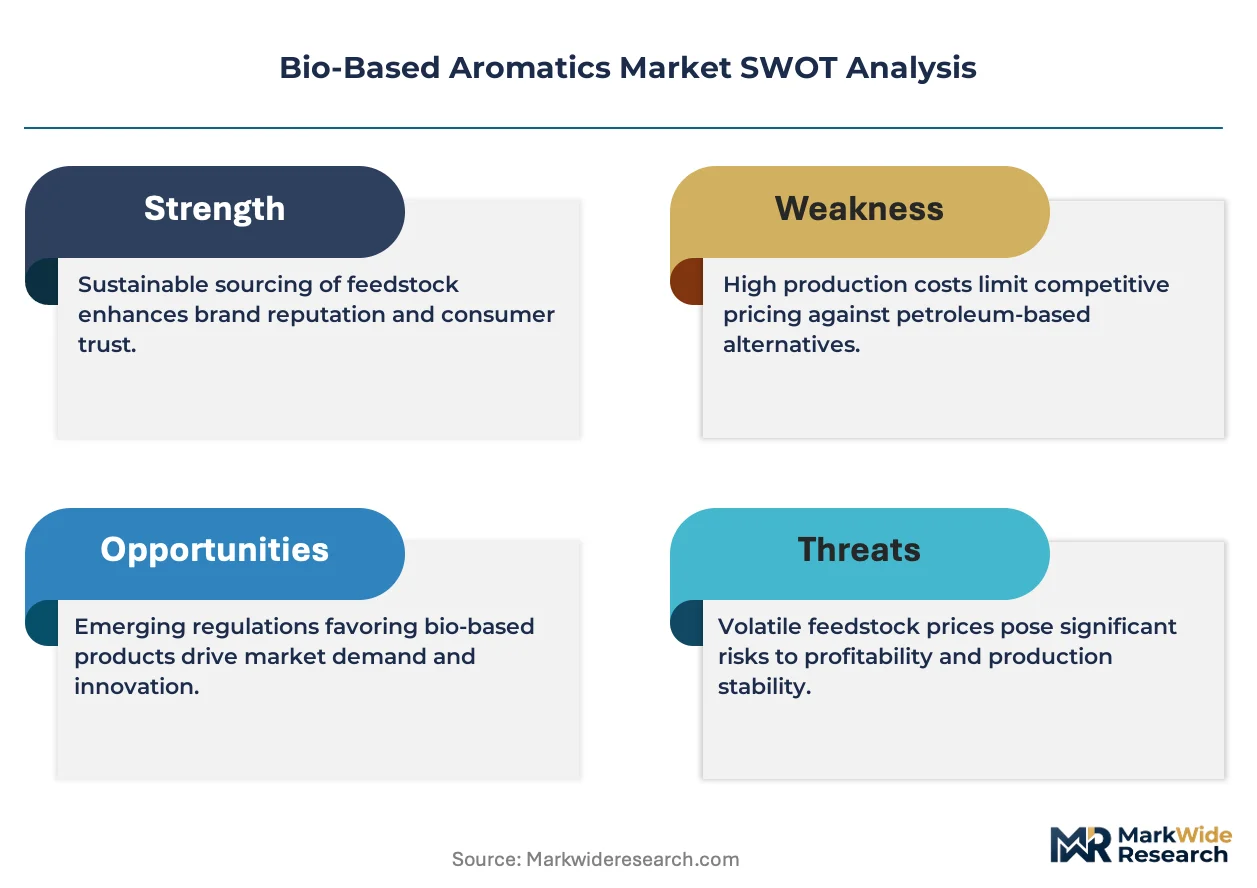
Growth Catalysts
- EU Green Deal Fit for 55 framework:Carbon intensity thresholds for petrochemical imports force coatings and adhesives manufacturers toward bio-based feedstock reformulation.
- Lignin depolymerization:Catalytic pyrolysis platforms unlock aromatic monomers from pulp and paper waste streams at commercial scale.
- Rotterdam biorefinery cluster:Concentrated processing infrastructure near the Netherlands port enables integrated feedstock-to-monomer logistics.
Market Restraints
- Sugar price volatility:Brazilian sucrose feedstock costs fluctuate with ethanol demand and weather patterns, compressing margin predictability for fermentation routes.
- REACH registration bottlenecks:Novel bio-based substance dossiers face extended ECHA review timelines, favoring pre-registered incumbents with established compliance records.
- Petroleum naphtha parity:Crude oil price dips below $70 per barrel erode the competitive position of bio-aromatics in commodity polymer applications.
Strategic Opportunities
- Pharmaceutical-grade phenol:USP and EP certification requirements create defensible margin pools in excipient sourcing for injectable formulations.
- Mass-balance certification:ISCC PLUS and RSB chain-of-custody standards unlock premium positioning in European polyester supply chains.
- Waste oil conversion:Neste's renewable refinery technology adapted for aromatic extraction opens feedstock diversification beyond agricultural sugars.
Industry Challenges
- Fermentation scale-up engineering:Translating pilot-scale titers to industrial bioreactors demands specialized biochemical process expertise in short supply.
- Digital product passport compliance:EU AI Act traceability requirements impose multi-tier supply chain documentation costs on bio-aromatic distributors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bio-Based Aromatics Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $6.14 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Phenol, Terephthalic Acid, Vanillin, Styrene End Use Industry: Plastics, Food & Beverage, Cosmetics, Pharmaceuticals Application: Coatings, Adhesives, Flavors, Fragrances Grade: Industrial Grade, Food Grade, Cosmetic Grade, Pharmaceutical Grade |
| Companies Covered | BASF SE, Chevron Phillips Chemical, Dow Chemical Company, DSM, ExxonMobil Chemical, LG Chem, LyondellBasell Industries, Neste, Braskem, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bio-Based Aromatics Market Strategic Shifts
Catalytic upgrading pathways are converging with synthetic biology to produce polymer-grade aromatics from heterogeneous waste streams, altering where value accumulates in chemical value chains.
Catalytic fast pyrolysis of lignin is hybridizing thermochemical and biotechnological processing routes. Packaging manufacturers in Germany and the Netherlands are piloting these intermediates for PET copolymer production. The technology is hybridizing equipment utilization across existing petroleum refinery infrastructure, allowing retrofitted FCC units to process bio-oil blends without greenfield capital deployment.
REACH registration deadlines for novel bio-based substances are compressing market entry timelines for new suppliers. ECHA's substance evaluation workload has extended dossier approval cycles beyond 24 months in several categories. Specialty chemical distributors with pre-2018 registrations are leveraging this friction to lock in formulation partnerships ahead of compliant competitors.
Mass-balance certification is displacing physical segregation as the dominant chain-of-custody model for brand-owners. Textile and packaging converters in Northern Europe now accept book-and-claim systems for bio-terephthalic acid sourcing. This shift concentrates purchasing decisions among traders with ISCC PLUS accreditation, marginalizing smaller distributors lacking audit infrastructure.
Bio-Based Aromatics Market Segmentation
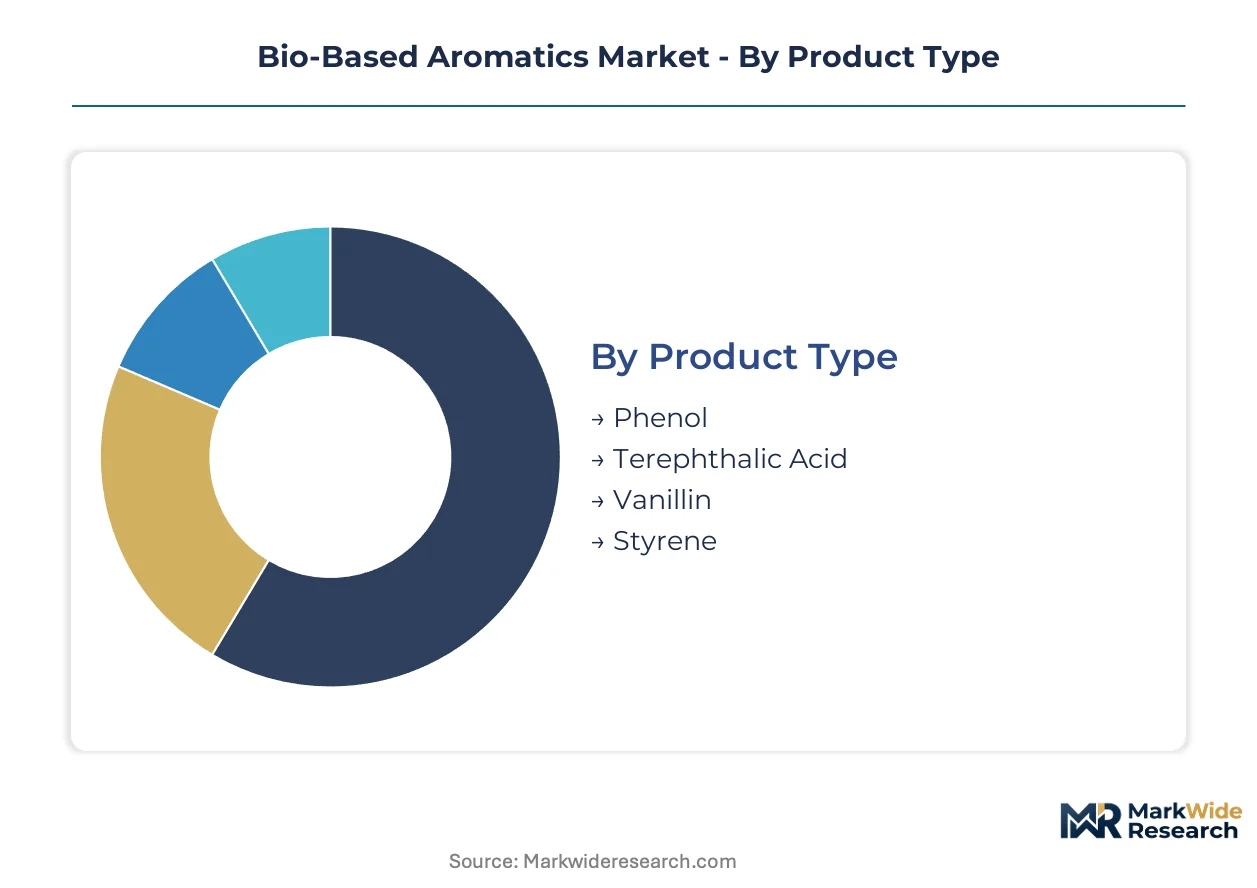
Segmentation in bio-based aromatics reveals divergent margin profiles across purity thresholds and end-use specifications. Cycle times compress from commodity polymer feedstocks to certified pharmaceutical grades, reshaping working capital requirements and inventory strategies for producers.
Product Type:
Terephthalic acid and phenol turn inventory fastest through polyester supply chains, while vanillin and styrene derivatives tie up capital longer due to batch certification and seasonal offtake patterns.
- Terephthalic Acid:Polymer-grade purity at 99.5% enables direct substitution in PET resin production. Demand concentrates in the Netherlands where Rotterdam biorefinery clusters process lignocellulosic feedstock at scale for European packaging converters.
- Phenol:Derived from lignin depolymerization or sugar fermentation routes depending on regional feedstock economics. Pharmaceutical-grade specifications command premium positioning in injectable formulation excipients under FDA and EMA sourcing guidelines.
- Vanillin:Ferulic acid bioconversion yields food-grade and fragrance-grade outputs with extended batch release timelines.
- Styrene:Bio-based routes remain constrained by fermentation scale-up engineering bottlenecks and petroleum naphtha parity pressures.
Terephthalic acid dominates installed base. Phenol is where expansion concentrates.
End Use Industry:
Plastics and food applications absorb volume at standard margins, while pharmaceuticals and cosmetics extract value through certification premiums and formulation partnerships.
- Plastics:PET copolymer and polystyrene manufacturers in Germany anchor offtake under EU Green Deal carbon intensity mandates. Mass-balance certification through ISCC PLUS unlocks premium positioning in Northern European converter networks.
- Pharmaceuticals:USP and EP certification requirements for injectable-grade phenol create defensible margin pools. EMA guidelines on excipient sourcing now recognize mass-balance certified bio-aromatics as acceptable alternatives to fossil-derived equivalents.
- Food & Beverage:Vanillin extraction from ferulic acid serves flavor formulation with batch-specific purity documentation.
- Cosmetics:Fragrance-grade bio-aromatics require REACH registration dossiers that favor pre-registered incumbent suppliers.
Plastics commands the largest volume position. Pharmaceuticals delivers the steepest expansion trajectory.
Application:
Coatings and adhesives reformulation cycles accelerate under tightening regulatory thresholds, while flavors and fragrances extend development timelines for sensory validation.
- Coatings:Industrial formulations incorporating bio-terephthalic acid reduce carbon intensity scores for automotive and construction OEMs. EU Green Deal Fit for 55 framework forces manufacturers toward feedstock substitution with documented chain-of-custody.
- Adhesives:Pressure-sensitive and structural adhesive producers in Germany pilot bio-based aromatic precursors to meet Scope 3 reduction targets. REACH compliance for novel bio-based substances extends formulation lock-in periods with established distributors.
- Flavors:Vanillin applications demand food-grade certification with extended analytical release protocols.
- Fragrances:Cosmetic-grade bio-aromatics require sensory panel validation and stability testing that compresses annual formulation turnover.
Coatings holds the broadest installed base. Adhesives is gaining share fastest.
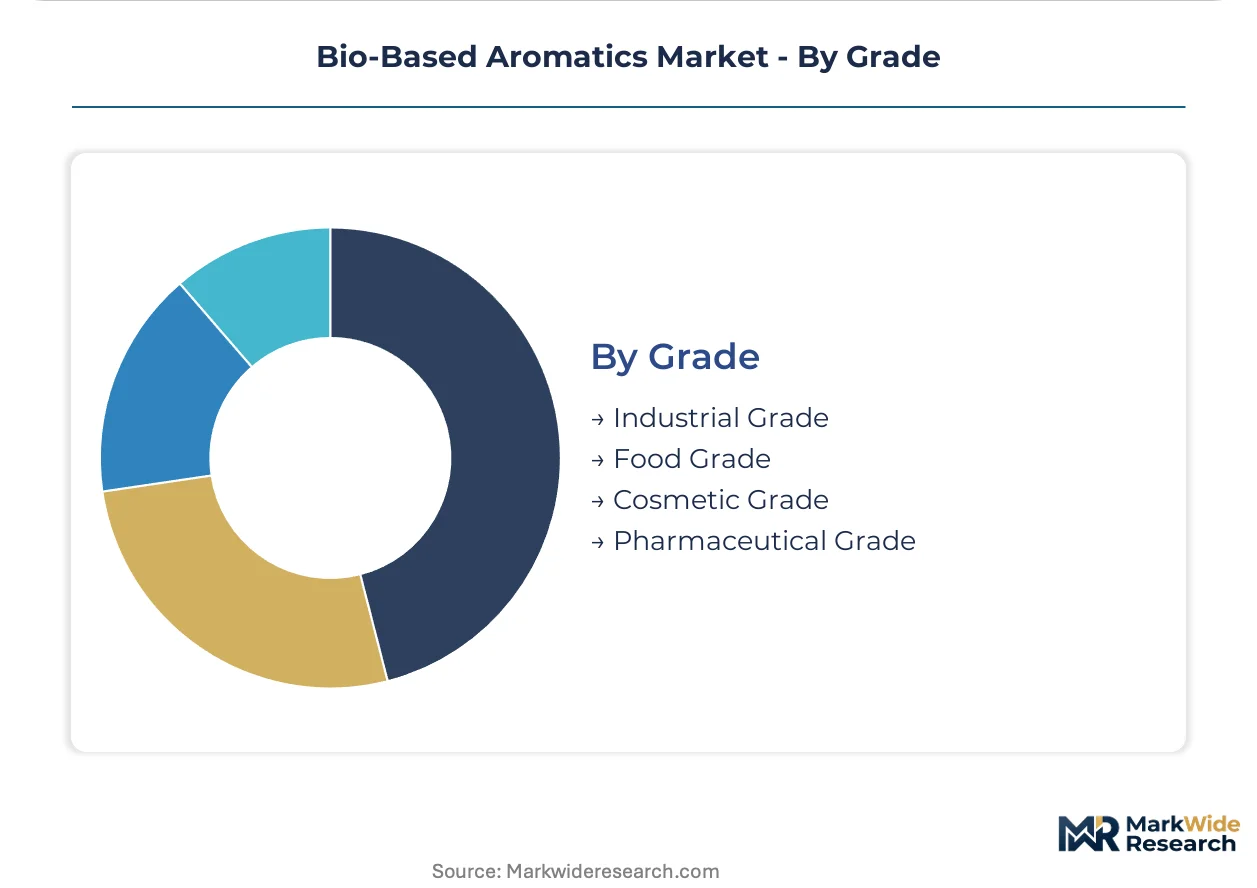
Grade:
Industrial and food grades flow through standardized specifications, while pharmaceutical and cosmetic grades accumulate value through audit infrastructure and documentation intensity.
- Pharmaceutical Grade:USP and EP certification for injectable phenol demands dedicated production suites and analytical release protocols. FDA sourcing guidelines create compliance moats that marginalize uncertified competitors in excipient supply chains.
- Industrial Grade:Polymer-grade terephthalic acid at 99.5% purity serves commodity PET production with volume-based pricing. Rotterdam biorefinery clusters enable integrated feedstock-to-monomer logistics that compress delivered costs for European converters.
- Food Grade:Vanillin specifications require FSSAI and EFSA compliance for regional market access.
- Cosmetic Grade:Fragrance applications demand REACH dossier completeness and stability documentation.
Industrial grade dominates throughput volume. Pharmaceutical grade is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany and the Netherlands consume bio-based aromatics primarily for polymer-grade terephthalic acid under EU Green Deal mandates, while Brazil and the United States deploy fermentation routes for sugarcane and corn stover feedstocks respectively.
Germany
Polymer manufacturers in North Rhine-Westphalia and Bavaria anchor offtake agreements for bio-terephthalic acid. REACH registration deadlines for novel bio-based substances favor pre-registered incumbents with established dossiers. BASF SE leverages its integrated Verbund sites in Ludwigshafen to secure feedstock flexibility across phenol and styrene derivatives.
Netherlands
Rotterdam biorefinery clusters process lignocellulosic feedstock at scale for European packaging converters. EU Green Deal Fit for 55 carbon intensity thresholds force coatings and adhesives manufacturers toward feedstock reformulation. Neste anchors European supply through its Rotterdam renewable refinery, converting waste oils into bio-based chemical precursors.
Brazil
Sugarcane-derived aromatics from São Paulo state operations serve polymer-grade outputs under fluctuating sucrose feedstock economics. ANVISA guidelines on pharmaceutical-grade excipient sourcing create compliance frameworks for regional producers. Braskem controls a vertically integrated path from agricultural feedstock to aromatic monomers.
United States
EPA renewable fuel standards tighten carbon intensity thresholds for petrochemical imports, forcing reformulation strategies among coatings manufacturers. FDA guidelines on pharmaceutical-grade excipient sourcing recognize mass-balance certified bio-aromatics as acceptable alternatives. Fermentation technology advances redirect capital from fossil-based BTX streams toward lignocellulosic conversion platforms in the Midwest corn belt.
China
Dual carbon goals accelerate investment in catalytic pyrolysis platforms for lignin depolymerization. NMPA standards for pharmaceutical-grade phenol create certification requirements for injectable formulation excipients. Yangtze River Delta chemical clusters pilot retrofitted FCC units processing bio-oil blends without greenfield capital deployment.
Bio-Based Aromatics Market Competitive Environment
Capability concentration sits with integrated petrochemical conglomerates possessing established REACH dossiers and mass-balance certification infrastructure; scale advantage sits with agricultural feedstock controllers with captive sugarcane or lignocellulosic supply chains. The market structures around three archetypes: European integrated chemical majors with Verbund site flexibility, Brazilian agricultural processors with vertical feedstock control, and Nordic renewable refinery operators with waste oil conversion technology. Dominant competitive moves include strategic offtake partnerships with packaging converters under EU Green Deal compliance deadlines and technology licensing for catalytic pyrolysis platforms.
Among European integrated majors, BASF SE exemplifies the capability-heavy archetype through its Ludwigshafen Verbund complex, while Neste represents the renewable refinery model with Rotterdam and Singapore operations. Braskem occupies the agricultural-integrated position, anchoring South American supply from Brazilian sugarcane feedstock bases.
| Leading Market Players |
|---|
| BASF SE |
| Chevron Phillips Chemical |
| Dow Chemical Company |
| DSM |
| ExxonMobil Chemical |
| LG Chem |
| LyondellBasell Industries |
| Neste |
| Braskem |
| Others |
Value Chain & Pricing Dynamics
Brazilian sugarcane concentration and Rotterdam biorefinery clusters anchor upstream feedstock supply, concentrating margin capture with processors possessing integrated agricultural control or waste-oil conversion technology. Long-term offtake contracts for polymer-grade terephthalic acid now dominate European procurement, while spot markets for vanillin and pharmaceutical-grade phenol retain premium volatility.
Pricing Analysis
Long-term offtake agreements structure the dominant pricing model for bio-terephthalic acid, with German packaging converters locking in multi-year supply under EU Green Deal compliance deadlines. Price differentiation rests on ISCC PLUS mass-balance certification tiers and polymer-grade purity thresholds. Cost compression in fermentation-derived styrene is intensifying because petroleum naphtha parity pressures erode margin buffers. Commodity polymer manufacturers exhibit highest price sensitivity, while pharmaceutical formulators accept premium positioning for USP-certified phenol.
Supply Chain Analysis
EU dual-use export controls on catalytic pyrolysis technology limit equipment flows to Chinese biorefinery developers, constraining technology diffusion. Supply concentrates in Brazil for sugarcane-derived aromatics, the Netherlands for waste-oil conversion platforms, and Germany for integrated Verbund processing. Raw material dependencies include lignocellulosic feedstock, waste oils, and sucrose streams. Single-source vulnerability sits with fermentation enzyme suppliers. Distribution runs through Rotterdam port infrastructure for European converter networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized biochemical process engineering for industrial-scale fermentation represents the critical capability gap constraining new supply entry, with pilot-to-production translation expertise commanding scarcity rents.
For Market Incumbents: Entrench position through backward integration into lignocellulosic feedstock supply and accelerated REACH dossier expansion ahead of ECHA evaluation bottlenecks. Lock in formulation partnerships with coatings manufacturers facing Fit for 55 carbon intensity mandates. Prioritize mass-balance certification infrastructure to capture premium positioning in Northern European polyester supply chains. For New Entrants and Emerging Players: Establish a beachhead in pharmaceutical-grade phenol where USP certification requirements create compliance moats against commodity competitors. Target injectable formulation excipient supply chains under FDA and EMA sourcing guideline recognition. Deploy licensing models for catalytic pyrolysis platforms rather than greenfield capital deployment. For Investors and Strategic Acquirers: Capital is best deployed toward agricultural-integrated processors with captive sugarcane or lignocellulosic supply chains and established fermentation scale-up engineering teams. Long-term viability hinges on feedstock flexibility across multiple renewable inputs. Watch for inflection in EU AI Act digital product passport implementation costs across multi-tier supply chains.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feedstock Supply | Captive lignocellulosic or sugarcane supply secures margin control against commodity volatility. |
| Mass-Balance Certification Investment | ISCC PLUS accreditation unlocks premium positioning in EU Green Deal-compliant converter networks. |
| Fermentation Scale-Up Engineering | Pilot-to-industrial bioreactor translation capability remains the binding constraint on new supply. |
| Catalytic Pyrolysis Technology Licensing | Platform licensing revenue reshapes margin pools away from commodity aromatics trading. |
| Long-Term Offtake Agreement Structuring | Multi-year contracts with German polymer manufacturers lock in volume under REACH compliance deadlines. |
Study Parameters
Initial hypotheses were tested against primary input from biorefinery plant managers, downstream polymer procurement leads, catalytic pyrolysis technology licensors, and REACH compliance consultants, then refined through secondary validation. Sources included ECHA registration dossiers, customs trade data for bio-aromatic flows, SEC filings from integrated chemical majors, and biorefinery project development databases. Bottom-up capacity modeling and top-down demand segmentation were triangulated to constrain estimate ranges.
Demand-supply-balance framing anchored the analytical approach across the analysis window, with segmentation by product type, end-use industry, application, and grade tier. CAGRs were derived from installed capacity expansion timelines and offtake agreement visibility. Key inputs included EU Green Deal implementation pace, fermentation titer improvement curves, and ECHA evaluation cycle durations for novel bio-based substances.
Sensitivities concentrate around crude oil price volatility, REACH registration timeline extensions, and EU AI Act traceability cost implementation. Forecasts reflect assumptions on technology licensing uptake and biorefinery cluster development pace. Material shifts in petroleum naphtha parity or ECHA regulatory enforcement would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
13X Molecular Sieve Activated Powder Market
Specialty Chemicals
Methyl Salicylate Market
Specialty Chemicals
Fatty Alcohol Alkoxylates Market
Specialty Chemicals
Global Immersion Oil Market
Specialty Chemicals
Polycarboxylate Ethers (Pces) Market
Specialty Chemicals
Shikimic Acid Market
Specialty Chemicals
Carbocernaite Market
Specialty Chemicals
Europe Squalene Market
Specialty Chemicals
Calcium D-Pantothenate Market
Specialty Chemicals
LAMEA Metal Biocides Market
Specialty Chemicals
CMIT/MIT Market
Specialty Chemicals
Perfluoropolyether (PFPE) Market
Specialty Chemicals
Bio-Based Phenol Market
Specialty Chemicals
Multimodal Chromatography Columns Market
Specialty Chemicals
Vulcanization Accelerators Market
Specialty Chemicals
Cellulose Esters and Ethers Market