
 Wood Plastic Composite (WPC) Market | 2026-2036
Wood Plastic Composite (WPC) Market Size, Share, and Industry Trends Forecast 2026-2036
Wood Plastic Composite (WPC) Market Intelligence
Expertise in polymer extrusion and recycled material science is redrawing the boundaries of WPC product performance and aesthetics. Trex Company Inc. specializes in manufacturing decking from a high percentage of recycled materials. The AZEK Company Inc. differentiates its products through advanced capping technologies that enhance durability and stain resistance. UFP Industries, Inc. leverages its extensive distribution network to supply WPC products to a diverse base of construction and industrial customers.
Wood Plastic Composites are hybrid materials produced by thoroughly mixing ground wood particles with heated thermoplastic resins, which are then extruded into a desired shape. This process yields products with superior moisture resistance and durability compared to traditional lumber. The primary commercial purpose is to provide a long-lasting, low-maintenance alternative for applications historically reliant on wood. Decking remains the dominant product type, driven by strong demand in residential construction. Polyethylene-based formulations are standard, offering manufacturers an effective balance of cost and performance.
Regulatory frameworks significantly shape the WPC landscape, including the US EPA's guidelines on recycled content and the EU's CE marking requirements for construction products. In China, GB standards dictate material safety and performance criteria for composites. These rules govern material sourcing, product testing, and market access for manufacturers. The ability to secure consistent streams of high-quality recycled plastic and wood fiber feedstock will be critical for producers to manage costs and maintain product quality.
Market Dynamics
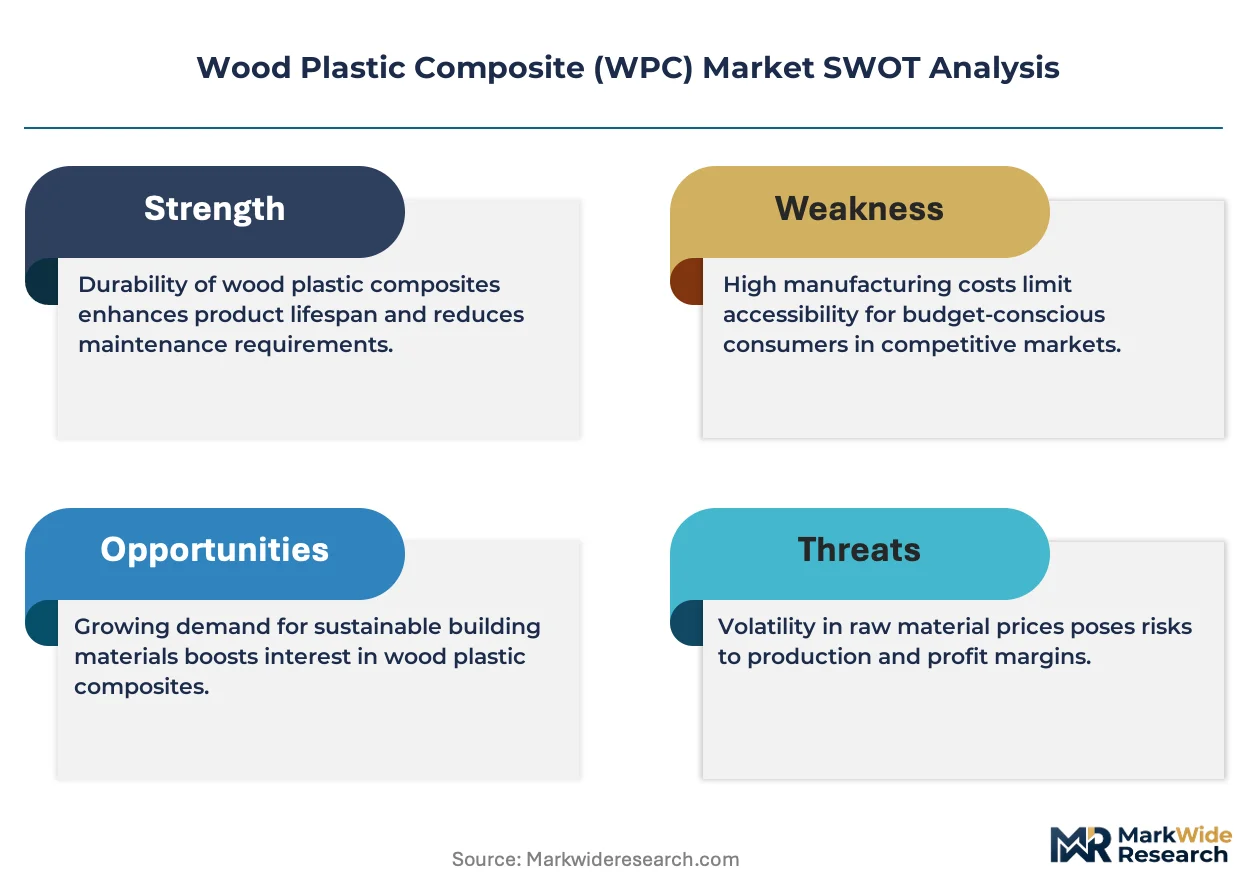
The market's central dynamic is the tension between the push for circularity, driven by regulations like the EU Green Deal, and the operational difficulty of securing consistent, high-quality recycled feedstock, which is essential for maintaining product performance and managing production costs.
Growth Catalysts
- Regulatory Frameworks:The EU Green Deal and similar policies promoting circular economy principles and recycled content in construction materials are creating structural demand for WPC products across member states.
- Residential Construction Demand:Strong activity in the United States residential sector, especially for renovation and remodeling, fuels demand for low-maintenance, durable materials for decking, fencing, and siding applications.
- Material Science Advances:Innovations in polymer extrusion and additives are enhancing the aesthetic qualities and performance characteristics of WPC, including better color retention and scratch resistance, expanding its appeal.
Market Restraints
- Feedstock Volatility:The WPC industry faces significant price and quality fluctuations in its primary raw materials, recycled plastics and wood fibers, which can impact manufacturing costs and product consistency.
- Structural Limitations:WPC materials have lower stiffness and strength compared to structural lumber or metals, limiting their use in primary load-bearing applications and confining them to non-structural or semi-structural roles.
- Material Substitution:Competition from alternative decking and siding materials, including all-PVC composites, fiber cement, and aluminum products, presents a persistent threat, particularly in premium and specialized segments.
Strategic Opportunities
- Geographic Expansion:Underpenetrated markets in Southeast Asia and Latin America, where urbanization and rising incomes are driving new construction, offer significant growth potential for WPC manufacturers.
- New Product Applications:Development of WPC for interior applications such as wall paneling and flooring, or for industrial uses like pallets, opens new revenue streams beyond the core decking market.
- Public Infrastructure Projects:Government specifications favoring materials with high recycled content for public works like boardwalks, park benches, and noise barriers create a stable, large-volume demand channel.
Industry Challenges
- Reverse Logistics Complexity:Establishing efficient, large-scale reverse logistics networks to collect, sort, and process post-consumer plastic and wood waste remains a major operational hurdle for feedstock security.
- Standardization Gaps:A lack of globally harmonized performance standards, with differing requirements between the EU's CE marking and China's GB standards, creates compliance burdens and complicates international trade.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wood Plastic Composite (WPC) Market |
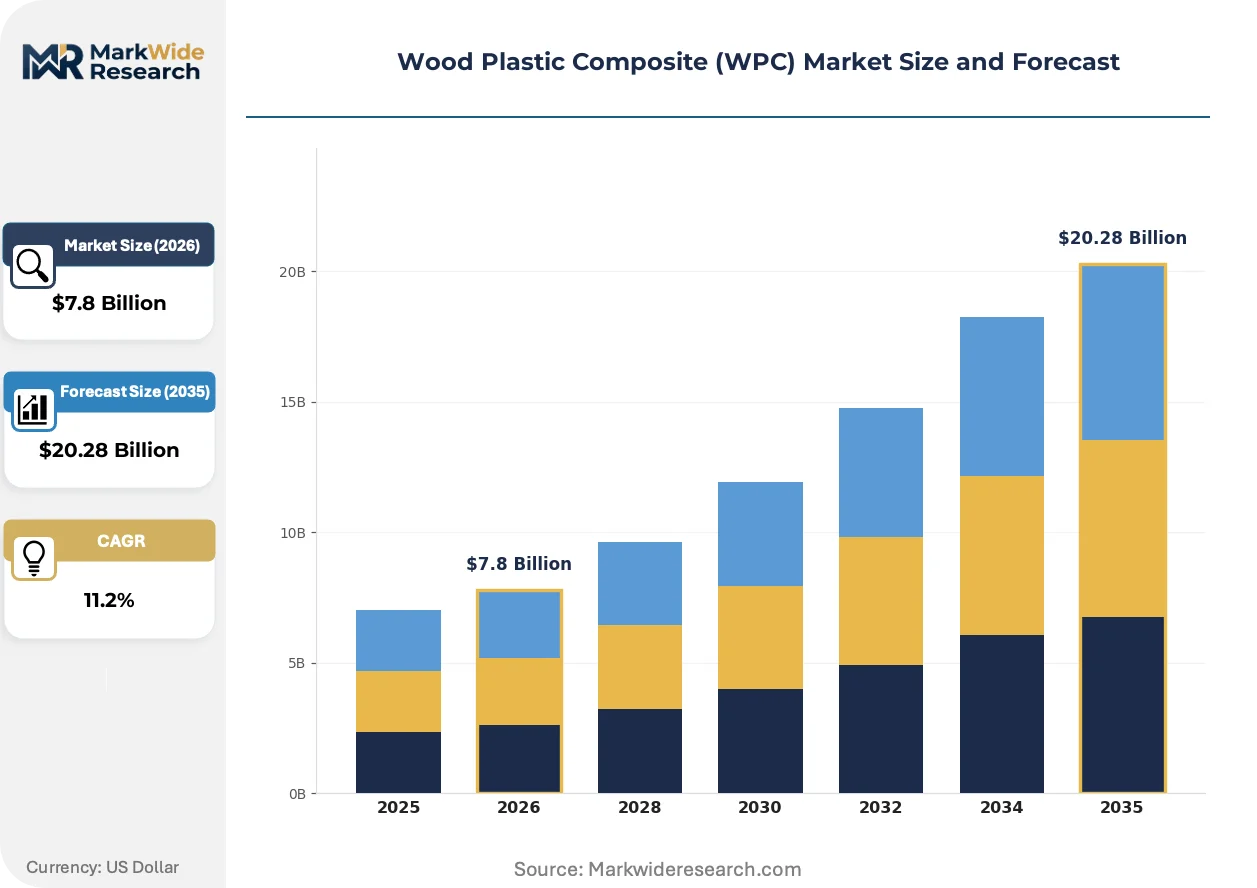
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $20.28 Billion |
| CAGR (2026 – 2036) | 11.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Decking, Fencing, Furniture, Flooring, Automotive Components, Packaging Material Composition: Polyethylene, Polyvinyl Chloride, Polypropylene, Wood Fiber, Rice Husk, Bamboo Fiber Application: Residential Construction, Commercial Construction, Outdoor Landscaping, Marine Structures, Recreational Parks, Agricultural Uses End User: Construction Contractors, Furniture Manufacturers, Vehicle Fabricators, Packaging Companies, Landscape Designers, Agricultural Equipment Makers |
| Companies Covered | Advanced Environmental Recycling Technologies, Oldcastle APG (CRH), Trex Company Inc., Metsä Wood, BASF, The AZEK Company Inc., Fiberon (Fortune Brands Innovations), CertainTeed, UFP Industries, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wood Plastic Composite (WPC) Market Strategic Shifts & Innovations
Innovation in material science is converging with circular economy mandates to redefine the performance and application scope of wood plastic composites. This is pushing WPC beyond its origins as a basic lumber substitute into higher-value, aesthetically demanding product categories.
Co-extrusion capping technology involves applying a durable, protective outer layer over the WPC core during manufacturing. High-end residential and commercial construction segments are adopting this technology for superior stain, fade, and scratch resistance. This advanced production method is supplanting older, uncapped composite products in premium market tiers due to its enhanced longevity and appearance.
China's "dual carbon goals" and associated GB standards for building materials are creating a significant regulatory pull. These national policies incentivize the use of materials with high recycled content and lower embodied energy, directly benefiting WPC production and specification in new projects. The commercial construction segment in major Chinese cities is most affected, with developers increasingly specifying WPC to meet green building certifications.
A demand-side shift is evident as contractors favor pre-assembled WPC systems for railings, fencing, and cladding over purchasing individual boards. This change disrupts the traditional distribution model focused on component sales through lumberyards, moving toward direct-to-installer kits. This trend is most prominent in the North American new home construction market, where it helps reduce on-site labor costs and accelerates project timelines.
Wood Plastic Composite (WPC) Market Segmentation
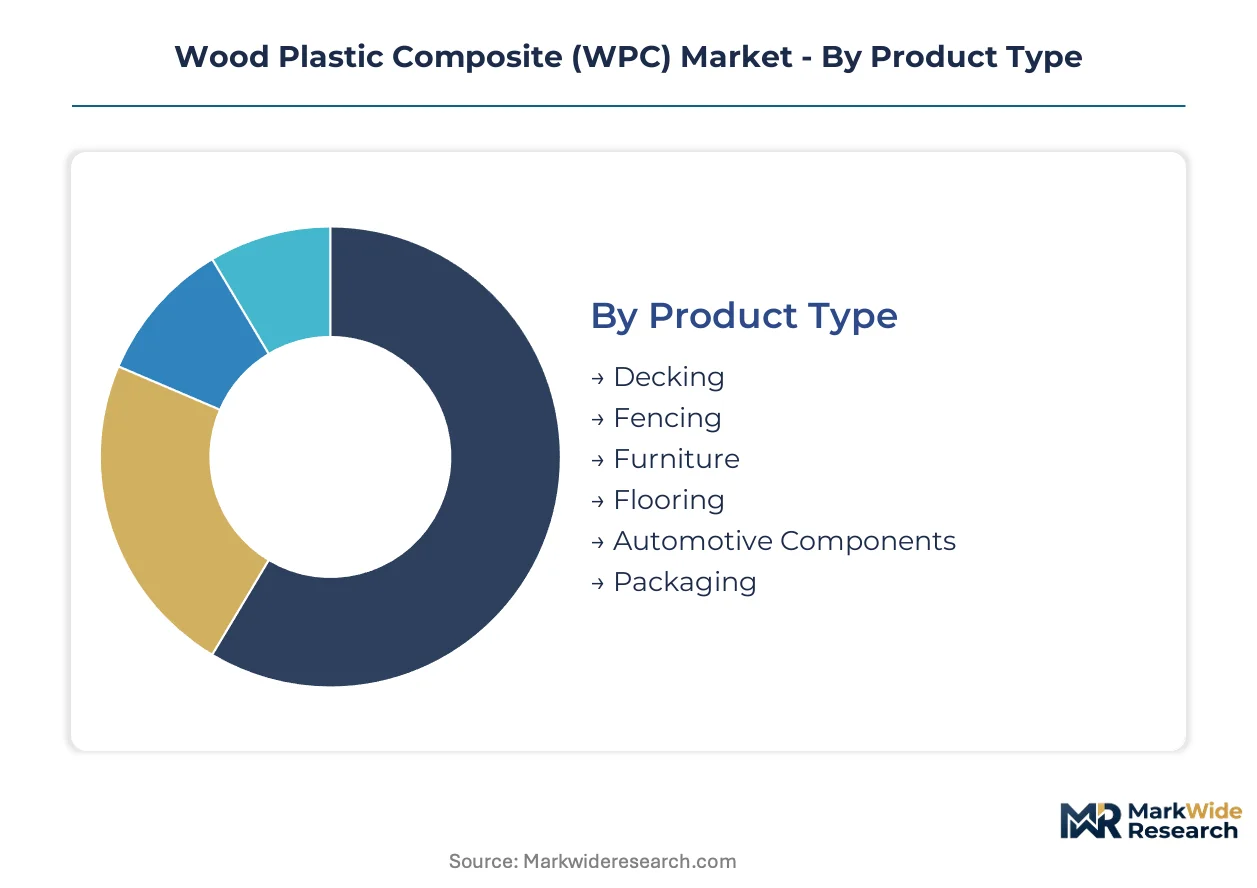
The Wood Plastic Composite market's segmentation provides a structured view of its diverse product offerings and varied end-use applications. Understanding these distinct segments allows manufacturers to tailor material properties and distribution strategies effectively.
Product Type:
The Wood Plastic Composite market's product diversity reflects varying regional adoption rates, with some segments primarily serving domestic markets while others target export opportunities.
- Decking:This segment comprises hybrid materials produced by mixing ground wood particles with heated thermoplastic resins. Demand concentrates in residential construction across the United States, driven by homeowners seeking durable, low-maintenance outdoor surfaces.
- Fencing:WPC fencing products offer superior moisture resistance and longevity compared to traditional wood, extruded into various profiles for perimeter enclosures. Residential and commercial developments in Europe increasingly specify WPC fencing to meet sustainability targets and reduce long-term upkeep.
- Furniture:WPC is utilized for outdoor and indoor furniture components, valued for its weather resistance.
- Flooring:WPC flooring solutions offer durable and water-resistant options for both residential and commercial interiors.
- Automotive Components:Automotive manufacturers incorporate WPC for interior panels and trim, leveraging its lightweight and recyclable properties.
- Packaging:WPC is used in specialized packaging solutions, providing rigidity and environmental benefits over virgin plastics.
Decking holds the largest share; momentum sits with Fencing.
Material Composition:
Material composition segments differentiate WPC products primarily based on cost-performance profiles, influencing their suitability for various applications.
- Polyethylene:Polyethylene-based formulations are standard in WPC production, offering an effective balance of cost and performance. This resin type is widely used in decking applications, particularly in North America, due to its processability and material stability.
- Wood Fiber:Ground wood particles serve as the primary natural filler, providing structural integrity and a wood-like aesthetic to composite products. Consistent streams of high-quality wood fiber feedstock are critical for maintaining product quality and managing production costs across all WPC segments.
- Polyvinyl Chloride:PVC composites provide enhanced rigidity and fire resistance, suitable for specific building codes.
- Polypropylene:Polypropylene offers good mechanical properties and heat resistance, expanding WPC's utility in industrial applications.
- Rice Husk:Rice husk acts as a sustainable alternative fiber source, reducing reliance on traditional wood.
- Bamboo Fiber:Bamboo fiber enhances the strength and appearance of WPC, catering to premium product lines.
Polyethylene formulations dominate current production; Polypropylene formulations are rapidly gaining market traction.
Application:
Application segments delineate primary consumption volumes, indicating where WPC materials achieve their highest utility and market penetration.
- Residential Construction:This segment encompasses new home builds and renovation projects, primarily utilizing WPC for decking, fencing, and siding. Strong activity in the United States residential sector fuels demand for low-maintenance, durable materials.
- Commercial Construction:Commercial projects incorporate WPC for facades, public area furniture, and non-structural elements in office buildings and retail spaces. Developers in major Chinese cities increasingly specify WPC to meet green building certifications and GB standards.
- Outdoor Landscaping:WPC is used for garden borders, planters, and decorative elements in public and private green spaces.
- Marine Structures:WPC finds application in docks, marinas, and boardwalks due to its superior moisture resistance.
- Recreational Parks:Park benches, playground components, and signage utilize WPC for durability and weather resistance.
- Agricultural Uses:WPC is employed in agricultural fencing and structural components for its longevity in outdoor environments.
Residential Construction commands the largest volume; Commercial Construction is expanding most quickly.
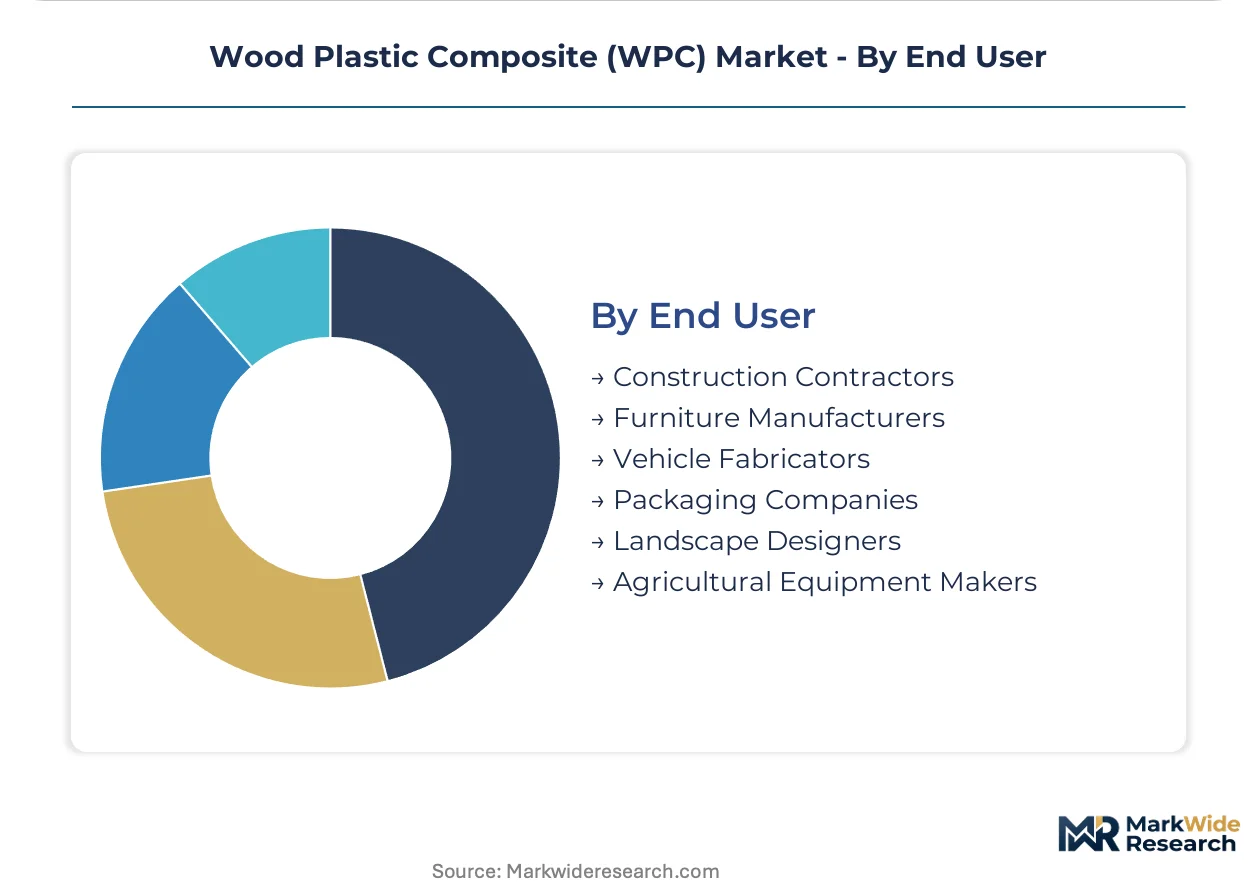
End User:
End-user categories highlight distinct customer types, each with specific procurement needs and product requirements for WPC materials.
- Construction Contractors:These professionals purchase WPC for installation in residential and commercial projects, often favoring pre-assembled systems. North American new home construction markets increasingly rely on WPC kits to reduce on-site labor costs.
- Furniture Manufacturers:Manufacturers integrate WPC components into outdoor and indoor furniture lines, valuing the material's durability and aesthetic versatility. This user group seeks consistent material quality and specific aesthetic finishes.
- Vehicle Fabricators:Fabricators utilize WPC for interior and exterior components, contributing to lighter and more sustainable vehicle designs.
- Packaging Companies:These companies use WPC for specialized, durable packaging solutions for various industrial goods.
- Landscape Designers:Designers specify WPC for outdoor projects, including decking, fencing, and decorative features.
- Agricultural Equipment Makers:Makers incorporate WPC into equipment requiring weather-resistant and robust materials.
Construction Contractors represent the largest purchasing group; Landscape Designers are demonstrating the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US Environmental Protection Agency's (EPA) guidelines on recycled content significantly influence the Wood Plastic Composite market. This regulatory environment, combined with strong residential demand, drives material innovation and adoption across key global regions. Manufacturers continuously adapt to diverse local market dynamics and policy frameworks.
United States
Residential construction demand fuels WPC market expansion in the United States, particularly for decking and fencing. The US EPA's guidelines on recycled content encourage manufacturers to integrate sustainable materials into their product lines. Major building material suppliers in states like Florida and California increasingly stock WPC products for their durability and low maintenance appeal.
China
China's "dual carbon goals" and stringent GB standards for building materials significantly propel WPC market growth. These national policies incentivize the use of high recycled content materials in new construction projects. Commercial construction in major cities like Shanghai and Beijing actively specifies WPC to meet green building certifications.
Germany
The EU Green Deal, emphasizing circular economy principles, creates substantial demand for WPC products across Germany. This regulatory push promotes the adoption of sustainable construction materials with recycled content. Manufacturers in industrial regions such as North Rhine-Westphalia are developing advanced WPC formulations for both public infrastructure and residential applications.
India
Urbanization and rising incomes in India present significant growth potential for WPC manufacturers in residential and commercial segments. The Bureau of Indian Standards (BIS) is developing performance criteria for composite building materials, influencing local market specifications. Construction hubs like Mumbai and Bengaluru are witnessing increased WPC usage for flooring and outdoor landscaping projects.
Brazil
Underpenetrated markets in Brazil offer substantial opportunities for WPC expansion, driven by new construction and renovation activities. National building codes increasingly favor durable and moisture-resistant materials for outdoor applications, benefiting WPC. Developers in cities such as São Paulo and Rio de Janeiro are exploring WPC for decking and facade elements in large-scale residential complexes.
Wood Plastic Composite (WPC) Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier within the Wood Plastic Composite market. The industry structure features a mix of large diversified material companies and focused WPC manufacturers. Strategic archetypes include raw material processors, specialized product innovators, and broad-line distributors. Dominant competitive moves involve capacity expansion and strategic partnerships for feedstock security.
Product innovators such as Trex Company Inc. exemplify expertise in manufacturing decking from a high percentage of recycled materials. The AZEK Company Inc. occupies a position among firms differentiating products through advanced capping technologies that enhance durability and stain resistance. UFP Industries, Inc. represents a player leveraging an extensive distribution network to supply WPC products to diverse construction and industrial customers.
| Leading Market Players |
|---|
| Advanced Environmental Recycling Technologies |
| Oldcastle APG (CRH) |
| Trex Company Inc. |
| Metsä Wood |
| BASF |
| The AZEK Company Inc. |
| Fiberon (Fortune Brands Innovations) |
| CertainTeed |
| UFP Industries, Inc. |
| Others |
Cost & Logistics Intelligence
Large-scale polymer extrusion and recycling operations drive significant scale economies, shaping WPC manufacturing costs and influencing both supply concentration and market price floors. This efficiency is critical for maintaining competitive pricing in a material-intensive industry.
Pricing Analysis
Geographic price spreads for WPC products reflect regional feedstock availability and regulatory compliance costs. Per-unit transactional pricing dominates for standard products, while large commercial projects often utilize contract-based long-term agreements. Material composition, particularly advanced capping technologies, and certified recycled content percentages drive significant price differentiation. Pricing softness stems from intense competition from alternative materials, making residential homeowners highly price-sensitive for basic decking.
Supply Chain Analysis
Strategic stockpiling of recycled plastics and wood fibers helps WPC manufacturers mitigate feedstock volatility, contrasting with just-in-time practices for finished goods. Global supply concentrates in China, the United States, and Germany, reflecting production capacity and regulatory drivers. The industry relies heavily on consistent streams of high-quality recycled polyethylene and ground wood particles. Feedstock quality and price fluctuations represent a significant structural risk, while distribution increasingly runs through direct-to-installer channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The WPC market is experiencing a cyclical recovery, primarily driven by renewed residential construction activity and remodeling trends in North America. This rebound supports sustained demand for durable, low-maintenance building materials.
For Market Incumbents: Fortify market share by investing in advanced capping technologies to counter material substitution threats from all-PVC composites. Expand capacity strategically in high-demand regions like the United States and Germany, leveraging the EU Green Deal's push for circularity. Secure long-term contracts for high-quality recycled plastic feedstock to mitigate price and quality volatility. Control over feedstock supply chains represents a critical lever against rising input costs.
For New Entrants and Emerging Players: Certification fast-tracks through adherence to specific national standards, like China's GB standards or India's BIS criteria, offer a strategic entry point into commercial construction. Target underpenetrated markets in Southeast Asia for interior applications such as wall paneling, leveraging urbanization trends. Develop specialized WPC products for public infrastructure projects, including boardwalks and park benches, to capitalize on government procurement favoring recycled content. A direct-to-developer sales model can accelerate market penetration in these segments.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized product innovators with proprietary material science and advanced capping technologies. WPC offers long-term viability as a sustainable alternative to traditional lumber, driven by environmental mandates and consumer preference for durability. Target companies with strong vertical integration into recycled feedstock processing or those developing new, high-performance WPC formulations beyond decking. Consistency in securing high-quality recycled plastic and wood fiber feedstock serves as a critical signal to watch.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Advanced Capping Technology | Enhances WPC durability and stain resistance, meeting demand from high-end residential construction segments. |
| Develop Reverse Logistics Networks | Secures consistent, high-quality recycled plastic and wood fiber feedstock, managing production costs. |
| Geographic Expansion into Southeast Asia | Captures new construction demand in underpenetrated markets driven by urbanization and rising incomes. |
| Product Diversification into Interior Applications | Opens new revenue streams for WPC beyond traditional outdoor uses like decking and fencing. |
| Partnerships for Public Infrastructure Projects | Creates stable, large-volume demand channels for WPC materials with high recycled content. |
Research Approach
Findings reconcile primary fieldwork against secondary review of regulatory documents, industry association reports, and company financial filings. Primary interviews engaged WPC manufacturers' R&D directors, construction contractors, material procurement leads, and regulatory compliance officers. This approach ensured a holistic understanding of market dynamics and technology adoption. Bottom-up data collection, combined with top-down market sizing, enabled robust triangulation of volume and value outputs.
Product type, material composition, application, end-user, and regional regulatory frameworks formed the segmentation dimensions modeled across the analysis window. The analytical framework integrated historical performance with projected growth drivers, deriving compound annual growth rates from a proprietary regression model. Key industry-specific forecast inputs included recycled plastic availability and residential construction starts in major markets. This comprehensive methodology ensures granular market insights.
Decision-makers should treat outputs as directional under base assumptions of stable regulatory frameworks and consistent feedstock supply; material deviation warrants model refresh. Revision becomes warranted when significant changes in global recycled material supply chains or green building mandates occur.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Composite Materials
Asia-Pacific Molded FRP Grating Market
Composite Materials
Stone Plastic Composite Flooring Market
Composite Materials
Medical Composite Material Market
Composite Materials
Global Carbon Fiber Reinforced Polymer Market
Composite Materials
Case Material Market
Composite Materials
Composite Preforms Market
Composite Materials
Fiber-Reinforced Plastic (FRP) Grating Market
Composite Materials
Asia-Pacific Natural Fiber Composites Market
Composite Materials
Glass Fiber Reinforced Plastics (GFRP) Composites Market
Composite Materials
CFRP Propeller Shaft Market
Composite Materials
Reinforced Nonwoven Plastics Market
Composite Materials
Europe Marine Composites Market
Composite Materials
Phenolic Panel Market
Composite Materials
FRP Grating Market
Composite Materials
Reinforced Carbon-Carbon Composite Market
Composite Materials
Scrim Reinforced Films Market