
 Composite Cans Market | 2026-2036
Composite Cans Market Size, Share, and Industry Trends Forecast 2026-2036
Composite Cans Market Analysis
Modular packaging configurations built around fiber-composite bodies with detachable metal or plastic ends is expanding choice for food and personal care buyers seeking format flexibility. Sonoco Products Company leverages its North American tube and core infrastructure to supply spiral-wound composite canisters at scale. Smurfit Kappa Group plc anchors European demand through integrated paperboard supply and on-site converting partnerships. Mondi Group competes via barrier-coated kraft solutions that extend shelf life without full lamination.
Composite cans are cylindrical containers formed from multiple layers of paperboard, kraft paper, or fiber-based materials, often combined with aluminum foil or polymer barriers, manufactured through spiral or convolute winding and sealed with metal, plastic, or composite ends. They protect oxygen-sensitive and moisture-critical contents while offering printability and structural rigidity at lower weight than metal or glass alternatives. Cardboard cans dominate unit volume in dry food and powder applications where cost and recyclability outweigh extreme barrier demands. Hybrid cans capture margin pools in cosmetics and specialty chemicals by combining fiber aesthetics with functional polymer or foil layers. The packaging application leads absolute demand, though display-oriented formats in premium cosmetics are gaining traction as unboxing experience becomes a purchase driver.
FDA food-contact regulations in the United States govern barrier coatings and adhesives used in composite food packaging, while the EU Packaging and Packaging Waste Regulation drives minimum recycled content thresholds and extended producer responsibility schemes across member states. REACH compliance in Europe further restricts certain chemical treatments in paperboard barrier layers, reshaping material specifications for exporters. Stakeholders must monitor how diverging state-level packaging laws in the United States and evolving EU recyclability assessments redefine acceptable end-of-life pathways for multi-material canisters.
Market Dynamics
EU Packaging and Packaging Waste Regulation mandates are compressing material recovery timelines, forcing converters to redesign multi-layer canister structures around mono-material or easily separable fiber-aluminum configurations. This regulatory pressure is restructuring supplier relationships and R&D priorities across the value chain.
Growth Catalysts
- EU recycled content thresholds:Extended producer responsibility schemes in Germany, France, and the Netherlands create compliance-driven demand for paperboard canisters with certified post-consumer fiber content.
- Powdered nutrition segment:Protein and supplement brands are replacing rigid plastic tubs with lightweight composite canisters to reduce shipping costs and improve shelf differentiation.
- Spiral-winding automation:Advances in precision cutting and inline barrier coating are lowering minimum efficient scale for regional converters serving craft food producers.
Market Restraints
- Kraft pulp price volatility:Composite canister margins compress when northern bleached softwood kraft prices spike, as paperboard constitutes 60-70% of material cost.
- Aluminum foil supply concentration:High-barrier canister production depends on thin-gauge foil supply from a limited set of European and Asian rolling mills.
- Multi-material sorting limitations:Municipal recycling infrastructure in the United States cannot consistently separate fiber bodies from metal or plastic ends, limiting circularity claims.
Strategic Opportunities
- Indian food exports:Spice and ready-mix brands targeting European retailers need compliant fiber-based packaging that satisfies FSSAI export requirements and EU recyclability standards.
- Cosmetics refill systems:Premium skincare brands are piloting composite canister bodies with detachable aluminum ends for closed-loop return programs.
- Water-based barrier coatings:Convergence of nanocellulose research and polymer chemistry is enabling oxygen and moisture barriers without laminated plastic films.
Industry Challenges
- Adhesive formulation expertise:Food-contact compliant laminating adhesives that bond kraft to foil while surviving retort or hot-fill processes require specialized polymer chemistry talent.
- End-of-life certification timelines:Obtaining recyclable or compostable validation from bodies like TUV Austria or BPI demands 12-18 month testing cycles that delay product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Composite Cans Market |
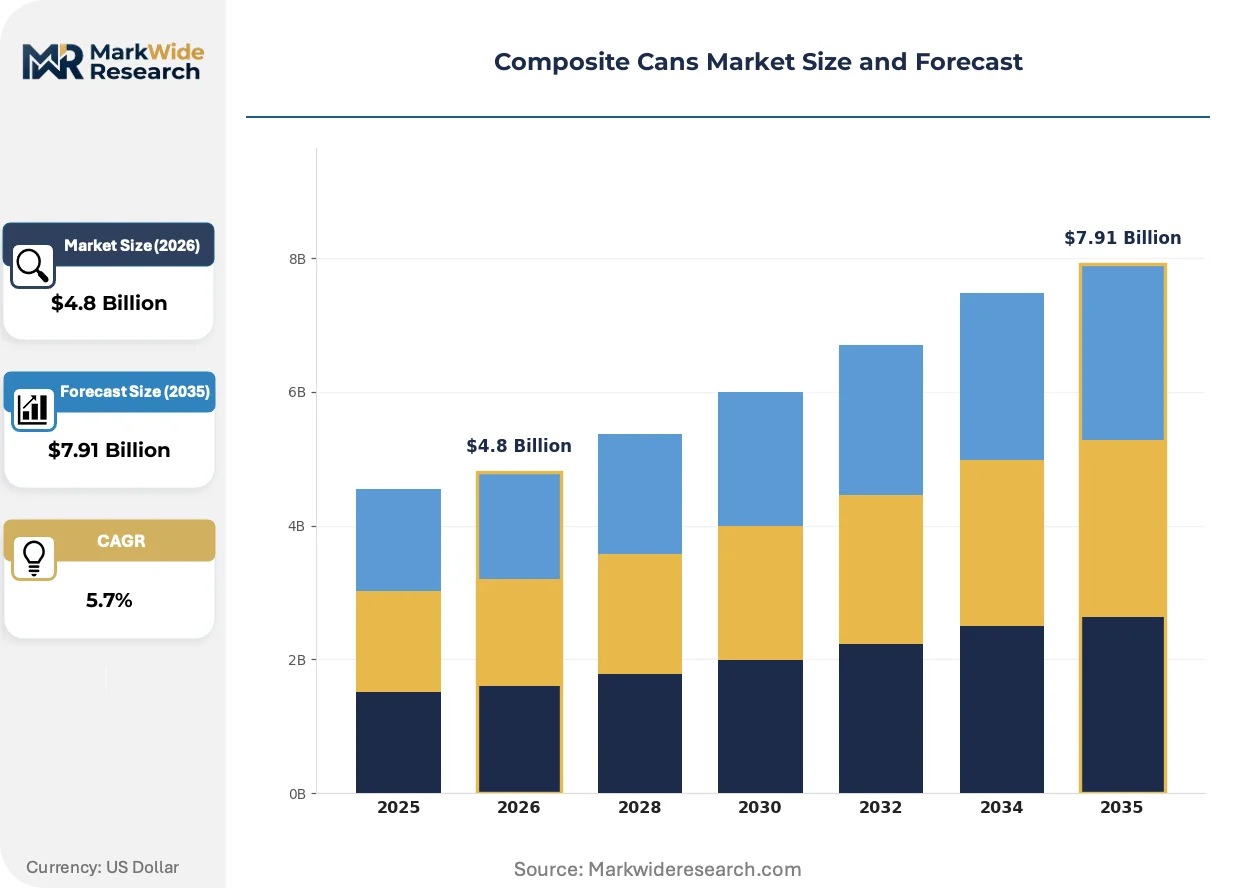
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cardboard Cans, Plastic Containers, Hybrid Cans, Metal Cans End User: Food & Beverage, Cosmetics, Chemicals, Pharmaceuticals Application: Packaging, Storage, Transport, Display Distribution Channel: Online Retail, Supermarkets, Convenience Stores, Wholesale |
| Companies Covered | Sonoco Products Company, Smurfit Kappa Group plc, Mondi Group, Corex Group, Irwin Packaging Pty Ltd, CANFAB Packaging Inc., Ace Paper Tube, WestRock Company, Amcor plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Composite Cans Market Emerging Trajectories
Barrier coating chemistry and winding automation are converging to displace traditional laminated structures. These technical advances are compressing the cost gap between standard and high-performance composite canisters while opening new application spaces.
Digital printing integration with spiral-winding lines is decentralizing short-run production economics. Specialty coffee roasters and craft supplement brands are adopting digitally printed kraft canisters with run lengths below five thousand units. This capability is fragmenting order patterns and enabling direct-to-brand relationships that bypass traditional distributor networks.
REACH restrictions on per- and polyfluoroalkyl substances are forcing reformulation of grease-resistant paperboard treatments used in composite food canisters. The European Chemicals Agency enforcement timeline is accelerating migration toward silicone-based or bio-wax alternatives. Bakery and confectionery applications in Germany and Scandinavia are most affected, with converters qualifying new barrier systems ahead of 2025 compliance deadlines.
Brand procurement teams are consolidating specification authority at headquarters while pushing volume commitments onto regional co-packers. This centralization is squeezing mid-tier converters who lack the scale to serve multinational accounts or the flexibility to serve local craft brands. The tension is most visible in North American dry food packaging, where national retailers now mandate uniform canister specifications across their private-label suppliers.
Composite Cans Market Segmentation
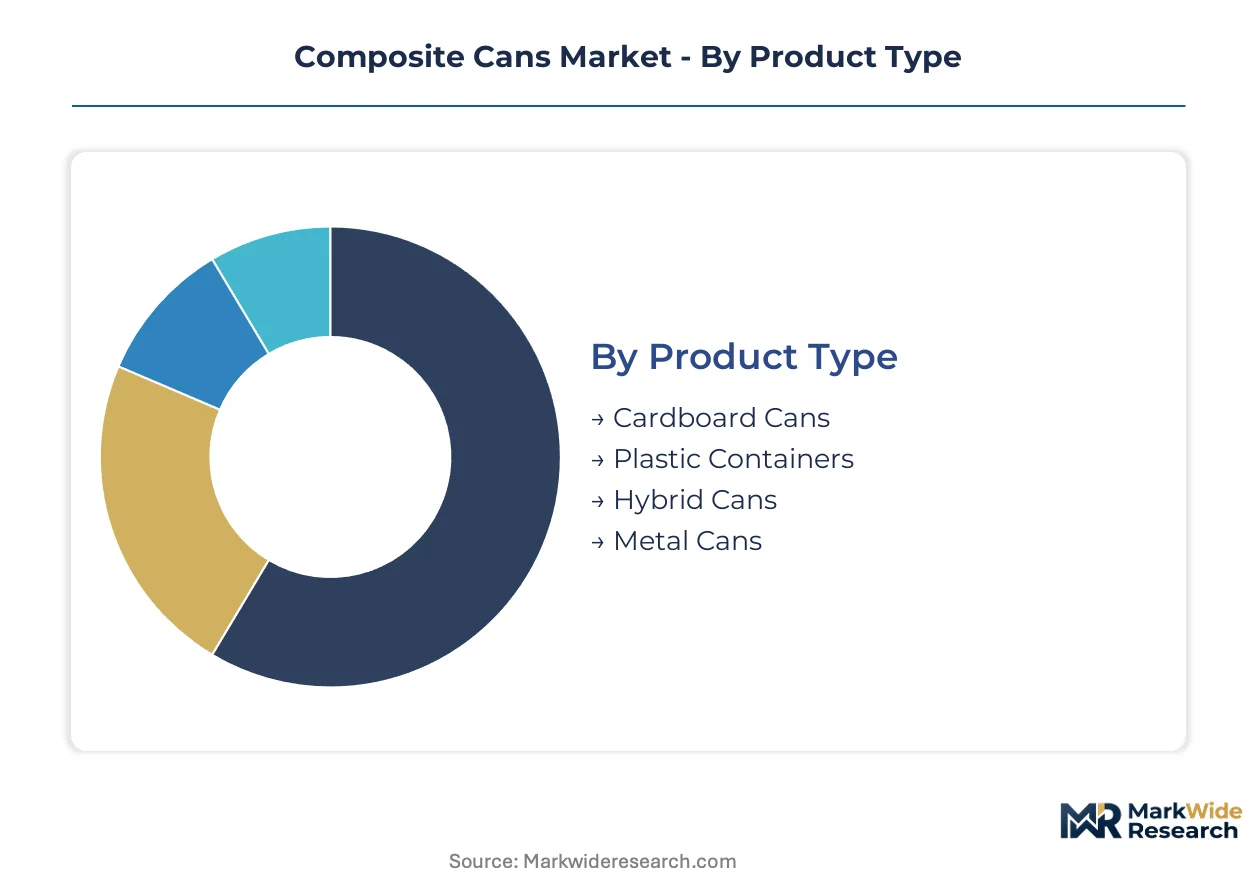
Composite canister buyers prioritize barrier performance, recyclability claims, and unit economics in sharply different combinations across food, cosmetics, and industrial end-uses. Segment boundaries are blurring as fiber-based formats absorb share from rigid plastic and metal alternatives.
Product Type:
Buyers segment primarily by cost-to-barrier ratio, balancing material cost against shelf-life requirements and end-of-life messaging.
- Cardboard Cans:Spiral-wound kraft paperboard bodies with optional foil or polymer barrier layers dominate dry food and powder applications. German retailers and North American private-label brands specify these for breakfast cereals and baking mixes where 12-18 month shelf life suffices and recycling credentials drive procurement.
- Hybrid Cans:Fiber-composite bodies married to aluminum or high-performance polymer ends capture premium cosmetics and specialty chemical demand. French skincare brands and Dutch chemical distributors pay 40-60% premiums for detachable-end formats that support refill and return programs.
- Plastic Containers:Injection-molded or thermoformed rigid polymer canisters retain position in moisture-critical applications where retort processing or hot-fill sterilization exceeds paperboard thermal limits. Indian spice exporters and Southeast Asian beverage co-packers specify these for tropical climate distribution.
- Metal Cans:Two-piece or three-piece steel and aluminum cylinders defend share in high-acid food and industrial coatings where absolute oxygen and light exclusion is mandatory. Italian tomato processors and German automotive chemical suppliers remain anchored to metal despite fiber-format encroachment.
Cardboard cans lead on scale; hybrid cans lead on momentum.
End User:
Application-specific regulatory exposure and sustainability disclosure requirements reshape vendor selection criteria across buyer categories.
- Food & Beverage:Dry goods, powdered supplements, and instant beverage brands generate the highest unit volumes. FDA food-contact compliance and EU Packaging and Packaging Waste Regulation recyclability thresholds dominate material specification conversations for US and European buyers.
- Cosmetics:Premium skincare and fragrance houses prioritize unboxing experience and refill-system compatibility. REACH restrictions on per- and polyfluoroalkyl substances are forcing reformulation of grease-resistant treatments in paperboard canisters sold into German and Scandinavian markets.
- Chemicals:Specialty agrochemicals, adhesives, and industrial coatings demand UN-certified transport performance. Hybrid canisters with fiber aesthetics and metal ends satisfy both retail shelf presence and hazardous material handling requirements.
- Pharmaceuticals:OTC powders, effervescent tablets, and medical device packaging require child-resistant closure systems and batch-level traceability. Barrier-coated fiber formats are gaining trial against traditional aluminum and HDPE alternatives.
Food and beverage commands absolute volume; cosmetics climbs the fastest on premium positioning.
Application:
Functional performance requirements diverge sharply between protection-focused and experience-focused use cases.
- Packaging:Primary containment for oxygen-sensitive and moisture-critical contents represents the foundational application. Spiral-wound composite canisters with inline barrier coating displace laminated structures as water-based chemistry advances.
- Storage:Long-term warehousing and intermediate bulk handling favors stackable, moisture-resistant formats. Hybrid canisters with reinforced polymer ends capture share in specialty chemical and pharmaceutical distribution.
- Transport:UN-certified performance for hazardous and fragile goods mandates specific crush strength and drop-test ratings. Metal cans retain dominance; fiber-composite alternatives are qualifying for limited non-hazardous chemical segments.
- Display:Shelf-ready and point-of-sale formats prioritize print quality, structural differentiation, and tactile finish. Digital printing integration with spiral-winding lines enables run lengths below five thousand units for craft brands.
Packaging anchors revenue; display gains share fastest on brand experience investment.
Distribution Channel:
Order scale and specification authority concentration determine converter relationship structures.
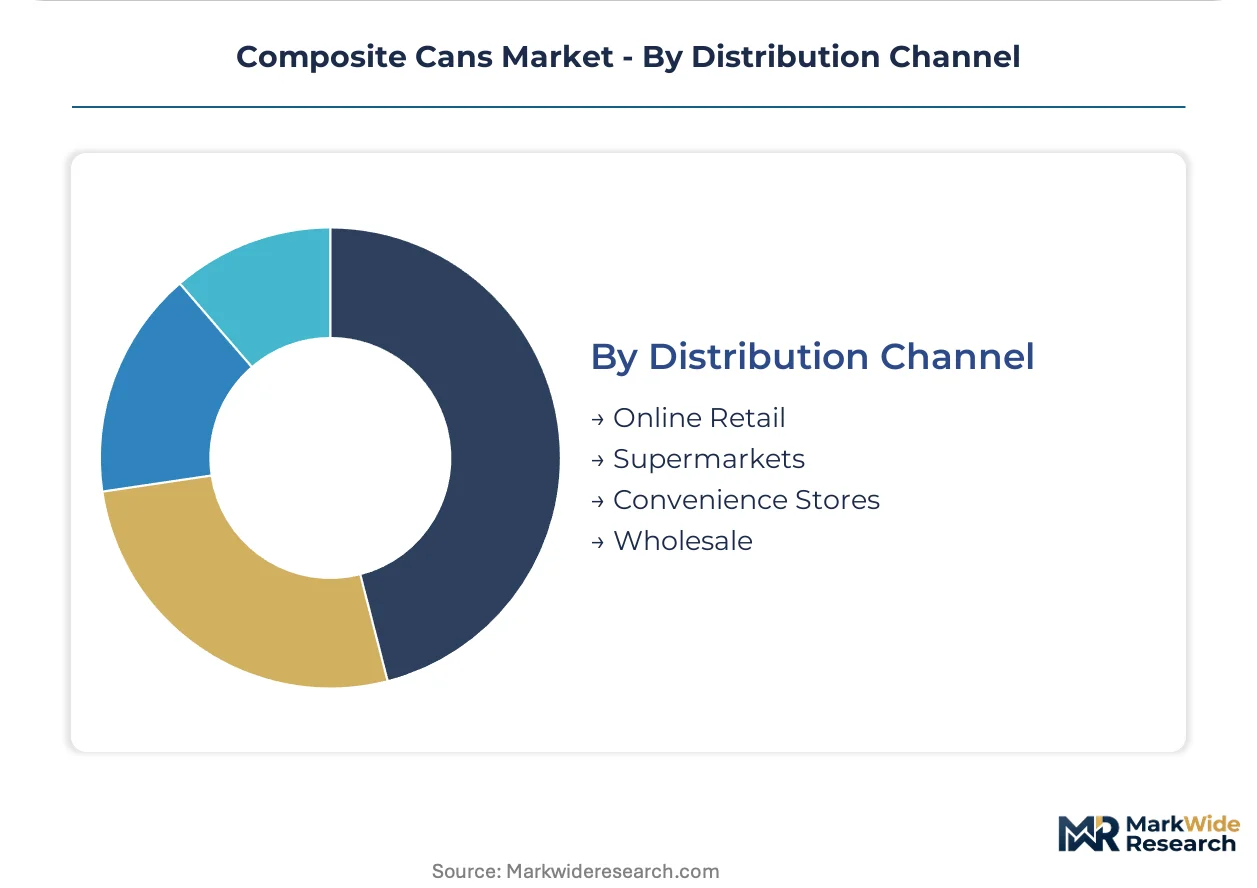
- Supermarkets:National and regional retail chains consolidate private-label canister specifications at headquarters level. Volume commitments flow to regional co-packers, squeezing mid-tier converters lacking multinational scale or craft-brand flexibility.
- Online Retail:Direct-to-consumer and marketplace fulfillment demands damage-resistant, lightweight formats with premium unboxing presentation. Supplement and specialty coffee brands specify digitally printed kraft canisters for subscription box integration.
- Wholesale:Industrial and foodservice bulk distribution prioritizes unit cost and pallet efficiency. Standardized cardboard can specifications dominate, with limited customization tolerance.
- Convenience Stores:Impulse-oriented formats and single-serve portions favor compact canister sizes with high-visibility graphics. Local and regional converters serve this fragmented demand through distributor relationships.
Supermarkets concentrate procurement authority; online retail expands most quickly on brand-direct relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Spiral-wound composite canister manufacturing first achieved industrial scale in mid-20th century North America before migrating to European paperboard clusters. Today production concentrates in Germany, the United States, India, China, and Brazil where converter infrastructure aligns with end-user demand and regulatory pressure.
Germany
Premium food exports and sustainability procurement mandates drive specification of high-barrier paperboard canisters over metal alternatives. The EU Packaging and Packaging Waste Regulation enforces strict material recovery targets that favor recyclable fiber-aluminum structures. Converter clusters in Baden-Württemberg and North Rhine-Westphalia supply spiral-wound canisters to private-label breakfast cereal brands and baking mix exporters.
United States
Powdered nutrition and specialty coffee segments displace rigid plastic tubs with lightweight composite formats for e-commerce fulfillment. FDA food-contact regulations govern barrier coatings and laminating adhesives in domestic food packaging. Regional converters in the Midwest and Southeast serve national retailers through automated spiral-winding lines with inline digital printing capability.
India
Spice and ready-mix food exporters targeting European retailers require compliant fiber-based packaging satisfying FSSAI export requirements. The FSSAI mandates food-contact safety standards for packaging materials in export-bound goods. Converter operations in Maharashtra and Gujarat supply spiral-wound canisters to agro-processing clusters in Nashik and Rajkot for turmeric, masala, and instant beverage brands.
China
Domestic demand for premium cosmetics and specialty chemical packaging absorbs hybrid canister production with fiber aesthetics and functional barriers. GB standards regulate food-contact paperboard materials and migration limits for composite structures. Manufacturing concentration in the Yangtze River Delta and Pearl River Delta serves both domestic brands and contract manufacturing for European cosmetics houses.
Brazil
Processed food and instant beverage brands adopt composite canisters for shelf differentiation in competitive retail environments. ANVISA regulates food-contact packaging materials including paperboard barrier layers and adhesives. Converter infrastructure in São Paulo state supplies spiral-wound formats to coffee roasters and powdered drink mixers in the Campinas industrial corridor.
Composite Cans Market Vendor Landscape
Premium-margin players sit above commodity-margin players across barrier technology and sustainability certification dimensions. The vendor base spans integrated paperboard producers, specialized tube and core converters, and diversified packaging conglomerates with composite canister divisions. Three archetypes dominate: integrated paperboard suppliers with captive converting capacity, standalone spiral-winding specialists serving regional craft brands, and multinational packaging groups leveraging global customer relationships. Competitive moves concentrate on barrier coating R&D partnerships and geographic expansion through distributor relationships rather than vertical integration.
Within the integrated paperboard tier, Smurfit Kappa Group plc and Mondi Group exemplify European-based converters with captive kraft supply and on-site converting partnerships. Sonoco Products Company occupies a position among North American tube and core infrastructure players with scale supply capability. These three entities anchor the competitive structure through their representation of distinct geographic and integration archetypes rather than through uniform strategic positioning.
| Leading Market Players |
|---|
| Sonoco Products Company |
| Smurfit Kappa Group plc |
| Mondi Group |
| Corex Group |
| Irwin Packaging Pty Ltd |
| CANFAB Packaging Inc. |
| Ace Paper Tube |
| WestRock Company |
| Amcor plc |
| Others |
Supply Flow & Price Mechanics
Captive kraft paperboard supply from integrated European mills anchors converter margins and insulates premium-tier producers from spot pulp volatility. This backward integration into northern bleached softwood kraft production concentrates pricing power among Smurfit Kappa and Mondi while forcing standalone spiral-winding specialists toward commodity cardboard can segments.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates hybrid canisters with detachable aluminum ends from laminated barrier cardboard cans and basic spiral-wound formats. Price differentiation rests on barrier certification grade and volume scale, with German private-label buyers showing highest sensitivity to per-unit differentials. Cost compression in standard-tier cardboard cans intensifies as Asian imports pressure European converter margins. Premium cosmetics brands exhibit lowest price sensitivity, absorbing 40-60% premiums for refill-compatible hybrid formats.
Supply Chain Analysis
Skilled technician availability in Baden-Württemberg, North Rhine-Westphalia, and the American Midwest sustains precision spiral-winding operations that cannot be easily relocated. Manufacturing gravity centers on Germany, the United States, and China, with each cluster drawing from regional kraft pulp supply and specialized aluminum foil rolling capacity. Raw material sourcing rests on northern bleached softwood kraft, thin-gauge aluminum foil, and food-contact adhesive formulations. Single-source vulnerability in European foil supply creates structural risk for high-barrier canister producers. Distribution runs through converter-direct relationships with multinational food brands and regional co-packer networks serving private-label retailers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The composite cans market compounds steadily as regulatory mandates for recyclable fiber-based packaging tighten across European and North American jurisdictions. This structural demand driver sustains volume growth independent of cyclical consumer spending swings.
For Market Incumbents: Acquire water-based barrier coating technology specialists to defend against laminate-displacement trends and REACH-driven adhesive reformulation requirements. Consolidate regional spiral-winding capacity in Germany and the American Midwest to capture scale efficiencies as national retailers centralize procurement authority. Prioritize TUV Austria recyclability certification investment ahead of EU Packaging and Packaging Waste Regulation enforcement timelines.
For New Entrants and Emerging Players: Enter via digital printing-integrated spiral-winding lines serving craft supplement and specialty coffee brands with sub-five-thousand-unit run lengths. Target Indian spice exporters needing FSSAI-compliant, EU-recyclable fiber packaging for European retail penetration. Pursue direct-to-brand relationships that bypass established distributor networks controlling supermarket and wholesale channels.
For Investors and Strategic Acquirers: Roll-up economics work for mid-tier European converters with captive kraft supply and on-site barrier coating partnerships because customer consolidation at multinational food brands rewards scale and certification breadth. Five-to-ten-year viability hinges on positioning ahead of water-based chemistry displacement of laminated structures. Monitor REACH restriction enforcement on per- and polyfluoroalkyl substances as inflection indicator for barrier coating technology winners.
| Strategic Initiative | Industry Significance |
|---|---|
| Water-Based Barrier Coating Scale-Up | REACH compliance in Germany and Scandinavia accelerates laminate displacement in bakery applications. |
| Digital Printing Line Integration | Craft coffee roasters in the United States adopt sub-five-thousand-unit runs for subscription channels. |
| Recyclability Certification Investment | TUV Austria validation enables EU Packaging and Packaging Waste Regulation compliance claims. |
| Regional Co-Packer Partnership | National retailers centralize private-label specifications while pushing volume to regional converters. |
| Refill System Format Development | French skincare brands pilot detachable aluminum ends for closed-loop return programs. |
Methodological Framework
Direct dialogue with spiral-winding plant managers, paperboard procurement leads at multinational food brands, barrier coating R&D directors, and sustainability compliance officers grounded qualitative findings in operational reality. Secondary validation drew from EU Packaging and Packaging Waste Regulation filings, FSSAI export compliance databases, REACH restriction enforcement timelines, and SEC disclosures from listed packaging conglomerates. Bottom-up capacity and demand modeling triangulated against top-down macroeconomic drivers across the analysis window.
Segment-level value and volume outputs emerged from disaggregated modeling across product type, end-user industry, functional application, and distribution channel dimensions. CAGRs were derived from regression analysis of historical shipment data and forward projection of regulatory-driven substitution elasticities. Key inputs included kraft pulp price indices, aluminum foil rolling capacity utilization, and digital printing adoption curves in North American craft food segments.
The model holds under stable regulatory enforcement timelines and intact raw material supply chains; deviation in REACH restriction acceleration, northern bleached softwood kraft price spikes, or aluminum foil supply disruption would shift volume and value trajectories. Forecasts reflect documented assumptions about barrier coating technology diffusion and retailer procurement centralization rates. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Composite Materials
Composites Distributor Market
Composite Materials
Laminar Composites Market
Composite Materials
Global Geocomposites Market
Composite Materials
Acrylic Laminates Market
Composite Materials
Isostatic Graphite Market
Composite Materials
Structural Core Materials Market
Composite Materials
Wall Cladding Materials Market
Composite Materials
Carbon Thermoplastic Composites Market
Composite Materials
Global FRP Vessels Market
Composite Materials
Composites Testing Market
Composite Materials
High Pressure Laminate (HPL) Market
Composite Materials
Aramid Fiber Reinforced Polymer Market
Composite Materials
Expandable Graphite Market
Composite Materials
Global Carbon Fiber Reinforced Polymer Market
Composite Materials
High Performance Carbon Fiber Precursor Market
Composite Materials
Synthetic Rope Market