
 Wind Turbine Composites Market | 2026-2036
Wind Turbine Composites Market Size, Share, and Industry Trends Forecast 2026-2036
Wind Turbine Composites Market Intelligence
The direct-to-OEM supply channel is narrowing as blade manufacturers consolidate preferred-partner agreements with resin and fiber suppliers. Toray Industries leverages its carbon fiber precursor capacity to anchor long-term contracts with leading blade producers. SGL Carbon competes through specialized pitch-based carbon fiber grades optimized for structural spar caps. Owens Corning sustains its position by controlling high-modulus glass fiber formulations that balance cost against performance in longer blades.
Wind turbine composites encompass fiber-reinforced polymer systems—typically epoxy or polyester matrices with glass, carbon, or aramid reinforcement—fabricated through infusion, prepreg lamination, or filament winding to achieve specific stiffness-to-weight ratios and fatigue resistance for rotating machinery. These materials reduce blade mass by 20-30% compared to metallic alternatives, enabling rotor diameters exceeding 150 meters that capture more energy at lower wind speeds. Glass fiber dominates blade skins and shear webs due to cost efficiency, while carbon fiber captures margin pools in spar caps where stiffness requirements intensify with blade length. Prepreg processing leads nacelle and hub applications requiring precise fiber placement, though vacuum infusion is displacing hand lay-up in blade manufacturing as scale demands repeatable cycle times.
The EU Green Deal and REACH chemical frameworks restrict hazardous resin constituents, while China's GB standards and dual carbon goals mandate recycled content thresholds in turbine construction. Germany's KBA and Denmark's national energy agency enforce blade recyclability protocols that reshape material selection and end-of-life liability across the value chain. Stakeholders must monitor how evolving extended producer responsibility rules in Europe and China's carbon trading scheme will alter composite formulation economics and supplier qualification requirements.
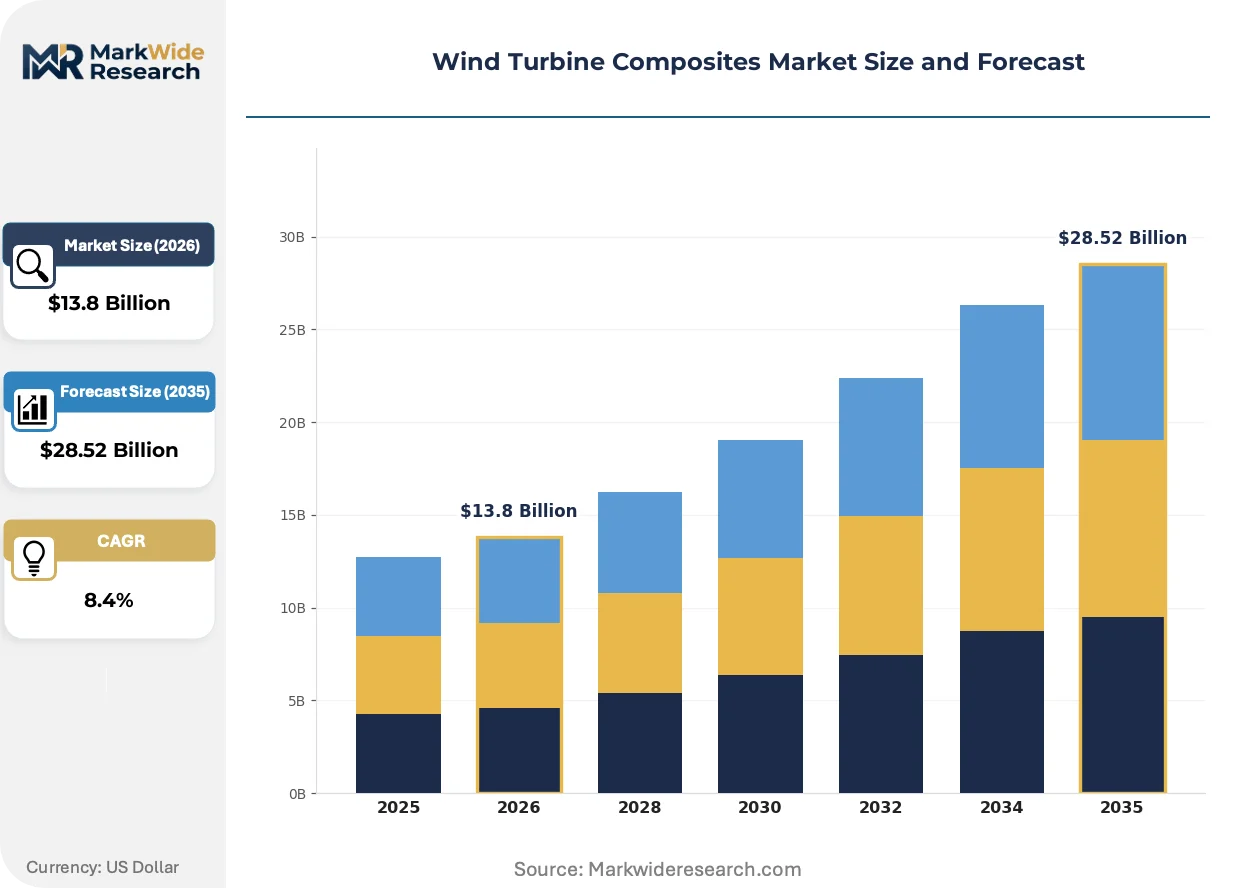
Market Dynamics
Offshore wind farm developers are consolidating procurement around single-source blade suppliers capable of delivering 100-meter-plus rotor systems, compressing the composite supply base into long-term preferred-partner structures that lock in resin and fiber volumes across decade-long project pipelines.
Growth Catalysts
- EU Green Deal carbon-intensity benchmarks:Germany and Denmark are tightening manufacturing emissions standards, forcing turbine OEMs to source lower-carbon composite precursors and qualifying new fiber suppliers with verified lifecycle data.
- China's coastal provincial mandates:Jiangsu, Guangdong, and Fujian governments are accelerating gigawatt-scale offshore installations, concentrating blade demand in manufacturing clusters with direct port access for oversized component logistics.
- Vacuum infusion process maturation:Blade fabricators are displacing hand lay-up with automated infusion systems, cutting cycle times for 80-meter-plus blades and enabling repeatable quality at volumes that match offshore deployment schedules.
Market Restraints
- Epoxy resin price volatility:Petrochemical feedstock fluctuations and bisphenol-A supply constraints are squeezing blade manufacturer margins, with resin representing 25-35% of total composite material costs.
- Carbon fiber supply concentration:Precursor production clusters in Japan and the United States create geographic vulnerability for spar cap manufacturers dependent on high-modulus grades for next-generation blade stiffness requirements.
- REACH chemical restrictions:ECHA's evolving substance restrictions on styrene and certain amine hardeners are forcing reformulation of polyester and vinyl ester systems used in nacelle housings, extending qualification timelines.
Strategic Opportunities
- Recyclable thermoplastic composites:Blade end-of-life liability under Germany's KBA protocols and emerging EU extended producer responsibility rules is creating first-mover advantage for suppliers with validated recycling pathways for glass-polypropylene systems.
- India's offshore wind auction pipeline:The country's national renewable energy agency is tendering multi-gigawatt coastal zones in Gujarat and Tamil Nadu, opening procurement channels for composite suppliers with experience in tropical corrosion environments.
- Digital twin integration with blade manufacturing:Real-time fiber placement monitoring and predictive cure modeling are converging with quality assurance systems, enabling defect reduction warranties that differentiate suppliers in OEM qualification processes.
Industry Challenges
- Non-destructive testing technician scarcity:Ultrasonic and thermography inspection specialists for 100-meter blade spar cap verification are concentrated in Northern European training programs, creating recruitment bottlenecks for new manufacturing facilities.
- DNV-ST-0126 certification timelines:Type certification for novel composite laminate designs requires 18-24 month test campaigns, delaying revenue recognition for blade platforms targeting next-generation turbine ratings.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wind Turbine Composites Market |
| Market Size in 2026 | $13.8 Billion |
| Market Size in 2035 | $28.52 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Glass Fiber, Carbon Fiber, Aramid Fiber, Others Component: Bla de, Hub, Tower, Nacelle Manufacturing Process: Prepreg, Infusion, Hand Lay-up, Filament Winding End User: OEMs, Components Manufacturers, Utility Companies, Offshore Developers |
| Companies Covered | Toray Industries, SGL Carbon, LM Wind Power, Zhongfu Lianzhong Group, Owens Corning, TPI Composites, Hexcel Corporation, Teijin Limited, Gurit Holding AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wind Turbine Composites Market Strategic Shifts & Innovations
Composite manufacturing for wind energy is pivoting from labor-intensive processes toward automated systems that compress cycle times while accommodating the geometric complexity of 15 MW-rated blade platforms.
Digital thread architecture is virtualizing quality assurance across blade manufacturing workflows. Siemens Gamesa and Vestas are deploying sensor-embedded molds that capture resin flow front progression in real time. This virtualization is compressing defect detection from post-cure inspection to in-process intervention, reducing scrap rates for spar cap infusion cycles.
REACH chemical frameworks are forcing resin system reformulation across European supply chains. ECHA's 2023-2025 substance evaluation roadmap targets specific amine curing agents used in blade adhesives and infusion resins. Manufacturers serving the German and Danish markets are accelerating bio-based epoxy development, with qualification timelines now determining supplier retention in Nordex and Siemens Gamesa preferred-partner programs.
Direct-to-OEM contracting is displacing tiered distribution for carbon fiber spar cap materials. Blade manufacturers are negotiating multi-year offtake agreements with Toray and SGL Carbon that bypass traditional composite distributors, securing volume commitments for 50-tonne carbon fiber annual deliveries. This pattern is most visible in China's coastal manufacturing zones, where Mingyang and Envision are consolidating supply relationships ahead of provincial offshore auction deadlines.
Wind Turbine Composites Market Segmentation
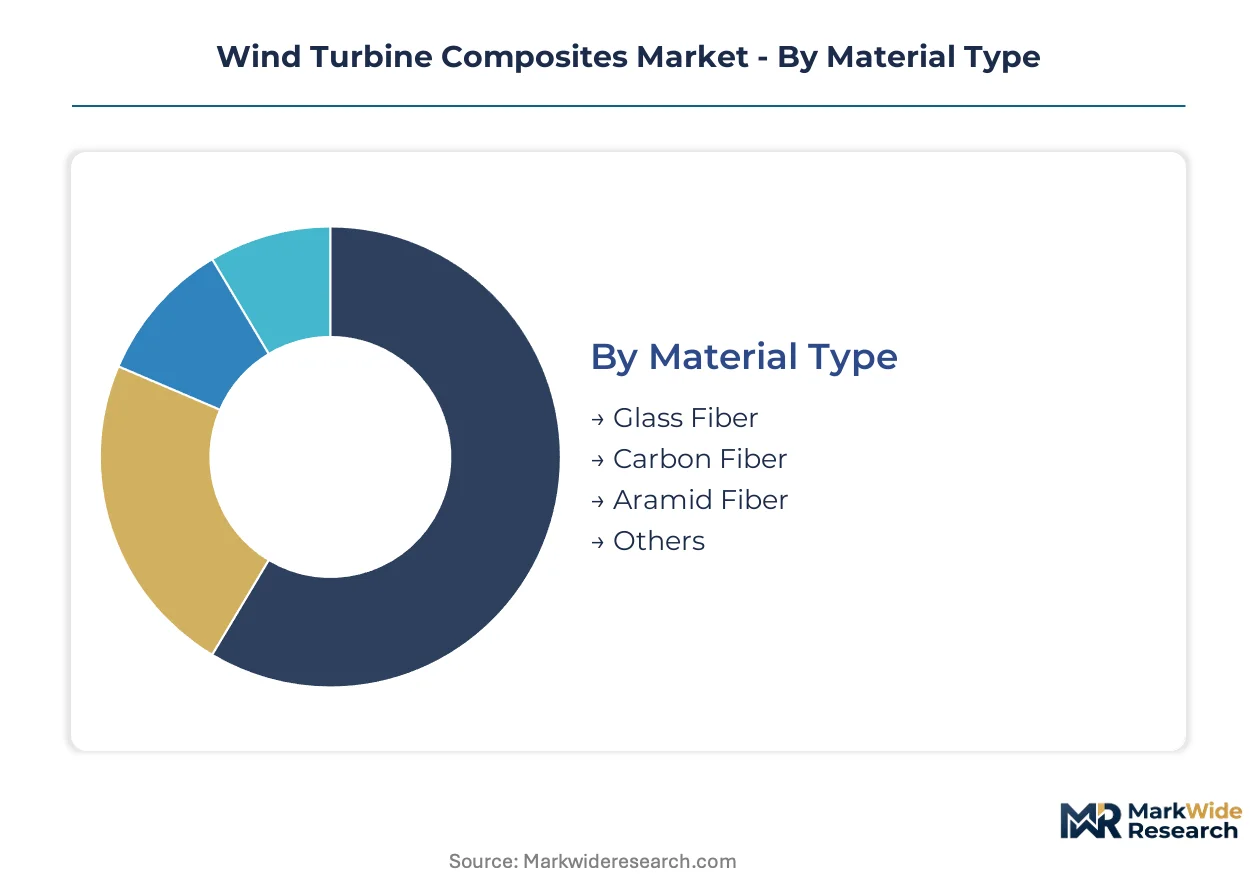
Segmentation in wind turbine composites reveals how material selection, component architecture, and manufacturing methods align with divergent cost-performance trade-offs across onshore and offshore installations. Blade length escalation and carbon-intensity regulations are fragmenting procurement patterns, forcing suppliers to specialize across distinct technical tiers rather than competing as generalists.
Material Type:
Mature glass fiber formulations dominate volume throughput, while emerging carbon fiber grades capture premium stiffness applications as blade lengths exceed 80 meters.
- Glass Fiber:E-glass and high-modulus formulations constitute the baseline reinforcement for blade skins, shear webs, and nacelle housings. Demand concentrates in China's Jiangsu and Guangdong manufacturing clusters, where provincial offshore mandates favor cost-efficient 70-90 meter blade platforms.
- Carbon Fiber:PAN-based and pitch-based precursors deliver the stiffness-to-weight ratios required for spar caps in 100-meter-plus rotors. Procurement is tightening around Toray Industries and SGL Carbon direct contracts as Germany's KBA protocols and EU Green Deal benchmarks pressure OEMs to document lifecycle carbon intensity.
- Aramid Fiber:Kevlar and Twaron grades provide impact resistance in leading-edge protection and root reinforcement zones.
- Others:Basalt fiber and natural fiber hybrids occupy niche sustainability trials in European demonstration projects.
Glass fiber handles the majority of throughput; carbon fiber is the fastest mover on share.
Component:
Cost tier segmentation separates high-unit-value blades from commoditized tower segments, with margin concentration tracking structural load intensity.
- Blade:Composite shells, spar caps, and shear webs integrate glass-carbon hybrid laminates through vacuum infusion or prepreg processing. Offshore developers in Denmark and Germany are consolidating procurement around single-source suppliers capable of delivering 100-meter-plus systems with integrated lightning protection.
- Hub:Cast-resin transfer molding and filament-wound composite hubs reduce nacelle mass while accommodating pitch bearing loads. Demand clusters with Vestas and Siemens Gamesa assembly facilities in Northern Europe.
- Tower:Hybrid steel-concrete towers with composite access platforms and cable management systems serve lower-margin onshore segments.
- Nacelle:Polyester and vinyl ester housings require reformulation as ECHA REACH restrictions target styrene emissions in European supply chains.
Blades command the dominant revenue share; nacelle composites face the steepest regulatory reformulation pressure.
Manufacturing Process:
Volume scale and cycle-time requirements are displacing artisan methods with automated systems that match offshore deployment schedules.
- Prepreg:Resin-impregnated fiber sheets enable precise fiber placement and controlled cure profiles for spar caps and structural inserts. Nacelle manufacturers serving German OEM qualification programs favor prepreg for DNV-ST-0126 certification consistency.
- Infusion:Vacuum-assisted resin transfer molding dominates blade production above 60 meters, cutting cycle times versus hand lay-up while accommodating complex aerodynamic geometries. China's coastal blade factories are completing automation retrofits ahead of provincial auction deadlines.
- Hand Lay-up:Manual lamination persists in repair operations, prototype development, and small-batch nacelle components.
- Filament Winding:Automated fiber placement produces cylindrical hub shells and drive shaft covers with optimized hoop strength.
Infusion captures the dominant production volume; prepreg maintains the steepest expansion trajectory in spar cap applications.
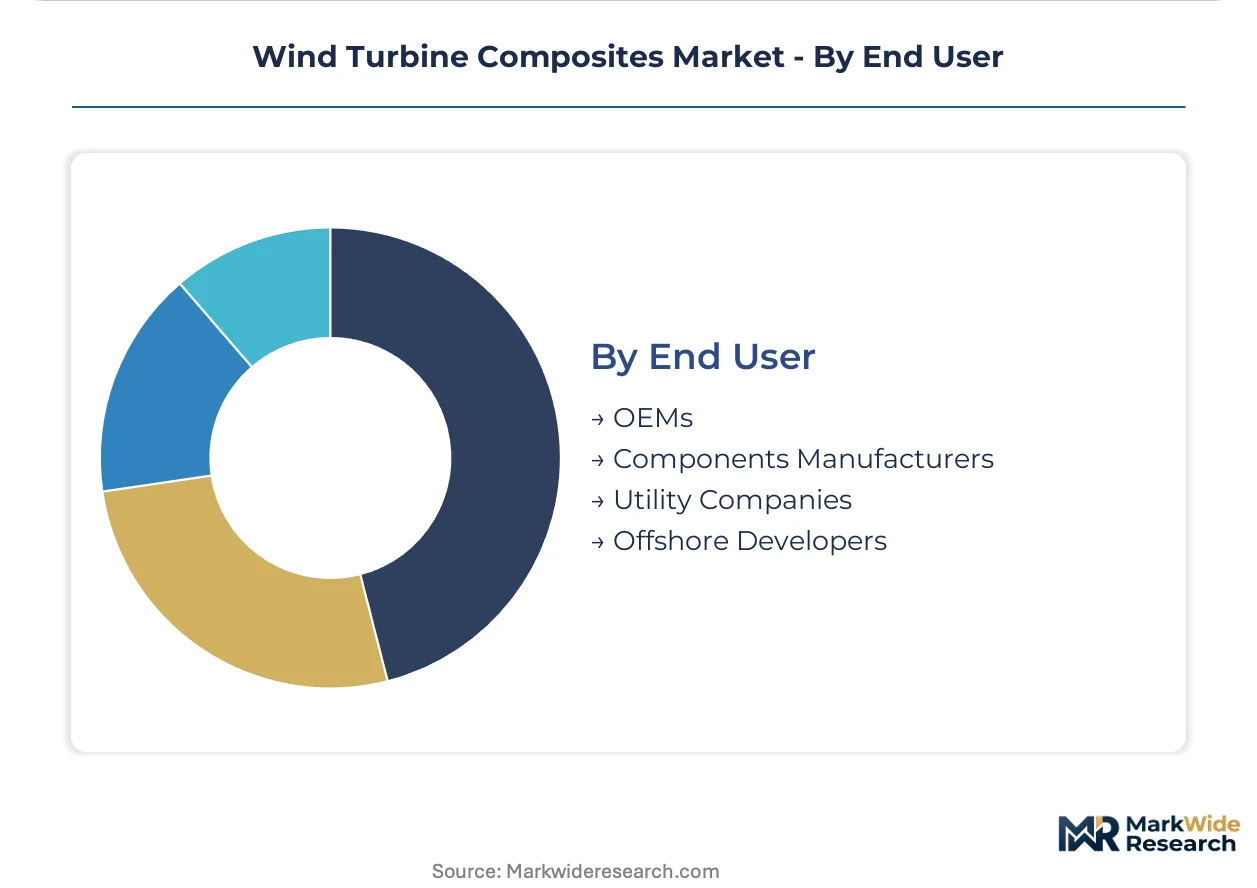
End User:
Customer type segmentation distinguishes direct OEM contracting from tiered component supply, with channel structure determining fiber and resin qualification requirements.
- OEMs:Vestas, Siemens Gamesa, and Goldwind specify composite formulations directly, negotiating multi-year offtake agreements that bypass traditional distributors. Preferred-partner programs now lock in resin and fiber volumes across decade-long offshore project pipelines.
- Components Manufacturers:Independent blade and nacelle suppliers serving secondary OEMs face margin compression from epoxy resin price volatility and extended qualification timelines.
- Utility Companies:European utilities with in-house project development capabilities are inserting material sustainability requirements into EPC contracts.
- Offshore Developers:Ørsted, Equinor, and China's state-owned coastal developers consolidate procurement around integrated turbine suppliers, reducing direct composite purchasing.
OEMs direct the majority of composite specification; offshore developers are gaining share fastest as procurement centralization accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China commands pricing leverage through coastal manufacturing scale, while European suppliers extract premiums from carbon-intensity verified supply chains. This asymmetry shapes procurement patterns across blade manufacturing clusters.
China
Jiangsu, Guangdong, and Fujian provincial governments are accelerating gigawatt-scale offshore installations through state-backed coastal development zones. GB standards and dual carbon goals mandate recycled content thresholds in turbine construction. Yancheng and Zhuhai manufacturing clusters host integrated blade factories with direct port access for 100-meter-plus component logistics.
Germany
The KBA enforces blade recyclability protocols that reshape material selection and end-of-life liability across the value chain. EU Green Deal carbon-intensity benchmarks force turbine OEMs to source lower-carbon composite precursors. Rostock and Bremerhaven port zones concentrate blade assembly facilities serving North Sea offshore pipelines.
Denmark
The national energy agency integrates blade certification requirements with offshore auction qualification criteria. REACH chemical frameworks restrict hazardous resin constituents in nacelle and blade manufacturing. Ringkøbing and Grenaa industrial zones anchor Vestas and Siemens Gamesa supply chain nodes for Baltic Sea deployments.
United States
The IRA production tax credits are stimulating domestic blade manufacturing capacity expansion along Gulf and Atlantic coasts. EPA industrial emissions guidelines intersect with state-level renewable portfolio standards in Texas and California. Corpus Christi and New Bedford port infrastructure is scaling for oversized component handling.
India
The national renewable energy agency is tendering multi-gigawatt coastal zones in Gujarat and Tamil Nadu. Central Electricity Authority grid integration standards are tightening turbine performance specifications for monsoon-corrosion environments. Mundra and Kattupalli port corridors are emerging as blade manufacturing hubs with direct OEM assembly linkages.
Wind Turbine Composites Market Key Industry Players
Carbon fiber precursor specialists and glass fiber formulation leaders split the market between premium stiffness applications and volume-efficient blade skins. The supply base concentrates around long-term preferred-partner agreements that lock in resin and fiber volumes across decade-long offshore project pipelines. Three archetypes dominate: Japanese and German carbon fiber specialists, American and Chinese glass fiber scale producers, and European blade integrators with captive composite engineering. Competitive moves center on backward integration into precursor production and multi-year offtake negotiations that bypass traditional distribution tiers.
Within the carbon fiber specialist tier, Toray Industries and SGL Carbon anchor premium spar cap supply relationships through direct OEM contracting structures. Owens Corning occupies a position among high-modulus glass fiber scale suppliers serving cost-optimized blade skin applications. Zhongfu Lianzhong Group represents the integrated Chinese archetype combining fiber production with blade manufacturing proximity to coastal provincial demand clusters.
| Leading Market Players |
|---|
| Toray Industries |
| SGL Carbon |
| LM Wind Power |
| Zhongfu Lianzhong Group |
| Owens Corning |
| TPI Composites |
| Hexcel Corporation |
| Teijin Limited |
| Gurit Holding AG |
| Others |
Cost & Logistics Intelligence
Yancheng and Zhuhai manufacturing clusters concentrate carbon fiber precursor capacity and vacuum infusion blade fabrication, translating port-adjacent logistics advantages into pricing power over inland competitors serving China's coastal offshore auctions. Resin and fiber suppliers leverage decade-long preferred-partner agreements to lock in volume commitments, compressing margin negotiation space for independent blade manufacturers.
Pricing Analysis
Configured-to-order spar cap laminates command 40-60% premiums over standard glass fiber blade skins, with price differentiation tracking carbon fiber grade certification and DNV-ST-0126 qualification status. Three-tier pricing structure across premium carbon-prepreg, standard glass-infusion, and economy polyester-hand-layup levels reflects stiffness-to-weight performance thresholds. Cost compression in mid-tier glass fiber formulations is intensifying because epoxy resin feedstock volatility squeezes blade manufacturer margins. Independent component manufacturers exhibit highest price sensitivity, while integrated OEMs with captive precursor supply absorb input cost swings through backward integration.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities from Toray Industries and SGL Carbon anchor procurement relationships with Vestas and Siemens Gamesa, reducing working capital burdens for spar cap manufacturers. Geographic supply concentration centers on Japan and the United States for high-modulus carbon fiber precursors, China for E-glass fiber scale production, and Germany for specialized pitch-based grades. Raw material dependencies rest on acrylonitrile monomer for PAN-based carbon fiber, bisphenol-A for epoxy resin systems, and boron-free glass melt formulations. Single-source vulnerability in Japanese precursor production creates geographic concentration risk for next-generation blade stiffness requirements. Distribution runs through direct-to-OEM contracting structures that bypass traditional composite distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Wind turbine composites markets generate substantial service-attach revenue through blade inspection, repair, and end-of-life recycling contracts, with aftermarket service layers expanding faster than hardware sales as offshore asset longevity requirements tighten.
For Market Incumbents: Pre-empt recyclable thermoplastic composite qualification ahead of Germany's KBA protocol expansion and EU extended producer responsibility rulemaking. Anchor backward integration into carbon fiber precursor production to defend margin position against resin price volatility. Capture preferred-partner status with China's state-owned offshore developers through integrated blade-logistics capabilities.
For New Entrants and Emerging Players: India's Gujarat and Tamil Nadu coastal zones offer underpenetrated procurement channels for composite suppliers with tropical corrosion environment expertise. Target nacelle housing reformulation opportunities created by ECHA REACH restrictions on styrene and amine curing agents. Enter through digital twin integration partnerships that reduce defect detection costs for blade manufacturers.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors suppliers with validated recycling pathways and carbon-intensity verified supply chains over commodity glass fiber scale producers. Long-term viability across the analysis window rests on lifecycle data transparency and preferred-partner contract depth. Monitor EU Green Deal carbon-intensity benchmark enforcement as inflection indicator for composite precursor qualification requirements.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Production | Toray Industries secures acrylonitrile supply chains against petrochemical volatility. |
| Recyclable Thermoplastic Composite Development | SGL Carbon validates glass-polypropylene recycling pathways for KBA compliance. |
| Direct-to-OEM Long-term Offtake Agreements | Mingyang locks resin and fiber volumes across decade-long offshore pipelines. |
| Digital Twin Quality Assurance Integration | Vestas deploys sensor-embedded molds for real-time resin flow monitoring. |
| Coastal Manufacturing Cluster Expansion | LM Wind Power scales Yancheng capacity for Jiangsu provincial auction deadlines. |
Research Approach
Cross-validation between primary interviews with blade manufacturing executives, resin procurement leads, and offshore project developers and secondary validation through ECHA substance evaluation roadmaps, DNV certification databases, and Chinese provincial auction disclosures anchors the qualitative findings. Bottom-up triangulation aggregates facility-level capacity data across Jiangsu, Guangdong, and Fujian manufacturing clusters, while top-down calibration incorporates EU Green Deal implementation timelines and national renewable portfolio standard trajectories.
Calibration against historical blade deployment volumes and resin consumption patterns informs the analytical framework across the projection horizon. Segmentation dimensions modeled include material type, component architecture, manufacturing process technology, and end-user channel structure. CAGRs derive from weighted average growth assumptions across coastal offshore installation pipelines, with carbon fiber penetration rates and vacuum infusion adoption curves as industry-specific forecast inputs.
Practitioners should monitor ECHA REACH substance restriction timelines, China dual carbon goal enforcement intensity, and epoxy resin feedstock price volatility for early signals of forecast revision triggers. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Composite Materials
Non-Honeycomb Sandwich Panel Core Materials Market
Composite Materials
Copper Clad Laminates Market
Composite Materials
Composites Distributor Market
Composite Materials
Polyphenylene Sulfide (PPS) Composites Market
Composite Materials
Ultra-Lightweight Cement Composites Market
Composite Materials
Global Honeycomb Core Materials Market
Composite Materials
Asia-Pacific Molded FRP Grating Market
Composite Materials
Green Composites Market
Composite Materials
Synthetic Rope Market
Composite Materials
High Temperature Composite Resin Market
Composite Materials
Metal Matrix Composites (Mmcs) Market
Composite Materials
Acrylic Laminates Market
Composite Materials
Composite Drums Market
Composite Materials
High Pressure Laminate (HPL) Market
Composite Materials
Malaysia High Pressure Laminate Market
Composite Materials
Pcb Laminate Materials Market