
 Composite Adhesives Market | 2026-2036
Composite Adhesives Market Size, Share, and Industry Trends Forecast 2026-2036
Composite Adhesives Market Analysis
The gap between thermoset and thermoplastic bonding requirements is narrowing as automated fiber placement and out-of-autoclave curing gain factory floor share. Henkel AG & Co. KGaA leverages its European formulation centers to serve Airbus and BMW structural programs. Sika AG anchors its position through construction-grade epoxy systems for wind turbine blade bonding. Dow competes on acrylic chemistry platforms optimized for automotive lightweighting cycles.
Composite adhesives are polymeric bonding agents engineered to join fiber-reinforced polymer substrates with lap-shear strengths typically exceeding 20 MPa and service temperatures ranging from −55°C to 180°C depending on resin backbone chemistry; they eliminate drilled holes that initiate crack propagation in carbon-fiber laminates. Epoxy formulations dominate primary structural applications in aerospace and marine segments due to their superior creep resistance and fatigue performance under cyclic loading. Polyurethane adhesives occupy faster-growing niches in automotive assembly where room-temperature curing and substrate flexibility reduce energy inputs and cycle times.
EPA regulates volatile organic compound emissions from adhesive manufacturing facilities under 40 CFR Part 63 Subpart HHHHH, while REACH restricts candidate substances of very high concern in imported formulations. EASA certification requirements for bonded primary aircraft structures mandate traceable cure schedules and nondestructive inspection protocols that filter supplier qualification. Buyers must weigh curing method selection against capital equipment constraints and throughput targets as UV systems displace thermal ovens in certain automated lines.
Market Dynamics
Aerospace manufacturers are replacing mechanical fasteners with adhesive bonding in primary structures, compressing cure cycles and demanding traceable quality systems that filter supplier qualification tiers.
Growth Catalysts
- REACH chemical restrictions:EU regulations on candidate substances of very high concern are accelerating demand for low-VOC epoxy and polyurethane formulations in automotive assembly plants.
- Out-of-autoclave curing:Automated fiber placement systems are expanding thermoplastic bonding applications, narrowing the performance gap with thermoset alternatives in wind turbine blade manufacturing.
- Stuttgart supplier corridor:Germany's automotive engineering cluster is concentrating R&D investment in structural adhesive programs for carbon-fiber reinforced polymer chassis components.
Market Restraints
- Petrochemical feedstock volatility:Epoxy resin precursors derived from bisphenol-A and epichlorohydrin face price instability tied to crude oil and propylene supply fluctuations.
- EASA certification timelines:European Aviation Safety Agency requirements for bonded primary aircraft structures impose 18-36 month qualification protocols that freeze supplier switches.
- Mechanical fastener residual preference:Marine repair yards and legacy aerospace maintenance facilities continue specifying riveted joints for field-serviceable assemblies.
Strategic Opportunities
- India automotive lightweighting:PLI scheme incentives for electric vehicle manufacturing are creating first-mover openings for structural adhesive specification in battery enclosure bonding.
- UV-curable acrylic platforms:Chemistry advances enabling room-temperature cure without thermal ovens are virtualizing capital equipment requirements for tier-two automotive suppliers.
- China wind turbine repowering:Aging onshore installations require blade repair and tip-extension bonding, generating aftermarket demand for paste adhesives with 30-year fatigue ratings.
Industry Challenges
- NDT technician scarcity:Nondestructive inspection protocols for bonded primary structures require certified ultrasonic or shearography operators that aerospace OEMs struggle to recruit.
- Cure schedule traceability:EASA mandates for documented thermal profiles force adhesive suppliers to integrate data-logging hardware into dispensing systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Composite Adhesives Market |
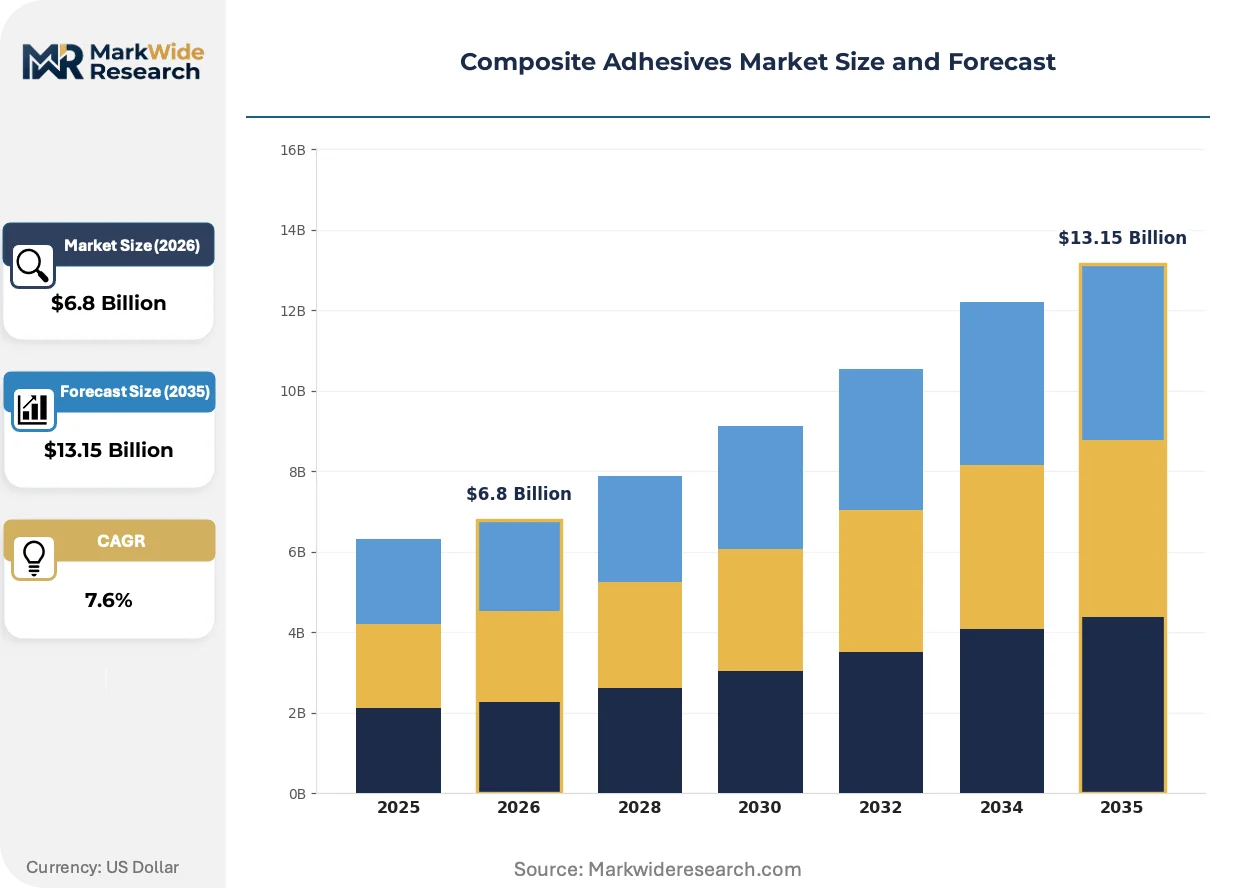
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $13.15 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Epoxy, Polyurethane, Acrylic, Cyanoacrylate End Use Industry: Aerospace, Automotive, Construction, Marine Curing Method: Thermal, UV, Moisture, Anaerobic Formulation: One-Part, Two-Part, Pre-mixed, Ready-to-use |
| Companies Covered | Henkel AG & Co. KGaA, 3M Company, Sika AG, Dow, Huntsman Corporation, H.B. Fuller, Illinois Tool Works Inc., Bostik, LORD Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Composite Adhesives Market Emerging Trajectories
Digital thread integration is compressing the gap between adhesive formulation and structural validation, with real-time cure monitoring displacing post-process inspection in high-volume assembly.
Single-component heat-curable film adhesives with embedded microcapsulated latent hardeners are virtualizing mixing operations on factory floors. Tier-one automotive suppliers in Germany and South Korea are adopting these systems for body-in-white bonding, eliminating meter-mix-dispense equipment and reducing footprint requirements by half. The shift is compressing capital barriers for mid-volume electric vehicle platforms.
EPA enforcement under 40 CFR Part 63 Subpart HHHHH is tightening volatile organic compound limits for adhesive manufacturing facilities. Formulators serving US aerospace and marine segments are investing in solvent recovery systems or switching to 100% solids chemistries. The regulatory pressure is accelerating waterborne epoxy development for secondary structural applications previously reserved for solvent-based systems.
Specifiers in automotive OEM engineering departments are consolidating approved vendor lists from twelve suppliers to three per adhesive chemistry family. Buyers now demand integrated technical service including joint design software, cure simulation, and failure analysis rather than commodity product supply. The concentration is most visible in Germany and Japan, where platform sharing across vehicle architectures amplifies purchasing leverage.
Composite Adhesives Market Segmentation
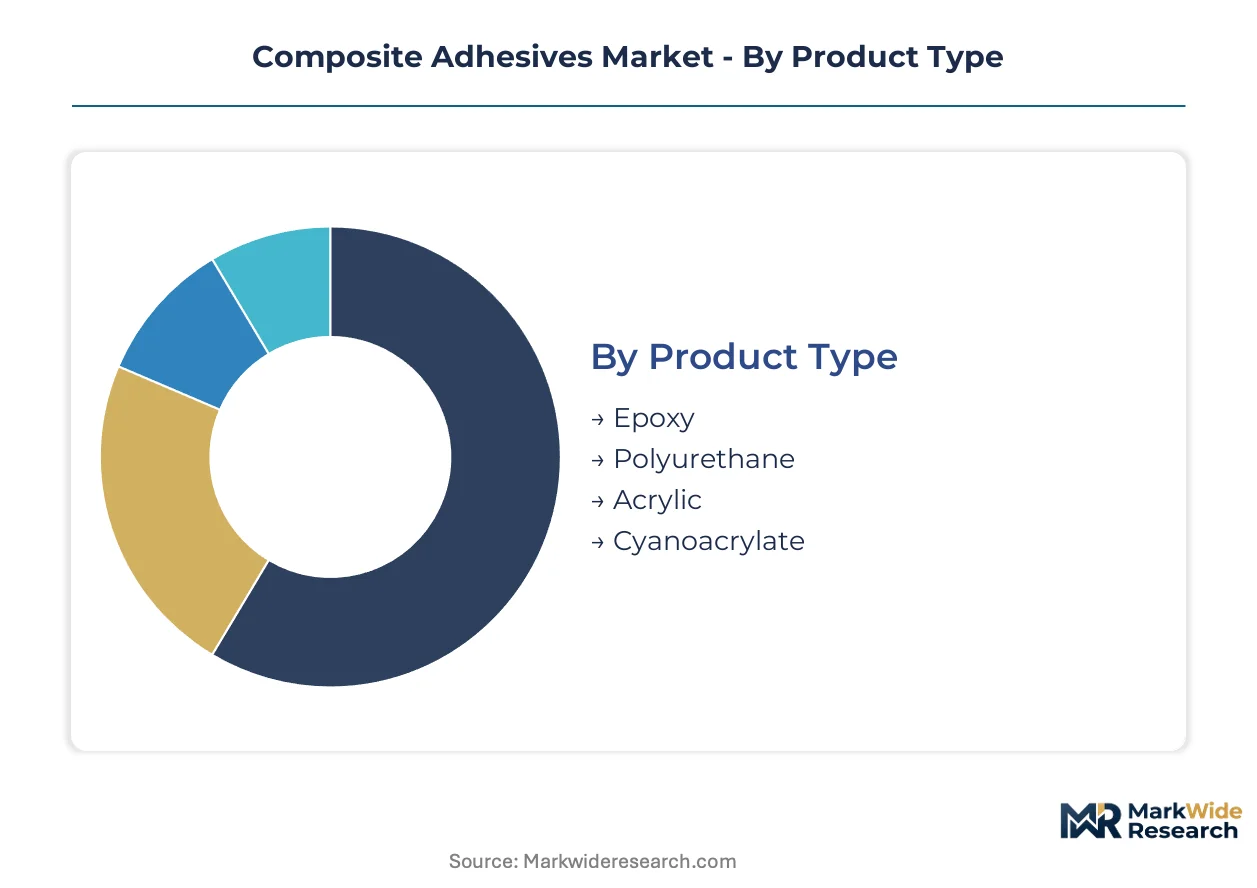
Segmentation in composite adhesives reveals how chemistry selection, cure mechanisms, and formulation complexity map to distinct capital intensity and qualification barriers across end-use verticals. Buyers optimize across lap-shear requirements, throughput constraints, and regulatory exposure rather than pursuing universal solutions.
Product Type:
Structural load paths and service temperature windows drive chemistry selection, with each resin backbone offering trade-offs between creep resistance, cure speed, and substrate compatibility.
- Epoxy:These thermoset formulations deliver lap-shear strengths exceeding 25 MPa and service temperatures to 180°C through crosslinked bisphenol-A or novolac backbones. Demand concentrates in Airbus and Boeing primary structure programs where EASA certification mandates documented cure schedules and nondestructive inspection protocols that freeze supplier tiers.
- Polyurethane:Isocyanate-terminated prepolymers bond dissimilar substrates with room-temperature curing that reduces energy inputs in high-throughput automotive lines. BMW's carbon-fiber chassis programs in Stuttgart's supplier corridor specify these systems for body-in-white applications where flexibility and impact resistance outweigh maximum thermal tolerance.
- Acrylic:UV-curable or two-part methacrylate platforms enable rapid fixture times without thermal ovens, compressing capital barriers for tier-two automotive suppliers.
- Cyanoacrylate:Instant-bonding ethyl esters serve secondary assembly and repair operations where bond line thickness remains below 0.15 mm.
Established volume favors Epoxy in aerospace qualification; emerging adoption favors Polyurethane in automotive lightweighting cycles.
End Use Industry:
Regulatory density and structural criticality separate end-use segments, with certification timelines and liability exposure shaping procurement patterns.
- Aerospace:Primary structure bonding for wings, fuselage sections, and empennage assemblies demands traceable quality systems under FAA and EASA mandates. Suppliers must integrate data-logging hardware into dispensing systems to document thermal profiles across cure cycles.
- Automotive:Battery enclosure bonding for electric vehicle platforms is climbing the fastest, with India's PLI scheme incentives creating first-mover openings for structural adhesive specification in OEM engineering programs.
- Construction:Wind turbine blade bonding anchors demand for paste adhesives with 30-year fatigue ratings, particularly in China's repowering cycle for aging onshore installations.
- Marine:Hull and deck laminations in yacht manufacturing and commercial vessel repair specify epoxy systems with moisture resistance and osmotic blister protection.
Procurement leverage concentrates in Automotive platform sharing; technical service intensity peaks in Aerospace primary structures.
Curing Method:
Capital equipment constraints and factory floor throughput targets force explicit trade-offs between energy input, cycle time, and bond performance.
- Thermal:Oven or autoclave curing remains dominant for aerospace primary structures where controlled temperature ramps ensure complete crosslinking of high-Tg epoxy formulations.
- UV:Photoinitiator-accelerated acrylic platforms are displacing thermal systems in certain automated automotive lines, virtualizing capital equipment requirements for mid-volume suppliers.
- Moisture:Alkoxy-silane or isocyanate systems cure via atmospheric humidity, enabling field application in construction and marine repair where controlled environments are unavailable.
- Anaerobic:Metal-bonding threadlockers and retaining compounds cure in the absence of oxygen, serving secondary mechanical assembly rather than primary composite lamination.
Process maturity favors Thermal in structural certification; capital virtualization favors UV in tier-two automotive adoption.
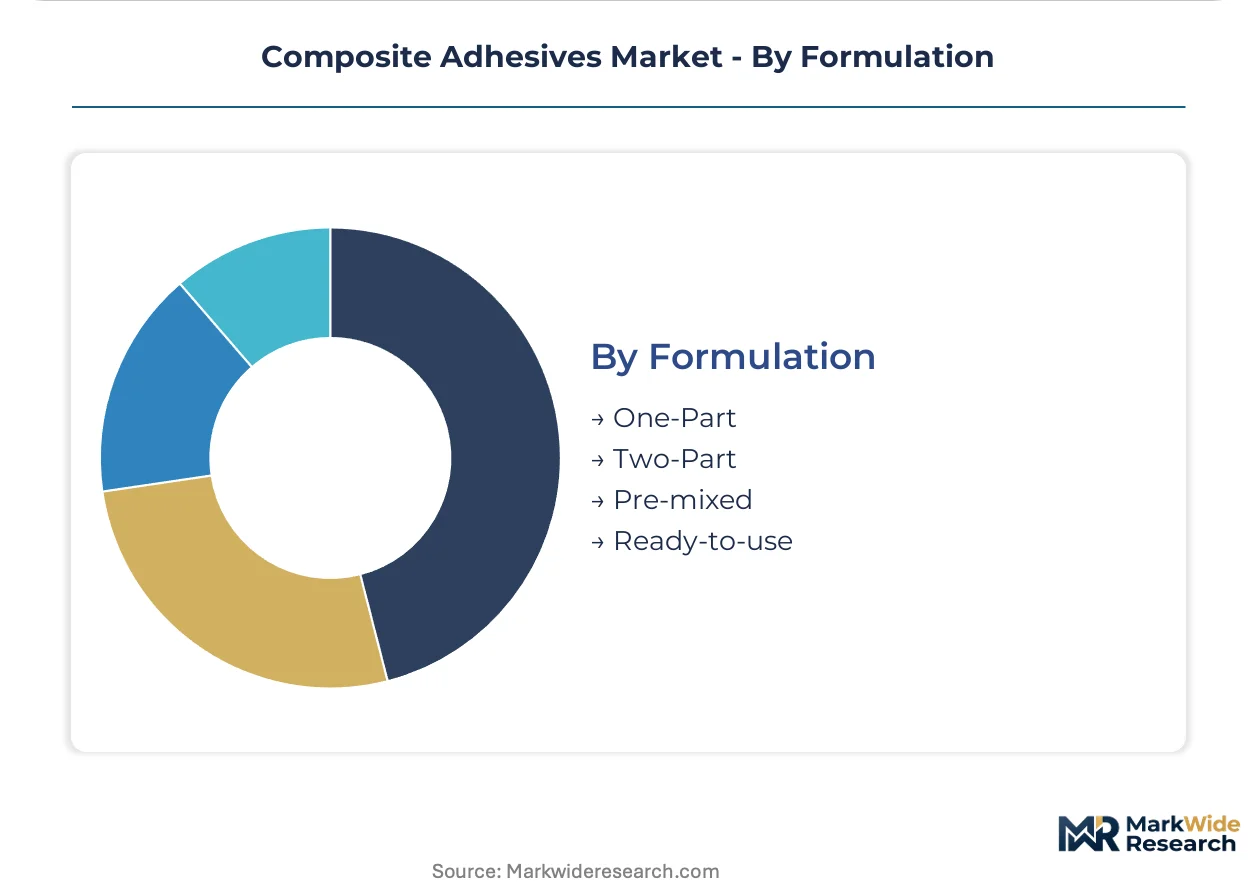
Formulation:
Mixing operations and shelf stability requirements determine logistics complexity, with single-component systems commanding premium positioning against two-part alternatives.
- One-Part:Latent hardener systems with extended shelf stability eliminate meter-mix-dispense equipment, reducing factory floor footprint by half in German and South Korean automotive plants.
- Two-Part:Base resin and hardener kits offer formulation flexibility and ambient storage, serving construction and marine segments where batch sizes vary widely.
- Pre-mixed:Factory-blended and frozen cartridges guarantee ratio accuracy for critical aerospace applications where off-ratio curing risks structural failure.
- Ready-to-use:Film adhesives with embedded microcapsulated hardeners virtualize mixing operations entirely, compressing capital barriers for electric vehicle platforms.
Operational simplicity favors One-Part in high-volume automation; ratio assurance favors Pre-mixed in aerospace qualification protocols.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German adhesive formulators export structural epoxy systems to Airbus final assembly lines in France and China, while South Korean suppliers serve Hyundai-Kia battery enclosure programs across Southeast Asian EV plants.
United States
Boeing's 787 and 777X programs in Washington State and South Carolina drive demand for EASA-traceable film adhesives with documented cure schedules. EPA enforcement under 40 CFR Part 63 Subpart HHHHH tightens VOC limits on manufacturing facilities, pushing formulators toward 100% solids chemistries. The aerospace corridor between Seattle and Charleston concentrates qualified suppliers integrating data-logging hardware into dispensing systems.
Germany
Stuttgart's automotive supplier corridor anchors BMW carbon-fiber chassis programs specifying polyurethane systems for body-in-white bonding. REACH restrictions on candidate substances of very high concern accelerate low-VOC epoxy and polyurethane formulation shifts. Wolfsburg engineering centers concentrate R&D investment in structural adhesive programs for electric vehicle platform sharing across Volkswagen Group architectures.
China
Aging onshore wind installations in Inner Mongolia and Gansu provinces generate aftermarket demand for paste adhesives with 30-year fatigue ratings in blade repair and tip-extension bonding. MIIT dual carbon goals pressure turbine OEMs toward lighter composite structures requiring advanced bonding systems. The Yangtze River Delta manufacturing belt concentrates domestic adhesive production serving both export markets and domestic wind repowering cycles.
India
PLI scheme incentives for electric vehicle manufacturing create first-mover openings for structural adhesive specification in battery enclosure bonding at Tata Motors and Mahindra facilities. BIS standards for automotive components gradually incorporate adhesive performance requirements previously absent from regulatory frameworks. The Tamil Nadu-Andhra Pradesh automotive belt near Chennai concentrates foreign supplier technical service operations supporting OEM localization programs.
Japan
Automotive platform sharing across Toyota, Honda, and Nissan architectures amplifies purchasing leverage for approved adhesive vendor lists consolidated to three suppliers per chemistry family. METI industrial standards for carbon-fiber reinforced polymer vehicle structures incorporate bonding specifications that filter supplier qualification. The Nagoya-Tokyo corridor concentrates formulation R&D serving both domestic OEMs and export markets across Southeast Asia.
Composite Adhesives Market Vendor Landscape
Channel-controlling players compete with product-specialist players across tiered qualification barriers that separate aerospace-certified suppliers from construction-grade commodity vendors. The market structure concentrates around three to four qualified suppliers per chemistry family in aerospace, while automotive segments fragment across regional formulators. Strategic archetypes include vertically integrated chemical conglomerates with captive resin supply, formulation specialists with EASA-certified quality systems, and regional construction adhesive suppliers scaling into wind energy applications. Dominant competitive moves include backward integration into epoxy resin precursors and technology licensing partnerships that bypass 18-36 month EASA certification timelines.
Within the European formulation tier, Henkel AG & Co. KGaA and Sika AG occupy positions exemplifying divergent strategic anchors—Henkel serving aerospace and automotive structural programs from German formulation centers, Sika anchoring construction-grade systems for wind turbine blade bonding. Dow represents the North American chemical conglomerate archetype with acrylic chemistry platforms positioned for automotive lightweighting cycles. These three companies illustrate how geographic origin and company structure map to distinct end-use segment concentrations without requiring specific product or financial claims.
| Leading Market Players |
|---|
| Henkel AG & Co. KGaA |
| 3M Company |
| Sika AG |
| Dow |
| Huntsman Corporation |
| H.B. Fuller |
| Illinois Tool Works Inc. |
| Bostik |
| LORD Corporation |
| Others |
Supply Flow & Price Mechanics
Undercapacity in European epoxy resin precursor facilities is compressing supplier margins and amplifying cost-pass-through leverage for bisphenol-A and epichlorohydrin producers serving aerospace formulators. This utilization squeeze forces adhesive manufacturers to absorb volatility or renegotiate annual contracts with German automotive OEMs.
Pricing Analysis
Cost-plus contracts with bisphenol-A indexation dominate raw material procurement for structural epoxy suppliers serving Airbus and Boeing programs. Price differentiation rests on EASA certification tier and volume commitment scale, with qualified aerospace suppliers commanding premiums over construction-grade commodity vendors. Pricing pressure stems from propylene feedstock volatility transmitted through epichlorohydrin supply chains. Tier-two automotive suppliers exhibit highest price sensitivity due to compressed EV platform margins, while primary aerospace contractors prioritize traceability over unit cost.
Supply Chain Analysis
Extended payment terms from 60 to 90 days are proliferating through supply-chain finance facilities backed by German automotive OEMs, straining mid-tier formulator cash conversion. Production concentrates in Germany, China, and the United States, with bisphenol-A and epoxy resin precursors drawn from petrochemical complexes in the US Gulf Coast and Northeast Asia. Single-source vulnerability runs through Taiwanese photoinitiator suppliers serving UV-curable acrylic platforms. Distribution runs through authorized distributor networks with technical service bundling for aerospace-qualified products.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
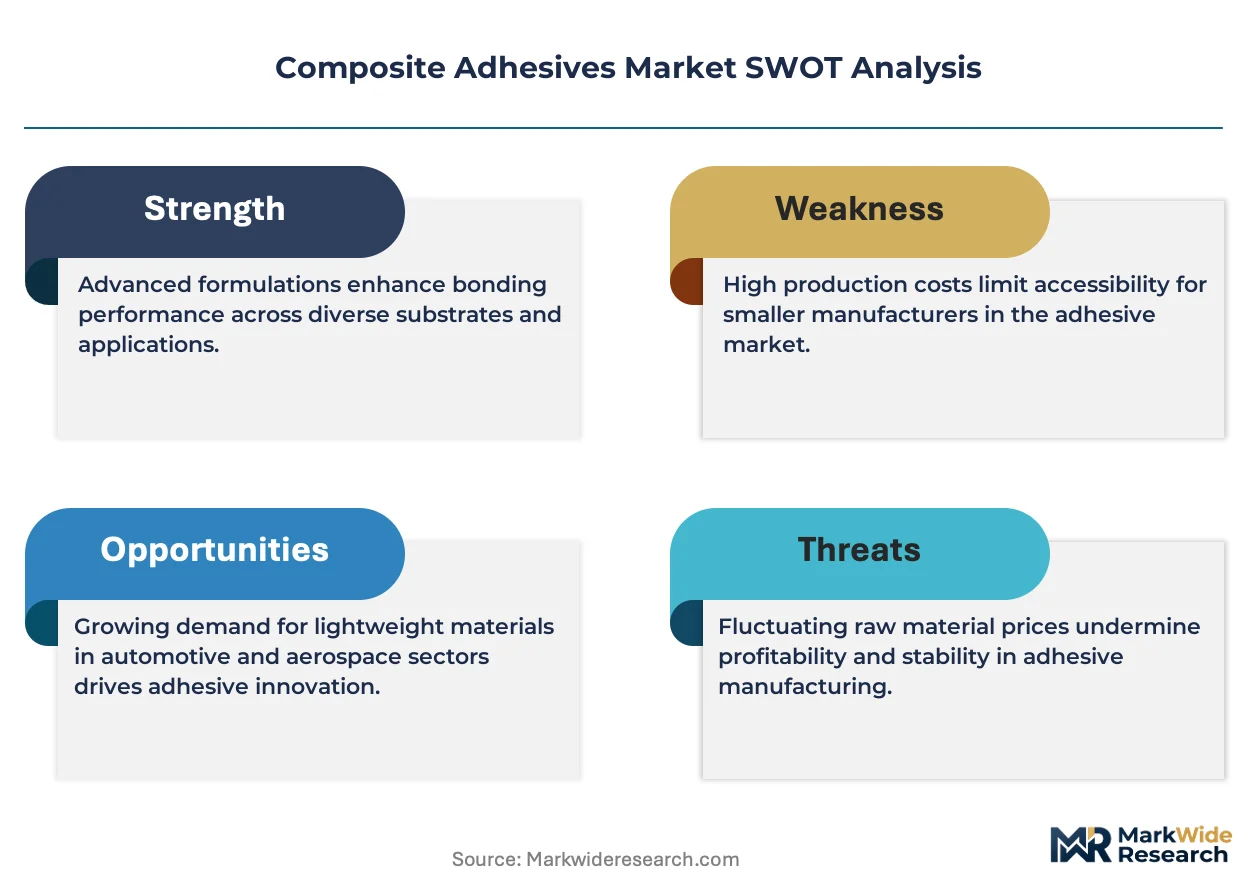
Analyst Recommendations
Platform economics are reshaping procurement as automotive OEMs consolidate approved vendor lists and demand integrated joint-design software, creating winner-take-most dynamics for adhesive suppliers with embedded technical service capabilities.
For Market Incumbents: Insulate EASA-certified positions through captive epoxy resin precursor supply or long-term offtake agreements with US Gulf Coast producers. Deepen integration of data-logging hardware into dispensing systems to lock in Boeing and Airbus program continuity against emerging Asian formulators.
For New Entrants and Emerging Players: Build out UV-curable acrylic formulation capabilities for India's PLI-subsidized EV battery enclosure programs, where qualification barriers remain lower than aerospace. Anchor initial penetration through technical partnerships with Tamil Nadu-based Tier 1 suppliers lacking in-house adhesive engineering.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among EASA-certified specialists with embedded dispensing system hardware and multi-year aerospace program contracts. Acquirers should prioritize formulators with documented cure schedule traceability and established Airbus or Boeing supply positions. The signal to watch is consolidation of German automotive approved vendor lists from twelve suppliers to three per chemistry family.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Epoxy Resins | Captive bisphenol-A supply secures margin stability against propylene volatility for aerospace formulators. |
| EASA Certification Fast-Track Partnership | Technology licensing agreements bypass 18-36 month qualification timelines for new market entrants. |
| UV Platform Expansion for EV Battery Bonding | Room-temperature cure systems virtualize thermal oven capital requirements for tier-two automotive suppliers. |
| Single-Component Film Adhesive Scale-Up | Microcapsulated hardener systems eliminate meter-mix-dispense equipment in German body-in-white programs. |
| China Wind Repowering Aftermarket Entry | Paste adhesives with 30-year fatigue ratings address blade repair demand in Inner Mongolia installations. |
Methodological Framework
The analysis maps structural epoxy, polyurethane, acrylic, and cyanoacrylate sub-sectors, each validated through procurement directors at Tier 1 automotive suppliers, EASA quality auditors, wind turbine blade engineers, and adhesive formulator R&D heads. Primary interview findings triangulate against customs trade data, Cefic chemical industry reports, SEC 10-K filings from listed suppliers, and FAA/EASA certification databases. Bottom-up volume estimates from end-use consumption patterns reconcile with top-down market sizing from resin precursor production data.
Forecast assumptions hold fixed current REACH chemical restriction timelines and EASA certification protocol durations while varying EV adoption intensity and wind repowering cycle acceleration across the projection horizon. Segmentation dimensions include chemistry family, cure mechanism, formulation type, and end-use vertical with regional production cluster overlays. CAGRs derive from regression analysis of historical volume elasticities against automotive lightweighting and aerospace bonding penetration rates, incorporating bisphenol-A price pass-through coefficients and UV platform adoption curves.
Sensitivities concentrate around petrochemical feedstock volatility, EASA certification timeline extensions, and Chinese wind repowering policy acceleration. Forecasts reflect documented assumptions about regulatory stability and technology substitution rates. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Composite Materials
Europe Aluminium Composite Panel Market
Composite Materials
Thermoset Composites Market
Composite Materials
Phenolic Panel Market
Composite Materials
Polypropylene and Polypropylene Composites Market
Composite Materials
Asia-Pacific Natural Fiber Composites Market
Composite Materials
High Performance Composites Market
Composite Materials
United States Marine Composites Market
Composite Materials
Pulp Moulding Tooling Market
Composite Materials
Global Molded FRP Grating Market
Composite Materials
PCR Laminates Market
Composite Materials
Reinforced Plastic Sheeting Market
Composite Materials
Glass Fiber Reinforced Plastic (GFRP) Market
Composite Materials
Glass Fiber Reinforced Plastics (GFRP) Composites Market
Composite Materials
High Performance Carbon Fiber Precursor Market
Composite Materials
Metal Matrix Composites (Mmcs) Market
Composite Materials
CFRTP Market