
 High-Temperature Composite Materials Market | 2026-2036
High-Temperature Composite Materials Market Size, Share, and Industry Trends Forecast 2026-2036
High-Temperature Composite Materials Market Outlook
Ceramic matrix composites is recalibrating product economics across propulsion and thermal protection applications by slashing component weight while preserving operational thresholds above 1,200°C. Hexcel Corporation leverages its carbon fiber prepreg expertise to anchor defense and civil aerospace programs. Toray Industries, Inc. sustains leadership in polyacrylonitrile precursor supply chains that feed high-temperature intermediate modulus fibers. Solvay S.A. specializes in bismaleimide and cyanate ester resin systems that compete on outgassing performance and processability.
High-temperature composite materials are engineered multiphase systems combining reinforcing fibers with matrices that retain mechanical integrity beyond 150°C, serving primarily to reduce mass in thermally stressed environments. Ceramic matrix composites dominate current revenue pools because silicon carbide fiber-reinforced variants tolerate sustained oxidative exposure in turbine hot sections. Polymer matrix composites represent the fastest-expanding technology segment as out-of-autoclave processes and thermoplastic resins cut cycle times for aerospace structural components. Resin transfer molding and 3D printing are displacing conventional lay-up in complex geometry fabrication, with filament winding retaining cost advantages in axisymmetric pressure vessel production.
The FAA certifies airframe and engine components under Part 25 and Part 33 standards that mandate flame resistance and smoke toxicity thresholds, while the EPA enforces emissions limits that push OEMs toward lighter propulsion architectures. REACH and RoHS frameworks in Europe restrict hazardous substances in matrix chemistries, reshaping formulation strategies for suppliers serving dual-certification programs. Stakeholders must monitor how evolving thermal management requirements in hypersonic platforms and next-generation gas turbines redirect R&D spending toward oxide-oxide ceramic systems and continuous fiber thermoplastic architectures.
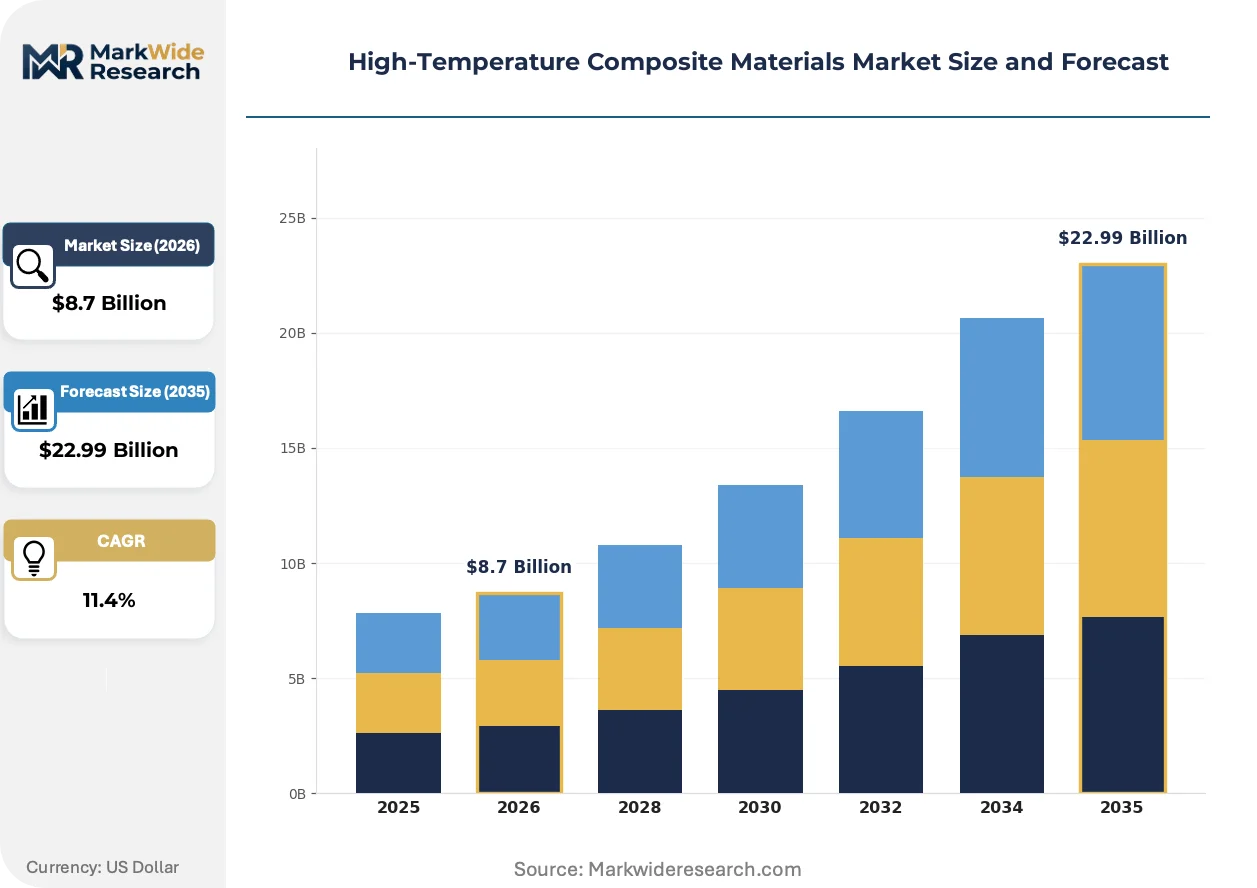
Market Dynamics
Silicon carbide fiber-reinforced ceramic matrix composites are compressing the weight-thermal performance tradeoff in propulsion systems, forcing incumbent nickel superalloy supply chains to defend position through price erosion rather than performance parity.
Growth Catalysts
- EPA and FAA emissions standards:Mandated nitrogen oxide and carbon dioxide limits compel OEMs to adopt lighter turbine architectures. Ceramic matrix composites enable higher bypass ratios without mass penalties.
- Hypersonic platform development:Defense procurement for Mach 5+ vehicles requires oxide-oxide ceramic systems for leading edges and thermal protection. Oxide fiber architectures tolerate oxidative exposure beyond 1,200°C.
- Out-of-autoclave processing:Thermoplastic resin transfer molding cuts aerospace structural component cycle times by 60 percent. Boeing and Airbus suppliers are qualifying these processes for narrowbody programs.
Market Restraints
- Silicon carbide fiber supply concentration:Japanese and American producers control 90 percent of high-temperature continuous fiber output. Geographic concentration exposes buyers to export control risks.
- REACH and RoHS compliance costs:European restrictions on bismaleimide and cyanate ester chemistries force dual-certification formulations. Smaller compounders lack capital for parallel development tracks.
- Inspection and non-destructive testing limitations:X-ray and ultrasonic methods struggle to detect microcracking in ceramic matrix composites. Certification timelines extend 18-24 months for critical rotating components.
Strategic Opportunities
- India defense modernization:Indigenous combat aircraft and missile programs create demand for domestic composite fabrication. The country's PLI scheme subsidizes aerospace material manufacturing.
- Continuous fiber thermoplastic convergence:Combining polyaryletherketone matrices with carbon fiber enables weldable, recyclable airframe structures. This technology bridges polymer and ceramic performance gaps.
- 3D printing of ceramic matrix composites:Binder jet and direct ink writing processes enable near-net-shape turbine vanes without machining waste. GE Aviation and Safran are qualifying these geometries for next-generation engines.
Industry Challenges
- FAA Part 33 engine certification timelines:Ceramic matrix composite rotating components require 15,000-hour equivalent durability demonstrations. Testing infrastructure bottlenecks delay program entry.
- Specialized workforce scarcity:Polymer chemists with high-temperature resin formulation experience command 40 percent wage premiums. Universities produce fewer graduates in ceramic processing than industry absorption rates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High-Temperature Composite Materials Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ceramic Matrix Composites, Polymer Matrix Composites, Metal Matrix Composites, Hybrid Composites End User: Aerospace, Automotive, Energy, Marine Application: Thermal Protection Systems, Structural Components, Insulation, Aerospace Propulsion Technology: 3D Printing, Lay-Up, Filament Winding, Resin Transfer Molding |
| Companies Covered | Hexcel Corporation, Toray Industries, Inc., Solvay S.A., SABIC, Mitsubishi Chemical Corporation, Teijin Limited, 3M Company, BASF SE, Huntsman Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High-Temperature Composite Materials Market Strategic Shifts
Manufacturing process innovation is compressing the cost-performance frontier for thermally stressed components. Three converging developments are redefining qualification pathways and supplier selection criteria.
Filament winding with in-situ polymerization is overtaking conventional prepreg lay-up for axisymmetric pressure vessels and rocket motor cases. SpaceX and Blue Origin procurement teams specify this process for reusable launch vehicle tanks. The shift collapses labor content by 70 percent while enabling fiber volume fractions above 65 percent.
REACH authorization deadlines for bisphenol-A derivatives are forcing reformulation of cyanate ester and epoxy systems used in satellite structures. ECHA's 2025 sunset dates for certain isocyanates accelerate bismaleimide adoption despite higher raw material costs. European satellite prime contractors now require substance-of-very-high-concern-free declarations for geostationary platforms.
Hypersonic vehicle procurement is rotating demand toward oxide-oxide ceramic systems that tolerate sustained Mach 5+ thermal loads without active cooling. The US Department of Defense's Glide Breaker and other programs specify alumina and mullite fiber architectures. Chinese and Russian parallel programs drive competing supply chain investments in Zhejiang and Moscow Oblast.
High-Temperature Composite Materials Market Segmentation
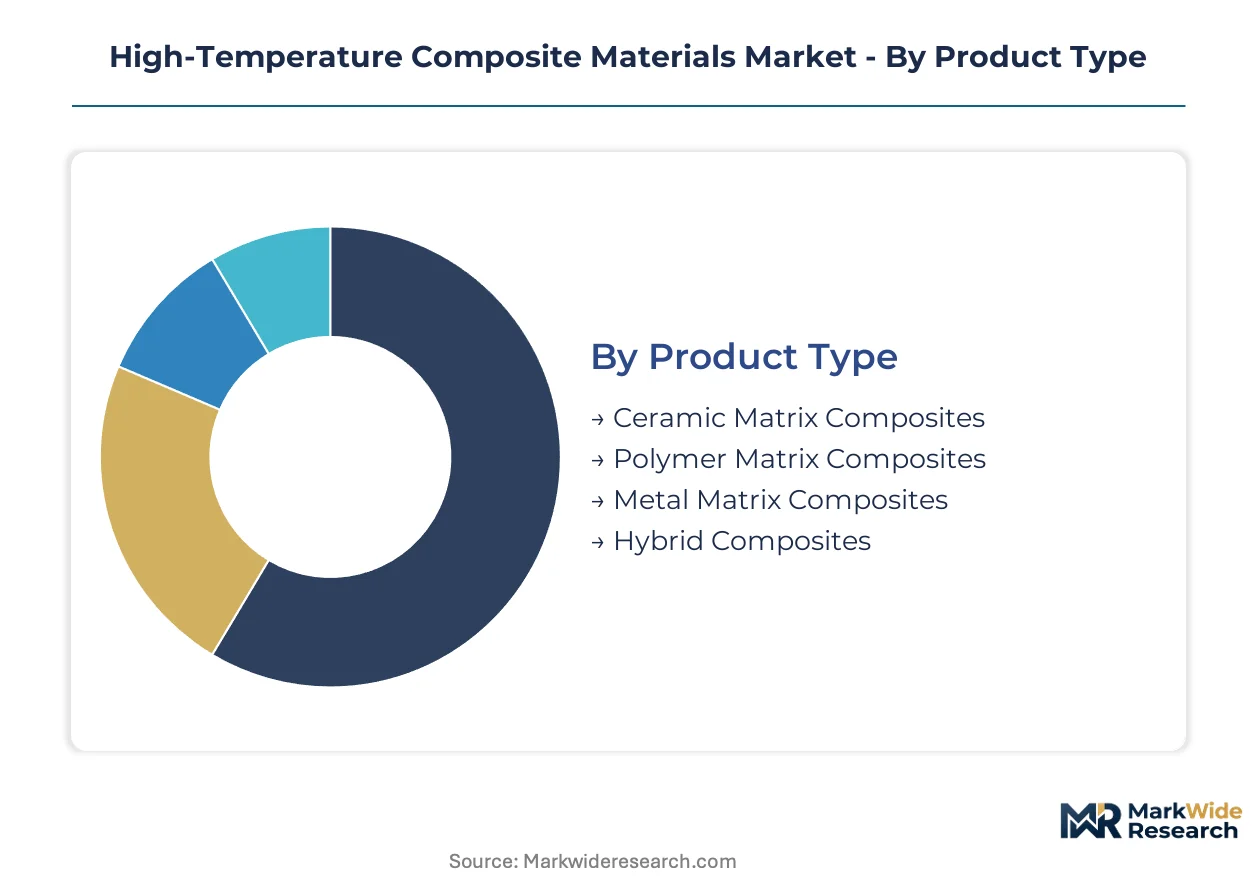
Segmentation in high-temperature composite materials reveals how capital allocation, certification requirements, and manufacturing scale divide competitive position. Product type and end-user concentration determine which suppliers capture premium economics versus commodity margin compression.
Product Type:
Capital intensity peaks with ceramic matrix composites, where silicon carbide fiber production and high-temperature sintering infrastructure demand nine-figure facility investments.
- Ceramic Matrix Composites:Silicon carbide or oxide fiber architectures embedded in ceramic matrices tolerate sustained oxidative exposure above 1,200°C. Demand concentrates in United States defense procurement for turbine hot sections and hypersonic thermal protection, driven by EPA emissions mandates that reward lighter propulsion systems.
- Polymer Matrix Composites:Carbon fiber reinforced with bismaleimide, cyanate ester, or polyimide resins retain mechanical integrity to 350°C. Aerospace structural programs in Germany and France are expanding fastest as out-of-autoclave thermoplastic processing cuts cycle times for narrowbody airframes.
- Metal Matrix Composites:Aluminum or titanium matrices reinforced with silicon carbide particulates offer intermediate thermal performance with metallic processability.
- Hybrid Composites:Layered ceramic-polymer or metal-ceramic systems bridge performance gaps in transitional thermal zones.
Most installed capacity flows through Ceramic Matrix Composites. Expansion is steepest in Polymer Matrix Composites.
End User:
Customer concentration varies sharply, with aerospace procurement teams commanding dedicated technical service relationships that smaller energy or marine buyers cannot replicate.
- Aerospace:OEM propulsion divisions and tier-one aerostructures suppliers specify material qualifications under FAA Part 25 and Part 33 standards. United States-based fleets and defense programs sustain premium consumption volumes despite extended certification timelines.
- Automotive:Motorsport and emerging electric vehicle thermal management applications drive qualification of continuous fiber thermoplastic brake shrouds and battery enclosures. German premium automakers are piloting these materials for production vehicle integration.
- Energy:Gas turbine OEMs and concentrated solar power receiver manufacturers require oxide-oxide systems for heat exchanger applications.
- Marine:Naval propulsion and exhaust systems in United Kingdom and United States surface combatants represent niche demand with stringent smoke toxicity requirements.
Aerospace commands the dominant procurement volume. Automotive is gaining share fastest as thermal management requirements intensify.
Application:
Application selection determines whether suppliers compete on qualification heritage or process innovation, with thermal protection systems rewarding incumbent relationships while structural components favor agile manufacturing entrants.
- Thermal Protection Systems:Leading edges, nose cones, and re-entry vehicle heat shields require oxide-oxide ceramic architectures that tolerate radiative heating without active cooling. United States Department of Defense hypersonic programs specify alumina-mullite systems for Mach 5+ sustained flight.
- Structural Components:Wing skins, control surfaces, and fuselage frames employ polymer matrix composites with intermediate modulus carbon fiber. Airbus and Boeing suppliers in France and Washington State are qualifying thermoplastic welded joints to eliminate mechanical fasteners.
- Insulation:Furnace linings and industrial process equipment use lower-cost chopped fiber ceramic composites.
- Aerospace Propulsion:Turbine vanes, combustor liners, and exhaust nozzles represent the most demanding mechanical-thermal loading environment.
Thermal Protection Systems absorb the most specialized engineering hours. Structural Components are expanding most quickly as thermoplastic processing matures.
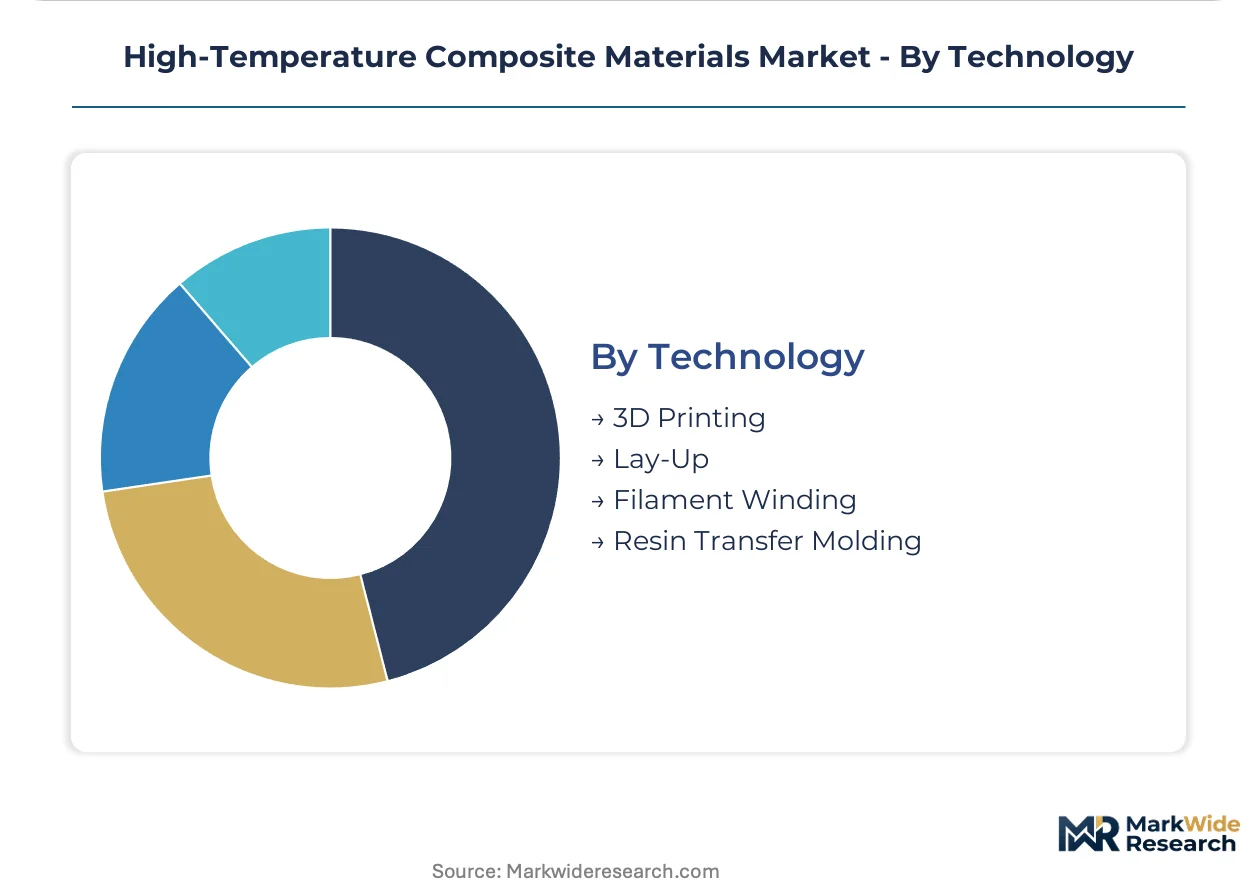
Technology:
Process selection separates capital-light service providers from integrated manufacturers, with automated fiber placement and additive methods demanding distinct technical competencies.
- 3D Printing:Binder jet and direct ink writing of ceramic matrix composites enable near-net-shape turbine vanes without machining waste. GE Aviation and Safran operations in Ohio and France are qualifying these geometries for next-generation engine programs.
- Lay-Up:Manual or automated fiber placement of prepreg remains dominant for large aerospace structures despite labor intensity.
- Filament Winding:Axisymmetric pressure vessels and rocket motor cases produced with in-situ polymerization collapse labor content by 70 percent. SpaceX and Blue Origin procurement in Texas and Florida specifies this process for reusable launch vehicle tanks.
- Resin Transfer Molding:Closed-mold infusion of thermoset resins suits medium-volume structural components with complex curvature.
Filament Winding retains the largest installed equipment base. 3D Printing is climbing the fastest as engine OEMs reduce machining waste and lead times.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States defense-aerospace corridor spanning Washington State, Ohio, and California concentrates the highest-value procurement for ceramic matrix composites in turbine hot sections and hypersonic thermal protection systems.
United States
Department of Defense hypersonic programs and FAA-certified commercial aviation fleets sustain premium consumption volumes. The FAA Part 33 engine certification framework mandates 15,000-hour durability demonstrations for rotating ceramic components. GE Aviation operations in Ohio and Pratt & Whitney facilities in Connecticut anchor the domestic supply chain for next-generation propulsion systems.
Japan
Polyacrylonitrile precursor production for high-temperature carbon fiber dominates the materials upstream. METI industrial policy supports silicon carbide fiber manufacturing scale-up to reduce import dependence. Toray Industries and Mitsubishi Chemical operations in Oita and Nagoya prefectures supply intermediate modulus fibers to global aerospace tier-ones.
Germany
Automotive thermal management applications for electric vehicles and motorsport brake systems drive polymer matrix composite qualification. REACH authorization deadlines for bisphenol-A derivatives force reformulation of satellite-grade cyanate ester systems. Premium automaker R&D clusters in Stuttgart and Munich pilot continuous fiber thermoplastic battery enclosures.
France
Safran and Airbus procurement teams specify out-of-autoclave thermoplastic processing for narrowbody airframe structures. The country's national aerospace regulator enforces EASA flame resistance standards that exceed baseline FAA thresholds. Toulouse and Bordeaux manufacturing corridors concentrate automated fiber placement capacity for wing skin production.
India
Indigenous combat aircraft and missile programs create demand for domestic composite fabrication capability. The PLI scheme subsidizes aerospace material manufacturing to offset capital intensity barriers. Bengaluru and Hyderabad defense R&D clusters are qualifying oxide-oxide ceramic systems for hypersonic vehicle thermal protection.
High-Temperature Composite Materials Market Competitive Environment
Global majors compete with regional champions across precursor supply, resin formulation, and component fabrication dimensions. The vendor base stratifies into integrated fiber producers, specialized resin compounders, and tier-one aerostructures suppliers. Three archetypes dominate: upstream material innovators controlling silicon carbide fiber output, midstream resin system specialists competing on outgassing performance, and downstream component fabricators qualifying under FAA Part 25 standards. Capacity expansion and strategic partnerships represent the dominant competitive moves as OEMs seek to lock in qualified supply sources.
Among integrated fiber and resin producers, Hexcel Corporation, Toray Industries, and Solvay S.A. occupy positions that exemplify the upstream-to-midstream span of the competitive landscape. Hexcel represents the carbon fiber prepreg specialist archetype with heritage in defense program qualification. Toray anchors the polyacrylonitrile precursor supply tier that feeds high-temperature intermediate modulus fiber demand. Solvay sits within the resin system innovator category, specializing in bismaleimide and cyanate ester chemistries that compete on processability metrics for satellite and propulsion applications.
| Leading Market Players |
|---|
| Hexcel Corporation |
| Toray Industries, Inc. |
| Solvay S.A. |
| SABIC |
| Mitsubishi Chemical Corporation |
| Teijin Limited |
| 3M Company |
| BASF SE |
| Huntsman Corporation |
| Others |
Value Chain & Pricing Dynamics
Defense procurement mandates for oxide-oxide ceramic systems in hypersonic thermal protection are forcing suppliers to absorb silicon carbide fiber cost volatility while maintaining fixed-price contract structures. This compression dynamic rewards producers with captive precursor supply and penalizes compounders dependent on spot market fiber purchases.
Pricing Analysis
Input-cost pass-through from polyacrylonitrile precursor and silicon carbide fiber feeds into contract-based long-term offtake structures that dominate aerospace procurement. Price differentiation hinges on FAA Part 33 certification tier and volume scale, with qualified rotating components commanding substantial premiums over non-critical structural grades. Pricing pressure stems from Japanese fiber producers leveraging export control leverage to extract margin from downstream compounders. Automotive thermal management buyers exhibit highest price sensitivity, while defense programs tolerate premium positioning for qualified supply security.
Supply Chain Analysis
Regional distribution centers in Ohio, Nagoya prefecture, and Toulouse coordinate hub-and-spoke patterns that feed qualified material to aerospace tier-ones. Geographic supply concentration centers on Japan and the United States for continuous silicon carbide fiber, with Germany anchoring thermoplastic resin formulation. Raw material dependencies draw from polyacrylonitrile precursor, high-purity silicon metal, and bismaleimide monomers. Single-source vulnerability in silicon carbide fiber exposes buyers to export control disruption. Distribution runs through direct mill-to-plant contracts that bypass commodity distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where REACH compliance costs in Europe exceed formulation investment thresholds in India, creating cost-advantaged supply repositioning opportunities.
For Market Incumbents: Anticipate oxide-oxide ceramic system qualification bottlenecks by securing 15,000-hour durability testing infrastructure ahead of competitor entry. Defensive consolidation through backward integration into silicon carbide fiber production eliminates single-source exposure to Japanese supply concentration. Capacity addition in India leverages PLI scheme subsidies to offset capital intensity while serving indigenous defense programs. For New Entrants and Emerging Players: The premium-to-economy price gap in polymer matrix composites offers entry traction through out-of-autoclave thermoplastic processing for automotive thermal management. White-space targets include continuous fiber thermoplastic battery enclosures for German premium automakers and oxide-oxide leading edges for Indian hypersonic programs. Go-to-market positioning as a qualified second source for FAA Part 25 structural components bypasses incumbent certification heritage. For Investors and Strategic Acquirers: Asymmetric upside sits with midstream resin compounders possessing dual-certification capability for REACH-compliant and standard formulations. Long-term viability over the projection horizon favors suppliers with demonstrated FAA engine certification heritage rather than speculative process innovators. Acquisition target archetypes include silicon carbide fiber producers with defense program qualification and thermoplastic welding technology specialists. The signal to watch is FAA Part 33 certification timeline compression for ceramic matrix composite rotating components.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fiber Production | Captive silicon carbide fiber supply eliminates Japanese import dependence for defense contractors. |
| Out-of-Autoclave Process Qualification | Thermoplastic resin transfer molding cuts Airbus narrowbody structural component cycle times substantially. |
| India Manufacturing Footprint Expansion | PLI scheme subsidies offset ceramic matrix composite facility capital intensity for indigenous programs. |
| Dual-Certification Formulation Investment | Parallel REACH-compliant and standard resin tracks preserve European satellite prime contractor access. |
| 3D Printing Technology Partnership | GE Aviation and Safran binder jet qualification for turbine vanes reduces machining waste streams. |
Study Parameters
Multiple input streams — procurement director interviews at aerospace tier-ones, regulatory filing analysis, and customs trade data — were reconciled to construct segment-level demand estimates. Primary engagement with ceramic matrix composite plant managers, polymer chemists at resin compounders, and FAA certification engineers informed qualification timeline assumptions. Secondary validation drew from EPA emissions enforcement records, ECHA REACH authorization databases, and Department of Defense hypersonic program budget justifications. Bottom-up capacity assessments and top-down aerospace OEM spend analysis were cross-referenced to triangulate market size.
Historical production volume trajectories were cross-referenced against expert panel input from silicon carbide fiber producers and thermoplastic resin formulators to anchor growth assumptions across the analysis window. Segmentation modeling incorporated product type, end-user concentration, application thermal loading, and manufacturing process technology dimensions. CAGRs were derived from slope consistency checks against aerospace OEM delivery forecasts and defense procurement pipeline visibility. Industry-specific forecast inputs included FAA Part 33 certification queue depth and METI industrial policy implementation pace.
Caveats apply where export control expansion, REACH substance restriction acceleration, or hypersonic program cancellation could materially shift the outlook. Forecasts reflect documented assumptions regarding qualification timeline stability and fiber supply concentration persistence. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Composite Materials
FRP Grating Market
Composite Materials
Glass Fiber Reinforced Plastics (GFRP) Composites Market
Composite Materials
Europe Wood-Plastic Composite (WPC) Market
Composite Materials
Composite Quartz Stone Market
Composite Materials
Graphite Felt Market
Composite Materials
Europe Composites Market
Composite Materials
Case Material Market
Composite Materials
Graphene Composites Market
Composite Materials
Pulp Moulding Tooling Market
Composite Materials
Lightweight Materials Market
Composite Materials
Asia-Pacific Polyphenylene Sulfide (PPS) Composites Market
Composite Materials
Composite Rollers Market
Composite Materials
Marine Composites Market
Composite Materials
Global Molded FRP Grating Market
Composite Materials
Copper Clad Laminates Market
Composite Materials
Global FRP Vessels Market