
 Pressure Vessel Composite Materials Market | 2026-2036
Pressure Vessel Composite Materials Market Size, Share, and Industry Trends Forecast 2026-2036
Pressure Vessel Composite Materials Market Intelligence
Market Dynamics
Software-defined pressure monitoring and predictive maintenance subscriptions is broadening the commercial scope beyond raw material supply. Solvay leverages its upstream resin chemistry portfolio to capture margin from epoxy formulations tailored for filament-wound hydrogen tanks. Mitsubishi Heavy Industries anchors its position through integrated vessel engineering services that bundle composite procurement with certification support. Hexagon Composites dominates the Type IV cylinder segment by controlling proprietary liner-to-composite interface technology that reduces permeation failure modes.
Technical Landscape
Pressure vessel composite materials combine fiber reinforcements—typically carbon fiber or glass fiber—with thermosetting or thermoplastic matrices to fabricate cylindrical or spherical containers engineered to withstand internal pressures exceeding 350 bar in hydrogen service. Filament winding remains the predominant manufacturing method for high-performance vessels, producing helical and hoop wound layers with precise fiber angle control to optimize burst strength-to-weight ratios. Thermosetting composites, particularly epoxy-based prepregs, currently lead product type demand due to established qualification databases under ISO 11119 and UN ECE R134. Filament winding as a fabrication method commands the deepest margin pools because equipment specialization and operator certification create defensible competitive barriers.
Regulatory Environment
ASME Section X and ISO 11119-2 govern composite pressure vessel design and testing in North America and international trade respectively, while UN ECE R134 specifically regulates hydrogen tank safety for automotive applications in Europe and aligned markets. These frameworks mandate extensive cycle testing and damage tolerance protocols that extend product development timelines and favor incumbent suppliers with accumulated certification capital. Stakeholders must monitor evolving harmonization between regional hydrogen infrastructure codes, as divergent tank-to-nozzle interface standards threaten to fragment procurement specifications across national buildout programs.
Market Dynamics
Filament winding equipment specialization is concentrating manufacturing capability among certified operators, creating a supply bottleneck that favors incumbents with accumulated ASME Section X qualification capital over new market entrants.
Growth Catalysts
- UN ECE R134 automotive mandates:European hydrogen fuel cell vehicle rollout is compressing procurement timelines for Type IV composite tanks across Germany, France, and the Netherlands.
- Carbon fiber tow supply expansion:Toray and Hexcel capacity additions in the US and Japan are stabilizing input costs for high-performance pressure vessel prepregs.
- 350-bar to 700-bar service pressure migration:Heavy-duty trucking and maritime applications are demanding thicker laminate designs that multiply material intensity per vessel.
Market Restraints
- Epoxy resin price volatility:Bisphenol-A and amine hardener feedstock fluctuations compress margins for filament winding shops without resin formulation in-house.
- Carbon fiber supply concentration:Japanese and US producers control 80% of aerospace-grade tow capacity, exposing hydrogen tank manufacturers to allocation risk during aerospace demand surges.
- Thermoplastic composite qualification gaps:ISO 11119-2 lacks established cycle databases for PA6 and PEEK matrices, extending development timelines versus epoxy baselines.
Strategic Opportunities
- India hydrogen hub buildout:Reliance Industries and Indian Oil Corporation refueling infrastructure tenders are opening procurement channels for Type IV tank suppliers with localized liner production.
- Software-defined pressure monitoring:Predictive maintenance subscriptions bundled with vessel supply are shifting revenue models from material sales to recurring service streams.
- Maritime ammonia storage retrofits:Dual-fuel vessel conversions are creating demand for spherical composite tanks rated to 50 bar with corrosion-resistant liner systems.
Industry Challenges
- ASME Section X inspector certification scarcity:The limited pool of qualified NDE technicians for composite pressure vessels extends factory acceptance testing queues by 8-12 weeks.
- Liner-to-composite interface IP complexity:Proprietary surface treatment patents held by incumbent cylinder manufacturers create licensing barriers for new tank designs.
Report Scope
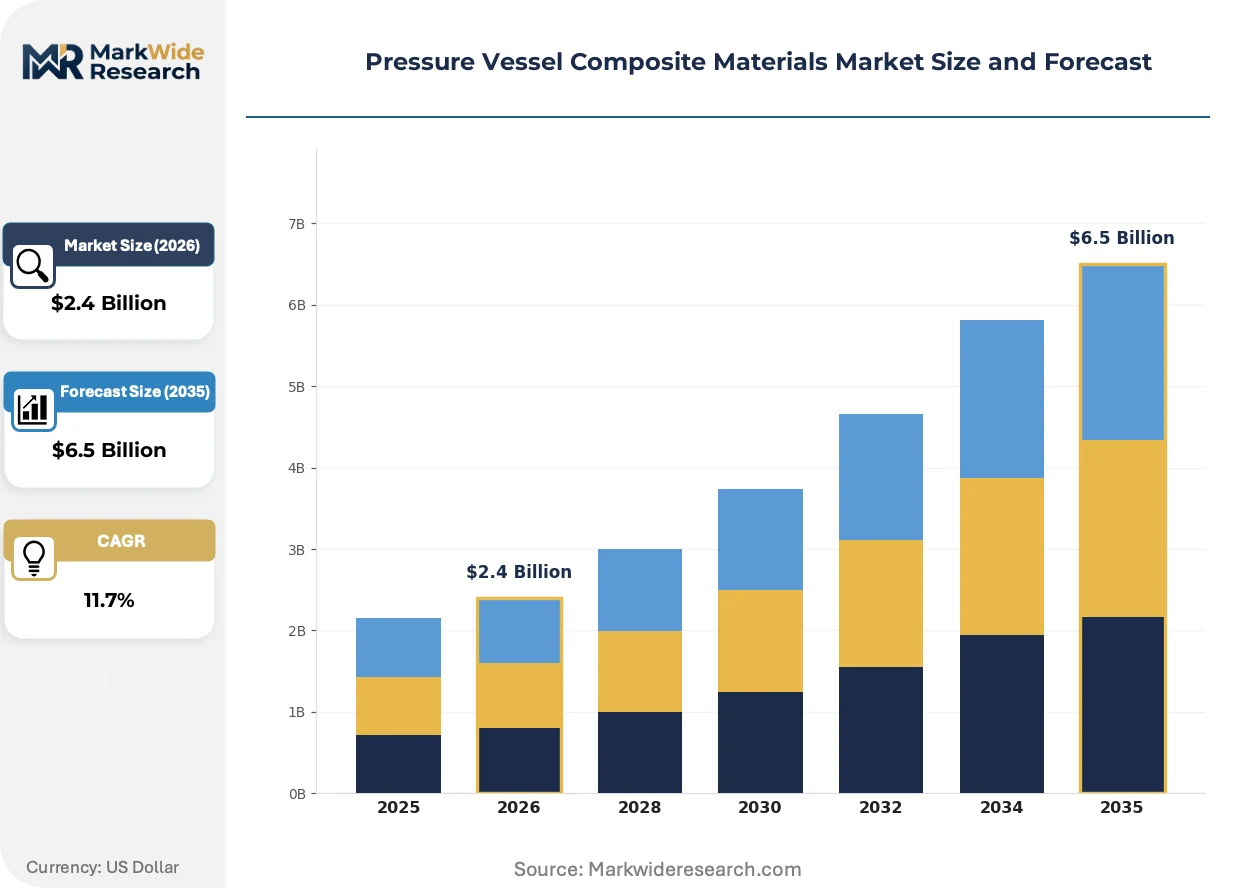
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pressure Vessel Composite Materials Market |
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $6.5 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thermosetting Composites, Thermoplastics, Hybrid Composites, Prepregs End User: Aerospace, Chemical Processing, Oil & Gas, Water Treatment Fabrication Method: Filament Winding, Open Molding, Autoclave Curing, Compression Molding Matrix Type: Epoxy, Polyester, Vinyl Ester, Phenolic, Others |
| Companies Covered | Solvay, Mitsubishi Heavy Industries, Hexagon Composites, Larsen & Toubro Limited, IHI Corporation, Steelhead Composites, Doosan Heavy Industries & Construction, Pentair, Huntsman Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pressure Vessel Composite Materials Market Strategic Shifts & Innovations
Thermoplastic composite welding and automated fiber placement are displacing conventional thermoset filament winding in next-generation vessel programs, compressing cure cycles and enabling in-situ repairability.
Automated fiber placement is converging with in-situ thermoplastic consolidation to produce hydrogen pressure vessels with weldable, inspectable seams that eliminate adhesive bondlines. Automotive OEMs in Germany and South Korea are piloting AFP-manufactured tanks for 2027 model year fuel cell platforms. This manufacturing shift is converging with real-time ultrasonic monitoring to compress qualification timelines and reduce scrap rates in high-volume production environments.
REACH restriction proposals on bisphenol-A derivatives are forcing epoxy formulators to accelerate bio-based hardener development ahead of 2026 sunset reviews. Solvay and Huntsman have initiated substitution programs for hydrogen tank prepregs using lignin-derived curing agents. The regulatory pressure is most acute in European automotive supply chains, where OEMs are requiring BPA-free material declarations to preempt downstream liability.
Buyer consolidation among hydrogen refueling station operators is compressing vendor qualification lists and unbundling aftermarket inspection services from initial tank supply contracts. Linde and Air Liquide are centralizing procurement across their European station networks, favoring suppliers with multi-country service infrastructure. This pattern is most visible in Germany, where H2 Mobility Deutschland's standardized tank specifications are displacing project-specific engineering across the national network buildout.
Pressure Vessel Composite Materials Market Segmentation
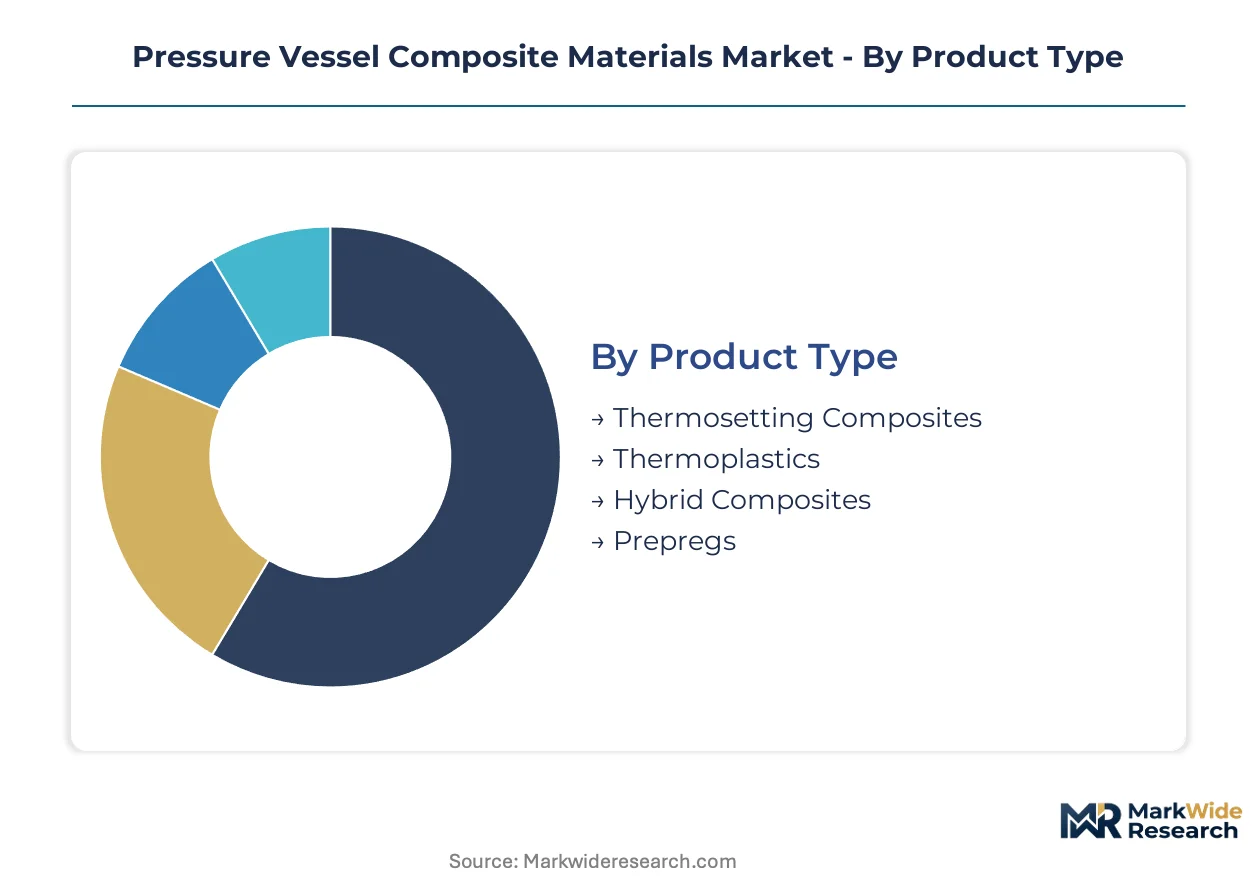
Segmentation in pressure vessel composite materials reflects divergent qualification pathways and manufacturing capital intensity. Each axis—product chemistry, end-use certification, fabrication method, and matrix formulation—carries distinct margin structures and competitive barriers.
Product Type:
Material chemistry governs thermal stability, cycle life, and regulatory acceptance in high-pressure hydrogen containment.
- Thermosetting Composites:Epoxy-based systems with carbon fiber reinforcement dominate current hydrogen tank production due to extensive ISO 11119 qualification databases. Demand concentrates in Germany's automotive fuel cell programs where UN ECE R134 mandates established material certifications.
- Thermoplastics:PA6 and PEEK matrices enable weldable seams and in-situ repairability, compressing manufacturing cycle times versus thermoset alternatives. South Korean automotive OEMs are piloting AFP-manufactured thermoplastic tanks for next-generation fuel cell platforms, though ISO 11119-2 cycle databases remain under development.
- Hybrid Composites:Combining thermoset and thermoplastic layers optimizes cost-performance for industrial gas containment below 200 bar.
- Prepregs:Resin-impregnated fiber tows streamline filament winding operations for aerospace-grade vessel production.
Thermosetting composites lead on scale; thermoplastics lead on momentum.
End User:
Application-specific pressure ratings and safety factors fragment procurement specifications across industrial verticals.
- Aerospace:FAA-certified COPV designs for spacecraft propulsion command premium pricing due to zero-failure tolerance and extensive NDE documentation requirements.
- Chemical Processing:Corrosion-resistant FRP vessels for chlorine and acid storage represent mature demand with standardized ASME RTP-1 specifications.
- Oil & Gas:Subsea composite risers and buoyancy modules require deepwater pressure ratings that concentrate procurement among Norwegian and Brazilian offshore contractors.
- Water Treatment:FRP pressure vessels for reverse osmosis membranes compete primarily on manufacturing scale and logistics proximity.
Aerospace commands margin premiums; oil and gas presents the steepest expansion trajectory for deepwater applications.
Fabrication Method:
Equipment specialization and operator certification create tiered competitive barriers across manufacturing approaches.
- Filament Winding:Computer-controlled fiber placement produces helical and hoop wound layers with precise angle optimization for burst strength-to-weight ratios. The method captures the deepest margin pools in hydrogen tank production due to ASME Section X inspector certification scarcity that extends factory acceptance queues.
- Open Molding:Hand lay-up techniques serve low-pressure industrial vessels where labor cost arbitrage outweighs automation benefits.
- Autoclave Curing:High-pressure thermal consolidation produces aerospace-grade laminates with void content below 1% for satellite propulsion tanks.
- Compression Molding:Matched-die forming enables high-volume production of standardized industrial pressure vessel components.
Filament winding dominates value capture; autoclave curing defends aerospace positioning.
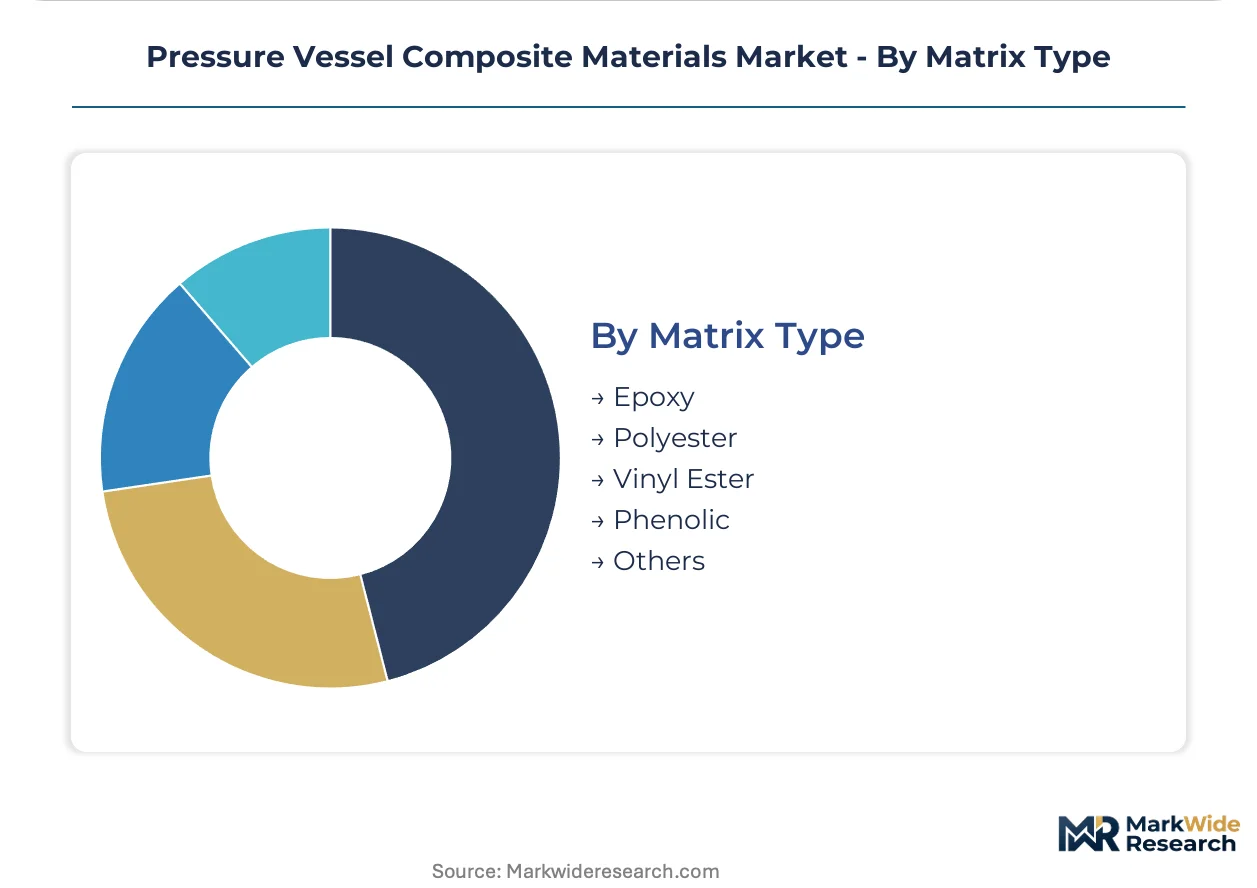
Matrix Type:
Resin chemistry selection balances chemical resistance, cure kinetics, and regulatory compliance timelines.
- Epoxy:Superior adhesion to carbon fiber and established hydrogen permeation resistance make this the default for Type IV automotive tanks. REACH restriction proposals on bisphenol-A derivatives are accelerating bio-based hardener substitution programs among European formulators.
- Polyester:Lower cost and faster cure cycles serve corrosion-resistant industrial vessels where thermal performance requirements moderate.
- Vinyl Ester:Enhanced chemical resistance versus polyester captures demand in chlorine processing and wastewater treatment applications.
- Phenolic:Fire-resistant properties meet offshore platform safety codes for hydrocarbon containment.
- Others:Cyanate ester and bismaleimide formulations address extreme temperature aerospace requirements.
Epoxy leads on revenue concentration; vinyl ester gains share fastest in chemical processing retrofits.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany compresses procurement timelines for Type IV hydrogen tanks faster than Japan stabilizes carbon fiber input costs, revealing divergent regional pacing across hydrogen infrastructure buildouts.
United States
ASME Section X inspector certification scarcity extends factory acceptance testing queues by 8-12 weeks, tightening qualification requirements for fiber-reinforced pressure vessels. EPA and DOT coordinate with NHTSA on hydrogen tank safety protocols for heavy-duty trucking corridors. Houston anchors subsea composite riser demand as Norwegian and Brazilian offshore contractors concentrate deepwater procurement.
Germany
H2 Mobility Deutschland standardizes tank specifications across national refueling networks, displacing project-specific engineering. KBA enforces UN ECE R134 mandates for automotive fuel cell platforms. Bavaria hosts automotive OEM pilot programs for 2027 model year thermoplastic tank manufacturing.
China
MIIT accelerates GB standards development for 700-bar hydrogen service pressure migration in heavy-duty applications. Dual carbon goals compress timelines for composite pressure vessel qualification in fuel cell bus fleets. Yangtze River Delta concentrates filament winding equipment manufacturing for domestic tank producers.
Japan
METI stabilizes carbon fiber tow supply through Toray capacity additions, reducing allocation risk for aerospace-grade pressure vessel prepregs. JIS standards govern composite vessel design for spacecraft propulsion applications. Nagoya anchors integrated vessel engineering services bundling composite procurement with certification support.
India
Reliance Industries and Indian Oil Corporation refueling infrastructure tenders open procurement channels for Type IV tank suppliers with localized liner production. BIS develops hydrogen storage standards aligned with ISO 11119 frameworks. Gujarat concentrates industrial gas containment demand for chemical processing retrofits.
Pressure Vessel Composite Materials Market Key Industry Players
Top-tier vendors anchor filament winding certification capital, while mid-tier fabricators compete on equipment specialization and operator training. The market concentrates manufacturing capability among ASME-qualified incumbents, creating supply bottlenecks that extend factory acceptance queues. Two strategic archetypes dominate: integrated engineering services bundling procurement with certification support, and resin chemistry specialists capturing margin from tailored epoxy formulations. Dominant competitive moves include strategic partnerships for liner-to-composite interface technology and geographic expansion toward hydrogen hub buildouts.
Within the integrated engineering tier, Mitsubishi Heavy Industries and Larsen & Toubro Limited exemplify bundled service models that combine composite procurement with regulatory navigation. Solvay occupies a position among resin chemistry specialists, leveraging upstream formulation capabilities to capture margin from hydrogen tank prepregs. Hexagon Composites anchors the proprietary interface technology segment, representing defensible competitive positioning through accumulated intellectual property in permeation reduction.
| Leading Market Players |
|---|
| Solvay |
| Mitsubishi Heavy Industries |
| Hexagon Composites |
| Larsen & Toubro Limited |
| IHI Corporation |
| Steelhead Composites |
| Doosan Heavy Industries & Construction |
| Pentair |
| Huntsman Corporation |
| Others |
Cost & Logistics Intelligence
Private-equity-rolled-up filament winding specialists in Germany and the United States have consolidated regional manufacturing footprints, tightening supply discipline while compressing procurement timelines for automotive OEMs seeking Type IV hydrogen tank certification. This ownership concentration amplifies pricing power among ASME Section X-qualified incumbents and extends factory acceptance queues by constraining certified operator availability.
Pricing Analysis
Capacity additions in Japan and the United States are reshaping price floors for aerospace-grade carbon fiber tow, yet epoxy resin volatility from bisphenol-A feedstock fluctuations sustains margin pressure on mid-tier filament winding shops. Three-tier pricing structure across premium, standard, and economy levels separates aerospace COPV specifications from automotive Type IV tanks and industrial FRP vessels. Cost compression in standard-tier automotive supply runs through REACH-mandated bio-based hardener substitution programs. Chemical processing buyers exhibit highest price sensitivity due to mature ASME RTP-1 specifications, while aerospace procurement tolerates premium positioning for zero-failure documentation.
Supply Chain Analysis
ASME Section X inspector certification scarcity in Houston and Bavaria constrains throughput at filament winding facilities, extending factory acceptance testing queues and concentrating manufacturing capability among incumbent operators. Raw material flows draw from Japanese carbon fiber tow producers, German epoxy formulators, and Yangtze River Delta equipment manufacturers. Single-source vulnerability in aerospace-grade tow allocation during demand surges threatens hydrogen tank production continuity. Distribution runs through integrated engineering service providers bundling composite procurement with certification navigation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between German hydrogen hub buildout with compressed procurement timelines and Indian infrastructure tenders with localized liner production cost advantages.
For Market Incumbents: Anticipate thermoplastic composite displacement in automotive fuel cell platforms by accelerating AFP manufacturing pilot programs ahead of ISO 11119-2 database completion. Accumulate certification capital in maritime ammonia storage specifications to defend against emerging spherical tank specialists. Prioritize backward integration into liner production to capture margin from India hydrogen hub tenders. For New Entrants and Emerging Players: The premium-to-economy price-point gap in hydrogen tank supply opens white-space at mid-tier industrial gas containment below 200 bar where hybrid composite specifications face less stringent cycle testing. Target Reliance Industries and Indian Oil Corporation refueling infrastructure procurement with localized manufacturing partnerships. Pursue software-defined pressure monitoring subscriptions as a service-layer entry point unbundled from initial vessel supply. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier filament winding fabricators lacking ASME Section X qualification capital but possessing equipment specialization and operator training infrastructure. Five-to-ten-year viability hinges on successful navigation from thermoset epoxy dominance toward thermoplastic composite qualification. Monitor harmonization progress between regional hydrogen infrastructure codes as the critical inflection signal for procurement specification consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Liner Production | Captures margin from India hydrogen hub tenders while reducing permeation failure risk. |
| Thermoplastic Composite Qualification Investment | Positions suppliers for South Korean automotive OEM 2027 fuel cell platform requirements. |
| Software-Defined Monitoring Platform Launch | Shifts revenue models from material sales to recurring predictive maintenance subscriptions. |
| ASME Section X Certification Expansion | Defends competitive positioning against new entrants facing 8-12 week inspector queue extensions. |
| Maritime Ammonia Storage Partnership | Opens spherical composite tank demand from dual-fuel vessel conversion programs. |
Research Approach
Bottom-up hydrogen storage system modeling reconciled against top-down carbon fiber prepreg supply tracking forms the analytical core of this study. Primary interviews with filament winding plant managers, automotive OEM platform engineers, ASME Section X inspectors, epoxy formulator R&D directors, and hydrogen refueling station procurement leads combined with secondary validation from UN ECE R134 regulatory filings, ISO 11119 certification databases, Toray and Hexcel capacity disclosures, and H2 Mobility Deutschland tender documentation. Triangulation between stakeholder demand signals and supply-side production data ensures segmentation integrity.
Historical trendline analysis of thermoset composite qualification timelines and thermoplastic adoption curves informed projection frameworks across the analysis window. Segmentation dimensions modeled include matrix chemistry, fabrication method specialization, end-use certification tier, and regional hydrogen infrastructure buildout phase. CAGRs derived from vessel production intensity per fuel cell vehicle deployment and pressure rating migration patterns from 350-bar to 700-bar service. Forecast inputs incorporated carbon fiber tow supply allocation risk and REACH regulatory sunset review timing.
Caveats apply where bisphenol-A restriction acceleration, aerospace demand surge allocation priority, or regional hydrogen code harmonization failure could materially shift the outlook. Forecasts reflect documented assumptions regarding filament winding equipment specialization barriers and inspector certification pipeline constraints. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Composite Materials
Aluminum Composite Materials Market
Composite Materials
Thermoplastic Honeycomb Market
Composite Materials
PCR Laminates Market
Composite Materials
Global Closed Molding Composites Market
Composite Materials
Long-Fiber Thermoset Composites Market
Composite Materials
Global Carbon Fiber Reinforced Plastic Market
Composite Materials
Scrim Reinforced Films Market
Composite Materials
Europe Marine Composites Market
Composite Materials
Composite Process Material Kits Market
Composite Materials
Fiber Reinforced Polymer (FRP) Panels and Sheets Market
Composite Materials
United States Marine Composites Market
Composite Materials
Low Temperature Sealing Glass Composite Powder Market
Composite Materials
Turbine Blade Material Market
Composite Materials
Global Carbon Felt and Graphite Felt Market
Composite Materials
Expandable Graphite Market
Composite Materials
Graphite Felt Market