
 Global Carbon Fiber Reinforced Polymer Market | 2026-2036
Global Carbon Fiber Reinforced Polymer Market Size, Share, and Industry Trends Forecast 2026-2036
Global Carbon Fiber Reinforced Polymer Market Intelligence
Long-term supply agreements that underwrite capital expenditure for new production lines is rewriting the competitive landscape for carbon fiber precursors. This model allows specialists to secure offtake before committing to costly capacity expansion. Toray Industries leverages its scale in aerospace-grade fibers to secure such contracts. Meanwhile, Hexcel Corporation differentiates through its portfolio of advanced composite materials, including prepregs, and SGL Carbon competes by focusing on industrial applications and automotive partnerships.
Carbon Fiber Reinforced Polymer is a composite material consisting of high-strength carbon fibers embedded within a polymer matrix, typically epoxy or thermoset resin. It delivers an exceptional strength-to-weight ratio, making it a critical material for replacing traditional metals like aluminum and steel in performance-driven applications. Demand for aerospace components continues to dominate application segments. However, the wind turbine blades segment represents the fastest-growing opportunity, driven by the push for longer, more efficient rotor designs and enabled by pultrusion and filament winding technologies.
Stringent airworthiness certification from bodies like the FAA in the United States and EASA in Europe governs the use of CFRP in critical aerospace structures. These regulations mandate extensive testing and process validation, creating high barriers to entry for material suppliers. In parallel, automotive emissions standards globally are accelerating R&D into cost-effective, high-volume CFRP manufacturing. Stakeholders must now decide whether to focus on high-margin aerospace or high-volume industrial and automotive sectors.
Market Dynamics
The central dynamic shaping the market is the strategic divergence between high-margin, long-certification aerospace applications and the emerging high-volume, cost-sensitive automotive and industrial sectors. This forces material suppliers and fabricators to make critical investment decisions, balancing long-term aerospace contracts against the potential scale of industrial automation.
Growth Catalysts
- Automated Manufacturing:The deployment of automated fiber placement and tape laying technologies in aerospace manufacturing significantly reduces labor costs and production cycle times, enabling higher build rates for commercial aircraft.
- Vehicle Emissions Mandates:Stringent CO2 emissions standards in Europe, China, and the United States compel automotive OEMs to pursue aggressive lightweighting strategies, creating sustained demand for CFRP in structural components and battery enclosures.
- Wind Turbine Sector Expansion:The global push for renewable energy drives demand for longer, more efficient wind turbine blades, an application where CFRP's stiffness and low weight are critical for performance and energy capture.
Market Restraints
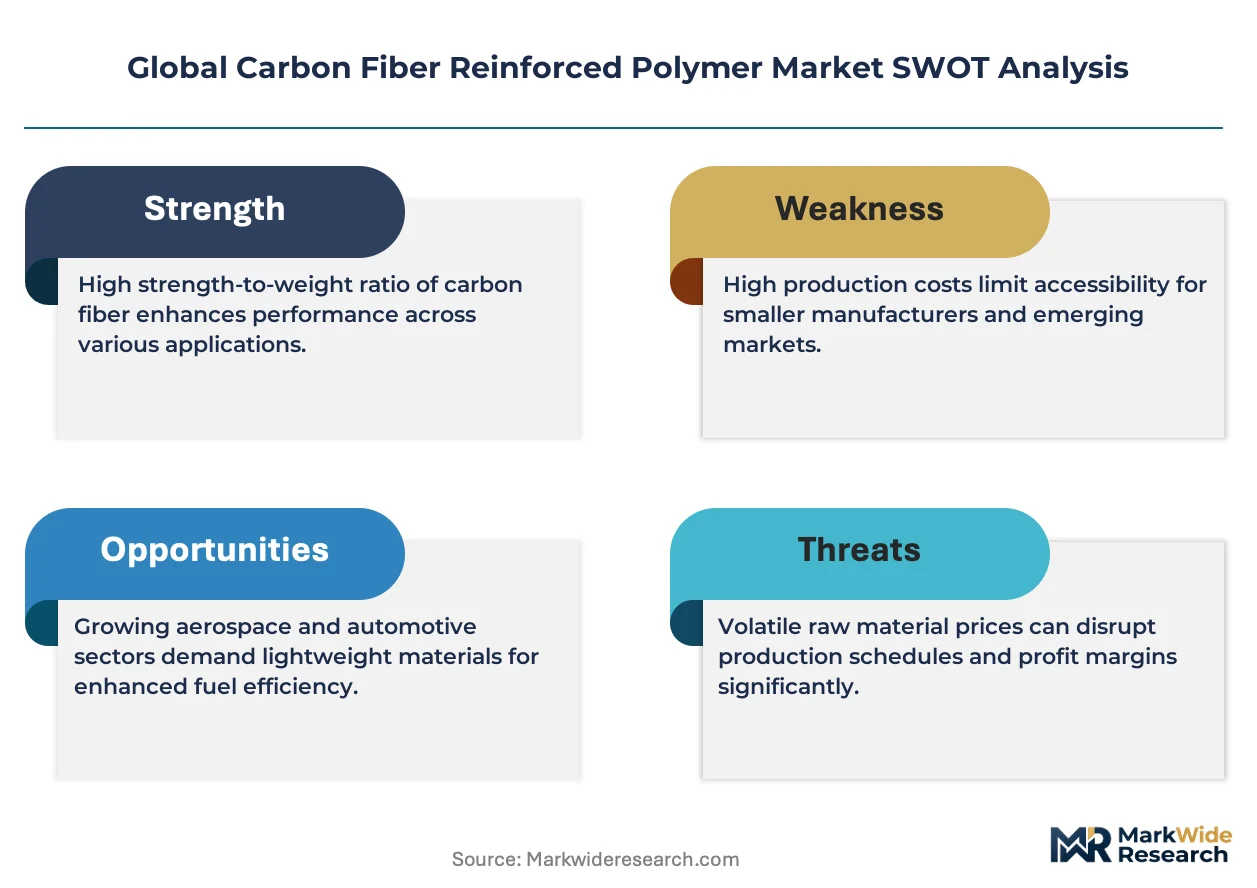
- Precursor Cost and Availability:The high cost and energy-intensive production of aerospace-grade polyacrylonitrile (PAN), the primary precursor for carbon fiber, remains a significant barrier to broader, cost-sensitive adoption.
- Recycling Infrastructure Deficit:A lack of mature, scalable recycling processes for end-of-life CFRP components, particularly those using thermoset resins, creates environmental concerns and limits circularity, hindering adoption in regulated industries.
- Stringent Certification Hurdles:The extensive and costly airworthiness qualification processes mandated by regulators like the FAA and EASA create high barriers to entry for new materials and suppliers in the aerospace segment.
Strategic Opportunities
- High-Pressure Hydrogen Storage:The development of the hydrogen economy presents a major opportunity for CFRP in Type IV pressure vessels for fuel cell electric vehicles, where high strength and light weight are essential.
- Additive Manufacturing Integration:Combining continuous carbon fiber reinforcement with 3D printing technologies enables the on-demand fabrication of complex, topology-optimized parts, creating new possibilities for tooling, jigs, and bespoke components.
- Industrial Automation Components:Underpenetration in industrial robotics and high-speed machinery offers a growth vector, as CFRP can be used for lighter, stiffer robotic arms and end-effectors, enabling faster and more precise automation.
Industry Challenges
- Capital-Intensive Capacity Expansion:Building new carbon fiber and precursor production lines requires immense upfront capital investment, creating a significant operational challenge for suppliers seeking to meet projected demand growth.
- Lack of Material Standardization:Disparate material specifications and testing protocols between the aerospace, automotive, and industrial sectors complicate supply chains and prevent economies of scale in material production and qualification.
- Composite Design Skill Gaps:A persistent shortage of engineers and technicians with deep expertise in composite design, analysis, and advanced manufacturing processes limits the ability of end-users to fully exploit the material's potential.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Carbon Fiber Reinforced Polymer Market |
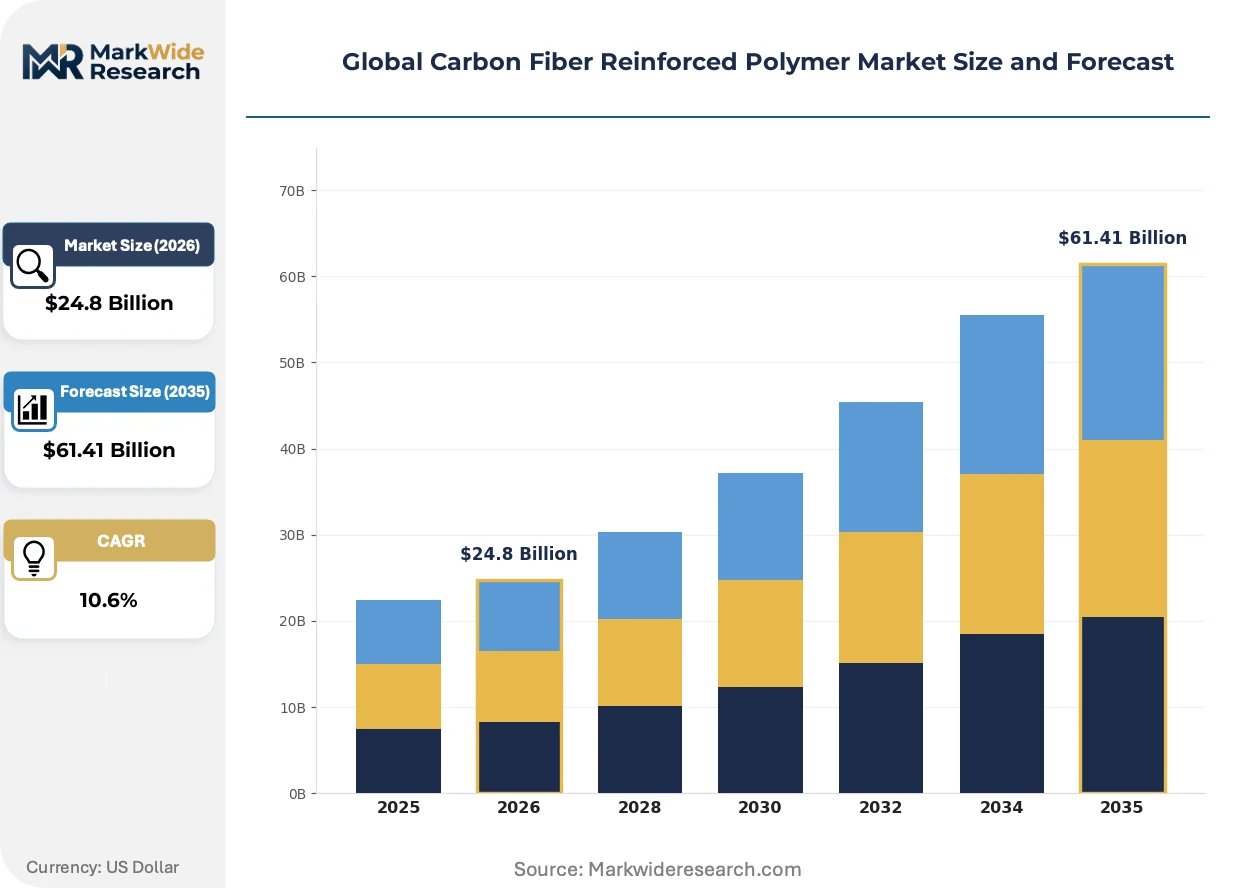
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $61.41 Billion |
| CAGR (2026 – 2036) | 10.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
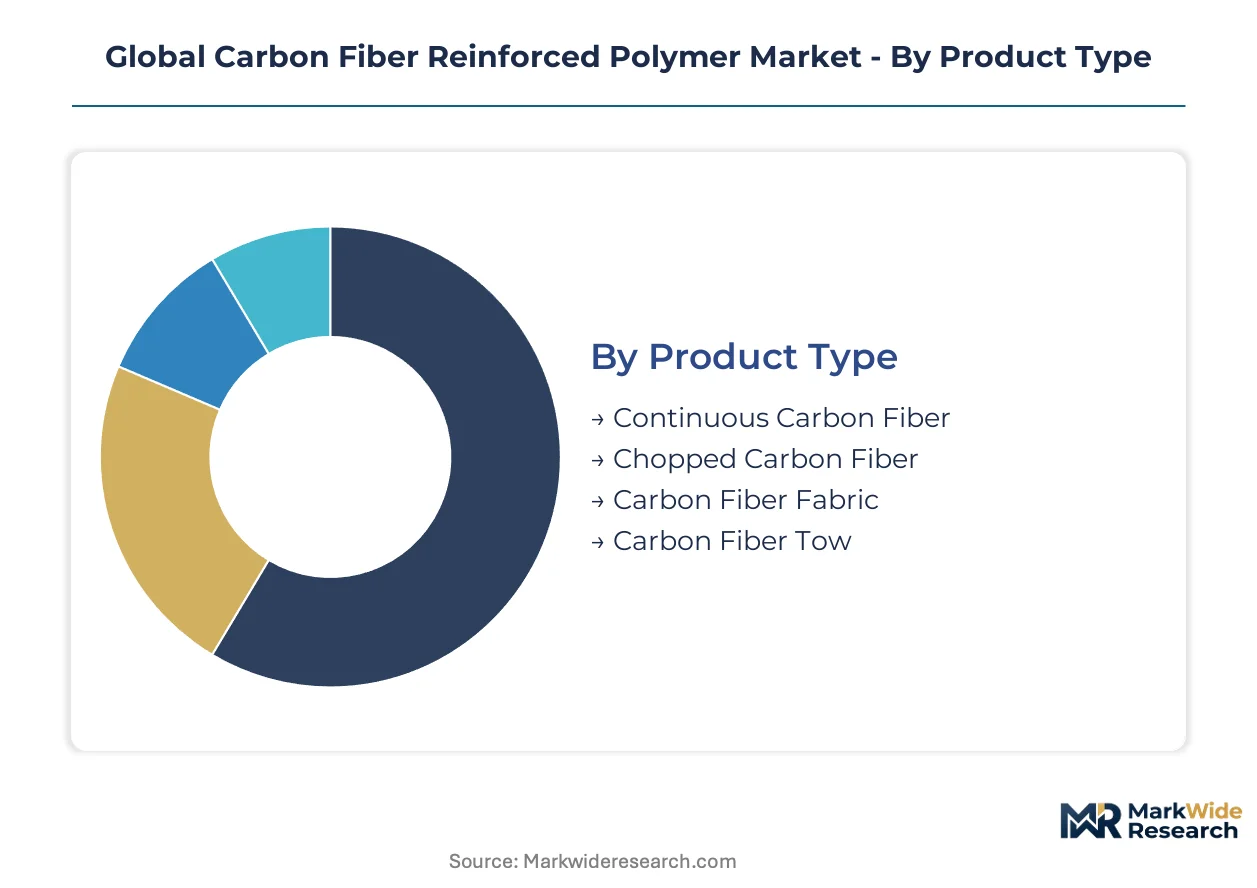
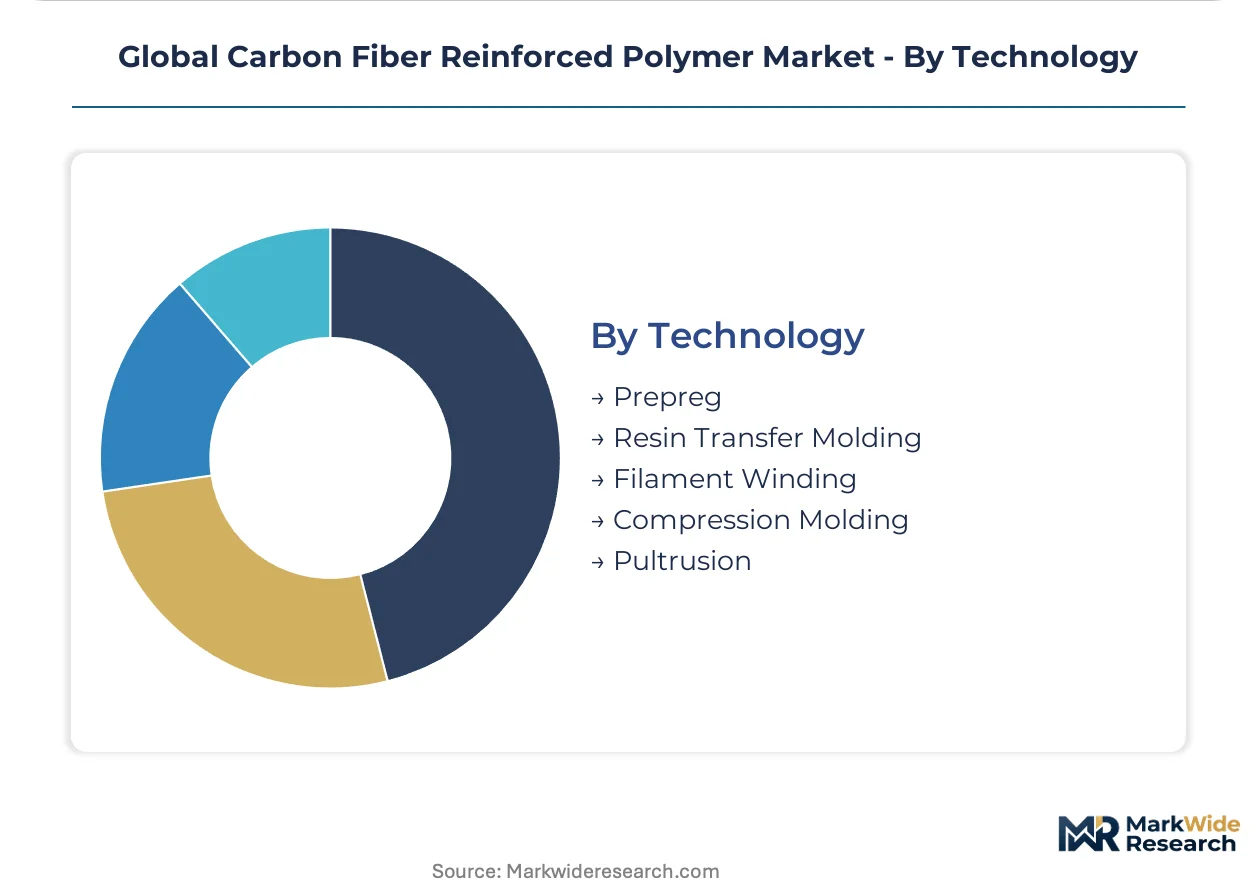
| Segmentation | Product Type: Continuous Carbon Fiber, Chopped Carbon Fiber, Carbon Fiber Fabric, Carbon Fiber Tow Application: Aerospace Components, Sporting Goods, Wind Turbine Blades, Civil Engineering Structures, Marine Equipment End User Industry: Commercial Aviation, High-Performance Sports, Renewable Energy, Construction, Shipbuilding Technology: Prepreg, Resin Transfer Molding, Filament Winding, Compression Molding, Pultrusion |
| Companies Covered | Mitsubishi Chemical Group, Zoltek, Toray Industries, DowAksa, Solvay, SGL Carbon, Teijin Limited, Formosa Plastics Corporation, Hexcel Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Carbon Fiber Reinforced Polymer Market Strategic Shifts & Innovations
Process industrialization is reshaping the competitive landscape. The market is moving beyond a singular focus on material properties toward a total-system approach that prioritizes manufacturing rate, cost-efficiency, and lifecycle considerations, opening the door for new material forms and production methods.
Thermoplastic composites are gaining significant traction as a viable alternative to traditional thermosets. The automotive and consumer electronics sectors are adopting these materials to leverage their rapid processing cycles, weldability, and improved recyclability. The material selection focus for many new programs is migrating from purely performance-driven thermoset solutions toward total-cost models that favor the production efficiencies of thermoplastics.
European Union sustainability policies, particularly the Circular Economy Action Plan, are creating new design and material selection pressures. This regulatory framework incentivizes greater material circularity and recyclability, directly challenging the dominance of difficult-to-recycle thermoset-based CFRP. Consequently, the aerospace and automotive segments are accelerating investment in recycling technologies and design-for-disassembly principles to ensure long-term compliance.
A notable shift in buying behavior involves OEMs procuring integrated composite structures rather than just raw materials. This trend disrupts the traditional supply model, favoring vertically capable suppliers that offer a full suite of design, simulation, and automated manufacturing services. This demand-side evolution is most pronounced in the United States and French aerospace clusters, where prime contractors seek to de-risk complex aerostructure programs.
Global Carbon Fiber Reinforced Polymer Market Segmentation
Understanding the varied segments within the Carbon Fiber Reinforced Polymer market reveals distinct dynamics for material suppliers and fabricators. Each category reflects unique material forms, application demands, end-user priorities, and processing technologies, driving specific investment and innovation pathways across the value chain.
Product Type:
The various product forms of carbon fiber dictate manufacturing cycle times and downstream processing complexity.
- Continuous Carbon Fiber:These long, unbroken strands offer maximum strength translation and stiffness, critical for structural integrity in high-performance applications. Demand concentrates in aerospace manufacturing in the United States and France, driven by the need for lightweight, high-strength aircraft components.
- Chopped Carbon Fiber:Short, discontinuous fibers provide isotropic properties and are suitable for molding processes, offering cost-effectiveness and design flexibility. The automotive sector in Germany and China drives demand for these fibers, seeking high-volume production of lightweight structural parts for emissions reduction.
- Carbon Fiber Fabric:Woven or non-crimp fabrics enable efficient lay-up and provide specific directional strength, utilized in complex composite structures.
- Carbon Fiber Tow:Bundles of continuous filaments serve as a raw material for various composite manufacturing processes like filament winding and pultrusion.
Continuous Carbon Fiber anchors the volume base while Chopped Carbon Fiber gains share at the steepest rate.
Application:
Application segments differentiate by their required performance specifications and the resulting margin profiles for CFRP materials.
- Aerospace Components:This segment demands exceptional strength-to-weight ratios, fatigue resistance, and thermal stability for critical aircraft structures, including wings, fuselages, and engine components. Airworthiness certification from bodies like the FAA in the United States and EASA in Europe imposes rigorous testing, creating significant barriers to entry.
- Wind Turbine Blades:CFRP enables the production of longer, stiffer, and more efficient wind turbine blades, increasing energy capture and reducing operational loads. Global renewable energy initiatives, particularly in Germany and Denmark, drive this segment, leveraging pultrusion and filament winding for large-scale manufacturing.
- Sporting Goods:CFRP provides lightweight and high-strength attributes for equipment like bicycles, tennis rackets, and golf clubs, enhancing athletic performance.
- Civil Engineering Structures:Reinforcement and repair of bridges, buildings, and infrastructure benefit from CFRP's corrosion resistance and high tensile strength.
- Marine Equipment:Lightweighting in yacht building, offshore platforms, and submersibles improves fuel efficiency and performance in harsh environments.
The segment for Aerospace Components demands stringent certification, contrasting with the high-volume requirements of Wind Turbine Blades.
End User Industry:
End-user industries categorize the market by their scale of material consumption and specific regulatory frameworks.
- Commercial Aviation:This industry requires CFRP for commercial aircraft to achieve fuel efficiency targets and reduce operational costs. Stringent airworthiness regulations from the FAA and EASA govern material selection and qualification processes.
- Renewable Energy:The wind energy sector utilizes CFRP extensively for turbine blades, driven by global mandates for carbon emission reduction and increased energy generation capacity. Countries like Germany and China are major consumers.
- High-Performance Sports:Manufacturers integrate CFRP into premium sports equipment, targeting performance enhancement and product differentiation for athletes.
- Construction:The construction industry employs CFRP for structural strengthening, seismic retrofitting, and lightweight prefabrication in buildings and bridges.
- Shipbuilding:CFRP finds use in marine vessels for weight reduction, corrosion resistance, and improved hydrodynamics, particularly in high-speed craft and luxury yachts.
Investment in Commercial Aviation infrastructure supports growth, while Renewable Energy drives material innovation for large structures.
Technology:
Manufacturing technologies for CFRP span a spectrum from mature, labor-intensive processes to highly automated, rapid production methods.
- Prepreg:Pre-impregnated materials offer precise fiber-to-resin ratios and consistent quality, predominantly used in aerospace and high-performance applications requiring autoclave curing. The United States and France utilize prepreg extensively for complex aerospace structures.
- Pultrusion:This continuous manufacturing process produces profiles with high fiber volume fractions and excellent unidirectional properties, ideal for long, straight components like wind turbine spars and construction elements. Germany and China lead in adopting pultrusion for industrial scale.
- Resin Transfer Molding:RTM involves injecting resin into a dry fiber preform within a closed mold, enabling complex shapes with good surface finish and reduced void content.
- Filament Winding:Continuous fibers are wound onto a rotating mandrel, creating hollow, high-strength structures like pressure vessels and pipes.
- Compression Molding:This process uses heat and pressure to form composite parts from sheet molding compound (SMC) or bulk molding compound (BMC), suitable for high-volume automotive components.
Advanced techniques like Filament Winding enable complex geometries, whereas Pultrusion optimizes for high-volume, continuous production.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for Carbon Fiber Reinforced Polymer materials is concentrating in key manufacturing hubs globally, driven by the need for lightweighting and performance in advanced applications. Aerospace and automotive sectors represent significant end-users. These regions also exhibit strong research and development capabilities.
United States
The United States market for Carbon Fiber Reinforced Polymer is primarily driven by its robust aerospace and defense sectors, seeking high-performance, lightweight materials. Stringent FAA airworthiness certifications dictate material selection and process validation for critical aircraft structures. Seattle's aerospace manufacturing cluster continues to innovate in automated fiber placement technologies for commercial aircraft programs.
Germany
Germany exhibits strong demand for CFRP in its automotive industry, driven by aggressive CO2 emissions standards from the European Union. Its wind energy sector also extensively uses CFRP for longer, more efficient turbine blades, supported by national renewable energy initiatives. Bavaria's automotive R&D centers are accelerating cost-effective, high-volume CFRP manufacturing processes.
China
China's market for CFRP is expanding rapidly, fueled by substantial investments in renewable energy infrastructure and the electric vehicle sector. The country's dual carbon goals and stringent vehicle emissions mandates compel OEMs to adopt lightweighting strategies. The Yangtze River Delta region is a hub for EV manufacturing, integrating CFRP into structural components.
France
France represents a significant market for Carbon Fiber Reinforced Polymer, largely due to its prominent commercial aviation and defense aerospace industries. EASA certification requirements for new aircraft programs drive demand for advanced composite materials. Toulouse remains a core aerospace cluster, where prime contractors procure integrated composite structures for complex aerostructure programs.
Global Carbon Fiber Reinforced Polymer Market Key Industry Players
Channel-controlling players compete with product-specialist players, creating a dynamic competitive landscape for Carbon Fiber Reinforced Polymer. The market exhibits a tiered structure, with a few large integrated firms alongside numerous niche material suppliers and fabricators. Key strategic archetypes include raw material producers, prepreg specialists, and integrated composite part manufacturers. Dominant competitive moves involve capital expenditure for capacity expansion and strategic partnerships across the value chain.
Among the established material suppliers, Toray Industries exemplifies a global leader in aerospace-grade fibers, leveraging its scale to secure long-term supply agreements. Hexcel Corporation represents a specialist in advanced composite materials, including prepregs, differentiating through its comprehensive portfolio. SGL Carbon occupies a position focusing on industrial applications and automotive partnerships, reflecting a strategic divergence towards high-volume sectors. These firms anchor different segments of the value chain, from precursor production to integrated composite solutions.
| Leading Market Players |
|---|
| Mitsubishi Chemical Group |
| Zoltek |
| Toray Industries |
| DowAksa |
| Solvay |
| SGL Carbon |
| Teijin Limited |
| Formosa Plastics Corporation |
| Hexcel Corporation |
| Others |
Cost & Logistics Intelligence
Commodity volatility in polyacrylonitrile (PAN) precursor materials directly determines pricing tier spreads and shapes the global carbon fiber reinforced polymer (CFRP) supply chain. This raw material cost factor drives strategic decisions across the value chain.
Pricing Analysis
Cost-plus contract patterns with polyacrylonitrile (PAN) indexation anchor pricing in the aerospace-grade carbon fiber market. Price differentiation stems from stringent certification levels mandated by the FAA and EASA, alongside the specific performance grade of the fiber. Pricing softness affects industrial and automotive grades, driven by the push for cost-effective, high-volume manufacturing. Aerospace components buyers exhibit the lowest price sensitivity, while automotive and wind turbine sectors are highly sensitive to material costs.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities are common in the capital-intensive carbon fiber precursor segment. Global supply of aerospace-grade carbon fiber concentrates in Japan and the United States, with significant production also in Germany. The market depends on polyacrylonitrile (PAN) precursor and specialized epoxy resins as critical inputs. Single-source vulnerability for aerospace-grade PAN represents a structural risk. Distribution runs through long-term supply agreements directly with prime aerospace contractors and large industrial fabricators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Carbon Fiber Reinforced Polymer market is at a platform-economics inflection, driven by the need for interoperability between material suppliers and automated manufacturing ecosystems. This shift prioritizes integrated solutions over standalone material sales.
For Market Incumbents:Pre-empt margin erosion from emerging thermoplastic composites by deepening vertical integration into precursor production. Secure long-term supply agreements with aerospace primes, leveraging existing certification investments to maintain market share. Invest in advanced recycling technologies to address environmental regulations and mitigate future cost pressures. This defends against new entrants and strengthens market position.
For New Entrants and Emerging Players:Build out capabilities in high-pressure hydrogen storage vessels and industrial automation components, which represent significant white-space opportunities. The industrial automation segment offers the most penetrable entry point due to less stringent regulatory hurdles than aerospace. Offer integrated design-to-part solutions, combining continuous carbon fiber with additive manufacturing for bespoke components. This approach circumvents established aerospace supply chains.
For Investors and Strategic Acquirers:The market sits at a growth phase that favors specialized fabricators with automated manufacturing expertise. Long-term viability over the next 5-10 years remains strong, driven by sustained demand for lightweighting across multiple sectors. Target acquisition profiles include companies with proprietary pultrusion or filament winding technologies for industrial scale-up. Watch for breakthroughs in cost-effective polyacrylonitrile (PAN) precursor production as a key inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Precursor Production | Increases supply of polyacrylonitrile (PAN) precursor to meet future demand in automotive. |
| Investment in Thermoplastic Composite R&D | Enables faster processing cycles and improved recyclability for automotive and consumer electronics. |
| Development of CFRP Recycling Infrastructure | Addresses EU sustainability policies and reduces environmental concerns for end-of-life components. |
| Strategic Partnerships with Automotive OEMs | Secures high-volume offtake for cost-effective CFRP solutions in electric vehicle platforms. |
| Acquisition of Automated Fiber Placement Specialist | Enhances manufacturing rate and efficiency for complex aerospace components in the United States. |
Research Approach
Desk research of regulatory filings, industry association reports, and patent databases preceded structured interviews with R&D directors, procurement leads, and aerospace engineers. Primary insights from wind turbine manufacturers and automotive OEMs were triangulated against secondary data for validation. This approach ensured a comprehensive bottom-up and top-down understanding of market dynamics.
Assumptions regarding raw material availability and regulatory stability were held fixed, while technological advancements and end-user demand were varied. The analytical framework modeled segmentation dimensions including product type, application, end-user industry, and regional manufacturing hubs across the analysis window. Compound annual growth rates were calculated based on historical trends and projected demand, incorporating inputs like aircraft build rates and wind turbine blade length trends.
Stress conditions across precursor supply chain disruptions and shifts in aerospace build rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions concerning market evolution and technological adoption. Geopolitical shifts affecting precursor supply or rapid adoption of alternative materials would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Composite Materials
Composite Material for Passenger Car Market
Composite Materials
Pressure Vessel Composite Materials Market
Composite Materials
Asia-Pacific Natural Fiber Composites Market
Composite Materials
Pultrusion Market
Composite Materials
Long-Fiber Thermoset Composites Market
Composite Materials
Europe Marine Composites Market
Composite Materials
Transportation Composites Market
Composite Materials
Global Carbon Felt and Graphite Felt Market
Composite Materials
Europe Composites Market
Composite Materials
High Performance Composites Market
Composite Materials
Global Coupling Agents Market
Composite Materials
Asia-Pacific Polyphenylene Sulfide (PPS) Composites Market
Composite Materials
North America Molded FRP Grating Market
Composite Materials
Short Fiber Thermoplastic Composites Market
Composite Materials
Turbine Blade Material Market
Composite Materials
Ultra-Lightweight Cement Composites Market