
 Global Advanced Composites Market | 2026-2036
Global Advanced Composites Market Size, Share, and Industry Trends Forecast 2026-2036
Global Advanced Composites Market Foresight
The direct-to-OEM supply channel is narrowing as Tier-1 suppliers consolidate purchasing power over carbon fiber prepreg volumes. Toray Industries leverages its integrated precursor-to-prepreg manufacturing footprint across Japan and the United States to sustain long-term aerospace contracts. Hexcel Corporation anchors North American defense and commercial aviation programs through qualification-locked material specifications. Solvay competes in thermoplastic composites by specializing in high-performance polyaryletherketone matrices for aircraft primary structures.
Advanced composites encompass engineered material systems combining high-strength fibers with polymer, ceramic, or metal matrices, typically achieving specific tensile strengths exceeding 1,500 MPa with densities below 2.0 g/cm³, manufactured through automated fiber placement, resin transfer molding, or compression molding processes for weight-critical structural applications. Carbon fiber dominates aerospace and wind energy applications where load-bearing efficiency commands premium pricing, while glass fiber occupies high-volume automotive and construction segments with mature cost structures. Thermoplastic technology represents the fastest-expanding processing category, driven by recyclability mandates and reduced cycle times versus thermoset alternatives.
The FAA certifies composite airframe structures under Part 25 damage tolerance requirements, while EASA enforces comparable CS-25 standards that shape material qualification timelines and testing protocols for European suppliers. REACH regulates chemical constituents in resin systems and fiber sizing agents, directly affecting formulation choices for manufacturers serving EU markets. Stakeholders must monitor evolving emissions accounting rules under the EU Green Deal and corresponding carbon border adjustments that will redefine cost competitiveness between regional supply bases.
Market Dynamics
Thermoplastic composites are compressing manufacturing cycle times and enabling recyclability compliance, forcing incumbents to retool legacy thermoset capacity or cede aerospace and automotive contracts to qualified competitors.
Growth Catalysts
- EU Green Deal embodied carbon thresholds:REACH compliance mandates are redirecting procurement toward low-carbon fiber precursors and bio-based resin systems for wind turbine blades and automotive body panels.
- Automotive lightweighting:Electric vehicle platforms in Germany and China are specifying carbon fiber-reinforced polymer battery enclosures to offset lithium-ion mass and extend range.
- Automated fiber placement:Robotic deposition systems are reducing layup labor hours and scrap rates for complex aerostructures, narrowing cost gaps with aluminum assemblies.
Market Restraints
- Acrylonitrile price volatility:Carbon fiber precursor costs fluctuate with propylene and ammonia feedstock markets, compressing margins for producers without backward integration into petrochemicals.
- Japanese supply concentration:Toray, Teijin, and Mitsubishi Chemical command over half of global PAN precursor capacity, creating single-source vulnerability for European and North American converters.
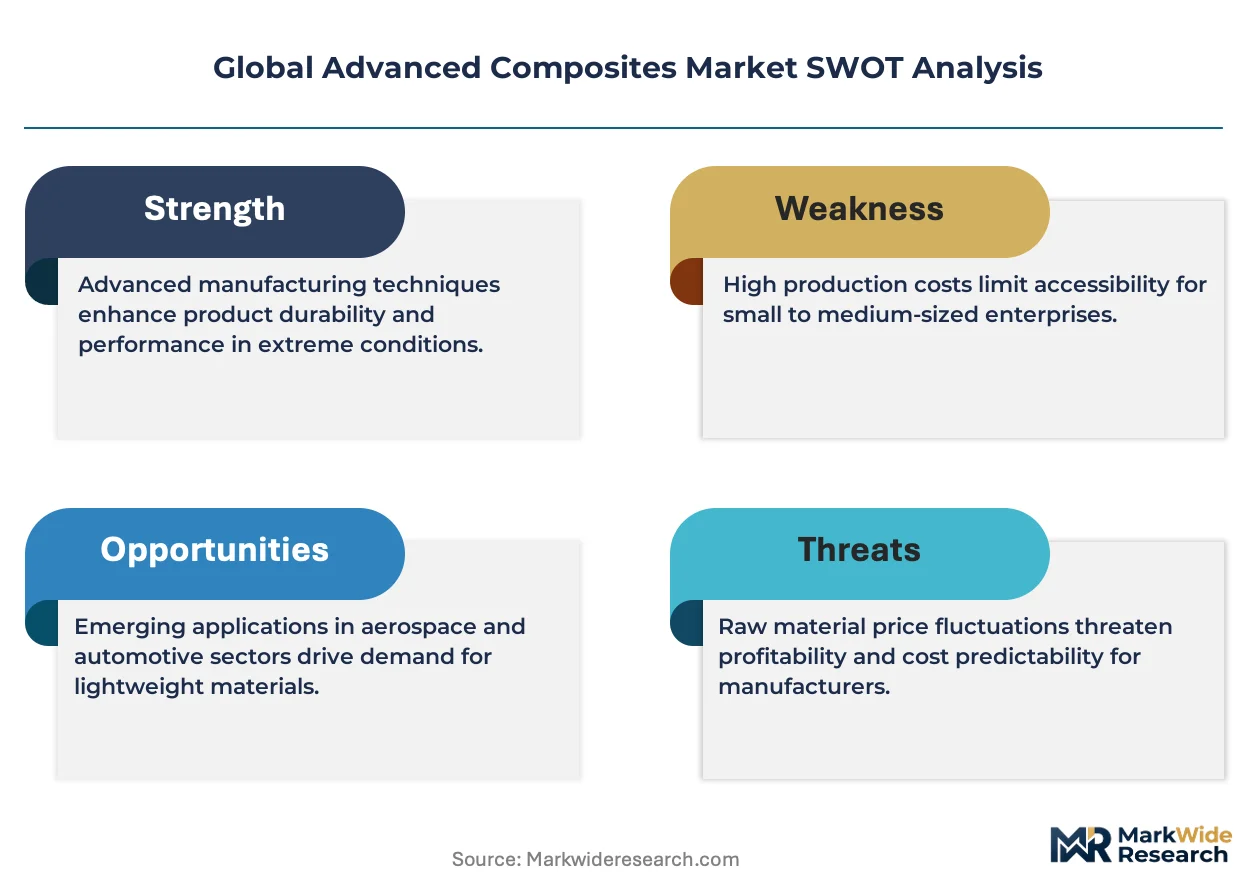
- Thermoset recyclability dead-end:Cross-linked epoxy matrices cannot be remelted or reprocessed, exposing manufacturers to extended producer responsibility fees under EU waste directives.
Strategic Opportunities
- India defense localization:The country's PLI scheme for aerospace and defense manufacturing is creating first-mover advantages for composite airframe suppliers establishing domestic prepreg facilities.
- Thermoplastic-thermoset hybrid welding:Induction consolidation of PAEK and epoxy subcomponents is enabling multi-material joints for primary aircraft structures without mechanical fasteners.
- Digital thread qualification:Model-based definition and in-situ process monitoring are compressing FAA Part 25 certification timelines for new material systems.
Industry Challenges
- Certification timeline compression:FAA and EASA damage tolerance testing protocols require 5-7 years for new composite airframe materials, locking out innovators without incumbent qualification heritage.
- Automated fiber placement technician scarcity:Programming multi-axis robotic layup systems demands cross-trained operators with both composites engineering and CNC coding competencies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Advanced Composites Market |
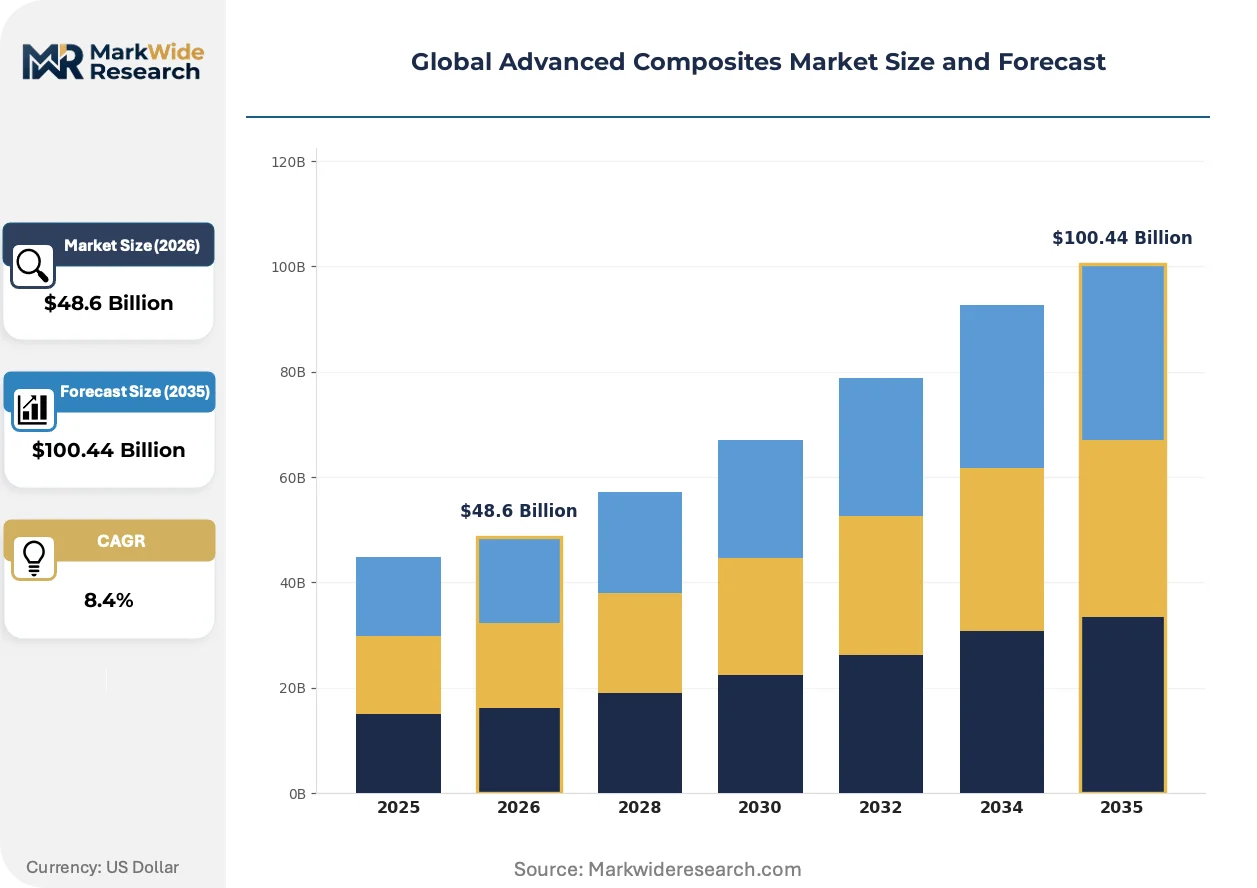
| Market Size in 2026 | $48.6 Billion |
| Market Size in 2035 | $100.44 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Carbon Fiber, Glass Fiber, Aramid Fiber, Basalt Fiber, Natural Fiber Technology: Thermoset, Thermoplastic, Ceramic Matrix, Metal Matrix, Nanocomposites Application: Aerospace, Wind Energy, Sports Equipment, Marine, Electrical & Electronics End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers, Defense Contractors |
| Companies Covered | Toray Industries, Inc., Hexcel Corporation, Solvay, SGL Carbon, Mitsubishi Chemical Corporation, Teijin Limited, Owens Corning, BASF SE, Huntsman Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Advanced Composites Market Shifts & Advancements
Digital manufacturing and circular material flows are redefining competitive advantage, separating suppliers with integrated qualification data from those trapped in paper-based traceability systems.
Out-of-autoclave curing is rendering obsolete capital-intensive autoclave infrastructure for large aerostructures. Boeing and Airbus Tier-1 suppliers are qualifying oven-cured epoxy and bismaleimide systems for wing skins and control surfaces. This shift is rendering obsolete the $20-50 million autoclave investments that previously gated market entry for mid-tier fabricators.
REACH chemical restriction lists are forcing reformulation of epoxy hardeners and fiber sizing chemistries. ECHA SVHC candidate substances now cover bisphenol-A derivatives and certain amine catalysts, compelling resin suppliers to validate drop-in alternatives without sacrificing Tg or moisture resistance. German and French automotive composite molders are accelerating bio-based anhydride hardener trials to preempt authorization sunset dates.
Consolidated direct-to-OEM contracting is squeezing distributor margins and technical service roles. Airbus and Boeing are negotiating multi-year carbon fiber prepreg supply agreements with volume commitments and price collars, bypassing traditional distribution channels that previously provided inventory buffering and small-lot technical support. This pattern is most visible in Toulouse and Hamburg aerospace clusters, where qualified material suppliers maintain resident engineering staff at final assembly lines.
Global Advanced Composites Market Segmentation
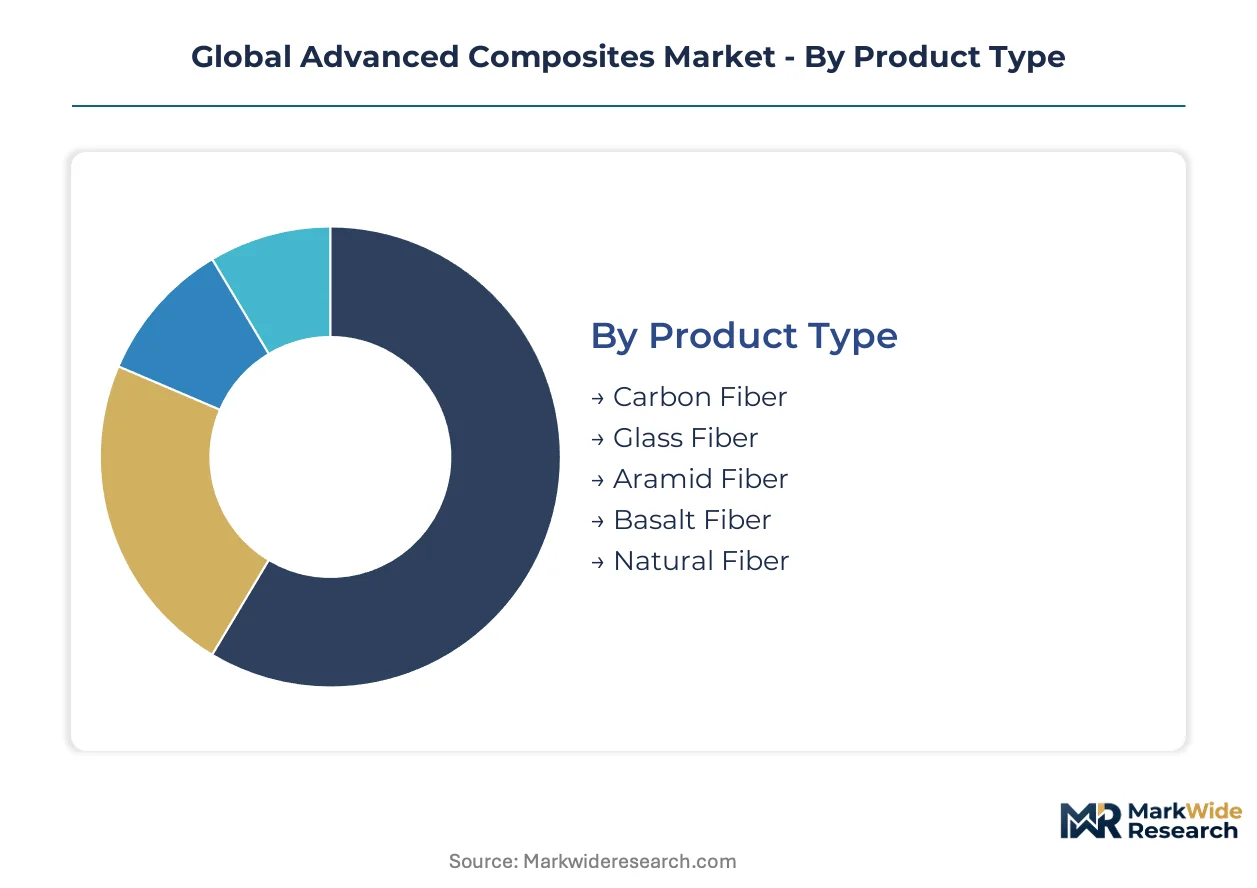
Advanced composites segmentation reflects divergent performance requirements across load-bearing and cost-sensitive applications. Fiber selection and matrix technology determine qualification pathways for aerospace certification versus automotive volume manufacturing.
Product Type:
End-use spectrum spans ultralight aerostructures requiring specific strength above 1,500 MPa to construction reinforcement accepting lower modulus thresholds.
- Carbon Fiber:PAN-based and pitch-based variants deliver tensile modulus exceeding 230 GPa for primary aircraft structures. Boeing 787 and Airbus A350 fuselage programs in the United States and France anchor demand, though acrylonitrile feedstock volatility compresses margin stability for non-integrated producers.
- Glass Fiber:E-glass and S-glass formulations dominate automotive underbody panels and wind turbine blades where cost-per-strength metrics outweigh modulus requirements. German automotive suppliers specify glass-reinforced thermoplastics for battery tray enclosures to offset lithium-ion mass.
- Aramid Fiber:Para-aramid structures absorb ballistic impact energy for military vehicle armor and pressure vessel containment.
- Basalt Fiber:Volcanic rock-derived filaments offer intermediate properties between glass and carbon for fire-resistant construction applications.
- Natural Fiber:Flax and hemp reinforcements serve interior automotive panels where EU Green Deal embodied carbon thresholds restrict synthetic fiber procurement.
The dominant share belongs to Carbon Fiber, while Natural Fiber is closing the gap fastest.
Technology:
Processing category selection locks manufacturers into irreversible capital commitments and recycling liability profiles.
- Thermoset:Cross-linked epoxy and bismaleimide matrices dominate qualified aerospace structures through automated fiber placement. FAA Part 25 damage tolerance protocols favor established thermoset qualifications, though end-of-life disposal exposes producers to extended producer responsibility fees under EU waste directives.
- Thermoplastic:PAEK and PPS matrices enable welding consolidation and reprocessing for automotive cycle time compression. German Tier-1 suppliers are qualifying induction-welded thermoplastic wing ribs for narrow-body aircraft to bypass autoclave bottlenecks.
- Ceramic Matrix:Silicon carbide fiber-reinforced ceramics withstand temperatures exceeding 1,200°C for turbine engine hot sections.
- Metal Matrix:Aluminum and titanium matrices deliver thermal conductivity for satellite structural heat dissipation.
- Nanocomposites:Carbon nanotube-enhanced resins provide multifunctional sensing capabilities for structural health monitoring.
Thermoset retains the largest installed base, though Thermoplastic is expanding most quickly.
Application:
Volume concentration varies sharply between qualification-intensive aerostructures and price-driven renewable energy components.
- Aerospace:Primary and secondary structures demand damage-tolerant designs under FAA and EASA certification timelines stretching 5-7 years. Airbus Hamburg and Boeing Charleston facilities drive prepreg consumption for fuselage barrels and wing skins.
- Wind Energy:Blade lengths exceeding 100 meters require carbon fiber spar caps to manage gravitational fatigue loads. Danish and German turbine OEMs specify low-embodied-carbon fiber to satisfy EU Green Deal procurement criteria.
- Sports Equipment:Bicycle frames and hockey sticks prioritize stiffness-to-weight aesthetics for premium consumer segments.
- Marine:Hull structures leverage corrosion resistance against saltwater environments for racing yachts and naval vessels.
- Electrical & Electronics:RF-transparent radomes and thermal management substrates serve telecommunications infrastructure.
Aerospace commands premium pricing tiers, while Wind Energy is gaining share fastest.
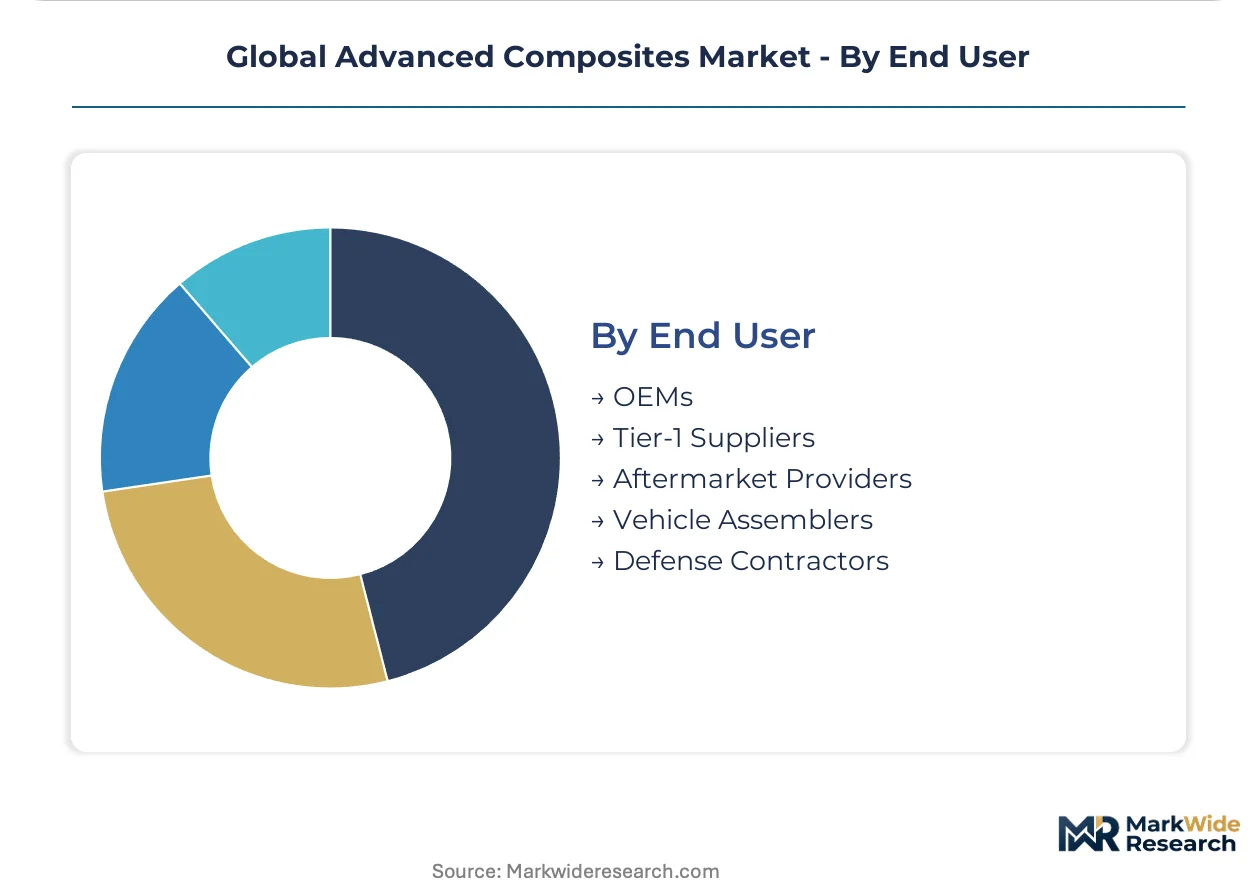
End User:
Procurement authority is consolidating toward final assemblers with resident engineering capabilities.
- OEMs:Airbus and Boeing negotiate direct multi-year prepreg agreements with volume commitments and technical resident staff at Toulouse and Hamburg final assembly lines. Consolidated contracting is squeezing traditional distributor margins and small-lot technical service roles.
- Tier-1 Suppliers:Spirit AeroSystems and GKN Aerospace maintain qualification-locked supply positions through dedicated manufacturing cells.
- Aftermarket Providers:MRO facilities perform composite repair and reinforcement for aging aircraft fleets.
- Vehicle Assemblers:BMW and Volkswagen Group specify carbon fiber battery enclosures for electric platforms.
- Defense Contractors:Lockheed Martin and BAE Systems drive armor and airframe programs with classified performance specifications.
OEMs hold procurement dominance, while Tier-1 Suppliers are consolidating influence fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EASA's CS-25 certification standards anchor European aerospace demand, while FAA Part 25 protocols govern North American airframe qualification timelines. Asian supply chains concentrate precursor manufacturing and wind turbine blade fabrication.
United States
Boeing's Charleston and Everett facilities drive carbon fiber prepreg consumption for 787 and 777X programs. FAA damage tolerance testing requirements lock in 5-7 year material qualification cycles for new composite systems. The Pacific Northwest aerospace cluster around Seattle maintains resident engineering staff from qualified prepreg suppliers.
Germany
Automotive lightweighting for BMW and Volkswagen electric platforms specifies carbon fiber battery enclosures to offset lithium-ion mass. REACH SVHC restrictions on bisphenol-A derivatives force reformulation of epoxy hardeners for automotive molders. The Hamburg aerospace cluster anchors Airbus fuselage barrel production with direct-to-OEM prepreg contracts.
China
Wind turbine OEMs source carbon fiber spar caps for blades exceeding 100 meters to manage gravitational fatigue. MIIT dual carbon goals tighten embodied carbon thresholds for imported composite materials. The Yangtze River Delta concentrates glass fiber manufacturing for construction and automotive applications.
Japan
Toray, Teijin, and Mitsubishi Chemical command over half of global PAN precursor capacity, creating supply concentration for acrylonitrile-based carbon fiber. METI industrial policy supports precursor-to-prepreg integration across domestic manufacturing sites. The Chubu region around Nagoya maintains aerospace-qualified material production for narrow-body aircraft programs.
India
Defense localization under the PLI scheme for aerospace manufacturing creates first-mover opportunities for composite airframe suppliers. CDSCO and DGFT regulations shape import substitution timelines for critical defense materials. The Bangalore-Hyderabad corridor concentrates defense contractor engineering capabilities for unmanned aerial vehicle structures.
Global Advanced Composites Market Competitive Landscape
Integrated precursor-to-prepreg manufacturers and specialized matrix formulators split the market between aerospace qualification heritage and automotive cycle-time compression. Three archetypes dominate: Japanese conglomerates with captive petrochemical feedstocks, European chemical specialists in high-performance thermoplastics, and North American defense-qualified fabricators. Consolidation pressures intensify as direct-to-OEM contracting bypasses traditional distribution channels, while capacity expansion in low-carbon precursor routes reshapes feedstock economics.
Within the integrated conglomerate tier, Toray Industries and Mitsubishi Chemical exemplify backward control over acrylonitrile supply chains. Hexcel Corporation occupies a position among North American defense-qualified suppliers with locked material specifications. Solvay anchors European thermoplastic specialization through polyaryletherketone matrix expertise for aircraft primary structures.
| Leading Market Players |
|---|
| Toray Industries, Inc. |
| Hexcel Corporation |
| Solvay |
| SGL Carbon |
| Mitsubishi Chemical Corporation |
| Teijin Limited |
| Owens Corning |
| BASF SE |
| Huntsman Corporation |
| Others |
Supply & Pricing Matrix
Acrylonitrile nameplate overcapacity in the Yangtze River Delta is compressing carbon fiber precursor margins while simultaneously emboldening Japanese conglomerates to enforce long-term offtake premiums on European and North American converters locked into aerospace qualification protocols.
Pricing Analysis
Japanese-origin carbon fiber commands 15-25% premiums over Chinese equivalents in aerospace-qualified grades, though this spread narrows for industrial applications where certification heritage carries less weight. Three-tier pricing structure across aerospace-qualified, automotive-industrial, and construction-grade tiers separates buyers by damage-tolerance testing investment and volume commitment scale. Cost compression in automotive thermoplastic grades is intensifying because German OEMs are consolidating multi-year battery enclosure contracts with price collars. Tier-1 aerospace suppliers exhibit lowest price sensitivity due to locked qualification specifications, while construction distributors face acute margin pressure from commoditized glass fiber alternatives.
Supply Chain Analysis
Toray Industries, Teijin, and Mitsubishi Chemical hold captive PAN precursor capacity across Chubu and Kansai manufacturing corridors, constraining supply alternatives for non-integrated converters. China, Japan, and the United States anchor carbon fiber manufacturing, though acrylonitrile feedstock draws from propylene-ammonia complexes concentrated in the Middle East and East Asia. Single-source vulnerability pervades aerospace supply chains where FAA Part 25 qualification locks converters into decade-long material specifications. Distribution runs through direct-to-OEM prepreg agreements with resident engineering staff at Toulouse, Hamburg, and Charleston final assembly lines, bypassing traditional inventory-buffering distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Advanced composites incumbents face substitution pressure from aluminum-lithium alloys in narrow-body aircraft structures and high-strength steel in automotive battery enclosures, demanding active defense of qualification-locked positions.
For Market Incumbents: Build certification moats by accelerating thermoplastic-thermoset hybrid welding qualifications for primary aircraft structures, locking out aluminum competitors from fuselage applications. Deepen backward integration into low-carbon acrylonitrile precursors to preempt EU Green Deal carbon border adjustments and capture embodied carbon premiums from Danish wind turbine OEMs. Capacity expansion in India under PLI scheme localization creates first-mover advantage against Chinese entrants in defense airframe supply chains. For New Entrants and Emerging Players: Establish a beachhead in natural fiber thermoplastic compounds for EU automotive interior panels, exploiting REACH SVHC restrictions on synthetic fiber sizing agents that incumbents struggle to reformulate. Target Indian defense UAV structures where CDSCO import substitution timelines create procurement windows for domestic prepreg facilities. Go-to-market leverage rests on digital thread qualification partnerships with Bangalore-Hyderabad engineering clusters to compress certification timelines versus legacy paper-based traceability systems. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across out-of-autoclave curing equipment as oven-cured epoxy systems displace $20-50 million autoclave investments, enabling mid-tier fabricator entry. Five-to-ten year viability favors specialists with integrated precursor-to-prepreg footprints and resident engineering contracts at Airbus or Boeing final assembly lines. Acquisition targets should exhibit locked FAA Part 25 material specifications and thermoplastic welding capabilities; signal to monitor is EASA adoption of digital thread certification protocols that would compress qualification timelines for qualified competitors.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Low-Carbon Precursors | Captures EU Green Deal embodied carbon premiums from German wind turbine OEMs. |
| Thermoplastic Welding Qualification | Enables induction-consolidated wing ribs for Airbus narrow-body programs bypassing autoclave bottlenecks. |
| India PLI Scheme Localization | Creates domestic prepreg capacity for defense UAV structures under CDSCO import substitution mandates. |
| Digital Thread Certification Investment | Compresses FAA Part 25 timelines through model-based definition and in-situ process monitoring. |
| Resident Engineering Expansion | Secures direct-to-OEM contracting positions at Toulouse and Hamburg final assembly lines. |
Research Methodology
A standing panel of aerospace procurement directors, automotive platform engineers, wind turbine blade designers, resin formulators, and carbon fiber plant managers provided ongoing calibration across primary interview cycles. Secondary validation drew from FAA Part 25 certification databases, EASA CS-25 submission records, EU ECHA SVHC restriction lists, customs trade data for acrylonitrile and carbon fiber precursor flows, and SEC 10-K filings from listed materials suppliers. Bottom-up segment modeling triangulated against top-down macroeconomic overlays across the analysis window.
Scenario-bracketing framed low, baseline, and high growth cases without discrete year anchoring, with CAGRs derived from elasticity modeling against aerospace delivery forecasts and automotive lightweighting content-per-vehicle trajectories. Segmentation dimensions spanned fiber type, matrix technology, processing method, end-use application, and regional regulatory cluster. Industry-specific inputs included qualification timeline distributions for new composite airframe materials and embodied carbon threshold trajectories under EU Green Deal implementation phases.
Macroeconomic conditions sit as an overlay; deviation in propylene-ammonia feedstock pricing, aerospace delivery cycles, or EU carbon border adjustment implementation would shift the trajectory materially. Forecasts embed assumptions regarding REACH SVHC sunset dates and FAA digital certification pathway adoption rates. Quarterly review of acrylonitrile contract pricing, Airbus-Boeing order backlogs, and EASA guidance on thermoplastic qualification protocols is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advanced Materials
Organic Aerogel Market
Advanced Materials
Advanced Polymer Composites Market
Advanced Materials
Synthetic Graphite Market
Advanced Materials
Silica Aerogel Market
Advanced Materials
Boron Nitride Market
Advanced Materials
Buckminsterfullerene Market
Advanced Materials
Thermal Conductive Material Market
Advanced Materials
Graphite Materials Market
Advanced Materials
Global Aluminum Honeycomb Market
Advanced Materials
Thermal Spray Market
Advanced Materials
Cubic Boron Nitrates Market
Advanced Materials
Rigid Foam Market
Advanced Materials
Liquid Thermal Interface Materials Market
Advanced Materials
Nanofibrillar Cellulose Market
Advanced Materials
Borophene Market
Advanced Materials
Europe Next Generation Anode Materials Market