
 Tow Prepreg Market | 2026-2036
Tow Prepreg Market Size, Share, and Industry Trends Forecast 2026-2036
Tow Prepreg Market Outlook
Commercial aerospace OEMs is rotating procurement priority toward lighter primary structures as fuel-efficiency mandates tighten. Hexcel Corporation leverages its vertical integration across carbon fiber and resin chemistry to sustain pricing power in narrowbody programs. SGL Carbon anchors European supply through its German manufacturing footprint, while Teijin Limited competes on aramid-tow hybrids for secondary structures.
Tow prepreg consists of continuous fiber tows impregnated with thermoset or thermoplastic resin matrices, typically achieving fiber volume fractions of 55-65% and cured ply thicknesses of 0.125-0.25 mm for automated fiber placement and filament winding. Carbon fiber tow prepreg dominates structural aerospace applications where specific stiffness requirements exceed 100 GPa/(g/cm³), while glass fiber variants occupy cost-sensitive automotive reinforcement segments. Unidirectional form factors lead in automated manufacturing throughput, though fabric forms capture margin pools in complex-cure marine hull assemblies.
FAA airworthiness standards and EASA CS-25 certification frameworks govern tow prepreg qualification for commercial aviation load-bearing structures, with REACH chemical restrictions additionally constraining resin formulation chemistry in European supply chains. EPA emissions rules and emerging state-level carbon mandates in California and Washington shape North American manufacturing investment decisions. Stakeholders must monitor evolving thermoplastic tow prepreg qualification timelines against incumbent thermoset process certifications.
Market Dynamics
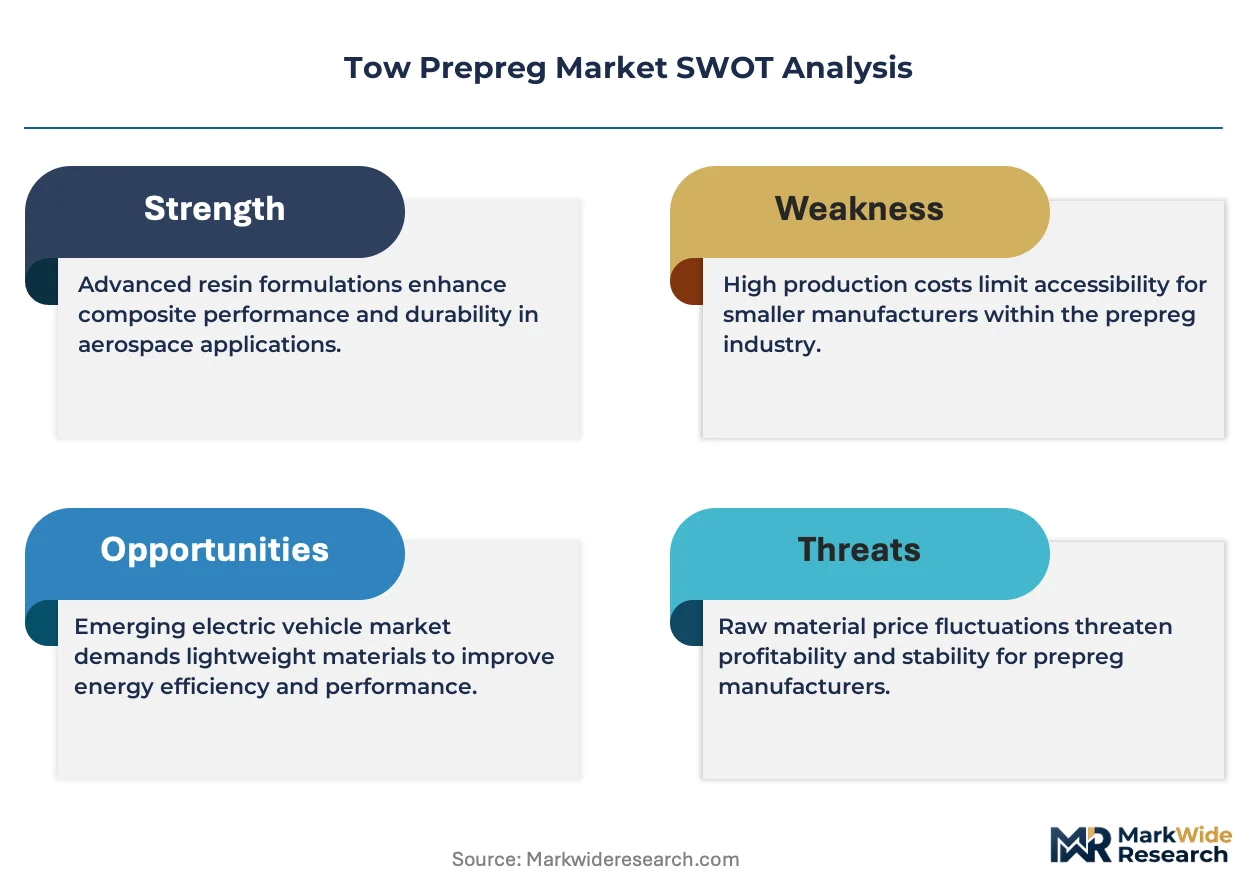
Thermoplastic tow prepreg qualification timelines are compressing against decades-old thermoset process certifications, forcing incumbents to defend their installed base while new entrants exploit out-of-autoclave curing cycles. This technological tension sits at the core of competitive positioning across aerospace and automotive supply chains.
Growth Catalysts
- EU Green Deal carbon-emission rules:REACH chemical restrictions are tightening material certification requirements across European aerospace and automotive corridors, accelerating demand for low-carbon resin formulations.
- Automated fiber placement throughput:Unidirectional tow prepreg form factors enable faster layup speeds in narrowbody wing production, reducing labor hours per shipset.
- German manufacturing corridors:Demand concentrates in Stuttgart and Hamburg aerospace clusters, where Tier 1 suppliers co-locate prepreg consolidation with final assembly lines.
Market Restraints
- Acrylonitrile feedstock volatility:Carbon fiber precursor costs fluctuate with oil-derived chemical pricing, squeezing margin predictability for tow prepreg converters.
- Japanese carbon fiber concentration:Toray, Teijin, and Mitsubishi Chemical supply over 70% of aerospace-grade tow, creating single-source vulnerability for Western laminators.
- Thermoset cure cycle rigidity:Epoxy-based systems require 180-350°F autoclave dwell times exceeding 4 hours, limiting throughput scalability against metallic alternatives.
Strategic Opportunities
- India automotive lightweighting:PLI scheme incentives for electric vehicle manufacturing create first-mover advantage for glass fiber tow prepreg in battery enclosure structures.
- Out-of-autoclave thermoplastic processing:PEEK and PPS matrix systems enable weldable joints and recyclable scrap, opening closed-loop manufacturing models.
- California state-level carbon mandates:Emerging rules in Sacramento and Washington state shape North American investment decisions toward lower-emission prepreg chemistries.
Industry Challenges
- Automated fiber placement technician scarcity:Machine programming and in-situ consolidation expertise remains concentrated among legacy aerospace workforces in Wichita and Toulouse.
- FAA-EASA dual certification timelines:Thermoplastic qualification for primary structure loads requires 5-7 year test matrices, delaying revenue recognition for new material entrants.
- Legacy ERP integration friction:Digital thread implementation for ply-by-ply traceability conflicts with decades-old MRP systems at Tier 2 converters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tow Prepreg Market |
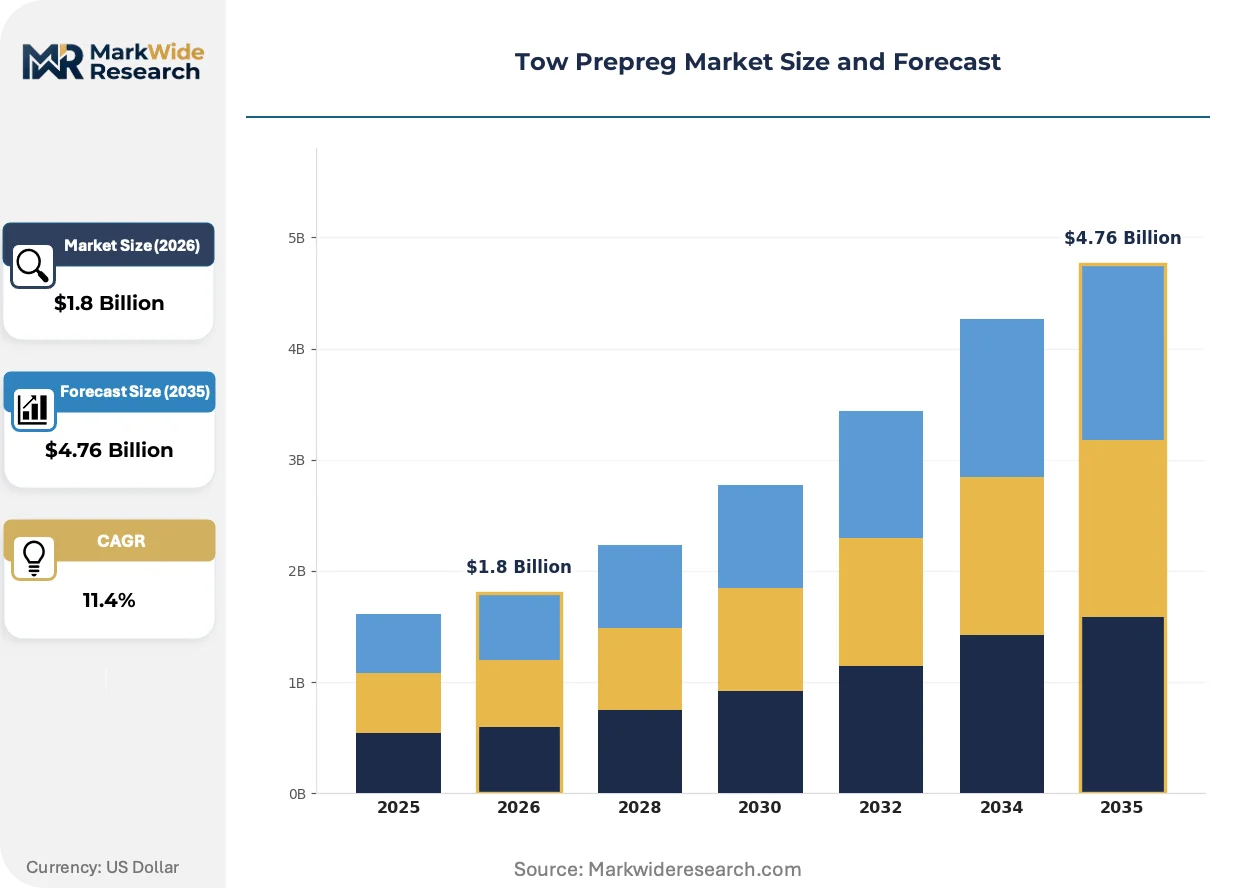
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Carbon Fiber, Glass Fiber, Aramid Fiber, Others End Use Industry: Aerospace, Automotive, Marine, Sporting Goods Form: Unidirectional, Fabric, Tape, Others Application: Structural Components, Composites, Reinforcements, Aerospace Parts |
| Companies Covered | Hexcel Corporation, SGL Carbon, Teijin Limited, Toray Industries, Mitsubishi Chemical, Solvay, TCR Composites, Porcher Industries, Arisawa Manufacturing, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tow Prepreg Market Strategic Shifts
Tow prepreg manufacturing is pivoting from thermoset dominance toward thermoplastic process economics, with resin chemistry, regulatory chemistry constraints, and procurement model compression operating as simultaneous change vectors.
Thermoplastic tow prepreg with PEEK and PPS matrices is supplanting epoxy-based systems in wing rib and fuselage frame applications where damage tolerance and weldability outweigh stiffness premiums. Airbus and Boeing procurement teams are qualifying these materials for secondary structure trials, with out-of-autoclave consolidation cycles compressing tool turnaround from days to hours. This shift is enabling smaller Tier 2 laminators to compete without capital-intensive autoclave infrastructure.
REACH chemical restrictions under the EU Green Deal are constraining bisphenol-A and formaldehyde-based resin formulations across European supply chains. ECHA substance evaluation timelines are forcing reformulation investments before 2030 sunset dates, with German automotive OEMs accelerating bio-based epoxy alternatives in Munich and Wolfsburg development centers. Aerospace laminators serving Hamburg and Toulouse final assembly lines face parallel pressure from EASA CS-25 emission disclosure requirements.
Long-term offtake agreements are displacing spot purchasing for carbon fiber tow and prepreg resin systems as buyers seek price certainty through 2030. Tier 1 aerostructures suppliers in Japan and Italy are locking in five-year resin supply contracts with volume commitments, compressing working capital flexibility for mid-tier converters. This pattern is most visible in Japan's METI-supported aerospace cluster, where Toray and Teijin have secured multi-program supply visibility.
Tow Prepreg Market Segmentation
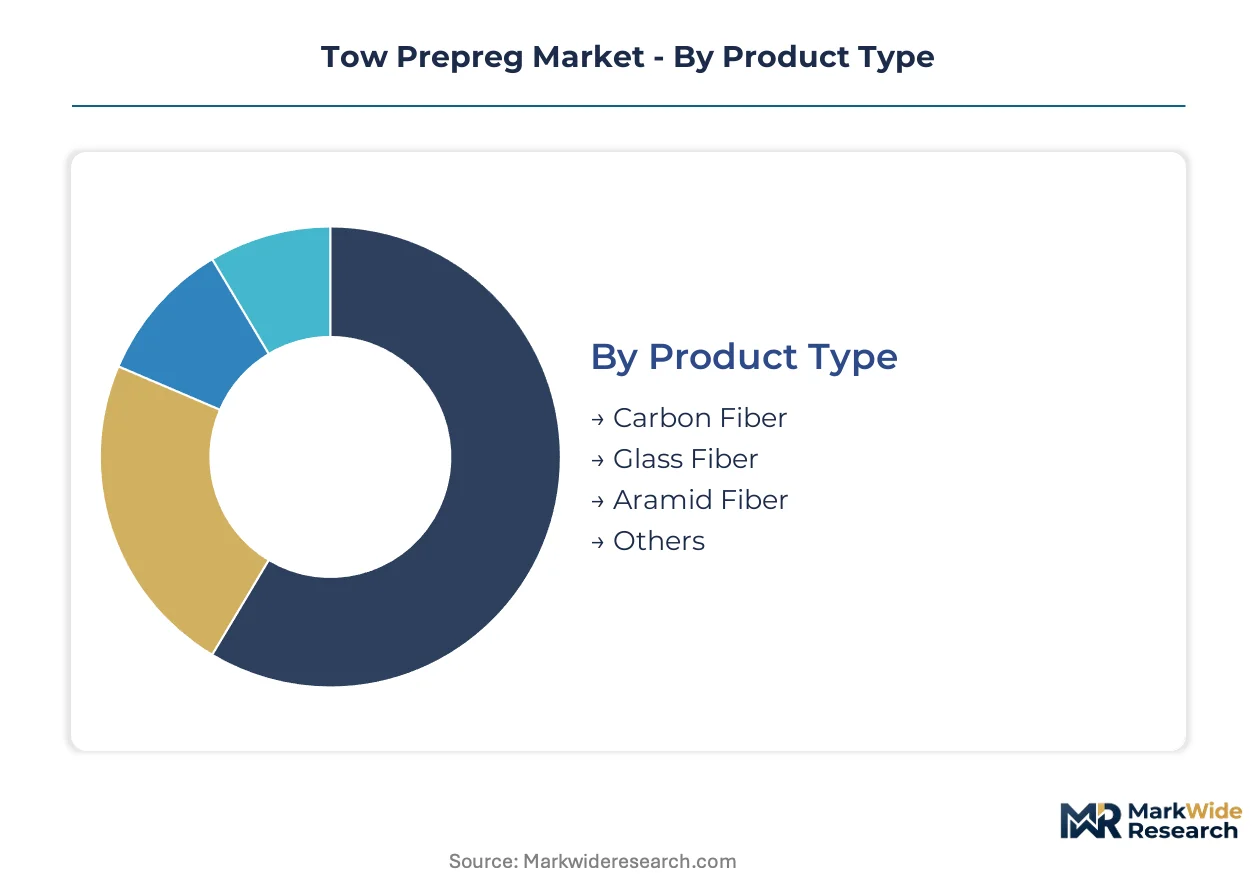
Tow prepreg procurement flows through distinct channel configurations depending on fiber grade and form factor. Aerospace laminators source carbon fiber unidirectional tapes through long-term offtake agreements, while automotive converters purchase glass fiber fabric through distributor networks.
Product Type:
Carbon fiber tow prepreg moves through direct mill relationships for aerospace qualification, whereas glass fiber variants flow through regional distributors serving automotive Tier 2s.
- Carbon Fiber:Continuous PAN-based tows with 55-65% fiber volume fraction dominate primary aerospace structures. Demand concentrates in Hamburg and Toulouse final assembly corridors where specific stiffness requirements exceed 100 GPa/(g/cm³). FAA-EASA dual certification timelines lock in incumbent suppliers.
- Glass Fiber:E-glass and S-glass variants achieve 40-50% fiber volume fractions for cost-sensitive automotive reinforcement. Stuttgart automotive clusters drive volume for battery enclosure applications. Acrylonitrile feedstock volatility squeezes converter margins unpredictably.
- Aramid Fiber:Teijin Limited anchors supply of Kevlar and Twaron tow hybrids for secondary structures and ballistic applications.
- Others:Basalt and natural fiber tow prepreg serve niche marine and construction segments through specialty distributors.
By volume, Glass Fiber leads. By growth pace, Carbon Fiber is ahead.
End Use Industry:
Cost tier stratification separates aerospace qualification premiums from automotive volume pricing, with marine and sporting goods occupying mid-tier positions.
- Aerospace:Primary structural assemblies—wings, fuselage frames, empennage—require thermoset epoxy systems with autoclave cure cycles. Boeing and Airbus procurement teams rotate priority toward lighter structures as fuel-efficiency mandates tighten. Thermoplastic qualification timelines compress against decades-old certifications.
- Automotive:Battery enclosures, floor pans, and crash structures utilize glass fiber tow prepreg for mass reduction in electric vehicle platforms. India's PLI scheme incentives create first-mover positioning for localized supply.
- Marine:Hull laminates and superstructures employ fabric-form tow prepreg for complex-cure geometries in yacht and commercial vessel production.
- Sporting Goods:Bicycle frames, hockey sticks, and golf shafts consume smaller tow sizes through specialty composite shops.
By revenue contribution, Aerospace dominates. By expansion trajectory, Automotive is climbing the fastest.
Form:
Manufacturing throughput requirements favor unidirectional formats for automated fiber placement, while fabric forms capture margin pools in manual layup applications.
- Unidirectional:Single-orientation fiber tows enable automated fiber placement at speeds exceeding manual layup rates by orders of magnitude. Narrowbody wing production in Wichita and Toulouse depends on this form factor for labor hour reduction per shipset.
- Fabric:Woven and non-crimp fabrics conform to complex geometries in marine hull assemblies and aerospace fairings. German automotive OEMs in Munich development centers specify fabric forms for Class-A surface finish requirements.
- Tape:Slit unidirectional tape supports filament winding of pressure vessels and drive shafts with precise width control.
- Others:Braided and stitched preforms serve niche aerospace ducting and satellite structures.
By manufacturing throughput, Unidirectional leads. By margin capture, Fabric is gaining share fastest.
Application:
Customer type segmentation separates qualified aerospace laminators from general industrial converters, with certification grade determining channel access.
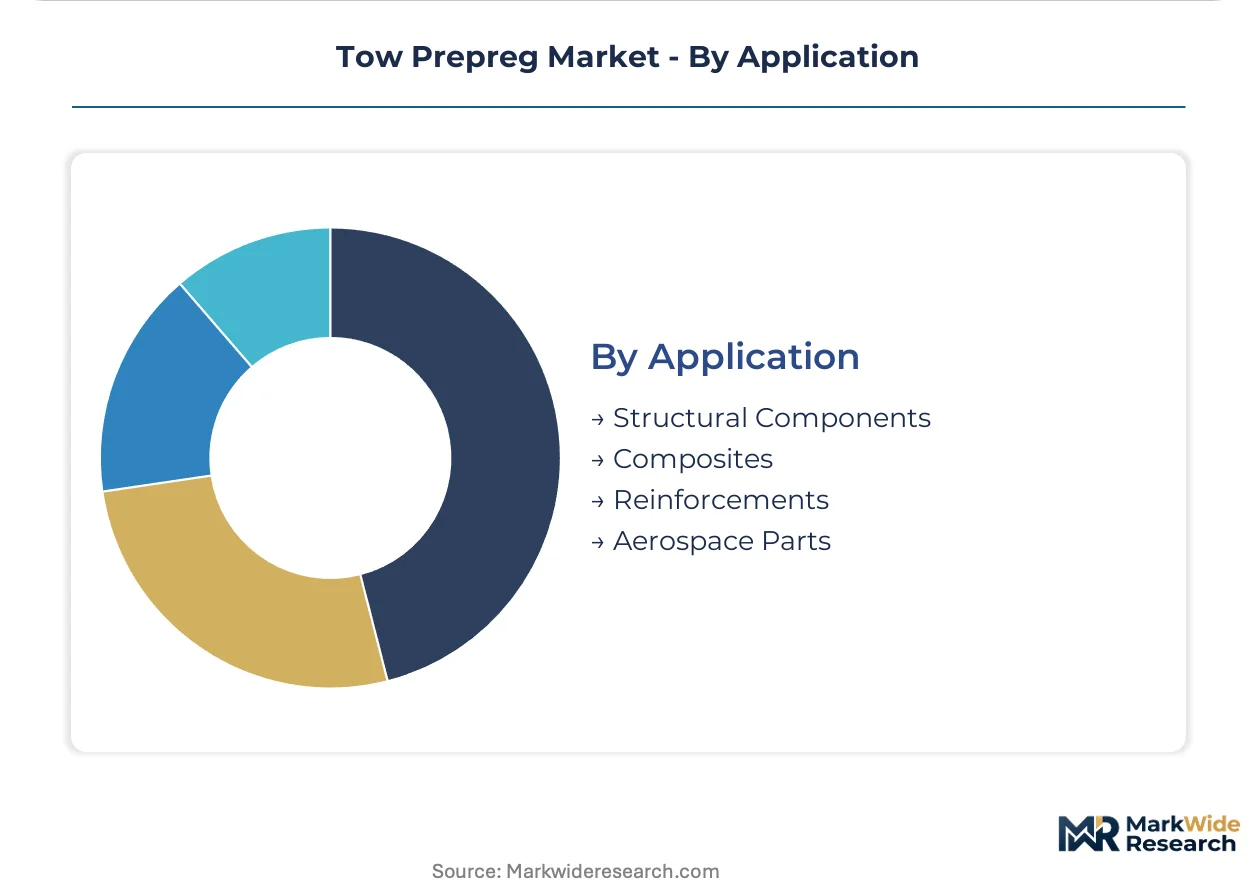
- Structural Components:Load-bearing elements—wing ribs, fuselage frames, control surfaces—require FAA airworthiness documentation and EASA CS-25 certification. Tier 1 aerostructures suppliers in Japan and Italy lock in five-year resin supply contracts for program visibility.
- Composites:General industrial laminates for tooling, industrial equipment, and infrastructure utilize lower-grade tow prepreg through distributor channels. California state-level carbon mandates shape North American investment decisions toward lower-emission chemistries.
- Reinforcements:Secondary stiffeners and local reinforcements employ chopped or narrow tow formats for patch repairs and localized strengthening.
- Aerospace Parts:Interior panels, galleys, and stowage bins utilize fire-resistant resin formulations meeting EASA emission disclosure requirements.
By qualification barrier height, Structural Components leads. By addressable market expansion, Composites shows the steepest trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Hamburg's specialized bulk handling facilities anchor European carbon fiber logistics, while Pacific Northwest rail corridors connect Japanese precursor suppliers to Boeing's Everett assembly complex.
United States
Commercial aerospace OEMs in Wichita and Seattle drive carbon fiber tow prepreg consumption for narrowbody wing programs. FAA airworthiness standards govern qualification timelines for primary structural applications. The Pacific Northwest manufacturing corridor concentrates automated fiber placement capacity adjacent to final assembly lines.
Germany
Automotive lightweighting mandates from Stuttgart OEMs accelerate glass fiber tow prepreg adoption for battery enclosures. REACH chemical restrictions under the EU Green Deal constrain bisphenol-A resin formulations through 2030 sunset dates. Hamburg aerospace clusters co-locate prepreg consolidation with Airbus final assembly operations.
Japan
METI-supported aerospace clusters secure multi-program supply visibility for carbon fiber tow through long-term offtake agreements. JIS standards govern material qualification for domestic commercial aviation applications. Nagoya and Tokyo metropolitan areas concentrate Toray and Teijin manufacturing footprints.
China
Dual carbon goals from MIIT accelerate thermoplastic tow prepreg investment for electric vehicle structural components. GB standards establish domestic certification pathways independent of FAA-EASA frameworks. Yangtze River Delta industrial zones concentrate filament winding capacity for pressure vessel applications.
India
PLI scheme incentives for electric vehicle manufacturing create first-mover positioning for glass fiber tow prepreg in battery enclosure structures. BIS certification requirements govern automotive material qualification timelines. Maharashtra and Gujarat automotive corridors attract localized prepreg converter investment.
Tow Prepreg Market Competitive Environment
Listed leaders compete with private specialists across resin chemistry and fiber placement automation dimensions. The vendor base stratifies into three tiers: integrated carbon fiber-prepreg producers, independent resin formulators, and regional conversion specialists. Two strategic archetypes dominate—vertically integrated chemical conglomerates and aerospace-focused material suppliers. Competitive moves concentrate on thermoplastic qualification acceleration and out-of-autoclave process partnerships.
Within the integrated chemical tier, Hexcel Corporation and Solvay occupy positions spanning carbon fiber production through prepreg formulation. SGL Carbon anchors European supply through its German manufacturing footprint. Toray Industries exemplifies the Japanese conglomerate archetype with backward integration into PAN precursor production. These three represent distinct competitive vectors: North American aerospace dominance, European automotive-aerospace hybrid positioning, and Asian precursor-to-prepreg captive supply chains.
| Leading Market Players |
|---|
| Hexcel Corporation |
| SGL Carbon |
| Teijin Limited |
| Toray Industries |
| Mitsubishi Chemical |
| Solvay |
| TCR Composites |
| Porcher Industries |
| Arisawa Manufacturing |
| Others |
Value Chain & Pricing Dynamics
Ninety-day carbon fiber tow lead times from Japanese precursor suppliers concentrate pricing power among integrated producers with captive PAN production, while spot-market buyers face volatility premiums. Aerospace laminators with five-year offtake agreements lock in resin-chemistry pricing, leaving Tier 2 converters exposed to acrylonitrile feedstock swings.
Pricing Analysis
Three-tier pricing structure across aerospace-qualified, automotive-industrial, and general-composite levels separates customer segments by certification burden and volume commitment. Price differentiation rests on FAA-EASA dual certification status and fiber grade, with aerospace premiums widening as thermoplastic qualification timelines compress. Cost compression in automotive glass fiber tiers is intensifying because Stuttgart OEMs are consolidating supplier panels for battery enclosure programs. General-composite buyers show highest price sensitivity, while qualified aerospace laminators accept premium pricing for program security.
Supply Chain Analysis
Container availability on Asia-North America trade lanes shapes inbound logistics costs for PAN precursor and epoxy resin shipments to Boeing's Everett complex. Geographic supply concentration centers on Japan, Germany, and the United States for aerospace-grade tow, with Chinese filament winding capacity expanding for pressure vessel applications. Raw material dependencies draw from acrylonitrile monomer, epoxy resin systems, and thermoplastic PEEK/PPS pellets. Single-source vulnerability runs through Toray-Teijin-Mitsubishi concentration in PAN-based carbon fiber. Distribution runs through direct mill relationships for qualified aerospace laminators and regional distributors serving automotive Tier 2s.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Shortages of automated fiber placement programming expertise and in-situ consolidation technicians concentrate margin capture among legacy aerospace workforces in Wichita and Toulouse, creating defensive moats for incumbents while constraining expansion for new entrants.
For Market Incumbents: Consolidate backward integration into PAN precursor production to offset Japanese carbon fiber concentration risk, while expanding thermoplastic qualification capacity in Hamburg and Nagoya corridors. Lock in five-year resin supply contracts with Tier 1 aerostructures suppliers before spot-market volatility returns. Priority lever: autoclave infrastructure redeployment toward out-of-autoclave thermoplastic processing partnerships. For New Entrants and Emerging Players: Aftermarket repair and retrofit services for existing thermoset structures represent an underserved layer where incumbents under-serve due to qualification resource allocation toward new programs. Target India's PLI scheme corridors for localized glass fiber tow prepreg conversion in Maharashtra battery enclosure supply chains. Go-to-market angle: weldable thermoplastic joint solutions for Tier 2 laminators lacking autoclave capital. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates with stranded aerospace-materials divisions lacking thermoplastic roadmap investment. Long-term viability favors converters with demonstrated FAA-EASA dual certification track records and established automated fiber placement technician training pipelines. Signal to watch: thermoplastic qualification timeline compression against incumbent thermoset process certifications as inflection indicator for portfolio reweighting.| Strategic Initiative | Industry Significance |
|---|---|
| Thermoplastic Qualification Acceleration | PEEK and PPS matrix approvals compress tool turnaround from days to hours for Airbus and Boeing secondary structures. |
| Backward Integration into PAN Precursor | Captive acrylonitrile-to-tow production insulates margin predictability against oil-derived chemical pricing swings. |
| Out-of-Autoclave Process Partnerships | Weldable joint capabilities enable Tier 2 laminators to compete without capital-intensive autoclave infrastructure. |
| Long-Term Resin Supply Agreements | Five-year offtake contracts with Tier 1 aerostructures suppliers compress working capital flexibility for mid-tier converters. |
| Regional Conversion Footprint Expansion | Localized prepreg consolidation in Stuttgart and Hamburg corridors co-locates with final assembly lines for logistics efficiency. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with automated fiber placement technicians, Tier 1 aerostructures procurement leads, epoxy resin formulators, and EASA certification engineers; and secondary validation through customs/trade data, SEC 10-K filings, FAA airworthiness directives, and REACH substance evaluation timelines. Bottom-up segment sizing triangulated against top-down aerospace and automotive production forecasts.
Across the analysis window, projections modeled fiber grade, resin chemistry, form factor, end-use industry, and regional manufacturing cluster dimensions. CAGRs derived from production volume elasticities and substitution coefficients between thermoset and thermoplastic process economics. Industry-specific inputs included narrowbody wing program ramp rates and PLI scheme incentive disbursement trajectories.
Forecasts assume regulatory continuity in FAA-EASA certification frameworks and REACH chemical restriction timelines; material policy shifts would require re-modeling. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Composite Materials
Biocomposites Market
Composite Materials
LAMEA Composite Process Material Kits Market
Composite Materials
Lignin-Based Graphene Market
Composite Materials
Geosynthetic Cementitious Composite Mats Market
Composite Materials
Asia Pacific Bio Composites Market
Composite Materials
Carbon Thermoplastic Composites Market
Composite Materials
China Marine Composites Market
Composite Materials
Thermoplastic Prepreg Market
Composite Materials
Global Carbon Fiber Reinforced Plastic Market
Composite Materials
Pcb Laminate Materials Market
Composite Materials
High Pressure Laminate (HPL) Market
Composite Materials
Europe Wood-Plastic Composite (WPC) Market
Composite Materials
Medical Composite Material Market
Composite Materials
Global Molded FRP Grating Market
Composite Materials
Polypropylene and Polypropylene Composites Market
Composite Materials
High Temperature Composite Resin Market