
 Chemical Resistant Coatings Market | 2026-2036
Chemical Resistant Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Chemical Resistant Coatings Market Outlook
Asset-light leasing models for coating application equipment is tilting competitive dynamics toward service-integrated suppliers. PPG Industries Inc leverages its captive distribution network to bundle application services with material supply. AkzoNobel NV anchors European demand through specialized marine coating protocols. BASF SE sustains R&D intensity in high-performance epoxy systems for chemical processing environments.
Chemical resistant coatings are formulated polymer systems, typically incorporating epoxy resins, polyurethane binders, or phenolic matrices with corrosion inhibitors, designed to withstand aggressive acids, solvents, and thermal cycling in industrial exposure conditions. These coatings function primarily as barrier protection for steel and concrete substrates in processing equipment, storage vessels, and containment structures. Epoxy coatings dominate protective applications due to their adhesion strength and chemical inertness, while polyurethane formulations capture aesthetic and flexible-use segments where weathering resistance matters. Powder coatings represent the fastest-growing form category as VOC regulations tighten across manufacturing jurisdictions.
EPA corrosion-prevention standards and OSHA workplace exposure limits in the United States mandate regular recoating intervals and specified performance thresholds for chemical handling infrastructure. REACH registration requirements and the EU Green Deal's industrial emissions framework in Europe drive reformulation toward lower-hazard chemistries and extended service-life products. Stakeholders must monitor regulatory divergence between jurisdictions to avoid compliance-driven margin erosion and stranded product registrations.
Market Dynamics
EPA corrosion-prevention mandates are compressing recoating cycles for Gulf Coast chemical processors while powder coating adoption accelerates under tightening VOC regimes across industrialized manufacturing bases.
Growth Catalysts
- REACH registration requirements:European formulators are extending product service lifespans to minimize re-registration burdens, pulling demand toward high-performance epoxy systems with decade-plus durability ratings.
- Pharmaceutical manufacturing clusters:Active ingredient synthesis facilities around Hyderabad and Ahmedabad require acid-resistant containment coatings for reactor vessels and effluent handling infrastructure.
- Epoxy-novolac hybridization:Advanced resin systems combining phenolic crosslink density with epoxy adhesion are penetrating sulfuric acid storage applications previously served by rubber linings.
Market Restraints
- Bisphenol A feedstock volatility:Epoxy resin pricing tracks benzene-propylene spreads, exposing coating manufacturers to margin compression when petrochemical cycles tighten.
- Chinese titanium dioxide concentration:Pigment supply for high-build chemical resistant formulations depends on sulfate-process TiO2 capacity concentrated in eastern China.
- Cure-time limitations:Ambient-cure epoxies require 7-day full chemical resistance development, constraining maintenance windows for continuous-process chemical plants.
Strategic Opportunities
- Biobased epoxy feedstocks:Lignin-derived phenolic precursors and epichlorohydrin from glycerol are enabling low-carbon coating certifications under EU Green Deal industrial emissions frameworks.
- Asset-light application services:Leasing models for plural-component spray equipment reduce capital barriers for mid-sized applicators entering chemical facility maintenance contracts.
- Modular containment systems:Prefabricated double-wall tank designs with factory-applied coatings are displacing field-applied systems in new petrochemical construction.
Industry Challenges
- NACE coating inspector certification scarcity:Qualified inspectors for holiday detection and dry-film thickness verification command premium wages, constraining contractor scaling.
- Surface preparation standards:SSPC-SP10 near-white blast cleaning requirements for immersion service demand specialized containment and abrasive recovery infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chemical Resistant Coatings Market |
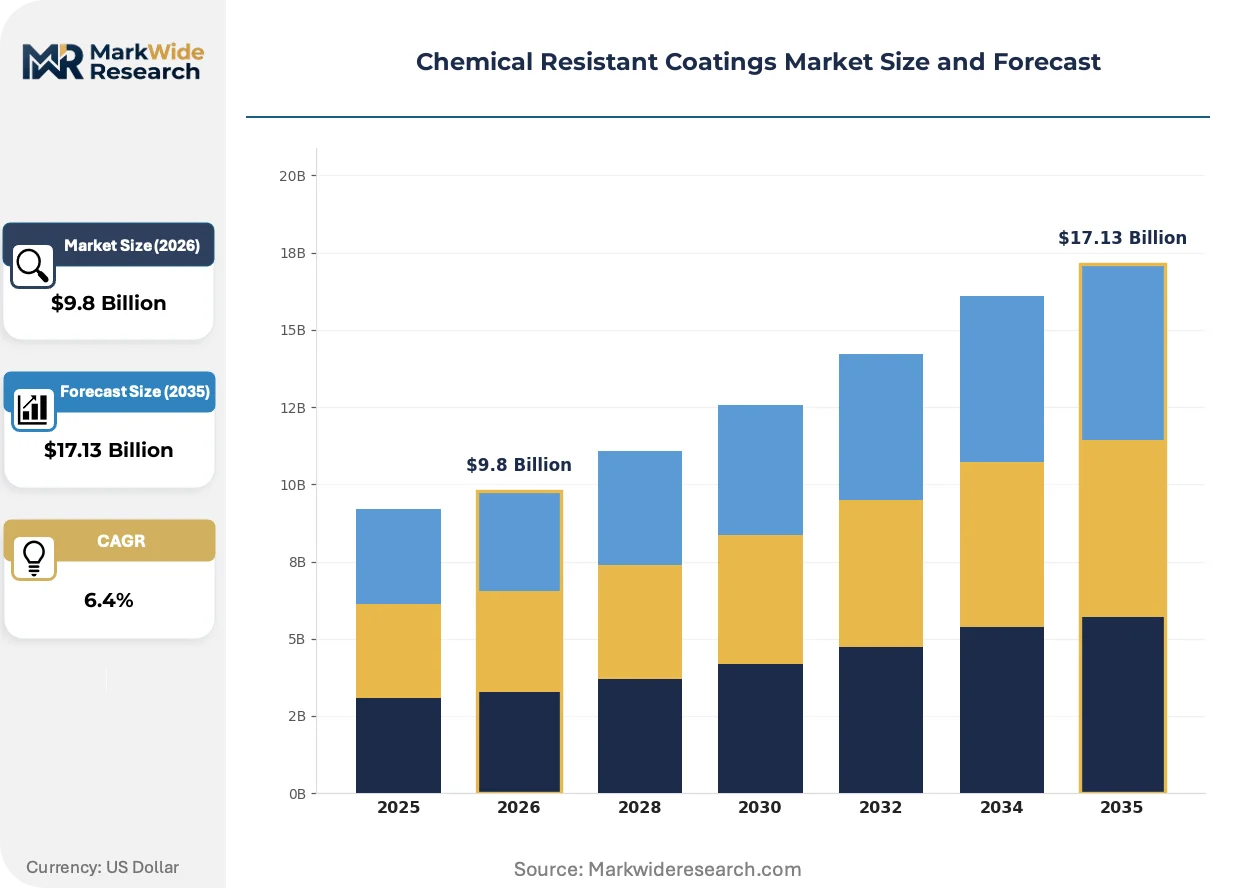
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $17.13 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Epoxy Coatings, Polyurethane Coatings, Acrylic Coatings, Phenolic Coatings End Use Industry: Chemical Manufacturing, Oil & Gas, Marine, Pharmaceuticals Application: Protective Coatings, Aesthetic Coatings, Primers, Floor Coatings Form: Liquid Coatings, Powder Coatings, Aerosol Coatings, Nano Coatings |
| Companies Covered | AkzoNobel NV, Sika AG, PPG Industries Inc, Kansai Paint Co. Ltd, Hempel AS, The Sherwin-Williams Company, Jotun, RPM International Inc, BASF SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chemical Resistant Coatings Market Strategic Shifts
Formulation chemistry is pivoting toward extended-service systems that eliminate volatile organic compounds while maintaining barrier performance under thermal cycling and concentrated acid exposure.
UV-curable oligomer systems are collapsing conventional solventborne and waterborne cure schedules for chemical resistant coatings in secondary containment and flooring applications. Specialty flooring contractors in semiconductor fabrication facilities are specifying these systems for rapid return-to-service during cleanroom maintenance windows. The technology is collapsing the 24-to-72-hour cure windows that previously forced production shutdowns or temporary containment measures.
The EU Green Deal's industrial emissions framework is mandating lifecycle assessment disclosure for protective coating systems procured by EU-based chemical manufacturers. Formulators must now document carbon footprint from raw material extraction through end-of-life, with preference weighting in public procurement scoring. Marine and offshore segments are responding fastest, integrating these requirements into existing IMO environmental compliance protocols.
Integrated coating-and-inspection service contracts are displacing material-only supply relationships in North American chemical processing. Facility operators in the US Gulf Coast are bundling specification development, surface preparation oversight, and warranty administration with volume coating purchases. This consolidation concentrates procurement authority among engineering firms with captive inspection capabilities and long-term maintenance relationships with plant reliability departments.
Chemical Resistant Coatings Market Segmentation
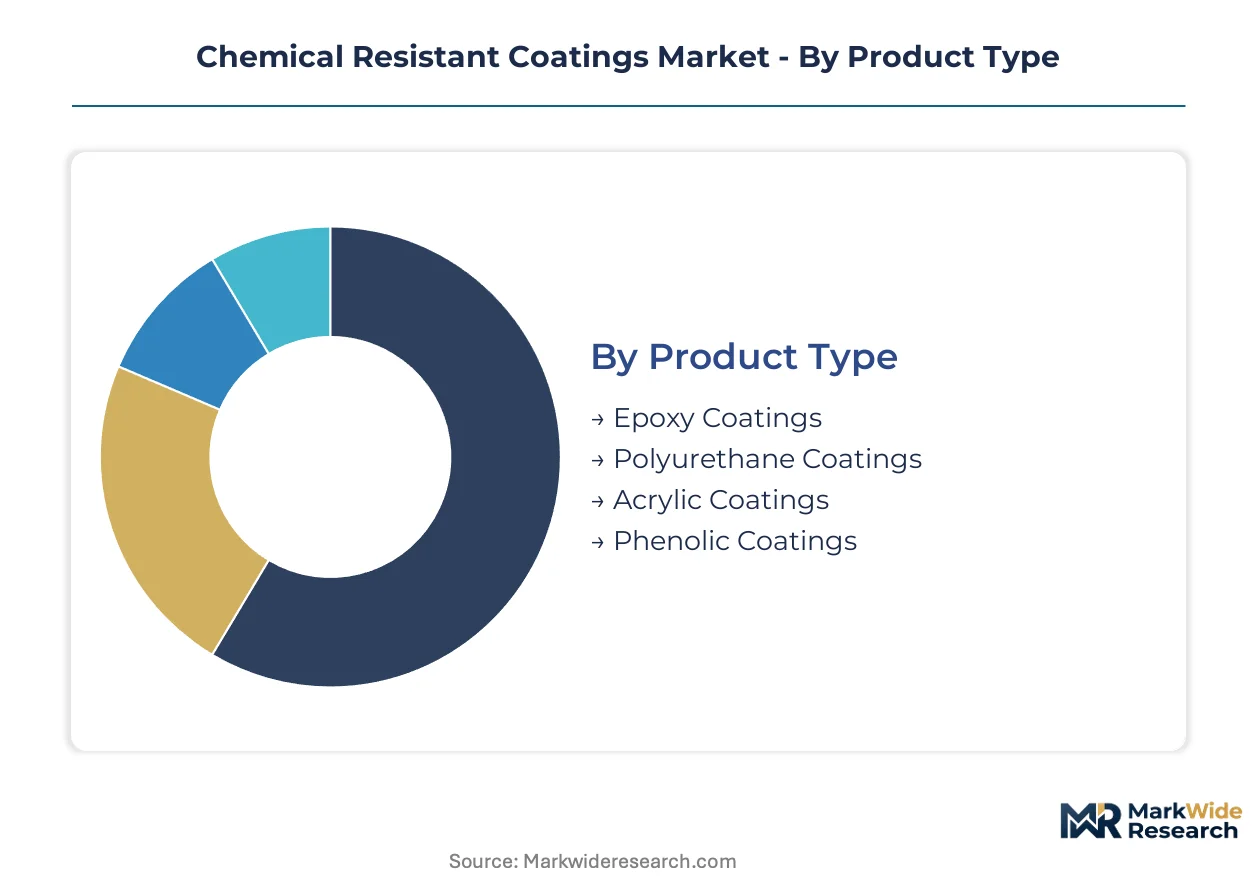
Chemical resistant coatings serve divergent performance requirements across industrial environments. Segmentation reveals how formulation chemistry, application method, and substrate demands create distinct competitive arenas with specialized technical barriers.
Product Type:
Cost tier differentiation separates commodity formulations from engineered systems commanding specification premiums in severe service.
- Epoxy Coatings:These thermosetting systems combine bisphenol-A or novolac resins with polyamine hardeners to achieve dense crosslink structures. Demand concentrates in US Gulf Coast chemical processing infrastructure where EPA corrosion-prevention mandates compress recoating intervals. Their adhesion strength and chemical inertness anchor specification in immersion service.
- Polyurethane Coatings:Aliphatic and aromatic isocyanate-cured systems deliver elastomeric films with UV stability. German automotive component suppliers specify these for weathering-resistant exterior tankage where aesthetic retention matters alongside chemical splash protection.
- Acrylic Coatings:Thermoplastic emulsions and solventborne formulations serve secondary containment and atmospheric exposure with faster recoat windows.
- Phenolic Coatings:High-crosslink density systems from acid-catalyzed condensation provide extreme acid resistance in limited thermal ranges.
Epoxy systems command the established base. The steepest expansion runs through polyurethane formulations penetrating flexible-use specifications.
End Use Industry:
Application severity varies dramatically by sector, with immersion service demanding decade-plus durability ratings against intermittent splash protection.
- Chemical Manufacturing:Sulfuric acid storage, chlorine handling, and solvent recovery operations require specialized novolac-epoxy hybrids. Facilities around the US Gulf Coast are expanding protective coating programs as EPA mandates tighten inspection and recoating protocols for aging infrastructure.
- Oil & Gas:Downstream refineries and midstream terminals need coatings resisting hydrocarbon permeation and sour gas exposure. Indian refining complexes at Jamnagar and Vadodara are specifying high-build epoxy systems for crude storage and product tankage.
- Marine:Ballast tanks, cargo holds, and deck structures face combined salt spray and chemical cargo exposure.
- Pharmaceuticals:Active ingredient synthesis and effluent containment demand acid-resistant barrier coatings with extractables testing for product contact scenarios.
Chemical manufacturing commands the established base. The steepest expansion runs through pharmaceutical applications around Hyderabad and Ahmedabad.
Application:
Volume concentration shifts with infrastructure lifecycle stage, from new construction specifications to maintenance recoating programs.
- Protective Coatings:High-build barrier systems prevent substrate corrosion under chemical immersion and splash conditions. These specifications dominate capital expenditure cycles in petrochemical construction.
- Aesthetic Coatings:Color-stable topcoats serve visibility, safety marking, and corporate identity requirements in non-immersion exposure.
- Primers:Surface-tolerant formulations with corrosion-inhibiting pigments enable adhesion over prepared steel in maintenance contexts.
- Floor Coatings:Self-leveling and trowel-applied systems resist chemical spillage, thermal shock, and mechanical abrasion in processing areas.
Protective applications command the established base. The steepest expansion runs through floor coatings in semiconductor and pharmaceutical cleanroom retrofits.
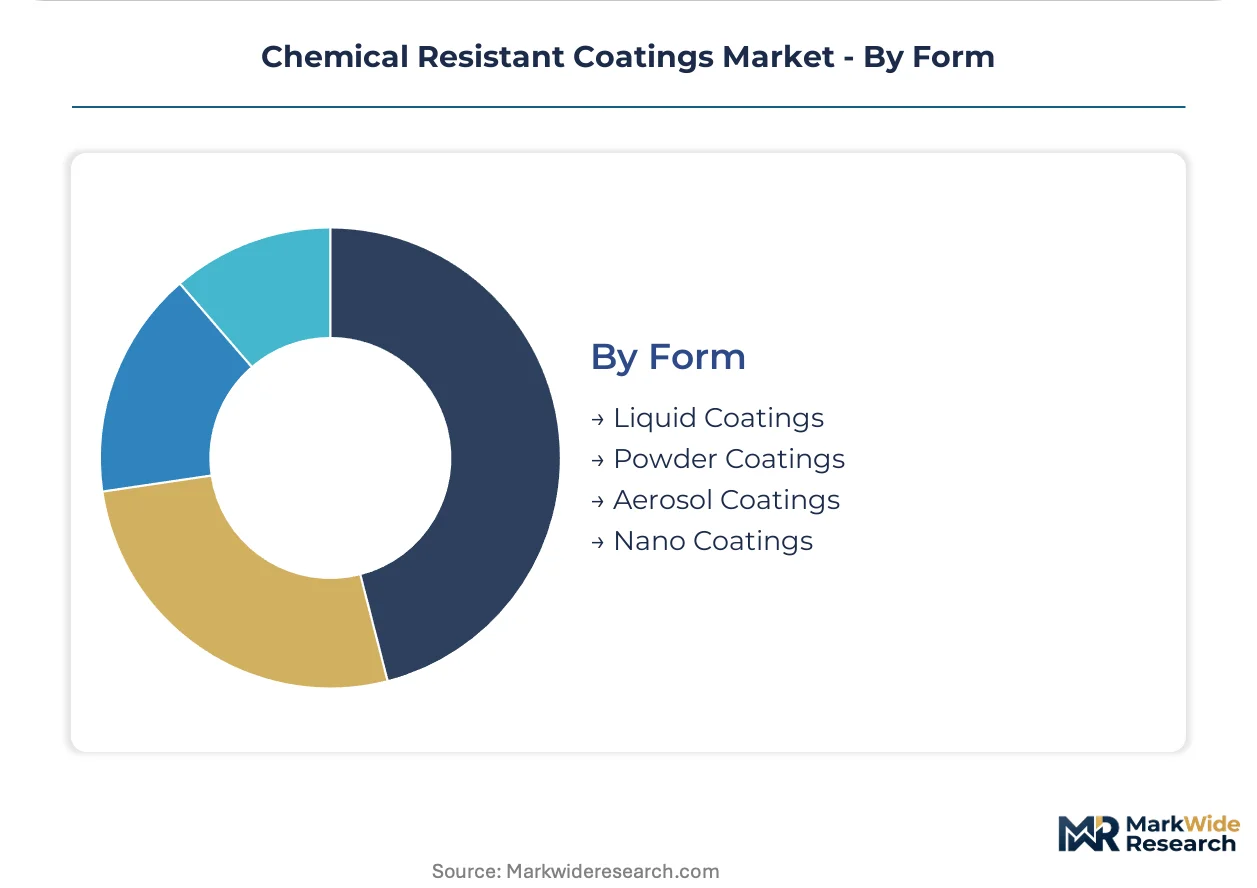
Form:
Customer type preferences split between high-volume applicators seeking transfer efficiency and specialized contractors demanding rapid return-to-service.
- Liquid Coatings:Solventborne and waterborne systems remain dominant in field-applied maintenance work where ambient cure flexibility matters. These formulations capture the majority of recoating volume in existing chemical plants.
- Powder Coatings:Thermosetting epoxy and hybrid powders eliminate VOC emissions and achieve uniform film builds on fabrications. German industrial manufacturers are accelerating adoption under tightening emissions frameworks.
- Aerosol Coatings:Touch-up and small-area repair applications use pressurized packaging for accessibility in confined spaces.
- Nano Coatings:Ultra-thin functional layers with modified surface energy properties penetrate specialized electronics and precision equipment protection.
Liquid formulations command the established base. The steepest expansion runs through powder coatings gaining share in factory-applied OEM specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Multinational chemical processors and regional applicators concentrate procurement authority in distinct geographic clusters, each shaped by local regulatory enforcement and industrial specialization.
United States
Gulf Coast petrochemical complexes drive recoating program expansion as EPA corrosion-prevention mandates compress maintenance intervals. OSHA workplace exposure limits for benzene and hexavalent chromium force specification upgrades in legacy tank farms. Houston-Beaumont-Port Arthur corridor facilities are bundling coating procurement with third-party inspection services under integrated maintenance contracts.
Germany
Automotive component suppliers and industrial machinery OEMs accelerate powder coating adoption under REACH registration burdens and EU Green Deal emissions frameworks. ECHA substance restrictions on isocyanates push reformulation toward blocked prepolymer systems. Bavarian and Baden-Württemberg manufacturing bases are factory-applying high-transfer-efficiency powders to eliminate solventborne VOC emissions.
India
Active pharmaceutical ingredient synthesis and specialty chemical manufacturing create acid-resistant containment demand around Hyderabad and Ahmedabad. CDSCO manufacturing facility inspections mandate extractables-tested coating systems for product-contact surfaces. Gujarat's Dahej and Mundra industrial zones are specifying novolac-epoxy hybrids for sulfuric acid storage and effluent handling infrastructure.
China
Downstream petrochemical construction and semiconductor fabrication drive protective coating specification in Yangtze River Delta and Pearl River Delta clusters. MEE air quality regulations tighten VOC limits for solventborne maintenance coatings in Jiangsu and Zhejiang provinces. Ningbo and Shanghai chemical parks are requiring lifecycle carbon disclosure for coating procurement under provincial dual carbon implementation protocols.
Saudi Arabia
Downstream refinery expansion and desalination infrastructure create specification demand for high-temperature chemical resistant systems. SASO technical regulations for construction materials mandate accelerated corrosion testing for coastal exposure applications. Jubail Industrial City and Yanbu facilities are integrating coating selection with 25-year asset life cycle planning for new petrochemical construction.
Chemical Resistant Coatings Market Competitive Environment
Channel-controlling players compete with product-specialist players across divergent routes to market, creating tiered competitive intensity based on specification authority and application service integration. Integrated coating-and-inspection contracts concentrate procurement among engineering firms with captive NACE-certified inspection capabilities. Three archetypes dominate: multinational formulators with captive distribution networks, regional applicators with maintenance relationships, and equipment-leasing service integrators. Competitive moves center on backward integration into raw material supply and geographic expansion through applicator network acquisition.
Among Netherlands-based multinational formulators, AkzoNobel NV occupies a position exemplifying marine and protective coating specialization through established specification protocols. German chemical conglomerate BASF SE represents the integrated feedstock-to-formulation archetype with captive epoxy resin production. US-based PPG Industries Inc anchors the distribution-integrated service model, bundling material supply with application oversight in North American chemical processing markets.
| Leading Market Players |
|---|
| AkzoNobel NV |
| Sika AG |
| PPG Industries Inc |
| Kansai Paint Co. Ltd |
| Hempel AS |
| The Sherwin-Williams Company |
| Jotun |
| RPM International Inc |
| BASF SE |
| Others |
Value Chain & Pricing Dynamics
Chinese titanium dioxide concentration determines both pricing tier spreads and supply chain shape, as sulfate-process pigment capacity in eastern China anchors cost structures for high-build formulations while creating single-source vulnerability for global formulators.
Pricing Analysis
Cost-plus contracts with benzene-propylene indexation dominate procurement between resin suppliers and coating manufacturers, passing feedstock volatility through to end-users. Price differentiation hinges on ISO 12944 corrosion protection grade and volume scale, with pharmaceutical-grade novolac-epoxy hybrids commanding premiums over standard tank linings. Pricing pressure stems from bisphenol-A feedstock volatility when petrochemical cycles tighten. Mid-sized applicators exhibit highest price sensitivity due to capital constraints on inventory carrying costs.
Supply Chain Analysis
Supplier-financing through 90-day extended payment terms and supply-chain finance facilities has become standard for TiO2 and epoxy resin procurement, easing working capital pressure on formulators. Raw material sourcing draws from China's sulfate-process pigment plants, Germany's specialty amine hardener producers, and Saudi Arabia's petrochemical-derived bisphenol-A output. Single-source vulnerability concentrates in Chinese TiO2 capacity. Distribution runs through PPG's captive applicator networks in North America and specialized marine coating distributors serving European shipyards.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Chemical resistant coatings represent a fragmentation opportunity as integrated coating-and-inspection contracts displace material-only supply relationships, creating niches for service-capable specialists.
For Market Incumbents: Harden specification authority by acquiring NACE-certified inspection firms in the US Gulf Coast, where EPA-mandated recoating cycles concentrate demand. Deepen backward integration into epoxy resin production to buffer margin compression from benzene-propylene spread volatility. Lock in pharmaceutical corridor relationships through CDSCO-compliant extractables testing capabilities. For New Entrants and Emerging Players: Build out asset-light application service models targeting mid-sized Indian pharmaceutical manufacturers around Hyderabad and Ahmedabad, where capital constraints limit in-house coating infrastructure. Capture share in UV-curable flooring for semiconductor cleanroom retrofits through rapid return-to-service positioning. Partner with plural-component spray equipment lessors to minimize capital barriers. For Investors and Strategic Acquirers: EU Green Deal lifecycle assessment mandates reshape the acquisition landscape toward formulators with documented carbon footprint transparency and biobased epoxy certifications. Target regional applicators with captive inspection capabilities and long-term plant reliability relationships. Watch for REACH re-registration deadlines as inflection indicators for consolidation pressure on smaller European formulators.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Epoxy Resin | Captive bisphenol-A supply buffers margin compression from petrochemical volatility cycles. |
| NACE-Certified Inspection Acquisition | Integrated coating-and-inspection contracts concentrate procurement authority in Gulf Coast chemical processing. |
| Biobased Feedstock Certification | Lignin-derived phenolic precursors unlock EU Green Deal procurement preference weighting. |
| UV-Curable Formulation Launch | Collapsing cure windows from 72 hours to minutes penetrates semiconductor cleanroom maintenance. |
| Modular Containment System Partnership | Factory-applied coating on prefabricated tanks displaces field application in new petrochemical construction. |
Study Parameters
Desk research of customs trade data, ACC and Cefic industry reports, and SEC 10-K filings preceded structured interviews with plant reliability managers, coating procurement leads at Gulf Coast chemical processors, NACE-certified inspection contractors, and specialty resin R&D directors. Primary fieldwork validated formulation trends and recoating cycle compression under EPA mandates. Bottom-up volume estimates triangulated against top-down value projections.
Assumptions held regulatory enforcement intensity and petrochemical feedstock spreads within historical bands while varying pharmaceutical manufacturing capacity expansion rates and powder coating adoption curves across geographies. Segmentation modeling spanned formulation chemistry, end-use industry, application method, and regional regulatory cluster. CAGRs derived from slope analysis of segment-specific volume trajectories, cross-referenced with capital expenditure pipelines in chemical processing and semiconductor fabrication.
Sensitivities concentrate around REACH substance restriction timelines, Chinese environmental enforcement intensity affecting TiO2 supply, and pharmaceutical capital expenditure cycles. Forecasts reflect documented assumptions on regulatory trajectory and feedstock cost structures. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
PACVD-Based Coatings Market
Coatings
Diamond-Like Carbon Coatings Market
Coatings
Nigeria Protective Coatings Market
Coatings
Insulation Coating Market
Coatings
High Build Rust Stabilizer with Reinforced Glass Flake Coating Market
Coatings
Global Low Temperature Powder Coatings Market
Coatings
Mexico Industrial Wood Coatings Market
Coatings
Middle East and Africa Super Hydrophobic Coatings Market
Coatings
Asia-Pacific Superhydrophobic Coating Market
Coatings
Middle-East and Africa Coil Coatings Market
Coatings
Global Sputter Coatings Market
Coatings
Electrocoat Market
Coatings
Zero Friction Coatings Market
Coatings
Russia Protective Coatings Market
Coatings
Non-Stick Coatings Market
Coatings
Electron Beam Curable Coating Market