
 GCC Decorative Laminates Market | 2026-2036
GCC Decorative Laminates Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Decorative Laminates Market Intelligence
Market Context
High-pressure laminate specifications with enhanced scratch and thermal resistance is reorganizing procurement priorities across Gulf fit-out contractors. Greenlam Industries leverages its Indian manufacturing base to supply cost-competitive decorative surfaces into Saudi Arabia's residential boom. Wilsonart sustains premium positioning through specialized distribution partnerships serving UAE hospitality developers. EGGER Group anchors its regional presence with European-sourced laminate collections targeting commercial office specifications in Qatar.
Technical Definition and Segment Structure
GCC decorative laminates are multi-layered thermosetting resin-impregnated sheets, typically comprising kraft paper cores saturated with phenolic resin and decorative overlays bonded with melamine formaldehyde, cured under heat and pressure to produce hard, dimensionally stable surfacing materials for interior applications. High-pressure laminates dominate value capture given their superior durability and moisture resistance in commercial kitchens and healthcare settings, while low-pressure laminates compete aggressively on furniture and cabinetry volumes through cost-optimized direct-lamination processes. Wall panel applications show the strongest structural momentum as Gulf developers prioritize integrated interior systems over traditional finishing trades, with flooring remaining the most mature application category characterized by established supplier relationships and thinner margin pools.
Regulatory Framework
Saudi Arabia's Saudi Standards, Metrology and Quality Organization (SASO) SABER platform mandates product conformity certificates for imported decorative laminates, while UAE Civil Defence fire-safety regulations classify interior surface materials by flame-spread indices that directly determine laminate specification eligibility. Qatar's Public Works Authority (ASHGHAL) material approval processes and Kuwait's Ministry of Commerce quality mark requirements add further compliance layers that favor suppliers with established certification infrastructure. Stakeholders must monitor evolving Gulf Cooperation Council harmonization initiatives for building material standards, as unified technical regulations would reshape competitive access across member states.
Market Dynamics
Saudi Arabia's SABER conformity platform and UAE Civil Defence fire-safety codes are tightening certification requirements for interior surfacing materials, forcing procurement departments to prioritize pre-certified suppliers over price-optimized alternatives.
Growth Catalysts
- Hospitality fit-out surge:Dubai and Riyadh hotel developments are specifying scratch-resistant high-pressure laminates for guest room surfaces and food-service areas.
- SASO SABER mandates:Saudi Arabia's product conformity certificates are filtering out non-compliant imports, creating protected market access for certified suppliers.
- Wall panel integration:Gulf developers are specifying factory-laminated interior systems that reduce on-site finishing labor and accelerate project handovers.
Market Restraints
- Kraft paper and phenolic resin volatility:Raw material cost swings compress margins for laminate manufacturers serving price-sensitive furniture segments.
- European supply concentration:Premium decorative paper and specialized overlay films depend on mills in Germany and Italy, exposing buyers to euro-denominated input cost pressure.
- Low-pressure laminate substitution:Direct-lamination processes for mass-market cabinetry are capturing volume that high-pressure laminates cannot serve profitably.
Strategic Opportunities
- Qatar commercial office pipeline:ASHGHAL material approvals favor suppliers with established Gulf certification infrastructure for upcoming government and private sector fit-outs.
- Healthcare surfacing specifications:Antimicrobial laminate grades are penetrating hospital and clinic renovations across the Emirates and Saudi Arabia.
- E-commerce distribution:Direct-to-contractor digital platforms are compressing traditional distributor markups for standardized laminate sheet orders.
Industry Challenges
- Fire-rating certification timelines:UAE Civil Defence flame-spread testing delays are extending project procurement cycles and compressing installation windows.
- Skilled applicator scarcity:Post-formed edge banding and precision cutting for high-end hospitality specifications require trained installers that Gulf labor markets undersupply.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Decorative Laminates Market |
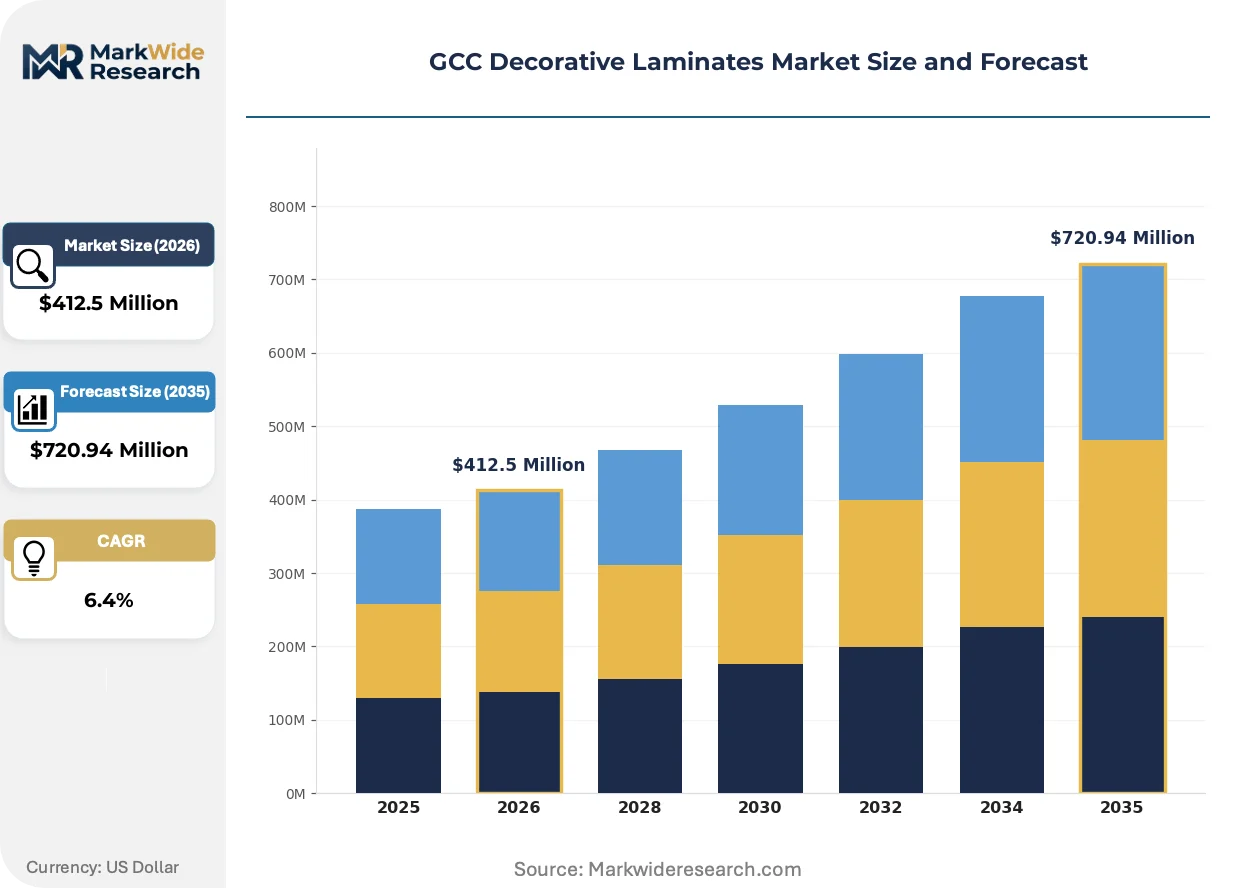
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $720.94 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High-Pressure Laminates, Low-Pressure Laminates, Backed Laminates, Overlay Laminates End User: Residential, Commercial, Hospitality, Retail Application: Countertops, Wall Panels, Furniture, Flooring Distribution Channel: Direct Sales, Distributors, Online Retail, Specialty Stores |
| Companies Covered | Greenlam Industries, Formica Corporation, Wilsonart, EGGER Group, Kronospan, Sonae Arauco, Arauco, Archidply Industries, FunderMax, Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Decorative Laminates Market Strategic Shifts & Innovations
Digital printing and antimicrobial surface treatments are redefining performance expectations for interior laminates, while regulatory harmonization pressures are consolidating supplier qualification requirements across Gulf markets.
Thin-gauge high-pressure laminates with enhanced thermal stability are displacing traditional solid-surface materials in commercial kitchen specifications. Dubai hospitality developers are specifying these grades for back-of-house durability. The shift is compressing solid-surface market share in food-service environments where heat resistance determines material selection.
UAE Civil Defence updated fire-safety classifications for interior finishes are mandating lower flame-spread indices for high-occupancy buildings. This regulatory tightening is disqualifying uncertified laminate grades from hotel and hospital specifications. Procurement teams in Dubai and Abu Dhabi are now requiring third-party test reports before issuing purchase orders.
Direct specification relationships between laminate manufacturers and Gulf fit-out contractors are displacing traditional distributor-led sales models for large commercial projects. Major hospitality developers in Riyadh and Doha are negotiating frame agreements that bypass regional stockists. This channel compression is visible most acutely in premium commercial segments where volume certainty justifies customized production runs.
GCC Decorative Laminates Market Segmentation
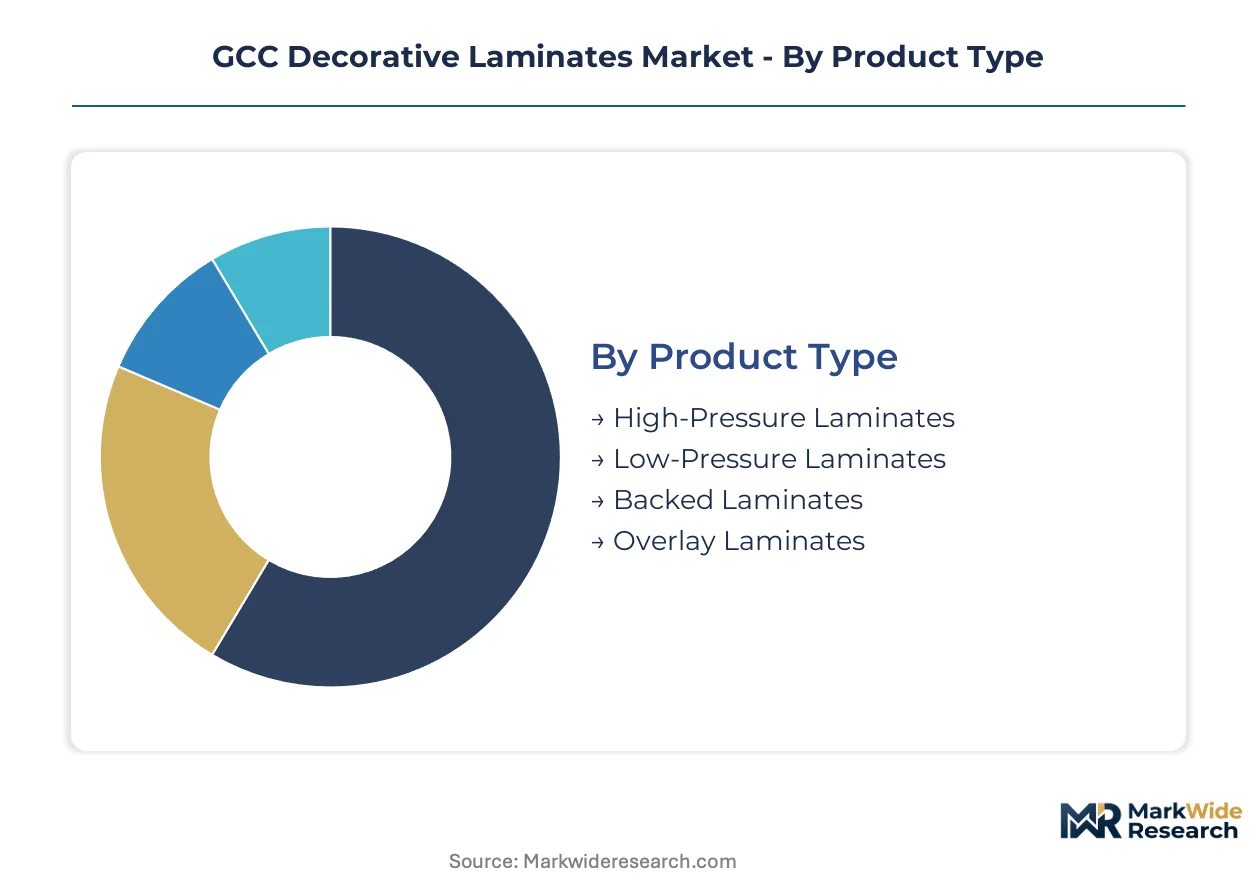
Segmentation in the GCC decorative laminates market reveals how product specifications, end-use requirements, and procurement channels create distinct margin pools. Understanding these divides helps suppliers allocate certification investments and distribution resources across a region with fragmented regulatory requirements.
Product Type:
Margin concentration sits with performance-graded laminates that command specification premiums in commercial and hospitality fit-outs.
- High-Pressure Laminates:Multi-layer construction with phenolic resin-impregnated kraft cores delivers superior scratch and thermal resistance. Demand clusters in Dubai and Riyadh hospitality kitchens where SASO SABER certification and UAE Civil Defence fire ratings filter out lower-grade alternatives.
- Low-Pressure Laminates:Direct-lamination onto particleboard substrates offers cost-optimized surfacing for mass-market furniture. Saudi Arabia's residential construction boom absorbs volume through price-sensitive procurement channels that prioritize local availability over performance specifications.
- Backed Laminates:Pre-glued or peel-and-stick variants reduce on-site adhesive application labor for renovation contractors.
- Overlay Laminates:Thin decorative films applied to engineered wood panels serve budget cabinetry segments in Qatar's emerging residential zones.
The dominant share belongs to High-Pressure Laminates, while Backed Laminates are gaining share fastest through renovation-focused distribution.
End User:
Volume flows toward project-driven segments where frame agreements and developer relationships override spot-market purchasing.
- Commercial:Office fit-outs in Doha and Abu Dhabi specify antimicrobial and fire-rated grades for high-occupancy environments. ASHGHAL material approvals in Qatar and UAE Civil Defence classifications create procurement friction that favors pre-certified suppliers.
- Hospitality:Dubai hotel developments and Riyadh entertainment district projects drive premium surfacing demand. Scratch-resistant grades for food-service areas and guest room durability specifications command the highest unit margins in the regional market.
- Residential:Saudi Arabia's giga-project housing and UAE apartment completions absorb standard-grade laminates through bulk contractor purchasing.
- Retail:Fit-out cycles for shopping malls and flagship stores in Kuwait City and Manama generate episodic demand with tight installation windows.
Commercial captures the largest revenue pool, though Hospitality exhibits the steepest expansion trajectory as Dubai and Riyadh development pipelines accelerate.
Application:
Specification complexity varies sharply by installation environment, with moisture exposure and fire-safety requirements determining grade eligibility.
- Wall Panels:Factory-laminated interior systems are displacing traditional on-site finishing in Gulf commercial projects. Integrated panel solutions reduce labor costs and accelerate handovers for Dubai developers facing compressed construction schedules.
- Countertops:High-pressure grades with enhanced thermal stability dominate commercial kitchen specifications. Thin-gauge laminates are displacing solid-surface materials in back-of-house food-service environments across UAE hospitality developments.
- Furniture:Cabinetry and millwork applications split between cost-driven low-pressure direct lamination and premium high-pressure edge-banded construction.
- Flooring:Established supplier relationships and thinner margins characterize this mature category where vinyl and engineered wood alternatives compete aggressively.
Wall Panels holds the dominant position, while Countertops is climbing the fastest as thermal-resistant specifications penetrate food-service fit-outs.
Distribution Channel:
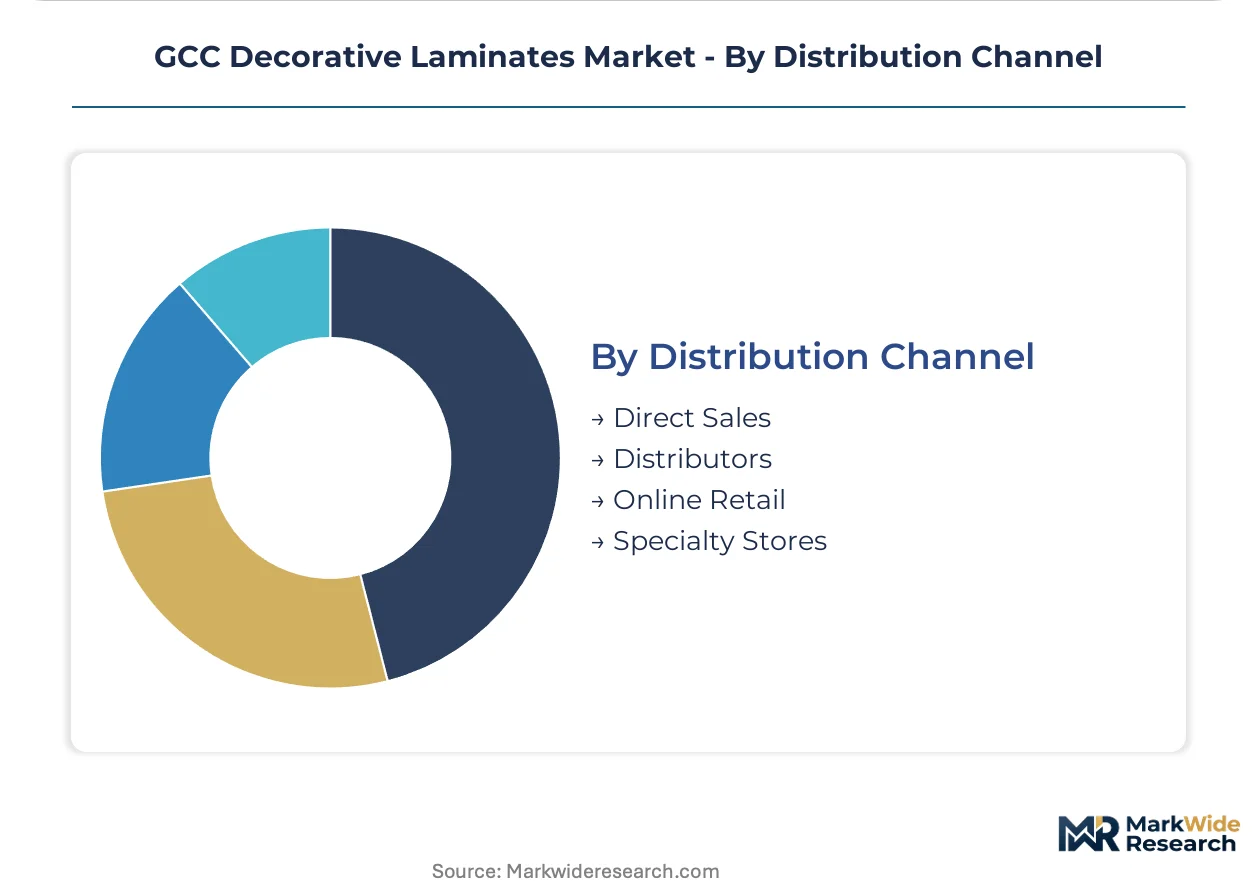
Channel economics reflect project scale certainty, with direct relationships compressing traditional distributor markups where volume justifies customized production.
- Direct Sales:Frame agreements between manufacturers and major hospitality developers in Riyadh and Doha bypass regional stockists. Volume certainty enables customized production runs and dedicated inventory allocation.
- Distributors:Regional stockists maintain inventory positions for spot-market procurement by smaller fit-out contractors. SASO SABER certification requirements favor distributors with established conformity infrastructure.
- Online Retail:Digital platforms targeting standardized sheet orders are compressing markups for small contractors and renovation specialists.
- Specialty Stores:Showroom-based specification support serves high-end residential and boutique commercial projects requiring material sampling and color matching.
Distributors retain the largest volume share, though Direct Sales is expanding most quickly as major developers consolidate procurement relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing capacity for decorative laminates concentrates in India and Europe, with Gulf markets depending on imported supply chains. Certification requirements vary sharply across member states, creating differentiated access conditions for suppliers.
United Arab Emirates
Dubai's hospitality construction pipeline drives premium laminate specifications for hotel fit-outs and entertainment venues. UAE Civil Defence mandates flame-spread classifications for interior finishes in high-occupancy buildings. Dubai Design District and Dubai South industrial zones concentrate procurement activity for megaproject developers seeking fire-rated surfacing materials.
Saudi Arabia
Riyadh's giga-project residential boom and entertainment district developments absorb volume across all laminate grades. SASO SABER conformity certificates filter non-compliant imports, creating protected market access for certified suppliers. Jeddah and Dammam serve as secondary demand nodes for Red Sea tourism projects and Eastern Province industrial facilities.
Qatar
Doha's commercial office pipeline and government infrastructure spending sustain mid-market laminate demand. ASHGHAL material approval processes favor suppliers with established Gulf certification infrastructure. Lusail City and Education City clusters generate concentrated specifications for integrated wall panel systems in institutional buildings.
Kuwait
Kuwait City retail and residential fit-outs generate episodic demand with tight installation windows. Ministry of Commerce quality mark requirements add compliance layers that favor distributors with established conformity infrastructure. Al Ahmadi industrial zone hosts fabrication facilities serving contractor procurement for oil sector housing projects.
GCC Decorative Laminates Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes across the GCC decorative laminates market. European manufacturers anchor premium positioning through specialized decorative paper and fire-rated formulations, while Asian suppliers compete on cost-optimized direct-lamination volumes. Three archetypes dominate: integrated European producers with captive decorative paper mills, Indian manufacturers leveraging scale and proximity, and regional distributors with SASO SABER certification infrastructure. Competitive moves center on frame agreement negotiations with hospitality developers and backward integration into kraft paper supply.
Among European-anchored producers, EGGER Group and FunderMax exemplify the premium-tier archetype serving commercial office and hospitality specifications. Greenlam Industries represents the cost-leadership position, leveraging Indian manufacturing proximity to supply Saudi Arabia's residential construction surge. Wilsonart occupies a position between these poles, sustaining specialized distribution partnerships for UAE hospitality developers requiring scratch-resistant and fire-rated grades.
| Leading Market Players |
|---|
| Greenlam Industries |
| Formica Corporation |
| Wilsonart |
| EGGER Group |
| Kronospan |
| Sonae Arauco |
| Arauco |
| Archidply Industries |
| FunderMax |
| Others |
Cost & Logistics Intelligence
Long-term frame agreements between Gulf hospitality developers and laminate manufacturers lock in supply access and price visibility across multi-year project pipelines. These contracts insulate certified suppliers from kraft paper and phenolic resin volatility while exposing spot-market buyers to input cost swings.
Pricing Analysis
SASO SABER conformity requirements dictate the pricing tier structure across the GCC decorative laminates market. Pricing stratifies across fire-rated premium grades for Dubai hospitality fit-outs, standard certified tiers for Saudi residential bulk procurement, and economy direct-lamination volumes serving Qatar's emerging residential zones. Cost compression in low-pressure laminate segments is intensifying because Indian manufacturers leverage proximity advantages to undercut European suppliers on mass-market furniture specifications. Saudi Arabia's giga-project contractors exhibit the highest price sensitivity, while UAE hospitality developers prioritize performance certification over unit cost.
Supply Chain Analysis
India and Germany anchor decorative laminate manufacturing for Gulf markets, with Indian mills feeding Saudi Arabia's residential surge and German producers supplying fire-rated collections for UAE commercial specifications. Kraft paper cores, phenolic resins, and decorative overlay films feed from European and Asian chemical complexes. Single-source vulnerability concentrates in specialized decorative paper mills located in Italy and Germany. Distribution runs through Dubai-based regional stockists holding SASO SABER-certified inventory for spot-market procurement by smaller fit-out contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The GCC decorative laminates market sits in a cyclical recovery phase driven by Dubai and Riyadh hospitality construction pipelines accelerating post-pandemic fit-out schedules.
For Market Incumbents: Consolidate certification infrastructure across SASO SABER, UAE Civil Defence, and ASHGHAL approval frameworks to defend against Asian cost competitors. Deepen backward integration into kraft paper supply to offset European input cost volatility. Lock frame agreements with Riyadh entertainment district developers before procurement consolidates around fewer pre-qualified suppliers. For New Entrants and Emerging Players: Differentiate on antimicrobial surface treatments for UAE and Saudi healthcare renovation specifications where incumbent coverage remains thin. Target Qatar's commercial office pipeline through ASHGHAL pre-approval investment, bypassing saturated Dubai hospitality channels. Pursue direct-to-contractor digital platforms for standardized sheet orders to compress traditional distributor markups. For Investors and Strategic Acquirers: The market sits at an early-expansion phase that favors certification-capable mid-cap suppliers over undifferentiated volume players. Five-to-ten-year viability hinges on regulatory harmonization progress across Gulf Cooperation Council member states. Watch for unified technical regulations as the inflection signal that would reshape competitive access and trigger consolidation among distributors lacking multi-market conformity infrastructure.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Market Certification Investment | SASO SABER, UAE Civil Defence, and ASHGHAL approvals unlock protected access across Saudi Arabia, UAE, and Qatar procurement channels. |
| Backward Integration into Kraft Paper | In-house phenolic resin saturation capacity insulates margins from European pulp cost volatility affecting laminate manufacturers. |
| Direct Distribution Platform Launch | Digital channels targeting standardized sheet orders compress 15-20% distributor markups for small contractor procurement. |
| Antimicrobial Grade Development | Hospital and clinic surfacing specifications across Emirates and Saudi Arabia create premium pricing tiers above commodity laminates. |
| Frame Agreement Negotiation | Volume commitments with Riyadh and Doha hospitality developers secure dedicated production runs and inventory allocation priority. |
Research Approach
Operator-level perspectives from fit-out contractor procurement directors, hospitality developer project managers, laminate distributor inventory planners, and SASO SABER certification consultants anchored the qualitative base. Primary interviews triangulated with secondary validation from UAE Civil Defence fire-safety classifications, Saudi Standards Metrology and Quality Organization technical regulations, Qatar Public Works Authority material approval databases, and customs trade records documenting kraft paper and resin import flows. Bottom-up project pipeline assessments and top-down construction spend forecasts cross-validated volume estimates.
Sensitivity analysis tested forecast outputs against variations in hospitality construction completion rates, raw material cost trajectories, and regulatory harmonization timelines across the projection horizon. Segmentation modeling captured product type tiers, end-user industry verticals, application environments, and distribution channel economics. CAGRs derived from fitted growth curves applied to disclosed project values and per-square-meter laminate intensity coefficients. Antimicrobial grade penetration rates and wall panel system adoption curves served as industry-specific demand drivers.
Material uncertainties — construction schedule delays, euro-denominated input cost spikes, and Gulf Cooperation Council regulatory harmonization setbacks — sit outside the modeled envelope. Forecasts reflect assumptions about certification timeline stability and project financing continuity. Recalibration cycles align with material shifts in hospitality pipeline announcements and SASO SABER platform rule modifications.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Composite Materials
Fiber Reinforced Composite Tapes Market
Composite Materials
Composites Distributor Market
Composite Materials
Organosheet and Semi-Finished Thermoplastic UD-Tape Laminate Market
Composite Materials
Global Wind Turbine Composites Material Market
Composite Materials
Lignin-Based Graphene Market
Composite Materials
Reinforced Plastic Sheeting Market
Composite Materials
Reinforced Plastics Market
Composite Materials
Isostatic Graphite Market
Composite Materials
Lightweight Materials Market
Composite Materials
Carbon Composites Market
Composite Materials
Biocomposites Market
Composite Materials
High Frequency High Speed Copper Clad Laminate CCL Market
Composite Materials
High-Temperature Composite Materials Market
Composite Materials
Reinforced Nonwoven Plastics Market
Composite Materials
Ultra-Lightweight Cement Composites Market
Composite Materials
Global Carbon Fiber Reinforced Plastic Market