
 Marine Composites Market | 2026-2036
Marine Composites Market Size, Share, and Industry Trends Forecast 2026-2036
Marine Composites Market Intelligence
European prepreg manufacturing is shifting toward larger autoclave capacity to serve next-generation hull programs. Toray Industries leverages its carbon fiber vertical integration to supply pressure-vessel-grade prepregs for high-performance sailing yachts. Hexcel Corporation anchors North American supply through advanced resin formulation capabilities for military patrol craft. Gurit Holding AG specializes in structural core kits that reduce laminate weight for competitive racing segments.
Marine composites encompass fiber-reinforced polymer systems engineered for submerged and atmospheric marine exposure, typically combining glass or carbon fibers with epoxy, vinyl ester, or polyester matrices to achieve specific strength-to-weight ratios and osmotic resistance. Their primary purpose is to replace corrosion-prone metals in hulls, decks, and superstructures while reducing fuel consumption through mass reduction. Fiber Reinforced Plastics dominates value capture due to decades of process maturation and repair infrastructure density, while Core Materials commands premium margins in racing and defense applications where shear stiffness justifies balsa or syntactic foam substitution. Resins represents the fastest-growing chemistry segment as formulators develop low-VOC systems that satisfy tightening workplace exposure limits without sacrificing infusion speed.
EMA's MDR framework pressures hull manufacturers to document laminate traceability for passenger-carrying vessels, while REACH restricts certain styrene-based formulations in European production environments. The EU Green Deal's embodied carbon tracking requirements are forcing shipyards to certify fiber sourcing and resin bio-content across supply tiers. Stakeholders must monitor how IMO's evolving lifecycle assessment protocols for vessels will cascade into composite specification language within classification society rules.
Market Dynamics
Carbon fiber hull adoption in naval defense procurement across France and Italy is compressing design cycles and forcing laminate suppliers to certify traceability under tightening EMA oversight for passenger vessels.
Growth Catalysts
- EU Green Deal emissions mandates:Yacht builders in Germany and the Netherlands face binding embodied carbon thresholds that accelerate fiberglass-to-carbon transitions in superstructure construction.
- Naval patrol craft modernization:Defense procurement offices specify carbon fiber monocoque hulls for next-generation interceptors, concentrating demand in Mediterranean shipyards.
- Prepreg out-of-autoclave curing:Advanced resin chemistry enables vacuum infusion at ambient pressure, reducing capital barriers for mid-tier hull manufacturers.
Market Restraints
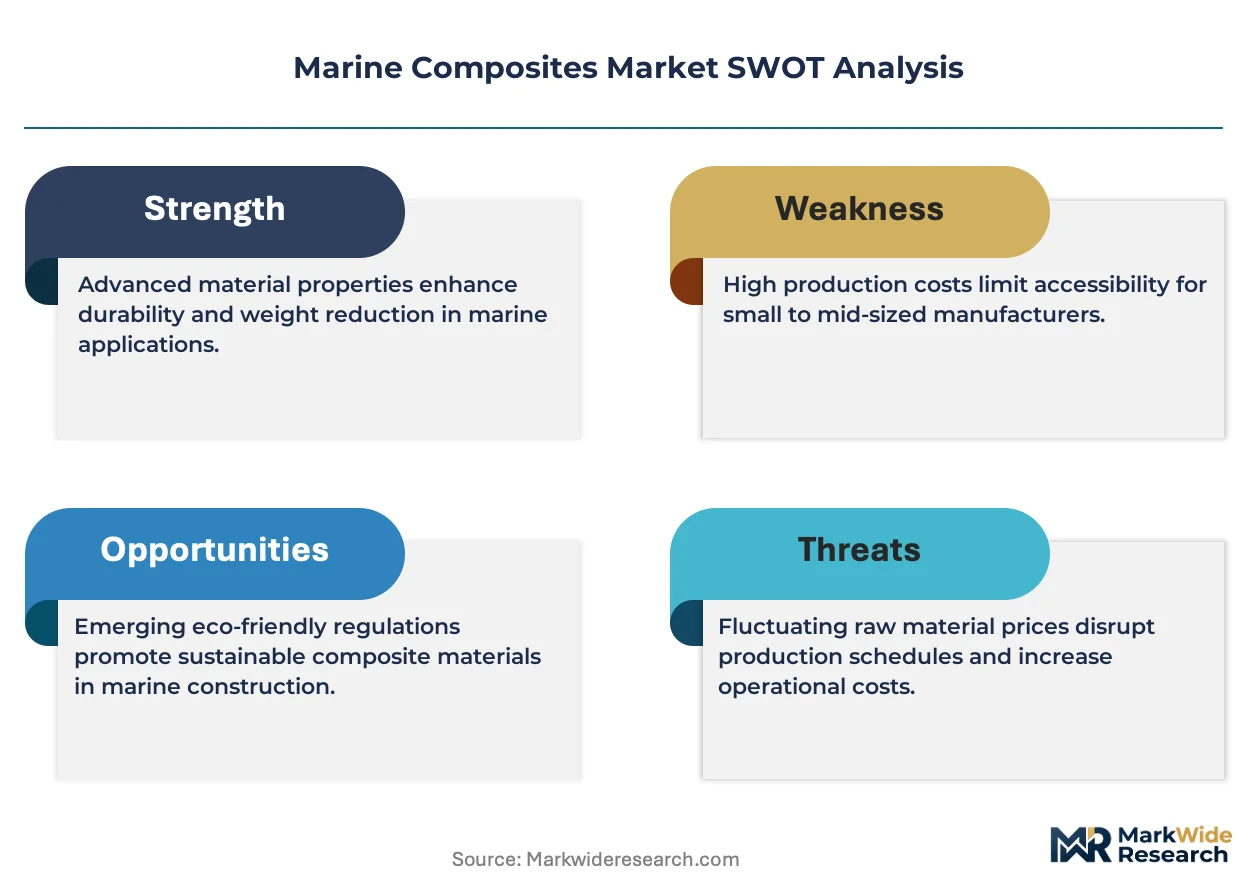
- Carbon fiber supply concentration:Precursor acrylonitrile and tow conversion capacity clusters in Japan and the United States, exposing European hull builders to currency and shipping volatility.
- REACH styrene restrictions:ECHA classification of certain vinyl ester formulations as substances of very high concern forces reformulation investments without immediate performance parity.
- Metallic hull repair infrastructure:Established aluminum and steel drydock networks in Baltic ports create switching friction for composite adoption in commercial ferry segments.
Strategic Opportunities
- Hydrogen storage pressure vessels:Sailing yacht builders in Norway leverage filament winding expertise to enter emerging marine hydrogen tank supply chains.
- Structural core kit modularization:Balsa and syntactic foam core suppliers develop pre-cut panel systems that reduce laminate labor hours for competitive racing segments.
- EU taxonomy alignment:Shipyards certifying bio-based resin content and recycled fiber sourcing gain preferential financing under the European Green Deal investment framework.
Industry Challenges
- Laminate technician certification gaps:EMA MDR documentation requirements for passenger vessels exceed current vocational training capacity in Mediterranean manufacturing clusters.
- Autoclave capacity bottlenecks:Next-generation hull programs require pressure vessel-grade cure cycles that exceed existing oven dimensions at most European prepreg facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Marine Composites Market |
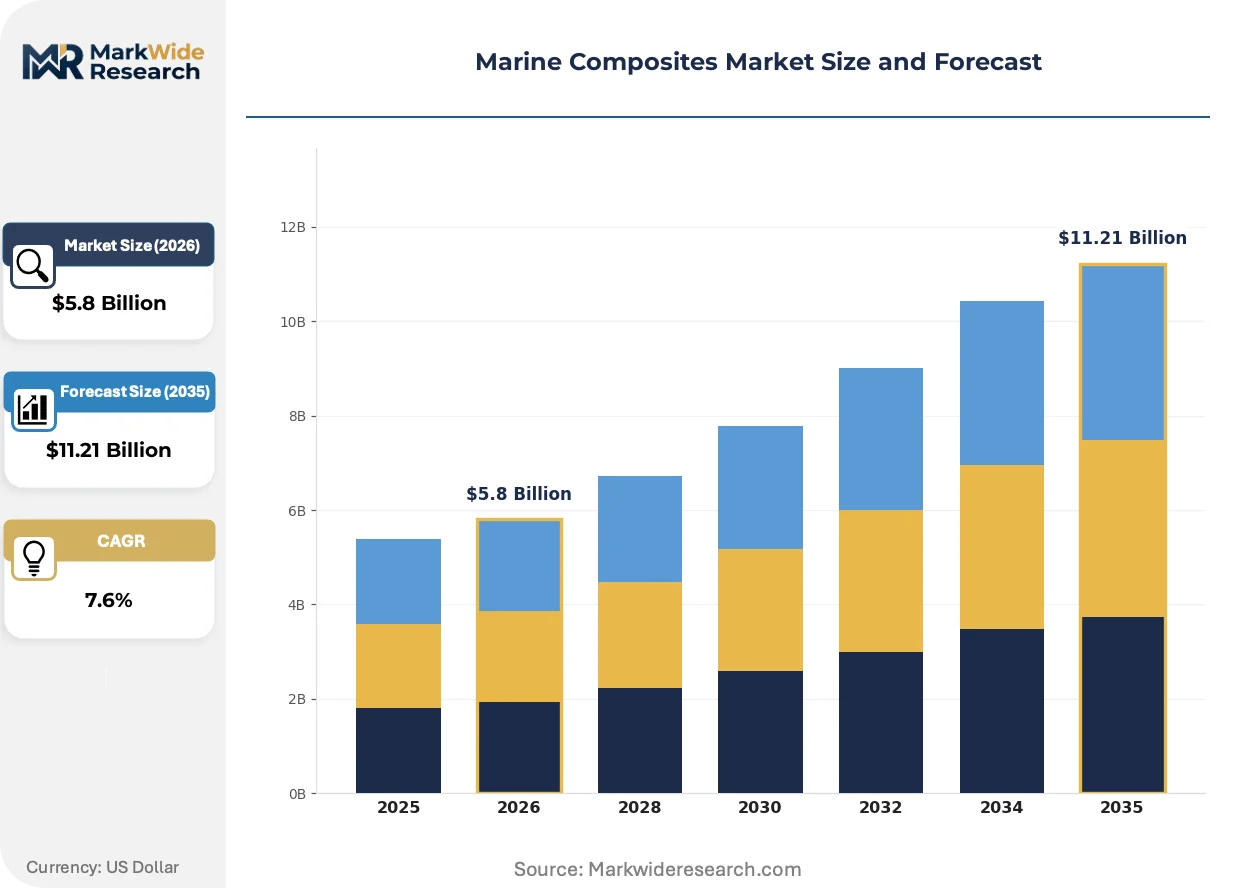
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $11.21 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fiber Reinforced Plastics, Gel Coatings, Core Materials, Resins Application: Sailing Yachts, Powerboats, Fishing Vessels, Commercial Ships End User: OEMs, Marine Repair Services, Shipbuilders, Boat Manufacturers Distribution Channel: Direct Sales, Distributors, Online Sales, Retailers |
| Companies Covered | Toray Industries, Inc., Hexcel Corporation, Gurit Holding AG, Owens Corning, SGL Carbon SE, Teijin Limited, Mitsubishi Chemical Corporation, DuPont, Huntsman Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Marine Composites Market Strategic Shifts & Innovations
Process automation and materials traceability systems are compressing quality assurance timelines while enabling new compliance documentation formats demanded by classification societies.
Automated fiber placement systems for complex hull geometries are integrating robotic tow steering with real-time compaction control. Italian superyacht builders deploy these systems to reduce laminate void content below 0.5 percent. The technology is integrating quality data logging directly into classification society submission packages, compressing certification timelines by eliminating manual inspection sampling.
EMA's MDR framework for medical device traceability is cross-pollinating into marine passenger vessel documentation requirements. Laminate batch records must now link fiber lot numbers to specific hull structural sections. Nordic shipyards are responding by deploying blockchain-anchored material passports that satisfy both EMA audit trails and DNV classification protocols.
Naval procurement offices are consolidating supplier qualification around single-source prepreg specifications. French defense procurement agencies now mandate Toray T800S-grade carbon for all carbon fiber hull contracts, displacing multi-source competitive bidding. This specification narrowing concentrates technical risk but accelerates hull-to-hull performance consistency for fleet operators.
Marine Composites Market Segmentation
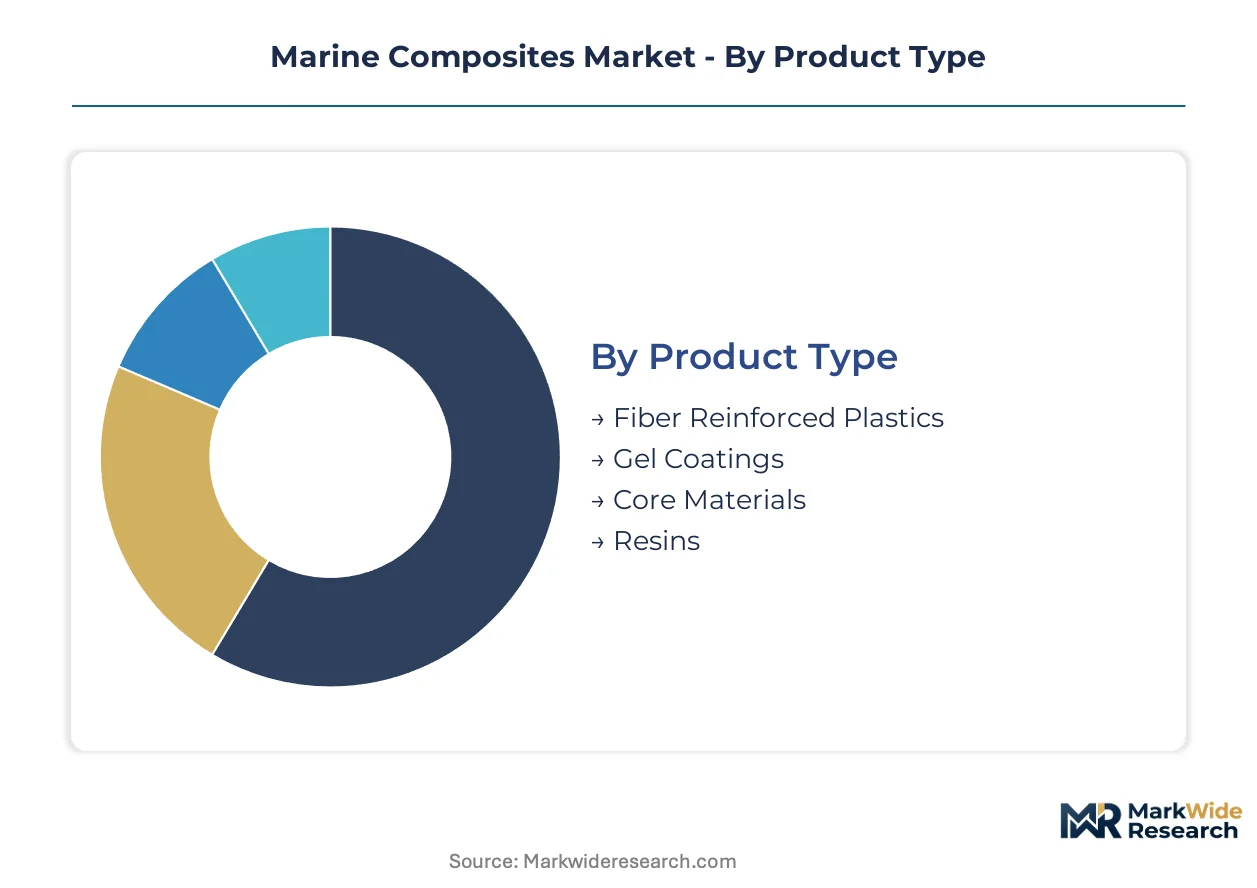
Segmentation in marine composites reveals divergent capital requirements across product categories and sharply different compliance burdens between defense and commercial end uses. Understanding these structural divisions clarifies where margin concentrates and where volume expansion faces technical barriers.
Product Type:
Capital intensity varies enormously across product categories, with autoclave-cured prepregs demanding the heaviest fixed-asset investment while commodity resins operate on comparatively lean manufacturing footprints.
- Fiber Reinforced Plastics:Glass and carbon fiber laminates dominate hull and deck construction through hand lay-up, infusion, or automated fiber placement. Demand clusters in Mediterranean superyacht yards and German coastal manufacturing corridors where EMA MDR traceability requirements now mandate batch-level documentation.
- Resins:Epoxy, vinyl ester, and polyester formulations serve as the matrix binding fibers into structural laminates. REACH restrictions on styrene-based systems force European formulators toward low-VOC alternatives without sacrificing infusion speed, compressing reformulation timelines.
- Core Materials:Balsa and syntactic foam cores reduce laminate weight while improving shear stiffness in racing and naval applications.
- Gel Coatings:Surface finishes provide osmotic protection and aesthetic finish for hull exteriors.
Fiber Reinforced Plastics absorbs the bulk of installed capacity; Resins is expanding most quickly as regulatory pressure accelerates chemistry innovation.
Application:
Application segmentation tracks divergent performance specifications, with racing and defense segments tolerating premium pricing for mass reduction while commercial shipping prioritizes repair accessibility and first cost.
- Sailing Yachts:Performance sailing demands extreme strength-to-weight ratios, driving carbon fiber prepregs into mast, boom, and hull structures. Italian and German builders specify pressure-vessel-grade cure cycles that exceed standard autoclave dimensions.
- Commercial Ships:Ferries and workboats face metallic repair infrastructure legacy in Baltic ports, creating switching friction for composite adoption despite fuel savings from mass reduction.
- Powerboats:Recreational motor yachts balance speed requirements with production cost constraints.
- Fishing Vessels:Small-scale commercial fishing fleets prioritize durability and repair simplicity over advanced composite specifications.
Sailing Yachts commands premium pricing tiers; Commercial Ships presents the steepest expansion trajectory if regulatory carbon accounting penetrates vessel lifecycle assessments.
End User:
End user structure reflects bifurcated procurement patterns between new-build specification and aftermarket repair, with defense OEMs consolidating suppliers while repair services fragment across thousands of small yards.
- OEMs:Original equipment manufacturers specify laminate systems at design stage, capturing value through long-term supply agreements. French defense procurement now mandates single-source prepreg qualifications, compressing competitive bidding.
- Shipbuilders:Construction yards integrate composite procurement into hull assembly workflows.
- Boat Manufacturers:Production boat builders optimize for throughput and material handling efficiency.
- Marine Repair Services:Aftermarket maintenance providers face technician certification gaps under tightening EMA documentation requirements.
OEMs concentrate procurement leverage; Marine Repair Services is gaining share fastest as fleet age extends and classification societies intensify inspection protocols.
Distribution Channel:
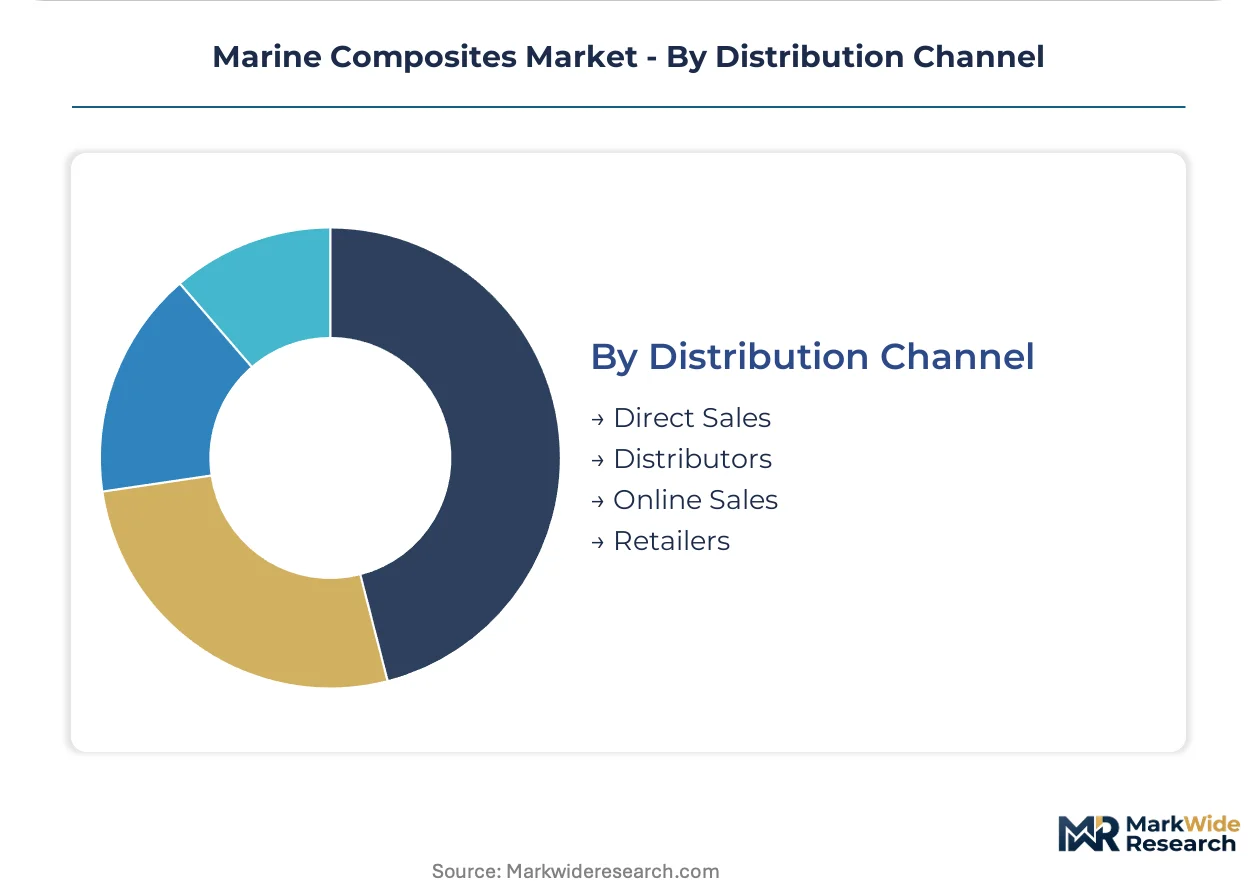
Channel structure varies by product technicality, with direct sales dominating engineered prepregs requiring formulation support while commodity resins flow through distributor networks.
- Direct Sales:Technical products including autoclave-grade prepregs and structural core kits move through manufacturer-direct relationships enabling application engineering support.
- Distributors:Regional stocking distributors serve mid-tier hull manufacturers with standardized resin and reinforcement portfolios.
- Online Sales:Small-volume specialty products and repair consumables migrate to digital procurement platforms.
- Retailers:Consumer-facing chandleries supply amateur repair and maintenance segments.
Direct Sales captures the highest-margin transactions; Distributors is climbing the fastest as mid-tier hull builders seek reduced inventory carrying costs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Acrylonitrile precursor production clusters in Japan and the United States shape raw-material availability for European and Asian hull builders. Carbon fiber tow conversion capacity concentrates near these feedstock sources, exposing Mediterranean shipyards to currency volatility and trans-Pacific shipping schedules. Defense procurement offices in France and Italy now mandate domestic laminate traceability under EMA MDR frameworks.
France
Naval defense procurement drives carbon fiber monocoque hull demand for next-generation interceptors. The country's national pharmaceutical regulator, ANSM, cross-pollinates traceability protocols into marine passenger vessel documentation through EMA MDR alignment. Mediterranean shipyards in La Ciotat and La Seyne-sur-Mer consolidate supplier qualification around single-source prepreg specifications for fleet consistency.
Italy
Superyacht builders deploy automated fiber placement systems to reduce laminate void content below 0.5 percent. REACH restrictions on styrene-based vinyl ester formulations force Ligurian formulators toward low-VOC alternatives. The industrial cluster around Viareggio and Carrara anchors high-performance sailing yacht production with pressure-vessel-grade autoclave capacity.
Germany
Yacht builders face binding embodied carbon thresholds under EU Green Deal mandates that accelerate fiberglass-to-carbon transitions. The KBA automotive regulator's materials testing protocols influence composite qualification standards for commercial vessels. Coastal manufacturing corridors in Lower Saxony and Mecklenburg-Vorpommern concentrate infusion-grade resin production for Baltic ferry programs.
Norway
Sailing yacht builders leverage filament winding expertise to enter marine hydrogen pressure vessel supply chains. The country's national petroleum regulator, the Norwegian Petroleum Directorate, extends offshore safety culture into composite tank certification protocols. Bergen and Stavanger manufacturing bases develop structural core kits for competitive racing segments requiring extreme shear stiffness.
Netherlands
Mid-tier hull manufacturers adopt prepreg out-of-autoclave curing to reduce capital barriers. ECHA classification of certain resin formulations as substances of very high concern forces Rotterdam-area formulators into rapid reformulation cycles. The Randstad industrial zone integrates blockchain-anchored material passports that satisfy DNV classification protocols for laminate batch traceability.
Marine Composites Market Key Industry Players
Global majors compete with regional champions across carbon fiber precursor supply and prepreg formulation capabilities. The vendor base separates into three tiers: integrated fiber-to-prepreg conglomerates, specialized core material fabricators, and regional resin compounders serving mid-volume hull builders. Strategic moves concentrate on backward integration into precursor acrylonitrile and geographic expansion through distributor network densification in Mediterranean manufacturing clusters.
Within the integrated fiber-to-prepreg tier, Toray Industries, Inc. and Teijin Limited exemplify conglomerate-scale carbon fiber verticalization. Hexcel Corporation anchors North American supply relationships through advanced resin formulation positioning. Gurit Holding AG occupies a specialist niche in structural core kits that reduce laminate labor hours for competitive racing applications.
| Leading Market Players |
|---|
| Toray Industries, Inc. |
| Hexcel Corporation |
| Gurit Holding AG |
| Owens Corning |
| SGL Carbon SE |
| Teijin Limited |
| Mitsubishi Chemical Corporation |
| DuPont |
| Huntsman Corporation |
| Others |
Cost & Logistics Intelligence
Acrylonitrile spot price volatility cascades through marine composite supply chains, compressing margins for European hull builders while concentrating pricing power among Japanese and American fiber conglomerates with captive precursor production. This raw-material cost pressure stratifies end-product pricing across pressure-vessel-grade autoclave systems, infusion-grade resin formulations, and commodity fiberglass laminates.
Pricing Analysis
Warranty-backed laminate certification commands substantial premiums over bare-material supply, with DNV-classified batch documentation bundled into prepreg contracts for passenger vessels while racing yacht builders absorb unbundled quality assurance costs. Three-tier pricing structure separates pressure-vessel-grade autoclave prepregs from infusion-grade resin systems and commodity hand-layup materials, with carbon fiber specifications from Toray Industries anchoring the premium tier. Cost compression in mid-tier resin formulations is intensifying because REACH-driven reformulation cycles force European compounders to absorb R&D overhead without immediate volume recovery. Commercial ferry operators exhibit the highest price sensitivity due to metallic repair infrastructure legacy in Baltic ports, while naval defense procurement offices prioritize fleet consistency over unit cost.
Supply Chain Analysis
Trans-Pacific container freight rates and air-cargo capacity constraints amplify landed cost differentials for European hull builders sourcing carbon fiber tow from Japan and the United States. Precursor acrylonitrile production clusters in Japan, the United States, and China, with tow conversion capacity tethered to these feedstock locations. Supply chain risk centers on single-source vulnerability as French defense procurement mandates Toray T800S-grade specifications exclusively. Distribution runs through direct sales relationships for autoclave-grade prepregs requiring application engineering support, while standardized resins flow through regional stocking distributors serving mid-tier Mediterranean and Baltic shipyards.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Marine composites markets are navigating a technology-transition phase as out-of-autoclave curing systems displace legacy pressure-vessel autoclave infrastructure, enabling mid-tier hull manufacturers to access prepreg performance without capital-intensive oven investments.
For Market Incumbents: Extend traceability certification advantages by embedding blockchain-anchored material passports deeper into supply chain relationships, defending against emerging modular core kit suppliers threatening laminate labor-hour reductions. Invest in backward integration into acrylonitrile precursor supply or secure long-term offtake agreements with Japanese fiber producers to mitigate currency volatility exposure. For New Entrants and Emerging Players: Out-of-autoclave resin chemistry expertise offers entry into mid-tier sailing yacht and commercial workboat segments underserved by autoclave capacity bottlenecks. Target Dutch and German coastal manufacturing corridors where EU Green Deal embodied carbon thresholds accelerate fiberglass-to-carbon transitions. Pursue filament winding technology licensing from Norwegian hydrogen pressure vessel specialists to diversify beyond hull structures into emerging marine energy storage applications. For Investors and Strategic Acquirers: Distressed-cycle entries favor specialized structural core fabricators with balsa and syntactic foam kit capabilities in Mediterranean manufacturing clusters, where racing segment demand justifies premium positioning. Long-term viability hinges on positioning for IMO lifecycle assessment protocol expansion into composite vessel classifications. Monitor EMA MDR documentation requirement enforcement intensity as the inflection indicator for traceability technology valuation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Supply | Captive acrylonitrile production insulates European prepreg formulators from trans-Pacific shipping volatility. |
| Out-of-Autoclave Resin Platform Launch | Ambient-pressure curing chemistry opens pressure-vessel-grade performance to mid-tier hull manufacturers without capital barriers. |
| Blockchain Material Passport Deployment | Immutable batch documentation satisfies both EMA audit trails and DNV classification protocols for laminate traceability. |
| Structural Core Kit Modularization | Pre-cut balsa and syntactic foam panels reduce laminate labor hours for competitive racing segments requiring extreme shear stiffness. |
| Filament Winding Capacity Expansion | Norwegian sailing yacht builders leverage existing expertise to capture emerging marine hydrogen pressure vessel supply chains. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with composite plant managers, naval procurement officers, hull design engineers, and aftermarket repair service heads. EMA MDR submission databases, REACH registration dossiers, and DNV classification society technical reports provided compliance-specific demand indicators. Bottom-up hull production estimates from Mediterranean and Baltic shipyard associations were triangulated against top-down carbon fiber consumption figures from Japanese and American precursor producers.
Granularity-level modeling distinguished autoclave-cured prepreg, infusion-grade resin, and commodity laminate systems by vessel class, end-use application, and regulatory certification tier across the projection horizon. CAGRs were derived from segmented volume trajectories weighted by embodied carbon accounting penetration assumptions and naval defense procurement cycle phasing. Industry-specific inputs included EU Green Deal threshold implementation timelines and IMO lifecycle assessment protocol development stages.
Several conditions sit outside the modeled scope, including potential REACH expansion to additional vinyl ester formulations and abrupt carbon fiber precursor supply disruptions from geopolitical events. Forecasts reflect underlying assumptions about regulatory enforcement consistency and technology adoption curves. Stakeholders should weight assumptions against their own operating context and monitor EMA documentation requirement rollout intensity for passenger vessel segments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Composite Materials
Wood Plastic Composite (WPC) Market
Composite Materials
PCR Laminates Market
Composite Materials
Copper Clad Laminates Market
Composite Materials
Low Temperature Sealing Glass Composite Powder Market
Composite Materials
Composite Quartz Stone Market
Composite Materials
Fiber Reinforced Polymer (FRP) Panels and Sheets Market
Composite Materials
Balsa Core Materials Market
Composite Materials
Composites Distributor Market
Composite Materials
Composite Process Material Kits Market
Composite Materials
Asia Pacific Bio Composites Market
Composite Materials
Europe Marine Composites Market
Composite Materials
Plastic Composites Market
Composite Materials
Ultra-Lightweight Cement Composites Market
Composite Materials
Decorative High-Pressure Laminates Market
Composite Materials
Phenolic Panel Market
Composite Materials
Global Carbon Fiber Reinforced Plastic Market