
 FRP Tanks Market | 2026-2036
FRP Tanks Market Size, Share, and Industry Trends Forecast 2026-2036
FRP Tanks Market Foresight
Direct-to-industrial distribution is reshaping how FRP tank suppliers reach municipal water boards and petroleum refiners across North America and Asia-Pacific. ZCL Composites leverages its vertical integration in filament winding to dominate large-diameter vertical tank contracts. Hexagon Composites ASA anchors European demand through specialized pressure vessel designs for oil and gas processing. LF Manufacturing competes aggressively in agricultural irrigation segments with cost-optimized horizontal tank configurations.
Fiber-reinforced plastic tanks integrate glass fiber reinforcements within thermoset polymer matrices such as vinyl ester or epoxy resins, delivering corrosion resistance against aggressive chemicals across pH extremes from 1 to 14 while maintaining structural integrity under cyclic loading. Their primary purpose centers on bulk liquid containment where metallic alternatives suffer galvanic or chemical degradation. Vertical tanks command the largest installed base due to footprint efficiency in chemical storage facilities, while vinyl ester formulations represent the fastest-expanding material category driven by sulfuric acid handling requirements in petroleum refining. Modular tank configurations attract emerging demand from decentralized water treatment installations where site access constraints prohibit monolithic construction.
EPA underground storage tank regulations and FDA food-contact material standards shape product certification requirements for domestic suppliers, while India's BIS certification mandates govern imported composite vessels for potable water applications. REACH compliance in Europe restricts certain styrene emissions during open-mold fabrication, pushing manufacturers toward closed-mold resin transfer molding processes. Stakeholders must monitor evolving PFAS restrictions and their downstream impact on fluoropolymer liner compatibility within aggressive chemical storage applications.
Market Dynamics
Filament winding automation is compressing production cycles for large-diameter vertical tanks while REACH compliance costs in Europe push smaller fabricators toward closed-mold resin transfer molding or exit.
Growth Catalysts
- CDSCO storage mandates:India's national pharmaceutical regulator tightened bulk chemical containment standards, forcing pharmaceutical manufacturers to replace metallic tanks with vinyl ester FRP systems for sulfuric acid and solvent storage.
- Petroleum refining corrosion upgrades:Refiners across Gujarat and Maharashtra industrial corridors are retrofitting sulfuric acid alkylation units with vinyl ester formulations as metallic vessels fail prematurely in concentrated acid service.
- Dual carbon goals:China's MIIT is accelerating composite adoption in chemical processing infrastructure as part of industrial decarbonization targets, favoring lightweight FRP over carbon-intensive steel fabrication.
Market Restraints
- Styrene price volatility:Unsaturated polyester resin feedstock costs swing with benzene and ethylene contract pricing, squeezing margin for open-mold fabricators locked into fixed-price municipal contracts.
- Carbon fiber supply concentration:Aerospace-grade carbon fiber tow production concentrates in Japan and the United States, limiting access for pressure vessel manufacturers seeking hybrid reinforcement schemes.
- Fluoropolymer liner compatibility:Emerging PFAS restrictions under ECHA evaluation threaten ETFE and PVDF liner availability for ultra-aggressive chemical service above 90°C, forcing material requalification.
Strategic Opportunities
- Decentralized water treatment:Modular FRP tank configurations address site access constraints in Indonesia's archipelago geography, where monolithic construction proves logistically impossible for remote industrial parks.
- CE marking acceleration:The EU's Construction Products Regulation is creating certification demand for standardized tank designs, favoring manufacturers with pre-approved technical documentation over project-specific engineering.
- Smart monitoring integration:Convergence of embedded fiber optic strain sensing with cloud-based predictive maintenance platforms enables tank-as-a-service business models for chemical distributors.
Industry Challenges
- Filament winding technician scarcity:Automated multi-axis winding programming requires specialized CAD/CAM skills that vocational training programs in India and Southeast Asia have not scaled to match installation demand.
- ASME RTP-1 certification timelines:Design review and witness testing protocols for reinforced thermoset plastic corrosion-resistant vessels extend project delivery by 8-14 weeks, compressing competitive response windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | FRP Tanks Market |
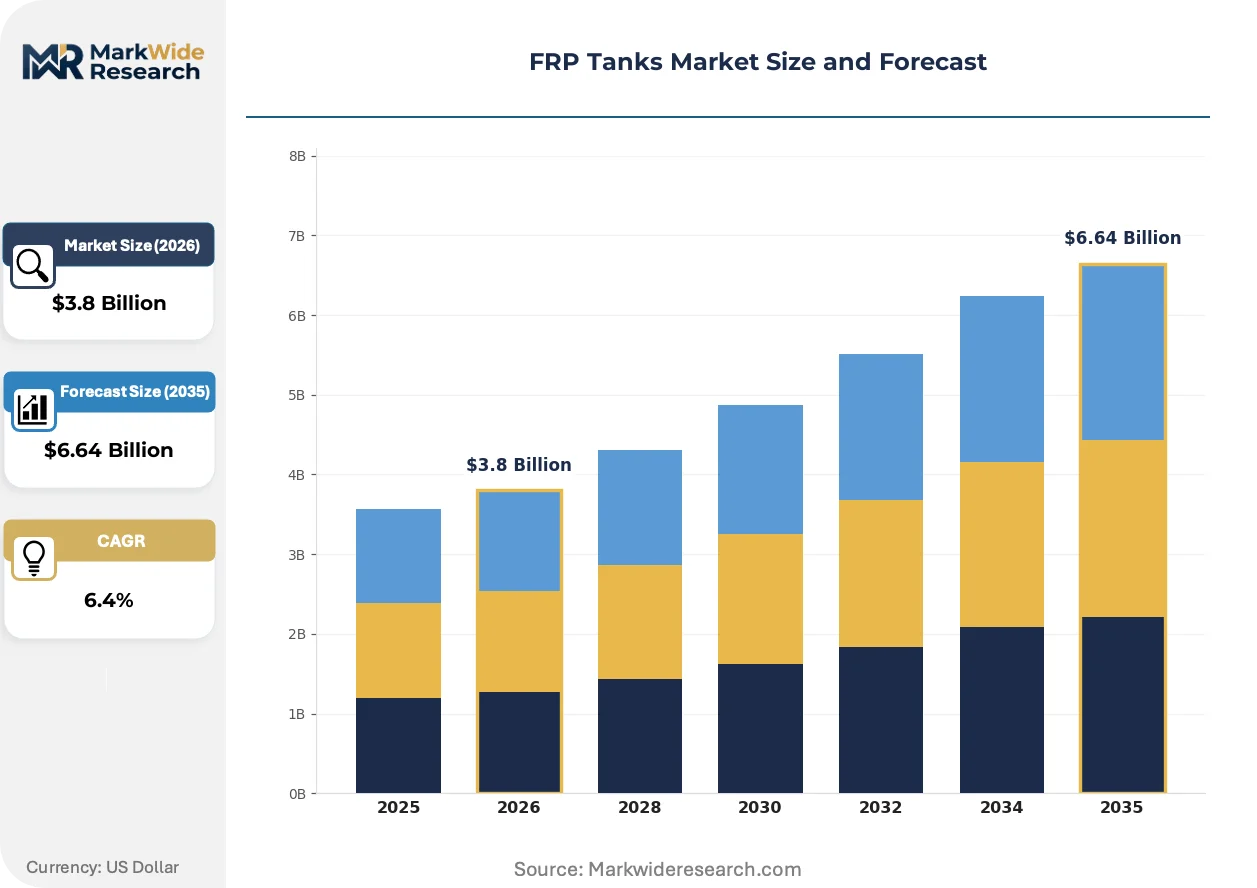
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vertical Tanks, Horizontal Tanks, Spherical Tanks, Modular Tanks, Cylindrical Tanks Material Type: Fiberglass Reinforced Polyester, Vinyl Ester, Epoxy, Phenolic, Polyester Vinyl Ester Application: Chemical Storage, Water & Wastewater Treatment, Oil & Gas Processing, Agriculture Irrigation, Fire Protection End User Industry: Chemical Manufacturers, Municipal Water Boards, Petroleum Refiners, Farming Operations, Fire Safety Services |
| Companies Covered | ZCL Composites, Hexagon Composites ASA, Luxfer Group, Enduro Composites, LF Manufacturing, Faber Industries, EPP Composites, Composite Technology Development Inc., Denali Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
FRP Tanks Market Shifts & Advancements
Digital thread technologies are penetrating tank fabrication workflows, linking design simulation to automated quality verification and reshaping how specifications propagate from engineering to field installation.
Automated ultrasonic testing is digitizing non-destructive evaluation of filament-wound laminate integrity. Pressure vessel fabricators in Germany and the Netherlands are deploying phased-array systems inline during cure monitoring. This capability is compressing final inspection cycles from days to hours while generating digital birth certificates traceable through asset lifecycle management platforms.
REACH Annex XVII restrictions on styrene emissions are accelerating closed-mold process adoption across European fabrication facilities. ECHA's 2023-2024 dossier updates tightened occupational exposure thresholds for manual layup operations. Northern Italian and Polish tank manufacturers are responding with vacuum-assisted resin transfer molding investments that eliminate open-air styrene release.
Specification bundling is consolidating procurement authority among engineering-procurement-construction firms managing chemical plant builds. EPCs in the Middle East and Southeast Asia now mandate pre-qualified FRP tank suppliers with integrated design-build capabilities, displacing fragmented local fabricator networks. Saudi Aramco's vendor registration requirements exemplify this concentration, favoring manufacturers with captive engineering resources over pure fabrication shops.
FRP Tanks Market Segmentation
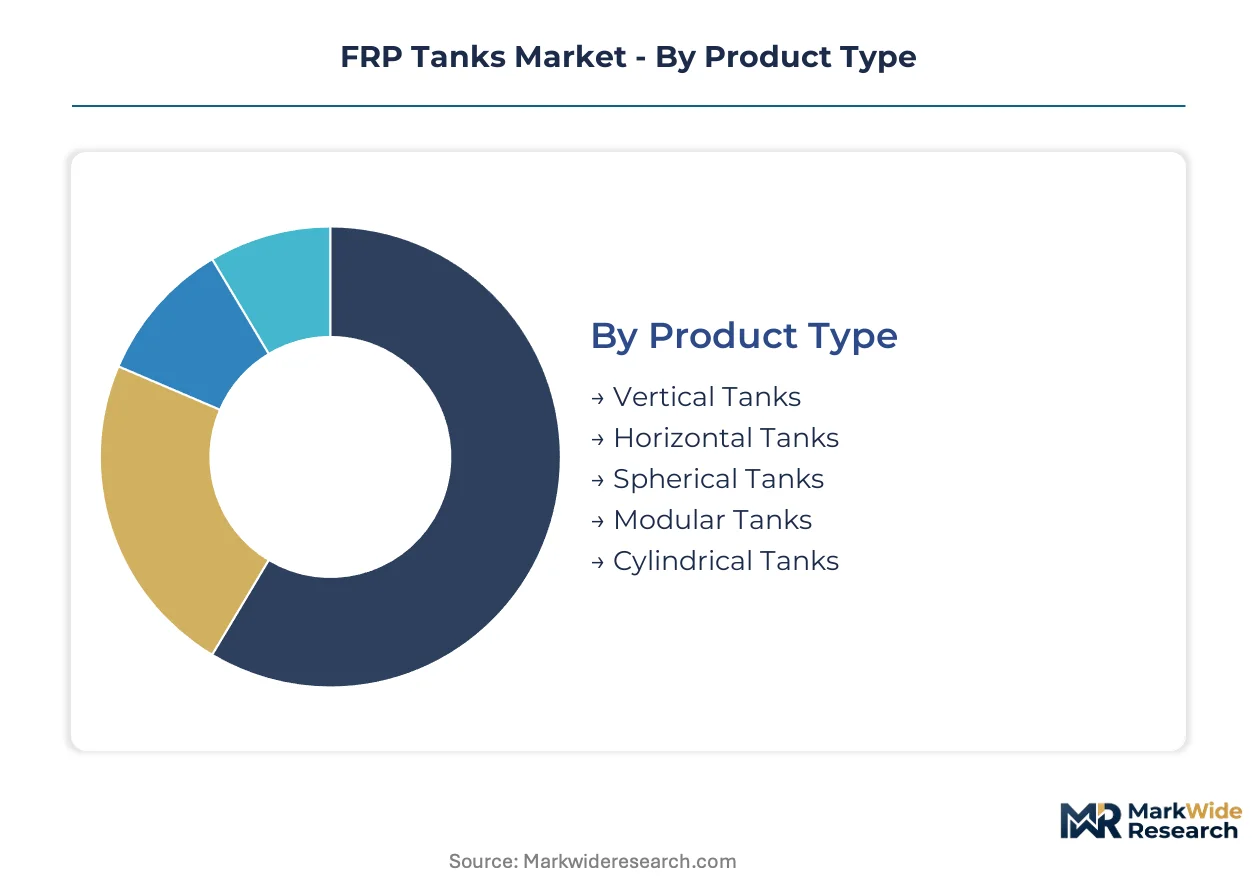
FRP tank procurement patterns diverge sharply across installation geometry, resin chemistry, and end-use severity. Specification requirements for sulfuric acid containment in petroleum refining differ fundamentally from potable water storage mandates issued by municipal regulators.
Product Type:
Footprint efficiency and site access constraints determine tank geometry selection for chemical facilities and remote installations.
- Vertical Tanks:Upright cylindrical configurations maximize storage density per square meter of plant footprint. Chemical manufacturers in Gujarat and Maharashtra specify these for concentrated acid service where floor space commands premium valuation.
- Horizontal Tanks:Low-profile designs suit below-grade installation and transportable applications. Petroleum refiners across India deploy these for underground fuel storage complying with evolving EPA and BIS leak detection standards.
- Spherical Tanks:Pressure-rated vessels for compressed gas containment in specialized chemical processes.
- Modular Tanks:Panelized construction enables field assembly where crane access is restricted. Indonesia's archipelago industrial parks drive specification for remote site installations.
- Cylindrical Tanks:Standardized geometries for agricultural irrigation and fire protection water reserves.
Vertical tanks command the established base. The steepest expansion runs through modular configurations.
Material Type:
Resin selection balances chemical resistance against fabrication cost and regulatory compliance timelines.
- Vinyl Ester:Superior hydrolytic stability and blister resistance in concentrated sulfuric acid above 90 percent concentration. CDSCO storage mandates are accelerating specification for pharmaceutical bulk chemical containment across Indian manufacturing corridors.
- Fiberglass Reinforced Polyester:Cost-optimized formulations for neutral pH water storage and agricultural applications. REACH Annex XVII styrene restrictions are compressing open-mold fabrication economics in European supply chains.
- Epoxy:High-performance matrices for elevated temperature service and food-contact applications under FDA jurisdiction.
- Phenolic:Fire-resistant formulations meeting offshore platform and tunnel infrastructure specifications.
- Polyester Vinyl Ester:Hybrid systems bridging cost and performance for mid-tier chemical processing equipment.
Fiberglass reinforced polyester dominates installed volume. Vinyl ester formulations are climbing the fastest as corrosion upgrades accelerate.
Application:
Fluid aggressiveness and containment duration define specification stringency across use cases.
- Chemical Storage:Aggressive acid and solvent containment requiring vinyl ester or epoxy construction with fluoropolymer liners. Petroleum refiners in Gujarat retrofit alkylation units as metallic vessels fail in concentrated sulfuric acid service.
- Water & Wastewater Treatment:Potable water certification under BIS and NSF standards, plus corrosion-resistant biological treatment tanks. China's MIIT industrial decarbonization targets favor lightweight composite over steel fabrication.
- Oil & Gas Processing:Produced water and condensate handling in upstream and midstream facilities.
- Agriculture Irrigation:Cost-sensitive bulk water storage with UV-stabilized exteriors for extended field exposure.
- Fire Protection:Static water reserves meeting NFPA and local fire code capacity requirements.
Chemical storage anchors revenue concentration. Water and wastewater treatment is expanding most quickly on infrastructure investment cycles.
End User Industry:
Procurement authority and technical specification capability vary dramatically across buyer types.
- Chemical Manufacturers:Sophisticated buyers with in-house corrosion engineering specifying ASME RTP-1 certified vessels. CDSCO tightened bulk containment standards force replacement of legacy metallic tanks with vinyl ester FRP systems.
- Petroleum Refiners:Large-scale capital projects with integrated EPC procurement favoring pre-qualified suppliers with captive engineering resources.
- Municipal Water Boards:Public tender processes with extended qualification timelines and fixed-price contract structures.
- Farming Operations:Price-sensitive decentralized demand served through distributor networks rather than direct manufacturer relationships.
- Fire Safety Services:Code-driven specification with emphasis on third-party certification and rapid deployment capability.
Chemical manufacturers concentrate value capture. Petroleum refiners are gaining share fastest on corrosion upgrade cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's CDSCO storage mandates are accelerating vinyl ester FRP tank adoption across pharmaceutical manufacturing corridors. China's MIIT dual carbon goals favor lightweight composite infrastructure over steel fabrication. EPA underground storage regulations and REACH Annex XVII styrene restrictions reshape certification requirements in North America and Europe.
United States
Petroleum refiners along the Gulf Coast are retrofitting sulfuric acid alkylation units with corrosion-resistant FRP vessels as metallic tanks fail prematurely. EPA underground storage tank regulations mandate leak detection systems for fuel storage applications. Houston and Corpus Christi industrial clusters concentrate demand for large-diameter vertical tank configurations.
India
CDSCO tightened bulk chemical containment standards force pharmaceutical manufacturers to replace legacy metallic tanks with vinyl ester FRP systems. BIS certification mandates govern imported composite vessels for potable water applications. Gujarat and Maharashtra industrial corridors drive specification for concentrated acid service tanks.
China
MIIT industrial decarbonization targets accelerate composite adoption in chemical processing infrastructure as part of dual carbon goals. GB standards for pressure vessels shape domestic certification timelines. Yangtze River Delta chemical parks favor lightweight FRP over carbon-intensive steel fabrication for new capacity.
Germany
REACH Annex XVII restrictions on styrene emissions push fabricators toward closed-mold resin transfer molding processes. ECHA's tightened occupational exposure thresholds eliminate open-air manual layup operations. Northern Italian and Polish manufacturers are responding with vacuum-assisted molding investments.
Indonesia
Modular FRP tank configurations address site access constraints across the archipelago geography where monolithic construction proves logistically impossible. Decentralized water treatment installations in remote industrial parks drive panelized construction demand. Java and Sumatra manufacturing zones specify field-assembly tank systems.
FRP Tanks Market Competitive Landscape
On the supply side, the industry is consolidating around engineering-procurement-construction procurement authority. Tiered competitive dynamics separate pre-qualified suppliers with captive engineering resources from fragmented local fabricator networks. Three archetypes dominate: vertically integrated filament winding specialists, regional cost-optimized fabricators, and technology-licensed modular system providers. Strategic moves center on specification bundling with EPC firms and closed-mold process investments for REACH compliance.
Among North American specialists, ZCL Composites and LF Manufacturing occupy distinct positioning vectors. ZCL Composites exemplifies the vertically integrated archetype through in-house filament winding capabilities for large-diameter vertical tank contracts. LF Manufacturing represents the cost-optimized horizontal tank segment serving agricultural irrigation applications. Hexagon Composites ASA anchors European demand through specialized pressure vessel designs, sitting within the technology-differentiated tier serving oil and gas processing requirements.
| Leading Market Players |
|---|
| ZCL Composites |
| Hexagon Composites ASA |
| Luxfer Group |
| Enduro Composites |
| LF Manufacturing |
| Faber Industries |
| EPP Composites |
| Composite Technology Development Inc. |
| Denali Inc. |
| Others |
Supply & Pricing Matrix
Overcapacity in European open-mold fabrication is compressing margins for unsaturated polyester resin processors while pushing contract structures toward longer-term offtake agreements that lock in volume commitments from municipal water boards and petroleum refiners across North America and Asia-Pacific.
Pricing Analysis
Volume-discount tiering structures separate ASME RTP-1 certified vessels from uncertified project-specific fabrications, with certification grade and customization level driving spreads between premium and economy tiers. Price differentiation reflects filament winding automation investments that compress production cycles for large-diameter vertical tanks. Cost compression in standard polyester formulations is intensifying as benzene and ethylene contract volatility squeezes open-mold fabricators locked into fixed-price municipal contracts. Farming operations exhibit highest price sensitivity, while chemical manufacturers with in-house corrosion engineering accept premium positioning for vinyl ester systems.
Supply Chain Analysis
Contract manufacturing concentration rests with captive filament winding operations at ZCL Composites and regional fabricators across Gujarat and Maharashtra industrial corridors. Geographic supply concentrates in India, China, and Germany, with raw material dependencies drawing from glass fiber roving, vinyl ester resin formulations, and fluoropolymer liner sheeting. Single-source vulnerability runs through aerospace-grade carbon fiber tow production concentrated in Japan and the United States. Distribution runs through engineering-procurement-construction firms consolidating procurement authority for chemical plant builds in the Middle East and Southeast Asia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Filament winding technician scarcity constrains capacity expansion across Indian and Southeast Asian fabrication networks, with automated multi-axis programming skills lagging installation demand by vocational training throughput gaps.
For Market Incumbents: Build certification moats through ASME RTP-1 pre-approval investments that compress competitive response windows against emerging closed-mold specialists. Anchor backward integration into vinyl ester resin formulation to offset styrene price volatility squeezing open-mold margins. Defend against EPC procurement consolidation by embedding engineering resources within specification bundling workflows for Saudi Aramco-tier vendor registration requirements. For New Entrants and Emerging Players: Indonesia's archipelago geography offers white-space access where modular panelized construction addresses site constraints prohibiting monolithic tank delivery. Target decentralized water treatment installations across Java and Sumatra manufacturing zones with field-assembly capabilities. Penetrate through technology licensing arrangements with European vacuum-assisted resin transfer molding equipment providers seeking REACH-compliant process validation partners. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across closed-mold resin transfer molding installations as ECHA occupational exposure thresholds eliminate manual layup operations. Long-term viability favors manufacturers with integrated design-build capabilities serving pre-qualified EPC procurement channels. Monitor CE marking acceleration under the EU Construction Products Regulation as inflection signal favoring standardized tank documentation over project-specific engineering.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Vinyl Ester Resin | Captive supply of corrosion-resistant formulations hedges benzene-ethylene contract volatility squeezing open-mold fabricator margins. |
| Closed-Mold Process Conversion | Vacuum-assisted resin transfer molding investments eliminate open-air styrene release under tightened ECHA occupational exposure thresholds. |
| ASME RTP-1 Pre-Certification | Pre-approved technical documentation compresses project delivery timelines against competitors locked in witness testing protocols. |
| Smart Monitoring Platform Integration | Embedded fiber optic strain sensing enables tank-as-a-service business models for chemical distributors seeking predictive maintenance. |
| Modular System Licensing | Panelized construction technology addresses site access constraints across Indonesia's archipelago industrial parks. |
Research Methodology
Operator-level perspectives from filament winding technicians, EPC procurement managers, plant engineers at petroleum refiners, and corrosion specialists at chemical manufacturers anchored the qualitative base. Primary interviews combined with secondary validation drawing from customs and trade data, SEC 10-K filings, BIS certification registries, and ECHA dossier updates. Bottom-up tank installation counts triangulated against top-down resin consumption figures across vinyl ester and polyester formulation categories.
Scenario-bracketing framed sensitivity analysis across conservative, baseline, and expansion cases throughout the forecast period. Segmentation dimensions modeled included tank geometry, resin chemistry grade, end-use severity tier, and regional regulatory cluster. CAGRs derived from elasticity-adjusted demand curves incorporating CDSCO mandate implementation timelines and MIIT dual carbon goal acceleration signals. Industry-specific inputs captured REACH Annex XVII compliance cost pass-through and filament winding automation penetration curves.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese state-backed composite infrastructure specialists or sudden ECHA PFAS restriction acceleration would shift outcomes. Forecasts assume continued EPC procurement consolidation and gradual closed-mold process adoption without disruptive technology substitution. Quarterly review of ASME RTP-1 certification backlog durations and vinyl ester resin contract pricing volatility is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Composite Materials
Biocomposites Market
Composite Materials
Wood Plastic Composite (WPC) Market
Composite Materials
Global Wind Turbine Composites Material Market
Composite Materials
Composite Preforms Market
Composite Materials
Fiber-Reinforced Plastic (FRP) Grating Market
Composite Materials
Global Carbon Fiber Reinforced Plastic Market
Composite Materials
Thermoset Composites Market
Composite Materials
PCR Laminates Market
Composite Materials
Composite Quartz Stone Market
Composite Materials
Structural Composites Market
Composite Materials
Europe Composites Market
Composite Materials
Global FRP Vessels Market
Composite Materials
Green Composites Market
Composite Materials
Europe Composite Process Material Kits Market
Composite Materials
Composite Cans Market
Composite Materials
Asia-Pacific Molded FRP Grating Market