

EUV Mask Inspection and Pellicle Monitoring Systems Market Size, Share, and Industry Trends Forecast 2026-2036
EUV Mask Inspection and Pellicle Monitoring Systems Market Insights
High-NA EUV lithography is rewriting mask qualification protocols by tightening defect tolerance thresholds below single-digit nanometers. KLA Corporation leverages its broad inspection portfolio to anchor metrology workflows across leading foundries. Lasertec Corporation specializes in actinic mask blank inspection, occupying a narrow but critical tier in the supply chain. ASML Holding controls the lithography ecosystem, extending its influence into adjacent process control layers.
EUV mask inspection and pellicle monitoring systems comprise equipment that detects particulate contamination, pattern defects, and membrane degradation on photomasks used in extreme ultraviolet projection lithography, operating at thirteen point five nanometer wavelength where traditional optical methods fail. These systems preserve lithographic yield by ensuring mask integrity before each wafer exposure cycle. Automated inspection systems and electron beam inspection units command the largest revenue pools due to their irreplaceable role in qualifying masks for sub-seven nanometer nodes. Pellicle defect detection systems represent the fastest-expanding category as membrane fragility under high-NA power densities demands real-time integrity verification.
The EPA regulates fluorinated greenhouse gas emissions from semiconductor manufacturing processes, while REACH restricts perfluorinated substance use in pellicle materials, compelling equipment vendors to certify chemistries for compliance. Taiwan's Industrial Development Bureau and South Korea's Ministry of Trade enforce local content and safety standards for imported inspection tools. Stakeholders must monitor regulatory divergence between jurisdictions as qualification requirements for mask cleanliness and pellicle durability harden unevenly across production geographies.
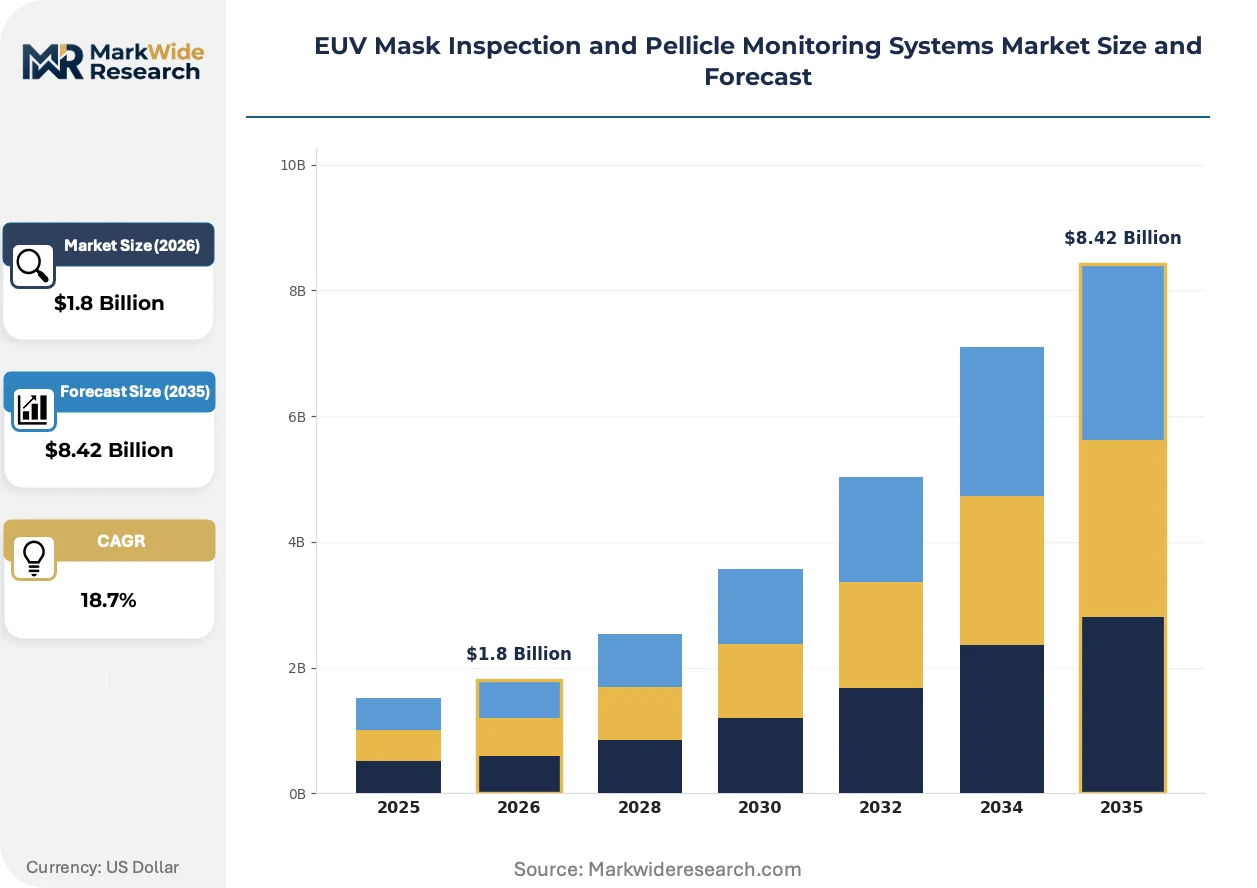
Market Dynamics
High-NA EUV lithography is compressing defect tolerance thresholds below single-digit nanometers, forcing foundries to accelerate mask qualification cycles and deploy real-time pellicle integrity verification at every exposure station.
Growth Catalysts
- Sub-three nanometer node expansion:Leading foundries in Taiwan and South Korea are scaling EUV lithography capacity, multiplying the number of masks requiring qualification per fab.
- REACH chemical restrictions:The European regulation is tightening perfluorinated substance rules for pellicle membrane chemistries, compelling equipment vendors to certify compliant inspection protocols.
- Actinic inspection wavelength adoption:Thirteen point five nanometer wavelength inspection systems are displacing optical alternatives as the sole method capable of detecting printable defects on EUV masks.
Market Restraints
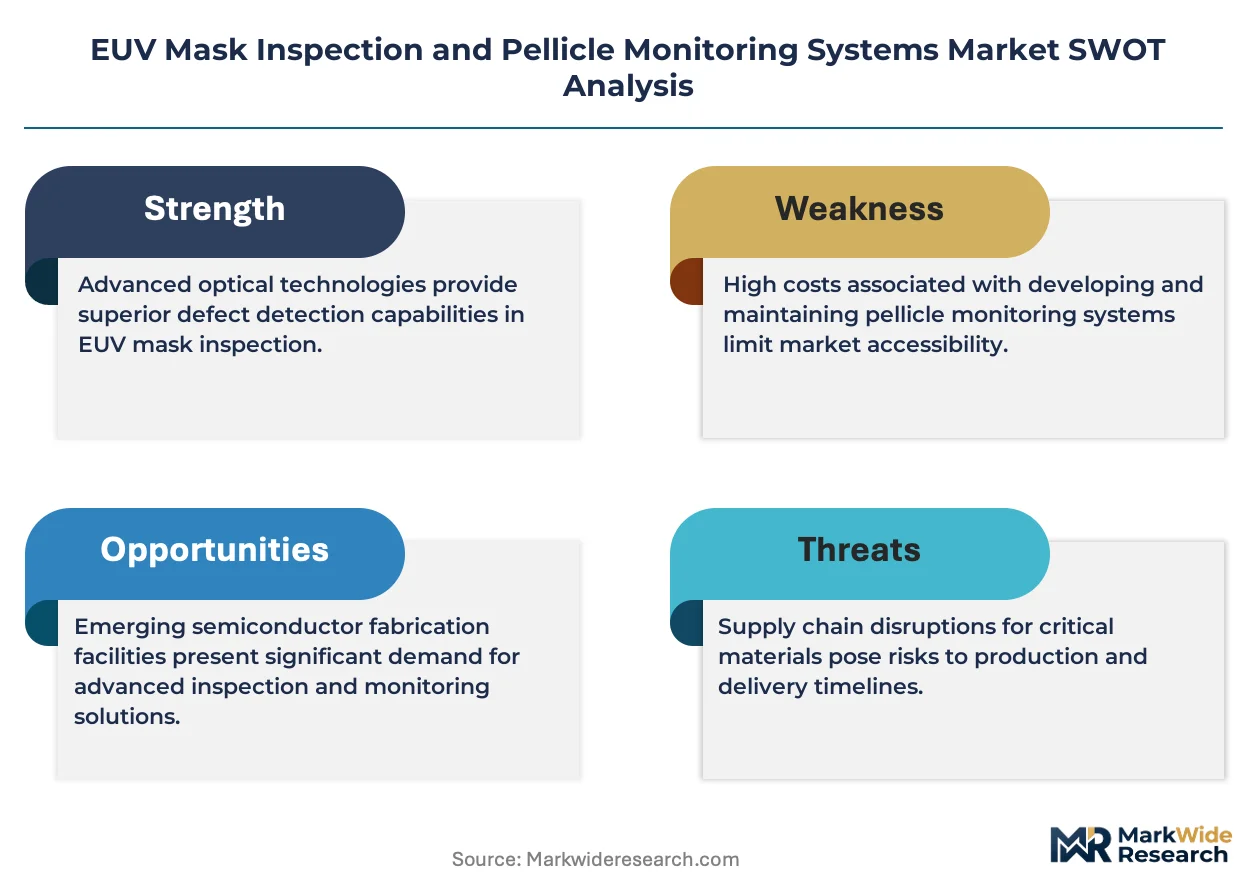
- Fluorinated chemistry supply concentration:Pellicle membrane production relies on a narrow base of specialty chemical suppliers concentrated in Japan and Germany, exposing the supply chain to single-source risk.
- EPA F-Gas emission controls:The US regulation is tightening fluorinated greenhouse gas reporting requirements for semiconductor manufacturing, adding compliance overhead to inspection tool operations.
- Electron beam inspection throughput limits:Sequential scanning architectures face fundamental speed constraints when qualifying masks for high-volume manufacturing, creating bottlenecks at advanced nodes.
Strategic Opportunities
- India semiconductor manufacturing incentives:The country's PLI scheme is attracting foundry investments that will require EUV mask inspection infrastructure as domestic logic production scales.
- AI-driven defect classification:Machine learning algorithms trained on historical mask databases are converging with inspection hardware to reduce false-positive rates and accelerate qualification decisions.
- Pellicle remanufacturing services:Emerging aftermarket channels are capturing value from membrane refurbishment, extending pellicle lifetime and creating recurring revenue streams for inspection system vendors.
Industry Challenges
- Actinic inspection physicist shortage:The specialized knowledge required to operate thirteen point five nanometer wavelength systems is concentrated among a small cohort of researchers, constraining workforce scaling.
- Multi-tool correlation complexity:Foundries must reconcile defect maps across electron beam, optical, and actinic inspection platforms, requiring expensive metrology harmonization programs.
- High-NA pellicle thermal stress modeling:Predicting membrane degradation under elevated power densities demands computational capabilities that exceed current simulation tool capacities.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
EUV Mask Inspection and Pellicle Monitoring Systems Market Trends and Innovations
Inspection architecture is pivoting from offline sampling to inline monitoring, compressing the feedback loop between defect detection and lithographic correction while embedding machine learning at the point of measurement.
Actinic mask blank inspection is collapsing the distinction between mask qualification and lithography simulation. These systems capture three-dimensional multilayer defects invisible to optical platforms. Leading foundries in Taiwan are mandating actinic qualification for all masks entering sub-five nanometer production. The technology is collapsing the need for separate print-test validation cycles, compressing time-to-yield for new mask designs.
REACH Annex XVII restrictions on perfluorinated substances are forcing pellicle material reformulation across European supply chains. The regulation is compelling membrane manufacturers to submit alternative chemistries for durability testing under EUV exposure. Equipment vendors serving Hsinchu and Pyeongtaek fabs are accelerating certification of fluorine-free inspection protocols to maintain market access.
After-sales service unbundling is fragmenting the traditional bundled maintenance model. Foundry procurement teams are negotiating inspection hardware and software support as separate line items, pressuring vendor margin structures. This behavioral shift is most pronounced in South Korea, where Samsung and SK Hynix procurement organizations have established dedicated metrology asset management functions.
EUV Mask Inspection and Pellicle Monitoring Systems Market Segmentation
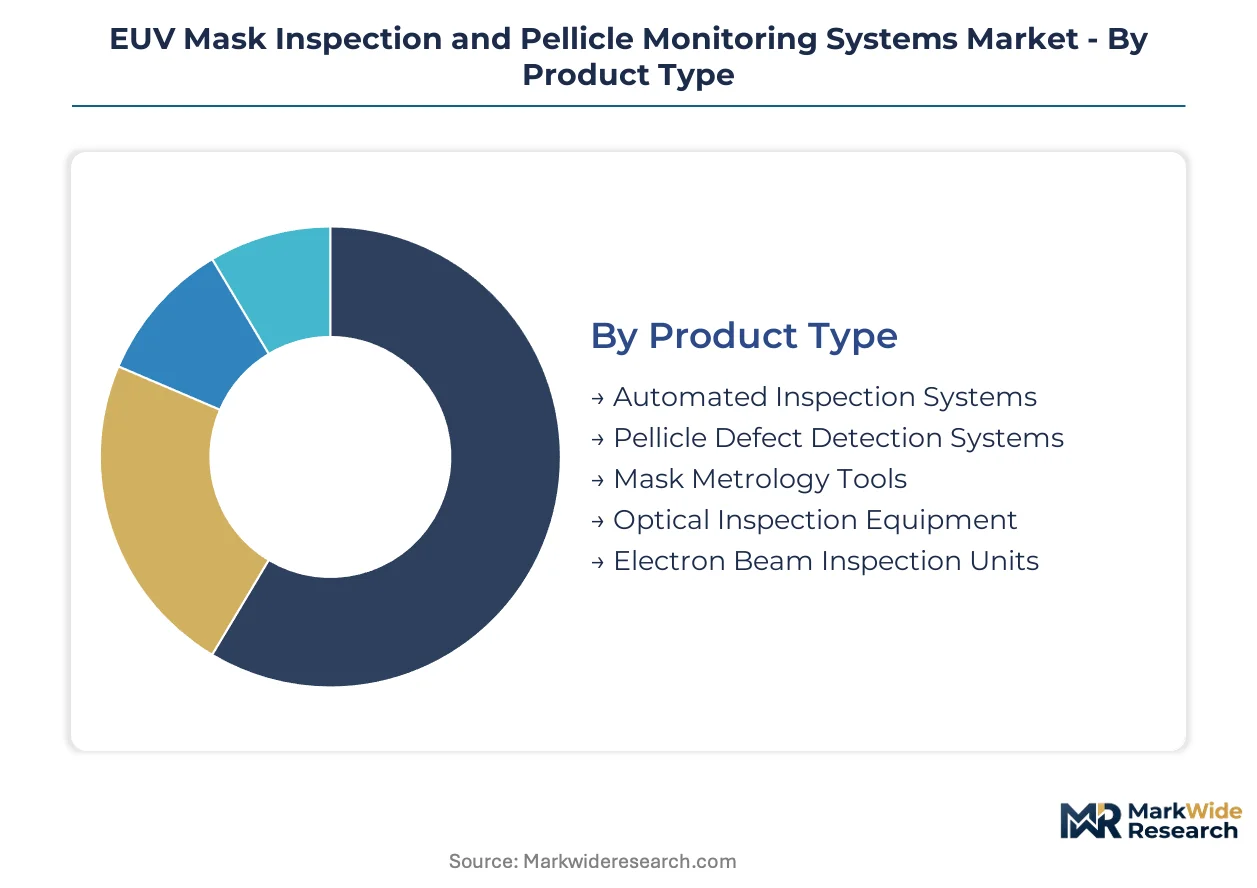
EUV mask inspection systems fragment across multiple technical dimensions, each governing distinct procurement criteria and operational workflows. Semiconductor foundries configure heterogeneous tool portfolios to cover the full defect detection spectrum from mask blank qualification through pellicle lifecycle monitoring. Understanding these segment boundaries clarifies vendor positioning and technology substitution risks.
Product Type:
Mature automated platforms dominate fab floor deployment while emerging modalities address high-NA lithography's compressed tolerance windows.
- Automated Inspection Systems:These platforms integrate multi-sensor architectures for high-throughput mask qualification, combining optical and electron beam modalities in unified workflows. Demand concentrates at Taiwan Semiconductor Manufacturing facilities in Hsinchu where sub-three nanometer production multiplies mask qualification cycles per exposure tool. Throughput requirements intensify as high-NA EUV reduces printable defect thresholds below five nanometers.
- Pellicle Defect Detection Systems:Specialized units monitor membrane integrity under EUV exposure power densities exceeding six hundred watts, detecting particulate contamination and thermal stress fractures. South Korea's Pyeongtaek semiconductor cluster drives procurement as Samsung Foundry scales high-NA lithography for two nanometer logic ramps. Membrane fragility under elevated irradiance demands real-time verification at every exposure station.
- Mask Metrology Tools:These systems quantify pattern placement accuracy and critical dimension uniformity across mask blanks.
- Optical Inspection Equipment:Deep ultraviolet platforms provide economical screening for larger defect categories before actinic qualification.
- Electron Beam Inspection Units:Sequential scanning architectures deliver nanometer-scale resolution for pattern defect characterization.
Automated Inspection Systems retain volume leadership; Pellicle Defect Detection Systems hold the steepest expansion curve.
Technology:
Cost tier stratification separates capital-intensive actinic platforms from accessible optical alternatives, with hybrid architectures emerging at intermediate price points.
- Extreme Ultraviolet:Thirteen point five nanometer wavelength inspection replicates lithographic imaging conditions, capturing phase defects and multilayer perturbations invisible to longer wavelengths. Taiwan's Industrial Development Bureau mandates actinic qualification for masks entering domestic five nanometer production. Equipment vendors face REACH compliance certification for chemistries used in source and collector assemblies.
- Scanning Electron Microscopy:High-resolution imaging resolves sub-ten nanometer defects through secondary electron detection, though throughput constraints limit deployment to sampling applications. Wafer fabricators in South Korea integrate SEM inspection with automated defect review stations. Voltage stability requirements complicate tool qualification for high-volume manufacturing environments.
- Dark Field Imaging:Oblique illumination enhances scattering contrast for small particulate detection on patterned masks.
- Scatterometry:Angular-resolved reflectometry reconstructs three-dimensional profile parameters without electron beam damage.
- Critical Dimension SEM:Dedicated architectures accelerate linewidth measurement throughput for mask qualification cycles.
- Laser Scanning:Coherent detection enables rapid pellicle surface inspection with reduced thermal loading.
Extreme Ultraviolet commands premium positioning; Laser Scanning gains share fastest in pellicle-specific applications.
Application:
Customer type differentiation separates integrated foundry procurement from lithography service provider rental models, with divergent performance specifications and uptime guarantees.
- Photomask Quality Assurance:Comprehensive validation protocols verify pattern fidelity, defect absence, and registration accuracy before mask release to production. IC design companies in Hsinchu Science Park outsource qualification to specialized mask shops with certified actinic capability. Contract terms increasingly specify zero-defect delivery thresholds for sub-seven nanometer designs.
- Pellicle Integrity Monitoring:Continuous membrane surveillance prevents catastrophic contamination events during wafer exposure sequences. Semiconductor foundries in Pyeongtaek deploy inline monitoring at every EUV scanner to minimize yield excursions from pellicle rupture. EPA F-Gas reporting requirements add operational overhead to membrane replacement workflows.
- Defect Identification:Classification algorithms distinguish killer defects from nuisance signals to prioritize repair interventions.
- Process Control:Statistical process control integration enables mask health trending and predictive maintenance scheduling.
- Yield Improvement:Root-cause analysis correlates mask defects with wafer print failures to close lithographic feedback loops.
Photomask Quality Assurance retains volume leadership; Pellicle Integrity Monitoring holds the steepest expansion curve.
End User:
Volume concentration tracks leading-edge logic capacity installation, with procurement authority fragmenting between central metrology groups and individual fab engineering organizations.
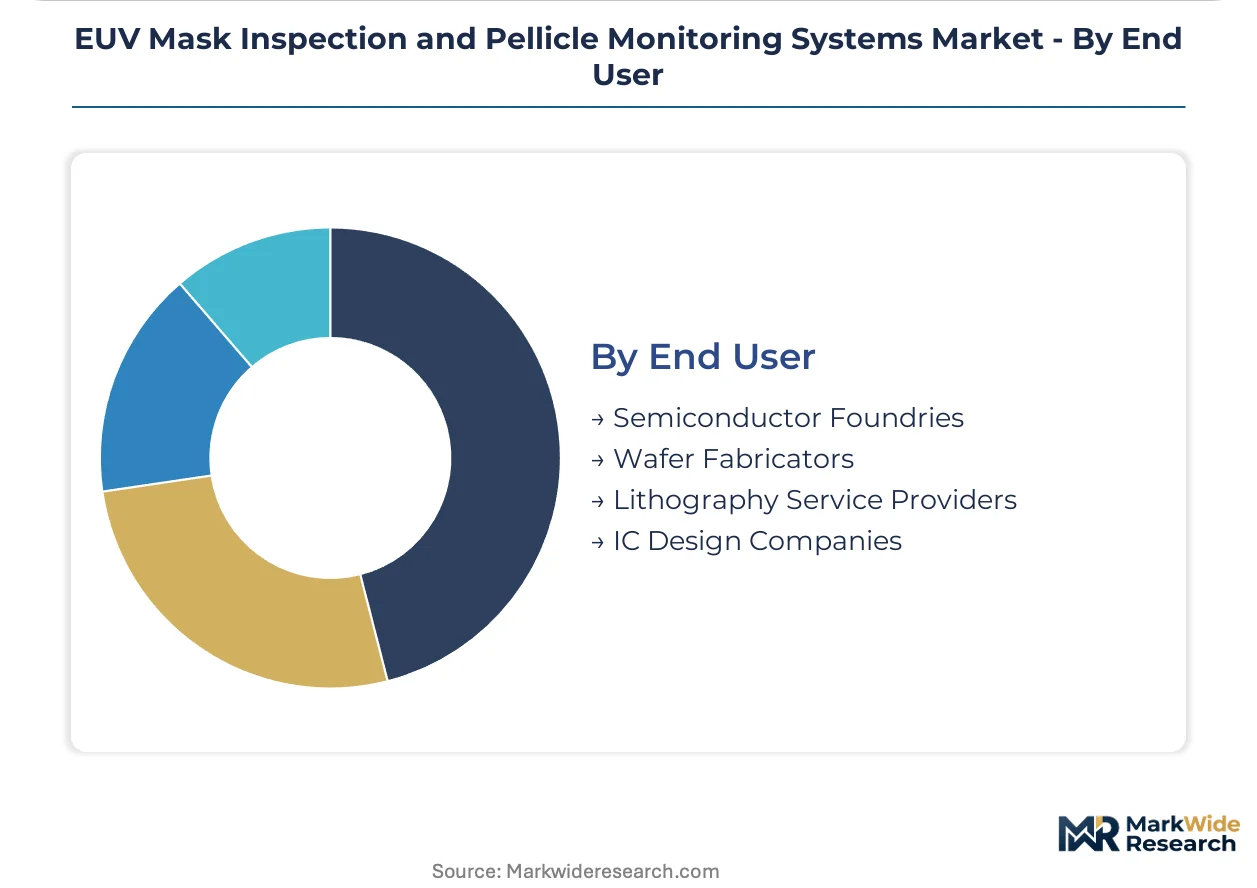
- Semiconductor Foundries:Merchant logic manufacturers operate the largest installed bases, qualifying hundreds of masks per technology node ramp. Taiwan and South Korea foundries account for dominant procurement volumes as three nanometer and below capacity expands. Multi-fab coordination challenges drive standardization initiatives for inspection recipe portability.
- Wafer Fabricators:Memory manufacturers deploy inspection infrastructure for EUV layers in DRAM and NAND stacks, with distinct defect sensitivity requirements. SK Hynix operations in Icheon prioritize pellicle monitoring for high-aspect-ratio contact hole layers. Cyclical capital intensity complicates long-term inspection tool planning.
- Lithography Service Providers:Mask shops and exposure service bureaus offer qualified masks and inspection data as bundled offerings.
- IC Design Companies:Fabless semiconductor firms specify qualification protocols and audit mask shop metrology capabilities.
Semiconductor Foundries retain volume leadership; Wafer Fabricators hold the steepest expansion curve as memory EUV adoption accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Merchant foundries in Taiwan and South Korea purchase the majority of EUV mask inspection capacity, while equipment vendors navigate divergent chemical compliance regimes across production geographies.
Taiwan
Hsinchu Science Park fabs consume automated inspection systems for sub-three nanometer mask qualification cycles. Taiwan's Industrial Development Bureau enforces local content standards for imported metrology tools. Tainan and Taichung satellite facilities are replicating Hsinchu's actinic qualification protocols as two nanometer capacity scales.
South Korea
Samsung Foundry and SK Hynix drive pellicle defect detection procurement for high-NA lithography ramps. MFDS regulates fluorinated substance handling in semiconductor manufacturing environments. Pyeongtaek's semiconductor cluster commands real-time membrane monitoring systems at every EUV exposure station.
United States
Intel's Arizona and Oregon fabs anchor North American demand for electron beam inspection units. EPA F-Gas reporting requirements add operational overhead to fluorinated chemistry workflows. Albany Nanotech Complex in New York hosts advanced lithography research programs qualifying next-generation mask architectures.
Japan
Tokyo Electron's domestic customer base sustains demand for mask metrology tools and optical screening platforms. METI oversees export control classifications for actinic inspection technologies. Yokohama and Kyoto equipment manufacturing corridors supply critical source components to global system integrators.
Germany
Zeiss SMT's Oberkochen operations anchor European supply for EUV optical subsystems used in inspection platforms. REACH Annex XVII restricts perfluorinated substances in pellicle membrane chemistries, compelling certification protocols. Dresden's silicon Saxony cluster qualifies masks for automotive and industrial semiconductor applications.
EUV Mask Inspection and Pellicle Monitoring Systems Market Competitive Landscape
Channel-controlling players compete with product-specialist players across three discernible tiers. Lithography ecosystem integrators leverage scanner installed bases to extend into adjacent process control layers. Independent metrology vendors defend position through actinic wavelength specialization and defect classification software. Equipment OEMs pursue strategic partnerships with mask shops to secure qualification workflow anchoring. Consolidation pressure intensifies as high-NA lithography compresses vendor qualification windows.
Within the lithography-integrated tier, ASML Holding and Carl Zeiss SMT represent ecosystem-control archetypes that shape adjacent equipment procurement standards. Among independent inspection specialists, KLA Corporation and Lasertec Corporation exemplify technology-deep positioning where actinic qualification capabilities create vendor stickiness. Applied Materials occupies a hybrid position spanning materials engineering and process control, reflecting portfolio breadth strategies that resist pure-play categorization.
| Leading Market Players |
|---|
| KLA Corporation |
| Lasertec Corporation |
| ASML Holding |
| Hitachi High-Tech Corporation |
| Applied Materials |
| Carl Zeiss SMT |
| Advantest Corporation |
| NuFlare Technology |
| JSR Corporation |
| Others |
Pricing and Supply Chain Analysis
Japanese and German specialty chemical suppliers dominate pellicle membrane feedstock production, anchoring margin capture upstream while foundries in Taiwan and South Korea absorb downstream pricing pressure through long-term equipment service contracts.
Pricing Analysis
Cost-plus contracts with rare earth and fluoropolymer indexation dominate equipment procurement between foundries and inspection system vendors. Price differentiation rests on actinic wavelength certification tier and after-sales service bundling intensity. Cost compression in optical inspection tiers is intensifying because South Korean procurement teams unbundle maintenance contracts. Memory wafer fabricators exhibit highest price sensitivity; leading-edge logic foundries show lowest sensitivity due to yield-risk premiums.
Supply Chain Analysis
Contract manufacturing concentrates with Tokyo Electron, Hitachi High-Tech, and Zeiss SMT facilities across Japan and Germany. Critical inputs draw from precision optics substrates, extreme ultraviolet source components, and high-purity fluorinated chemistries. Single-source vulnerability pervades actinic source collector assemblies. Distribution runs through direct foundry relationships with lithography equipment OEMs, bypassing traditional distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat structure where regulatory entrenchment via REACH and EPA certification requirements creates substantial switching costs for qualified vendors.
For Market Incumbents: Insulate qualification workflows by deepening backward integration into fluoropolymer supply and accelerating actinic inspection capacity expansion in Hsinchu. Emerging entrants from China's domestic equipment push threaten mid-tier optical inspection margins. Certification investment in fluorine-free pellicle protocols represents the critical lever for European market retention. For New Entrants and Emerging Players: Build out AI-driven defect classification software layers that integrate with existing KLA and Lasertec hardware footprints. India semiconductor manufacturing incentives create the most penetrable geography as domestic foundry capacity scales without entrenched inspection vendor relationships. Partnership with emerging mask shops in Gujarat and Karnataka offers viable go-to-market anchoring. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed metrology software specialists holding machine learning defect classification capabilities. Long-term viability centers on five-to-ten year lithography node roadmaps where high-NA EUV penetration sustains equipment refresh cycles. Watch for Intel and Samsung Foundry qualification decisions on next-generation actinic platforms as inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| Actinic Inspection Platform Launch | Enables single-digit nanometer defect detection for TSMC's sub-three nanometer ramps. |
| Fluorine-Free Pellicle Certification | Secures European market access under REACH Annex XVII perfluorinated substance restrictions. |
| AI Defect Classification Integration | Reduces false-positive rates in Samsung Foundry's high-NA lithography qualification cycles. |
| Backward Integration into Source Components | Captive supply of EUV collector assemblies mitigates Zeiss SMT single-source dependency. |
| India Manufacturing Partnership | Positions inspection vendors for Tata Electronics and ISMC Digital fab equipment procurement. |
Research Methodology
The analysis maps automated inspection systems, pellicle defect detection platforms, and electron beam architectures, each validated through semiconductor foundry metrology directors, lithography equipment procurement officers, mask shop operations managers, and regulatory compliance specialists. Primary interviews combined with secondary validation from SEC semiconductor equipment filings, SEMI industry statistics, EPA F-Gas emission reports, and ECHA REACH substance databases. Bottom-up equipment shipment analysis triangulates against top-down foundry capex allocation patterns.
Assumptions held fixed include current REACH and EPA regulatory trajectories, while high-NA EUV adoption pace and India foundry construction timelines varied across scenarios. Segmentation dimensions modeled encompass product type, inspection technology wavelength, application workflow, and end-user foundry versus memory fabricator classification. CAGRs derived from equipment unit forecasts multiplied by average selling price trajectories, incorporating fluoropolymer cost pass-through assumptions and service unbundling trends.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese domestic equipment vendors or accelerated India foundry ramps would shift outcomes. Quarterly review of foundry capex guidance, REACH substance restriction amendments, and high-NA EUV scanner installation rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.