
 Japan Semiconductor Memory Market | 2026-2036
Japan Semiconductor Memory Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Semiconductor Memory Market Insights
METI's push for domestic semiconductor supply chain resilience is hardening procurement requirements for Japanese memory suppliers. Kioxia Holdings Corporation leverages its vertical integration in NAND flash fabrication to sustain cost advantages against offshore competitors. Renesas Electronics Corporation anchors its position in automotive-grade memory through specialized reliability testing protocols. Samsung Electronics Co. Ltd competes aggressively in the mobile DRAM segment, while Micron Technology Inc. controls advanced packaging capacity through its Hiroshima operations.
Semiconductor memory encompasses integrated circuits designed for data storage and retrieval, with DRAM cells built from one transistor and one capacitor per bit to achieve nanosecond access times and SRAM employing six-transistor flip-flop architectures for faster cache applications. These devices serve as the foundational storage layer in computing systems, from edge sensors to hyperscale servers. NAND flash dominates product type revenue due to its density advantages in solid-state drives and mobile storage, while DDR5 technology is displacing prior generations in data center and AI accelerator boards. The automotive end user segment commands premium pricing through extended temperature and vibration specifications that consumer electronics do not require.
METI's semiconductor subsidy framework and JIS standards for electronic component quality shape domestic procurement rules and export qualification pathways. PMDA oversight intersects with memory markets indirectly through medical device data integrity requirements that favor Japanese-certified suppliers. Stakeholders must monitor how METI's next funding allocations prioritize memory-specific fabrication against logic chip investments, as this determines which domestic facilities receive preferential licensing and utility support.
Market Dynamics
METI's semiconductor resilience subsidies are redirecting capital toward domestic fabrication while DDR5 memory architectures compress refresh cycles in data center deployments across Kanto.
Growth Catalysts
- Automotive-grade specifications:Japanese OEMs now mandate AEC-Q100 qualified memory for powertrain controllers, creating captive demand for extended-temperature NAND and DRAM components.
- METI subsidy framework:Domestic foundry investments receive preferential licensing and utility rate structures under the 2021 Economic Security Promotion Act, lowering operational expenditure for memory-specific fabs.
- Packaging cluster concentration:Yokohama and Tokyo host vertically integrated assembly and test facilities that reduce logistics friction for Kanto-based system integrators.
Market Restraints
- Raw material import dependency:Silicon wafer and photoresist supply concentrates with Taiwanese and South Korean chemical suppliers, exposing cost volatility to yen fluctuations and maritime chokepoints.
- Extreme ultraviolet lithography scarcity:ASML equipment allocation prioritizes logic chip foundries, constraining Japanese memory producers' access to sub-7nm process nodes.
- JIS certification timelines:Extended qualification periods for automotive and medical device memory modules delay revenue recognition by 18-24 months against offshore competitors.
Strategic Opportunities
- Chubu region fab expansion:Nagoya and surrounding industrial corridors offer underutilized utility infrastructure and proximity to Toyota supply chains for automotive memory localization.
- AI accelerator integration:High-bandwidth memory architectures are converging with GPU-based training clusters, opening white space for Japanese suppliers in domestic hyperscale builds.
- Green technology mandates:METI's carbon-neutral factory standards create first-mover advantages for memory producers deploying renewable-powered cleanroom operations.
Industry Challenges
- Process engineering talent scarcity:Japanese universities produce insufficient analog circuit designers and yield optimization specialists to staff expanded domestic fabrication.
- Legacy system integration friction:Industrial automation customers in Osaka and Nagoya operate 20-year controller architectures requiring custom memory form factors that fragment production runs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Semiconductor Memory Market |
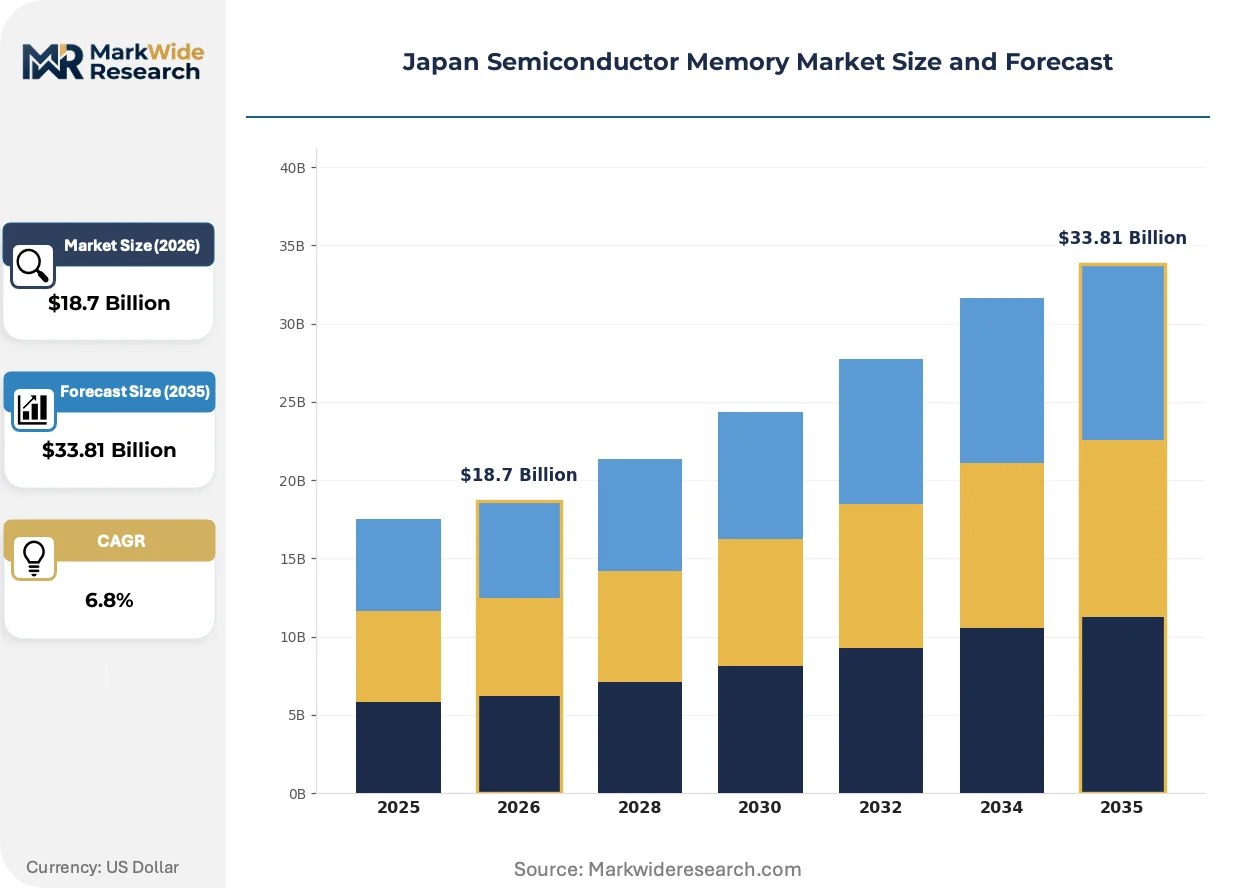
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: DRAM, NAND Flash, SRAM, PCM End User: Consumer Electronics, Automotive Electronics, Data Centers, Mobile Devices Technology: 3D NAND, DDR4, DDR5, LPDDR4 Application: Cloud Computing, Artificial Intelligence, Gaming Consoles, Mobile Computing |
| Companies Covered | Kioxia Holdings Corporation, Renesas Electronics Corporation, ROHM Co. Ltd., Micron Technology Inc., SK Hynix Inc., Samsung Electronics Co. Ltd, Tokyo Electron, Sony Semiconductor Solutions Corporation, RAMXEED Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Semiconductor Memory Market Trends and Innovations
Memory architectures are fragmenting across performance tiers as automotive reliability requirements diverge from consumer density priorities, while packaging innovations compress physical footprints.
DDR5 synchronous DRAM is overtaking DDR4 in server motherboard designs through improved power management and channel architecture. Hyperscale operators in Tokyo data centers are adopting the standard at replacement-cycle velocity. This transition is overtaking commodity DDR4 pricing structures and compressing margin recovery windows for legacy inventory holders.
METI's semiconductor resilience policies now require domestic content thresholds for government-procured electronic systems. Japanese system integrators must certify memory provenance through JIS-compliant supply chain documentation. Automotive and medical device segments face the steepest compliance ramps as PMDA data integrity rules intersect with METI localization mandates.
Direct procurement contracts between memory suppliers and tier-one automotive OEMs are displacing traditional distribution through generalist semiconductor traders. Toyota and Honda purchasing departments now negotiate annual volume commitments for AEC-Q100 qualified components. This pattern concentrates most visibly in the Chubu region where Nagoya-based suppliers maintain captive relationships with powertrain module manufacturers.
Japan Semiconductor Memory Market Segmentation
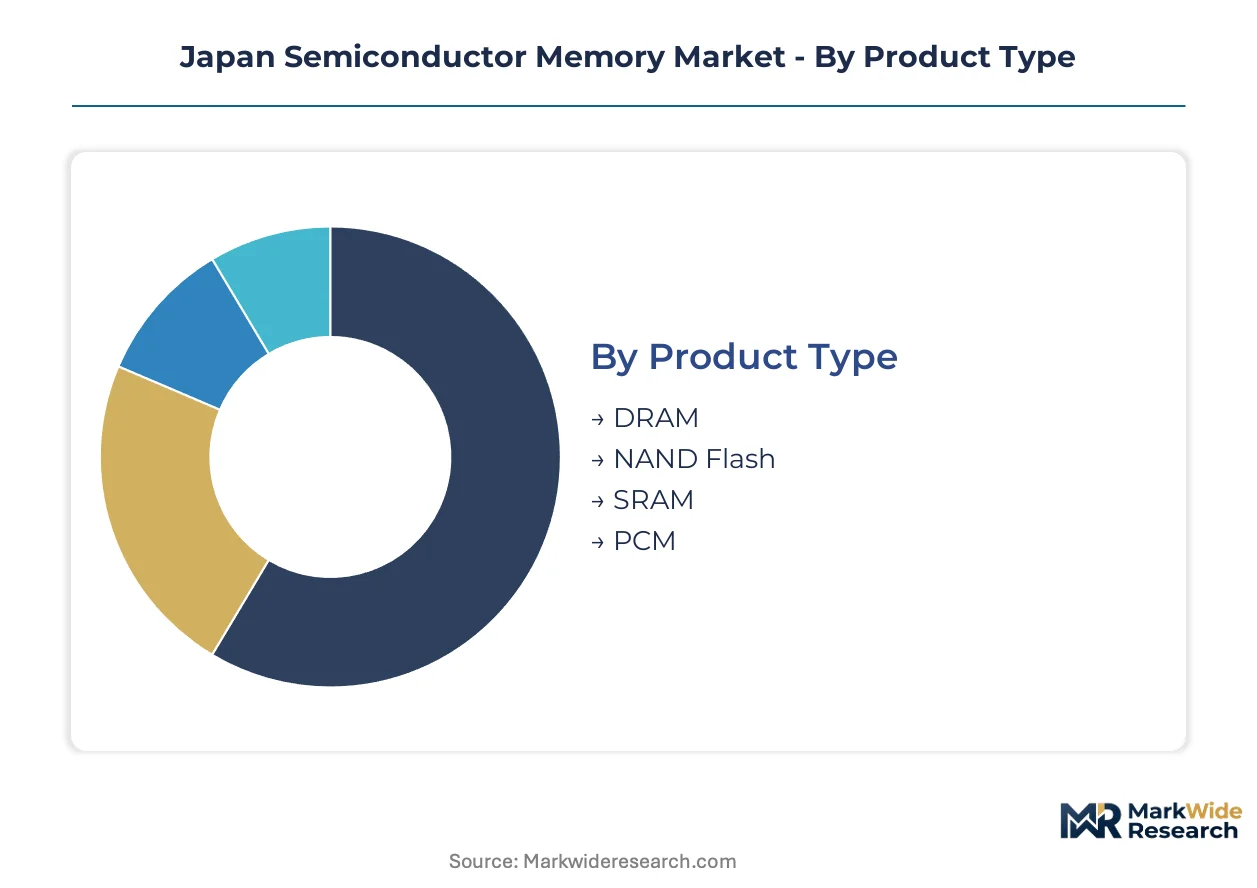
Memory architectures in Japan fragment sharply between embedded automotive systems and standalone data center modules. METI's domestic content thresholds force suppliers to map each segment against JIS certification pathways and foundry licensing priorities.
Product Type:
Standalone memory chips dominate high-volume server deployments while embedded configurations penetrate automotive powertrain controllers and industrial automation systems.
- NAND Flash:Charge-trap cell architecture achieves higher bit density than floating-gate alternatives through vertical stacking of 176-layer and 232-layer configurations. Tokyo data centers and Kanto-based hyperscale operators absorb the majority of enterprise-grade solid-state drive output, though automotive infotainment systems in Nagoya corridors are climbing fastest for industrial-temperature qualified modules.
- DRAM:Capacitor-based volatile storage delivers nanosecond access latencies for CPU cache hierarchies and main system memory. Demand concentrates in DDR5 server modules for Tokyo financial services infrastructure, with DDR4 legacy support constraining margin recovery for foundries maintaining multi-node production lines.
- SRAM:Six-transistor flip-flop cells enable faster access than DRAM without refresh cycles, serving processor cache layers and high-speed networking buffers.
- PCM:Phase-change materials exploit chalcogenide glass resistance switching to bridge the latency gap between DRAM and NAND, targeting persistent memory applications.
Volume placements concentrate in NAND Flash; the faster expansion belongs to DRAM as DDR5 displacement accelerates.
End User:
Cost-tier stratification separates automotive-grade qualification premiums from consumer electronics commodity pricing, with certification timelines driving 18-24 month revenue recognition gaps.
- Automotive Electronics:AEC-Q100 qualification mandates extended temperature ranges, vibration resistance, and zero-defect traceability for powertrain and advanced driver-assistance systems. Toyota and Honda procurement departments in the Chubu region negotiate annual volume commitments directly with memory suppliers, bypassing traditional semiconductor distributors.
- Data Centers:Hyperscale operators in Tokyo and Yokohama deploy high-capacity DDR5 modules and NVMe SSD arrays for cloud infrastructure. METI's carbon-neutral factory standards create procurement preferences for memory sourced from renewable-powered Kanto facilities.
- Mobile Devices:Smartphone and tablet manufacturers prioritize low-power LPDDR packages with stacked packaging configurations.
- Consumer Electronics:Television and appliance controllers utilize commodity memory with relaxed reliability specifications.
Automotive Electronics commands the steepest pricing premiums; Data Centers represent the largest absolute volume absorption.
Technology:
Maturity curves separate established DDR4 infrastructure from DDR5 replacement cycles, while 3D NAND layer counts determine foundry equipment allocation priorities.
- 3D NAND:Vertical channel architectures stack memory cells to circumvent planar scaling limits, with 232-layer production concentrating in Yokohama packaging clusters for proximity to Kanto system integrators.
- DDR5:On-die power management and doubled burst length improve channel efficiency over DDR4. Tokyo financial and AI training facilities are adopting the standard at replacement-cycle velocity, compressing legacy inventory recovery windows.
- DDR4:Mature node production continues for industrial automation controllers in Osaka and Nagoya operating 20-year legacy architectures.
- LPDDR4:Low-voltage operation targets mobile device power budgets with reduced standby current draw.
DDR4 retains the widest installed base; DDR5 is climbing the fastest as server motherboard designs complete transition.
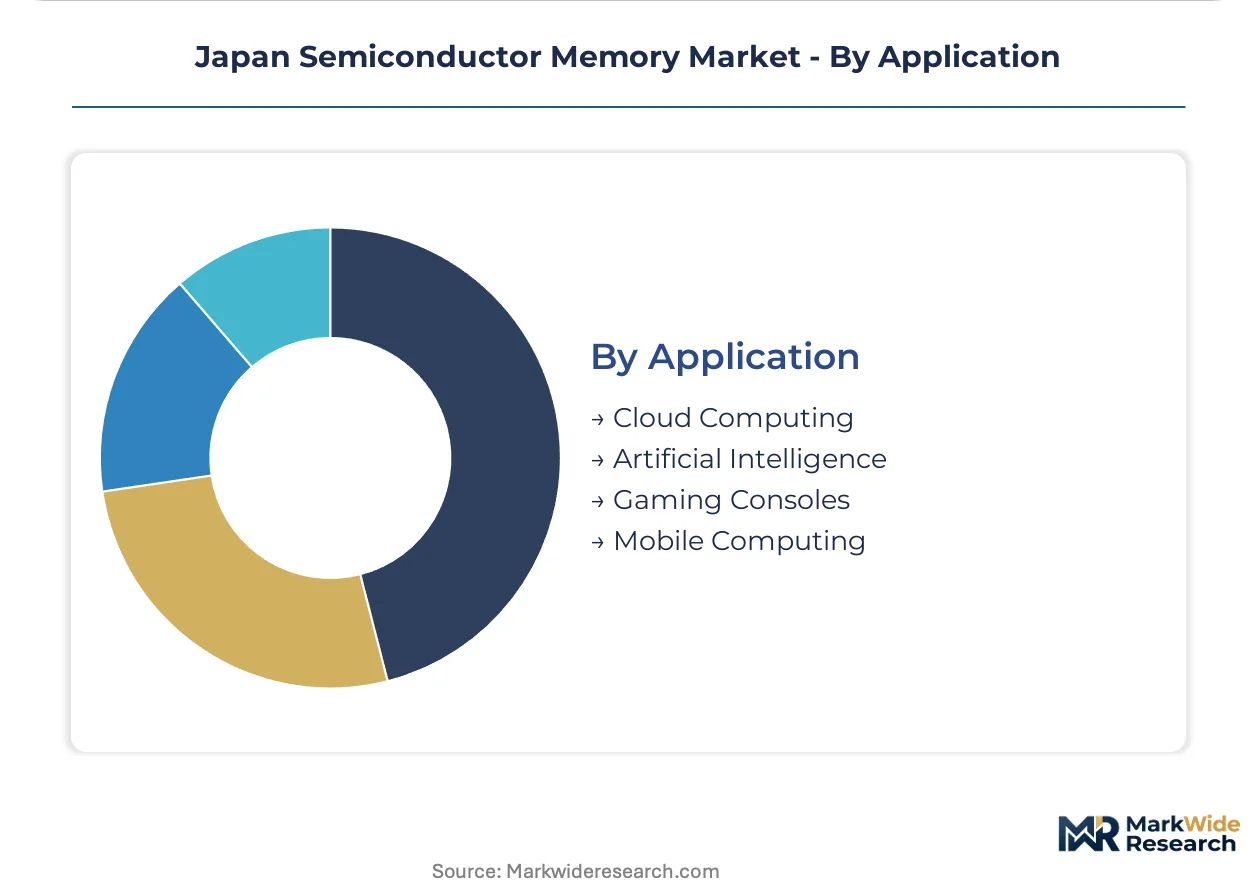
Application:
Customer-type divergence separates enterprise procurement through direct OEM negotiation from consumer channel distribution through electronics retailers.
- Cloud Computing:Distributed storage architectures demand high-capacity NAND for object storage tiers and low-latency DRAM for caching layers. METI's domestic content requirements for government-procured systems advantage Japanese-certified suppliers in public cloud infrastructure bids.
- Artificial Intelligence:GPU-based training clusters integrate high-bandwidth memory architectures with 2.5D and 3D packaging for bandwidth-intensive matrix operations. Domestic hyperscale builds in Kanto are opening procurement opportunities for local packaging specialists.
- Mobile Computing:Notebook and tablet form factors balance performance against thermal and power constraints.
- Gaming Consoles:Unified memory architectures share bandwidth between CPU and GPU subsystems.
Cloud Computing absorbs the highest memory density per rack; Artificial Intelligence is gaining share fastest through training cluster expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Kanto's Tokyo-Yokohama corridor anchors Japan's semiconductor memory concentration through clustered foundry and packaging operations serving domestic hyperscale and automotive demand.
Kanto
Tokyo data centers absorb high-capacity DDR5 modules and enterprise-grade NAND for cloud infrastructure expansion. METI's carbon-neutral factory standards advantage memory sourced from renewable-powered Kanto facilities. Yokohama hosts vertically integrated assembly and test operations that reduce logistics friction for regional system integrators.
Chubu
Nagoya corridors generate captive demand from Toyota and Honda powertrain module manufacturers requiring AEC-Q100 qualified components. METI's Economic Security Promotion Act channels preferential licensing toward automotive memory localization in this industrial belt. Direct procurement contracts between tier-one OEMs and memory suppliers are displacing traditional semiconductor distribution here.
Kansai
Osaka's industrial automation sector operates legacy controller architectures demanding custom memory form factors that fragment production runs. JIS certification timelines for automotive and medical device modules delay revenue recognition by 18-24 months against offshore competitors. Local suppliers maintain multi-node DDR4 production lines to support 20-year equipment lifecycles.
Kyushu
Sub-regional utility infrastructure supports backend packaging operations for consumer electronics memory with relaxed reliability specifications. Green technology mandates from METI are redirecting capital toward renewable-powered cleanroom operations in this underutilized corridor. Proximity to Asian maritime shipping lanes offers logistical advantages for export-oriented NAND flash output.
Japan Semiconductor Memory Market Competitive Landscape
Premium-margin players sit above commodity-margin players across automotive-grade qualification and data center density tiers. The vendor base stratifies between domestic fabricators with METI subsidy access and offshore competitors controlling advanced packaging capacity. Three archetypes dominate: vertically integrated NAND specialists, automotive reliability testers, and mobile DRAM scale operators. Capacity expansion in Chubu and strategic partnerships for high-bandwidth memory architectures represent the dominant competitive moves.
Among Japan-based fabricators, Kioxia Holdings Corporation occupies a position within the vertically integrated NAND tier, while Renesas Electronics Corporation exemplifies the automotive-grade specialization archetype through captive reliability protocols. Samsung Electronics Co. Ltd represents the scale-driven mobile DRAM segment competing aggressively for socket placements. These three anchors illustrate how geographic origin and structural positioning determine subsidy eligibility and customer access pathways under METI's domestic content thresholds.
| Leading Market Players |
|---|
| Kioxia Holdings Corporation |
| Renesas Electronics Corporation |
| ROHM Co. Ltd. |
| Micron Technology Inc. |
| SK Hynix Inc. |
| Samsung Electronics Co. Ltd |
| Tokyo Electron |
| Sony Semiconductor Solutions Corporation |
| RAMXEED Limited |
| Others |
Pricing and Supply Chain Analysis
Automotive-grade AEC-Q100 certification against consumer-tier commodity specifications bifurcates Japanese memory markets, concentrating pricing power with Yokohama-based suppliers serving Toyota powertrain modules while fragmenting margins for undifferentiated NAND flash bound for consumer electronics channels. METI's domestic content thresholds reinforce this divergence by attaching procurement preferences to JIS-compliant supply chain documentation, effectively taxing offshore competitors through extended qualification timelines.
Pricing Analysis
Throughput-based pricing anchors enterprise DDR5 server modules deployed in Tokyo financial data centers, where nanosecond latency guarantees command sustained premiums against commodity DRAM. Certification tier and volume scale differentiate automotive NAND contracts in Nagoya corridors, with zero-defect traceability requirements insulating qualified suppliers from spot-market volatility. Cost compression in consumer-grade mobile DRAM intensifies as Samsung Electronics Co. Ltd and SK Hynix Inc. compete for socket placements, while hyperscale operators exhibit lowest price sensitivity given integration costs dominating component expenditure.
Supply Chain Analysis
AEC-Q100 and JIS certification gates constrain supplier qualification for automotive and medical device segments, extending revenue recognition timelines 18-24 months against offshore competitors. Raw material supply concentrates with Taiwanese silicon wafer foundries and South Korean photoresist chemical suppliers, exposing Japanese fabricators to yen fluctuation risk and maritime chokepoint vulnerability through the Taiwan Strait. Distribution runs through direct procurement contracts between tier-one OEMs and memory suppliers in Chubu, displacing traditional semiconductor traders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Japanese semiconductor memory markets constitute a vertical-integration race where captive control over 3D NAND fabrication and advanced packaging capacity determines subsidy eligibility under METI's Economic Security Promotion Act. Players securing Yokohama-based assembly and test operations gain preferential licensing and utility rate structures that compound cost advantages across the projection horizon.
For Market Incumbents: Cement dominance in automotive-grade memory by deepening captive reliability testing protocols and securing direct annual volume commitments with Nagoya-based powertrain module manufacturers. Capacity addition in Chubu industrial corridors defends against emerging packaging specialists targeting Toyota supply chain localization. METI's next funding allocation cycle presents a regulatory threat to margin recovery if logic chip investments displace memory-specific fab licensing priorities. For New Entrants and Emerging Players: Launch via specialized high-bandwidth memory architectures for domestic AI training clusters in Kanto, where GPU-based integration demands outstrip established supplier bandwidth. White-space concentration sits with persistent memory applications bridging DRAM-NAND latency gaps, particularly for Tokyo financial services infrastructure requiring data integrity guarantees. A go-to-market angle targeting JIS-compliant medical device modules exploits 18-24 month qualification barriers that deter offshore commodity competition. For Investors and Strategic Acquirers: Re-rating potential sits with vertically integrated NAND specialists given METI subsidy flow-through and carbon-neutral factory standard compliance. Long-term viability over the analysis window favors fabricators with backward integration into 176-layer and 232-layer 3D NAND production, insulating against ASML extreme ultraviolet lithography allocation constraints favoring logic chip foundries. The signal to watch is METI's prioritization of memory-specific fabrication against logic chip investments in upcoming subsidy tranches.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Chubu Region | Proximity to Toyota and Honda powertrain supply chains reduces logistics friction for automotive-grade memory localization. |
| Backward Integration into 3D NAND Fabrication | Vertical control over 176-layer and 232-layer charge-trap cell production secures METI subsidy eligibility and cost advantages. |
| High-Bandwidth Memory Packaging Partnership | 2.5D and 3D packaging capabilities for GPU-based AI training clusters open procurement opportunities in Kanto hyperscale builds. |
| JIS Certification Investment for Medical Devices | PMDA data integrity requirements intersect with METI localization mandates to create procurement preferences for Japanese-certified suppliers. |
| Renewable-Powered Cleanroom Operations | Carbon-neutral factory standards under METI's green technology mandates generate first-mover advantages in government procurement bids. |
Research Methodology
Document review covered METI subsidy framework filings, JIS electronic component standards, PMDA medical device data integrity guidelines, and hyperscale operator capex disclosures, complemented by interviews with foundry operations directors, automotive Tier 1 procurement managers, and data center infrastructure planners. Secondary validation drew from semiconductor trade customs data, SEC 10-K filings of memory suppliers, and Tokyo Electron equipment shipment reports. Bottom-up segment sizing and top-down market reconciliation triangulated volume and value estimates.
Segment-level outputs across product type, end user, technology, and application dimensions were modeled against foundry capacity utilization, AEC-Q100 qualification timelines, and DDR5 server motherboard adoption curves. CAGRs were derived from regression analysis of historical replacement cycles and projected technology transitions. Forecast inputs incorporated ASML equipment allocation constraints, yen-denominated raw material cost trajectories, and METI domestic content threshold enforcement patterns.
Extreme ultraviolet lithography scarcity, raw material import dependency through Taiwan Strait maritime routes, and METI funding reallocation toward logic chip investments are the dominant revision risks to modeled outputs. A model refresh is warranted upon material change in METI's next semiconductor subsidy framework prioritization.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Memory Chips
Global Emerging Non-Volatile Memory Market
Memory Chips
Non-Volatile Memory (NVM) Market
Memory Chips
MRAM Market
Memory Chips
Europe Dynamic Random Access Memory (DRAM) Market
Memory Chips
Embedded Non-Volatile Memory Market
Memory Chips
Japan Flash Memory Market
Memory Chips
Smartphone RAM Market
Memory Chips
Memory Module Market
Memory Chips
China Flash Memory Market
Memory Chips
Hybrid Memory Cube Market
Memory Chips
Nano RAM Market
Memory Chips
Ferroelectric RAM Market
Memory Chips
Next Generation Non Volatile Memory Market
Memory Chips
Asia Pacific Semiconductor Memory Market
Memory Chips
Automotive DRAM Market
Memory Chips
Memory Interface Chip Market