
 Wet Station Market | 2026-2036
Wet Station Market Size, Share, and Industry Trends Forecast 2026-2036
Wet Station Market Analytics
Consolidation among healthcare facility buyers is repositioning procurement power toward large hospital networks and integrated health systems. Thermo Fisher Scientific Inc. leverages its diagnostic equipment footprint to bundle wet station solutions with broader laboratory workflows. Labconco Corporation anchors its position through specialized containment product lines that serve high-biosafety environments. Waldner Laboreinrichtungen GmbH & Co. KG dominates European laboratory furniture markets with engineered water and gas delivery systems.
A wet station is a plumbed or self-contained fixture designed for controlled hand washing, material rinsing, or decontamination, typically featuring integrated water supply, drainage, splash containment, and optional chemical dispensing at specified flow rates and pressure tolerances. These units serve infection control, hazardous material handling, and cleanroom compliance across clinical, educational, and industrial settings. Automatic stations command premium positioning due to touchless sensor activation and reduced cross-contamination risk, while portable units address fastest-growing demand from temporary healthcare expansions and mobile testing deployments. Permanent installation systems retain the deepest margin pools through long-term service contracts and facility integration complexity.
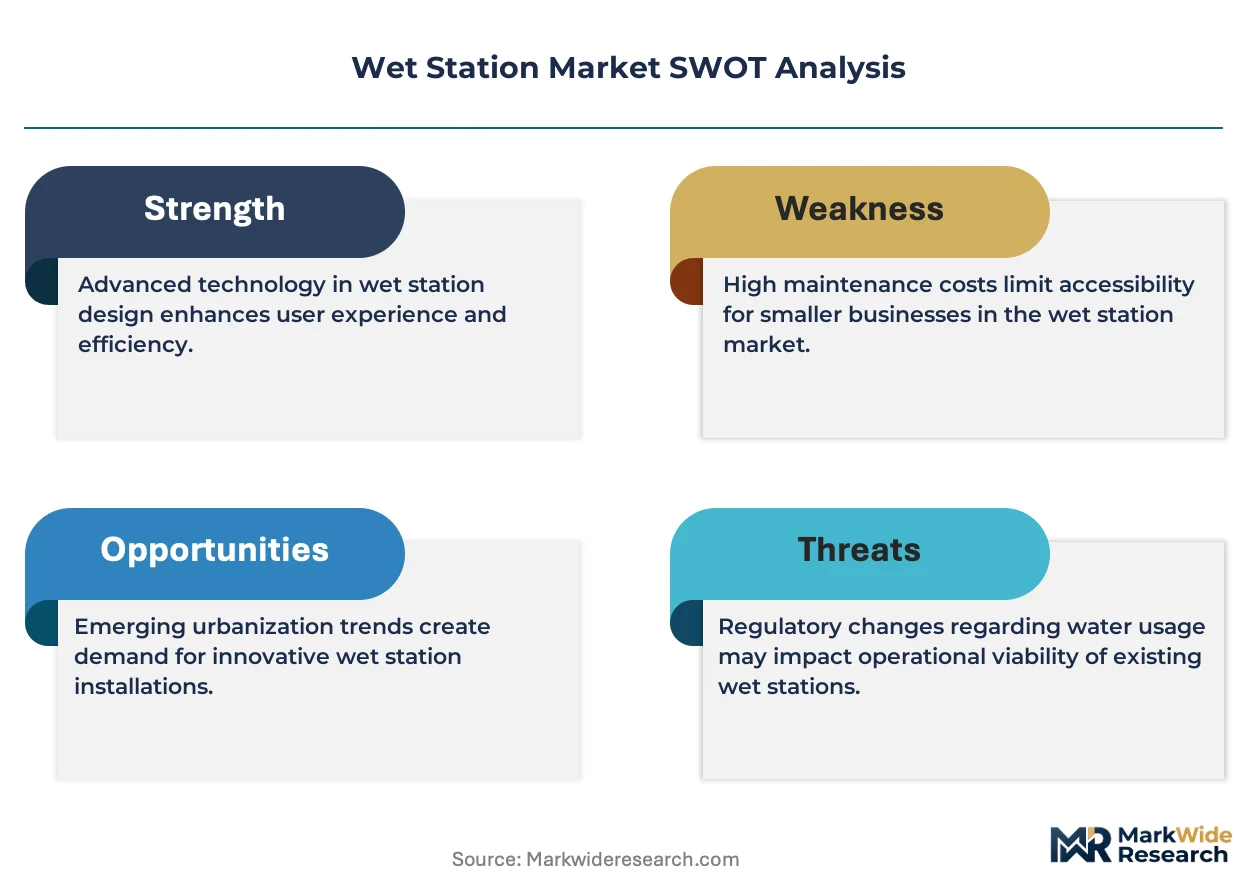
FDA guidelines on healthcare hand hygiene, OSHA bloodborne pathogen standards, and EPA WaterSense efficiency specifications collectively shape product design, certification requirements, and market access thresholds for wet station manufacturers. The EU Green Deal adds pressure through embodied carbon and water consumption benchmarks that filter procurement eligibility in public tenders. Stakeholders must weigh capital intensity against regulatory compliance velocity when selecting between standardized platforms and custom-engineered installations.
Market Dynamics
Healthcare facility consolidation and the EU F-Gas Regulation are compressing procurement cycles while forcing manufacturers toward water-efficient, low-emission wet station architectures that integrate with building management systems.
Growth Catalysts
- EU Green Deal water benchmarks:Public tenders in Germany and France now mandate embodied carbon thresholds and WaterSense-equivalent efficiency ratings, disqualifying legacy plumbed systems from hospital procurement pools.
- Laboratory infrastructure investment:Pharmaceutical R&D facilities across Switzerland and the Netherlands are retrofitting BSL-3 containment suites with permanent wet stations that feature integrated chemical dispensing and negative-pressure drainage.
- Touchless sensor activation:Infrared and capacitive proximity sensors are replacing manual faucets in clinical settings, reducing cross-contamination incidents and aligning with FDA hand hygiene guidance for surgical preparation areas.
Market Restraints
- Stainless steel input volatility:Grade 316L sheet metal constitutes 35-45% of wet station bill-of-materials, exposing manufacturers to nickel and molybdenum price swings from Indonesian and Philippine mining operations.
- Specialized fabricator concentration:Precision welding and electropolishing capabilities for pharmaceutical-grade wet stations cluster in southern Germany and northern Italy, creating single-source vulnerability for pan-European projects.
- Plumbing infrastructure lock-in:Existing cast-iron drainage systems in US healthcare facilities built before 1990 cannot accommodate low-flow sensor faucets without costly pipe diameter modifications, slowing retrofit adoption.
Strategic Opportunities
- Modular portable deployments:Mobile testing units and temporary pandemic response facilities in Spain and Poland are sourcing self-contained wet stations with onboard water tanks and battery-powered pumps, bypassing permanent infrastructure requirements.
- CE-MDR convergence:The EU Medical Device Regulation is reclassifying certain decontamination wet stations as Class I medical devices, creating certification moats for early-compliant manufacturers in public hospital tenders.
- IoT-enabled predictive maintenance:Flow sensor data and valve cycle counts transmitted via LoRaWAN networks are enabling service contract bundling, shifting revenue from hardware sales to recurring facility management subscriptions.
Industry Challenges
- Certified welder scarcity:ASME IX and EN ISO 9606-1 qualified TIG welders for pharmaceutical-grade stainless steel fabrication face 6-9 month lead times in the UK and Ireland, constraining capacity expansion.
- Legacy BMS integration complexity:BACnet and Modbus protocol mismatches between new wet station sensor networks and 1990s-era building automation systems in US academic medical centers require costly middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wet Station Market |
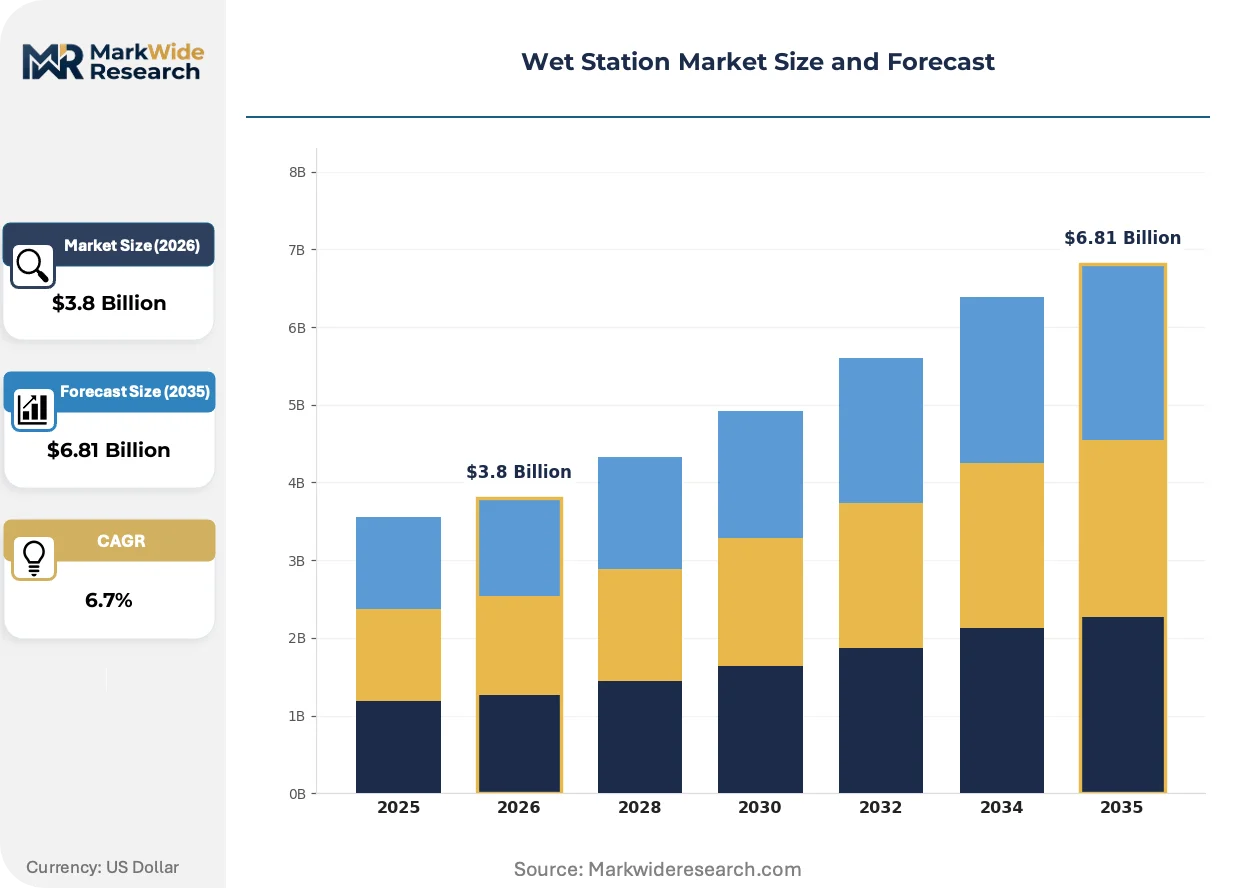
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hand Wash Stations, Automatic Stations, Portable Units, Wall-Mounted Stations End User: Healthcare Facilities, Educational Institutions, Food Services, Industrial Plants Installation: Permanent Installation, Temporary Setup, Mobile Solutions, Fixed Infrastructure Distribution Channel: Direct Sales, Online Retailers, Distributors, Wholesale |
| Companies Covered | Thermo Fisher Scientific Inc., Labconco Corporation, LEEC Limited, Terra Universal, Inc., Waldner Laboreinrichtungen GmbH & Co. KG, Koettermann GmbH & Co. KG, HEMCO Corporation, Esco Group, NuAire, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wet Station Market Evolving Landscape
Water reclamation and sensor fusion technologies are redefining wet station architecture, while regulatory pressure on embodied carbon is forcing redesigns of traditional plumbed systems.
Ultraviolet-C LED arrays for effluent disinfection are integrating into surgical scrub stations and pharmaceutical rinse sinks, enabling real-time microbial load reduction without chlorine residuals that corrode stainless steel. Academic medical centers in Denmark and Sweden are piloting these systems in transplant unit renovations, attracted by elimination of chemical storage compliance burdens. The technology is integrating water treatment directly at point-of-use, compressing the traditional centralized sterilization infrastructure footprint.
The EU F-Gas Regulation's phasedown of hydrofluorocarbon-based refrigerants is indirectly pressuring wet station manufacturers to eliminate foam insulation containing blowing agents with high global warming potential. German and Austrian laboratory furniture producers are substituting vacuum-insulated panels and mineral wool in self-contained tempering units, triggering supply chain requalification for component vendors. Pharmaceutical cold-chain wet stations for temperature-sensitive reagent handling are most affected, with redesign cycles extending 18-24 months to secure new insulation certifications.
Consolidated procurement by integrated health systems is compressing vendor evaluation timelines and demanding outcome-based service level agreements rather than equipment-only transactions. Large hospital networks in France and Belgium are unbundling installation, commissioning, and 10-year maintenance into separate contract lots, favoring wet station manufacturers with certified in-house service teams over pure equipment OEMs. This pattern is most visible in public-private partnership hospital builds, where facility management concessionaires prioritize lifecycle cost predictability over upfront capital expenditure minimization.
Wet Station Market Segmentation
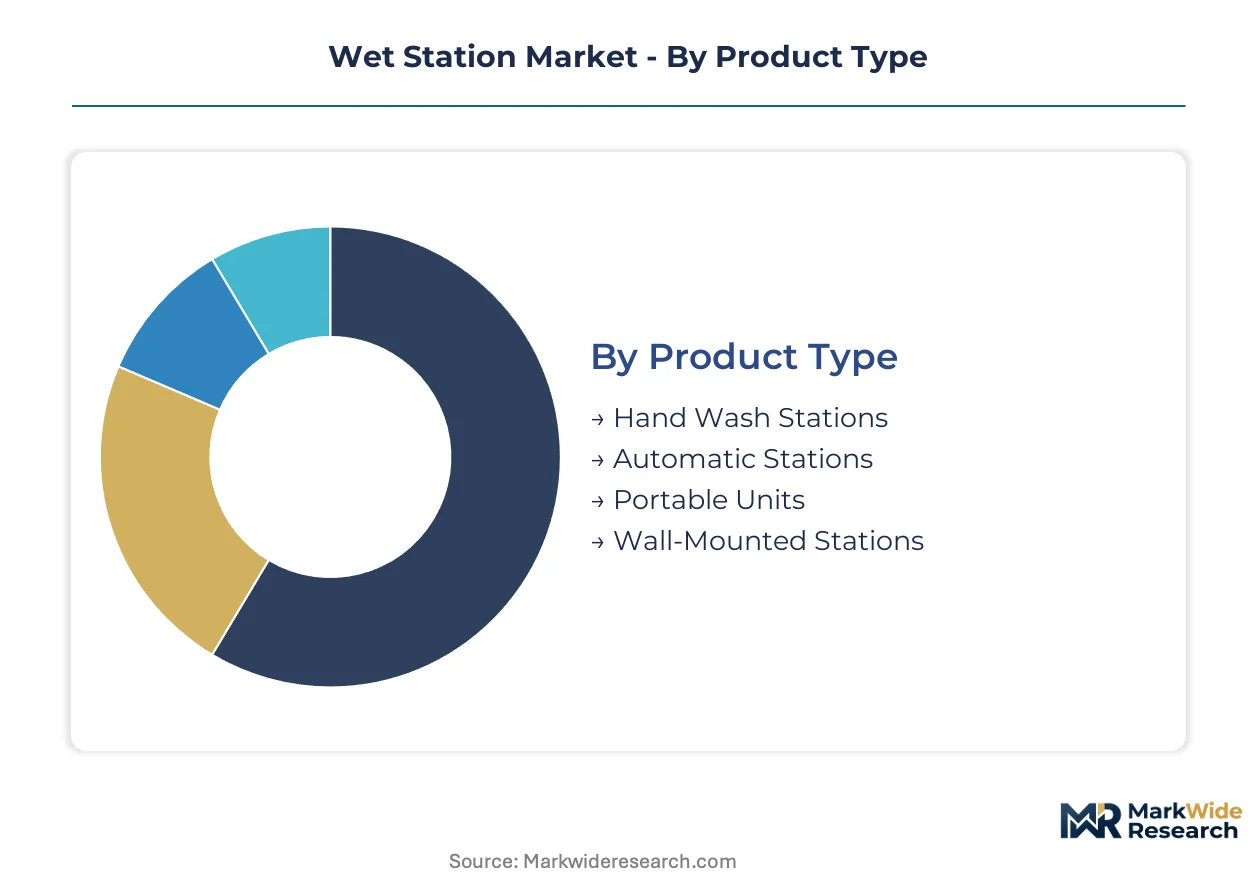
Wet station procurement patterns diverge sharply across facility types and infrastructure constraints. Product architecture, installation permanence, and channel access each create distinct margin profiles and competitive dynamics that manufacturers must navigate simultaneously.
Product Type:
Upgrade cycles for sensor-activated systems are compressing from seven to four years as touchless protocols become standard in clinical environments.
- Hand Wash Stations:These plumbed fixtures integrate ceramic basins, thermostatic mixing valves, and splash guards for controlled hand hygiene in surgical suites and pharmaceutical cleanrooms. German hospital networks are retrofitting legacy scrub sinks with infrared-activated faucets to meet EU Green Deal water efficiency benchmarks, though cast-iron drainage infrastructure in facilities built before 1990 slows conversion timelines.
- Automatic Stations:Sensor-activated units with capacitive proximity detection and programmable flow rates command premium positioning through reduced cross-contamination risk and precise water metering. Swiss and Dutch pharmaceutical R&D facilities specify these for BSL-3 containment suites where manual contact violates biosafety protocols.
- Portable Units:Self-contained systems with onboard tanks and battery-powered pumps serve mobile testing deployments and temporary pandemic response infrastructure in Spain and Poland.
- Wall-Mounted Stations:Space-constrained fixtures for corridor and utility room placement in older European healthcare facilities with limited floor area.
Volume placements concentrate in Hand Wash Stations; the faster expansion belongs to Automatic Stations.
End User:
Cost tier stratification separates capital-intensive healthcare procurement from price-sensitive institutional segments.
- Healthcare Facilities:Hospitals, outpatient clinics, and diagnostic laboratories with stringent FDA and EU MDR compliance requirements for infection control infrastructure. French and Belgian integrated health systems are unbundling installation and 10-year maintenance contracts, favoring manufacturers with certified in-house service teams.
- Educational Institutions:Universities and research laboratories with intermittent usage patterns and deferred maintenance budgets prioritize standardized, repairable platforms over custom configurations.
- Food Services:Commercial kitchens and processing plants governed by HACCP protocols where stainless steel corrosion resistance and chemical dispensing integration drive specification.
- Industrial Plants:Chemical manufacturing and electronics cleanrooms requiring hazardous material decontamination and specialized effluent handling.
Healthcare Facilities absorb the deepest procurement volume; Educational Institutions are climbing the fastest as research infrastructure investment accelerates.
Installation:
Application requirements dictate infrastructure commitment levels and corresponding service contract structures.
- Permanent Installation:Engineered systems with building-integrated water, drainage, and gas delivery infrastructure. German laboratory furniture specialists dominate this segment through long-term facility management partnerships.
- Temporary Setup:Rapid-deployment configurations for renovation periods and surge capacity without structural modification.
- Mobile Solutions:Trailer-mounted or skid-based units for field hospitals, disaster response, and remote research stations requiring complete infrastructure independence.
- Fixed Infrastructure:Hard-piped installations with dedicated mechanical rooms and centralized water treatment in large academic medical centers.
Permanent Installation retains the largest installed base; Mobile Solutions are gaining share fastest as emergency preparedness budgets expand.
Distribution Channel:
Customer type and order scale determine channel economics and manufacturer margin capture.
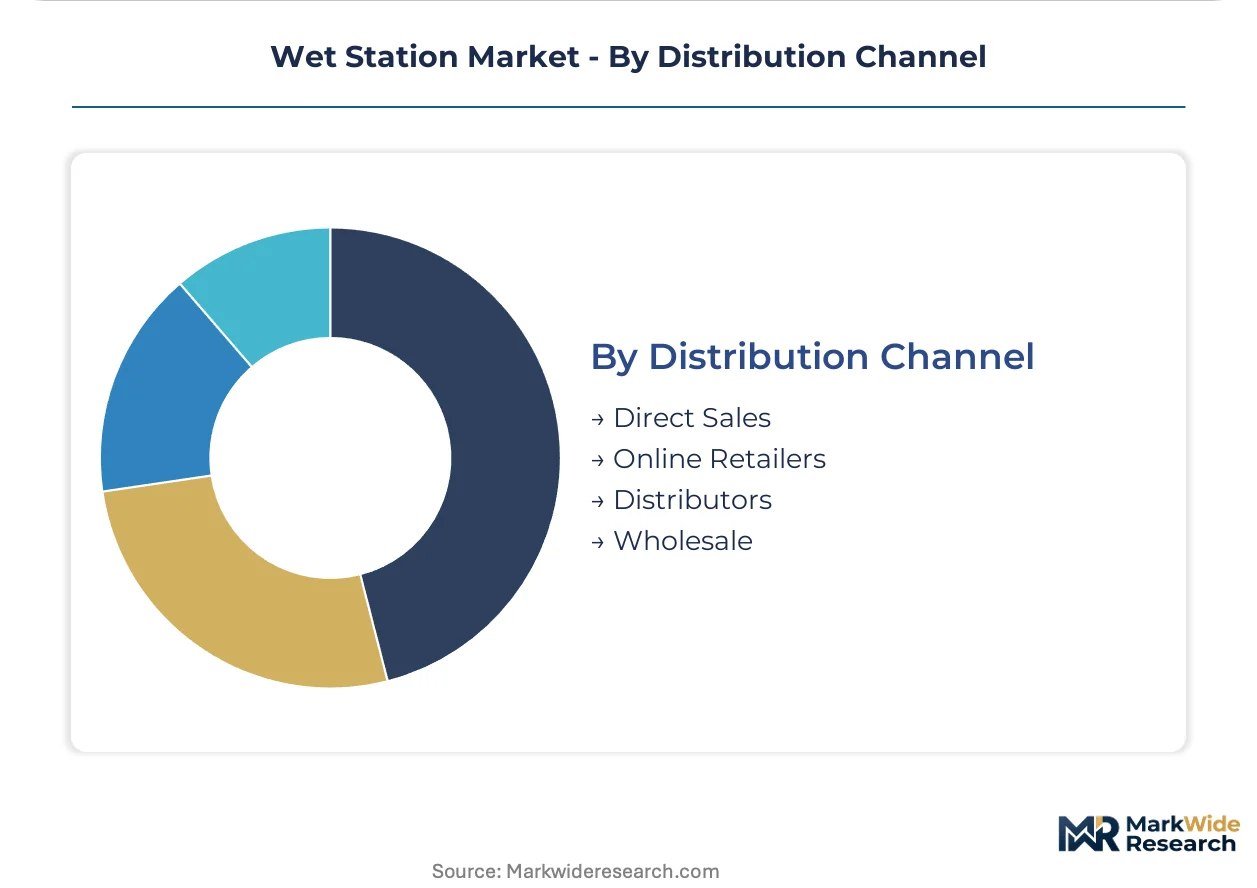
- Direct Sales:Manufacturer-led specification and commissioning for large hospital networks and public-private partnership builds where lifecycle cost predictability outweighs upfront capital minimization.
- Online Retailers:Standardized portable units and replacement components for smaller educational and food service buyers with limited procurement staff.
- Distributors:Regional inventory and technical support for mid-tier healthcare facilities requiring rapid spare parts availability.
- Wholesale:Volume aggregation for contractor-led new construction projects with specified brand allowances.
Direct Sales commands the highest average order value; Online Retailers are expanding most quickly as catalog standardization reduces configuration complexity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German laboratory infrastructure investment and stringent biosafety standards concentrate demand for permanent installation wet stations in pharmaceutical and research applications across Europe. Healthcare facility consolidation in France and Belgium is repositioning procurement power toward large hospital networks with unbundled service contracts.
Germany
Pharmaceutical R&D facilities in Bavaria and Baden-Württemberg are retrofitting BSL-3 containment suites with integrated chemical dispensing systems. The EU F-Gas Regulation pressures manufacturers in southern Germany toward vacuum-insulated panel designs. Waldner Laboreinrichtungen GmbH & Co. KG anchors engineered water delivery systems from Wangen im Allgäu.
France
Integrated health systems in Île-de-France are compressing vendor evaluation timelines for public-private partnership hospital builds. ANSM guidance on infection control infrastructure shapes procurement specifications in Paris and Lyon clusters. Facility management concessionaires prioritize lifecycle cost predictability over upfront capital minimization in new construction.
Switzerland
Pharmaceutical cleanroom operators in Basel and Zurich specify automatic stations with capacitive proximity detection for biosafety protocol compliance. Swissmedic oversight of medical device classification creates certification requirements for decontamination equipment. Precision fabrication capabilities cluster around the Swiss-German border for pharmaceutical-grade stainless steel work.
Netherlands
Academic medical centers in Rotterdam and Utrecht pilot ultraviolet-C LED arrays for effluent disinfection in surgical scrub stations. The EU Green Deal water efficiency benchmarks filter eligibility in university hospital tenders. Research infrastructure investment accelerates demand for modular portable deployments in temporary testing facilities.
United Kingdom
ASME IX and EN ISO 9606-1 qualified TIG welders face 6-9 month lead times, constraining capacity expansion for pharmaceutical-grade fabrication. MHRA alignment with EU MDR creates transitional certification complexity for wet station imports. London and Cambridge laboratory clusters source specialized containment products through distributor networks.
Wet Station Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue modular portable configurations and IoT-enabled service contracts. The vendor base stratifies across three tiers: diversified laboratory equipment conglomerates with diagnostic bundling capabilities, specialized containment fabricators with electropolishing expertise, and regional furniture specialists with building-integrated system competencies. Consolidation among healthcare buyers favors manufacturers with certified in-house service teams over pure equipment OEMs. Dominant competitive moves include strategic partnerships for facility management concessions and geographic expansion through distributor network capture.
Within the specialized containment tier, Labconco Corporation and Terra Universal, Inc. represent North American precision fabrication capabilities for high-biosafety environments. Waldner Laboreinrichtungen GmbH & Co. KG anchors European laboratory furniture markets with engineered water and gas delivery systems from southern Germany. Thermo Fisher Scientific Inc. exemplifies the diversified conglomerate archetype, leveraging diagnostic equipment footprints to bundle wet station solutions with broader laboratory workflows.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc. |
| Labconco Corporation |
| LEEC Limited |
| Terra Universal, Inc. |
| Waldner Laboreinrichtungen GmbH & Co. KG |
| Koettermann GmbH & Co. KG |
| HEMCO Corporation |
| Esco Group |
| NuAire, Inc. |
| Others |
Value Network & Pricing Analysis
London Metal Exchange nickel price volatility cascades through wet station manufacturing, compressing margins on pharmaceutical-grade stainless steel fabrications while amplifying cost spreads between sensor-activated premium tiers and basic plumbed configurations. Buyers in consolidated French hospital networks exploit this input cost transparency to demand outcome-based service bundling that locks in lifecycle pricing predictability.
Pricing Analysis
Volume placements concentrate in standardized hand wash stations with compressed margins, while automatic sensor-activated systems retain premium positioning through reduced cross-contamination risk and precise water metering capabilities. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated surgical scrub stations from basic clinical fixtures and portable emergency deployments. Cost compression in the standard tier intensifies because German laboratory furniture specialists leverage long-term facility management partnerships to amortize installation complexity. Educational institutions exhibit highest price sensitivity due to deferred maintenance budgets, whereas Swiss pharmaceutical cleanroom operators prioritize biosafety protocol compliance over capital expenditure minimization.
Supply Chain Analysis
ASME IX and EN ISO 9606-1 certified TIG welder scarcity in the UK and Ireland constrains capacity expansion for precision pharmaceutical-grade fabrication, forcing lead time extensions across pan-European projects. Manufacturing gravity centers on southern Germany, northern Italy, and the Swiss-German border for electropolished stainless steel containment products. Grade 316L sheet metal, nickel, and molybdenum feed from Indonesian and Philippine mining operations into these fabrication clusters. Single-source vulnerability in precision welding capabilities creates supply chain risk for BSL-3 containment suite retrofits. Distribution runs through direct manufacturer relationships with large hospital networks, supplemented by regional distributors for mid-tier healthcare facilities requiring rapid spare parts availability.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Wet station manufacturing is consolidating around service-integrated incumbents as EU MDR certification complexity and certified welder scarcity force pure equipment OEMs toward distressed exits or strategic absorption.
For Market Incumbents: To counter margin compression from stainless steel input volatility, deepen backward integration into electropolishing capabilities and secure captive supply of Grade 316L sheet metal through long-term offtake agreements with Nordic distributors. Acquire certified welding capacity in southern Germany to eliminate single-source vulnerability in pharmaceutical-grade fabrication. For New Entrants and Emerging Players: Capture modular portable deployment demand from Spanish and Polish mobile testing infrastructure, where self-contained battery-powered units bypass permanent plumbing requirements and incumbent service integration advantages. Pursue online retail channel penetration for standardized educational and food service segments with limited procurement staff. For Investors and Strategic Acquirers: Distressed-cycle entries favor specialized containment fabricators with EN ISO 9606-1 welding certifications and existing CE-MDR technical documentation in southern Germany, positioned for public hospital tender eligibility as EU medical device reclassification raises compliance barriers. Watch for inflection when French facility management concessionaires accelerate unbundling of 10-year maintenance contracts into separate award lots.| Strategic Initiative | Industry Significance |
|---|---|
| CE-MDR Certification Investment | Creates regulatory moats for public hospital tenders under EU medical device reclassification. |
| IoT-Enabled Predictive Maintenance | Shifts revenue from hardware sales to recurring facility management subscriptions via LoRaWAN sensor networks. |
| Backward Integration into Electropolishing | Eliminates single-source dependency on southern German precision fabricators for pharmaceutical-grade stainless steel work. |
| Modular Portable Product Line Expansion | Addresses fastest-growing demand from Spanish and Polish temporary healthcare infrastructure without permanent plumbing. |
| Long-Term Facility Management Partnership | Aligns with French and Belgian integrated health systems prioritizing lifecycle cost predictability over upfront capital minimization. |
Research Methodology
EU F-Gas Regulation filings, hospital procurement databases, and SEC equipment manufacturer disclosures formed the secondary backbone, cross-referenced with primary interviews involving hospital biomedical engineers, laboratory facility managers, GPO contracts managers, and containment product procurement leads. Bottom-up and top-down triangulation validated wet station shipment volumes across product architectures and installation types.
Bottom-up modeling aggregated facility-level procurement patterns by product type, installation permanence, and end-user segment, while top-down analysis tracked regulatory flow-through effects on manufacturer pricing power across the projection horizon. Segmentation dimensions included sensor activation technology, biosafety containment level, and regional regulatory cluster. CAGRs derived from fitted growth curves incorporating EU Green Deal water efficiency mandate adoption timelines and laboratory infrastructure investment cycles.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to nickel price volatility, certified welder availability, and EU MDR enforcement consistency. Material deviation in stainless steel input costs, ASME IX qualification backlogs, or CE-MDR reclassification timelines warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Equipment
Lithographic Photomasks Market
Semiconductor Equipment
Global Semiconductor Coolers Market
Semiconductor Equipment
Semiconductor Wafer Process Control Equipment Market
Semiconductor Equipment
Vacuum Ovens Market
Semiconductor Equipment
Vacuum Spin Coaters Market
Semiconductor Equipment
Molecular Beam Epitaxy System Market
Semiconductor Equipment
Semiconductor Photolithography Equipment Market
Semiconductor Equipment
Chip Conveyors Market
Semiconductor Equipment
Solar Texturing Equipment Market
Semiconductor Equipment
Thin Film Deposition Equipment Market
Semiconductor Equipment
Semiconductor Bonding Equipment Market
Semiconductor Equipment
Multi-Touch Equipment Market
Semiconductor Equipment
Global Sputtering Equipment Market
Semiconductor Equipment
Middle East Extreme Ultraviolet Lithography (EUVL) Systems Market
Semiconductor Equipment
Reticle Pod Cleaning System Market
Semiconductor Equipment
EUV Mask Inspection and Pellicle Monitoring Systems Market