
 Europe Semiconductor Manufacturing Equipment Market | 2026-2036
Europe Semiconductor Manufacturing Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Semiconductor Manufacturing Equipment Market Foresight
The capability gap between lithography leaders and mid-tier packaging specialists is bifurcating competitive dynamics across European semiconductor equipment. ASML Holding N.V. dominates extreme ultraviolet lithography through unmatched R&D intensity. Infineon Technologies AG anchors power semiconductor fabrication with captive capacity in Dresden and Villach. EV Group specializes in wafer bonding and lithography equipment for compound semiconductor substrates.
Europe Semiconductor Manufacturing Equipment encompasses the precision tools, process chambers, metrology systems, and automation platforms used to fabricate, assemble, and validate integrated circuits on silicon and compound semiconductor wafers. These systems operate at nanometer-scale resolution, with leading-edge photolithography systems achieving sub-3nm patterning for logic and memory devices. Wafer Fabrication Equipment captures the largest value pool, driven by lithography and deposition tool demand from foundry expansions in Germany and France. Test Equipment is expanding fastest as automotive-grade reliability standards require 100% parametric validation for ADAS and powertrain chips. Assembly & Packaging Equipment remains structurally fragmented, with margin pressure concentrated in legacy leadframe and wire bonding segments.
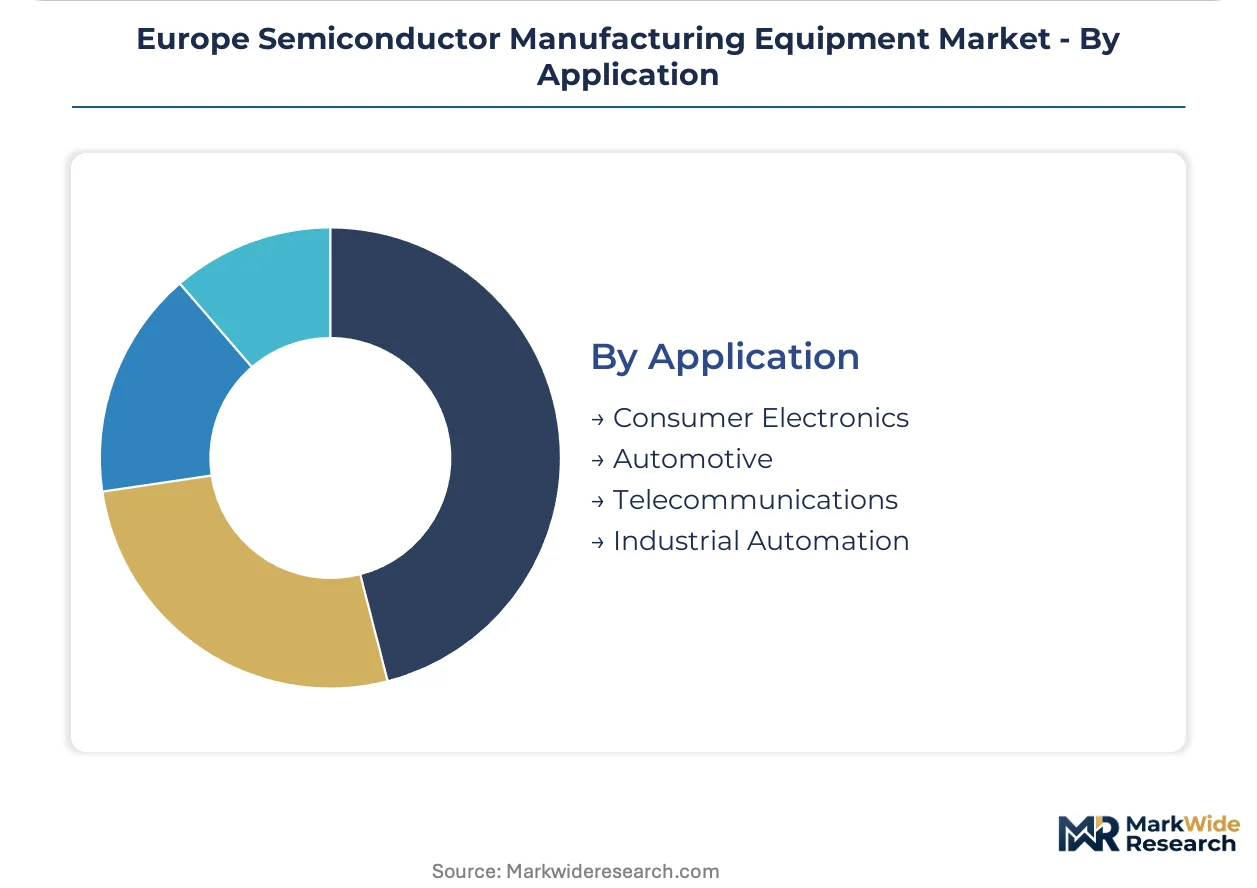
EMA device standards, REACH chemical compliance, and the EU Chips Act subsidy framework collectively shape equipment procurement cycles and facility permitting timelines across member states. CE marking and the EU AI Act impose traceability and safety requirements on autonomous manufacturing systems deployed in European fabs. Stakeholders must monitor how national allocation of Chips Act funds reshapes equipment demand geography and supplier qualification criteria.
Market Dynamics
The EU Chips Act subsidy framework is redistributing equipment demand geography across member states, concentrating capital flows into German and Dutch lithography clusters while reshaping supplier qualification timelines for foundry projects in France and Italy.
Growth Catalysts
- Automotive Chip Demand:German OEMs are expanding captive semiconductor capacity for electric powertrains and ADAS systems, pulling lithography and test equipment orders into Saxony and Bavaria.
- REACH Chemical Compliance:Stricter fluorinated gas regulations under the EU F-Gas Regulation are accelerating replacement cycles for etch and deposition chambers in older European fabs.
- Compound Semiconductor Substrates:Silicon carbide and gallium nitride fabrication for power electronics is expanding wafer bonding and lithography equipment demand in Austria and Switzerland.
Market Restraints
- Extreme Ultraviolet Optics Concentration:Single-source dependency on Dutch lithography component suppliers creates vulnerability for any European foundry scaling below 7nm.
- Helium Supply Volatility:Cryogenic cooling systems for superconducting magnets in ion implantation equipment face input cost pressure from Russian supply disruption.
- CE Marking Complexity:The EU AI Act imposes traceability and safety validation requirements on autonomous manufacturing systems that extend facility permitting timelines by 8-14 months.
Strategic Opportunities
- Polish Packaging Corridor:Underdeveloped advanced packaging capacity in Central Europe offers white space for fan-out wafer-level packaging equipment as German foundries seek nearshoring options.
- Photonics-Electronics Convergence:Silicon photonics integration with CMOS logic is creating demand for hybrid lithography systems that pattern optical and electrical layers simultaneously.
- Chips Act National Allocation:Italian and Spanish subsidy windows for trailing-edge analog fabs are opening procurement channels for 200mm wafer processing equipment outside the German-Dutch core.
Industry Challenges
- Cleanroom Engineering Talent:The shortage of vibration isolation and particulate control specialists is delaying facility commissioning for new European megafabs.
- Legacy Tool Integration:300mm equipment from the 2000s requires costly retrofitting to interface with modern factory automation protocols in expanded Dresden and Villach facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Semiconductor Manufacturing Equipment Market |
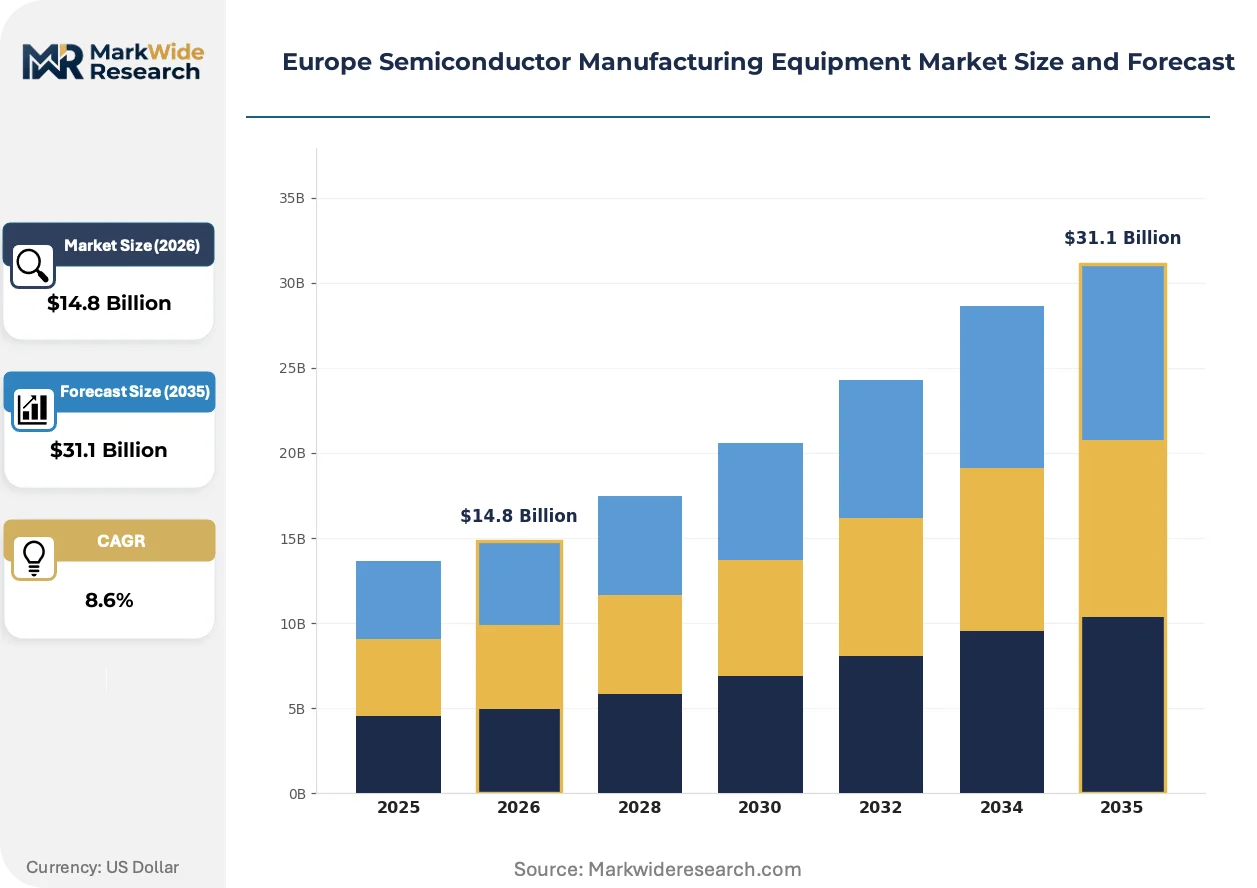
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $31.1 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wafer Fabrication Equipment, Assembly & Packaging Equipment, Test Equipment, Mask/Etch Equipment Technology: Photolithography, CVD, PVD, Ion Implantation End User: OEMs, Foundries, Integrated Device Manufacturers, Research Institutions Application: Consumer Electronics, Automotive, Telecommunications, Industrial Automation |
| Companies Covered | Evatec AG, Nordson Corporation, ASML Holding N.V., NXP Semiconductors N.V., Infineon Technologies AG, EV Group, ASM International, STMicroelectronics N.V., SUSS MicroTec SE, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Semiconductor Manufacturing Equipment Market Shifts & Advancements
High-NA extreme ultraviolet lithography, sustainable process chemistry mandates, and unbundled equipment service models are compressing technology cycles and reshaping supplier-buyer relationships across European semiconductor manufacturing.
EUV pellicle membrane technology is miniaturizing defect tolerance thresholds for photomask protection. Leading-edge logic foundries in the Netherlands and Germany are adopting multi-layer carbon nanotube structures at accelerated qualification pace. This miniaturizing of contamination control specifications is forcing deposition equipment suppliers to redesign chamber architectures for sub-0.5nm particle sensitivity.
The EU F-Gas Regulation is phasing down hydrofluorocarbon consumption in plasma etching and chamber cleaning processes. Equipment manufacturers must certify alternative chemistries like fluorine gas mixtures and cryogenic aerosol systems. Wet etch equipment segments face the steepest compliance redesign burden, with French and Italian fabs piloting closed-loop abatement systems ahead of 2027 reduction targets.
Equipment-as-a-service contracts are displacing traditional capital purchase models for metrology and inspection systems. Foundry operators in Germany and the Netherlands now prefer per-wafer pricing with guaranteed uptime clauses over outright ownership. This shift is most visible in automotive-qualified fabs, where variable output volumes make fixed depreciation schedules economically unattractive.
Europe Semiconductor Manufacturing Equipment Market Segmentation
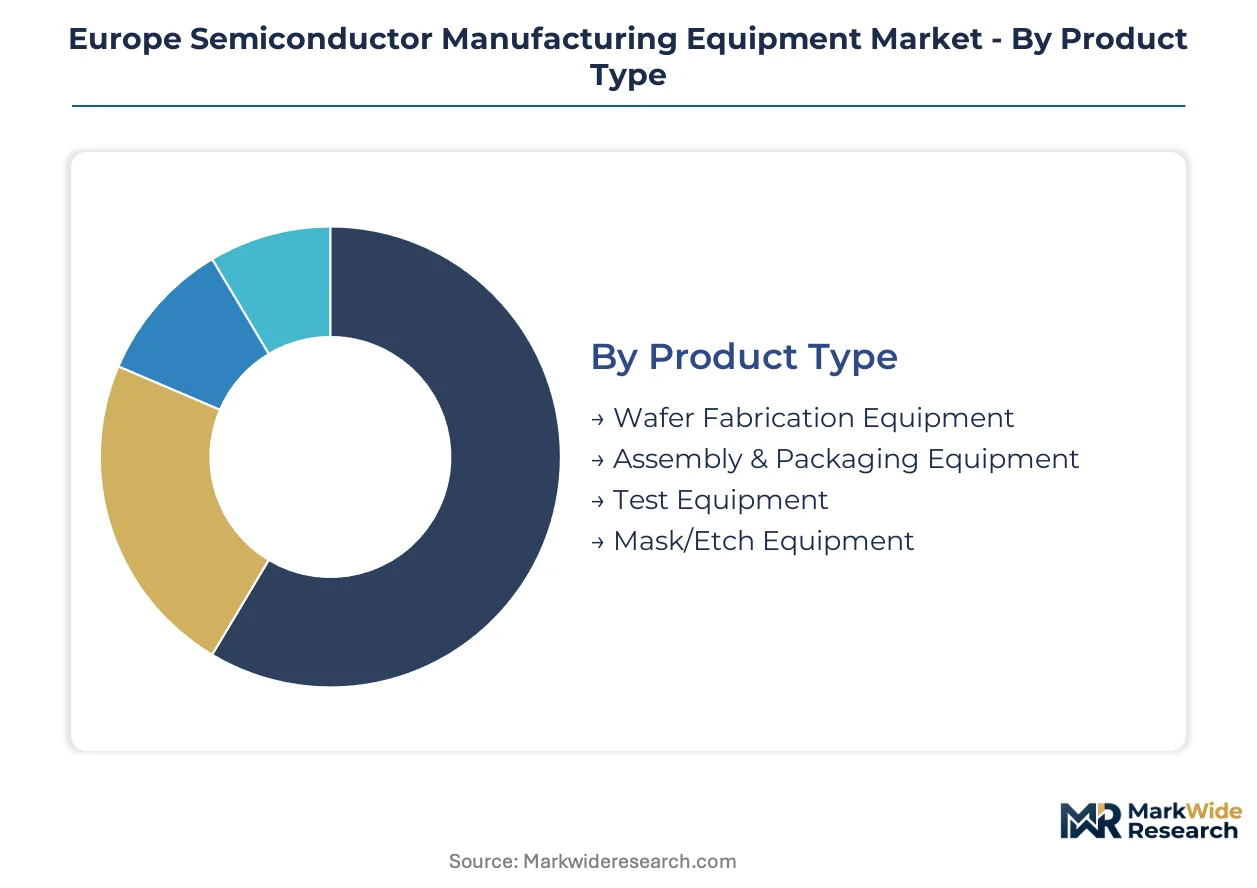
Segmentation reveals how capital flows concentrate across equipment categories in European semiconductor manufacturing. Procurement patterns diverge sharply between German automotive-qualified fabs and Dutch lithography clusters.
Product Type:
Domestic demand concentrates in wafer fabrication systems anchored by Dutch lithography and German power semiconductor capacity. Export-led segments serve Asian foundries through specialized packaging and test platforms.
- Wafer Fabrication Equipment:Lithography, deposition, and etch systems process silicon wafers at sub-10nm resolution. German OEMs in Saxony and Bavaria pull deposition tool orders for electric powertrain chip production. EU Chips Act subsidies accelerate qualification timelines for these high-value systems.
- Test Equipment:Parametric validation systems verify automotive-grade reliability through 100% inspection protocols. French and Italian fabs deploy these for ADAS chip certification under EMA device standards. REACH compliance extends replacement cycles for legacy analog test platforms.
- Assembly & Packaging Equipment:Die attach, wire bonding, and advanced packaging systems complete device fabrication.
- Mask/Etch Equipment:Photomask fabrication and plasma etching tools pattern circuit geometries.
Wafer Fabrication Equipment commands the established base. The steepest expansion runs through Test Equipment.
Technology:
Cost tiers separate EUV-capable platforms from trailing-edge deposition systems. Premium lithography commands five to ten times the unit economics of legacy ion implantation.
- Photolithography:Extreme ultraviolet and deep ultraviolet systems project circuit patterns onto photosensitive wafers. Dutch suppliers dominate EUV optics for sub-7nm logic production. F-Gas Regulation compliance is forcing chemistry redesigns in resist processing subsystems.
- CVD:Chemical vapor deposition builds thin-film layers for gate stacks and interconnects. German foundries in Dresden scale these for silicon carbide power device fabrication. Helium supply volatility from Russian disruption pressures cryogenic precursor delivery systems.
- PVD:Physical vapor deposition sputters metal contacts and barrier layers.
- Ion Implantation:Dopant acceleration modifies semiconductor electrical properties.
Photolithography absorbs the dominant capital share. CVD is climbing the fastest as compound semiconductor capacity expands.
End User:
Customer type determines procurement cadence and qualification rigor. Captive fabs run continuous equipment refresh cycles distinct from merchant foundry spot purchasing.
- OEMs:German automotive manufacturers operate captive fabs for powertrain and sensor chip supply security. Infineon's Dresden and Villach facilities anchor lithography demand from these vertically integrated operators. CE marking complexity under the EU AI Act extends permitting for autonomous manufacturing deployments.
- Foundries:Merchant semiconductor manufacturers serve fabless chip designers on contract. Dutch and French foundries concentrate 300mm logic capacity with EU Chips Act backing. Per-wafer service contracts are displacing capital purchases for metrology systems in these facilities.
- Integrated Device Manufacturers:Combined design and fabrication operations control full production chains.
- Research Institutions:Universities and national laboratories pilot next-generation process technologies.
OEMs anchor the installed base. Foundries are gaining share fastest as EU subsidy windows open.
Application:
End-use application shapes equipment specification and reliability requirements. Automotive qualification imposes the most stringent validation protocols across all segments.
- Automotive:Electric powertrain and ADAS chips require zero-defect manufacturing with full traceability. German OEMs in Stuttgart and Munich drive lithography and test equipment demand for silicon carbide inverters. EMA standards mandate 100% parametric validation extending equipment utilization rates.
- Consumer Electronics:Smartphone and computing processors demand leading-edge logic fabrication. Dutch foundries supply these through EUV-capable capacity concentrated in Eindhoven and Veldhoven clusters. Volume volatility makes equipment-as-a-service contracts attractive for variable output planning.
- Telecommunications:5G baseband and RF chips require compound semiconductor processing.
- Industrial Automation:Factory control systems use trailing-edge microcontrollers and power devices.
Automotive commands the established base. Consumer Electronics is expanding most quickly through leading-edge logic demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Dutch lithography clusters while German automotive fabs absorb cost premiums for qualified equipment. This asymmetry reshapes procurement geography across the continent.
Germany
Automotive OEMs in Stuttgart and Munich drive lithography demand for silicon carbide powertrain chips. The EU Chips Act channels subsidies toward Saxony and Bavaria fab expansions. Dresden anchors wafer fabrication clusters where Infineon scales captive capacity for electric vehicle inverters.
Netherlands
Eindhoven-Veldhoven lithography ecosystems supply extreme ultraviolet systems to global foundries. REACH chemical compliance and F-Gas Regulation mandates accelerate chamber replacement cycles. ASML's supplier network concentrates precision optics manufacturing in the southern Netherlands corridor.
France
Grenoble microelectronics institutes pilot compound semiconductor process technologies for power electronics. EMA device standards extend qualification timelines for automotive-grade test equipment. Crolles foundry clusters expand 300mm capacity with EU Chips Act backing for trailing-edge analog production.
Italy
Milan and Turin semiconductor packaging corridors serve German automotive nearshoring strategies. National allocation of Chips Act funds opens procurement channels for 200mm wafer processing equipment. Agrate Brianza anchors legacy analog fab capacity with upgraded automation protocols.
Austria
Villach power semiconductor fabrication drives wafer bonding equipment demand for silicon carbide substrates. CE marking complexity under the EU AI Act extends permitting for autonomous manufacturing deployments. The Carinthia cluster specializes in compound semiconductor epitaxy systems for industrial power applications.
Europe Semiconductor Manufacturing Equipment Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across European semiconductor equipment. Lithography specialists command premium positioning through optics precision and R&D intensity. Packaging and test equipment segments fragment across regional specialists with narrower geographic footprints. Three archetypes dominate: integrated lithography platforms, compound semiconductor process specialists, and automotive-qualified test system providers. Competitive moves concentrate on strategic partnerships for EUV component supply security and geographic expansion into Central European packaging corridors.
Among Dutch lithography and deposition specialists, ASML Holding N.V., ASM International, and EV Group occupy positions at the precision-process end of the equipment spectrum. These Netherlands-anchored entities exemplify the technology-intensive archetype where optical systems and wafer-level processing capabilities define competitive positioning. German-based SUSS MicroTec SE and Infineon Technologies AG represent the vertically integrated and captive-fab operator models respectively, with the former sitting within precision substrate handling tiers and the latter anchoring demand-side equipment procurement through in-house fabrication scale.
| Leading Market Players |
|---|
| Evatec AG |
| Nordson Corporation |
| ASML Holding N.V. |
| NXP Semiconductors N.V. |
| Infineon Technologies AG |
| EV Group |
| ASM International |
| STMicroelectronics N.V. |
| SUSS MicroTec SE |
| Others |
Supply & Pricing Matrix
Long-term capacity reservation contracts with Dutch lithography component suppliers lock in both extreme ultraviolet optics access and price visibility for German and French foundry expansions under EU Chips Act subsidy windows. These arrangements transfer input cost volatility from ASML's supplier network to equipment purchasers while securing allocation priority during supply-constrained qualification cycles.
Pricing Analysis
Configured-to-order pricing for extreme ultraviolet lithography systems commands a 40-60% premium over standard deposition and etch platforms due to optics customization and site-specific installation engineering. Three-tier pricing structure across premium EUV-capable, standard 300mm trailing-edge, and economy 200mm legacy equipment reflects certification grade and after-sales service bundling. Cost compression in standard-tier wafer bonding equipment is intensifying because Chinese packaging specialists are entering European qualification pipelines. Automotive OEMs in Saxony show least price sensitivity due to captive fab strategies, while Italian analog foundries exhibit highest sensitivity given trailing-edge margin structures.
Supply Chain Analysis
Port congestion at Rotterdam and Hamburg elevates inbound logistics costs for Japanese-sourced ceramic components and American-made RF power supplies critical to plasma etch systems. Precision optics manufacturing concentrates in the Netherlands, Germany, and Japan, with wafer handling robotics drawing from Taiwan and South Korea. German foundries face single-source vulnerability for extreme ultraviolet pellicle membranes. Distribution runs through direct manufacturer-to-fab relationships with minimal distributor intermediation, reflecting the technical complexity of installation and commissioning protocols.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe Semiconductor Manufacturing Equipment Market is approaching a platform-economics inflection where equipment-as-a-service contracts and per-wafer pricing are redefining supplier-buyer relationships around guaranteed uptime rather than asset ownership. Interoperability between Dutch lithography clusters and German automotive fabs is creating ecosystem lock-in that favors incumbents with established service networks.
For Market Incumbents: Fortify lithography service infrastructure in Saxony and Bavaria to capture recurring revenue from EUV system uptime guarantees. Backward integration into extreme ultraviolet optics component supply reduces vulnerability to Dutch single-source concentration. CE marking complexity under the EU AI Act is the priority regulatory lever for differentiation through faster permitting support. For New Entrants and Emerging Players: CE marking fast-track capabilities for autonomous manufacturing systems open procurement channels in Italian and Spanish trailing-edge analog fabs underserved by established German-Dutch suppliers. Polish advanced packaging corridors represent the most penetrable geography, with fan-out wafer-level equipment demand outpacing local supply. A go-to-market angle targeting nearshoring partnerships with Stuttgart automotive OEMs bypasses direct lithography competition. For Investors and Strategic Acquirers: Compound semiconductor process specialists with silicon carbide epitaxy and wafer bonding capabilities offer acquisition exposure to power electronics electrification independent of extreme ultraviolet lithography cycles. Long-term viability centers on equipment-as-a-service contract penetration and recurring revenue share. The signal to watch is per-wafer pricing adoption rates in automotive-qualified fabs as an indicator of business model transformation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| EU Chips Act Subsury Alignment | Secures national allocation priority for German and Dutch fab expansions under EMA compliance frameworks. |
| Helium Supply Diversification | Mitigates Russian disruption exposure for cryogenic cooling systems in ion implantation equipment through Qatari and Algerian sourcing. |
| Equipment-as-a-Service Transition | Captures recurring revenue from metrology and inspection systems through per-wafer pricing with uptime guarantees. |
| F-Gas Regulation Compliance Certification | Accelerates replacement cycles for etch and deposition chambers ahead of 2027 reduction targets under ECHA mandates. |
| Polish Packaging Corridor Entry | Establishes geographic presence in Central Europe for fan-out wafer-level packaging equipment near German automotive demand. |
Research Methodology
Two parallel data streams informed the analysis: primary field engagement with equipment procurement directors at German automotive fabs, Dutch lithography specialists, and French foundry operators; and secondary validation through SEC filings of listed equipment manufacturers, ECHA chemical registration databases, and EU Chips Act national implementation reports. Semiconductor equipment engineering heads, cleanroom facility managers, and REACH compliance officers provided operational perspective. Bottom-up equipment shipment tallies triangulated against top-down fab capex disclosure aggregation.
Across the projection horizon, the analytical framework modeled demand across wafer fabrication, test, and packaging equipment categories by technology node, end-use application, and customer type. Segmentation incorporated lithography capability tier, compound semiconductor substrate material, and automotive qualification status as industry-specific dimensions. CAGRs derived from equipment shipment run-rates, fab construction timelines, and subsidy disbursement schedules. Forecast inputs included EU F-Gas Regulation compliance deadlines and helium supply contract renewal patterns.
Decision-makers should treat outputs as directional under assumptions of sustained EU Chips Act funding continuity and no severe escalation in Russian helium supply disruption; material deviation would warrant model refresh. Specific risk factors include subsidy reallocation across member states, extreme ultraviolet optics export control expansion, and automotive semiconductor demand cyclicality. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Equipment
Wafer Grinding Machine Market
Semiconductor Equipment
Vacuum Soldering System Market
Semiconductor Equipment
United States Chip Mounter Market
Semiconductor Equipment
Wet Station Market
Semiconductor Equipment
China Extreme Ultraviolet Lithography (EUVL) Systems Market
Semiconductor Equipment
Semiconductor Wafer Fab Equipment (WFE) Market
Semiconductor Equipment
Semiconductor Wafer Cleaning Equipment Market
Semiconductor Equipment
Automatic Laser PCB Depaneling Machines Market
Semiconductor Equipment
Wire Bonder Equipment Market
Semiconductor Equipment
Remote Plasma Source Market
Semiconductor Equipment
Global Equipment Front End Module (EFEM) Market
Semiconductor Equipment
Global Sputtering Equipment Market
Semiconductor Equipment
Plasma Etching Equipment Market
Semiconductor Equipment
Electrolytic Etching Machine Market
Semiconductor Equipment
Laser Annealing System Market
Semiconductor Equipment
Dry Reactor Market