
 Die Bonder Machinery Market | 2026-2036
Die Bonder Machinery Market Size, Share, and Industry Trends Forecast 2026-2036
Die Bonder Machinery Market Insights
East Asian equipment builders is broadening die bonder capacity to serve memory and logic packaging expansion. ASM Pacific Technology leverages vertical integration across bonding heads and motion stages to control delivery timelines. Kulicke & Soffa Industries anchors North American service infrastructure for high-mix, low-volume applications. BE Semiconductor Industries specializes in advanced packaging platforms for hybrid bonding and 3D integration.
Die bonder machinery refers to precision assembly equipment that places semiconductor dies onto substrates, lead frames, or interposers with placement accuracy typically below 10 micrometers and throughput exceeding 15,000 units per hour. These systems serve the critical function of interconnecting bare silicon to external circuitry in packaged electronics manufacturing. Automatic equipment dominates volume deployment in high-throughput OSAT environments where labor cost minimization and yield consistency determine total cost of ownership. Eutectic bonding technology leads in power device applications requiring thermal dissipation and electrical conductivity, while laser-assisted bonding gains traction in memory stacking where thermal budget constraints limit conventional methods.
China's MIIT enforces GB standards on semiconductor equipment energy efficiency that filter import eligibility for foreign die bonder suppliers. Japan's METI coordinates JIS standards for precision equipment vibration isolation that shape cleanroom installation specifications. The EU AI Act and CSRD disclosure requirements are beginning to influence equipment procurement criteria for European automotive semiconductor fabs. Stakeholders must monitor how regional subsidy conditions and carbon accounting rules reshape supplier qualification timelines across major packaging geographies.
Market Dynamics
Advanced packaging architectures are compressing die bonder throughput requirements while tightening placement tolerances below 5 micrometers, forcing equipment builders to reengineer motion control systems and thermal management subsystems simultaneously.
Growth Catalysts
- HBM stacking protocols:Memory manufacturers in South Korea and Taiwan are procuring laser-assisted bonders to manage thermal budget constraints during 12-high and 16-high die stacks.
- China's dual carbon mandates:MIIT energy efficiency standards are filtering import eligibility and accelerating domestic equipment substitution in packaging foundries.
- Power module electrification:Silicon carbide device packaging for automotive traction inverters is pulling eutectic bonding platforms with specialized flux-free processes.
Market Restraints
- Precision motion component scarcity:Linear motor stages and air-bearing gantries from Japanese and German suppliers face 26-32 week lead times, constraining equipment delivery schedules.
- Cleanroom floor space economics:Advanced bonders occupy 40-60% more footprint than legacy systems, limiting upgrade paths in capacity-constrained OSAT facilities.
- Process validation timelines:Automotive AEC-Q100 and industrial JEDEC qualification cycles extend 18-24 months, freezing equipment selection decisions.
Strategic Opportunities
- India packaging greenfield:PLI scheme subsidies for semiconductor assembly are attracting first-mover equipment deployments in Gujarat and Karnataka.
- Photonics die bonding:Silicon photonics transceiver manufacturing requires sub-micron placement accuracy for optical coupling, opening premium equipment tiers.
- EU carbon border adjustments:CSRD disclosure requirements are embedding embodied carbon metrics into European automotive fab procurement criteria.
Industry Challenges
- Mechatronics talent scarcity:Motion control firmware engineers and precision mechanical designers command 35-50% salary premiums, constraining R&D expansion.
- Retrofit integration complexity:Legacy wire bonder footprints and material handling systems resist seamless upgrade to hybrid bonding platforms without full line reconfiguration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Die Bonder Machinery Market |
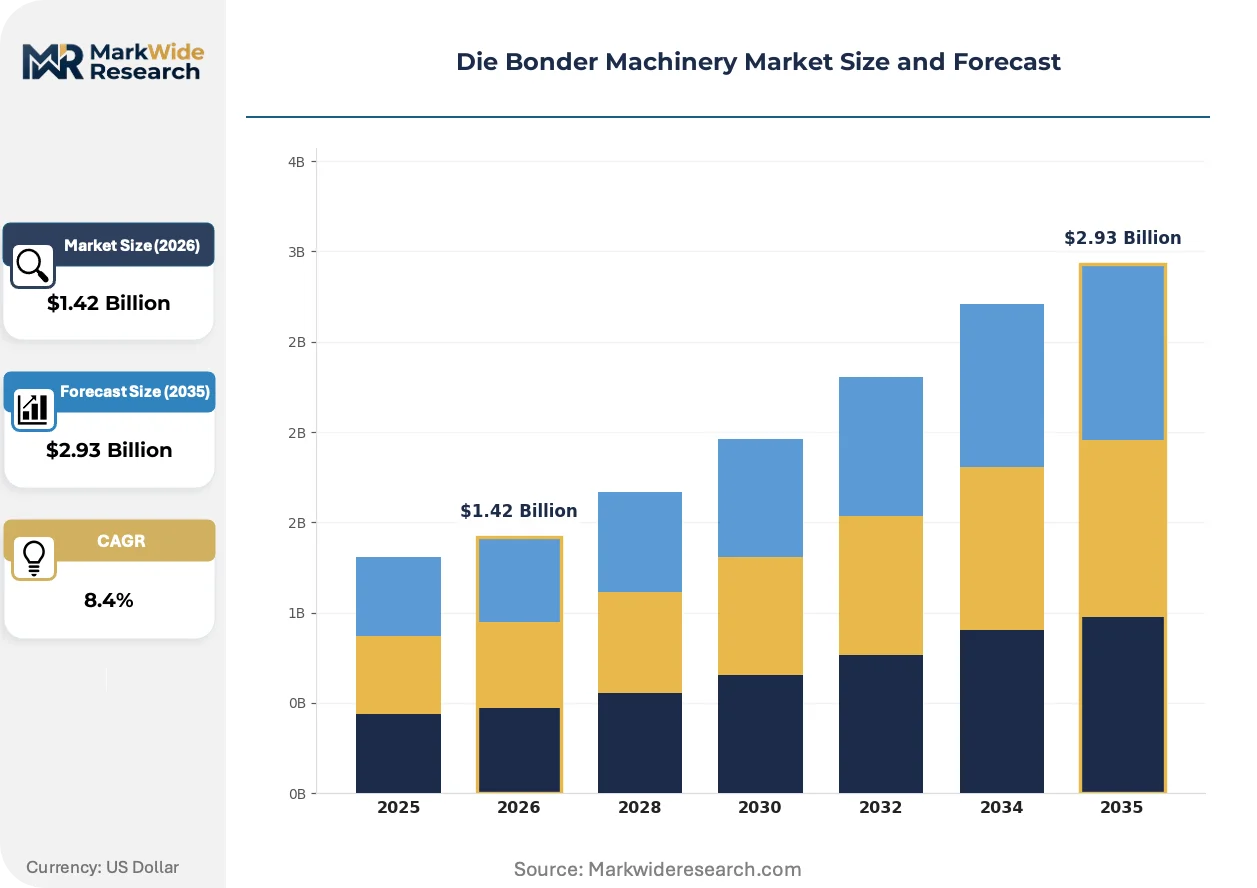
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.93 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual, Automatic, Semi-Automatic, Robotic Technology: Thermal, Laser, Ultrasonic, Eutectic end User: Electronics, Automotive, Aerospace, Telecommunications Application: Microelectronics, Power Devices, MEMS, Sensors |
| Companies Covered | ASM Pacific Technology, Kulicke & Soffa Industries, BE Semiconductor Industries, Shinkawa Ltd., Palomar Technologies, TRESKY GmbH, West·Bond, MRSI Systems, Finetech GmbH & Co. KG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Die Bonder Machinery Market Trends and Innovations
Thermal compression bonding is absorbing capital allocation from traditional thermosonic methods as memory and logic stacking architectures multiply interconnection density requirements.
Thermal compression bonding with non-conductive film interposers is absorbing process development resources at memory manufacturers. Samsung and SK Hynix packaging divisions are transitioning 70% of new HBM4 capacity to this method. The technology is absorbing market share from thermosonic wire bonding in applications below 40 micrometer pad pitch.
Japan's METI is coordinating JIS B 9908 vibration isolation standards that now govern cleanroom installation specifications for sub-5 micrometer placement accuracy equipment. Foreign suppliers must demonstrate compliance through third-party testing at designated Japanese laboratories. European automotive semiconductor fabs are adopting these standards preemptively to qualify for JIS-certified component sourcing.
Equipment-as-a-service contracts with throughput guarantees are displacing traditional capital purchase models among mid-tier OSATs. ASM Pacific Technology and Kulicke & Soffa are piloting per-die bonding fee structures in Southeast Asian packaging houses. This shift is most visible in Malaysia and Vietnam where balance sheet constraints favor operational expenditure treatment.
Die Bonder Machinery Market Segmentation
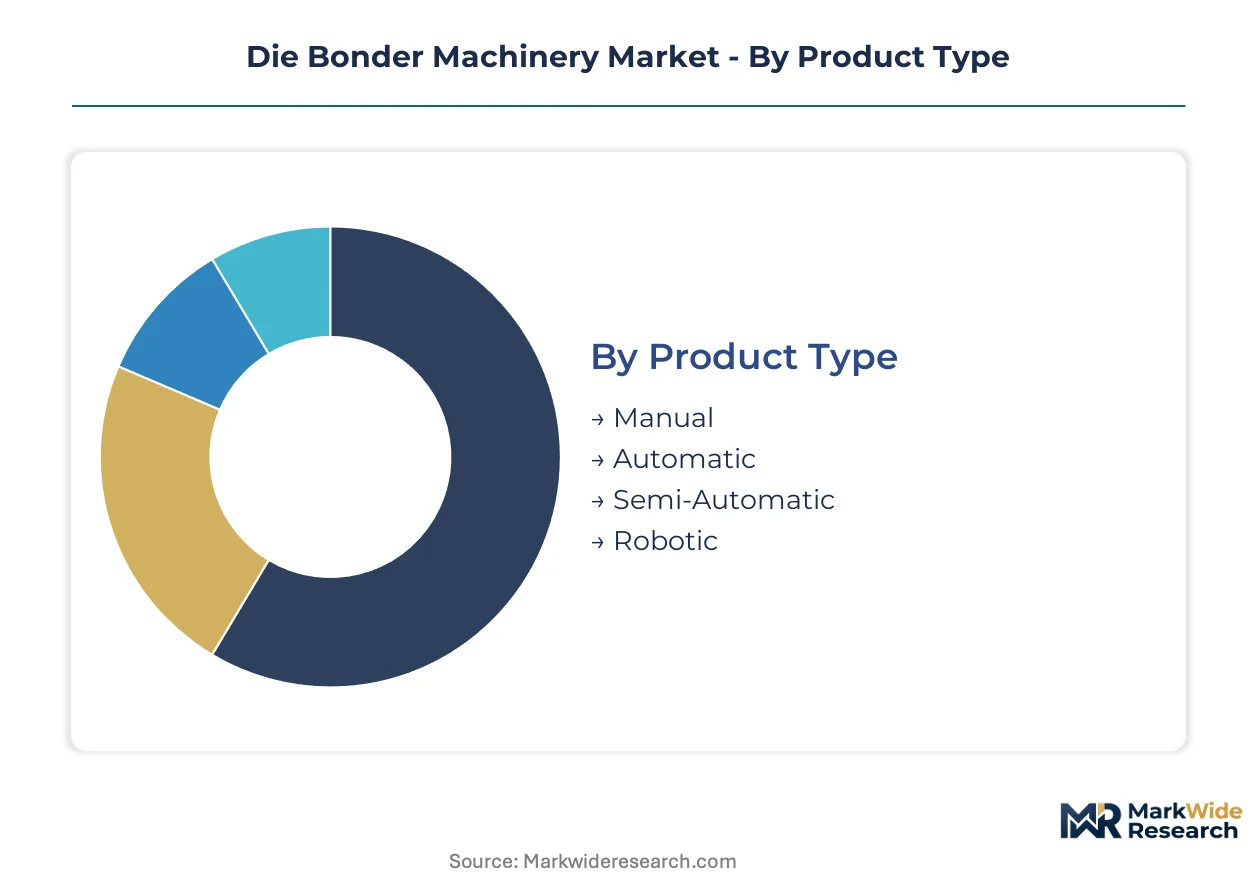
Die bonder machinery segmentation reveals how placement accuracy requirements and throughput demands split procurement patterns across packaging foundries. Equipment specifications diverge sharply between high-volume memory manufacturers and precision-oriented photonics assemblers.
Product Type:
Cost tier separates buyers most decisively in this category, with labor economics and floor space constraints driving the selection logic.
- Automatic:Systems achieve placement accuracy below 10 micrometers at throughput exceeding 15,000 units per hour. OSAT facilities in Taiwan and South Korea deploy these platforms for HBM stacking where yield consistency determines total cost of ownership.
- Manual:Benchtop units serve prototype development and specialty device validation where engineering oversight outweighs speed requirements. R&D labs at European automotive semiconductor fabs retain manual bonders for AEC-Q100 qualification cycles.
- Semi-Automatic:Hybrid platforms blend operator oversight with programmable motion stages for mid-volume production.
- Robotic:Fully autonomous cells integrate vision-guided pick-and-place with adaptive force control for flexible manufacturing.
Volume sits with Automatic; growth tilts toward Robotic.
Technology:
Application thermal budget dictates technology selection, with memory stacking constraints pulling investment away from conventional methods.
- Thermal:Thermosonic and thermal compression methods dominate legacy wire bonding and flip-chip attachment. Samsung and SK Hynix packaging divisions are transitioning 70% of new HBM4 capacity toward thermal compression with non-conductive film interposers.
- Eutectic:Flux-free bonding platforms attach silicon carbide dies to direct-bonded copper substrates. Automotive traction inverter manufacturers specify these systems for power module electrification.
- Laser:Localized heating minimizes thermal stress during 12-high and 16-high die stacks.
- Ultrasonic:Vibration-assisted bonding suits dissimilar material interfaces in MEMS packaging.
Eutectic commands the steepest expansion trajectory as silicon carbide packaging scales; Thermal retains installed base dominance.
End User:
Customer certification requirements create the primary dividing line, with automotive qualification timelines freezing equipment decisions for 18-24 months.
- Electronics:Consumer electronics packaging foundries drive the highest absolute equipment throughput. Smartphone and wearable manufacturers in East Asia specify automatic bonders for high-volume substrate assembly.
- Automotive:AEC-Q100 and industrial JEDEC standards mandate traceable process control. European fabs embed CSRD disclosure criteria into procurement specifications alongside technical requirements.
- Aerospace:MIL-STD reliability requirements dictate extended burn-in and documentation protocols.
- Telecommunications:5G base station and optical transceiver production pulls sub-micron placement accuracy for photonics coupling.
Electronics absorbs the greatest unit volume; Aerospace claims the highest average selling prices.
Application:
Placement precision requirements stratify this category, with microelectronics and photonics demanding accuracy thresholds unavailable to power device platforms.
- Microelectronics:Logic die attachment to organic substrates and interposers requires sub-5 micrometer placement for advanced node production. Taiwan packaging houses are expanding capacity to serve chiplet-based processor architectures.
- Power Devices:Silicon and silicon carbide die bonding prioritizes thermal interface integrity over placement precision. Eutectic platforms with specialized flux-free processes serve this segment.
- MEMS:Micro-electromechanical systems packaging combines die bonding with hermetic sealing requirements.
- Sensors:Environmental and inertial sensor assembly balances cost sensitivity with reliability specifications.
Power Devices anchor current shipment volumes; Microelectronics is climbing the fastest as chiplet adoption accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
High-purity ceramic bearing assemblies from Japanese and German suppliers anchor die bonder precision manufacturing, with regional procurement patterns reflecting proximity to advanced packaging clusters.
China
MIIT dual carbon mandates are filtering import eligibility for foreign die bonder suppliers while accelerating domestic equipment substitution in packaging foundries. GB standards on semiconductor equipment energy efficiency now govern cleanroom installation specifications. Yangtze River Delta packaging houses in Suzhou and Wuxi are expanding automatic die bonder procurement to support advanced node production.
South Korea
Memory manufacturers are procuring laser-assisted bonders to manage thermal budget constraints during 12-high and 16-high HBM die stacks. MFDS coordinates with METI-aligned standards for precision equipment vibration isolation. Seoul Capital Area packaging divisions in Icheon and Cheongju are transitioning majority HBM4 capacity toward thermal compression bonding platforms.
Taiwan
OSAT facilities are expanding automatic die bonder capacity to serve chiplet-based processor architectures with placement accuracy below 5 micrometers. Industrial Development Bureau incentives support cleanroom floor space expansion for advanced packaging. Hsinchu Science Park and Taichung Precision Machinery clusters are concentrating hybrid bonding equipment deployments.
Japan
METI coordinates JIS B 9908 vibration isolation standards that govern cleanroom installation specifications for sub-5 micrometer placement accuracy equipment. Foreign suppliers must demonstrate compliance through third-party testing at designated Japanese laboratories. Nagoya precision equipment builders and Tokyo metropolitan packaging research centers are absorbing capital allocation for thermal management subsystem development.
United States
Automotive AEC-Q100 qualification cycles are freezing equipment selection decisions for 18-24 months at power module electrification facilities. NHTSA and EPA fuel efficiency standards indirectly pull silicon carbide device packaging investments. Arizona semiconductor packaging greenfields and Texas automotive traction inverter manufacturing clusters are specifying eutectic bonding platforms with specialized flux-free processes.
Die Bonder Machinery Market Competitive Landscape
Global majors compete with regional champions across precision motion control and thermal management subsystems, creating a tiered structure where technology leadership and service proximity determine positioning. Equipment builders cluster into three strategic archetypes: vertically integrated Asian conglomerates controlling bonding heads and motion stages, European precision specialists dominating vibration isolation and sub-micron placement, and North American service-oriented vendors anchoring high-mix applications. Dominant competitive moves include strategic partnerships for linear motor stage supply security and portfolio diversification into equipment-as-a-service contracts with throughput guarantees.
Within the vertically integrated tier, ASM Pacific Technology exemplifies backward integration across critical subsystems. Among European precision specialists, Finetech GmbH & Co. KG and TRESKY GmbH occupy positions anchored by JIS-aligned certification capabilities. At the service-oriented end, Kulicke & Soffa Industries represents the archetype of regional infrastructure deployment for qualification-heavy automotive segments.
| Leading Market Players |
|---|
| ASM Pacific Technology |
| Kulicke & Soffa Industries |
| BE Semiconductor Industries |
| Shinkawa Ltd. |
| Palomar Technologies |
| TRESKY GmbH |
| West·Bond |
| MRSI Systems |
| Finetech GmbH & Co. KG |
| Others |
Pricing and Supply Chain Analysis
High-purity ceramic bearing price indices from Japanese suppliers cascade through die bonder manufacturing into three distinct procurement tiers, with motion control subsystem costs determining whether equipment falls into premium precision or standard throughput categories for OSAT buyers.
Pricing Analysis
Warranty and service bundling separates premium from standard offerings, with multiyear throughput guarantees commanding 25-40% price premiums over unbundled capital purchases. Three-tier pricing structure across premium, standard, and economy levels reflects placement accuracy certification tiers under JIS B 9908 and MIIT GB standards. Cost compression in economy-tier manual bonders is intensifying because Chinese domestic suppliers are absorbing local packaging foundry demand. Mid-tier OSATs in Southeast Asia exhibit highest price sensitivity, while European automotive fabs prioritize qualification traceability over unit cost.
Supply Chain Analysis
Refurbishment flows for legacy wire bonders and motion stage returns concentrate reverse logistics through Taiwan and South Korea, with rebuilt subsystems reentering supply chains at 60-70% of new component cost. Precision linear motor stages and air-bearing gantries draw from Japan and Germany, while thermal management subsystems source from domestic Chinese foundries. Single-source vulnerability around high-purity ceramic bearings from specific Nagoya-area suppliers creates chokepoint exposure. Distribution runs through direct OEM relationships with major OSATs rather than channel intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race where captive control over bonding heads and motion stages determines delivery reliability and margin capture against precision component scarcity.
For Market Incumbents: Acquire linear motor stage production capacity to secure supply timelines against 26-32 week lead time exposure from Japanese and German component suppliers. Expand service infrastructure in India to capture PLI scheme packaging greenfield deployments before domestic competitors establish qualification relationships. Defend against emerging Chinese equipment builders by accelerating JIS B 9908 certification pipelines that filter import eligibility. For New Entrants and Emerging Players: India's PLI scheme for semiconductor assembly opens a window for first-mover equipment deployments in Gujarat and Karnataka where incumbent service density remains thin. Target photonics die bonding applications requiring sub-micron placement accuracy, as this segment tolerates premium pricing and lacks established specialist vendors. Pursue equipment-as-a-service contracts with throughput guarantees to bypass balance sheet constraints at mid-tier Southeast Asian OSATs. For Investors and Strategic Acquirers: The window for entry favors precision motion control specialists with JIS-aligned certification capabilities and existing relationships with Japanese ceramic bearing suppliers. Long-term viability hinges on exposure to HBM stacking and silicon carbide power module growth vectors rather than legacy wire bonding replacement cycles. Monitor MIIT domestic substitution mandates and MFDS-METI coordination on vibration isolation standards as inflection indicators for foreign supplier market access.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Motion Stages | Captive supply of linear motor stages insulates against 26-32 week lead time bottlenecks from Japanese and German component suppliers. |
| Equipment-as-a-Service Launch | Per-die bonding fee structures unlock mid-tier OSAT demand in Malaysia and Vietnam where capex constraints dominate procurement decisions. |
| JIS B 9908 Certification Investment | Third-party testing at designated Japanese laboratories qualifies equipment for sub-5 micrometer placement accuracy segments. |
| India Greenfield Service Deployment | PLI scheme subsidies in Gujarat and Karnataka attract first-mover packaging capacity requiring localized qualification support. |
| Photonics Equipment Tier Development | Sub-micron placement accuracy for silicon photonics transceivers opens premium pricing tiers beyond memory and logic packaging. |
Research Methodology
Independent corroboration across packaging equipment OEMs, OSAT procurement directors, and precision component suppliers underwrites the qualitative findings in this study. Primary interviews with die bonder R&D heads, cleanroom facility engineers, and motion control subsystem vendors combined with secondary validation from SEC 10-K filings, METI equipment shipment statistics, and MIIT GB standard documentation. Bottom-up equipment deployment tallies triangulated against top-down packaging capacity expansion announcements across Taiwan, South Korea, and China.
Rate-of-change decomposition across the analysis window separates volume effects from mix shifts toward higher-accuracy platforms. Segmentation dimensions modeled include equipment automation level, bonding technology type, end-user certification requirements, and regional regulatory framework. CAGRs derive from equipment shipment trajectories correlated with packaging foundry capex cycles and memory manufacturer HBM stacking roadmaps. Forecast inputs incorporate thermal compression bonding adoption curves and silicon carbide power module electrification timelines.
The model assumes a particular technology adoption path; alternative pathways for hybrid bonding and 3D integration would alter the outlook if memory manufacturers accelerate beyond thermal compression methods. Forecasts reflect assumptions around JIS B 9908 certification penetration and MIIT domestic equipment substitution rates. Practitioners should monitor ceramic bearing supplier capacity expansion and MFDS-METI regulatory coordination for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Equipment
Global Semiconductor Etch Equipment Market
Semiconductor Equipment
APAC Die Attach Equipment Market
Semiconductor Equipment
Semiconductor Lithography Equipment Market
Semiconductor Equipment
Lithography Systems Market
Semiconductor Equipment
Thin Wafer Processing and Dicing Equipment Market
Semiconductor Equipment
Global Sputtering Equipment Market
Semiconductor Equipment
Thin Film Deposition Equipment Market
Semiconductor Equipment
Semiconductor POD Cleaner Market
Semiconductor Equipment
Unscrambling Machine Market
Semiconductor Equipment
High Current Ion Implanter Market
Semiconductor Equipment
300 Mm Front Opening Unified Pods (Foups) Market
Semiconductor Equipment
Plasma Etch System Market
Semiconductor Equipment
Automatic Dicing Saw Market
Semiconductor Equipment
Automatic Mounter Wafer Equipment Market
Semiconductor Equipment
Molecular Beam Epitaxy System Market
Semiconductor Equipment
Global Semiconductor Machinery Market