
 Reticle Pod Cleaning System Market | 2026-2036
Reticle Pod Cleaning System Market Size, Share, and Industry Trends Forecast 2026-2036
Reticle Pod Cleaning System Market Insights
Advanced logic foundries is bifurcating from memory fabs as the dominant buyer archetype for reticle pod cleaning systems, driven by EUV reticle complexity and stricter particle specifications. Entegris leverages its materials science heritage to anchor the premium pod services segment across multiple Asian manufacturing hubs. Brooks Automation sustains automation integration capabilities that differentiate its cleaning system offerings for high-volume fabs. Gudeng Precision dominates reticle pod manufacturing in Taiwan and extends this position into adjacent cleaning equipment services.
A reticle pod cleaning system removes particulate and molecular contaminants from photomask transport pods used in semiconductor lithography, typically achieving sub-0.1 micron particle removal through controlled chemical, ultrasonic, or plasma processes to prevent yield-destroying defects on wafers. Ultrasonic cleaners lead the product type landscape for standard contamination removal, while plasma cleaners command premium positioning for EUV-compatible pods where amorphous carbon and tin residue demand aggressive yet precise surface treatment. Smart Cleaning Systems represent the fastest-growing technology segment, integrating particle counters and AI-driven cycle optimization to reduce manual intervention in Class 1 cleanroom environments.
ISO 14644 cleanroom classification standards and Japan's METI semiconductor subsidies collectively shape equipment specifications and investment incentives for contamination control infrastructure. The EPA's National Emission Standards for Hazardous Air Pollutants and South Korea's K-Battery and K-Semiconductor Acts further tighten chemical handling and domestic supply chain requirements for cleaning system deployments. Stakeholders must monitor regulatory divergence between East Asian manufacturing incentives and Western environmental compliance frameworks when configuring regional service networks and equipment portfolios.
Market Dynamics
EUV lithography deployment at sub-7nm nodes is compressing particle tolerance thresholds for reticle pods, forcing fabs to upgrade from ultrasonic to plasma-based cleaning protocols and triggering capacity expansion across East Asian manufacturing clusters.
Growth Catalysts
- ISO 14644-1 Class 1 mandates:Stricter cleanroom classifications in Japan and South Korea are mandating automated pod handling systems that integrate directly with reticle cleaning infrastructure, eliminating manual contamination risks.
- EUV reticle complexity:Pellicle-less EUV masks accumulate amorphous carbon and tin residue requiring aggressive plasma cleaning cycles, expanding addressable equipment demand beyond traditional ultrasonic systems.
- Taiwan foundry expansion:TSMC and UMC are commissioning dedicated reticle pod cleaning facilities at Tainan and Taichung science parks to support 3nm and 2nm production ramps.
Market Restraints
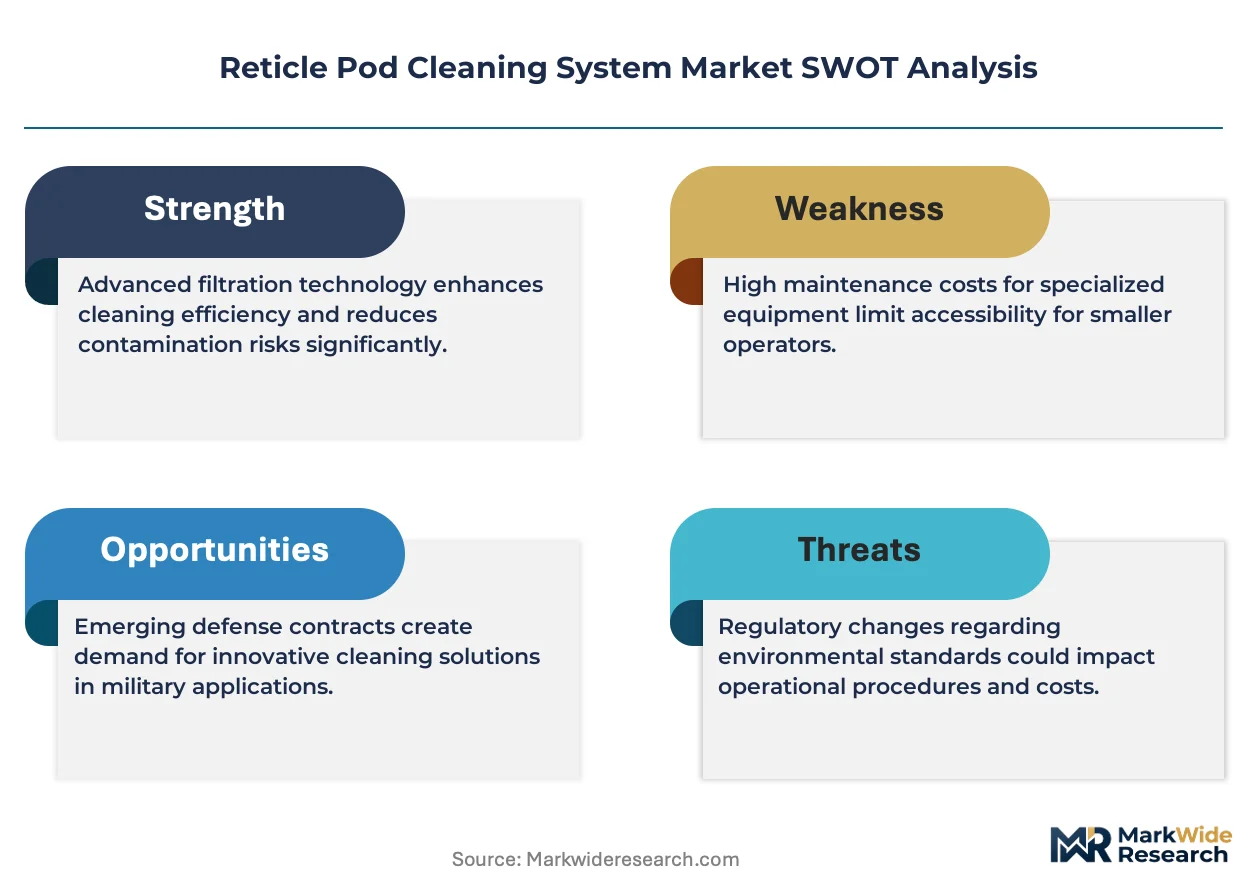
- Specialized chemical supply concentration:High-purity solvents and process gases for EUV-compatible cleaning originate from a limited supplier base in Germany and Japan, creating input cost volatility and allocation risk during demand surges.
- Plasma system technical limitations:Current atmospheric-pressure plasma cleaners struggle with throughput rates matching high-volume logic fab requirements, constraining deployment at memory facilities with faster reticle turnover.
- EPA NESHAP compliance friction:US-based equipment deployments face extended permitting timelines for solvent recovery systems, delaying installation schedules versus Asian regulatory pathways.
Strategic Opportunities
- India semiconductor manufacturing incentives:The country's PLI scheme for fabs and ATMP units creates first-mover positioning for cleaning system vendors as domestic pod infrastructure develops from near-zero base.
- AI-driven Smart Cleaning convergence:Integration of real-time particle metrology with machine learning cycle optimization enables predictive maintenance contracts that shift revenue from equipment sales to recurring service streams.
- Service unbundling from pod OEMs:Third-party cleaning service providers can capture maintenance contracts from captive operations at mature-node fabs seeking cost reduction without capital replacement.
Industry Challenges
- Cross-disciplinary talent scarcity:Equipment engineering teams require simultaneous expertise in vacuum systems, plasma physics, and semiconductor contamination control, with qualified candidates concentrated in Japan and Taiwan.
- Legacy ultrasonic system integration:Retrofitting Smart Cleaning sensors and automated handling into existing Class 100 cleanroom footprints demands structural modifications that disrupt production continuity.
- EUV pod material certification timelines:New ceramic and polymer formulations for advanced pods require 18-24 month qualification cycles with ASML and individual fabs before cleaning process validation can commence.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Reticle Pod Cleaning System Market |
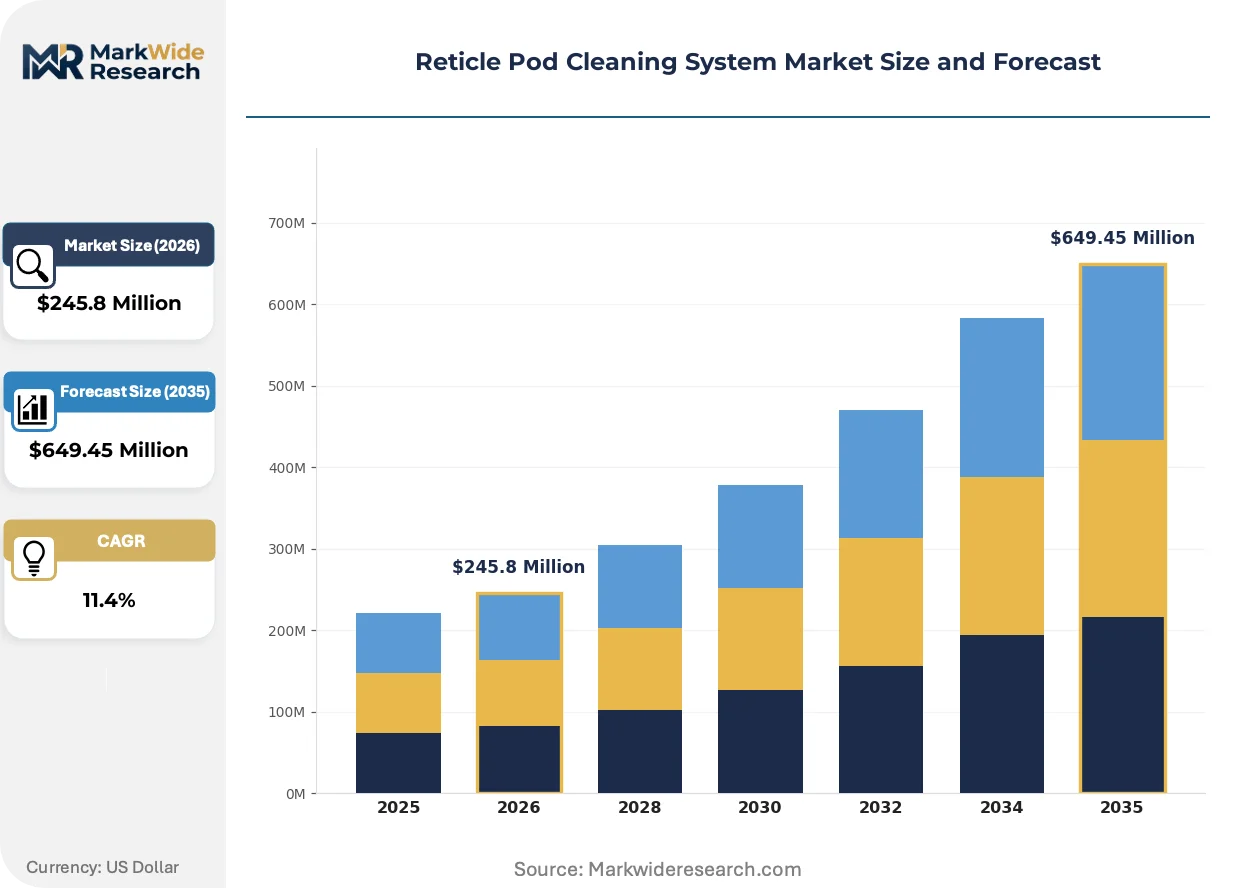
| Market Size in 2026 | $245.8 Million |
| Market Size in 2035 | $649.45 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ultrasonic Cleaners, Chemical Cleaners, Plasma Cleaners, Dry Cleaning Systems End User: Semiconductor Manufacturers, Laboratory Personnel, Research Institutions, Aerospace Industries Technology: Automated Cleaning Units, Manual Cleaning Tools, Hybrid Cleaning Devices, Smart Cleaning Systems Application: Surface Preparation, Equipment Maintenance, Quality Control, Contamination Removal |
| Companies Covered | Brooks Automation, Hugle Electronics, DEVICEENG, AP&S International, Entegris, Gudeng Precision, Chung King Enterprise, Pozzetta, Microtome, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Reticle Pod Cleaning System Market Trends and Innovations
Equipment architecture is bifurcating between high-throughput standard pod cleaners and precision EUV-specific systems, with software-defined automation emerging as the primary differentiation vector beyond base hardware specifications.
Atmospheric-pressure plasma cleaning is fragmenting the technology landscape for EUV reticle pod maintenance. This surface treatment method removes carbonaceous and metallic residues without vacuum chamber constraints. Leading logic foundries in Taiwan and South Korea are adopting hybrid ultrasonic-plasma configurations for their EUV-dedicated lines. The technology is fragmenting vendor specialization, separating precision surface engineering specialists from traditional wet-process equipment manufacturers.
Japan's METI semiconductor revitalization subsidies are redirecting domestic equipment investment toward contamination control infrastructure. The policy framework ties capital grants to ISO 14644-1 compliance upgrades and local supply chain localization targets. Memory fabs in Yokkaichi and Kitakami are prioritizing automated pod cleaning systems that qualify for these incentives, accelerating replacement of manual cleaning stations.
Foundry procurement teams are consolidating vendor relationships around integrated pod lifecycle management contracts. Equipment suppliers now compete on total cost of ownership metrics spanning cleaning, inspection, and predictive maintenance rather than capital expenditure alone. This behavioral shift is most pronounced at Samsung and TSMC, where multi-year service agreements are displacing transactional equipment purchases for non-EUV pod categories.
Reticle Pod Cleaning System Market Segmentation
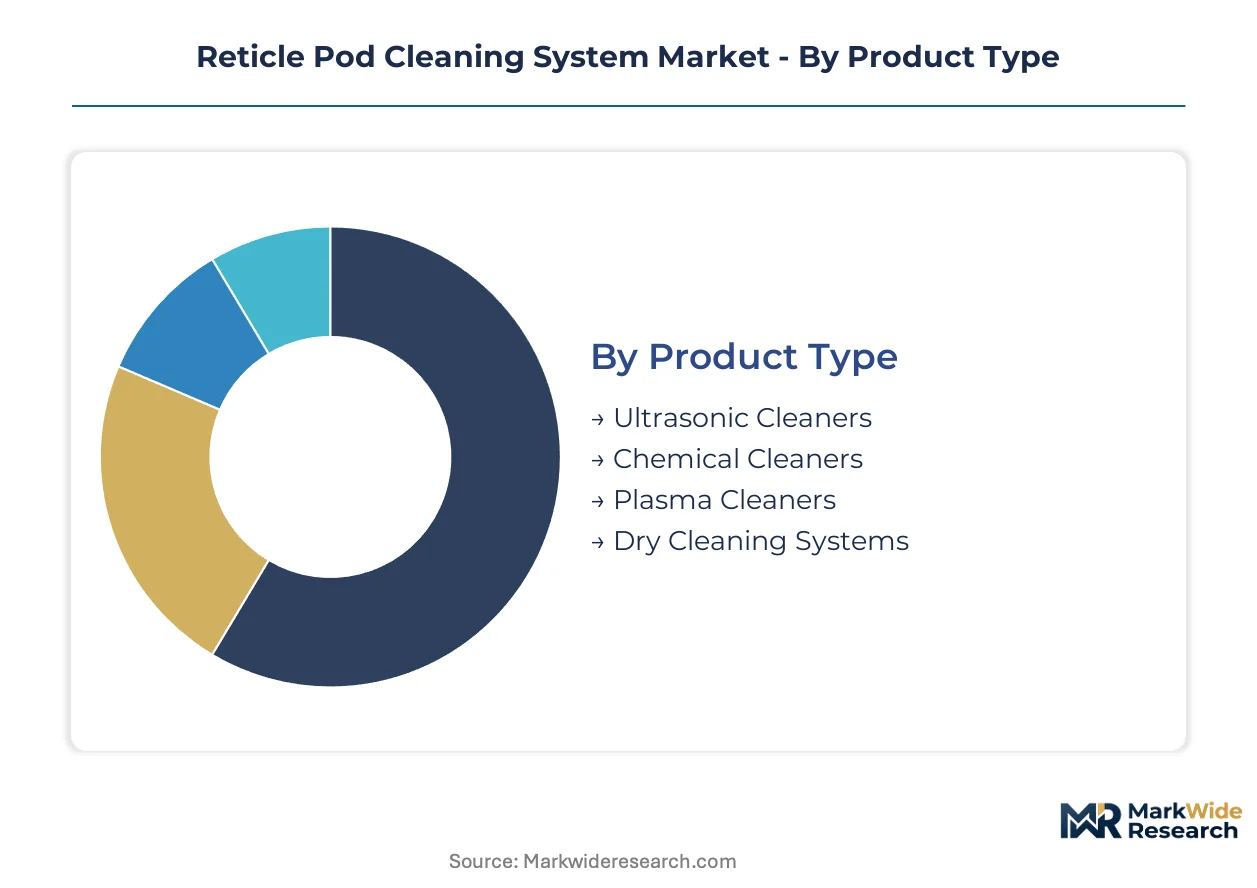
Segmentation in reticle pod cleaning systems tracks how EUV lithography complexity splits procurement patterns between precision-critical logic foundries and cost-sensitive mature-node operations. Equipment specifications diverge sharply across contamination tolerance thresholds, automation requirements, and regional regulatory compliance mandates.
Product Type:
Ultrasonic cleaners dominate domestic supply chains in Taiwan and South Korea, while plasma systems concentrate in export-led EUV tool deployments to European and North American research facilities.
- Ultrasonic Cleaners:These systems deploy high-frequency sound waves in aqueous or solvent baths to dislodge particulate contaminants from standard reticle pods. Demand concentrates at memory fabs in Yokkaichi and Kitakami where throughput economics favor established wet-process protocols over plasma precision.
- Plasma Cleaners:Atmospheric-pressure plasma systems remove amorphous carbon and tin residue from EUV reticle pods through ionized gas surface treatment. Taiwan's Tainan and Taichung science parks anchor procurement as TSMC and UMC ramp 3nm and 2nm production requiring pellicle-less mask maintenance.
- Chemical Cleaners:Solvent-based systems target molecular contamination removal through controlled chemical reactions in closed-loop configurations.
- Dry Cleaning Systems:Cryogenic and CO2 snow systems address water-sensitive pod materials without liquid exposure risks.
Ultrasonic cleaners command the established base. The steepest expansion runs through plasma cleaners.
End User:
Procurement scale separates high-volume semiconductor manufacturers from fragmented laboratory and research buyers with irregular equipment refresh cycles.
- Semiconductor Manufacturers:Logic foundries and memory fabs in East Asia drive equipment standardization through multi-year service contracts. Samsung and TSMC procurement teams now consolidate vendor relationships around total cost of ownership metrics spanning cleaning, inspection, and predictive maintenance.
- Research Institutions:Universities and national laboratories in Germany and the United States purchase lower-throughput systems for process development and materials characterization. Funding cycles and grant dependencies create lumpy demand patterns distinct from commercial fab procurement.
- Laboratory Personnel:Quality assurance and metrology labs within fab complexes require portable or benchtop cleaning units for spot maintenance.
- Aerospace Industries:Satellite and precision optics manufacturers adapt semiconductor-grade contamination control for non-standard substrate dimensions.
Semiconductor manufacturers absorb the dominant equipment volume. Research institutions present the most volatile demand profile.
Technology:
Automation intensity correlates with cleanroom classification stringency, separating Class 1 compliant automated systems from manual tools in lower-grade environments.
- Smart Cleaning Systems:AI-driven platforms integrate real-time particle metrology with machine learning cycle optimization to reduce manual intervention. South Korea's K-Semiconductor Act incentives accelerate deployment at Samsung's Pyeongtaek complex where predictive maintenance contracts displace transactional equipment purchases.
- Automated Cleaning Units:Robotic handling systems eliminate human contamination risks in ISO 14644-1 Class 1 environments. Japan's METI subsidies tie capital grants to automation upgrades at Yokkaichi memory facilities replacing manual cleaning stations.
- Hybrid Cleaning Devices:Configurable systems combine ultrasonic and plasma modalities for fabs transitioning between DUV and EUV production lines.
- Manual Cleaning Tools:Low-capital options persist at mature-node facilities and aftermarket service providers seeking cost reduction without full system replacement.
Automated cleaning units hold the installed base. Smart cleaning systems are climbing the fastest.
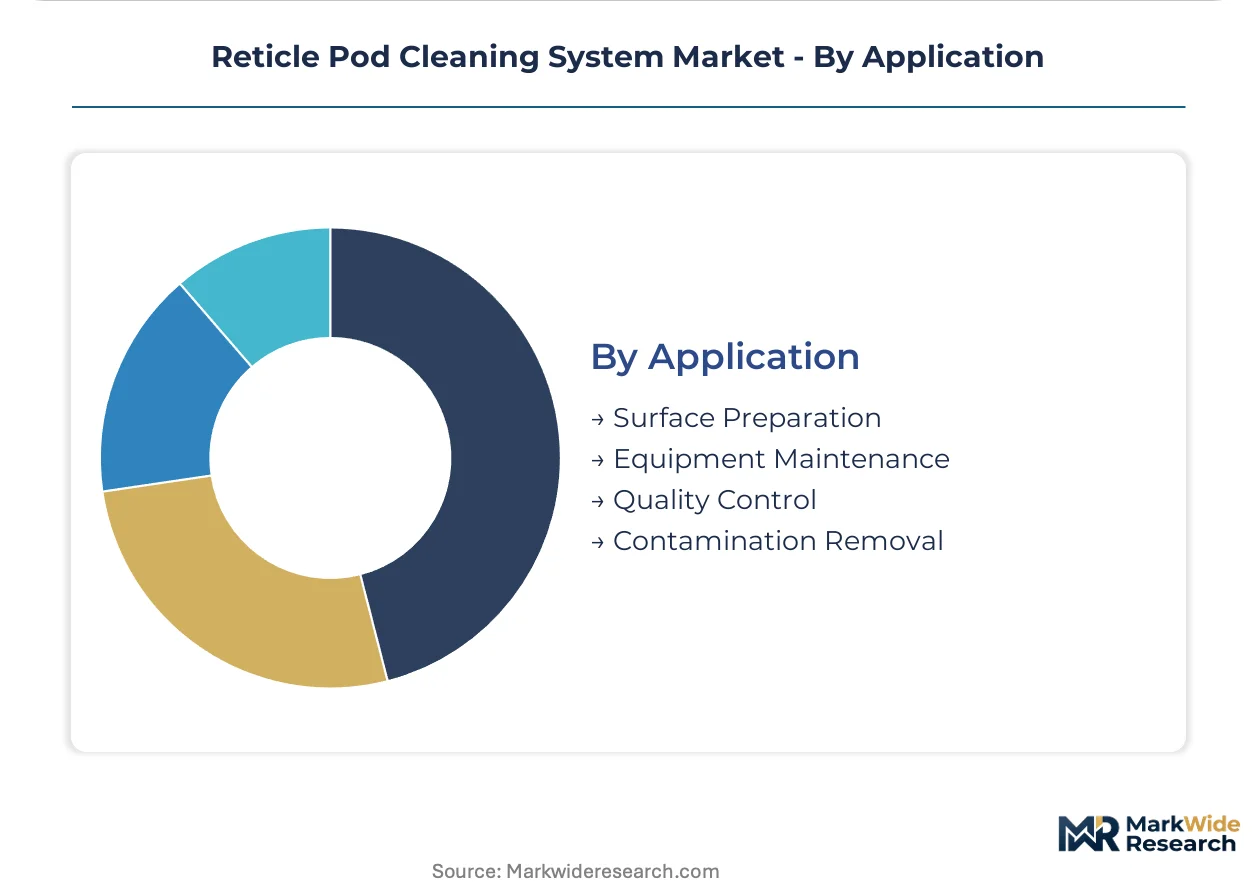
Application:
Process criticality separates preventive surface preparation from reactive contamination removal, with quality control applications commanding premium metrology integration.
- Contamination Removal:The core function addresses particulate and molecular residue elimination from reticle pod interior surfaces. Taiwan foundry clusters prioritize this application category as EUV deployment compresses particle tolerance thresholds below 0.1 micron specifications.
- Quality Control:Integrated inspection and cleaning workflows verify pod cleanliness before lithography tool loading. South Korea's MFDS-equivalent semiconductor standards and Japan's METI compliance frameworks mandate documentation trails for high-volume production environments.
- Surface Preparation:Pre-conditioning treatments optimize pod surfaces for specific reticle materials and pellicle configurations.
- Equipment Maintenance:Cleaning system self-maintenance and component refurbishment extends operational life in capital-constrained facilities.
Contamination removal anchors functional demand. Quality control applications are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Advanced logic foundries in Taiwan and South Korea command the dominant procurement volume for reticle pod cleaning systems, while Japan's memory fabs and emerging Indian facilities reshape geographic demand distribution.
Taiwan
TSMC and UMC drive equipment demand through dedicated reticle pod cleaning facilities at Tainan and Taichung science parks supporting 3nm and 2nm production ramps. The National Development Council's semiconductor advancement programs subsidize contamination control infrastructure investments. Hsinchu Science Park anchors the highest concentration of EUV-compatible cleaning system deployments in East Asia.
South Korea
Samsung's Pyeongtaek complex and SK Hynix expand plasma cleaning capacity for EUV reticle maintenance as sub-7nm logic production scales. The K-Semiconductor Act directs tax incentives toward automated pod handling systems meeting Class 1 cleanroom specifications. Yongin and Icheon semiconductor clusters concentrate hybrid ultrasonic-plasma cleaning equipment procurement.
Japan
Memory fabs in Yokkaichi and Kitakami prioritize automated cleaning systems replacing manual stations under METI semiconductor revitalization subsidies. Stricter ISO 14644-1 compliance mandates accelerate equipment refresh cycles at legacy facilities. Hiroshima and Kumamoto production sites integrate predictive maintenance contracts for mature-node pod cleaning operations.
United States
Research institutions in California and Texas purchase lower-throughput systems for EUV process development and materials characterization. EPA NESHAP compliance extends permitting timelines for solvent recovery systems versus Asian regulatory pathways. Albany Nanotech Complex and Sandia National Laboratories anchor non-commercial demand for precision cleaning equipment.
India
The PLI scheme for fabs and ATMP units creates first-mover positioning opportunities as domestic pod infrastructure develops from near-zero base. State semiconductor policies in Gujarat and Karnataka designate specialized zones for contamination control equipment deployment. Dholera and Greater Noida emerging fab sites require greenfield cleaning system installations without legacy retrofit constraints.
Reticle Pod Cleaning System Market Competitive Landscape
Player mix skews toward materials science specialists and automation integrators competing across differentiated technology tiers. Consolidation concentrates around pod OEMs extending into adjacent cleaning services and independent equipment vendors serving third-party maintenance contracts. Strategic archetypes separate premium EUV-compatible system providers from high-throughput standard pod cleaners and emerging smart automation platforms. Competitive moves center on multi-year service agreement structures displacing transactional equipment sales and geographic expansion into India's developing semiconductor infrastructure.
Within the premium-tier materials science segment, Entegris anchors contamination control heritage across multiple Asian manufacturing hubs. Brooks Automation exemplifies automation integration capabilities for high-volume fab deployments. Gudeng Precision occupies a position bridging reticle pod manufacturing dominance in Taiwan with extension into adjacent cleaning equipment services. These three companies represent the strategic spectrum from materials specialization through robotic systems integration to regional manufacturing scale.
| Leading Market Players |
|---|
| Brooks Automation |
| Hugle Electronics |
| DEVICEENG |
| AP&S International |
| Entegris |
| Gudeng Precision |
| Chung King Enterprise |
| Pozzetta |
| Microtome |
| Others |
Pricing and Supply Chain Analysis
18-to-24-month EUV pod material certification cycles concentrate pricing power with German and Japanese high-purity solvent suppliers, compressing margins for system integrators while amplifying cost pass-through leverage at the specialty chemical tier.
Pricing Analysis
Ultrasonic-to-plasma technology-generation pricing gaps exceed three-to-one multiples, with atmospheric-pressure plasma systems commanding premium positioning for EUV-compatible residue removal. Three-tier pricing structure across premium EUV-specific, standard automated, and economy manual systems stratifies procurement budgets, with ISO 14644-1 Class 1 certification tier and after-sales predictive maintenance bundling as primary differentiation drivers. Cost compression in ultrasonic tiers is intensifying because foundry procurement teams now consolidate around total cost of ownership metrics. Mature-node memory fabs exhibit highest price sensitivity; EUV-dedicated logic foundries demonstrate lowest.
Supply Chain Analysis
Strait of Malacca transit vulnerability underwrites logistics risk for high-purity solvent shipments originating from German and Japanese specialty chemical producers. Manufacturing concentration in Taiwan, South Korea, and Japan draws from ceramic pod substrates, ionized gas delivery systems, and AI-enabled particle metrology sensors as critical component dependencies. Single-source vulnerability in atmospheric-pressure plasma generator assemblies creates allocation exposure during demand surges. Distribution runs through fab-integrated service contracts and third-party maintenance providers at mature facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Predictive maintenance service contracts are expanding faster than hardware shipments as foundry procurement shifts from capital expenditure to recurring operational expenditure frameworks.
For Market Incumbents: Compound defensive positioning through backward integration into high-purity solvent recycling systems and captive certification laboratory capacity in Taiwan and South Korea. Threat from third-party cleaning service unbundling demands channel control over pod lifecycle management contracts. Priority lever: automated handling system R&D to compress plasma cleaner throughput gaps versus memory fab requirements. For New Entrants and Emerging Players: ISO 14644-1 fast-track certification partnerships with Japanese METI-subsidized facilities unlock white-space positioning. Most penetrable target: India's greenfield fab infrastructure under PLI scheme incentives. Specific angle: portable benchtop cleaning units for laboratory personnel and quality assurance spot maintenance applications. For Investors and Strategic Acquirers: Long-term, this sits as a contamination control infrastructure play because EUV lithography deployment creates irreversible precision maintenance demand across successive process nodes. Acquisition target archetype: AI-driven Smart Cleaning platform developers with real-time particle metrology integration. Signal to watch: hybrid ultrasonic-plasma system adoption rates at Samsung and TSMC as inflection indicator for technology transition velocity.| Strategic Initiative | Industry Significance |
|---|---|
| AI-Driven Smart Cleaning Platform Development | Machine learning cycle optimization at Samsung Pyeongtaek displaces transactional equipment purchases with recurring service revenue. |
| Backward Integration into Solvent Recycling Systems | In-house recovery infrastructure reduces EPA NESHAP compliance friction and input cost volatility for US-based deployments. |
| ISO 14644-1 Certification Fast-Track Partnerships | METI subsidy qualification accelerates equipment refresh cycles at Yokkaichi memory facilities replacing manual cleaning stations. |
| India Greenfield Market Entry | Dholera and Greater Noida emerging fab sites require contamination control infrastructure without legacy retrofit constraints. |
| Predictive Maintenance Contract Expansion | Multi-year service agreements at TSMC and UMC consolidate vendor relationships around total cost of ownership metrics. |
Research Methodology
Operator-level perspectives from fab engineering directors, contamination control specialists, equipment procurement managers, and aftermarket service heads anchored the qualitative base. Primary interview insights combined with secondary validation from SEMI equipment market databases, EPA NESHAP regulatory filings, Japan METI subsidy disclosure records, and South Korea K-Semiconductor Act implementation reports. Bottom-up equipment shipment tracking and top-down fab capital expenditure analysis enabled triangulation across data sources.
Sensitivity analysis on EUV deployment velocity and plasma cleaner throughput improvement rates shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include cleaning technology type, automation intensity tier, end-user facility category, and regional regulatory compliance cluster. CAGRs derived from equipment shipment run-rates, fab capacity expansion schedules, and service contract value migration patterns. Industry-specific inputs incorporated ASML lithography tool delivery timelines and ISO 14644-1 adoption curves.
Decision-makers should treat outputs as directional under sustained EUV lithography expansion and stable East Asian manufacturing incentive frameworks; material deviation in semiconductor capital expenditure cycles or regulatory subsidy discontinuation would warrant model refresh. Practitioners should keep alternative scenarios live as atmospheric-pressure plasma throughput limitations and specialized chemical supply concentration evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Equipment
Dry Reactor Market
Semiconductor Equipment
Global Semiconductor Front-End Equipment Market
Semiconductor Equipment
300 Mm Front Opening Unified Pods (Foups) Market
Semiconductor Equipment
Acid Filling and Leveling Machine Market
Semiconductor Equipment
Unscrambling Machine Market
Semiconductor Equipment
Vacuum Coating Equipment Market
Semiconductor Equipment
Die Bonder Equipment Market
Semiconductor Equipment
Cathode Stripping Machines Market
Semiconductor Equipment
Semiconductor Laser Equipment Market
Semiconductor Equipment
150mm Probe Station Market
Semiconductor Equipment
United States Chip Mounter Market
Semiconductor Equipment
X-Ray Lithography Equipment Market
Semiconductor Equipment
Thin Film Deposition Equipment Market
Semiconductor Equipment
Vacuum Ovens Market
Semiconductor Equipment
North America Semiconductor Etch Equipment Market
Semiconductor Equipment
Global SMT Placement Equipment Market