
 Asia-Pacific Aligner Sheet Market | 2026-2036
Asia-Pacific Aligner Sheet Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Aligner Sheet Market Outlook
A capital-intensity divergence between multinational tooling networks and regional sheet converters is rotating competitive advantage toward firms with captive polymer extrusion. Align Technology leverages its proprietary thermoplastic formulation to sustain margin capture across direct-to-practitioner channels in Australia and South Korea. Angelalign Technology Inc. anchors its position through deep orthodontic software integration and domestic manufacturing scale within China. MAXFLEX CO, Ltd competes on specialized polyurethane sheet grades optimized for shorter Asian arch forms.
Asia-Pacific aligner sheets are multi-layer thermoplastic appliances, typically 0.5–1.0 mm in thickness, engineered from medical-grade polyurethane or polyethylene terephthalate glycol (PETG) substrates through precision extrusion and die-cutting processes, designed to deliver programmed orthodontic force over sequential wear intervals. Bioplastic formulations now lead material innovation as practitioners and regulators push for reduced petroleum dependence in disposable dental devices. Teeth alignment applications dominate volume, though retention and cosmetic treatment segments are expanding fastest as post-treatment protocols lengthen and adult aesthetic demand rises across urban India and Vietnam.
China's NMPA medical device classification rules, Japan's PMDA quality management system requirements, and India's CDSCO import registration mandates collectively shape product standards and market access timelines for foreign sheet suppliers. The EU MDR's extraterritorial influence on CE-marked reference products further complicates regulatory alignment for manufacturers serving dual export-domestic strategies. Stakeholders must monitor evolving biocompatibility testing protocols and polymer traceability requirements as the region's national regulators harmonize toward stricter material disclosure frameworks.
Market Dynamics
Material compliance divergence between China's NMPA medical device classification pathways and Japan's PMDA quality management systems is fragmenting supply access for foreign sheet converters across the Asia-Pacific region.
Growth Catalysts
- Bioplastic formulation mandates:China's dual carbon goals and provincial green procurement policies are accelerating medical-grade polyurethane substitution with bio-based PETG alternatives in tier-one city dental clinics.
- Adult aesthetic demand concentration:Urban India and Vietnam are witnessing pronounced clear aligner preference shifts among professionals aged 25-40, compressing traditional braces adoption timelines in metropolitan dental corridors.
- Orthodontic software integration:Deep CAD/CAM workflow embedding is reducing chairside adjustment frequency and enabling direct-to-practitioner sheet supply models across South Korea and Australia.
Market Restraints
- Medical-grade polymer supply concentration:Specialty thermoplastic polyurethane feedstock production clusters heavily in East Asian chemical corridors, exposing sheet converters to single-source disruption risk.
- NMPA registration timeline friction:China's extended medical device classification review periods for imported aligner materials delay market entry by 18-24 months versus domestic equivalents.
- Direct-to-consumer aligner substitution:Remote orthodontic platforms utilizing generic thermoplastic sheets are compressing premium branded sheet pricing power in Australia's deregulated dental retail channels.
Strategic Opportunities
- Retention protocol extension:Post-treatment maintenance regimens are lengthening across Japan's aging demographic, creating sustained demand for lower-force retention-grade sheet variants.
- Indonesia and Philippines penetration gaps:Orthodontist density in Southeast Asian secondary cities remains below saturation thresholds, offering first-mover positioning for localized sheet distribution networks.
- CDSCO streamlined registration:India's 2023 medical device rules amendment is compressing import approval timelines for EU MDR-harmonized sheet products, accelerating foreign supplier access to Mumbai and Delhi dental clusters.
Industry Challenges
- Polymer traceability system implementation:Batch-level material genealogy documentation requirements under tightening PMDA and NMPA frameworks are forcing sheet converters to reconfigure extrusion line data architecture.
- Biocompatibility testing protocol divergence:Cytotoxicity and sensitization assay standards differ materially between China's GB/T specifications and Japan's JIS frameworks, necessitating dual certification investments.
- Orthodontic technician training scarcity:CAD/CAM case design specialization remains concentrated in Shanghai, Seoul, and Sydney, constraining treatment planning throughput in emerging Southeast Asian markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Aligner Sheet Market |
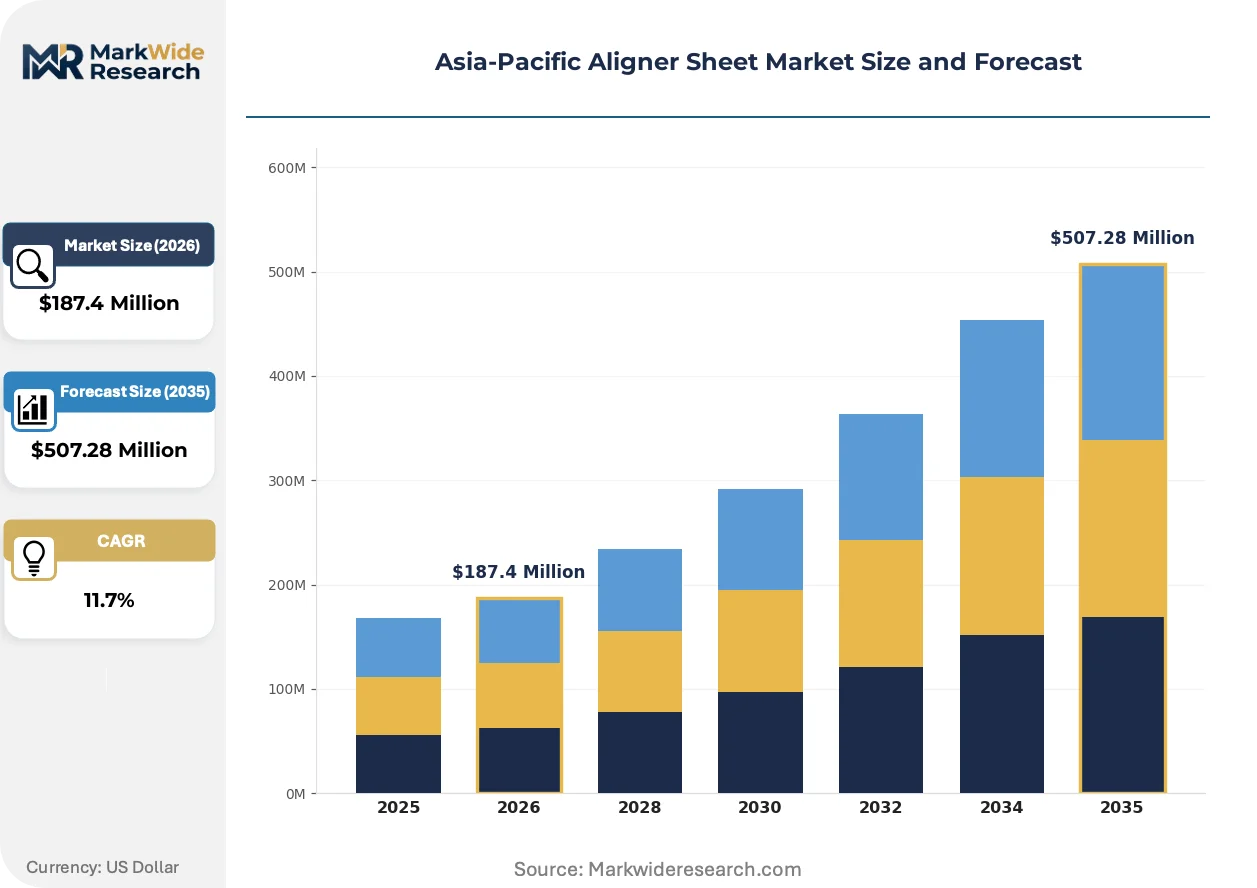
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $507.28 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bioplastic, Polyurethane, Polyethylene, Others End User: Orthodontists, Dentists, Clinics, Home Users Application: Teeth Alignment, Retention, Cosmetic Treatment, Preventive Care Distribution Channel: Online, Offline, Dental Supply Stores, Direct Sales |
| Companies Covered | Ormco Corporation, Institut Straumann AG, MAXFLEX CO, Ltd, Whitesmile Clear, Dentsply Sirona, Align Technology, Inc., 3M, Vedia Solutions, Angelalign Technology Inc., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Aligner Sheet Market Strategic Shifts
Multi-layer thermoplastic engineering and regulatory disclosure frameworks are converging to reshape competitive differentiation across Asia-Pacific aligner sheet supply chains.
Precision co-extrusion technology is miniaturizing layer thickness control to sub-50-micron tolerances, enabling programmed force decay curves across sequential wear intervals. Premium dental clinics in Tokyo and Singapore are adopting these advanced sheet grades for complex malocclusion cases. The technology is miniaturizing production lot sizes and compressing minimum order quantities for regional converters serving mid-tier orthodontic practices.
Japan's PMDA quality management system requirements are tightening polymer additive disclosure thresholds for imported medical devices, forcing foreign sheet suppliers to restructure material safety data file architectures. Manufacturers serving dual China-Japan export strategies face compliance cost bifurcation as NMPA and PMDA documentation formats diverge. Australian TGA-registered reference products are gaining preference among Southeast Asian distributors seeking regulatory pre-approval leverage.
Direct procurement relationships between dental clinic chains and sheet converters are displacing traditional distributor intermediaries across South Korea's consolidated orthodontic market. Large multi-location practices in Seoul and Busan are negotiating volume-based thermoplastic supply contracts with extrusion specialists, compressing margin capture for legacy dental product distributors. Channel consolidation is most pronounced where clinic networks exceed 50 locations and maintain in-house treatment planning capabilities.
Asia-Pacific Aligner Sheet Market Segmentation
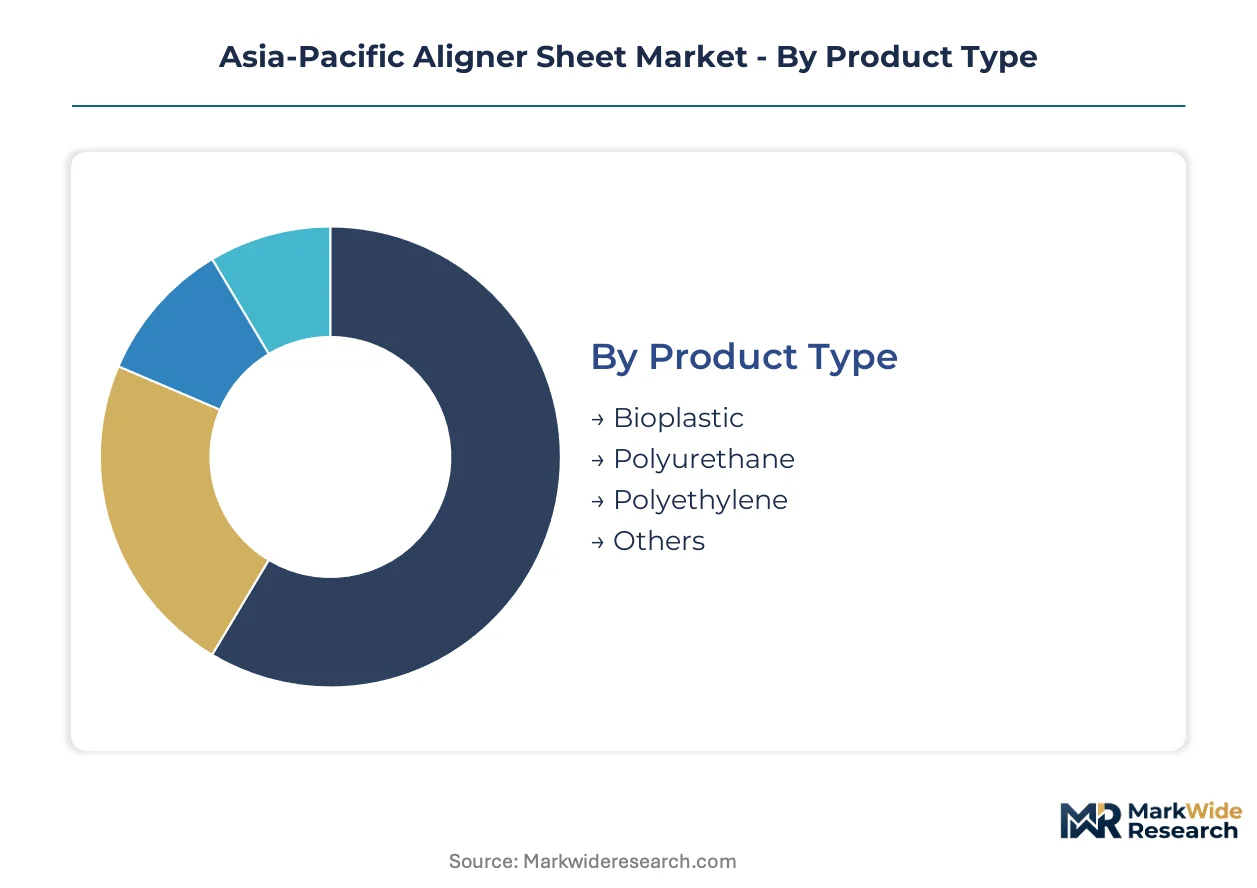
Aligner sheet procurement patterns diverge sharply across Asia-Pacific dental channels. Material specifications, end-user technical sophistication, and regulatory exposure create distinct segment economics that reshape supplier prioritization.
Product Type:
Channel mix varies by polymer chemistry—bioplastic formulations flow through premium clinic-direct networks, while conventional thermoplastics dominate distributor-led supply chains.
- Bioplastic:Medical-grade polylactic acid and bio-based PETG formulations deliver reduced petroleum dependence for sustainability-focused practitioners. Tier-one city dental clinics in Shanghai and Tokyo are mandating bio-based alternatives under corporate ESG procurement policies. Supply constraints in specialty resin production limit volume scaling.
- Polyurethane:Thermoplastic polyurethane substrates remain the clinical standard for programmed force delivery across sequential wear intervals. Australia's TGA-registered practitioners and South Korea's orthodontic chains specify polyurethane grades for complex malocclusion cases. MAXFLEX CO, Ltd has optimized shorter-arch variants for Asian anatomical profiles.
- Polyethylene:Lower-cost polyethylene sheet variants serve price-sensitive retention and preventive applications.
- Others:Experimental copolymer blends and composite laminates occupy niche R&D channels.
By volume, polyurethane leads. By growth pace, bioplastic is gaining share fastest.
End User:
Cost tiers stratify sharply—orthodontists command premium sheet grades while home users access commoditized alternatives through direct-to-consumer platforms.
- Orthodontists:Specialist practitioners with CAD/CAM treatment planning capabilities source precision co-extruded sheets through direct manufacturer relationships. Seoul and Sydney orthodontic networks negotiate volume contracts bypassing traditional distributors.
- Dentists:General dental practitioners in India's metropolitan corridors represent expanding prescription volume for clear aligner therapy.
- Clinics:Multi-location clinic chains in South Korea and Australia are consolidating procurement through centralized thermoplastic supply agreements.
- Home Users:Remote orthodontic platforms utilizing generic thermoplastic sheets are compressing branded pricing power in Australia's deregulated channels.
Orthodontists generate premium margin capture. Home users are expanding most quickly.
Application:
Maturity gradients separate established teeth alignment protocols from emerging cosmetic and retention segments with elongated treatment horizons.
- Teeth Alignment:Corrective malocclusion therapy constitutes the foundational volume driver across Asia-Pacific orthodontic practices. China's tier-one cities and India's metropolitan dental corridors concentrate demand for active treatment protocols.
- Retention:Post-treatment maintenance regimens are lengthening across Japan's aging demographic, creating sustained demand for lower-force retention-grade variants.
- Cosmetic Treatment:Adult aesthetic demand among professionals aged 25-40 in urban Vietnam and India is compressing traditional braces adoption timelines.
- Preventive Care:Early intervention protocols for adolescent patients remain underdeveloped outside Australia and Japan.
Teeth alignment dominates current volume. Retention protocols show the steepest expansion trajectory.
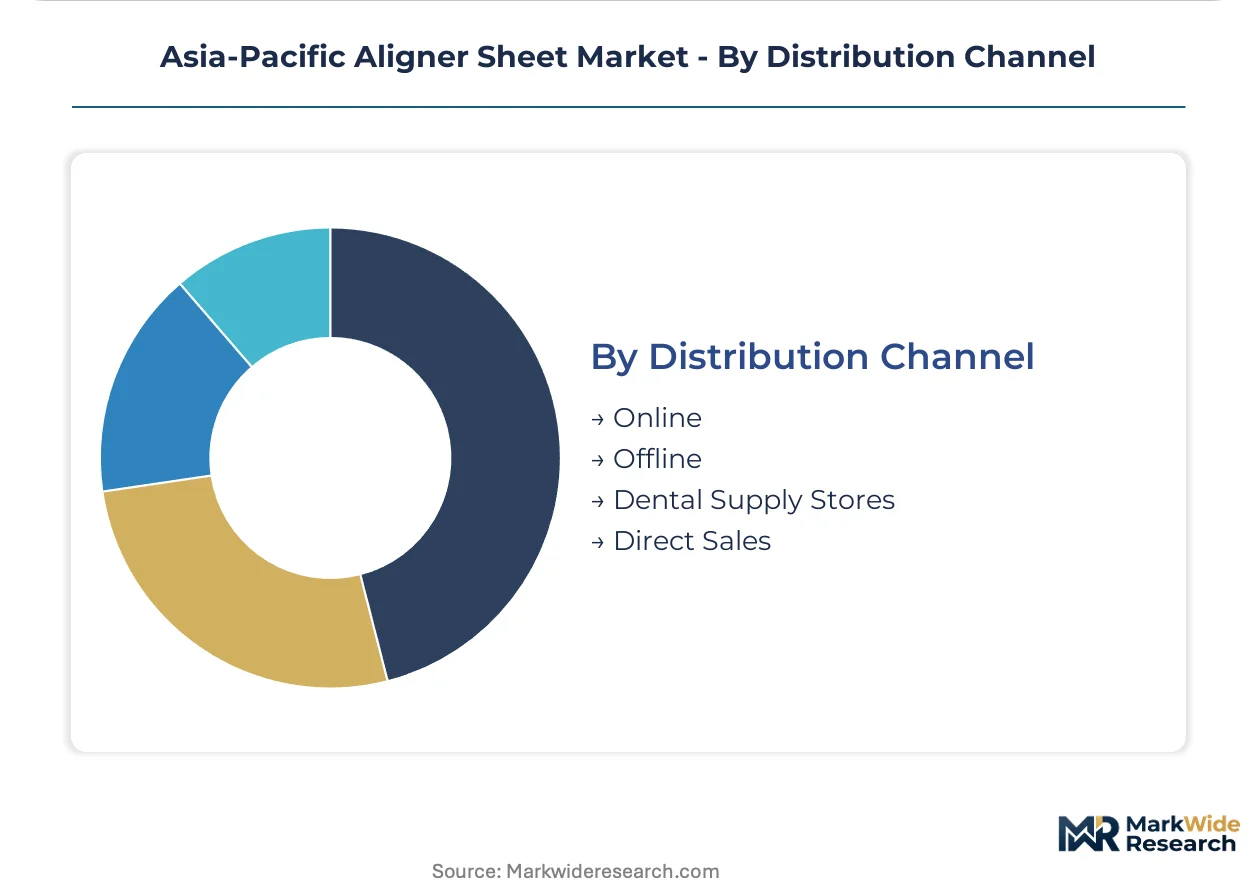
Distribution Channel:
Supply concentration in East Asian extrusion corridors shapes channel access—direct sales favor captive polymer production while offline networks depend on regional converter relationships.
- Online:E-procurement platforms are penetrating mid-tier orthodontic practices in Southeast Asian secondary cities where distributor coverage remains sparse.
- Offline:Traditional dental supply distributors retain relevance in fragmented markets like Indonesia and the Philippines.
- Dental Supply Stores:Physical retail channels serve emergency replacement and small-practice procurement in Australia's consolidated market.
- Direct Sales:Large clinic networks in Seoul and Busan negotiate volume-based thermoplastic contracts with extrusion specialists, displacing intermediary margin capture.
Direct sales command the highest value per transaction. Online channels are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Asia-Pacific aligner sheet trade flows reflect divergent manufacturing capabilities and regulatory access tiers across the region. Import dependency for medical-grade thermoplastics concentrates in Southeast Asian markets while Northeast Asian economies sustain captive extrusion capacity. The regional market fragments across five national corridors with distinct procurement patterns and compliance architectures.
China
Tier-one city dental clinics in Shanghai and Beijing drive polyurethane sheet consumption for complex malocclusion protocols. NMPA medical device classification rules extend registration timelines for imported materials by 18-24 months versus domestic equivalents. Zhengzhou and Suzhou extrusion corridors host domestic thermoplastic production serving Angelalign's manufacturing scale.
Japan
Aging demographic expansion of post-treatment retention regimens sustains demand for lower-force sheet variants in Tokyo and Osaka orthodontic networks. PMDA quality management system requirements tighten polymer additive disclosure thresholds for imported devices. Kanto region clinics adopt precision co-extruded grades for complex case management.
India
Metropolitan dental corridors in Mumbai and Delhi witness compressed traditional braces adoption among professionals aged 25-40 seeking aesthetic alternatives. CDSCO import registration mandates shape foreign supplier access timelines, though 2023 medical device rules amendments compress approval timelines for EU MDR-harmonized products. Bangalore and Hyderabad emerge as CAD/CAM treatment planning hubs.
Australia
TGA-registered reference products gain preference among Southeast Asian distributors seeking regulatory pre-approval leverage. Direct-to-consumer aligner platforms utilizing generic thermoplastic sheets compress premium branded pricing power in deregulated dental retail channels. Sydney and Melbourne orthodontic networks negotiate direct procurement contracts bypassing traditional distributors.
South Korea
Consolidated clinic chains in Seoul and Busan exceed 50-location thresholds for centralized thermoplastic supply agreements with extrusion specialists. MFDS medical device regulations align with international standards while maintaining domestic quality benchmarks. Deep CAD/CAM workflow embedding enables direct-to-practitioner sheet supply models displacing intermediary margin capture.
Asia-Pacific Aligner Sheet Market Competitive Environment
Concentration sits with multinational dental technology conglomerates possessing captive polymer formulation capabilities and direct-to-practitioner channel infrastructure. Regional sheet converters compete on specialized material grades and shorter-arch anatomical optimization for Asian patient profiles. Two strategic archetypes dominate: vertically integrated dental technology platforms with proprietary thermoplastic IP, and regional extrusion specialists serving localized orthodontic networks. Competitive moves center on backward integration into polymer feedstock production and strategic partnerships with CAD/CAM software platforms.
Among Asia-Pacific-based specialists, MAXFLEX CO, Ltd and Angelalign Technology Inc. exemplify divergent positioning archetypes. MAXFLEX occupies a position within the regional converter tier, optimized for shorter Asian arch forms through specialized polyurethane grades. Angelalign anchors the domestic manufacturing scale archetype within China, leveraging deep orthodontic software integration. Align Technology, Inc. represents the multinational platform model with proprietary thermoplastic formulation sustaining margin capture across direct channels in Australia and South Korea.
| Leading Market Players |
|---|
| Ormco Corporation |
| Institut Straumann AG |
| MAXFLEX CO, Ltd |
| Whitesmile Clear |
| Dentsply Sirona |
| Align Technology, Inc. |
| 3M |
| Vedia Solutions |
| Angelalign Technology Inc. |
| Others |
Value Chain & Pricing Dynamics
Eighteen-to-twenty-four-month NMPA registration timelines for imported polyurethane sheet grades compress pricing power for foreign suppliers while amplifying margin capture for domestic extrusion specialists in Zhengzhou and Suzhou. This lead-time asymmetry binds supply chain configuration to pricing tier stratification across China's tier-one city dental corridors.
Pricing Analysis
The customization-premium spread between configured-to-order precision co-extruded sheets and standard polyurethane grades runs 40-60% across Seoul and Sydney orthodontic networks. Three-tier pricing structure across premium, standard, and economy levels separates TGA-registered bioplastic formulations from conventional PETG variants and generic retention-grade polyethylene. Pricing pressure stems from direct-to-consumer aligner platforms utilizing commoditized thermoplastic sheets in Australia's deregulated dental retail channels. Home users exhibit the highest price sensitivity, while large multi-location clinic chains in South Korea demonstrate the lowest.
Supply Chain Analysis
Inventory-to-delivery cycles for medical-grade thermoplastic polyurethane feedstock stretch 45-60 days for Southeast Asian sheet converters lacking captive extrusion capacity. Supply concentrates in East Asian chemical corridors spanning China, South Korea, and Japan, with specialty resin production anchoring in Shanghai and Busan industrial zones. Raw material dependencies center on petroleum-derived polyurethane precursors, bio-based PLA feedstock, and medical-grade PETG resin. Single-source vulnerability from concentrated East Asian chemical production exposes converters to disruption. Distribution runs through direct procurement contracts between large clinic networks and extrusion specialists, displacing traditional dental supply distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a defensive-moat story where NMPA registration entrenchment creates 18-24 month switching costs that protect incumbent positioning against foreign supplier entry.
For Market Incumbents: Compound regulatory entrenchment by deepening NMPA and PMDA certification portfolios ahead of biocompatibility testing protocol harmonization. Backward integration into bio-based PETG resin production secures feedstock access as China's dual carbon goals accelerate material substitution mandates. Channel control through direct-to-practitioner CAD/CAM workflow embedding defends margin capture against remote orthodontic platform substitution.
For New Entrants and Emerging Players: Differentiate on specialized polyurethane grades optimized for shorter Asian arch forms, following MAXFLEX's regional converter archetype. Indonesia and Philippines secondary cities present the most penetrable white space, with orthodontist density sitting below saturation thresholds. A localized sheet distribution network with Indonesian dental supply partnerships offers the clearest go-to-market angle.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-capture play because medical device classification timelines and polymer traceability requirements compound incumbent advantages across successive compliance cycles. Acquisition targets should profile as regional extrusion specialists with existing NMPA or PMDA registrations and captive thermoplastic formulation IP. The signal to watch is CDSCO import registration timeline compression for EU MDR-harmonized products, which would accelerate foreign supplier access to Indian metropolitan dental corridors.
| Strategic Initiative | Industry Significance |
|---|---|
| NMPA Medical Device Registration | 18-24 month review timelines protect domestic manufacturers against imported sheet competition in Shanghai and Beijing. |
| Backward Integration into Bio-Based Resin | Captive PLA and bio-PETG production secures supply as China's provincial green procurement policies tighten. |
| CAD/CAM Platform Partnership | Deep workflow embedding with Angelalign's orthodontic software stack enables direct-to-practitioner sheet supply models. |
| Precision Co-Extrusion Capacity Expansion | Sub-50-micron layer control technology commands premium positioning in Tokyo and Singapore complex malocclusion cases. |
| Southeast Asian Distribution Network | Localized presence in Jakarta and Manila captures first-mover positioning as orthodontist density rises in secondary cities. |
Study Parameters
A spread of perspectives from orthodontic clinic procurement managers, dental supply distributors, thermoplastic extrusion specialists, and regulatory affairs consultants converged on the working assumptions underlying volume and value estimates. Primary interviews with these stakeholders combined with secondary validation from NMPA medical device registration databases, PMDA quality management system filings, CDSCO import approval records, and customs trade data for medical-grade polymer imports. Bottom-up clinic-level demand estimation and top-down thermoplastic feedstock production analysis were triangulated to anchor projections.
Segmentation dimensions modeled span polymer chemistry, end-user technical sophistication, application protocol maturity, and distribution channel structure across the projection horizon. CAGRs were derived from trend extrapolation of historical registration volumes, clinic expansion patterns, and material substitution rates. Industry-specific forecast inputs include NMPA review timeline trajectories and provincial bioplastic procurement mandate adoption curves.
Material uncertainties — NMPA regulatory pathway revisions, PMDA additive disclosure threshold adjustments, and bio-based resin supply scaling bottlenecks — sit outside the modeled envelope. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Equipment
Chip Probing Market
Semiconductor Equipment
FOUP Load Port Market
Semiconductor Equipment
Electrolytic Etching Machine Market
Semiconductor Equipment
Plasma Etch System Market
Semiconductor Equipment
Global Semiconductor Coolers Market
Semiconductor Equipment
Global Battery Manufacturing Equipment Market
Semiconductor Equipment
Global Cleanroom Technologies Market
Semiconductor Equipment
Vacuum Soldering System Market
Semiconductor Equipment
Vacuum Ovens Market
Semiconductor Equipment
Global Semiconductor Back-End Equipment Market
Semiconductor Equipment
Semiconductor Production Equipment Market
Semiconductor Equipment
Semiconductor Wafer Fab Equipment (WFE) Market
Semiconductor Equipment
Laser Annealing System Market
Semiconductor Equipment
Ion Milling System Market
Semiconductor Equipment
Semiconductor Manufacturing Equipment Market
Semiconductor Equipment
Cathode Stripping Machines Market