
 High Electron Mobility Transistor Market | 2026-2036
High Electron Mobility Transistor Market Size, Share, and Industry Trends Forecast 2026-2036
High Electron Mobility Transistor Market Analysis
Buyer concentration in telecommunications infrastructure is rebalancing as tier-one base station OEMs consolidate procurement while defense primes fragment orders across specialized GaN foundries. NXP Semiconductors leverages its RF power portfolio to anchor European aerospace programs. Wolfspeed sustains vertical integration from SiC substrate through epitaxy, controlling critical material supply. Qorvo specializes in GaN MMIC design for phased array radar, differentiating through foundry partnerships with domestic defense contractors.
High electron mobility transistors are heterostructure field-effect devices that exploit quantum well confinement at semiconductor interfaces, typically AlGaN/GaN or InGaAs/InP, to achieve electron mobilities exceeding 2000 cm²/V·s and breakdown fields above 3 MV/cm. These properties enable power amplification at microwave and millimeter-wave frequencies with efficiencies surpassing 70% in continuous-wave operation. GaN product variants lead absolute revenue due to penetration in 5G macro base stations and military radar, while InGaAs HEMTs occupy niche high-frequency instrumentation and satellite communications where indium phosphide substrates justify premium positioning. RF Power Amplifiers technology commands the largest application share, though Power Management ICs for electric vehicle onboard chargers represent the fastest-expanding margin pool as automotive voltage platforms migrate to 800V architectures.
FDA device regulations indirectly shape HEMT demand through medical imaging equipment incorporating RF chains, while FCC spectrum allocations for 5G and 6G directly dictate frequency bands where GaN HEMTs outperform silicon alternatives. EPA hazardous substance rules govern gallium and indium refining waste streams, constraining raw material processing capacity in domestic supply chains. REACH chemical registration in Europe imposes compliance burdens on III-V compound importers, filtering market access for non-integrated suppliers. Stakeholders must monitor foundry utilization rates against defense contract award timelines to calibrate capacity commitments before substrate supply tightens.
Market Dynamics
GaN-on-SiC epitaxy capacity concentration in Taiwanese and South Korean foundries is tightening substrate allocation for defense and telecommunications buyers, forcing procurement timelines to compress and qualification cycles to extend.
Growth Catalysts
- 5G spectrum densification:FCC mid-band auctions and subsequent base station buildouts in the United States are pulling GaN HEMT demand for massive MIMO arrays.
- REACH chemical registration:European compliance burdens on III-V compound importers are filtering non-integrated suppliers, consolidating volume with qualified vendors.
- Electronic warfare modernization:Pentagon radar refresh programs are accelerating GaN MMIC insertion into phased array architectures.
Market Restraints
- Silicon carbide substrate scarcity:Wolfspeed and II-VI captive production limits merchant SiC wafer availability for GaN epitaxy houses.
- Indium refining constraints:EPA hazardous substance rules govern gallium and indium waste streams, capping domestic raw material processing throughput.
- Silicon LDMOS residual base:Legacy amplifier infrastructure in emerging market telecommunications delays GaN conversion economics.
Strategic Opportunities
- 800V automotive platforms:Onboard charger and DC-DC converter applications for electric vehicles represent underpenetrated GaN HEMT volume.
- India PLI scheme:Domestic compound semiconductor incentives are attracting epitaxy equipment investment for regional RF component supply.
- 6G terahertz research:InP HEMT integration with photonic interconnects is opening instrumentation and satellite communication white space.
Industry Challenges
- Compound semiconductor process engineering:Foundry talent scarcity in MOCVD reactor operation and heterostructure characterization extends yield ramp timelines.
- Defense qualification cycles:MIL-STD-883 screening and space-grade hermetic packaging certification compress margin realization windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High Electron Mobility Transistor Market |
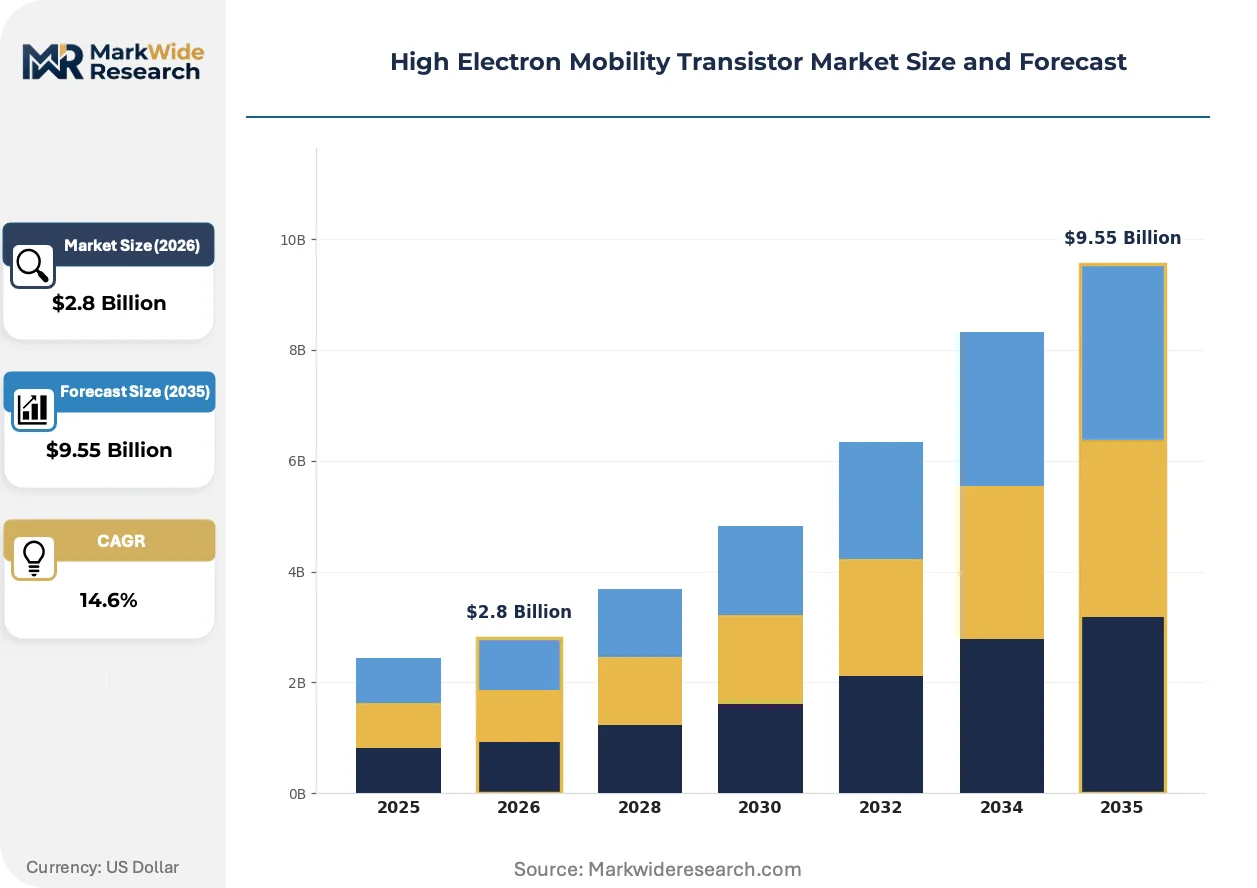
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $9.55 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: GaN, InGaAs, AlGaN, Others Technology: RF Power Amplifiers, Low Noise Amplifiers, Signal Switches, Power Management ICs End User: Aerospace, Telecommunications, Consumer Electronics, Automotive Application: Satellites, 5G Infrastructure, Radar Systems, Electronics Testing |
| Companies Covered | NXP Semiconductors, Infineon Technologies, Texas Instruments, ST Microelectronics, Renesas Electronics, Qorvo, Wolfspeed, Mitsubishi Electric, MACOM Technology Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High Electron Mobility Transistor Market Emerging Trajectories
Device architectures are converging toward higher frequency operation and thermal efficiency, while regulatory frameworks and procurement models compress traditional supply chain timelines.
GaN-on-diamond substrates is integrating synthetic diamond heat spreaders directly beneath the active device layer to achieve thermal resistances below 0.5 K·mm/W. Defense prime contractors in the United States are piloting this configuration for next-generation radar transmit-receive modules. The structural consequence is compressing thermal management subsystem count and enabling higher power density packaging.
EU F-Gas Regulation phase-down schedules are restricting fluorinated greenhouse gas availability for semiconductor plasma etching processes. European GaN foundries are retrofitting dry etch chambers for alternative chemistries to maintain throughput. RF power amplifier manufacturers with European packaging operations face the most acute compliance timeline pressure.
Direct foundry contracting by tier-one base station OEMs is displacing traditional distributor-mediated component procurement. NXP Semiconductors and Qorvo are establishing dedicated capacity reservation agreements with telecommunications infrastructure buyers. South Korean and Taiwanese equipment manufacturers are the earliest adopters of this volume-commitment model.
High Electron Mobility Transistor Market Segmentation
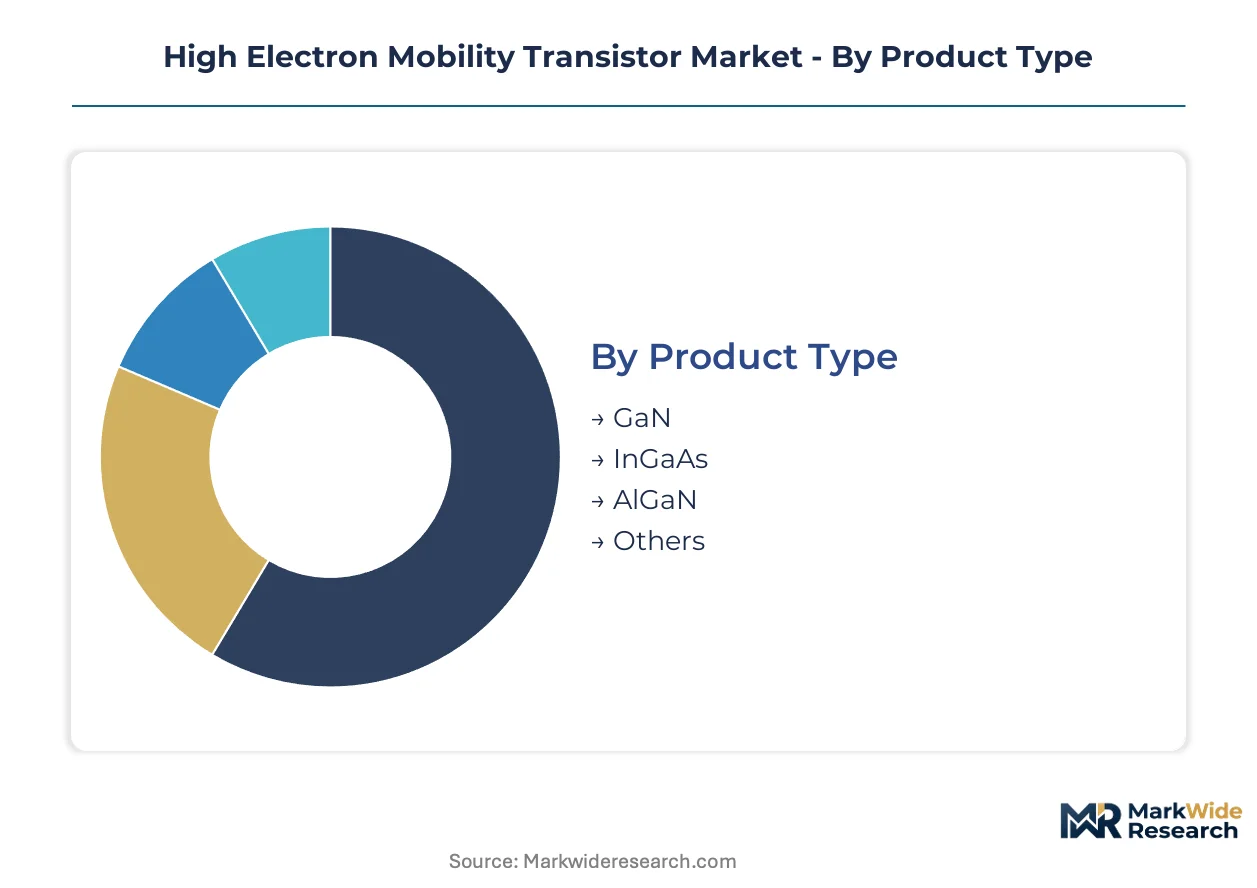
HEMT architectures diverge sharply across frequency, power, and thermal requirements, forcing procurement teams to match material systems precisely to deployment environments. Segment boundaries reflect substrate availability, epitaxy maturity, and end-use qualification timelines rather than interchangeable commodity tiers.
Product Type:
Gallium nitride compound variants dominate power amplification where thermal conductivity and breakdown field determine device scaling limits.
- GaN:Wide-bandgap hexagonal crystal structure grown on silicon carbide substrates delivers electron saturation velocities exceeding 2.5 × 10⁷ cm/s. Defense radar programs in the United States and 5G massive MIMO deployments in South Korea concentrate procurement volume here, though silicon carbide substrate scarcity compresses foundry allocation timelines.
- InGaAs:Indium gallium arsenide lattice-matched to indium phosphide substrates achieves cutoff frequencies above 500 GHz for millimeter-wave instrumentation. Satellite communication terminals in Japan and test equipment manufacturers in Germany anchor demand, with indium refining constraints capping supply elasticity.
- AlGaN:Aluminum gallium nitride barrier layers form the heterostructure foundation for GaN HEMTs, with aluminum mole fraction tuning polarization charge density.
- Others:Emerging material systems include aluminum indium nitride and gallium oxide heterostructures under active research.
Mature deployment sits with GaN. Newer deployment is concentrated in InGaAs for sub-terahertz frontier applications.
Technology:
Circuit function determines frequency band, linearity requirements, and thermal design complexity across the HEMT integration stack.
- RF Power Amplifiers:These devices convert DC bias to microwave output power with drain efficiencies surpassing 70% in Class AB operation. Base station OEMs in Taiwan and defense primes in the United States drive volume, with FCC spectrum auctions pulling demand into C-band and mmWave allocations.
- Power Management ICs:Synchronous rectification and DC-DC conversion circuits exploit GaN switching speeds above 100 MHz. Automotive onboard chargers for 800V electric vehicle platforms in Germany and China represent the steepest expansion trajectory, though AEC-Q100 qualification extends design-in cycles.
- Low Noise Amplifiers:Front-end receiver chains prioritize noise figures below 1 dB for weak signal detection.
- Signal Switches:High-isolation switching matrices route RF paths in phased array architectures.
RF Power Amplifiers absorb the dominant share of wafer starts. Power Management ICs are climbing the fastest as automotive voltage platforms migrate upward.
End User:
Customer verticals impose divergent qualification protocols, volume scales, and margin structures on HEMT suppliers.
- Aerospace:MIL-STD-883 screening and space-grade hermetic packaging certification compress margin realization windows. Pentagon radar refresh programs and European satellite constellations concentrate procurement with domestic foundry partners.
- Telecommunications:Massive MIMO base station deployments require thermal cycling reliability above 15 years. South Korean and Taiwanese equipment manufacturers consolidate procurement through direct foundry contracting, displacing traditional distributor channels.
- Automotive:800V platform migration for electric vehicles is pulling GaN HEMT insertion into onboard chargers and DC-DC converters.
- Consumer Electronics:Smartphone RF front-end modules and Wi-Fi 6E access points drive high-volume, cost-constrained demand.
Aerospace commands premium pricing through qualification barriers. Automotive represents the most aggressive volume expansion path.
Application:
Use-case environments dictate thermal management, radiation hardness, and bandwidth specifications that filter device selection.
- 5G Infrastructure:Massive MIMO arrays with 64-element configurations require phase-coherent amplification across 3.5 GHz and 28 GHz bands. FCC mid-band auctions in the United States and spectrum releases in India concentrate deployment timelines, with GaN HEMTs displacing silicon LDMOS in macro cell power amplifiers.
- Radar Systems:Active electronically scanned arrays for fighter aircraft and naval vessels demand GaN MMICs with output power densities above 10 W/mm. Pentagon electronic warfare modernization programs and NATO allied upgrades sustain defense foundry capacity reservation.
- Satellites:Geostationary and low-earth-orbit payloads require radiation-hardened devices with decade-plus mission lifetimes.
- Electronics Testing:Vector network analyzers and spectrum analyzers for 5G and 6G research depend on InP HEMT front-ends for millimeter-wave signal integrity.
5G Infrastructure absorbs the greatest wafer volume. Radar Systems maintain the most inelastic demand through defense procurement cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense procurement agencies in the United States and allied nations are expanding GaN-on-SiC HEMT orders for next-generation radar and electronic warfare systems. Demand concentrates in East Asian semiconductor manufacturing clusters, particularly Taiwan and South Korea, where foundry capacity for compound semiconductor epitaxy continues to scale.
United States
Pentagon radar refresh programs and electronic warfare modernization are accelerating GaN MMIC insertion into phased array architectures. FCC mid-band spectrum auctions for 5G infrastructure pull demand into C-band allocations. Defense prime contractors in California and Massachusetts are piloting GaN-on-diamond substrates for thermal management.
Germany
Automotive onboard chargers for 800V electric vehicle platforms represent the steepest expansion trajectory for GaN HEMT volume. EU F-Gas Regulation phase-down schedules are restricting fluorinated greenhouse gas availability for semiconductor plasma etching processes. Bavarian and Baden-Württemberg automotive suppliers are retrofitting dry etch chambers for alternative chemistries.
South Korea
Massive MIMO base station deployments require thermal cycling reliability above 15 years for telecommunications infrastructure. The country's national spectrum regulator releases mid-band frequencies that concentrate deployment timelines. Seoul-based equipment manufacturers consolidate procurement through direct foundry contracting with domestic epitaxy houses.
Taiwan
GaN-on-SiC epitaxy capacity concentration is tightening substrate allocation for defense and telecommunications buyers. The central government's semiconductor industrial policy supports compound semiconductor foundry scaling. Hsinchu Science Park hosts the densest cluster of MOCVD reactor operations for heterostructure characterization.
Japan
Satellite communication terminals and test equipment manufacturers anchor demand for InP HEMT front-ends at millimeter-wave frequencies. METI industrial policy frameworks support domestic compound semiconductor supply chain resilience. Tokyo and Osaka metropolitan areas concentrate precision instrumentation OEMs integrating photonic interconnects.
High Electron Mobility Transistor Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue automotive power management and 6G terahertz research frontiers. The vendor base stratifies across three tiers: integrated device manufacturers with captive epitaxy, fabless designers leveraging foundry partnerships, and substrate suppliers controlling critical material supply. Two dominant competitive moves are reshaping positioning: direct foundry contracting by tier-one OEMs displacing distributor channels, and backward integration into silicon carbide substrate production securing raw material allocation.
Among European integrated device manufacturers, NXP Semiconductors and Infineon Technologies exemplify the RF power portfolio archetype anchoring aerospace and automotive programs. Wolfspeed occupies a position representing vertical control from substrate through epitaxy. Qorvo sits within the fabless-specialist tier, differentiating through GaN MMIC design partnerships with domestic defense contractors.
| Leading Market Players |
|---|
| NXP Semiconductors |
| Infineon Technologies |
| Texas Instruments |
| ST Microelectronics |
| Renesas Electronics |
| Qorvo |
| Wolfspeed |
| Mitsubishi Electric |
| MACOM Technology Solutions |
| Others |
Supply Flow & Price Mechanics
Foundry-backed compound semiconductor specialists in Taiwan and South Korea anchor pricing discipline through captive epitaxy capacity, while defense procurement agencies in the United States absorb premium positioning for MIL-STD-qualified devices. This ownership concentration compresses margin leakage to distributor intermediaries and reinforces long-term offtake contracting as the dominant commercial mechanism.
Pricing Analysis
Volume absorption concentrates in telecommunications infrastructure where South Korean and Taiwanese base station OEMs negotiate direct foundry contracts, while margin capture clusters in aerospace and defense applications demanding space-grade hermetic packaging. Three-tier pricing structure across defense-certified, automotive-qualified, and commercial-grade tiers separates qualification-burdened premiums from cost-optimized volume production. Cost compression in commercial-grade GaN HEMTs is intensifying because silicon LDMOS residual demand delays full conversion economics. Consumer electronics RF front-end modules exhibit the highest price sensitivity; Pentagon radar programs demonstrate the least.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale telecommunications and defense prime demand, displacing traditional distributor-mediated procurement for qualified GaN-on-SiC devices. Substrate supply concentrates in the United States through Wolfspeed and II-VI captive production, epitaxy processing clusters in Taiwan and South Korea, and packaging operations across Germany and Japan. Raw material dependencies draw from gallium refining capacity governed by EPA hazardous substance rules, indium phosphide substrate supply constrained by mining concentration, and synthetic diamond heat spreaders piloted for next-generation thermal management. Single-source vulnerability in silicon carbide substrate production presents acute supply chain risk. Distribution runs through long-term capacity reservation agreements with tier-one OEMs rather than spot-market transactions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH chemical registration in Europe filters non-integrated III-V compound importers, erecting a compliance moat that consolidates volume with qualified vendors and elevates cost-of-entry for prospective competitors. This regulatory barrier rewards incumbents with established European chemical handling infrastructure.
For Market Incumbents: Extend backward integration into silicon carbide substrate production to secure raw material allocation against Wolfspeed and II-VI captive supply constraints. Expand MOCVD reactor operations in Hsinchu Science Park and Seoul metropolitan clusters to capture telecommunications infrastructure volume commitments. Defense qualification cycle compression threatens margin realization windows; accelerate yield ramp timelines through heterostructure characterization automation.
For New Entrants and Emerging Players: Begin with automotive onboard charger applications for 800V electric vehicle platforms in Germany and China, where AEC-Q100 qualification barriers are lower than MIL-STD-883 defense certification. Target GaN power management IC design for electric vehicle DC-DC converters as the most penetrable white-space segment. Establish foundry partnerships with Taiwanese epitaxy houses rather than pursuing captive MOCVD capacity.
For Investors and Strategic Acquirers: Distressed-cycle entries favor fabless GaN MMIC designers with established defense contractor partnerships in the United States during Pentagon procurement cycle troughs. Long-term viability hinges on compound semiconductor process engineering talent retention and heterostructure IP accumulation. Monitor foundry utilization rates against defense contract award timelines as the critical inflection signal for capacity commitment timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into SiC Substrate Production | Wolfspeed's vertical control from substrate through epitaxy secures critical material supply allocation. |
| Direct Foundry Contracting with Tier-One OEMs | NXP Semiconductors anchors European aerospace programs through dedicated capacity reservation agreements. |
| GaN-on-Diamond Thermal Management Piloting | Defense prime contractors in California compress thermal subsystem count for radar transmit-receive modules. |
| REACH Chemical Registration Compliance Investment | European III-V compound importers filter market access for non-integrated suppliers. |
| Automotive AEC-Q100 Qualification Pathway | German and Chinese electric vehicle platforms pull GaN HEMT insertion into onboard chargers. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with MOCVD reactor operators, defense procurement officers at Pentagon agencies, base station OEM procurement leads, automotive Tier 1 power electronics engineers, and compound semiconductor foundry executives combined with secondary validation. SEC 10-K disclosures, FCC spectrum auction records, EPA hazardous substance compliance databases, and EU REACH registration filings provided quantitative grounding. Bottom-up wafer start estimates and top-down equipment shipment data underwent cross-triangulation.
Data-stream reconciliation across foundry utilization surveys, defense contract award databases, and telecommunications infrastructure capex disclosures shaped the analytical framework. Segmentation dimensions modeled include product type, circuit function, end-use vertical, and regional regulatory cluster throughout the forecast period. CAGRs derived from equipment shipment trajectories and substrate supply elasticity curves. GaN-on-SiC epitaxy capacity expansion timelines and InP substrate availability constraints served as industry-specific forecast inputs.
Underlying measurement precision varies by segment; defense radar applications carry tighter precision than emerging automotive power management due to classified program visibility. Forecasts reflect assumptions regarding silicon carbide substrate supply expansion and FCC spectrum allocation timelines. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Devices
Ram BOP Market
Semiconductor Devices
Global Substrate-Like PCB Market
Semiconductor Devices
Global Inp Wafer Market
Semiconductor Devices
Asia Pacific Motherboard Market
Semiconductor Devices
Global ASIC Bitcoin Mining Hardware Market
Semiconductor Devices
Japan CEP Market
Semiconductor Devices
Nanowires Market
Semiconductor Devices
Silicon on Insulator Market
Semiconductor Devices
Power Supply in Package (Psip) and Power Supply on Chip (Pwrsoc) Market
Semiconductor Devices
Chip Equalizers Market
Semiconductor Devices
Gan-On-Silicon Market
Semiconductor Devices
Silicon Epitaxial Wafer Market
Semiconductor Devices
Quartz Crystal Oscillators Market
Semiconductor Devices
China Semiconductor Device Market
Semiconductor Devices
Europe Semiconductor Device Market
Semiconductor Devices
Micro Thermoelectric Modules Market