
 DUV Lithography Systems Market | 2026-2036
DUV Lithography Systems Market Size, Share, and Industry Trends Forecast 2026-2036
DUV Lithography Systems Market Foresight
Software-defined process control is pivoting how DUV lithography contracts are structured, bundling real-time overlay correction with hardware leases. ASML sustains its technology leadership through deep ultraviolet source development and scanner-wafer-table integration. Nikon Corporation competes in ArF immersion segments where Japanese supply chain proximity offers delivery advantages. Canon Inc. anchors its position in KrF and i-line legacy nodes serving power semiconductor and analog chip fabricators.
Deep ultraviolet lithography systems project circuit patterns onto silicon wafers using 193 nm (ArF) or 248 nm (KrF) excimer laser light, achieving critical dimensions down to 7 nm with multiple patterning. These systems enable the mass production of logic and memory chips where extreme ultraviolet tools remain economically prohibitive for mature nodes. Semiconductor Manufacturing applications dominate system deployments as foundries expand 28 nm and above capacity to serve automotive and industrial demand. Wafer Fabricators represent the most concentrated end-user category, with Integrated Device Manufacturers adding capacity for insulated-gate bipolar transistors and radio-frequency components. ArF technology leads value generation due to immersion scanner complexity and patterning-layer intensity at advanced nodes.
Japan's Ministry of Economy, Trade and Industry restricts exports of 14 nm-class equipment, compelling buyers to qualify alternative sourcing or seek licenses for ArF immersion scanners. The US Bureau of Industry and Commerce administers foreign direct product rules affecting lithography components with American intellectual property, reshaping vendor-country pairings for Chinese fabs. The EU Chips Act funding criteria require semiconductor manufacturing investments to meet CE machinery directives and REACH chemical safety standards for photoresist chemistries. Stakeholders must monitor how export control alignment across Tokyo, Washington, and Brussels reshapes equipment availability for specific node targets.
Market Dynamics
Foundry demand for mature-node chips is compressing equipment procurement cycles while export controls from Tokyo, Washington, and Brussels fragment vendor-country pairings for Chinese fabs. ArF immersion scanner utilization is climbing as automotive and industrial chip demand outpaces EUV economic viability at 28 nm and above.
Growth Catalysts
- Automotive semiconductor demand:Electric vehicle powertrains and advanced driver-assistance systems require insulated-gate bipolar transistors and radio-frequency components fabricated on 28 nm to 90 nm nodes. Wafer fabricators are expanding ArF immersion capacity to serve this demand.
- METI licensing frameworks:Japan's Ministry of Economy, Trade and Industry export controls on 14 nm-class equipment are accelerating alternative supplier qualification programs. Buyers are diversifying sourcing across Korean and European vendors to mitigate license uncertainty.
- Multiple patterning economics:Self-aligned quadruple patterning and litho-etch-litho-etch sequences extend 193 nm immersion resolution to 7 nm critical dimensions. This process complexity sustains scanner intensity per wafer start at nodes where EUV capital costs remain prohibitive.
Market Restraints
- Fluorinated gas supply concentration:ArF excimer laser operation depends on neon and fluorine gas supplies concentrated in Ukrainian and Russian production corridors. Geopolitical disruption elevates operating cost volatility for immersion scanner fleets.
- Optical component supplier lock-in:Deep ultraviolet projection lens systems rely on calcium fluoride crystal growth capabilities concentrated in German and Japanese specialty glass houses. Single-source dependencies extend lead times for scanner refurbishment.
- EUV substitution trajectory:ASML's high-NA EUV systems are compressing the economic window for multi-patterning DUV at 5 nm and below logic nodes. Memory manufacturers are accelerating EUV adoption for DRAM capacitor formation.
Strategic Opportunities
- India semiconductor manufacturing incentives:The country's PLI scheme for semiconductor fabrication is attracting foundry investments targeting 28 nm and above nodes. DUV scanner demand from Indian greenfield fabs represents an underpenetrated geography.
- Photoresist chemistry convergence:Metal oxide resists compatible with both DUV and EUV exposure wavelengths are simplifying process integration. Dual-platform resist qualification reduces fab chemistry inventory complexity.
- Real-time overlay correction bundling:Software-defined process control packages combining scanner metrology with computational lithography are creating new recurring revenue streams. Hardware vendors are pivoting toward subscription-based performance contracts.
Industry Challenges
- Computational lithography talent scarcity:Inverse lithography technology and optical proximity correction algorithm development require rare combinations of physics and software engineering expertise. Foundries are competing for limited pools of scanner-resist-process integration specialists.
- Legacy node equipment refurbishment:KrF and i-line scanner fleets serving power semiconductor fabricators require specialized maintenance knowledge as original equipment manufacturer support windows narrow. Third-party service providers face certification barriers from proprietary control software.
- Cross-border IP licensing friction:Scanner-wafer-table synchronization algorithms and laser pulse control patents span multiple jurisdictional portfolios. Equipment vendors navigate complex royalty stacking when deploying systems in restricted markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | DUV Lithography Systems Market |
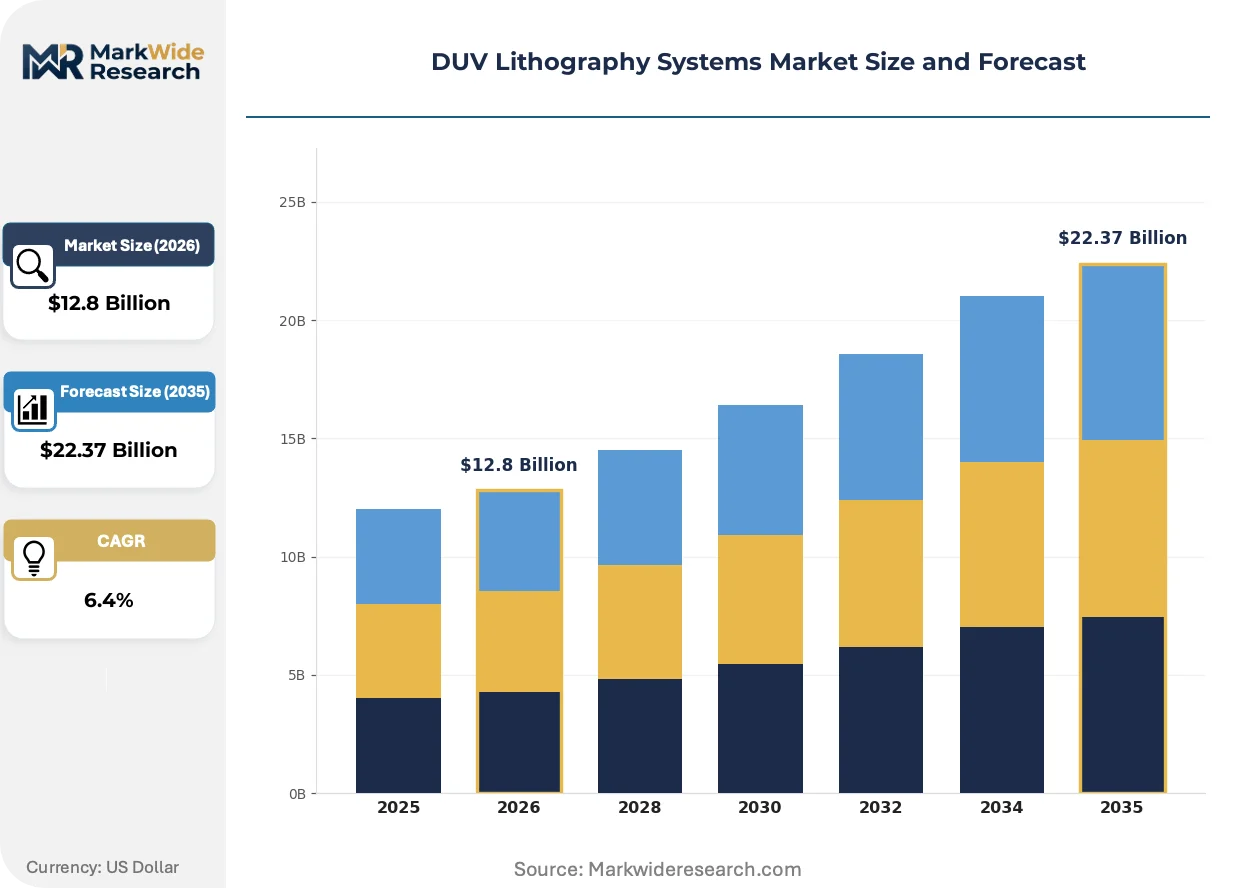
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $22.37 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: ArF, KrF, Excimer, Others Application: Semiconductor Manufacturing, Flat Panel Display, Microelectronics, Others End User: Wafer Fabricators, Foundries, Integrated Device Manufacturers, Research Institutions Product Type: Mask/Etch, Clean Room Tools, Alignment Equipment, Others |
| Companies Covered | Veeco Instruments, EV Group, ASML, Rudolph Technologies, HORIBA, Nikon Corporation, SUSS MicroTec, Applied Materials, Canon Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
DUV Lithography Systems Market Shifts & Advancements
Software-defined lithography is collapsing the boundary between hardware performance and computational correction, while regulatory fragmentation forces buyers to architect multi-vendor qualification strategies. These forces are reshaping how scanner contracts are structured and where capacity investments flow.
Computational lithography is rewriting the resolution-cost tradeoff for mature-node production. Inverse lithography technology and source-mask optimization algorithms extend 193 nm immersion patterning to 7 nm equivalent critical dimensions. Memory and logic foundries are adopting these computational layers at accelerating pace, compressing the economic window where EUV capital investment delivers returns. This convergence is enabling 28 nm capacity expansions without corresponding EUV scanner procurement.
REACH chemical safety standards and the EU Chips Act machinery directives are tightening photoresist qualification requirements for equipment receiving European subsidy support. Semiconductor manufacturing investments must demonstrate compliance with CE marking and substance restriction protocols across the chemical supply chain. Automotive chip fabricators targeting European OEM supply chains are prioritizing resist chemistries with pre-qualified regulatory dossiers, accelerating substitution away from legacy formulations.
Scanner procurement is consolidating around performance-based contracting models that unbundle hardware ownership from overlay yield guarantees. Foundries in Taiwan's Science Park corridor are piloting contracts where vendors retain scanner title and charge per wafer processed against specified critical dimension uniformity targets. This consumption-pattern shift transfers capital risk to equipment suppliers while aligning vendor incentives with fab yield outcomes.
DUV Lithography Systems Market Segmentation
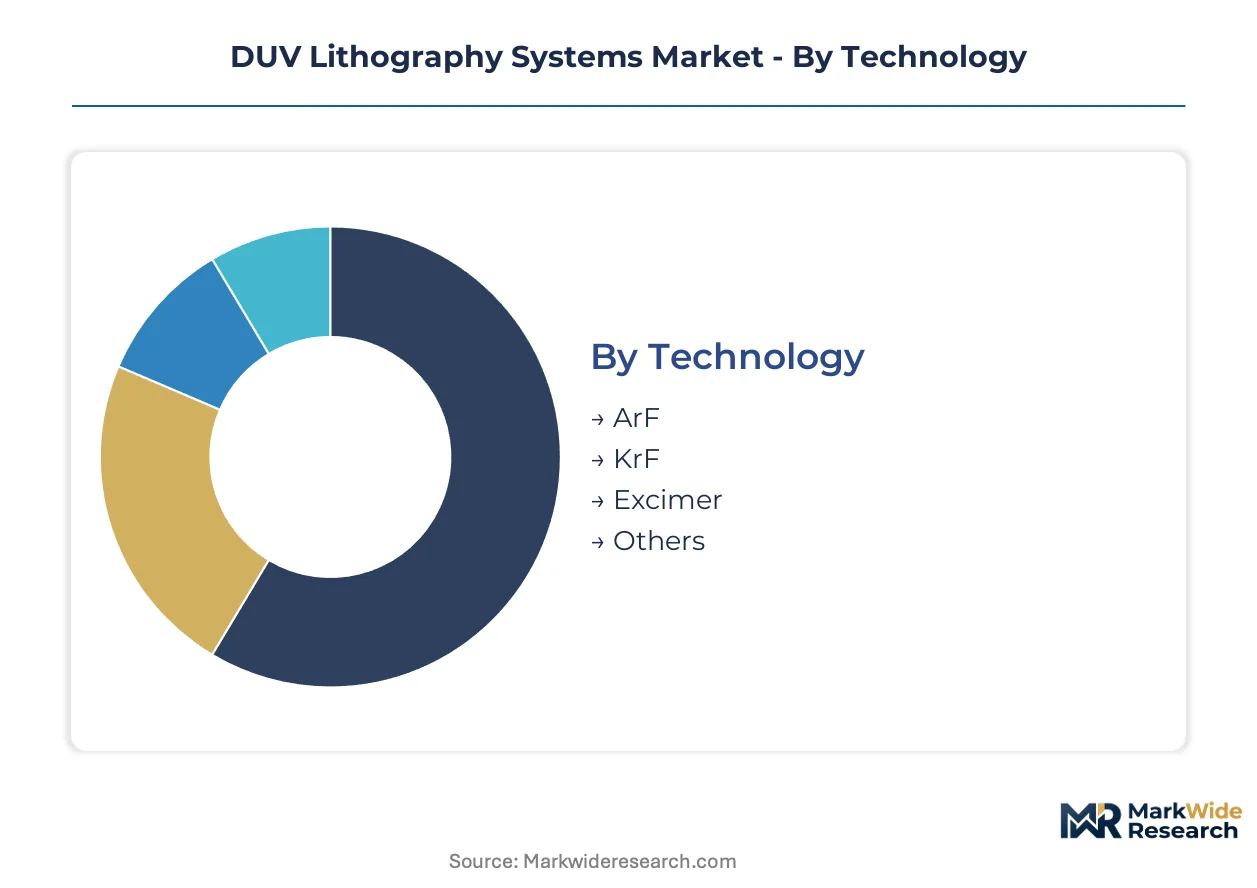
DUV lithography segmentation reveals how scanner procurement priorities diverge across technology generations and end-use applications. Equipment replacement cycles and node-specific patterning requirements reshape how vendors allocate R&D and service resources.
Technology:
Upgrade cycles for immersion scanners dominate capital planning as foundries extend 193 nm patterning through computational lithography while legacy KrF fleets age out of support windows.
- ArF:193 nm argon fluoride excimer lasers enable immersion lithography with numerical apertures exceeding 1.35, achieving sub-40 nm half-pitch resolution through multiple patterning. Demand concentrates in Taiwan's Science Park corridor where foundries expand 28 nm capacity for automotive microcontroller supply chains constrained by METI licensing uncertainty.
- KrF:248 nm krypton fluoride systems anchor mature-node production for power semiconductors and analog chips where critical dimensions exceed 130 nm. Procurement from Japanese IDMs accelerates as Canon and Nikon prioritize domestic service response times under export control compliance pressures.
- Excimer:Broadband deep ultraviolet sources support specialty applications including MEMS fabrication and advanced packaging lithography.
- Others:Mercury i-line and broadband DUV systems serve legacy research and small-volume production environments.
Volume placements concentrate in ArF immersion scanners; the faster expansion belongs to KrF refurbishment programs extending fleet life for power semiconductor fabricators.
Application:
Cost tier differentiation separates high-volume logic foundry deployments from display panel investments where larger substrate formats demand specialized optical columns.
- Semiconductor Manufacturing:Logic and memory chip fabrication consumes the majority of scanner throughput, with 300 mm wafer processing driving ArF immersion intensity. Taiwanese foundries in Hsinchu and Tainan Science Parks anchor demand as they qualify multiple patterning flows for 7 nm-equivalent nodes without EUV capital commitment.
- Flat Panel Display:Generation 8.5 and larger substrate formats require projection optics with field sizes exceeding 1.5 meters, constraining supplier base to Nikon and Canon for Gen 10.5 oxide TFT backplanes. Korean and Chinese panel makers dominate procurement as OLED capacity expands for automotive and IT displays.
- Microelectronics:MEMS, RF filters, and photonics devices utilize DUV patterning for feature sizes between 500 nm and 5 microns.
- Others:Advanced packaging lithography for fan-out wafer-level packaging and 2.5D interposers represents an emerging application segment.
Capital intensity peaks in semiconductor manufacturing; display applications are climbing fastest as OLED substrate sizes expand.
End User:
Customer type determines contract structure, with foundries demanding per-wafer pricing and IDMs preferring capital ownership with long-term service agreements.
- Wafer Fabricators:Merchant foundry operators including TSMC, GlobalFoundries, and UMC deploy scanner fleets across multiple nodes to serve fabless design houses. These operators prioritize overlay matching between tools and real-time correction software bundling to maintain yield across high-mix production.
- Foundries:Captive foundry operations at Samsung and Intel fabricate chips for internal product divisions alongside external customers.
- Integrated Device Manufacturers:Texas Instruments, Infineon, and STMicroelectronics operate in-house fabs for analog, power, and automotive chips where process control IP provides differentiation.
- Research Institutions:IMEC, LETI, and academic cleanrooms qualify next-generation resists and patterning techniques.
Equipment utilization runs highest at wafer fabricators; IDM captive expansions are gaining share fastest as automotive semiconductor supply chains regionalize.
Product Type:
Supply concentration in German and Japanese optical component houses shapes margin structures across scanner subsystems.
- Mask/Etch:Photomask patterning and plasma etch equipment for transferring resist images into underlying films. Zeiss and NuFlare dominate mask writer optics while Lam Research and TEL supply etch chambers for multi-patterning sequences.
- Clean Room Tools:Wafer handling, environmental control, and contamination management systems maintaining Class 1 conditions.
- Alignment Equipment:Overlay metrology and wafer positioning systems achieving sub-nanometer placement accuracy.
- Others:Resist processing tracks, developer modules, and ancillary thermal processing equipment.
Revenue concentration sits with mask/etch subsystems; alignment equipment is expanding most quickly as overlay budgets tighten at advanced nodes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in Japanese and Dutch optical supply chains while consumption clusters in Taiwanese foundry corridors and expanding Chinese fabrication parks. Equipment fabrication runs through Yokohama precision glass houses and Veldhoven scanner assembly lines. Foundry demand pulls utilization rates upward across Hsinchu and Shanghai wafer starts.
United States
Automotive microcontroller demand from Detroit-area OEMs is accelerating IDM capacity commitments for 28 nm to 90 nm nodes. The Bureau of Industry and Commerce administers foreign direct product rules affecting lithography components with American intellectual property, reshaping vendor-country pairings for restricted markets. Texas Instruments operates captive fabrication in Richardson and Sherman serving insulated-gate bipolar transistor supply chains.
Japan
Domestic IDM procurement for power semiconductors and analog chips sustains KrF and i-line scanner refurbishment cycles. METI licensing frameworks restrict exports of 14 nm-class equipment, compelling buyers to qualify alternative sourcing or seek licenses for ArF immersion scanners. Nikon and Canon anchor production in Kumagaya and Utsunomiya, prioritizing domestic service response times under export control compliance pressures.
Taiwan
Foundry demand for mature-node automotive chips is compressing equipment procurement cycles across 28 nm and above capacity expansions. Science Park administration coordinates infrastructure for Hsinchu and Tainan corridors where TSMC and UMC deploy scanner fleets. Real-time overlay correction bundling is piloting in Taichung fabs where vendors retain scanner title and charge per wafer processed.
South Korea
Memory manufacturers are accelerating EUV adoption for DRAM capacitor formation while sustaining DUV intensity for peripheral logic layers. MFDS chemical safety standards and trade ministry coordination shape photoresist qualification protocols for subsidized investments. Samsung operates captive foundry capacity in Giheung and Pyeongtaek serving internal product divisions alongside external customers.
China
Domestic foundry construction targets 28 nm and above nodes where EUV capital costs remain prohibitive for volume production. MIIT industrial policy and SAMR standards administration guide equipment procurement toward qualified domestic and non-restricted foreign vendors. SMIC and Hua Hong expand 300 mm wafer starts in Shanghai and Wuxi, qualifying multiple patterning flows for 7 nm-equivalent nodes.
DUV Lithography Systems Market Competitive Landscape
Top-tier vendors anchor scanner-wafer-table integration, while mid-tier specialists concentrate in alignment metrology and resist processing tracks. The vendor base stratifies across three layers: integrated lithography platform providers, optical subsystem specialists, and process control software houses. Competitive positioning crystallizes around computational lithography bundling and performance-based contracting models. Equipment vendors are pivoting toward subscription-based yield guarantees while foundries transfer capital risk through per-wafer pricing structures.
Among integrated platform providers, ASML, Nikon Corporation, and Canon Inc. occupy positions spanning ArF immersion, KrF, and legacy i-line technology generations. These vendors exemplify the tier-one archetype where deep ultraviolet source development and projection lens capabilities determine competitive boundaries. ASML represents the Dutch integrated model, while Nikon and Canon anchor Japanese supply chain proximity advantages in Asian markets. Canon's concentration in KrF and i-line segments illustrates how legacy node specialization sustains defensible positions in power semiconductor and analog chip fabricator procurement cycles.
| Leading Market Players |
|---|
| Veeco Instruments |
| EV Group |
| ASML |
| Rudolph Technologies |
| HORIBA |
| Nikon Corporation |
| SUSS MicroTec |
| Applied Materials |
| Canon Inc. |
| Others |
Supply & Pricing Matrix
REACH chemical safety standards and the EU Chips Act machinery directives gate qualified supply access for DUV lithography equipment receiving European subsidy support, concentrating premium-tier pricing power among vendors with pre-certified photoresist chemistry portfolios and CE-marked scanner platforms. Buyers targeting automotive chip supply chains for European OEMs must absorb higher upfront equipment costs to secure regulatory-compliant sourcing, while non-qualifying vendors compete on price in unrestricted markets.
Pricing Analysis
Margin tightening in ArF immersion scanner contracts reflects the shift toward performance-based subscription models where vendors retain equipment title and charge per wafer processed against overlay yield targets. Three-tier pricing structure across premium, standard, and economy levels separates vendors bundling real-time computational lithography software from bare hardware lessors and refurbished KrF fleet operators. Price differentiation hinges on certification tier under METI licensing frameworks and after-sales service response commitments. Foundries in Taiwan's Science Park corridor exhibit lowest price sensitivity due to yield-critical production requirements, while Indian greenfield fabs negotiating inaugural fleet purchases demonstrate highest cost-down pressure.
Supply Chain Analysis
Regional distribution centers in Yokohama and Veldhoven coordinate hub-and-spoke patterns for projection lens systems and scanner-wafer-table assemblies, with satellite facilities in Hsinchu and Shanghai managing final alignment and field service dispatch. Optical component fabrication concentrates in Germany and Japan, where calcium fluoride crystal growth capabilities and deep ultraviolet source development anchor supply. Raw material dependencies include neon and fluorine gases for ArF excimer laser operation, high-purity synthetic quartz, and specialized photoresist polymers. Single-source vulnerability in calcium fluoride lens blanks extends refurbishment lead times. Distribution runs through direct vendor-fab relationships for immersion scanners, with third-party logistics providers handling KrF spare parts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
DUV lithography operates in a technology-transition phase where high-NA EUV systems are displacing multi-patterning economics at 5 nm and below logic nodes, compressing the addressable window for advanced ArF immersion deployments while extending fleet life demand for mature-node KrF capacity.
For Market Incumbents: Deploy computational lithography bundling as the primary retention lever against EUV substitution threats. Integrate inverse lithography technology and source-mask optimization algorithms into subscription-based performance contracts to lock in foundry relationships. Add refurbishment capacity in Kumagaya and Utsunomiya to capture Canon and Nikon domestic service advantages under METI compliance pressures. Deepen backward integration into calcium fluoride crystal supply to reduce optical component lead time vulnerability.
For New Entrants and Emerging Players: Enter via alignment metrology and overlay correction software specialization, where computational lithography talent scarcity creates white-space opportunities outside integrated scanner platforms. Target Indian greenfield fabs qualifying 28 nm capacity under PLI scheme incentives, where incumbent vendor relationships remain unformed. Pursue joint development agreements with domestic resist formulators to bypass established chemical supply chain gatekeepers.
For Investors and Strategic Acquirers: Per-wafer pricing contract proliferation in Taichung pilot programs is the leading indicator that capital-risk transfer models are gaining traction across foundry procurement. Long-term viability favors vendors with software-defined process control IP and recurring revenue architectures over hardware-dependent capital sales. Acquisition focus should center on computational lithography specialists with scanner-resist-process integration expertise. Monitor EUV adoption trajectories in DRAM capacitor formation as the primary demand compression signal for advanced DUV.
| Strategic Initiative | Industry Significance |
|---|---|
| Performance-Based Contracting Pivot | Subscription models align ASML and Nikon incentives with TSMC yield outcomes while transferring capital risk. |
| Computational Lithography Acquisition | Specialist firms with inverse lithography IP address talent scarcity constraining multi-patterning economics. |
| India Greenfield Fab Partnership | PLI scheme investments by SMIC competitors create inaugural fleet procurement opportunities outside incumbent relationships. |
| Calcium Fluoride Backward Integration | In-house crystal growth reduces German and Japanese specialty glass house dependency for projection lens refurbishment. |
| Metal Oxide Resist Co-Development | Dual-platform chemistries simplify fab inventory for EUV-DUV hybrid environments qualifying under REACH standards. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with scanner procurement directors at merchant foundries, lithography process integration engineers, photoresist formulation chemists, and aftermarket service operations managers. SEMI equipment market databases, METI export license disclosures, EU Chips Act funding award documentation, and Bureau of Industry and Commerce foreign direct product rule determinations provided demand-side validation. Bottom-up wafer start projections across Hsinchu, Tainan, Shanghai, and Wuxi fabrication corridors were cross-checked against top-down equipment spending forecasts from capital expenditure disclosures.
Data-stream reconciliation combined unit shipment tallies from scanner-wafer-table manufacturers with value estimates from service contract disclosures and refurbished equipment transaction tracking. The projection framework modeled technology generation splits across ArF immersion, KrF, and i-line platforms; application segmentation spanning semiconductor manufacturing, flat panel display, and advanced packaging; and end-user categories distinguishing wafer fabricators from IDM captive operations. CAGRs were derived from equipment replacement cycle analysis and node-specific patterning intensity coefficients. Forecast inputs included neon and fluorine gas supply corridor stability assessments and computational lithography adoption curves at 7 nm-equivalent nodes.
Revisions become necessary when METI licensing frameworks expand restriction thresholds, EUV cost curves compress faster than modeled, or geopolitical disruption severs Ukrainian and Russian noble gas supply channels. Forecasts reflect assumptions regarding export control alignment stability across Tokyo, Washington, and Brussels, alongside continued automotive semiconductor demand concentration in 28 nm to 90 nm nodes. Periodic stress-testing of base assumptions against scanner utilization rates and photoresist chemistry qualification timelines is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Equipment
Semiconductor POD Cleaner Market
Semiconductor Equipment
SMT Machine Market
Semiconductor Equipment
Vacuum Soldering System Market
Semiconductor Equipment
PVD Coaters Market
Semiconductor Equipment
UV-Based Nanoimprint Lithography (UV-NIL) System Market
Semiconductor Equipment
Asia-Pacific Extreme Ultraviolet Lithography (EUVL) Systems Market
Semiconductor Equipment
Die Attach Equipment Market
Semiconductor Equipment
Europe Semiconductor Manufacturing Equipment Market
Semiconductor Equipment
Semiconductor Process and Control Equipment Market
Semiconductor Equipment
Wafer Grinding Machine Market
Semiconductor Equipment
Plasma Etching Equipment Market
Semiconductor Equipment
150mm Probe Station Market
Semiconductor Equipment
Ion Milling System Market
Semiconductor Equipment
Focused Ion Beam Market
Semiconductor Equipment
X-Ray Lithography Equipment Market
Semiconductor Equipment
EUV Mask Inspection and Pellicle Monitoring Systems Market