
 Door Control Modules Market | 2026-2036
Door Control Modules Market Size, Share, and Industry Trends Forecast 2026-2036
Door Control Modules Market Analysis
Aluminum housings are repositioning stamped steel enclosures in door control modules, cutting unit weight and improving thermal dissipation for high-pin-count semiconductor packages. Continental AG leverages captive PCB assembly lines across Central Europe to sustain cost discipline on integrated module programs. Robert Bosch GmbH anchors its position through in-house ASIC design for motor-drive subsystems. HELLA GmbH & Co. KGaA competes on lamp-driver integration within the same module housing.
Door control modules are electromechanical assemblies that manage lock actuation, window lift, mirror adjustment, and ambient lighting within a vehicle door, typically operating on 12 V or 48 V vehicle electrical architectures with LIN or CAN bus communication protocols. Their primary commercial purpose is to consolidate distributed door functions into a single replaceable unit, reducing wiring harness complexity and assembly labor. Smart modules now lead technology migration as OEMs demand over-the-air update capability and smartphone-based entry integration. Wired technology still dominates volume shipments but carries thinner margins; wireless technology captures expanding share in premium electric vehicle programs where antenna integration and cybersecurity certification create margin pools.
NHTSA mandates for side-impact protection and power-window anti-entrapment shape module housing strength and motor-control algorithm requirements in the United States. The EU Green Deal and REACH substance restrictions push suppliers toward halogen-free substrates and recycled-content housings for modules sold into Europe. China's GB standards for electromagnetic compatibility and MIIT connected-vehicle security rules add compliance layers for modules with wireless entry. Stakeholders must decide whether to absorb certification costs across all platforms or segment module variants by regulatory jurisdiction.
Market Dynamics
Wireless access architectures are compressing development cycles for door control modules as automakers consolidate distributed door functions into single smart units with over-the-air update capability. This shift forces suppliers to reconfigure engineering teams around cybersecurity certification and antenna integration rather than traditional electromechanical design.
Growth Catalysts
- EU Green Deal substance mandates:REACH restrictions on halogenated compounds push module suppliers toward recycled-content aluminum housings and halogen-free PCB substrates, opening premium positioning for compliant suppliers.
- 48 V electrical architectures:High-voltage vehicle platforms enable faster window-lift motors and more powerful mirror-adjustment actuators, requiring upgraded semiconductor packages in door modules.
- Smartphone-based entry systems:Bluetooth Low Energy and ultra-wideband protocols are replacing physical key fobs in premium electric vehicle programs, creating pull for wireless-enabled module variants.
Market Restraints
- Semiconductor supply concentration:Motor-drive ASICs and LIN transceivers source predominantly from Taiwan and South Korea foundries, exposing module programs to geopolitical disruption and allocation constraints.
- Copper and aluminum price volatility:Wiring harnesses and thermal housings consume significant base metal volumes, compressing margins when commodity markets spike.
- Cybersecurity certification complexity:UN R155 vehicle cybersecurity regulations and China's MIIT connected-vehicle security rules impose multi-month validation timelines before wireless modules reach production.
Strategic Opportunities
- India automotive production expansion:Domestic OEMs and joint ventures are localizing module procurement under PLI scheme incentives, creating white space for suppliers with captive PCB assembly capability.
- Lamp-driver integration convergence:Ambient lighting and puddle-lamp control functions can merge into door modules, reducing separate controller counts per vehicle.
- Over-the-air revenue models:Smart modules enable subscription-based feature activation for mirror folding and window tinting, shifting supplier economics toward software-enabled recurring value.
Industry Challenges
- Embedded cybersecurity engineering scarcity:Module suppliers struggle to hire sufficient penetration-testing and secure-boot architecture specialists to meet OEM certification demands.
- Legacy LIN bus integration friction:New wireless-enabled modules must maintain backward compatibility with decade-old vehicle electrical architectures, complicating software stack maintenance.
- Multi-jurisdiction certification parallelism:Simultaneous NHTSA, REACH, and GB standard compliance requires duplicative test matrices that strain validation laboratory capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Door Control Modules Market |
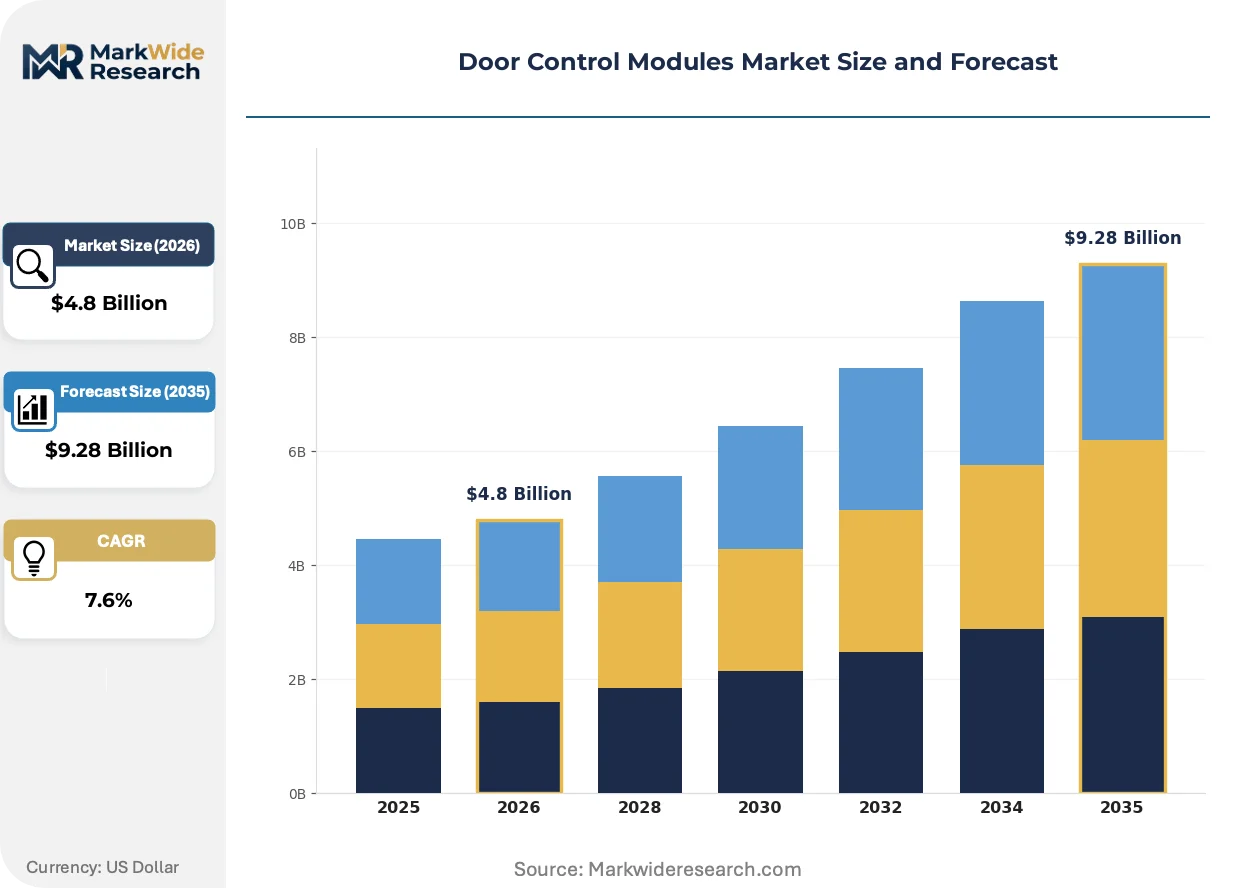
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $9.28 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Conventional Modules, Smart Modules, Integrated Modules, Standalone Modules Technology: Wired Technology, Wireless Technology, Bluetooth Technology, RFID Technology End User: Residential, Commercial, Industrial, Automotive Installation Type: New Installations, Retrofit Installations, Upgrades, Maintenance |
| Companies Covered | STMicroelectronics, HELLA GmbH & Co. KGaA, Continental AG, Valeo SA, Aptiv PLC, Robert Bosch GmbH, Texas Instruments Incorporated, ZF Friedrichshafen AG, Magna International Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Door Control Modules Market Emerging Trajectories
Module architecture is converging around domain-centralized computing, where door functions migrate from standalone controllers toward zonal gateways. This reconfiguration compresses unit volumes per vehicle while raising per-module semiconductor content and software complexity.
Ultra-wideband positioning chips are integrating into door control modules to enable centimeter-accurate smartphone-based entry without physical key fobs. Premium electric vehicle programs in Germany and California are adopting this technology first, with luxury OEMs specifying dual-antenna configurations for redundancy. The technology is integrating previously separate immobilizer and entry-control hardware into unified secure elements, reducing module count per door.
NHTSA power-window anti-entrapment mandates are tightening motor-control algorithm requirements for all vehicles sold in the United States. Suppliers must implement pinch-detection sensitivity calibration and automatic reversal logic that adds microcontroller processing overhead. The regulation most affects entry-level passenger vehicles where cost-optimized modules previously lacked force-sensing capabilities.
Automotive OEMs are consolidating module procurement under multi-year platform contracts that bundle door, seat, and mirror controllers with single-source suppliers. Tier-1 suppliers respond by acquiring specialized motor-drive firmware houses to differentiate beyond hardware cost. The shift is most visible in China, where BYD and NIO have reduced their door module vendor panels from six to two suppliers per vehicle program.
Door Control Modules Market Segmentation
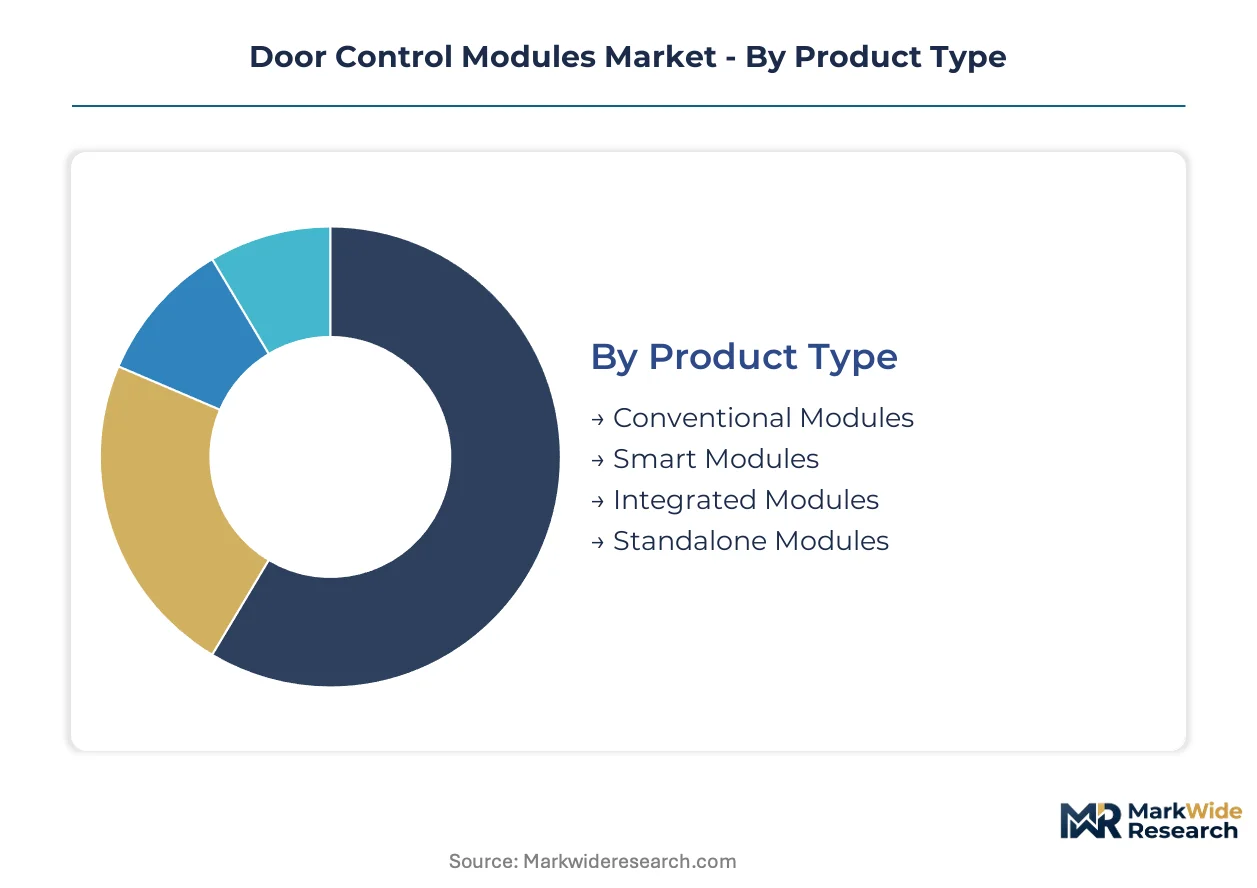
Door control modules segment across electromechanical sophistication, connectivity protocols, and vehicle lifecycle stages. Each axis carries distinct margin profiles and certification burdens that reshape supplier resource allocation.
Product Type:
Electromechanical sophistication determines semiconductor content, software stack complexity, and per-unit margin capture in door control modules.
- Smart Modules:LIN/CAN bus controllers with over-the-air firmware update capability and smartphone entry integration dominate premium electric vehicle programs. Demand concentrates in Germany and California where NIO and Mercedes-Benz specify unified secure elements for immobilizer and entry control.
- Conventional Modules:Discrete electromechanical controllers managing lock actuation and window lift without network connectivity. Volume shipments persist in entry-level internal combustion platforms across India and Brazil where cost optimization overrides feature expansion.
- Integrated Modules:Consolidated door, seat, and mirror controllers under single housings.
- Standalone Modules:Single-function controllers for legacy vehicle electrical architectures.
Mature deployment sits with Conventional Modules. Newer deployment is concentrated in Smart Modules.
Technology:
Connectivity architecture selection gates entry into specific OEM supply chains and determines cybersecurity certification scope.
- Wireless Technology:Ultra-wideband and Bluetooth Low Energy protocols enable smartphone-based entry without physical key fobs. Germany and China lead specification where MIIT connected-vehicle security rules and UN R155 impose multi-month validation timelines before production release.
- Bluetooth Technology:Low-energy stacks for proximity-based entry authorization and over-the-air diagnostic access. BYD and NIO in China specify dual-antenna configurations for redundancy in luxury electric vehicle lines.
- Wired Technology:LIN bus and dedicated wiring harness architectures for legacy compatibility.
- RFID Technology:Passive transponder systems for basic entry authorization in fleet vehicles.
Wired Technology anchors current volume. Wireless Technology is climbing the fastest as OEMs consolidate distributed functions into single smart units.
End User:
Customer category dictates reliability specifications, volume scale, and aftermarket service expectations for module suppliers.
- Automotive:Passenger and commercial vehicle OEMs requiring 12 V or 48 V electrical compatibility with domain-centralized computing migration. Procurement concentrates in Germany, China, and the United States where tier-1 suppliers co-locate engineering centers with major automakers.
- Commercial:Fleet operators and commercial building access systems.
- Industrial:Heavy equipment and agricultural machinery with sealed housing requirements.
- Residential:Smart home entry systems with lower automotive-grade reliability thresholds.
Automotive represents the dominant revenue pool. Commercial applications are gaining share fastest in fleet electrification programs.
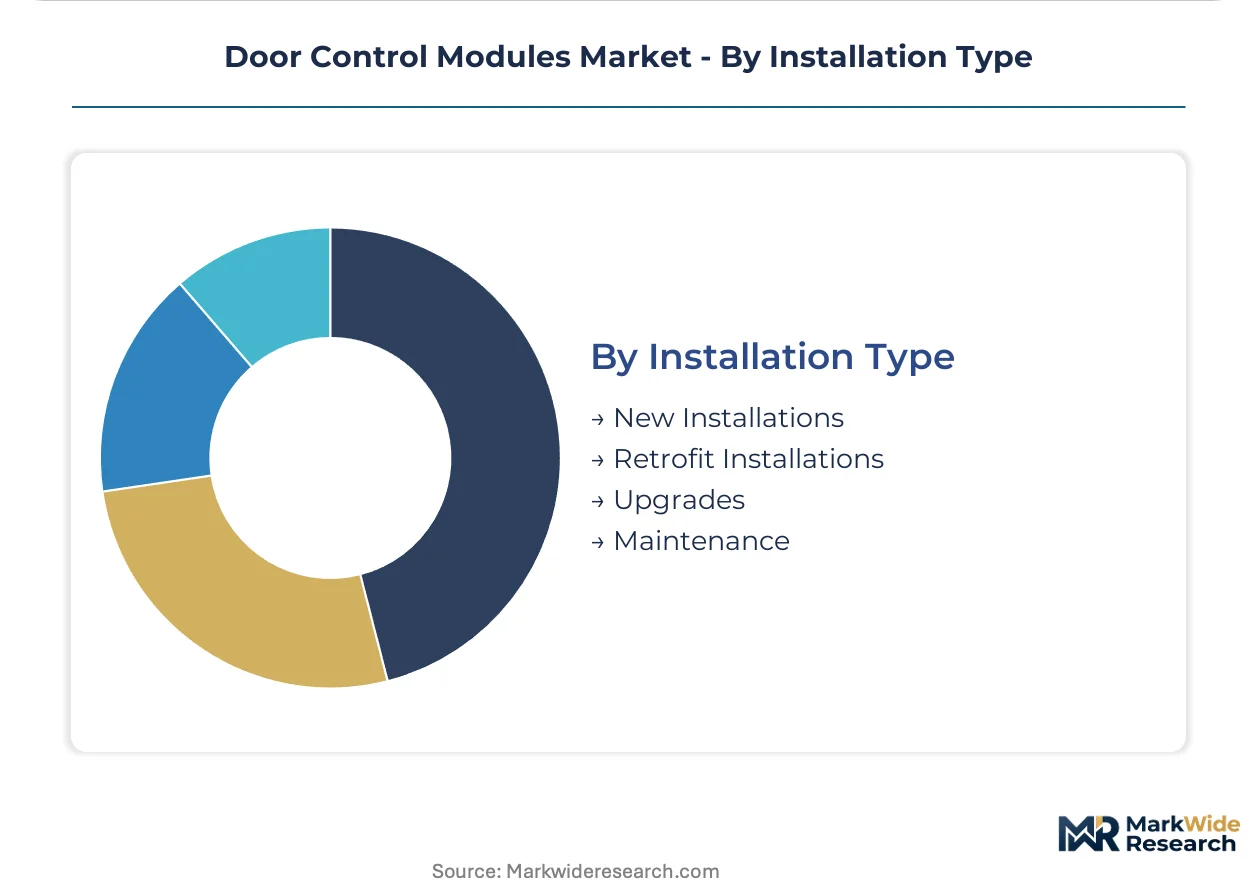
Installation Type:
Lifecycle stage determines module specification flexibility, backward compatibility requirements, and channel economics.
- New Installations:Factory-fit modules specified during vehicle platform development with full feature enablement. China and Germany concentrate volume where 48 V electrical architectures enable faster window-lift motors and upgraded semiconductor packages.
- Retrofit Installations:Aftermarket replacement modules for legacy vehicles requiring LIN bus backward compatibility.
- Upgrades:Feature expansion modules enabling subscription-based mirror folding and window tinting activation.
- Maintenance:Warranty replacement units with identical specification to original equipment.
New Installations command the highest per-unit margins. Upgrades are expanding most quickly through software-enabled recurring revenue models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive special economic zones in China and Germany concentrate module engineering capacity alongside major OEM assembly plants. Tier-1 suppliers co-locate development centers within these zones to compress prototype-to-production cycles. Tax incentives for electric vehicle component manufacturing accelerate facility investments in designated industrial corridors.
China
BYD and NIO consolidate supplier panels from six to two vendors per vehicle program, concentrating procurement power. MIIT connected-vehicle security rules impose multi-month validation timelines for wireless-enabled modules before production release. The Yangtze River Delta hosts engineering centers where tier-1 suppliers develop ultra-wideband antenna integration for smartphone-based entry systems.
Germany
Mercedes-Benz specifies unified secure elements combining immobilizer and entry control in premium electric vehicle lines. EU Green Deal REACH restrictions on halogenated compounds push suppliers toward recycled-content aluminum housings and halogen-free PCB substrates. Bavaria anchors Continental AG's captive PCB assembly lines serving integrated module programs across Central Europe.
United States
NHTSA mandates for side-impact protection and power-window anti-entrapment shape module housing strength requirements for all vehicles sold domestically. California luxury electric vehicle programs adopt dual-antenna ultra-wideband configurations for redundant smartphone-based entry. Michigan-based engineering centers align module development with Detroit Three platform cycles.
India
Domestic OEMs and joint ventures localize module procurement under PLI scheme incentives for automotive component manufacturing. BIS standards for electromagnetic compatibility add compliance verification steps for imported semiconductor packages. Tamil Nadu and Gujarat industrial corridors attract suppliers with captive PCB assembly capability seeking white space expansion.
South Korea
Foundries in Taiwan and South Korea supply motor-drive ASICs and LIN transceivers, exposing module programs to geopolitical allocation constraints. Hyundai-Kia platform consolidation creates volume concentration for smart module variants with over-the-air update capability. Seoul Capital Area engineering centers specialize in cybersecurity certification for wireless entry architectures.
Door Control Modules Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated tier-1 suppliers commanding premium electric vehicle programs and discrete component houses serving cost-optimized internal combustion platforms. The vendor base organizes around three strategic archetypes: semiconductor-integrated module specialists, electromechanical assembly contract manufacturers, and domain-centralized computing platform providers. Consolidation pressure intensifies as OEMs bundle door, seat, and mirror controllers under single-source contracts. Capacity expansion and strategic partnerships represent the dominant competitive moves, with suppliers acquiring motor-drive firmware houses to differentiate beyond hardware cost.
Among European-based integrated suppliers, Continental AG and Robert Bosch GmbH occupy positions exemplifying the semiconductor-integrated archetype, while HELLA GmbH & Co. KGaA represents specialists competing on lamp-driver integration within unified module housings. These entities anchor the premium-tier vector where aluminum thermal housings and in-house ASIC design create defensible positioning. Texas Instruments Incorporated and STMicroelectronics sit within the semiconductor supplier tier, providing motor-drive components and LIN transceivers that module integrators incorporate into finished assemblies. The competitive dynamic forces tier-1 integrators to deepen backward integration into PCB assembly while semiconductor houses push downstream toward reference design partnerships.
| Leading Market Players |
|---|
| STMicroelectronics |
| HELLA GmbH & Co. KGaA |
| Continental AG |
| Valeo SA |
| Aptiv PLC |
| Robert Bosch GmbH |
| Texas Instruments Incorporated |
| ZF Friedrichshafen AG |
| Magna International Inc. |
| Others |
Supply Flow & Price Mechanics
EU Green Deal REACH restrictions on halogenated compounds gate qualified supply for door control modules destined for European OEMs, compressing vendor pools to certified suppliers commanding premium positioning for compliant aluminum housings and halogen-free PCB substrates.
Pricing Analysis
Short lead-time premiums separate expedited wireless-enabled module deliveries from standard-cycle conventional units stocked for legacy platforms. Three-tier pricing structure across premium smart modules, standard integrated variants, and economy conventional controllers reflects cybersecurity certification burden and semiconductor content differentials. Price differentiation hinges on UN R155 validation status and 48 V architecture compatibility. Pricing pressure stems from Taiwan and South Korea foundry allocation constraints forcing spot-market premiums for motor-drive ASICs. Fleet operators in commercial segments exhibit highest price sensitivity; luxury electric vehicle OEMs in Germany and California show least.
Supply Chain Analysis
Workforce availability constraints in Bavaria and Tamil Nadu industrial corridors limit captive PCB assembly expansion for tier-1 suppliers pursuing integrated module programs. Geographic supply concentrates in Germany, China, and South Korea where engineering centers co-locate with OEM assembly plants. Raw material dependencies span copper wiring harnesses, aluminum thermal housings, and semiconductor packages from Taiwan foundries. Single-source vulnerability in LIN transceiver supply exposes module programs to geopolitical disruption. Distribution runs through tier-1 direct contracts with OEM platform teams, bypassing traditional aftermarket channels for new installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Door control module supply is tightening around semiconductor packaging capacity and cybersecurity engineering scarcity, propping pricing for qualified suppliers while squeezing margin at uncertified competitors.
For Market Incumbents: Acquire motor-drive firmware houses to differentiate beyond hardware cost as OEMs consolidate supplier panels from six to two vendors per vehicle program. Deepen backward integration into captive PCB assembly lines across Central Europe to sustain cost discipline. Prioritize UN R155 and MIIT cybersecurity certification investment to defend position against emerging semiconductor-integrated specialists from Asia-Pacific. For New Entrants and Emerging Players: Capture white space in India's PLI scheme corridors where domestic OEMs localize procurement and qualified supplier pools remain thin. Target aftermarket retrofit modules for legacy LIN bus architectures requiring backward compatibility. Penetrate through engineering center co-location with emerging electric vehicle platforms in Tamil Nadu and Gujarat industrial belts. For Investors and Strategic Acquirers: OEM supplier panel consolidation from six to two vendors per program is the leading indicator that module integration specialists with captive firmware capability will command acquisition premiums. Long-term viability favors semiconductor-integrated tier-1s with in-house ASIC design and zonal gateway positioning. Monitor ultra-wideband antenna integration adoption rates in premium German and California electric vehicle lines as inflection signal for wireless-enabled module demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Cybersecurity Certification Investment | UN R155 and MIIT validation unlocks wireless-enabled module supply to Mercedes-Benz and NIO programs. |
| Motor-Drive Firmware Acquisition | Specialized software houses differentiate tier-1s beyond hardware cost in consolidated procurement. |
| Captive PCB Assembly Expansion | Continental AG's Central European lines demonstrate cost discipline for integrated module programs. |
| Ultra-Wideband Antenna Integration | Dual-antenna configurations specified by BYD and luxury OEMs enable smartphone-based entry. |
| Halogen-Free Substrate Transition | REACH compliance opens premium positioning for European-bound module variants. |
Methodological Framework
Multi-period observation of OEM supplier panel consolidation, semiconductor allocation patterns, and cybersecurity certification timelines anchored the trend analysis, supplemented by interviews with tier-1 supplier procurement directors, OEM platform engineers, aftermarket distributors, and semiconductor foundry account managers. Secondary validation drew from vehicle production databases, IHS Markit registration data, NHTSA regulatory filings, EU REACH substance restriction updates, and MIIT connected-vehicle security guidance. Bottom-up module shipment estimates triangulated against top-down automotive production forecasts.
Input-output matrices mapped semiconductor content per module variant, certification burden by regulatory jurisdiction, and OEM procurement concentration across the projection horizon. Segmentation dimensions modeled include electromechanical sophistication tier, connectivity protocol architecture, vehicle lifecycle stage, and regional production cluster. CAGRs derived from slope analysis of platform adoption curves and technology substitution rates. Forecast inputs incorporated 48 V electrical architecture penetration and ultra-wideband entry system specification trends.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to Taiwan foundry allocation constraints, EU Green Deal substance mandate expansion, and geopolitical friction affecting semiconductor supply. Forecasts reflect documented assumptions regarding OEM platform cycle timing and certification pathway duration. Material deviation in foundry capacity expansion or cybersecurity regulation enforcement warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Canada Digital Thermometer Market
Sensors and Controls
Global Wireless Brain Sensors Market
Sensors and Controls
Global Acceleration and Yaw Rate Sensors Market
Sensors and Controls
Asia-Pacific Bulk Acoustic Wave Sensors Market
Sensors and Controls
North America Wireless Sensors Market
Sensors and Controls
Capacitive Proximity Sensor Market
Sensors and Controls
Area Sensor Market
Sensors and Controls
Industrial Combustion Control Components and Systems Market
Sensors and Controls
Sensor Screwdrivers Market
Sensors and Controls
Global E-Nose Market
Sensors and Controls
Smart Hydrophone Market
Sensors and Controls
RET Controller Market
Sensors and Controls
Smart Visor Market
Sensors and Controls
Glucose Sensor Market
Sensors and Controls
Absolute Pressure Sensor Market
Sensors and Controls
Thermistor Temperature Sensor Market