
 Pulsed Laser Deposition Systems Market | 2026-2036
Pulsed Laser Deposition Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Pulsed Laser Deposition Systems Market Analysis
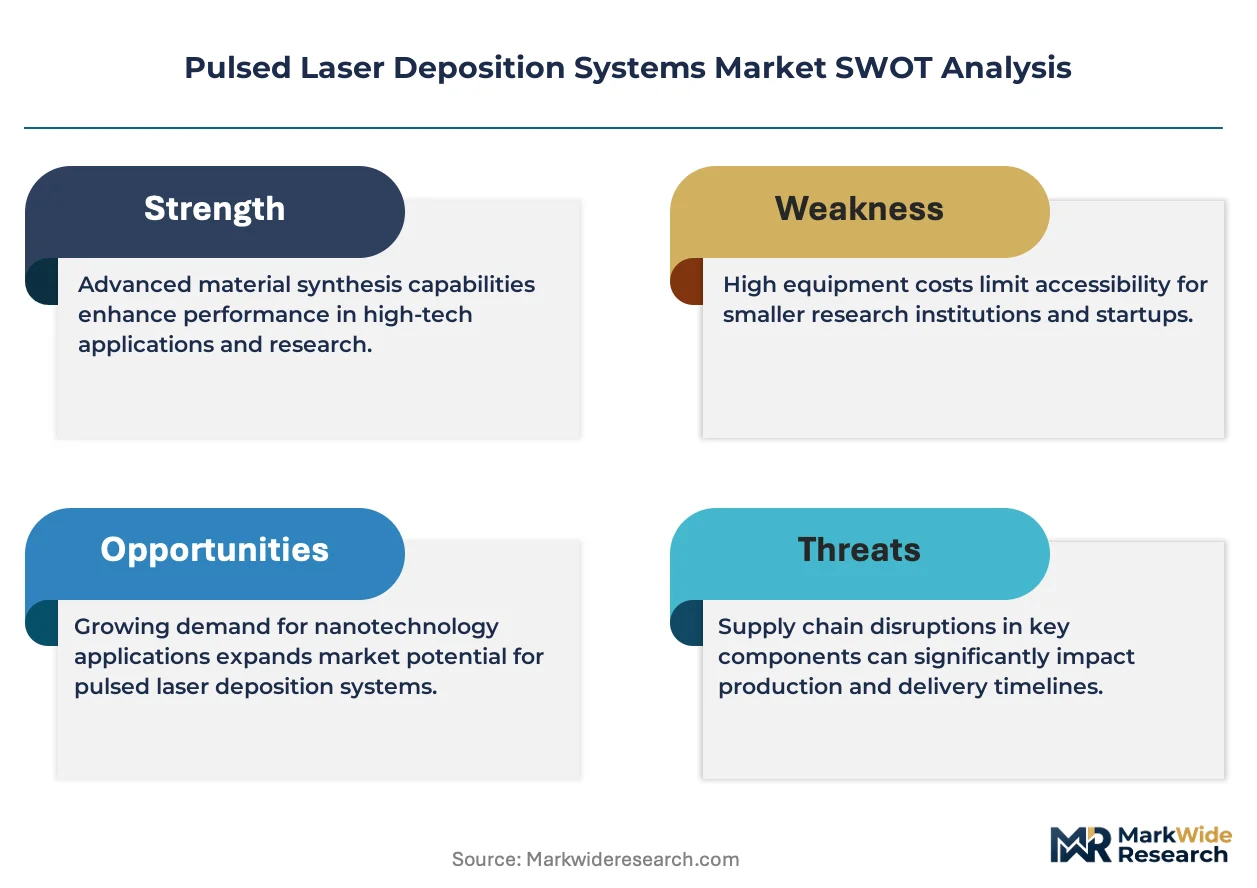
Complex oxide ceramics is rebalancing cost-performance trade-offs in high-temperature superconductor deposition. Veeco leverages integrated source-substrate architectures to sustain North American laboratory market presence. PVD Products anchors its position through specialized multi-target carousel designs for combinatorial materials screening. Scienta Omicron differentiates via ultrahigh-vacuum compatibility that extends tool utility into surface science cross-selling.
Pulsed laser deposition systems employ high-energy excimer or solid-state lasers to ablate material from a ceramic or metallic target, depositing stoichiometric thin films onto heated substrates in vacuum environments with typical operating pressures below 10^-3 mbar. These systems enable epitaxial growth of multicomponent oxides, nitrides, and complex functional materials for next-generation electronics and energy applications. Physical vapor deposition variants dominate current installed base economics, while atomic layer deposition hybrid configurations capture the fastest-growing segment as chipmakers demand sub-nanometer thickness precision. Superconductor end users concentrate margin pools through cryogenic quantum computing substrate contracts, whereas coatings applications remain mature with replacement-cycle purchasing patterns.
FDA device classification rules and EPA hazardous waste protocols from ablated target materials shape system design and operational compliance for U.S. installations. REACH substance restrictions in Europe constrain target material sourcing, while CE marking mandates govern vacuum chamber safety interlocks and laser enclosure standards. ISO 14644 cleanroom compatibility requirements increasingly filter procurement specifications across academic and industrial buyer segments. Stakeholders must monitor emerging export control frameworks targeting dual-use deposition technologies and pre-position service infrastructure accordingly.
Market Dynamics
Oxide superconductors are tightening material efficiency mandates across quantum device fabrication, while Fraunhofer institutes in Germany's Dresden cluster anchor applied research procurement and redirect vendor development priorities toward epitaxial precision specifications.
Growth Catalysts
- EU Green Deal material efficiency mandates:These frameworks accelerate metallic thin film replacement with complex oxide ceramics in superconductor deposition, tightening alignment requirements for stoichiometric thin film production.
- Cryogenic quantum computing substrate contracts:Superconductor end users concentrate margin pools through multi-year procurement agreements that lock in specialized PLD tool configurations and service infrastructure.
- Atomic layer deposition hybrid configurations:Chipmakers demanding sub-nanometer thickness precision are pulling fastest-growing segment adoption across physical vapor deposition installed base economics.
Market Restraints
- Excimer laser source cost volatility:High-energy solid-state and excimer laser systems represent concentrated capital expenditure with limited supplier diversification, compressing laboratory budget flexibility.
- REACH substance restrictions:European target material sourcing faces constrained feedstock availability from ECHA-regulated precursor chemicals, extending procurement timelines for oxide and nitride targets.
- Atomic layer deposition precision substitution:ALD systems threaten PLD market penetration in sub-nanometer thickness applications where conformal coverage requirements exceed ablation-based stoichiometric control.
Strategic Opportunities
- Combinatorial materials screening expansion:Multi-target carousel designs enable rapid composition mapping for battery electrolyte and catalyst discovery, opening academic-industrial collaborative procurement channels.
- India PLI scheme semiconductor manufacturing:Production-linked incentives for domestic chip fabrication create virgin installed base demand for epitaxial growth tools serving compound semiconductor foundries.
- Surface science cross-selling integration:Ultrahigh-vacuum compatible PLD systems extend utility into scanning probe microscopy and electron spectroscopy workflows, capturing shared infrastructure budgets.
Industry Challenges
- Epitaxial growth technician scarcity:Specialized expertise in laser fluence optimization and substrate temperature profiling remains concentrated in national laboratory and elite academic programs, constraining operational scaling.
- ISO 14644 cleanroom certification timelines:Extended validation protocols for vacuum chamber safety interlocks and laser enclosure standards delay installation acceptance and revenue recognition cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pulsed Laser Deposition Systems Market |
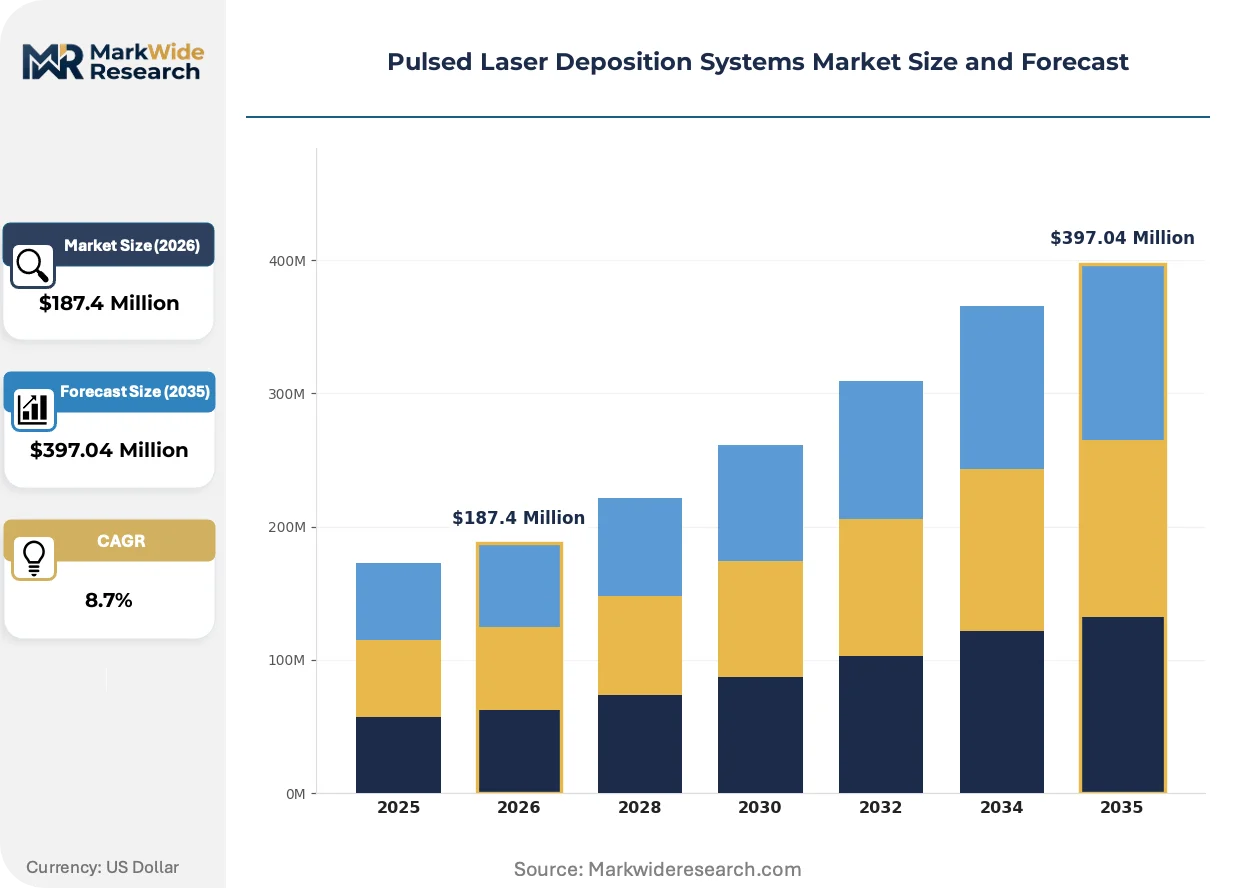
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Physical Vapor Deposition, Molecular Beam Epitaxy, Atomic Layer Deposition, Thermal Evaporation End User: Semiconductors, Optoelectronics, Coatings, Superconductors Technology: Laser Source, Target Material, Substrate Type, Process Control Application: Thin Film Growth, Nanostructuring, Surface Modification, Device Fabrication |
| Companies Covered | SVT Associates, DE Technology, AdNaNoTek, Solmates, Scienta Omicron, PVD Products, Neocera, Veeco, BlueWave Semiconductors, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pulsed Laser Deposition Systems Market Emerging Trajectories
Hybrid deposition architectures are compressing traditional tool category boundaries, as chipmakers and national laboratories demand multi-modal systems that combine pulsed laser ablation with atomic layer precision within unified vacuum platforms.
Combinatorial PLD systems equipped with automated multi-target carousels are expanding into high-throughput materials discovery workflows. National laboratories and battery research consortia are adopting these configurations at accelerated procurement cycles. This expansion is compressing traditional sequential deposition timelines and enabling parallel composition mapping across ternary and quaternary oxide phase spaces.
REACH substance restrictions and EU Green Deal material efficiency mandates are reshaping target material supply chains. ECHA-regulated precursor limitations constrain feedstock availability for complex oxide ceramics. European superconductor device fabricators are responding by qualifying alternative stoichiometric targets and locking long-term supply agreements with certified rare-earth processors.
Service unbundling is fragmenting traditional capital equipment purchasing patterns. Cryogenic quantum computing substrate contractors are separating tool acquisition from maintenance and upgrade pathways, favoring vendors with modular source-substrate architectures. This behavioral shift concentrates most visibly in Germany's Dresden semiconductor cluster, where Fraunhofer institutes negotiate performance-based service tiers independent of initial system procurement.
Pulsed Laser Deposition Systems Market Segmentation
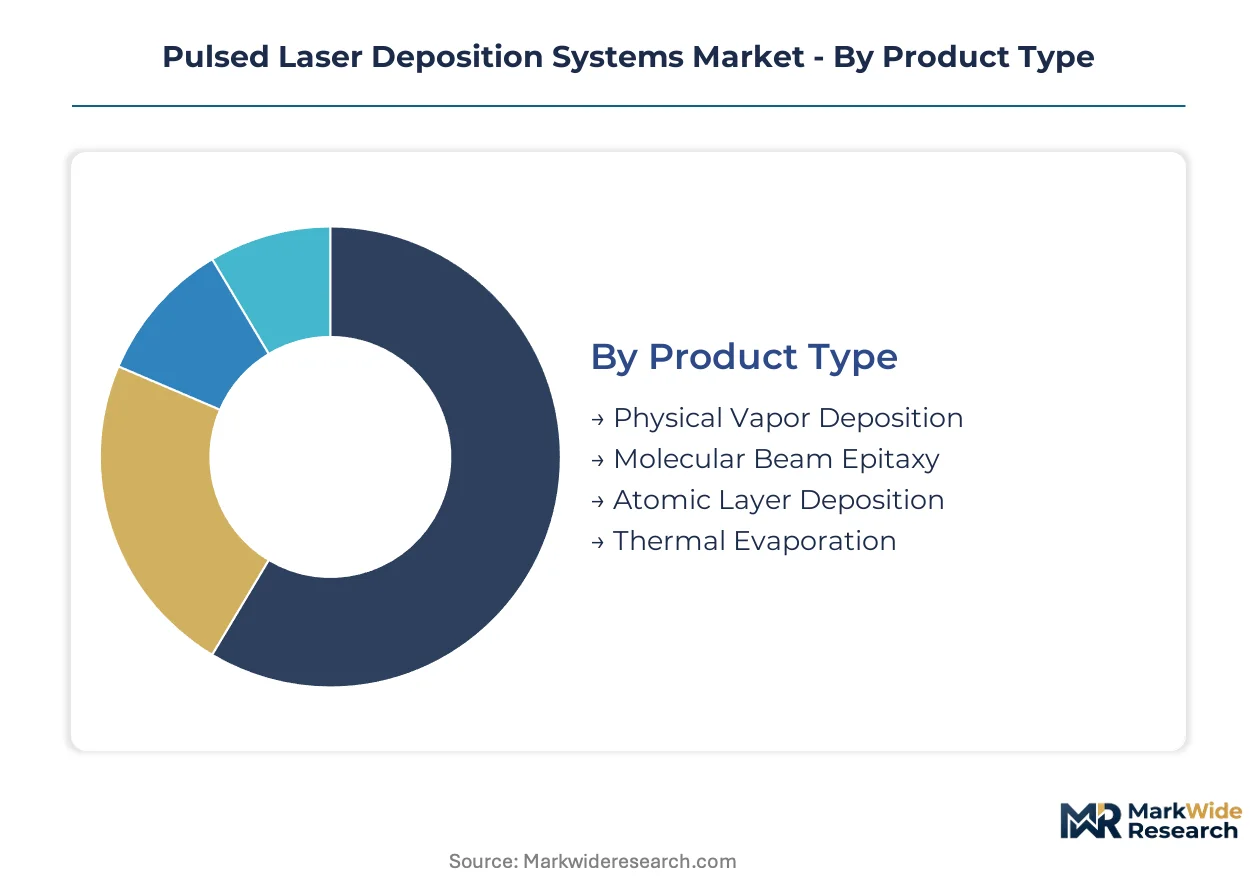
PLD system procurement diverges sharply across buyer technical requirements and operational scale. Laboratory researchers prioritize stoichiometric precision for oxide ceramics, while semiconductor foundries demand throughput compatibility with existing cleanroom infrastructure.
Product Type:
Capital allocation thresholds separate academic buyers from industrial volume purchasers in this category.
- Physical Vapor Deposition:Dominant installed base economics leverage sputtering and evaporation variants for metallic thin film production. Fraunhofer institutes in Germany's Dresden cluster anchor procurement for quantum device fabrication, though EU Green Deal material efficiency mandates are accelerating metallic thin film replacement with complex oxide ceramics.
- Atomic Layer Deposition:Hybrid configurations with PLD modules capture chipmaker demand for sub-nanometer thickness precision. India's PLI scheme for domestic semiconductor manufacturing is pulling fastest-growing segment adoption as compound semiconductor foundries qualify epitaxial growth tools.
- Molecular Beam Epitaxy:Ultrahigh-vacuum compatibility enables surface science cross-selling into scanning probe microscopy workflows.
- Thermal Evaporation:Mature replacement-cycle purchasing patterns characterize coatings applications with limited differentiation.
Physical Vapor Deposition leads volumes today; Atomic Layer Deposition is gaining share fastest.
End User:
Margin concentration varies dramatically by technical complexity and contract duration.
- Superconductors:Cryogenic quantum computing substrate contracts lock in multi-year procurement agreements with specialized tool configurations. Germany's Dresden semiconductor cluster concentrates margin pools through performance-based service tiers negotiated by Fraunhofer institutes.
- Semiconductors:Compound semiconductor foundries in India drive virgin installed base demand under production-linked incentive schemes. REACH substance restrictions constrain European target material sourcing, extending procurement timelines for oxide and nitride precursors.
- Optoelectronics:LED and laser diode manufacturers require epitaxial precision for III-V compound deposition.
- Coatings:Mature end-use with replacement-cycle purchasing patterns and limited service unbundling.
Superconductors command premium pricing; Semiconductors show steepest expansion trajectory.
Technology:
System architecture choices determine operational flexibility and cross-selling potential.
- Laser Source:Excimer and solid-state laser configurations represent concentrated capital expenditure with limited supplier diversification. High-energy source cost volatility compresses laboratory budget flexibility across North American and European installations.
- Process Control:Automated fluence optimization and substrate temperature profiling enable technician-scarce operational scaling. ISO 14644 cleanroom certification timelines delay installation acceptance, extending revenue recognition cycles for vendors.
- Target Material:ECHA-regulated precursor limitations constrain feedstock availability for complex oxide ceramics.
- Substrate Type:Heated substrate compatibility determines epitaxial growth quality for multicomponent oxides.
Laser Source dominates capital allocation; Process Control is climbing the fastest.
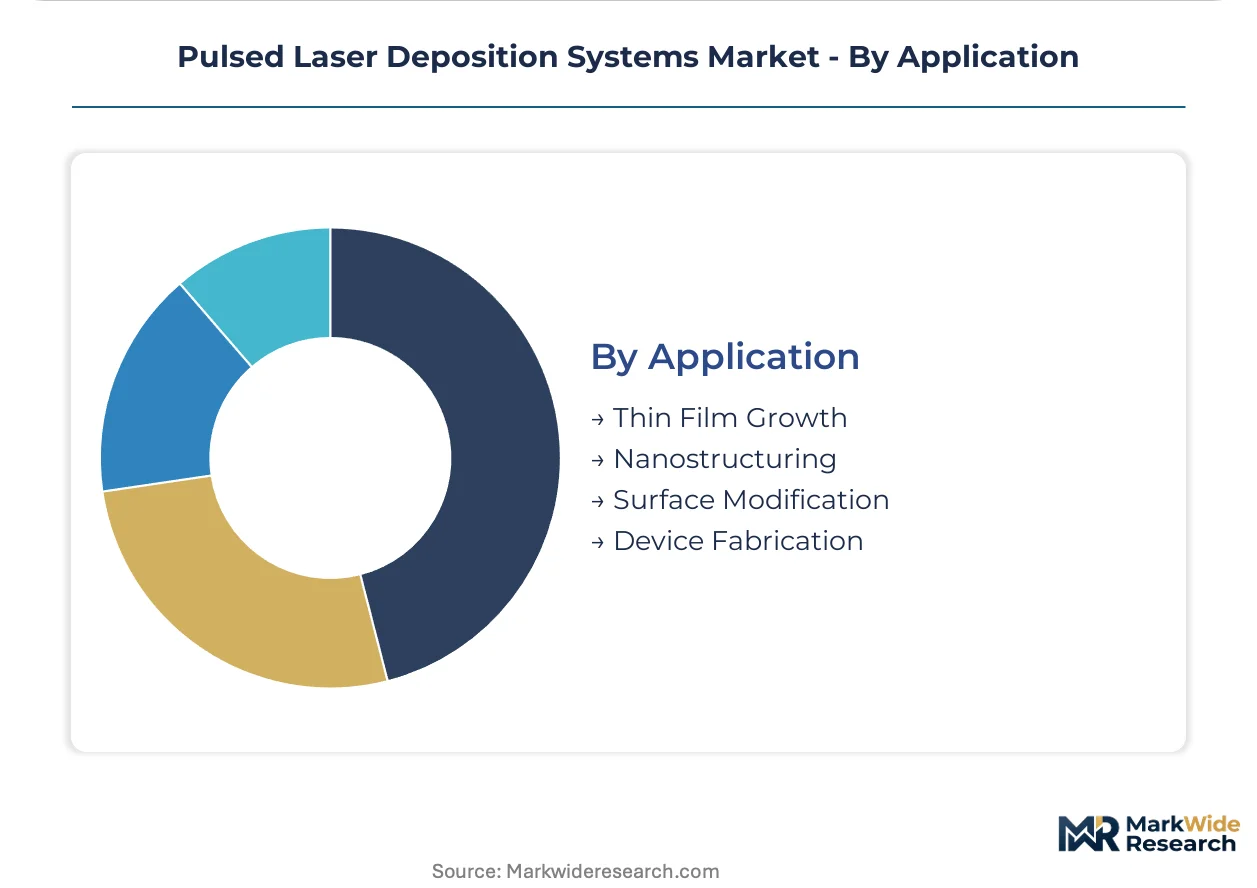
Application:
Technical specifications diverge between research discovery and production transfer workflows.
- Thin Film Growth:Stoichiometric deposition of multicomponent oxides, nitrides, and complex functional materials enables next-generation electronics. National laboratories adopt combinatorial multi-target carousel designs for high-throughput materials discovery, compressing sequential deposition timelines.
- Device Fabrication:Quantum device fabrication tightens alignment requirements as oxide superconductors displace metallic thin films. FDA device classification rules and EPA hazardous waste protocols shape system design for U.S. installations.
- Surface Modification:Functionalization workflows extend tool utility into battery electrolyte and catalyst research.
- Nanostructuring:Pulsed laser ablation enables precise material removal for patterned device architectures.
Thin Film Growth leads procurement volumes; Device Fabrication is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's Dresden semiconductor cluster concentrates quantum device fabrication demand for complex oxide ceramics, with Fraunhofer institutes anchoring applied research procurement. National laboratories in the United States and compound semiconductor foundries in India are accelerating parallel installed base expansion.
United States
Cryogenic quantum computing substrate contracts drive multi-year procurement agreements for specialized PLD configurations. FDA device classification rules and EPA hazardous waste protocols from ablated target materials shape system design compliance. National laboratories in the San Francisco Bay Area and Greater Boston adopt combinatorial multi-target carousel designs for high-throughput materials discovery.
Germany
Fraunhofer institutes negotiate performance-based service tiers independent of initial system procurement, fragmenting traditional capital equipment purchasing patterns. REACH substance restrictions constrain feedstock availability for oxide and nitride targets from ECHA-regulated precursor chemicals. The Dresden semiconductor cluster anchors European demand for epitaxial precision specifications in superconductor device fabrication.
India
Production-linked incentives for domestic semiconductor manufacturing create virgin installed base demand for epitaxial growth tools. BIS certification requirements and CDSCO oversight extend equipment qualification timelines for compound semiconductor foundries. Karnataka and Telangana host emerging fabrication facilities qualifying atomic layer deposition hybrid configurations.
Japan
METI funding for next-generation electronics sustains laboratory procurement for multicomponent oxide deposition. JIS standards and PMDA device regulations govern cleanroom compatibility specifications for industrial installations. The Kanto region around Tokyo maintains concentrated research infrastructure for surface science cross-selling integration.
South Korea
Compound semiconductor foundries demand sub-nanometer thickness precision for III-V optoelectronics manufacturing. MFDS oversight and national strategic technology programs shape import qualification for dual-use deposition equipment. The Seoul Capital Area concentrates corporate R&D procurement for atomic layer deposition hybrid system adoption.
Pulsed Laser Deposition Systems Market Vendor Landscape
Global majors compete with regional champions across laser source integration and vacuum platform architectures. The vendor base separates into three tiers: integrated equipment conglomerates with multi-modal deposition portfolios, specialized PLD fabricators with carousel-based combinatorial systems, and surface science instrument providers leveraging ultrahigh-vacuum compatibility. Strategic moves concentrate on modular source-substrate architectures for service unbundling and geographic expansion into India's PLI-driven semiconductor manufacturing zones.
Among North American equipment specialists, Veeco and PVD Products occupy positions within the integrated architecture tier, while Scienta Omicron exemplifies the surface science cross-selling archetype through ultrahigh-vacuum platform compatibility. These three anchors represent divergent strategic vectors: laboratory market presence through source-substrate integration, combinatorial screening specialization via multi-target carousel designs, and electron spectroscopy workflow extension respectively.
| Leading Market Players |
|---|
| SVT Associates |
| DE Technology |
| AdNaNoTek |
| Solmates |
| Scienta Omicron |
| PVD Products |
| Neocera |
| Veeco |
| BlueWave Semiconductors |
| Others |
Supply Flow & Price Mechanics
Excimer laser source costs propagate downstream through three-tier pricing structures across premium, standard, and economy levels, with high-energy solid-state configurations commanding premium allocations from national laboratory buyers while budget-constrained academic programs cluster in economy tiers.
Pricing Analysis
Input-cost pass-through from ECHA-regulated precursor chemicals tightens margins on complex oxide ceramic targets, compressing standard-tier pricing. Price differentiation separates CE-marked industrial systems with ISO 14644 cleanroom certification from laboratory-grade configurations lacking vacuum interlock redundancy. Pricing pressure stems from atomic layer deposition substitution threats in sub-nanometer applications. Semiconductor foundries exhibit lowest price sensitivity due to production-linked incentive procurement timelines, whereas independent research laboratories face acute budget elasticity.
Supply Chain Analysis
India's PLI scheme domestic-content mandates reshape sourcing patterns for compound semiconductor foundries qualifying epitaxial growth tools. Laser source manufacturing concentrates in Germany, Japan, and the United States, while rare-earth oxide feedstock processing anchors in China and Australia. Supply chain risk centers on single-source vulnerability for high-energy excimer laser tubes. Distribution runs through direct vendor relationships with national laboratories and Fraunhofer institutes, bypassing traditional equipment distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in service unbundling and modular upgrade pathways, as cryogenic quantum computing substrate contractors separate tool acquisition from performance-based maintenance tiers.
For Market Incumbents: Anchor market position through backward integration into rare-earth oxide target processing, captive supply of ECHA-compliant precursor chemicals mitigates REACH restriction exposure. Defend against atomic layer deposition substitution by embedding combinatorial screening capabilities into base system architectures. Prioritize modular source-substrate designs that enable post-sale service tier negotiation independent of initial procurement. For New Entrants and Emerging Players: Automated multi-target carousel technology offers entry wedge into battery electrolyte and catalyst discovery workflows, white-space concentrates in academic-industrial collaborative procurement channels. Target India's emerging compound semiconductor foundries under PLI scheme qualification timelines. Lead with surface science cross-selling integration as go-to-market angle, extending ultrahigh-vacuum compatibility into scanning probe microscopy infrastructure budgets. For Investors and Strategic Acquirers: Consolidation pressure builds where service unbundling fragments traditional capital equipment purchasing patterns. Long-term viability favors vendors with installed base density in Germany's Dresden cluster and national laboratory networks. Acquisition target archetype: specialized PLD fabricators with carousel-based combinatorial systems and established Fraunhofer institute relationships. Monitor India's BIS certification completion rates as inflection indicator for virgin installed base demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rare-Earth Processing | Captive supply of ECHA-compliant precursors insulates margin from REACH volatility. |
| Modular Source-Substrate Architecture Development | Service unbundling captures performance-based tiers from Fraunhofer procurement patterns. |
| Combinatorial Screening Capability Embedding | Multi-target carousels defend against ALD substitution in materials discovery workflows. |
| India PLI Scheme Qualification Pathway | BIS certification completion opens virgin installed base at compound semiconductor foundries. |
| Surface Science Cross-Selling Integration | Ultrahigh-vacuum compatibility extends into electron spectroscopy infrastructure budgets. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with thin film deposition engineers, cleanroom facility managers, semiconductor foundry procurement leads, and national laboratory instrumentation officers with secondary validation from SEC equipment manufacturer filings, ISO certification registries, ECHA substance restriction databases, and customs trade data for laser source imports. Bottom-up installed base enumeration and top-down market sizing triangulated volume estimates.
Segment-weighting approaches distributed value across physical vapor deposition, atomic layer deposition, molecular beam epitaxy, and thermal evaporation product categories, with further stratification by superconductor, semiconductor, optoelectronics, and coatings end-use segments. Technology dimensions incorporated laser source configuration, process control automation, target material composition, and substrate heating capability. CAGRs derived from regression analysis against semiconductor capital expenditure cycles and quantum computing substrate contract announcements. Industry-specific forecast inputs included EU Green Deal material efficiency mandate compliance timelines and India's PLI scheme disbursement schedules.
The model holds under stable rare-earth oxide supply conditions and continued REACH enforcement; deviation in excimer laser source supplier consolidation or export control framework expansion would shift trajectory. Forecasts reflect documented assumptions regarding Fraunhofer institute procurement continuity and national laboratory budget authorization patterns. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Equipment
I-Line Lithography Market
Semiconductor Equipment
Global Resist Processing Equipment Market
Semiconductor Equipment
Vapor Blasting Machine Market
Semiconductor Equipment
Solar Texturing Equipment Market
Semiconductor Equipment
Analog and Digital IC Development Tools Market
Semiconductor Equipment
Die Bonder Equipment Market
Semiconductor Equipment
Semiconductor Laser Equipment Market
Semiconductor Equipment
Semiconductor Manufacturing Equipment Market
Semiconductor Equipment
Underfill Dispenser Market
Semiconductor Equipment
Global Sputtering Equipment Market
Semiconductor Equipment
FOUP Load Port Market
Semiconductor Equipment
Molecular Beam Epitaxy System Market
Semiconductor Equipment
Partition Inserter Machines Market
Semiconductor Equipment
Global Microelectronics Cleaning Equipment Market
Semiconductor Equipment
North America Semiconductor Etch Equipment Market
Semiconductor Equipment
Vacuum Spin Coaters Market