
 Electron Beam Lithography Machine Market | 2026-2036
Electron Beam Lithography Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Electron Beam Lithography Machine Market Insights
Sub-10nm resolution requirements in advanced node photomask fabrication is narrowing the gap between electron beam lithography and optical alternatives for critical-layer patterning. JEOL Ltd. leverages its long-standing installed base in semiconductor research facilities across Japan and Taiwan. Raith GmbH sustains its position in European university labs and nanotechnology centers through specialized research tool configurations. Nuflare Technology Inc. competes aggressively in the mask writer segment where throughput and pattern fidelity determine procurement decisions among leading foundries.
An electron beam lithography machine directs a focused beam of electrons onto a substrate coated with electron-sensitive resist, achieving pattern resolutions below 10 nanometers through precise electrostatic beam deflection and electromagnetic lens systems; this technology serves as the backbone for photomask production, nanoscale device prototyping, and advanced research requiring arbitrary pattern generation beyond optical lithography limits. Mask writer systems command the strongest margin pools as foundries demand ever-tighter critical dimension uniformity for EUV lithography masks. Research tools experience accelerating replacement cycles as university labs and national institutes expand programs in quantum device fabrication and two-dimensional material patterning.
FDA oversight of electron beam systems used in medical device prototyping shapes validation requirements for manufacturers serving the healthcare technology sector, while ISO 14644 cleanroom standards govern installation environments and operational certification protocols across all major markets. Japan's METI coordinates domestic supply chain security measures that influence export licensing timelines for advanced lithography components. Stakeholders must monitor evolving semiconductor export control alignments between the US, Netherlands, and Japan as these tripartite restrictions reshape equipment vendor access patterns and customer procurement contingency planning.
Market Dynamics
EUV node transitions below 7nm are compressing photomask complexity requirements, forcing foundries to prioritize electron beam systems capable of sub-10nm pattern fidelity over legacy optical mask writers.
Growth Catalysts
- Sub-7nm EUV Mask Demand:Taiwan and South Korea foundries require precision patterning for high-NA EUV lithography masks, accelerating mask writer replacement cycles.
- Quantum Device Fabrication Programs:National research institutes in Japan and Germany are expanding electron beam infrastructure for superconducting qubit and quantum dot patterning.
- METI Supply Chain Security Measures:Japan's domestic content incentives are redirecting procurement toward local tool vendors and reducing reliance on foreign component streams.
Market Restraints
- Electromagnetic Lens Supply Concentration:Precision lens assemblies rely on a limited supplier base concentrated in Germany and Japan, creating single-source vulnerability.
- Cleanroom Infrastructure Requirements:ISO 14644 Class 1-3 cleanroom specifications demand facility investments that exclude smaller research institutions and startup fabs.
- Throughput Limitations Versus Optical Lithography:Serial electron beam patterning cannot match wafer-per-hour rates of optical steppers for high-volume manufacturing layers.
Strategic Opportunities
- Two-Dimensional Material Patterning:Graphene and transition metal dichalcogenide research at European nanotechnology centers requires specialized low-energy electron beam configurations.
- US CHIPS Act Fab Construction:Federal incentives for domestic semiconductor manufacturing are creating installed base expansion opportunities in Arizona and Texas greenfield sites.
- Medical Device Prototyping Validation:FDA 21 CFR Part 820 quality system requirements for electron beam-patterned implantable devices open service bureau revenue streams.
Industry Challenges
- Electro-Optics Specialist Shortage:System alignment and column maintenance require expertise in charged particle physics that outpaces university pipeline output.
- Multi-Vendor Integration Complexity:Mask data preparation workflows must bridge electron beam writers with optical lithography clusters and metrology tools from competing suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electron Beam Lithography Machine Market |
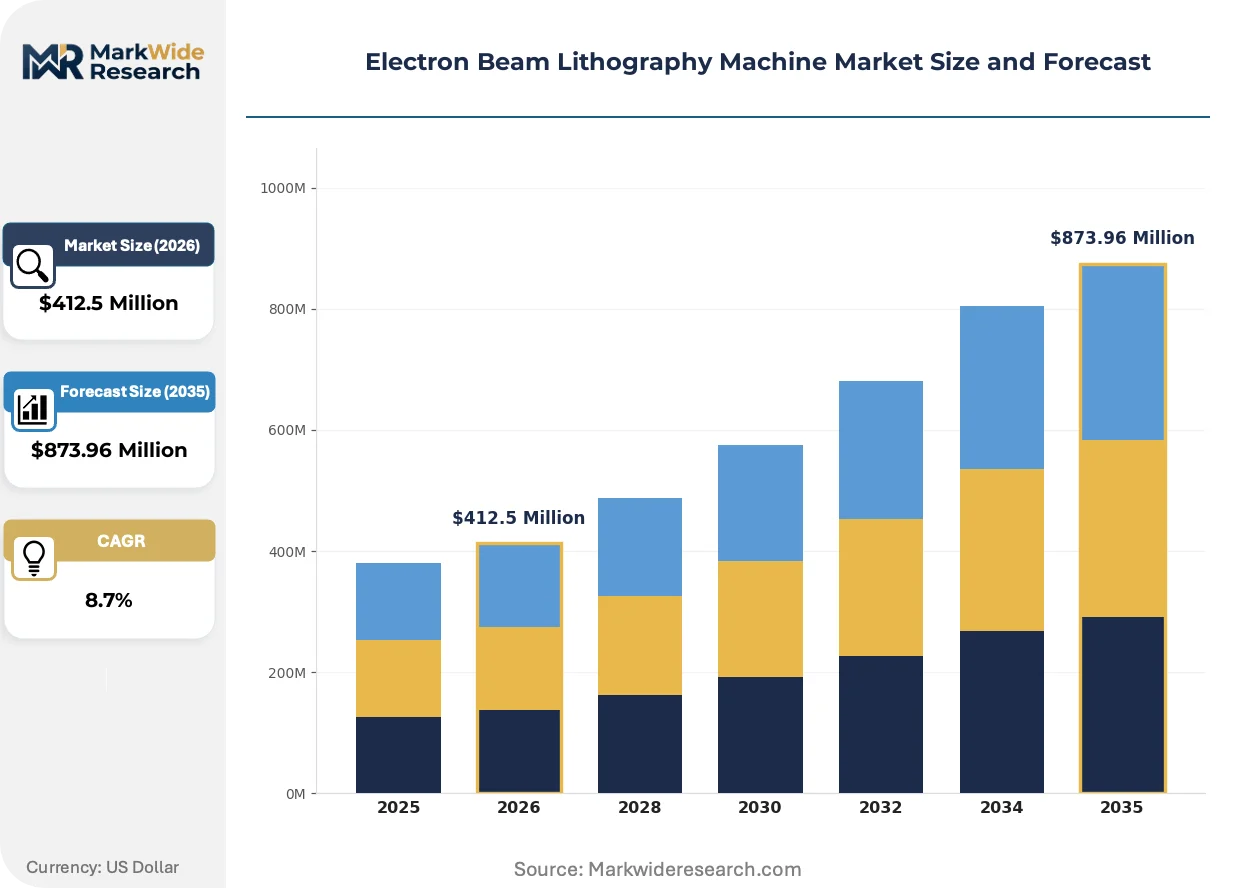
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $873.96 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Batch System, Mask Writer, Research Tool, Advanced Tool End User: Semiconductor Manufacturers, Research Institutions, University Labs, Aerospace Companies Application: Microelectronics, Nanotechnology, Optical Devices, Photonic Devices Technology: Direct Write, Maskless Lithography, Hybrid Systems, Electron Optics |
| Companies Covered | IMS Nanofabrication GmbH, Raith GmbH, Nuflare Technology Inc., Elionix Inc., JEOL Ltd., Vistec Electron Beam GmbH, Crestec Corporation, Advantest Corporation, NanoBeam Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electron Beam Lithography Machine Market Trends and Innovations
Multi-beam electron source architectures are transforming throughput economics for mask writing applications, while regulatory alignment on semiconductor export controls is fragmenting vendor access patterns.
Variable-shaped beam technology with character projection capabilities is rendering obsolete traditional Gaussian beam raster scanning for repetitive pattern elements. Leading foundries in Taiwan are adopting these systems for EUV stencil mask production. The technology is rendering obsolete hour-per-mask write times that previously constrained photomask fab capacity planning.
Japan's METI export licensing framework for advanced lithography components is extending approval timelines for electron beam column assemblies and precision stages. European tool vendors face elongated order-to-delivery cycles for East Asian customers. Mask writer procurement teams in South Korea are accelerating dual-source qualification programs to mitigate access uncertainty.
Consolidated service contracts bundling preventive maintenance, resist process optimization, and application engineering are displacing traditional break-fix support models. University labs and national institutes favor fixed-cost operational budgets over capital-intensive system ownership. This shift concentrates most visibly in German and Swiss nanotechnology centers where shared research infrastructure models dominate funding structures.
Electron Beam Lithography Machine Market Segmentation
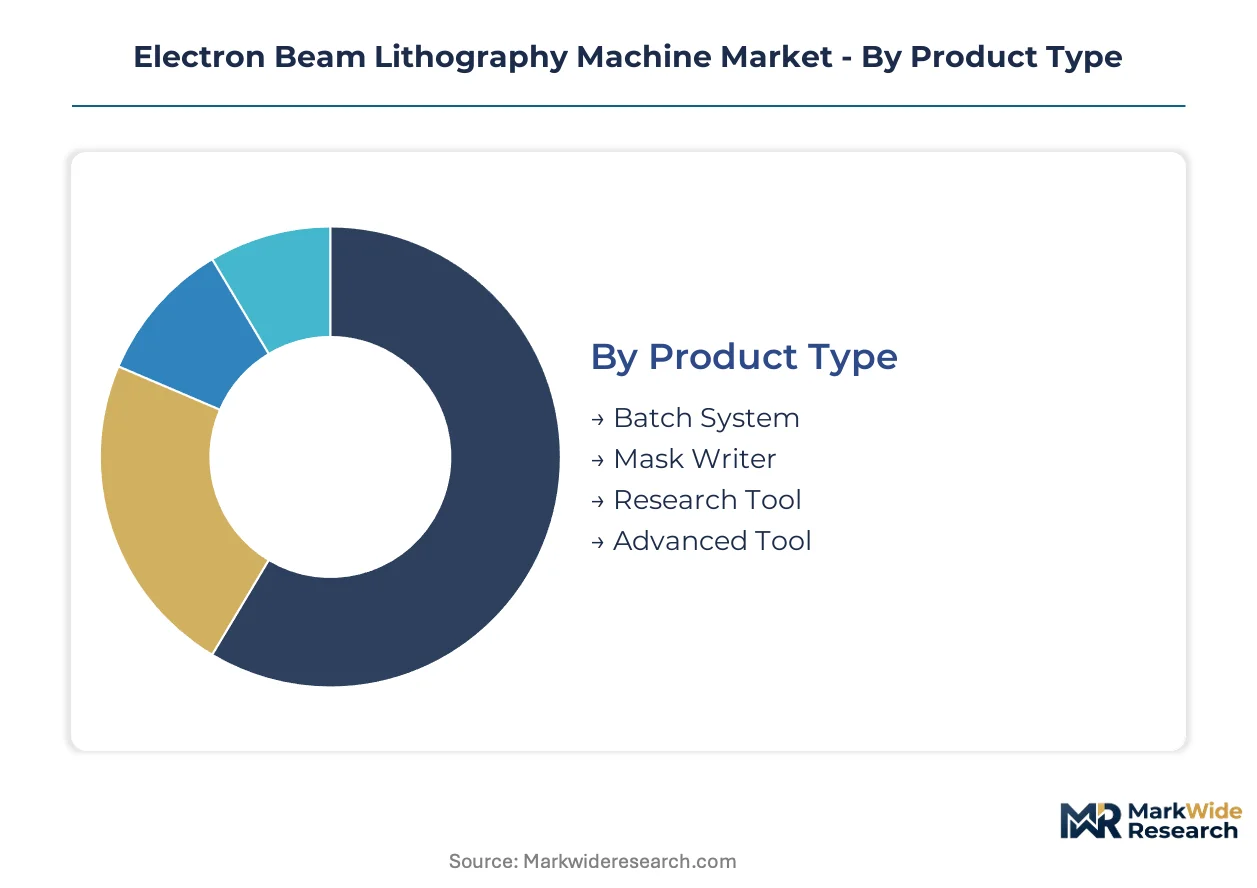
Electron beam lithography machines serve divergent operational requirements across mask production, research prototyping, and advanced manufacturing. Each segment category reflects distinct capital intensity levels, technical specifications, and customer procurement workflows that shape vendor product strategies.
Product Type:
Use cases span high-volume photomask fabrication to specialized academic research, with throughput and resolution specifications determining system architecture.
- Mask Writer:Systems engineered for photomask patterning with variable-shaped beam technology achieve sub-10nm critical dimension control for EUV lithography masks. Taiwan and South Korea foundries dominate procurement as sub-7nm node transitions intensify replacement cycles.
- Research Tool:Configurations prioritize flexibility over throughput, supporting arbitrary pattern generation for quantum device prototyping and two-dimensional material studies. German and Swiss nanotechnology centers are expanding shared infrastructure investments.
- Batch System:Multi-wafer processing architectures serve mid-volume prototyping needs in compound semiconductor development.
- Advanced Tool:Multi-beam source configurations address emerging throughput requirements for direct-write applications beyond traditional mask writing.
Established volume favors Mask Writer; emerging adoption favors Research Tool.
End User:
Customer types reflect fundamentally different acquisition models, from capital-intensive fab installations to grant-funded laboratory procurements.
- Semiconductor Manufacturers:Foundries and integrated device manufacturers deploy systems for photomask production and process development. Procurement concentrates in East Asian manufacturing hubs where EUV node transitions drive equipment refresh cycles.
- Research Institutions:National laboratories and government-funded centers operate systems for quantum computing and advanced materials programs. Japan and Germany are expanding electron beam infrastructure for superconducting qubit fabrication.
- University Labs:Academic facilities prioritize lower-cost configurations with extensive application engineering support.
- Aerospace Companies:Defense contractors utilize systems for radiation-hardened component prototyping and specialized sensor development.
Procurement scale distinguishes Semiconductor Manufacturers; grant funding flexibility distinguishes Research Institutions.
Application:
Technical requirements vary substantially across electronic, photonic, and nanoscale device fabrication domains.
- Microelectronics:Patterning of integrated circuits and interconnect structures requires precise critical dimension control for logic and memory devices. Sub-7nm transistor development in Taiwan foundries depends on electron beam mask writing for multiple patterning layers.
- Nanotechnology:Arbitrary pattern generation for graphene, nanowires, and quantum dots demands specialized low-energy beam configurations. European research centers are expanding capacity for two-dimensional material device fabrication.
- Optical Devices:Diffractive optical element patterning requires high-aspect-ratio structures with sub-wavelength feature sizes.
- Photonic Devices:Silicon photonics and integrated optical circuit fabrication utilize electron beam systems for waveguide and coupler definition.
Revenue concentration sits with Microelectronics; steepest expansion trajectory characterizes Nanotechnology.
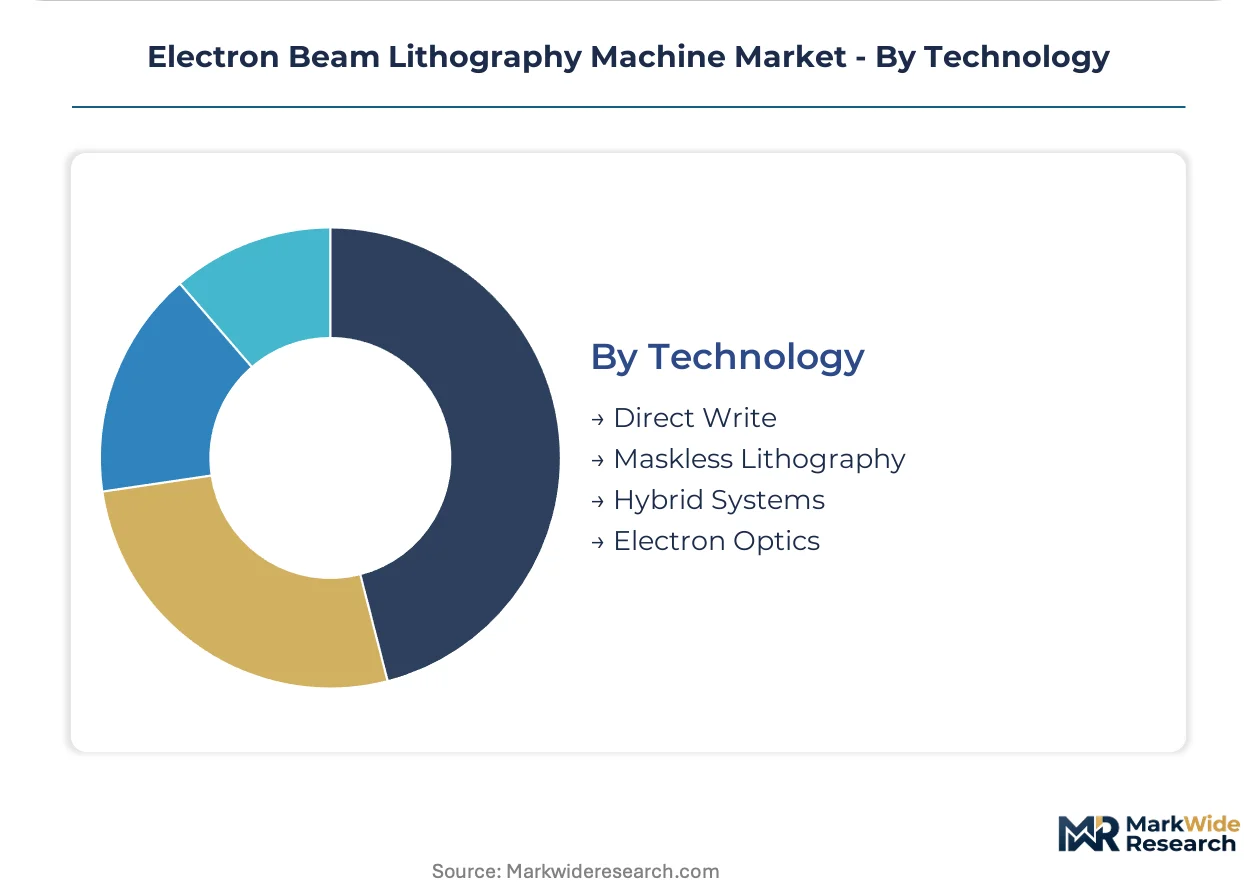
Technology:
Patterning methodologies differentiate between serial direct-write approaches and optimized maskless configurations.
- Direct Write:Serial electron beam deflection enables arbitrary pattern generation without photomask intermediates. Aerospace and research applications in the US leverage this capability for low-volume, high-mix prototyping requirements.
- Maskless Lithography:Multi-beam architectures transform throughput economics for applications requiring photomask elimination. Leading foundries are evaluating these systems for EUV stencil mask production.
- Hybrid Systems:Combined electron-optical approaches integrate electron beam precision with optical lithography throughput for specific layer applications.
- Electron Optics:Core column technology encompassing electromagnetic lenses and electrostatic deflection systems underpins all patterning methodologies.
Technical maturity favors Electron Optics; performance innovation favors Maskless Lithography.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Foundry procurement teams in Taiwan and South Korea command the largest equipment budgets, while research institutes in Japan and Germany expand capacity for quantum device fabrication. National security measures are redirecting supply chain configurations across all major manufacturing hubs.
Taiwan
TSMC and UMC drive mask writer demand as sub-3nm EUV node development accelerates photomask complexity requirements. The National Science and Technology Council funds advanced lithography research at Hsinchu Science Park facilities. Tainan and Taichung science parks concentrate the island's electron beam infrastructure expansion for leading-edge foundry operations.
South Korea
Samsung Foundry and SK Hynix prioritize multi-beam mask writer acquisitions for high-NA EUV stencil production. The Ministry of Trade, Industry and Energy subsidizes domestic equipment vendor development through K-Chips 2024 initiatives. Pyeongtaek and Yongin semiconductor clusters host the country's primary electron beam lithography installations for memory and logic device development.
Japan
JEOL and Nuflare anchor domestic supply chains as METI export controls extend licensing timelines for advanced column assemblies. The New Energy and Industrial Technology Development Organization funds superconducting qubit patterning programs at national labs. Tsukuba and Sendai research corridors concentrate government-backed electron beam infrastructure for quantum computing initiatives.
Germany
Fraunhofer Institutes and Max Planck facilities expand shared research tool access for two-dimensional material device studies. The Federal Ministry of Education and Research finances nanotechnology infrastructure through the Quantum Technologies Program. Dresden and Munich metropolitan areas host Europe's densest concentration of electron beam lithography systems for semiconductor research.
United States
Intel and GlobalFoundries deploy mask writers at Arizona and New York greenfield fabs under CHIPS Act incentives. The Department of Commerce Bureau of Industry and Security coordinates export control alignment with Japanese and Dutch counterparts. Albany Nanotech Complex and Portland semiconductor clusters represent the primary domestic electron beam lithography installations for advanced node development.
Electron Beam Lithography Machine Market Competitive Landscape
Channel-controlling players compete with product-specialist players across mask writer and research tool segments. The vendor base clusters around three strategic archetypes: integrated conglomerates with semiconductor equipment portfolios, dedicated lithography specialists, and precision electron-optics houses. Consolidation pressures favor acquisition activity among mid-scale European specialists, while capacity expansion dominates East Asian vendor strategies. Technology licensing agreements are displacing pure equipment sales as procurement teams seek operational flexibility.
Among German precision electron-optics fabricators, Raith GmbH and Vistec Electron Beam GmbH exemplify the research-tool specialization archetype with configurations targeting university and national laboratory workflows. JEOL Ltd. and Nuflare Technology Inc. occupy positions within the integrated conglomerate tier, leveraging semiconductor equipment portfolios to anchor mask writer procurement decisions at leading foundries. These three companies represent the geographic and structural diversity characterizing competitive positioning across precision patterning applications.
| Leading Market Players |
|---|
| IMS Nanofabrication GmbH |
| Raith GmbH |
| Nuflare Technology Inc. |
| Elionix Inc. |
| JEOL Ltd. |
| Vistec Electron Beam GmbH |
| Crestec Corporation |
| Advantest Corporation |
| NanoBeam Ltd. |
| Others |
Pricing and Supply Chain Analysis
Undercapacity in precision electromagnetic lens fabrication across Germany and Japan is compressing supplier margins while amplifying pricing power for electron beam column assemblies. Taiwan foundries absorb these cost escalations through long-term service contracts that bundle preventive maintenance with resist process optimization.
Pricing Analysis
Cost-plus contracts with quarterly indexation to rare earth metal prices dominate mask writer procurement between East Asian foundries and Japanese vendors. Price differentiation hinges on critical dimension uniformity certification and bundled application engineering support. Pricing pressure stems from multi-beam source commoditization as IMS Nanofabrication and JEOL expand competing variable-shaped beam architectures. Research institutions exhibit highest price sensitivity due to grant-funded capital constraints, while leading foundries prioritize pattern fidelity over unit economics.
Supply Chain Analysis
Contract manufacturing concentrates at JEOL's Akishima facility and Nuflare's Yokohama operations for precision stage assemblies, with Raith drawing from German precision optics fabricators in Munich and Jena. Electron beam lithography supply chains rest on high-purity tungsten filament sources from Austria, rare earth magnetic materials from China, and ultra-high vacuum chamber components from Japan. Single-source vulnerability in electromagnetic lens assemblies creates tariff exposure risk under evolving METI export licensing frameworks. Distribution runs through direct vendor-fab relationships for mask writers, while research tools channel through regional distributors with application engineering capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electron beam lithography is approaching a platform-economics inflection as mask data preparation workflows demand seamless interoperability between electron beam writers, optical lithography clusters, and metrology tools from competing suppliers. Vendors that orchestrate this ecosystem integration will capture disproportionate value.
For Market Incumbents: Build switching-cost moats through consolidated service contracts that embed resist process IP and preventive maintenance algorithms. Incumbents should anchor mask writer procurement decisions by deepening backward integration into precision stage manufacturing, mitigating METI licensing exposure. Multi-vendor workflow integration represents the critical defensive lever against emerging multi-beam specialists threatening throughput advantages. For New Entrants and Emerging Players: Mid-tier compound semiconductor fabs in the United States represent the most penetrable entry point, as CHIPS Act greenfield construction creates installed base expansion without entrenched vendor relationships. Specialized low-energy configurations for two-dimensional material patterning at European nanotechnology centers offer secondary white-space. Go-to-market should emphasize outcome-based pricing tied to pattern fidelity metrics rather than capital equipment sales. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among precision electron-optics houses with captive service contract portfolios and resist process IP. Long-term viability across the analysis window favors vendors with demonstrated multi-beam source roadmaps and foundry qualification track records. The signal to watch is dual-source qualification acceleration among South Korean mask writer procurement teams, indicating vendor access uncertainty and potential consolidation windows.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Beam Source Roadmap Execution | IMS Nanofabrication's variable-shaped beam architectures are displacing hour-per-mask write times at Taiwan foundries. |
| Consolidated Service Contract Expansion | Fixed-cost operational budgets at German nanotechnology centers are displacing traditional break-fix support models. |
| Precision Stage Backward Integration | In-house production of electromagnetic lens assemblies mitigates METI export licensing timeline elongation. |
| Mask Data Preparation Ecosystem Integration | Seamless workflow bridging with optical lithography clusters determines procurement decisions at Samsung Foundry. |
| Low-Energy Configuration Development | Specialized systems for graphene patterning capture European research institute grant funding expansion. |
Research Methodology
The analysis maps mask writer systems, research tools, batch systems, and advanced multi-beam configurations, each validated through mask data preparation engineers, foundry procurement directors, and national laboratory facility managers. Primary interviews with electron-optics specialists and resist process chemists combined with secondary validation from SEMI equipment market data, METI export licensing disclosures, and CHIPS Act funding announcements. Bottom-up equipment shipment tracking and top-down foundry capex triangulation anchored market sizing.
Assumptions held fixed include continued EUV node transition timelines and tripartite export control alignment between the United States, Netherlands, and Japan; variables tested included multi-beam throughput improvement rates and quantum computing research funding trajectories. The forecast framework models product type, end user archetype, application domain, and patterning technology methodology across the projection horizon. CAGRs derive from equipment replacement cycle compression analysis and greenfield fab construction pipelines, with sensitivity analysis applied to high-NA EUV mask complexity requirements.
Practitioners should monitor METI licensing timeline shifts and rare earth supply chain disruptions for early signals of forecast revision. Forecasts reflect assumptions regarding continued East Asian foundry concentration and research infrastructure grant funding stability. Quarterly review of dual-source qualification announcements and multi-beam system adoption rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Equipment
Temperature Calibration Equipment Market
Semiconductor Equipment
Semiconductor Photolithography Equipment Market
Semiconductor Equipment
Solar Texturing Equipment Market
Semiconductor Equipment
Die Attach Equipment Market
Semiconductor Equipment
Global Semiconductor Back-End Equipment Market
Semiconductor Equipment
Pulse Tube and Gifford-Mcmahon Cryocoolers Market
Semiconductor Equipment
Cathode Stripping Machines Market
Semiconductor Equipment
Global Semiconductor Etch Equipment Market
Semiconductor Equipment
Slide Processing System Market
Semiconductor Equipment
Global Semiconductor Coolers Market
Semiconductor Equipment
Europe Semiconductor Etch Equipment Market
Semiconductor Equipment
Laser Micro Perforation Equipment Market
Semiconductor Equipment
Automatic Flip Chip Bonders Market
Semiconductor Equipment
Semiconductor Wafer Cleaning Equipment Market
Semiconductor Equipment
Semiconductor Assembly Equipment Market
Semiconductor Equipment
Vapor Blasting Machine Market