
 Analog and Mixed Signal IP Market | 2026-2036
Analog and Mixed Signal IP Market Size, Share, and Industry Trends Forecast 2026-2036
Analog and Mixed Signal IP Market Analysis
Taiwan is rewriting the competitive map for analog and mixed-signal IP by expanding specialty foundry capacity at nodes critical for precision conversion and power management blocks. Cadence Design Systems leverages its Virtuoso platform to dominate custom analog design environments across leading fabs. Synopsys sustains broad portfolio coverage spanning verification and implementation tools that anchor mixed-signal workflows. ARM competes through physical IP libraries optimized for energy-efficient sensor interfaces in IoT endpoints.
Analog and mixed-signal IP encompasses reusable silicon-proven circuit blocks including data converters, phase-locked loops, and power management units that interface between continuous real-world signals and digital processing subsystems, typically manufactured in CMOS, BiCMOS, or SOI processes with operating voltages from sub-1V to 40V depending on application tolerance. These blocks serve as the sensory and actuation layer in systems-on-chip where digital logic alone cannot acquire or drive physical quantities. Converters and amplifiers occupy the deepest margin pools due to their irreplaceable role in precision measurement chains across automotive and healthcare applications. CMOS technology leads in shipment volume for consumer and telecom integration, while GaN-based power IP represents the fastest-growing technology tier as electric vehicle inverters and telecom base stations push efficiency requirements beyond silicon limits.
ISO 26262 functional-safety mandates from Germany's KBA and Japan's METI certification frameworks are forcing automotive IP suppliers to deliver fault-tolerant architectures with documented failure modes for battery management and lidar signal chains. REACH and RoHS constraints from ECHA restrict hazardous substrate materials in European-bound semiconductor packages, altering material selection for high-voltage analog blocks. The US CHIPS program and FDA digital health guidance create dual compliance pressures for medical and defense-adjacent mixed-signal designs. Stakeholders must weigh foundry diversification against the performance penalties of migrating precision analog IP away from established process platforms.
Market Dynamics
Automotive electrification is compressing design cycles for battery management and sensor interface blocks, forcing IP vendors to pre-qualify analog cores against ISO 26262 safety tiers before foundry tape-out.
Growth Catalysts
- ISO 26262 mandates:Germany's KBA and Japan's METI certification frameworks require fault-tolerant architectures for lidar signal chains and battery monitors, pulling silicon-proven IP into automotive SoC roadmaps.
- GaN process maturation:Electric vehicle inverters and telecom base stations push efficiency requirements beyond silicon limits, opening new margin pools for wide-bandgap power management blocks.
- Taiwan foundry concentration:Unmatched specialty capacity at precision analog nodes locks in fabless IP customer dependence on TSMC and UMC process platforms.
Market Restraints
- 300mm specialty wafer allocation:Leading-edge digital customers crowd out analog mask sets at mature nodes, extending lead times for BiCMOS and SOI runs.
- REACH substrate restrictions:ECHA constraints on hazardous packaging materials force material requalification for high-voltage blocks bound for European automotive Tier 1s.
- Digital calibration substitution:Machine learning-based error correction in data converters threatens discrete analog precision IP in consumer measurement applications.
Strategic Opportunities
- EU Chips Act localization:Subsidized European foundry capacity at nodes above 28nm creates captive demand for regionally-developed analog blocks in industrial and medical devices.
- Sensor fusion convergence:Lidar, radar, and camera interface IP integration into unified analog front-ends reduces die area for autonomous driving compute platforms.
- Digital health FDA pathway:510(k) clearance requirements for continuous glucose monitors and wearable ECG create certified IP pull-through for ultra-low-power ADC architectures.
Industry Challenges
- Analog designer scarcity:Foundry-specific device modeling expertise concentrates among retiring engineers, constraining IP house hiring pipelines.
- Multi-project wafer slot competition:Prototype runs for precision converter validation face scheduling pressure from AI accelerator tape-outs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Analog and Mixed Signal IP Market |
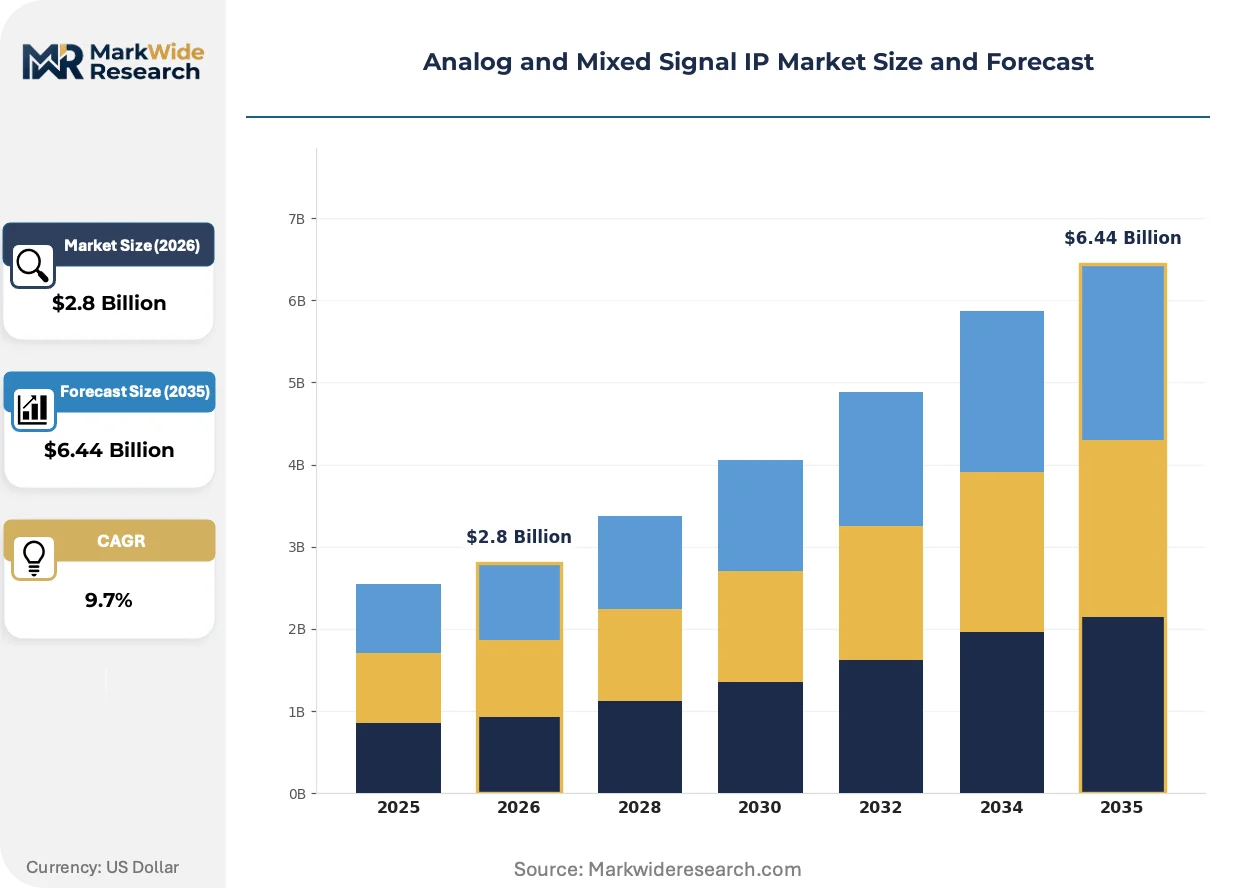
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $6.44 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Amplifiers, Converters, Oscillators, Filters Technology: CMOS, BiCMOS, GaN, SOI Application: Consumer Electronics, Telecommunications, Automotive, Healthcare End User: OEMs, Fabless Companies, Research Institutions, Aftermarket Providers |
| Companies Covered | Cadence Design Systems, Synopsys, ARM, Texas Instruments, Analog Devices, NXP Semiconductors, STMicroelectronics, Infineon Technologies, Renesas Electronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analog and Mixed Signal IP Market Emerging Trajectories
Process-node fragmentation is splitting the market between leading-edge digital integration and trailing-edge specialty analog, with each trajectory demanding incompatible IP development methodologies.
Time-interleaved SAR ADC architectures are collapsing the power-area tradeoff for 12-16 bit precision conversion in battery-powered industrial sensors. Medical device OEMs are adopting these blocks for portable ultrasound and patient monitoring equipment ahead of traditional pipeline converter timelines. The structural consequence is collapsing ASPs for mid-resolution data converter IP as single-channel designs displace multi-chip module approaches.
REACH and RoHS amendments from ECHA are tightening substrate material declarations for semiconductor packages entering European automotive supply chains. High-voltage analog blocks now require documented compliance across lead-frame alloys and mold compound chemistries before design win approval. German automotive Tier 1s are pushing this burden upstream to IP vendors through supplier qualification portals.
Consolidated procurement through foundry-direct IP marketplaces is displacing traditional EDA vendor distribution for mature-node analog blocks. Fabless customers in Taiwan and South Korea now license converter and PLL cores through TSMC's IP alliance program rather than standalone EDA contracts. This channel shift concentrates pricing leverage with foundry partners and compresses standalone IP house margins.
Analog and Mixed Signal IP Market Segmentation
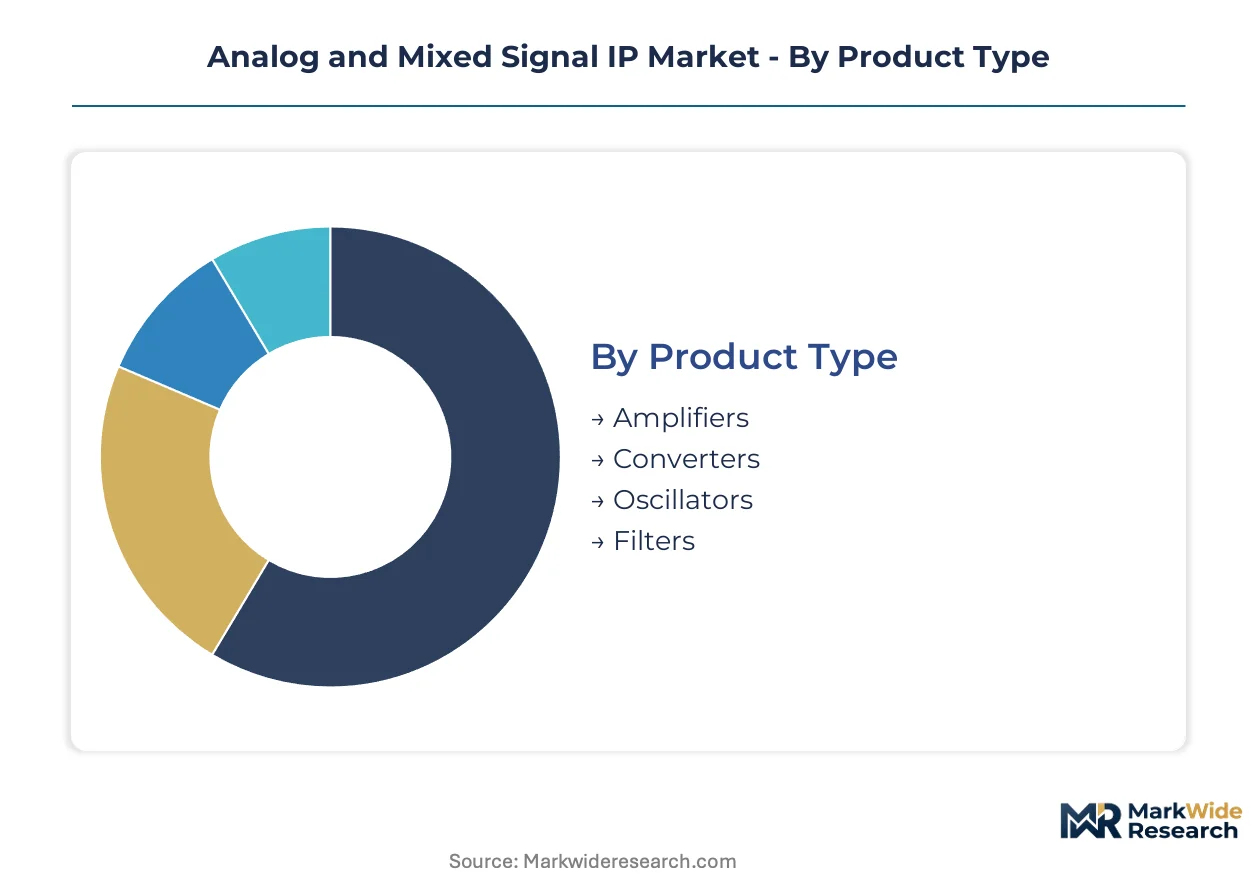
Analog and mixed-signal IP vendors must align development roadmaps with divergent technical requirements across precision conversion, power efficiency, and noise immunity. Segmentation reveals where process-specific expertise commands premium pricing versus commoditized volume play.
Product Type:
Design teams select IP blocks based on signal chain position, with precision requirements and power constraints driving architectural choices from sensor front-ends to data acquisition backbones.
- Converters:Data converters bridge continuous analog signals to digital domains through successive-approximation, pipeline, or delta-sigma architectures. Automotive lidar systems and portable medical imaging equipment in Germany and Japan concentrate demand for 12-16 bit precision with sub-milliwatt consumption.
- Amplifiers:These blocks condition small-signal inputs through low-noise, instrumentation, or operational amplifier topologies. Battery management systems in electric vehicles drive orders for high-voltage-capable designs with ISO 26262 fault tolerance documentation.
- Oscillators:Timing references including phase-locked loops and crystal oscillators establish clock distribution hierarchies. 5G base station deployments in South Korea and Taiwan pull low-jitter designs for millimeter-wave transceiver synchronization.
- Filters:Active and passive filtering networks suppress out-of-band interference before analog-to-digital conversion. Hearing aid manufacturers in Switzerland and Denmark specify ultra-low-power switched-capacitor implementations.
The dominant share belongs to Converters, while Amplifiers is closing the gap fastest.
Technology:
Process selection trades off integration density against voltage handling, with each platform serving distinct application voltage ranges and frequency requirements.
- CMOS:Dominant volume platform leveraging scaled lithography for dense digital-analog integration in consumer SoCs. Smartphone OEMs in Taiwan and South Korea drive mask set volumes at 22nm and above for audio codec integration.
- GaN:Wide-bandgap process enables switching frequencies beyond silicon limits for power conversion efficiency. Electric vehicle inverter manufacturers in Germany and California specify 650V-rated gate drivers and power stages.
- BiCMOS:Bipolar-CMOS fusion delivers transconductance and noise performance for precision instrumentation. Test and measurement equipment vendors in the US and Japan license high-linearity front-end blocks.
- SOI:Silicon-on-insulator isolation reduces substrate coupling in mixed-signal environments with aggressive digital switching. RF transceiver designers in France and Israel adopt RF-SOI for antenna tuning and switch matrices.
CMOS maintains volume leadership, though GaN claims the steepest expansion trajectory as electrification accelerates.
Application:
End-market certification requirements and operating environment specifications fragment IP qualification pathways across consumer, infrastructure, and safety-critical domains.
- Automotive:Battery management, lidar signal chains, and motor control demand fault-tolerant architectures with documented failure modes. KBA and METI certification mandates in Germany and Japan force pre-qualification against ASIL-D safety tiers.
- Healthcare:Continuous glucose monitors, wearable ECG, and portable ultrasound require ultra-low-power ADCs with FDA 510(k) clearance support. Digital health guidance from the FDA creates certified IP pull-through for US-bound designs.
- Consumer Electronics:Audio codecs, touch controllers, and display drivers prioritize die area minimization over absolute precision. Smartphone and TWS earbud OEMs in Taiwan and China drive high-volume licensing at aggressive ASPs.
- Telecommunications:Base station transceivers and optical modules demand high-speed data converters with linearity specifications for dense modulation schemes. 5G infrastructure deployments in South Korea and Finland specify RF-sampling architectures.
Automotive commands the premium tier by qualification burden, while Healthcare is gaining share fastest on FDA digital health pathway expansion.
End User:
Procurement authority and technical evaluation criteria differ sharply between integrated device manufacturers, fabless design houses, and research-driven adopters.
- Fabless Companies:These customers license complete subsystem IP for tape-out at foundry partners without captive fabrication. Taiwan-based fabless analog specialists concentrate procurement through TSMC's IP alliance marketplace.
- OEMs:Automotive and industrial equipment manufacturers increasingly source directly from IP houses for in-house ASIC programs. German automotive Tier 1s maintain supplier qualification portals mandating REACH documentation.
- Research Institutions:Universities and national labs license prototype blocks for multi-project wafer runs at subsidized academic pricing. European research frameworks under the EU Chips Act fund localization pilots.
- Aftermarket Providers:Replacement component suppliers and repair ecosystem players license legacy-node compatible blocks for extended product support. Industrial automation retrofit markets in Japan sustain demand for mature CMOS libraries.
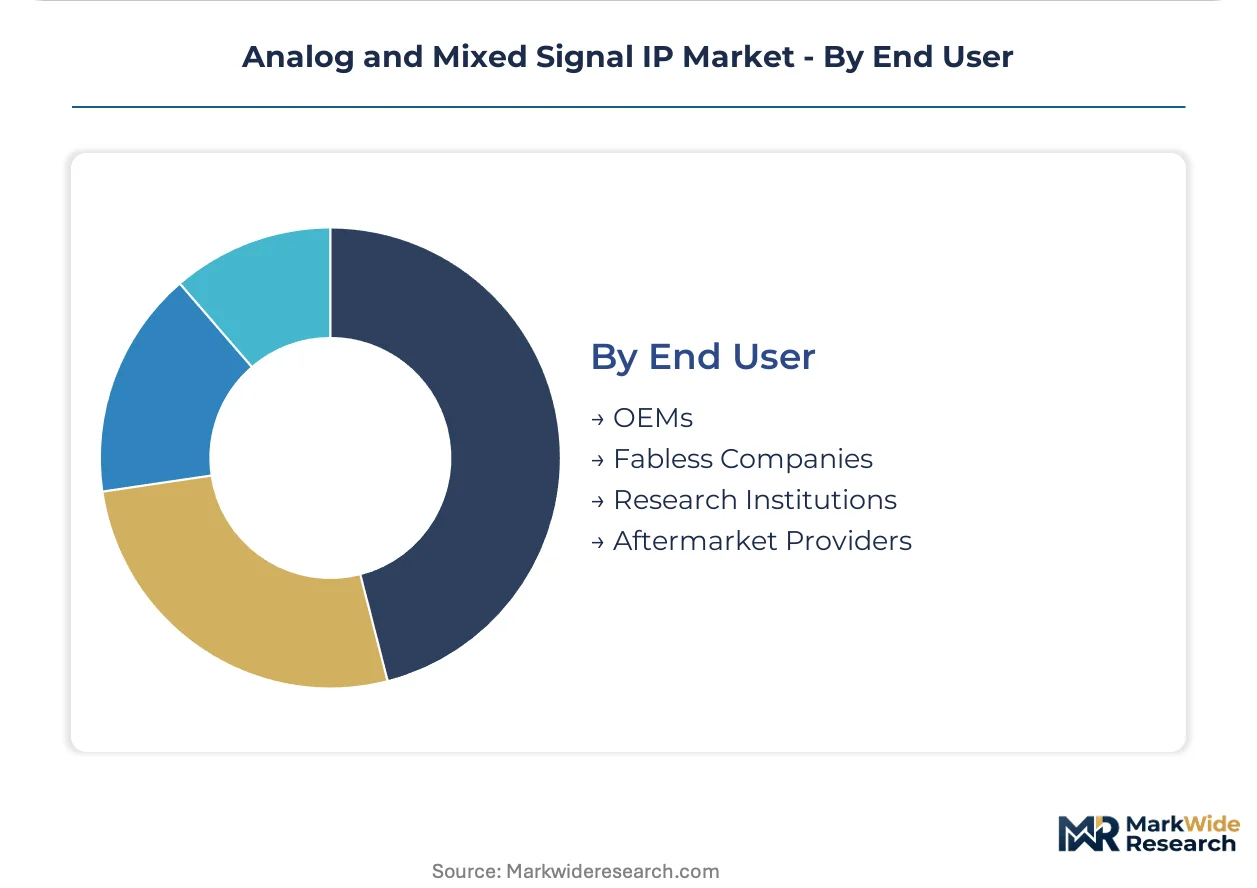
Fabless Companies dominate licensing volume, while OEMs are expanding procurement authority fastest through vertical integration into custom silicon.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Hsinchu Science Park anchors Taiwan's unmatched concentration of specialty foundry capacity, while the EU Chips Act redirects European semiconductor investment toward regional analog IP development. Submarine cable landing stations in Singapore and cable systems linking Japan to US West Coast data centers underpin Asia-Pacific's dominance in precision converter demand.
Taiwan
Hsinchu and Tainan Science Parks concentrate TSMC and UMC capacity for precision analog nodes that fabless IP vendors depend upon. METI-aligned Japanese automotive OEMs source certified blocks through foundry-direct marketplaces here. The Southern Taiwan Science Park expansion adds 300mm capacity for BiCMOS processes serving lidar signal chains.
Germany
KBA certification mandates for ASIL-D battery management systems pull fault-tolerant converter IP into automotive SoC programs. REACH substrate documentation requirements flow through Tier 1 supplier portals to IP vendors. Munich and Stuttgart industrial clusters drive demand for high-voltage amplifier blocks in motor control applications.
United States
FDA 510(k) clearance pathways for continuous glucose monitors create certified pull-through for ultra-low-power ADC architectures. The CHIPS program subsidizes domestic foundry capacity above 28nm for defense-adjacent mixed-signal designs. Austin and Boston design hubs concentrate fabless procurement of precision instrumentation IP.
Japan
METI functional-safety frameworks for automotive lidar force pre-qualification of analog cores against documented failure modes. Kyushu and Hiroshima production bases sustain demand for mature-node compatible blocks in industrial automation retrofit markets. Tokyo-based OEMs maintain captive analog design teams for sensor interface integration.
South Korea
5G base station deployments in Seoul and Busan pull low-jitter PLL designs for millimeter-wave transceiver synchronization. KOSPI-listed memory giants backward-integrate into mixed-signal IP for system-level differentiation. Pangyo and Hwaseong clusters concentrate procurement of RF-sOI switch matrices for smartphone antenna tuning.
Analog and Mixed Signal IP Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in precision conversion and power management niches. The vendor base concentrates around EDA platforms that anchor custom analog design workflows, with foundry-direct marketplaces displacing traditional distribution channels for mature-node blocks. Three archetypes dominate: full-flow EDA vendors with captive IP libraries, standalone analog specialists licensing silicon-proven cores, and IDMs monetizing internal development through external licensing programs. Competitive moves center on strategic partnerships with foundry alliances and portfolio diversification into GaN-based power blocks.
Among US-based platform vendors, Cadence Design Systems and Synopsys occupy positions spanning design environments through verification tools. ARM exemplifies the physical IP archetype, licensing energy-efficient libraries optimized for IoT sensor interfaces. These three anchors represent distinct competitive vectors: Cadence anchors custom analog workflow dominance, Synopsys sustains broad verification and implementation coverage, and ARM competes through processor-adjacent physical IP integration.
| Leading Market Players |
|---|
| Cadence Design Systems |
| Synopsys |
| ARM |
| Texas Instruments |
| Analog Devices |
| NXP Semiconductors |
| STMicroelectronics |
| Infineon Technologies |
| Renesas Electronics |
| Others |
Supply Flow & Price Mechanics
300mm specialty wafer undercapacity at Taiwan foundries is compressing analog mask set availability and amplifying pricing leverage for silicon-proven IP houses serving automotive and medical certification tiers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs converter and PLL licensing, with ISO 26262 ASIL-D certification and foundry process node maturity as the primary price differentiation drivers. Cost compression in mid-resolution consumer-grade blocks is intensifying because time-interleaved SAR architectures are collapsing power-area tradeoffs and displacing multi-chip module approaches. Fabless companies in Taiwan exhibit the highest price sensitivity due to foundry-direct marketplace concentration, while German automotive Tier 1s demonstrate the least sensitivity given REACH documentation mandates and fault-tolerance requirements.
Supply Chain Analysis
Extended payment terms from Japanese automotive OEMs and supply-chain finance facilities anchored by TSMC's IP alliance program are restructuring working capital requirements for analog IP vendors. Taiwan, South Korea, and the United States anchor fabrication and design capacity, with the supply chain drawing from 300mm silicon wafers, GaN-on-silicon substrates, and BiCMOS process development kits. Single-source vulnerability concentrates around TSMC's specialty analog nodes for precision conversion blocks. Distribution runs through foundry-direct marketplaces displacing traditional EDA vendor channels for mature-node licensing.

Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Post-license verification services and iterative safety-documentation updates are expanding faster than hardware royalties, creating a service-attach layer that sustains recurring revenue through multi-year automotive qualification cycles.
For Market Incumbents: Build a certification moat by pre-qualifying analog cores against METI functional-safety frameworks before foundry tape-out, and deepen backward integration into GaN process development kits to defend margin position against wide-bandgap specialists. Channel control through TSMC's IP alliance marketplace represents the critical lever for locking out standalone converter houses.
For New Entrants and Emerging Players: Establish a beachhead in EU Chips Act-subsidized European foundry capacity above 28nm for industrial and medical device analog blocks, where localization requirements create captive demand absent from Taiwan's saturated marketplace. A direct licensing model through German Tier 1 supplier qualification portals bypasses foundry marketplace concentration.
For Investors and Strategic Acquirers: Capital is best deployed toward analog specialists with documented ISO 26262 fault-tolerant architectures and existing KBA certification relationships, as these assets compound defensibility across the electrification cycle. The inflection signal to watch is FDA 510(k) clearance velocity for ultra-low-power ADC architectures in continuous glucose monitoring applications.
| Strategic Initiative | Industry Significance |
|---|---|
| Foundry Alliance Partnership | TSMC IP alliance membership locks in fabless customer access and pricing leverage. |
| GaN Process Development Investment | 650V-rated power stage qualification opens electric vehicle inverter margin pools. |
| ISO 26262 Pre-Certification Program | ASIL-D documentation accelerates German automotive Tier 1 design wins. |
| Sensor Fusion IP Integration | Lidar-radar-camera front-end consolidation reduces autonomous driving die area. |
| EU Localization Facility | Subsidized capacity above 28nm captures industrial medical device demand. |
Methodological Framework
Cross-validation between primary interviews with analog design leads, foundry business development officers, automotive Tier 1 procurement managers, and FDA regulatory consultants and secondary validation through SEC semiconductor filings, ECHA REACH substance databases, ISO 26262 certification registries, and foundry capacity announcements anchors the qualitative findings. Bottom-up modeling of licensing transaction volumes and top-down triangulation against foundry wafer starts and EDA tool shipment data ensures consistency across estimation approaches.
Calibration against historical analog IP royalty disclosures and foundry revenue splits by process node shapes the analytical framework across the analysis window. Segmentation dimensions include converter architecture type, process technology platform, automotive safety integrity level, and regional foundry sourcing pattern. CAGRs emerge from fitted growth curves incorporating electric vehicle production trajectories, 5G base station deployment schedules, and FDA digital health guidance expansion as semiconductor-specific forecast inputs.
Sensitivities concentrate around Taiwan foundry allocation decisions, REACH substrate material amendments, and machine learning-based digital calibration substitution threats. Forecasts reflect documented assumptions about automotive electrification pacing and telecom infrastructure investment cycles. Macroeconomic contraction, regulatory restriction tightening, or disruptive architectural substitution would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
IC (Integrated Circuits)
Global Amplifier and Comparator IC Market
IC (Integrated Circuits)
Global Application Specific Automotive Analog IC Market
IC (Integrated Circuits)
Programmable ASIC Market
IC (Integrated Circuits)
Americas Integrated Circuit (IC) Market
IC (Integrated Circuits)
RFID Reader IC Market
IC (Integrated Circuits)
Mixed Signal IC Market
IC (Integrated Circuits)
Global SRAM and ROM Design IP Market
IC (Integrated Circuits)
Application Specific Integrated Circuit Market
IC (Integrated Circuits)
Global Interface IC Market
IC (Integrated Circuits)
Gate Driver IC Market
IC (Integrated Circuits)
United States Analog Integrated Circuits Market
IC (Integrated Circuits)
Global Consumer Standard Logic IC Market
IC (Integrated Circuits)
Automotive Special Purpose Logic IC Market
IC (Integrated Circuits)
Motor Driver IC Market
IC (Integrated Circuits)
Mixed-Signal Microcontroller Market
IC (Integrated Circuits)
Global Application Specific Industrial Analog IC Market