
 Plasma Etch System Market | 2026-2036
Plasma Etch System Market Size, Share, and Industry Trends Forecast 2026-2036
Plasma Etch System Market Analytics
South Korea's Pyeongtaek semiconductor complex is narrowing the supply gap for high-throughput etch chambers serving sub-7nm logic production. Lam Research Corporation leverages its installed base in 3D NAND string etch to sustain recurring revenue from consumables and upgrades. Applied Materials Inc. anchors its position through integrated materials-to-systems workflows for gate-all-around transistor architectures. Tokyo Electron Ltd differentiates via its proprietary high-aspect-ratio etch platforms deployed at leading DRAM fabs.
A plasma etch system generates chemically reactive ion species in a vacuum chamber to selectively remove material from semiconductor wafers, with process parameters including RF power density, gas chemistry ratios, and chamber pressure typically operating below 100 mTorr. Its primary purpose enables pattern transfer from photoresist masks into underlying films with nanometer-scale precision. Dry etcher configurations dominate capital allocation due to their versatility across dielectric and metal etch steps, while inductively coupled plasma technology leads in advanced logic applications where independent ion density and energy control proves critical. Reactive ion etcher demand accelerates in MEMS production where deep silicon etching requires precise sidewall profile management.
EPA emissions standards for perfluorinated compounds constrain fluorocarbon gas selection and abatement system requirements in US-based fabrication facilities. REACH restrictions on hazardous substances and the EU F-Gas Regulation limit process gas chemistries available to European semiconductor manufacturers, while China's GB standards and MEE directives enforce localized environmental compliance for domestic fabs. Stakeholders must monitor evolving chemical hazard classifications and dual-use export control frameworks that could restrict plasma source technology transfers to specific fabrication regions.
Market Dynamics
Gate-all-around transistor architectures at sub-3nm nodes are forcing radical chamber redesigns as independent ion density control becomes non-negotiable for vertical nanosheet etch profiles.
Growth Catalysts
- EU Chips Act capital subsidies:European foundry buildouts in Dresden and Leuven are triggering equipment procurement waves for advanced logic capacity.
- 3D NAND string stacking:Memory manufacturers now exceed 200-layer vertical structures, multiplying etch steps per wafer and chamber utilization rates.
- China's MIIT localization mandates:Domestic fab equipment procurement quotas are redirecting supply chain flows toward certified local etch system vendors.
Market Restraints
- Fluorinated gas cost volatility:Perfluorinated compound prices swing with refrigerant market arbitrage and EPA emissions quota trading.
- RF power component concentration:Solid-state RF generators for sub-7nm precision depend on a narrow supplier base concentrated in Japan and Germany.
- Atomic-scale roughness limitations:Stochastic plasma-surface interactions at 2nm feature sizes introduce line-edge roughness that resist trimming cannot fully correct.
Strategic Opportunities
- India's semiconductor PLI scheme:Gujarat and Tamil Nadu greenfield fabs offer first-mover positioning for etch system vendors before supplier relationships solidify.
- Power device silicon carbide etch:Trench gate formation in 650V-1200V MOSFETs requires specialized high-rate silicon carbide chemistry development.
- Digital twin chamber modeling:Physics-based simulation platforms are compressing process development cycles and enabling remote troubleshooting services.
Industry Challenges
- Plasma physicist talent scarcity:Computational modeling of low-temperature plasma kinetics requires rare cross-training in atomic physics and semiconductor process engineering.
- Cleanroom footprint constraints:Next-generation multi-chamber cluster tools exceed existing fab bay dimensions, demanding costly structural retrofits.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plasma Etch System Market |
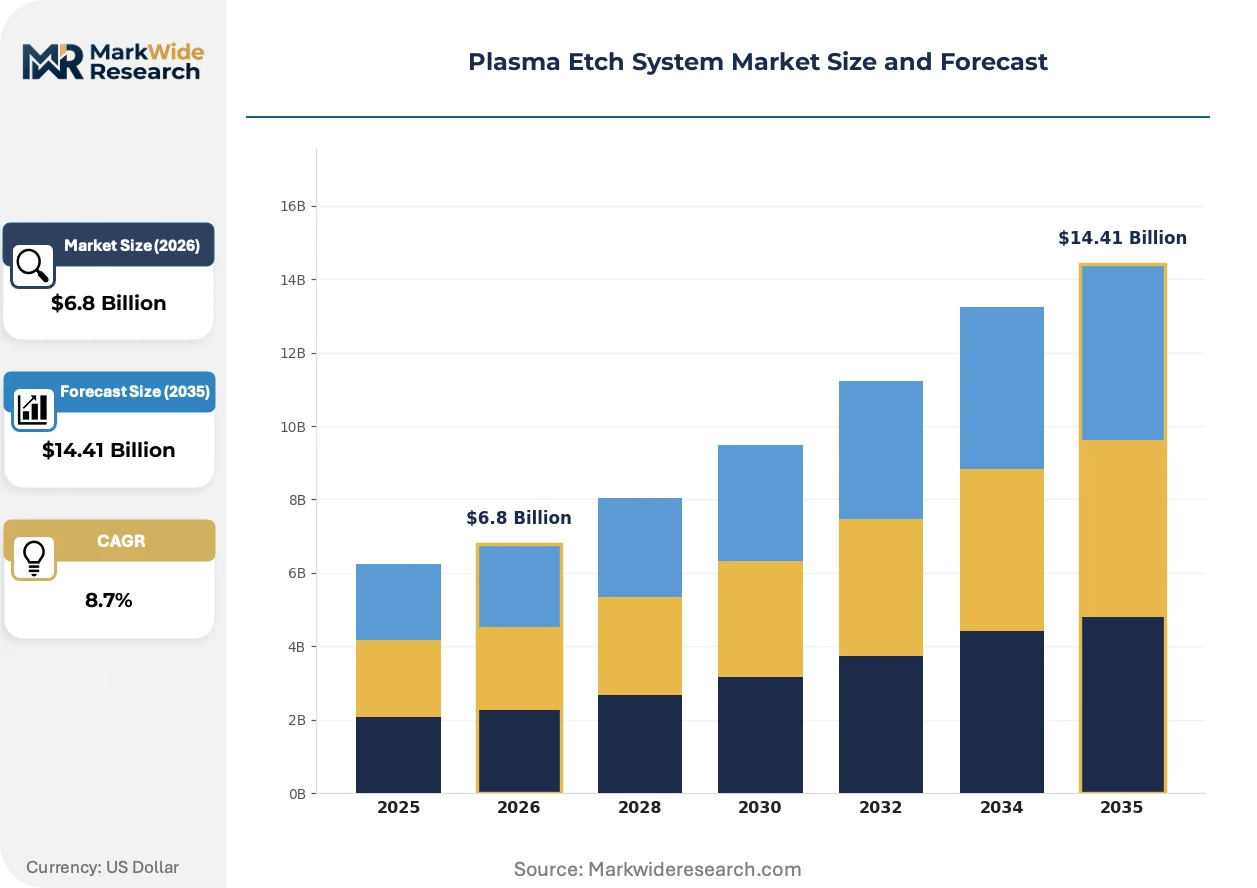
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.41 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dry Etcher, Reactive Ion Etcher, Plasma Ashing System, Barrel Etcher End User: Semiconductor Manufacturers, PCB Fabricators, MEMS Producers, Research Institutions Technology: Inductively Coupled Plasma, Capacitively Coupled Plasma, Microwave Plasma, Remote Plasma Application: Microelectronics, Nanotechnology, Solar Cells, Optoelectronics |
| Companies Covered | Lam Research Corporation, Applied Materials Inc., Tokyo Electron Ltd, SPTS Technologies, Oxford Instruments PLC, Plasma-Therm LLC, Samco Inc., Advanced Micro-Fabrication Equipment Inc., Sentech Instruments GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plasma Etch System Market Evolving Landscape
Plasma etch technology is bifurcating between extreme precision for logic scaling and extreme throughput for memory stacking, with equipment architectures diverging accordingly.
Atomic layer etching is hybridizing with conventional reactive ion etch platforms to enable Ångström-level thickness control. Memory manufacturers are piloting these hybrid sequences for 3D NAND staircase etch applications where critical dimension uniformity across 10+ micron depths is mandatory. The convergence is compressing process development timelines from months to weeks for new layer stacks.
REACH restrictions on perfluorinated compounds are forcing gas chemistry substitutions across European fabs. ECHA hazard classifications for NF3 and CF4 are triggering abatement system upgrades and process requalification cycles. German automotive chip suppliers are accelerating etch process audits to preempt supply chain disclosure requirements under the EU Corporate Sustainability Reporting Directive.
Foundry customers are unbundling etch chamber upgrades from full system replacement cycles. Taiwan-based logic manufacturers now procure plasma source retrofits and gas delivery module refreshes as standalone capital items. This consumption pattern is most visible in Hsinchu and Tainan Science Parks where tool depreciation schedules extend beyond technology node transitions.
Plasma Etch System Market Segmentation
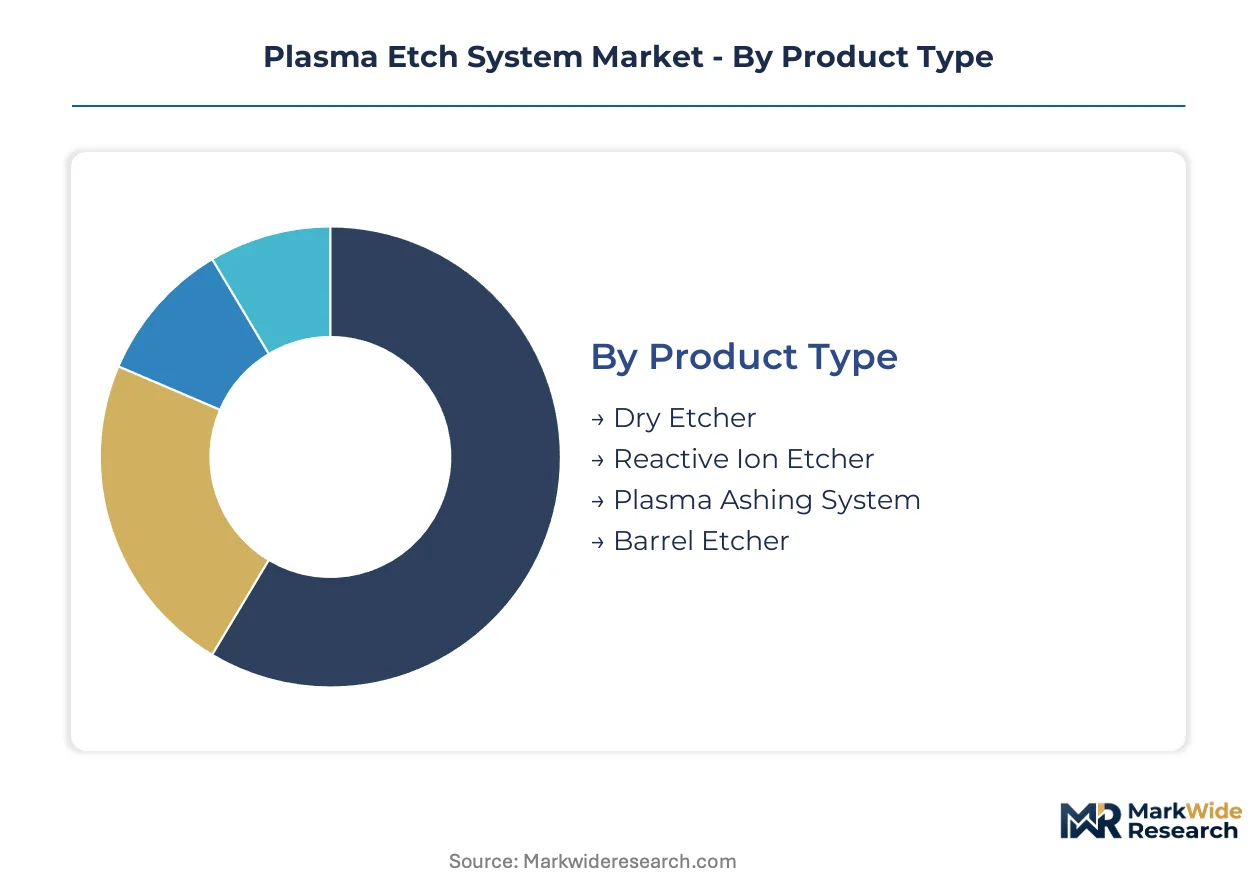
Equipment segmentation in plasma etch systems directly shapes aftermarket revenue streams, as chamber refurbishment cycles and consumables attach rates vary dramatically across product configurations and end-user categories. Understanding these structural differences enables vendors to calibrate service contracts and upgrade pricing to customer utilization intensity.
Product Type:
After-sales intensity peaks with dry etcher platforms, where chamber refurbishment and RF component replacement generate recurring revenue exceeding initial system margins over a ten-year operational life.
- Dry Etcher:These systems employ chemically reactive plasmas in vacuum environments to selectively remove dielectric and metal films with nanometer precision. Demand concentrates at Taiwan Semiconductor Manufacturing Company and Samsung Electronics foundry complexes, where sub-7nm logic production requires independent ion density and energy control for vertical nanosheet etch profiles. Chamber utilization rates exceed 85% in high-volume manufacturing, accelerating consumables turnover and preventive maintenance scheduling.
- Reactive Ion Etcher:Configurations combine physical ion bombardment with chemical reactivity to achieve anisotropic etch profiles in deep silicon structures. Bosch and STMicroelectronics MEMS fabrication facilities in Germany and France drive procurement, as trench and via formation for inertial sensors and pressure transducers demands precise sidewall angle management. The technology's versatility across silicon, silicon dioxide, and compound semiconductor substrates sustains multi-process tool deployment.
- Plasma Ashing System:Specialized equipment for photoresist stripping and organic residue removal operates at lower ion energies than etch platforms. Memory manufacturers deploy these for post-etch polymer cleaning in 3D NAND string fabrication.
- Barrel Etcher:Isotropic etch systems for non-critical layers and batch processing serve research institutions and specialty semiconductor producers with lower throughput requirements. Chinese domestic fabs incorporate these for trailing-node production where cost efficiency outweighs precision demands.
By volume, dry etcher installations lead. By growth pace, reactive ion etcher demand is ahead.
End User:
Customer type determines procurement authority structure, with semiconductor manufacturers centralizing capital decisions at corporate engineering headquarters while research institutions delegate to principal investigators.
- Semiconductor Manufacturers:Integrated device foundries and memory producers operate the highest chamber utilization rates, typically exceeding 7,000 hours annually. Taiwan and South Korean fabrication clusters anchor equipment demand, where advanced node capacity expansion triggers multi-chamber cluster tool procurement. These customers negotiate enterprise service agreements covering predictive maintenance and process engineering support.
- MEMS Producers:Bosch, STMicroelectronics, and TDK-InvenSense drive specialized etch system requirements for deep reactive ion etching of silicon structures. Automotive sensor demand in Germany and Japan sustains capital investment in high-aspect-ratio etch platforms.
- PCB Fabricators:Printed circuit board manufacturers deploy plasma etch for microvia drilling and surface treatment in high-density interconnect production. Southeast Asian facilities in Vietnam and Thailand concentrate demand.
- Research Institutions:University cleanrooms and national laboratories procure flexible multi-process platforms for process development and materials characterization. Funding cycles from NSF, DOE, and EU Horizon programs drive irregular purchase patterns.
Semiconductor manufacturers command the largest installed base. MEMS producers are expanding most quickly.
Technology:
Plasma source architecture determines process control capabilities, with independent ion density and energy decoupling becoming mandatory at sub-5nm nodes.
- Inductively Coupled Plasma:Separate RF coils decouple plasma generation from substrate bias, enabling independent control of ion density and ion energy. Leading logic foundries in Taiwan and South Korea standardize on ICP configurations for gate-all-around transistor fabrication.
- Capacitively Coupled Plasma:Parallel-plate electrode configurations dominate dielectric etch applications where simpler process control suffices. Mature node production in China and Malaysia sustains CCP equipment demand.
- Microwave Plasma:Electron cyclotron resonance sources generate high-density plasmas at lower pressures for advanced material etch. Compound semiconductor manufacturers in the United States and Japan deploy these for gallium nitride and silicon carbide processing.
- Remote Plasma:Downstream plasma generation separates active species creation from substrate exposure, minimizing ion damage. Photoresist stripping and surface preparation applications favor this architecture.
Capacitively coupled plasma retains volume leadership. Inductively coupled plasma is climbing the fastest.
Application:
Application focus shapes gas chemistry requirements and chamber materials compatibility, with compound semiconductor processing demanding specialized hardware configurations.
- Microelectronics:Silicon-based integrated circuit fabrication consumes the majority of etch system capacity, spanning logic, memory, and power device production. Taiwan Semiconductor Manufacturing Company and Samsung Electronics anchor demand concentration.
- Nanotechnology:Patterning of two-dimensional materials and quantum devices requires atomic-scale precision etch control. National laboratory and university research programs in the United States, Germany, and Japan drive specialized platform development.
- Solar Cells:Crystalline silicon photovoltaic manufacturing employs plasma texturing and edge isolation processes. Chinese and Southeast Asian cell production facilities sustain equipment demand.
- Optoelectronics:Laser diode and photodetector fabrication in compound semiconductors requires chlorine-based chemistries and corrosion-resistant chamber materials. Japanese and American producers concentrate demand.
Microelectronics applications dominate by volume. Nanotechnology shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Kaohsiung-Tainan high-speed rail corridor underwrites Taiwan's semiconductor logistics supremacy, shuttling wafers and equipment between southern fabrication parks and northern headquarters clusters within ninety minutes.
Taiwan
TSMC's N2 node ramp at Baoshan and Longtan Science Parks drives chamber procurement for gate-all-around transistor production. The National Development Council's Chip Industry Promotion Program subsidizes 20% of equipment costs for domestic suppliers. Hsinchu Science Park hosts the densest concentration of etch system service engineers outside Japan.
South Korea
Samsung Electronics and SK Hynix are expanding Pyeongtaek and Yongin complexes for 3D NAND string stacking beyond 300 layers. The Ministry of Trade, Industry and Energy's K-Semiconductor Belt initiative allocates $450 billion through 2030 for fabrication infrastructure. Seoul's Pangyo Techno Valley anchors equipment vendor regional headquarters and process engineering centers.
China
Yangtze Memory Technologies and Hua Hong Semiconductor are scaling domestic etch capacity under MIIT localization mandates requiring 50% domestic equipment procurement by 2025. GB standards and MEE directives enforce perfluorinated compound abatement at Shanghai and Beijing fabs. The Yangtze River Delta cluster concentrates 60% of national semiconductor equipment demand.
United States
Intel's Ohio One and Arizona Ocotillo campuses trigger multi-billion-dollar etch system orders for advanced logic and packaging applications. EPA emissions standards for CF4 and NF3 constrain process gas selection at domestic facilities. Oregon's Silicon Forest and Arizona's Phoenix metro area concentrate Intel and emerging foundry operations.
Japan
Kioxia and Western Digital's Yokkaichi and Kitakami fabs sustain demand for high-aspect-ratio etch platforms in 3D NAND production. METI's semiconductor revitalization strategy funds domestic equipment vendor competitiveness programs. The Tohoku region's Sendai-Kitakami corridor hosts specialized plasma source component manufacturing.
Plasma Etch System Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in RF power delivery and gas abatement subsystems. The vendor landscape consolidates around three chamber architecture standards, with second-tier players licensing core plasma source patents. Two strategic archetypes dominate: full-stack system houses with captive service networks, and focused subcomponent suppliers capturing margin in precision RF matching networks. Competitive moves center on vertical integration into consumables and geographic expansion through joint ventures in restricted markets.
Among North American platform vendors, Lam Research Corporation and Applied Materials Inc. occupy positions as archetypal full-stack integrators with recurring revenue engines in chamber refurbishment. Tokyo Electron Ltd represents the precision-specialist model, with its geographic origin signaling access to Japanese RF component supply chains. These three exemplify the divergence between scale-driven system consolidation and technology-differentiated niche positioning.
| Leading Market Players |
|---|
| Lam Research Corporation |
| Applied Materials Inc. |
| Tokyo Electron Ltd |
| SPTS Technologies |
| Oxford Instruments PLC |
| Plasma-Therm LLC |
| Samco Inc. |
| Advanced Micro-Fabrication Equipment Inc. |
| Sentech Instruments GmbH |
| Others |
Value Network & Pricing Analysis
Japanese solid-state RF generator suppliers concentrate upstream control over the highest-margin subsystem tier, forcing downstream etch system integrators to absorb cost volatility or pass through via service contract repricing. This concentration pattern situates margin capture with plasma source component specialists rather than platform assemblers.
Pricing Analysis
EPA emissions quotas for perfluorinated compounds dictate the pricing tier structure across North American installations, with abatement-equipped systems commanding premium positioning over standard configurations. Three-tier pricing structure across premium, standard, and economy levels separates ICP architectures with independent ion control from CCP platforms and refurbished trailing-node equipment. Cost compression in the economy tier is intensifying because Chinese domestic vendors undercut legacy import pricing. Memory manufacturers exhibit the highest price sensitivity due to volume procurement leverage, while leading logic foundries prioritize performance specifications over unit economics.
Supply Chain Analysis
High-purity fluorocarbon feedstock production centers on Japan, the United States, and Germany, with specialty gas purification capacity constraining wafer throughput at European fabs. Solid-state RF power modules, ceramic chamber components, and precision gas delivery systems draw from a narrow supplier base concentrated in the Tohoku region and Bavaria. Single-source vulnerability in ECR plasma source magnetics creates chokepoint exposure for compound semiconductor processors. Distribution runs through direct OEM service networks for high-value cluster tools, with regional spare parts hubs in Hsinchu, Pyeongtaek, and Dresden supporting uptime guarantees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cross-disciplinary plasma physicist talent shortages constrain process development velocity across all vendor tiers, creating durable competitive moats for firms with captive modeling capabilities and university partnership pipelines.
For Market Incumbents: Entrench installed base loyalty through predictive maintenance contracts and chamber refurbishment programs that extend depreciation schedules beyond node transitions. Deepen backward integration into consumables to capture recurring revenue streams threatened by third-party refurbishment entrants. Priority lever: captive RF matching network production to reduce Japanese supplier dependency. For New Entrants and Emerging Players: Trailing-node barrel etcher demand at Chinese domestic fabs represents the most penetrable entry point before certification requirements solidify around MIIT localization mandates. MEMS foundry clusters in Germany and Japan offer secondary white-space for specialized DRIE platforms with silicon carbide etch chemistry packages. Go-to-market angle: equipment-as-a-service financing structures that defer capital outlay for research institutions. For Investors and Strategic Acquirers: Capital is best deployed toward RF power delivery specialists with automotive-qualified manufacturing processes and existing relationships with Japanese magnetics suppliers. Long-term viability hinges on exposure to gate-all-around node ramps rather than mature planar capacity. Signal to watch: foundry disclosure of chamber utilization rates above 85% triggering refresh cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Digital Twin Chamber Modeling | Physics-based simulation platforms compress TSMC and Samsung process development timelines from months to weeks. |
| RF Power Module Backward Integration | Captive solid-state generator production insulates Lam Research and Applied Materials from Japanese supplier concentration risk. |
| Gas Chemistry Substitution R&D | Non-fluorinated etch process qualification preempts EPA and REACH regulatory restrictions on CF4 and NF3. |
| India Greenfield Joint Venture | First-mover positioning in Gujarat and Tamil Nadu fabs secures supplier relationships before PLI scheme allocations solidify. |
| Atomic Layer Etch Hybridization | ALE-RIE convergence enables Ångström-level control for 3D NAND staircase etch at SK Hynix and Kioxia. |
Research Methodology
Operator-level perspectives from etch process engineers, fab operations directors, RF component procurement leads, and aftermarket service managers anchored the qualitative base. Primary fieldwork combined with secondary validation against SEC 10-K filings from equipment vendors, SEMI equipment market data, Japanese METI industrial production statistics, and EPA emissions compliance disclosures. Bottom-up chamber installation counts triangulated against top-down foundry capital expenditure announcements.
Scenario-bracketing around high-low node transition velocity assumptions structured the analytical framework across the projection horizon. Segmentation dimensions modeled include plasma source architecture, end-user category, application focus, and regional regulatory cluster. CAGRs derived from weighted average of equipment shipment trajectories and fab capacity expansion pipelines. Forecast inputs incorporated MIIT localization quota enforcement timelines and EU Chips Act subsidy disbursement pacing.
Practitioners should monitor fluorocarbon gas price volatility and dual-use export control expansion for early signals requiring forecast revision. Cross-checking against SEMI quarterly equipment billings data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Equipment
Semiconductor Laser Equipment Market
Semiconductor Equipment
China Extreme Ultraviolet Lithography (EUVL) Systems Market
Semiconductor Equipment
Wafer Back-Grinding Machine Market
Semiconductor Equipment
Photolithography Market
Semiconductor Equipment
4-Inch SiC Laser Annealing Equipment Market
Semiconductor Equipment
Vacuum Soldering System Market
Semiconductor Equipment
Wafer CMP Machine Market
Semiconductor Equipment
Ion Beam Etching System Market
Semiconductor Equipment
Electrostatic Chucks Market
Semiconductor Equipment
Asia-Pacific Extreme Ultraviolet Lithography (EUVL) Systems Market
Semiconductor Equipment
India Extreme Ultraviolet Lithography (EUVL) Systems Market
Semiconductor Equipment
SMT Reflow Soldering Equipment Market
Semiconductor Equipment
Wet Based Wafer Cleaning Equipment Market
Semiconductor Equipment
Vacuum Coating Equipment Market
Semiconductor Equipment
Dry Reactor Market
Semiconductor Equipment
Automatic Laser PCB Depaneling Machines Market