
 Focused Ion Beam Market | 2026-2036
Focused Ion Beam Market Size, Share, and Industry Trends Forecast 2026-2036
Focused Ion Beam Market Intelligence
The European Union's push for energy efficiency in electronics under frameworks like the Ecodesign for Sustainable Products Regulation is rebalancing demand toward advanced semiconductor process control and failure analysis. This places a premium on tools that can rapidly diagnose defects in complex 3D chip architectures. Thermo Fisher Scientific leverages its broad portfolio in dual-beam systems to address these needs. Hitachi High-Tech competes on the precision of its instruments, while ZEISS differentiates through integrated workflow solutions.
A focused ion beam is a materials science tool that directs a finely focused stream of ions, often from a Gallium liquid metal ion source, onto a sample surface. This enables site-specific milling, deposition, imaging, and analysis with nanometer-scale precision. Its primary purpose is preparing ultra-thin samples for transmission electron microscopy and performing circuit editing on integrated circuits. Applications in semiconductor failure analysis and nanofabrication constitute the largest segments, while Gallium ion technology leads the market.
Export controls on advanced semiconductor equipment, managed by entities like the US Department of Commerce's Bureau of Industry and Security, directly shape market access. Concurrently, adherence to ISO 14644 cleanroom standards is a non-negotiable prerequisite for system installation in electronics manufacturing facilities in China and Germany. The key strategic decision for end-users revolves around the trade-off between capital expenditure for in-house systems and the operational expenditure for outsourced analytical services.
Market Dynamics
The semiconductor industry's transition to complex, three-dimensional gate-all-around transistor architectures is the central force shaping the market. This technological pivot demands unprecedented precision in failure analysis and process control, directly increasing the need for advanced focused ion beam capabilities.
Growth Catalysts
- Advanced Transistor Architectures:The adoption of gate-all-around (GAA) structures in sub-3nm semiconductor nodes necessitates nanometer-scale precision for process development and failure analysis, directly pulling demand for high-resolution FIB systems from leading foundries.
- Sustainable Electronics Regulation:The European Union's Ecodesign for Sustainable Products Regulation encourages higher energy efficiency, which spurs development of advanced power semiconductors and requires precise defect analysis tools like FIB to optimize device performance and manufacturing yields.
- Materials Science Expansion:Growth in materials research, particularly for next-generation batteries, advanced alloys, and composites, creates new demand for FIB systems for site-specific sample preparation and microstructural characterization in academic and industrial labs.
Market Restraints
- High Capital Expenditure:The significant upfront investment required for advanced dual-beam (FIB-SEM) systems acts as a major adoption barrier for smaller research institutions, startups, and academic labs, concentrating ownership among large corporations.
- Ion Implantation Artifacts:The potential for Gallium ion implantation and amorphization during the milling process remains a key technical restraint, as it can alter the properties of the sample and compromise subsequent atomic-scale analysis.
- Raw Material Concentration:The global supply of high-purity Gallium, essential for the dominant liquid metal ion source technology, is geographically concentrated, exposing the supply chain to price volatility and geopolitical trade risks.
Strategic Opportunities
- Quantum Computing Fabrication:The emerging field of quantum computing offers a high-value opportunity for FIB systems in the precise fabrication, modification, and characterization of qubits and other quantum device components.
- Instrument Integration:Combining FIB with complementary in-situ analytical techniques, such as energy-dispersive X-ray spectroscopy or Raman spectroscopy, into a single integrated workflow platform presents a major opportunity for improving analytical throughput.
- National Semiconductor Initiatives:Government-led programs like the US CHIPS and Science Act and India's Production Linked Incentive (PLI) scheme are creating new sales opportunities as they fund the construction of advanced fabrication and R&D facilities.
Industry Challenges
- Specialized Talent Scarcity:A persistent shortage of operators and engineers with the expertise to perform complex circuit editing, advanced TEM sample preparation, and system maintenance limits the effective utilization of the installed base.
- Regulatory and Compliance Burden:Navigating complex export controls from entities like the US Bureau of Industry and Security and meeting strict ISO 14644 cleanroom installation standards adds significant time, cost, and complexity to deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Focused Ion Beam Market |
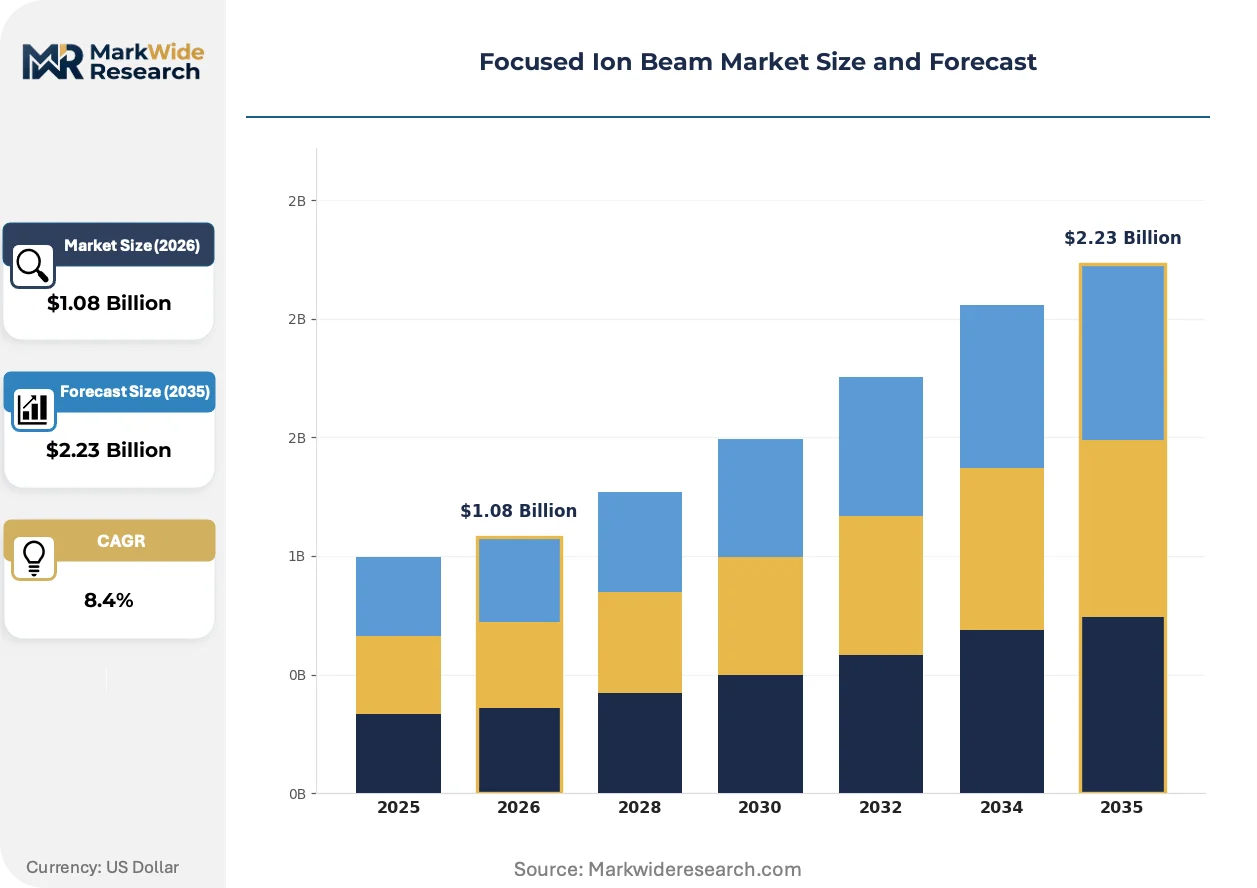
| Market Size in 2026 | $1.08 Billion |
| Market Size in 2035 | $2.23 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dual Beam Systems, Single Beam Systems, Plasma FIB, Gas Field Ion Source, Lithography FIB Technology: Gallium Ion, Helium Ion, Neon Ion, Xenon Ion, Lithium Ion Application: Semiconductor Inspection, Materials Research, Failure Analysis, Nanofabrication, Biological Sample Preparation End User Industry: Electronics Manufacturing, Academic Research, Aerospace Components, Defense Equipment, Nanotechnology Development |
| Companies Covered | JEOL Ltd., Raith GmbH, Thermo Fisher Scientific, A&D Company, Oxford Instruments, ZEISS, TESCAN, FOCUS GmbH, Hitachi High-Tech, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Focused Ion Beam Market Strategic Shifts & Innovations
Workflow integration is actively reshaping the market, driving a shift from standalone, general-purpose instruments toward automated, application-specific systems. This evolution prioritizes higher throughput and data consistency, especially within high-volume semiconductor fabrication and quality control environments.
Multi-ion source technology, which includes plasma FIB (PFIB) using heavier ions like Xenon, offers significantly faster milling rates for large-volume characterization. Materials science labs and semiconductor failure analysis teams are adopting these systems for rapid cross-sectioning and 3D reconstruction. This development is consolidating the market around versatile platforms that combine high-speed plasma milling with high-precision Gallium-based editing.
Export controls on advanced semiconductor equipment, administered by the US Department of Commerce, directly influence technology access and competitive dynamics. This regulatory pressure compels companies in affected regions to re-evaluate technology roadmaps and diversify their supply chains. The semiconductor industry in China is most impacted, which accelerates its domestic efforts to develop indigenous fabrication and analysis equipment.
A notable behavioral shift from pure capital equipment purchases toward hybrid access models that include outsourced analytical services is gaining traction. This allows smaller companies and research groups to utilize advanced FIB capabilities without the large upfront investment, paying instead for specific analytical tasks. This trend is most prominent within the biotechnology and academic research segments.
Focused Ion Beam Market Segmentation
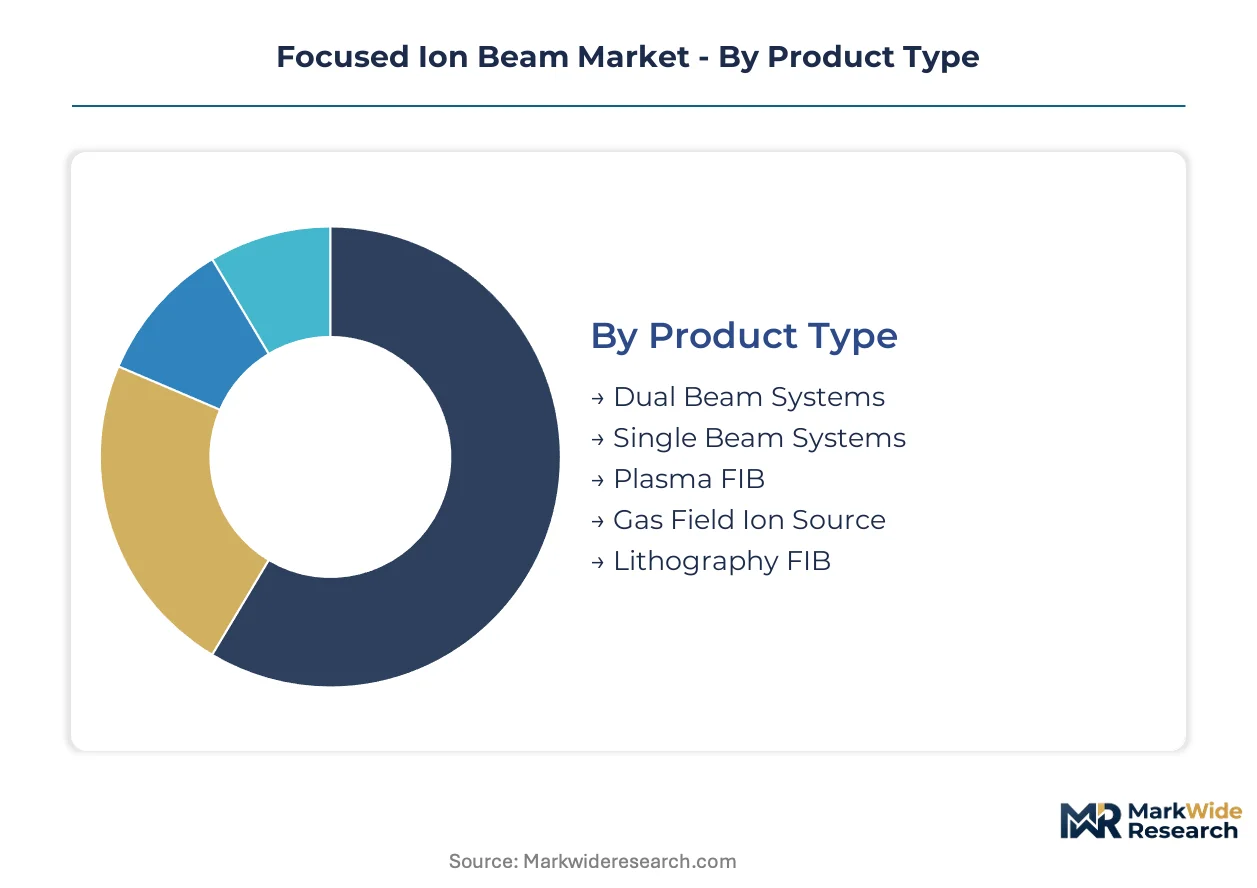
Segmentation within the Focused Ion Beam market clarifies the diverse needs driving system adoption across various industries. Understanding these distinct segments helps manufacturers tailor product development and service offerings. This analysis highlights specific technological preferences and application-driven demands that shape market dynamics.
Product Type:
Buyers in the product type segment are differentiated by their need for specific functionalities and throughput capabilities for their workflows.
- Dual Beam Systems:These instruments integrate a focused ion beam with a scanning electron microscope, enabling simultaneous milling, deposition, and high-resolution imaging. Semiconductor fabrication facilities in Taiwan and South Korea demand these for complex failure analysis.
- Plasma FIB:Utilizing heavier ions like Xenon, plasma focused ion beam systems offer significantly faster material removal rates compared to traditional Gallium-based sources. Materials science laboratories use these for rapid large-volume sample preparation.
- Single Beam Systems:These simpler, cost-effective FIB setups provide basic milling, deposition, and imaging capabilities for less demanding applications.
- Gas Field Ion Source:These systems employ a cryogenic field emitter to produce highly coherent, low-energy ion beams for ultra-high resolution imaging.
- Lithography FIB:Specialized FIB systems designed for direct-write nanofabrication, enabling precise pattern generation and modification on a nanometer scale.
Dual Beam Systems leads volumes today; Plasma FIB is gaining share fastest.
Technology:
The technology segment's performance characteristics and potential for ion implantation artifacts influence adoption across applications.
- Gallium Ion:This dominant liquid metal ion source technology provides a highly focused ion beam for precise milling, deposition, and imaging. Its widespread use in semiconductor failure analysis and TEM sample preparation drives market leadership.
- Xenon Ion:Employed in plasma FIB systems, Xenon ions offer much higher beam currents and faster milling rates, ideal for rapid cross-sectioning and large-volume material removal. Demand from advanced semiconductor manufacturers in the United States is accelerating adoption.
- Helium Ion:These sources produce very fine ion beams with minimal sample damage, suitable for high-resolution surface imaging.
- Neon Ion:Neon ion beams provide a balance between resolution and milling speed, finding niche applications in specific nanofabrication tasks.
- Lithium Ion:Emerging lithium ion sources are explored for specific applications requiring unique ion-material interactions, particularly in battery research.
Gallium ion technology dominates the current market landscape, while Xenon ion approaches exhibit the steepest expansion trajectory.
Application:
The application segment is shaped by the specific analytical challenges and precision requirements of various industries, from chip manufacturing to materials science.
- Semiconductor Inspection:This involves using FIB systems for in-line process control, defect review, and metrology in semiconductor manufacturing, crucial for sub-3nm node fabrication. The transition to GAA transistor architectures intensifies demand.
- Failure Analysis:Focused ion beams are indispensable for identifying and characterizing defects in integrated circuits and electronic components. This application supports yield improvement and reliability engineering for complex 3D chip architectures.
- Materials Research:FIB systems prepare ultra-thin samples for transmission electron microscopy and enable microstructural characterization of novel alloys.
- Nanofabrication:This application leverages FIB for direct-write lithography, creating nanoscale structures and modifying quantum devices with extreme precision.
- Biological Sample Preparation:FIB facilitates precise sectioning and thinning of biological specimens, enabling detailed imaging and analysis of cellular structures.
Semiconductor inspection and failure analysis drive significant demand, with nanofabrication also showing substantial growth.
End User Industry:
Customer types within the end-user industry segment range from large-scale industrial operations with high throughput needs to specialized research entities.
- Electronics Manufacturing:This sector utilizes FIB for process development, quality control, and failure analysis of semiconductor devices and advanced electronic components. Facilities in China and Germany require adherence to ISO 14644 cleanroom standards.
- Academic Research:Universities and public research institutions employ FIB systems for fundamental materials science, nanofabrication, and advanced microscopy. Smaller labs often opt for outsourced analytical services.
- Aerospace Components:The aerospace industry uses FIB for microstructural analysis, defect detection, and material characterization of critical components.
- Defense Equipment:FIB applications in defense involve materials analysis, reverse engineering, and quality assurance for high-performance military electronics.
- Nanotechnology Development:This segment leverages FIB for prototyping novel nanodevices, creating quantum structures, and advanced material synthesis.
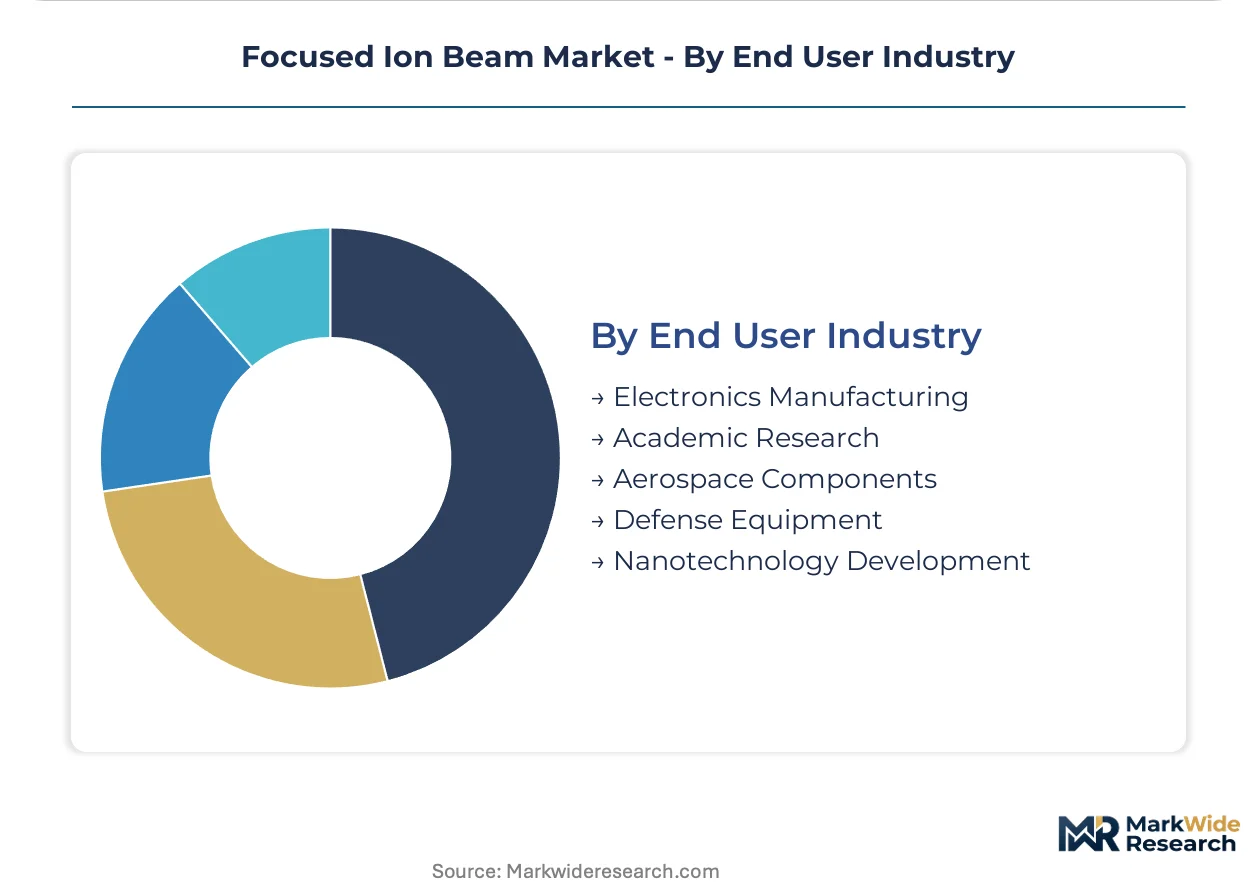
Electronics manufacturing represents the largest end-user segment, with nanotechnology development also expanding quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global focused ion beam market benefits from concentrated expertise in advanced semiconductor manufacturing. This specialized workforce drives innovation and adoption of sophisticated failure analysis tools. Key regions with high concentrations of skilled engineers and researchers significantly influence market expansion.
United States
The United States sees demand for FIB systems driven by quantum computing fabrication and advanced semiconductor research. The US CHIPS and Science Act provides significant funding for domestic chip production and R&D infrastructure. Austin, Texas, and Phoenix, Arizona, are developing new fabrication facilities requiring advanced metrology.
South Korea
South Korea's market growth stems from its leadership in advanced memory and logic chip development, particularly for GAA architectures. The country's national semiconductor initiatives support substantial investment in next-generation fabrication technologies. Gyeonggi Province remains a critical hub for major semiconductor foundries and advanced research.
Taiwan
Taiwan experiences strong demand from its high-volume, leading-node semiconductor manufacturing base for complex 3D chip architectures. Taiwan's government policies actively foster a competitive environment for advanced process control and failure analysis tools. The Hsinchu Science Park anchors global foundry services and advanced R&D.
China
China's market is shaped by its drive for indigenous semiconductor equipment development and failure analysis needs in electronics manufacturing. Export controls from the US Department of Commerce accelerate domestic efforts to develop advanced analysis tools. Shanghai and Shenzhen are emerging as key centers for local fabrication and R&D.
Germany
Germany shows robust demand for FIB systems in automotive electronics, industrial automation, and advanced materials science research. The EU Ecodesign for Sustainable Products Regulation encourages precise defect analysis for energy-efficient components. Dresden's "Silicon Saxony" region continues to attract investment in microelectronics and automotive R&D.
Focused Ion Beam Market Key Industry Players
Capital-heavy producers compete with asset-light designers, creating a market structure that balances specialized innovation with broad portfolio offerings for complex analytical needs. The focused ion beam market exhibits a moderately consolidated structure, with established players holding significant shares across various application segments. Strategic archetypes include integrated system providers, precision instrument specialists, and niche application innovators. Portfolio diversification into multi-ion source technologies and strategic partnerships for workflow integration are dominant competitive moves.
Integrated system providers, such as Thermo Fisher Scientific, exemplify broad portfolio strategies, leveraging their extensive product ranges to address diverse analytical requirements across multiple industries. ZEISS occupies a significant position as a precision instrument specialist, known for its advanced microscopy and integrated workflow solutions that streamline complex analytical processes. Hitachi High-Tech further anchors the market with its established reputation for high-precision instruments and broad technology offerings, particularly in semiconductor manufacturing. These major players collectively navigate the evolving landscape of advanced semiconductor inspection, failure analysis, and materials research.
| Leading Market Players |
|---|
| JEOL Ltd. |
| Raith GmbH |
| Thermo Fisher Scientific |
| A&D Company |
| Oxford Instruments |
| ZEISS |
| TESCAN |
| FOCUS GmbH |
| Hitachi High-Tech |
Cost & Logistics Intelligence
Gallium, as a critical raw material, influences the cost structure of focused ion beam systems, particularly those using liquid metal ion sources, impacting pricing for end-users like semiconductor foundries. This concentration of a key input affects the overall market dynamics.
Pricing Analysis
Bundled system sales, often including installation and initial training, contrast with unbundled service contracts for ongoing maintenance and analytical support. A hybrid pricing model combines capital expenditure for in-house systems with operational expenditure for outsourced analytical services. Price differentiation stems from system performance tiers, customization, and after-sales support levels. Pricing softness for basic single-beam systems reflects competition from alternative lower-cost microscopy techniques. Academic research institutions exhibit high price sensitivity, while advanced semiconductor manufacturers prioritize performance.
Supply Chain Analysis
Direct sales channels, often supported by specialized technical teams, manage high-value system deployments to electronics manufacturing facilities and research hubs. The supply of high-purity Gallium is geographically concentrated in China, exposing the supply chain to geopolitical trade risks. Key dependencies include Gallium for ion sources, high-precision optics, and advanced vacuum components. Geopolitical trade risks, particularly export controls on advanced semiconductor equipment, create supply chain volatility for end-users.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The focused ion beam market presents a late-cycle quality story, driven by the semiconductor industry's demand for ultra-precise defect analysis in sub-3nm gate-all-around architectures. This shift prioritizes advanced system capabilities and integrated workflow solutions.
For Market Incumbents:To counter market commoditization for basic FIB systems, established players must deepen vertical integration into critical component manufacturing. This secures supply chains and protects intellectual property in high-value sub-systems. Investing in multi-ion source R&D expands portfolios beyond Gallium-centric solutions. Strategic partnerships for workflow integration with other analytical tools enhance solution completeness.
For New Entrants and Emerging Players:Begin with targeting academic research and smaller companies seeking outsourced analytical services, leveraging hybrid access models. Focus on niche applications like advanced materials science or biological sample preparation, where cost-effectiveness differentiates offerings. A service-centric go-to-market approach, emphasizing rapid turnaround times, addresses the high capital expenditure barrier for in-house systems.
For Investors and Strategic Acquirers:Consolidation pressure builds where specialized talent scarcity limits operational scale and workflow integration creates value. The market offers long-term viability, underpinned by complex chip architectures and advanced materials innovation. Acquisition targets include niche innovators in multi-ion source technology or software providers for automated FIB data analysis. A signal to watch is increasing investment in quantum computing fabrication, demanding ultra-high precision nanofabrication tools.
| Strategic Initiative | Industry Significance |
|---|---|
| Develop next-generation multi-ion source systems | This initiative addresses the need for faster milling rates and broader material compatibility for advanced applications. |
| Integrate FIB with in-situ analytical techniques | Seamless workflow integration enhances analytical throughput and data consistency for semiconductor failure analysis teams. |
| Form strategic partnerships with quantum research labs | Collaborations accelerate the development of specialized FIB tools for fabricating and characterizing quantum devices. |
| Acquire software firms specializing in automated data analysis | Enhanced software capabilities streamline complex data interpretation and improve system usability for diverse end-users. |
| Expand service offerings in emerging fabrication hubs | Establishing a presence in regions like India supports new R&D facilities and provides localized analytical expertise. |
Research Approach
Bottom-up electronics manufacturing modeling reconciled against top-down advanced equipment supplier tracking forms the analytical core. Primary interviews with industry stakeholders and secondary validation informed this approach. Stakeholder roles included semiconductor R&D directors, materials science lab managers, FIB system engineers, and cleanroom operators. Secondary data comprised academic research, patent databases, national semiconductor initiative reports, and manufacturer filings.
Historical trendline analysis established baseline market performance across the analysis window, projecting future growth. Segmentation dimensions modeled included product type, technology, application, end-user industry, and regional manufacturing capacity. Compound annual growth rates derived from multi-variant regression analysis incorporated technological advancements and regulatory impacts. Forecast inputs included sub-3nm node fabrication roadmaps and cleanroom construction schedules.
Several conditions sit outside the modeled scope, including geopolitical shifts impacting raw material access or disruptive non-FIB analytical technologies. Forecasts reflect assumptions regarding sustained investment in advanced semiconductor R&D and stable export control regimes. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Equipment
China Extreme Ultraviolet Lithography (EUVL) Systems Market
Semiconductor Equipment
North America Semiconductor Etch Equipment Market
Semiconductor Equipment
Global Laser Dicing Systems Market
Semiconductor Equipment
Semiconductor Capital Equipment Market
Semiconductor Equipment
Global Semiconductor Machinery Market
Semiconductor Equipment
Global Semiconductor Stepper Systems Market
Semiconductor Equipment
Temperature Calibration Equipment Market
Semiconductor Equipment
Wafer CMP Machine Market
Semiconductor Equipment
Ion Milling System Market
Semiconductor Equipment
Vacuum Spin Coaters Market
Semiconductor Equipment
Die Bonder Machinery Market
Semiconductor Equipment
Semiconductor Wafer Cleaning Equipment Market
Semiconductor Equipment
Semiconductor Wafer Process Control Equipment Market
Semiconductor Equipment
4-Inch SiC Laser Annealing Equipment Market
Semiconductor Equipment
Vacuum Soldering System Market
Semiconductor Equipment
Solar Module Production Equipment Market