
 Global Vibratory Hammer Market | 2026-2036
Global Vibratory Hammer Market Size, Share, and Industry Trends Forecast 2026-2036
Global Vibratory Hammer Market Intelligence
The adoption of high-frequency, variable moment hammers for noise-sensitive urban projects is unwinding the market's reliance on traditional fixed-frequency models. This shift favors specialized suppliers like Dieseko Group, which leverages its PVE and ICE brands for a wide hydraulic range. BAUER Maschinen integrates its vibratory units into comprehensive foundation systems. Meanwhile, MOVAX Oy differentiates through its advanced side-grip pile driving technology, enhancing operational flexibility on constrained sites.
A vibratory hammer is a construction machine utilizing counter-rotating eccentric weights to produce vibration. This process liquefies adjacent soil, drastically reducing friction for pile driving and extraction. Hydraulic vibratory hammers dominate the product landscape due to their power-to-weight ratio and adaptability. While pile driving for bridges and marine construction remains the core application, Variable Frequency Drive technology is becoming a critical feature for winning contracts in regulated environments.
Noise and vibration regulations enforced by municipal authorities in cities like Berlin and Tokyo directly influence equipment selection toward lower-impact models. Concurrently, engine emission standards, including the EU's Stage V and the EPA's Tier 4 in the United States, dictate the power packs used with hydraulic units. Stakeholder decisions must therefore balance the capital cost of advanced, compliant equipment against the long-term benefits of broader market access and operational efficiency.
Market Dynamics
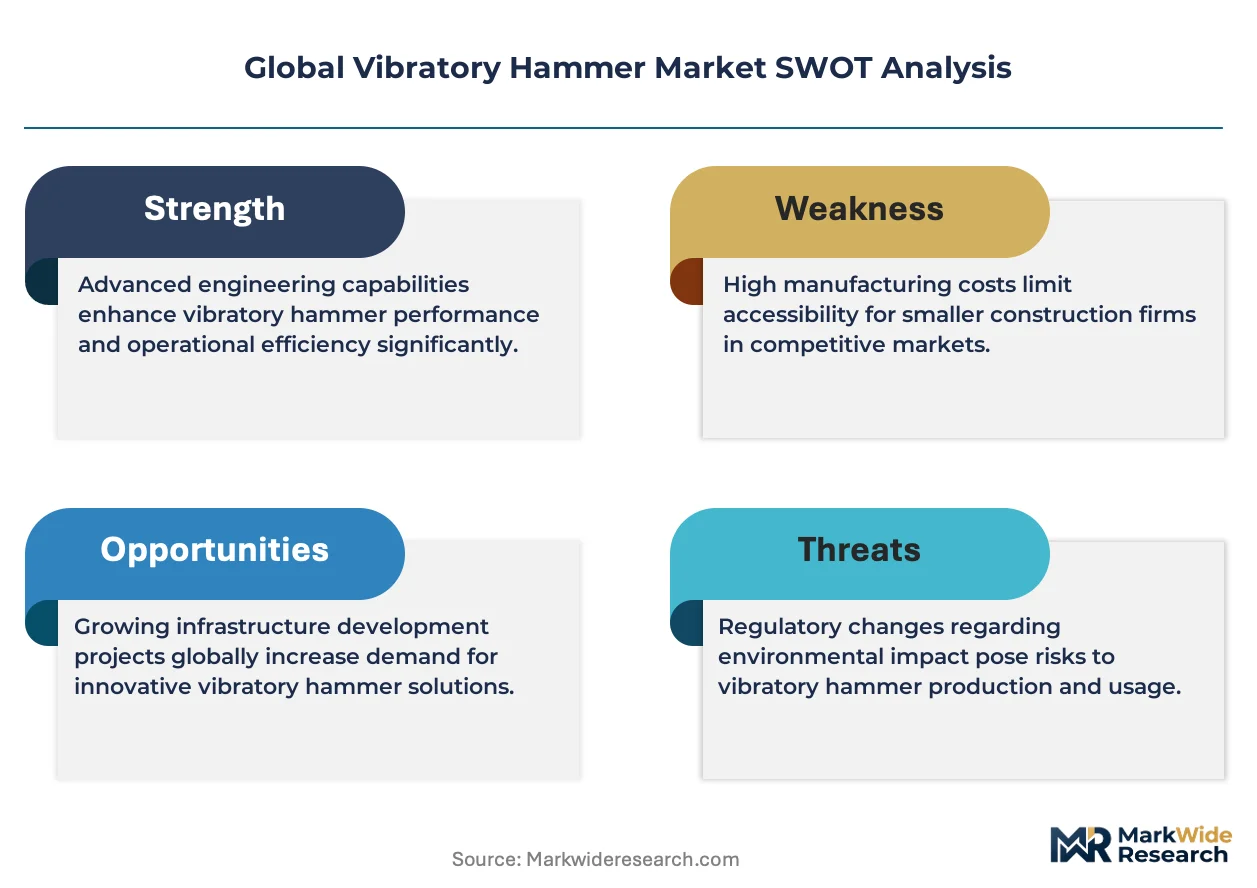
The vibratory hammer market is shaped by the fundamental tension between accelerating infrastructure development, particularly for marine energy projects, and tightening environmental regulations. This dynamic forces a market-wide pivot towards higher-cost, technologically advanced equipment that can meet stringent noise and emissions standards in urban and offshore environments.
Growth Catalysts
- Offshore Wind Development:Government-led initiatives, such as those aligned with the EU Green Deal, are accelerating the construction of offshore wind farms, creating substantial demand for large hydraulic hammers for monopile foundation installation.
- Southeast Asian Infrastructure:Rapid urbanization and economic expansion in nations like Vietnam and Indonesia are driving significant public and private investment in new bridges, ports, and high-rise buildings, which are core applications for pile driving.
- Variable Frequency Drive Adoption:The integration of VFD technology allows for precise control over vibration, minimizing negative externalities and enabling contractors to operate in previously inaccessible, highly regulated urban zones, thereby expanding the total addressable market.
Market Restraints
- High Capital Expenditure:The initial acquisition cost for high-frequency, variable moment hammers and their associated EU Stage V or EPA Tier 4 compliant power packs presents a significant financial barrier for small to mid-sized contractors.
- Stringent Noise Ordinances:Municipal regulations in densely populated cities, including Berlin and Tokyo, impose strict limits on noise and ground vibration, restricting the operational hours and types of hammers that can be deployed.
- Geotechnical Limitations:The effectiveness of vibratory hammers is highly dependent on soil composition. In dense, cohesive clays or ground with significant rock obstructions, the technology is less efficient, creating a substitution threat from bored piling or impact hammers.
Strategic Opportunities
- Decommissioning Services:The growing need to decommission aging offshore oil and gas platforms and wind turbines presents a significant opportunity for pile extraction applications, requiring powerful vibratory extractors.
- Sensor and Automation Integration:There is an opportunity to merge real-time geotechnical monitoring sensors with hammer control systems, enabling automated adjustments to frequency and amplitude for optimized pile driving efficiency and reduced soil fatigue.
- African Port Expansion:Underdeveloped coastal infrastructure across several African nations represents a long-term opportunity, as future investments in port modernization and logistics hubs will require extensive foundation work.
Industry Challenges
- Skilled Operator Scarcity:A shortage of technicians and operators proficient in managing the advanced electronic control systems of variable moment hammers limits the effective deployment and full utilization of the technology's capabilities.
- Emission Standard Compliance:The continuous evolution of engine emission standards, such as the transition to EU Stage V, requires significant and costly redesign efforts for hydraulic power pack manufacturers, impacting production timelines.
- System Integration Friction:Ensuring seamless compatibility between a vibratory hammer from one manufacturer and the complex hydraulic and control systems of a foundation rig from another remains a persistent technical challenge for contractors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Vibratory Hammer Market |
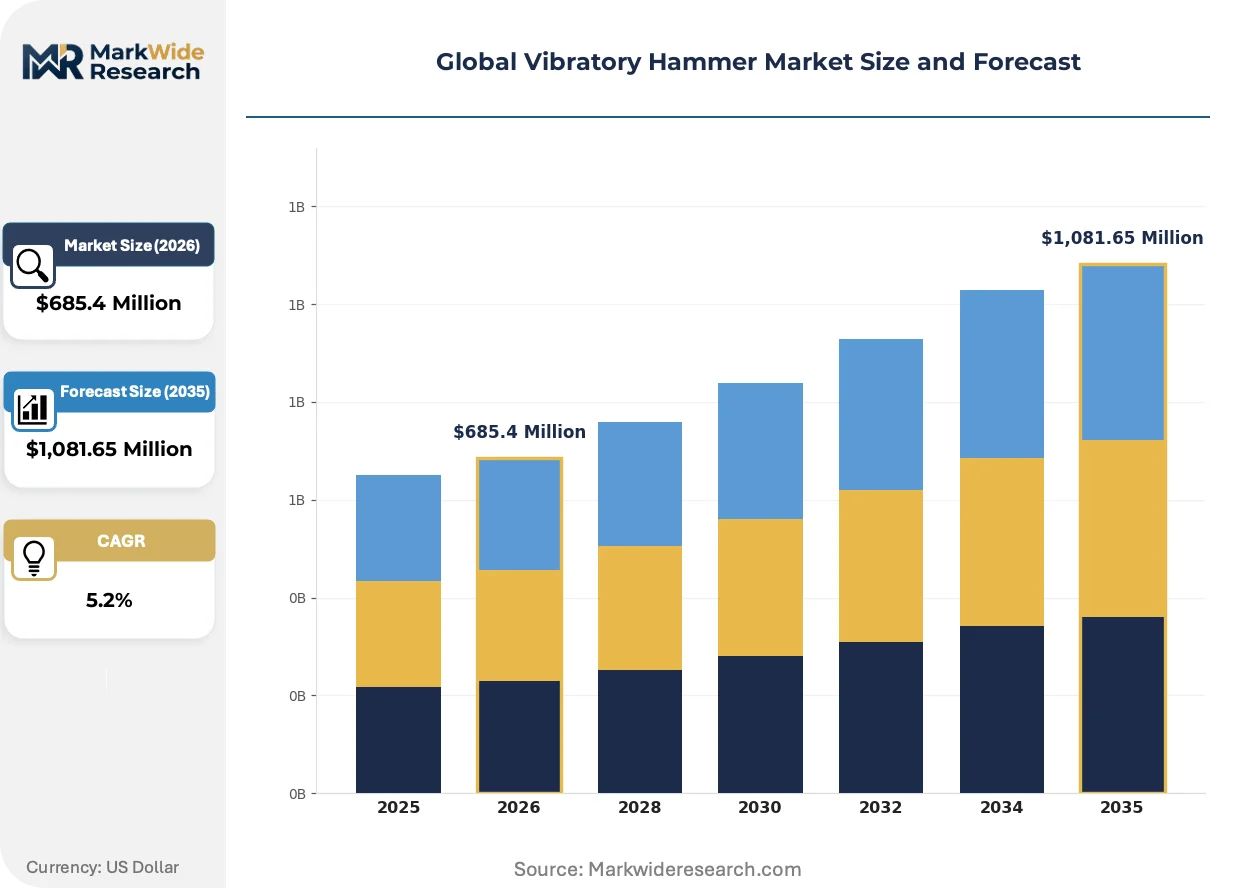
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,081.65 Million |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Vibratory Hammer, Hydraulic Vibratory Hammer, Diesel Vibratory Hammer, Pneumatic Vibratory Hammer Technology: Variable Frequency Drive, Fixed Frequency Drive, Dual Frequency Drive, Integrated Control Systems Application: Pile Driving, Bridge Construction, Marine Construction, Road Infrastructure, Dredging End User: Construction Companies, Foundation Contractors, Marine Contractors, Civil Engineering Firms |
| Companies Covered | BAUER Maschinen, Dieseko Group, Atlas Copco, Liebherr, ThyssenKrupp Infrastructure, MOVAX Oy, Junttan, American Piledriving Equipment, ABI Equipment Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Vibratory Hammer Market Strategic Shifts & Innovations
Technological refinement is directly responding to regulatory pressures, pushing the industry toward equipment that offers greater operational control and a lower environmental footprint. This evolution prioritizes efficiency and compliance, altering purchasing criteria and competitive dynamics across the equipment value chain.
Variable Frequency Drive (VFD) technology gives operators the ability to precisely adjust a hammer's operating frequency and eccentric moment during operation. Contractors executing projects in noise-sensitive urban centers or fragile marine ecosystems are the primary adopters. This advanced control capability is decomposing the market's traditional structure, which was based on simple fixed-frequency models, into a more sophisticated, performance-tiered landscape.
Engine emission mandates, including the EU's Stage V and the EPA's Tier 4 Final in the United States, directly govern the diesel power packs that drive hydraulic vibratory hammers. This regulatory pressure compels manufacturers to engineer cleaner, more complex power units, often incorporating diesel particulate filters and selective catalytic reduction systems. The hydraulic hammer segment is most impacted, with compliance becoming a prerequisite for market access in Europe and North America.
A distinct shift in equipment acquisition models is moving from direct capital purchases to project-based rental and leasing agreements. This trend disrupts the direct-to-contractor sales channel, benefiting large rental companies that can offer a diverse and modern fleet of specialized hammers. The pattern is most visible in developed markets where stringent, site-specific regulations make it uneconomical for many construction firms to own a comprehensive range of compliant equipment.
Global Vibratory Hammer Market Segmentation
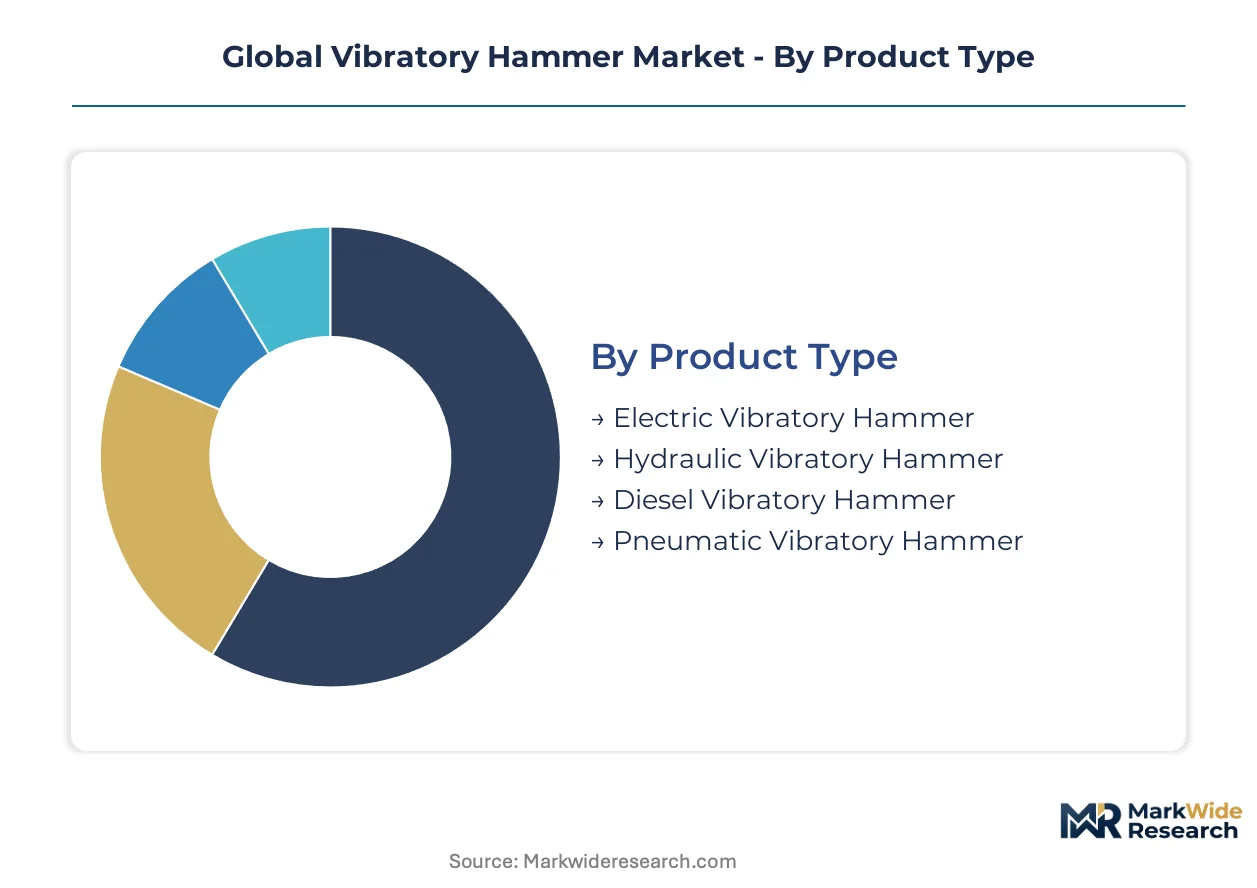
The vibratory hammer market segments reveal distinct preferences and operational drivers shaping equipment demand. Understanding these categories helps stakeholders align product development with evolving project requirements and regulatory landscapes. Each segment reflects specific technological capabilities and application environments.
Product Type:
The distribution channel for vibratory hammers often dictates the product types available to contractors, influencing both direct sales and rental fleet composition.
- Hydraulic Vibratory Hammer:These units utilize hydraulic power for superior force-to-weight ratios and precise control, making them highly adaptable across various ground conditions. Demand concentrates in marine construction, particularly for installing large monopiles in offshore wind farms in Europe and Asia.
- Electric Vibratory Hammer:Offering quieter operation and zero direct emissions, electric models are increasingly specified for environmentally sensitive or urban projects. Their adoption is growing in cities like Berlin and Tokyo, where stringent noise and emission regulations are enforced.
- Diesel Vibratory Hammer:Powered by internal combustion engines, these hammers provide robust performance in remote locations where electrical infrastructure is limited.
- Pneumatic Vibratory Hammer:Driven by compressed air, these hammers are less common and typically used for lighter piling applications or in specific industrial settings.
Hydraulic Vibratory Hammers dominate the installed base. Electric Vibratory Hammers are where expansion concentrates.
Technology:
Technological sophistication directly influences the operational environments where vibratory hammers can be deployed, impacting project viability in regulated zones.
- Variable Frequency Drive:VFD technology enables operators to precisely adjust vibration frequency and amplitude, optimizing performance and minimizing ground vibration and noise. This capability is critical for winning contracts in noise-sensitive urban centers and regulated marine environments.
- Integrated Control Systems:These systems combine real-time geotechnical monitoring with automated hammer adjustments, enhancing efficiency and reducing soil fatigue during pile driving. Such integration improves project outcomes in complex foundation work.
- Fixed Frequency Drive:These traditional systems operate at a constant frequency, offering a simpler, more cost-effective solution for less constrained construction sites.
- Dual Frequency Drive:Providing selectable operating frequencies, these systems offer greater versatility for adapting to a range of soil conditions than single-frequency models.
Variable Frequency Drive technology offers the most significant growth potential. Fixed Frequency Drive models maintain a substantial market presence due to their cost-effectiveness.
Application:
The diverse applications of vibratory hammers reflect their adaptability across various construction disciplines, from large-scale marine projects to essential urban infrastructure.
- Marine Construction:This segment includes installing foundations for offshore wind turbines, port expansions, and coastal protection structures. Government-led initiatives like the EU Green Deal significantly boost demand for hammers in these projects.
- Pile Driving:The fundamental application for vibratory hammers, encompassing the installation of various pile types for building foundations, bridges, and other structural supports. It remains a core activity across all global construction markets.
- Bridge Construction:Vibratory hammers are essential for establishing robust foundations for new bridges and viaducts, particularly in regions with soft ground conditions.
- Road Infrastructure:Used in constructing overpasses, underpasses, and retaining walls for road networks, these hammers support rapid development in urban and rural areas.
- Dredging:In specific dredging operations, vibratory hammers assist in the extraction of sheet piles or other temporary structures from waterways and harbors.
Marine Construction exhibits the steepest expansion trajectory. Pile Driving represents the largest volume application globally.
End User:
The end-user landscape for vibratory hammers is characterized by specialized contractors and larger construction firms, each with distinct equipment acquisition strategies.
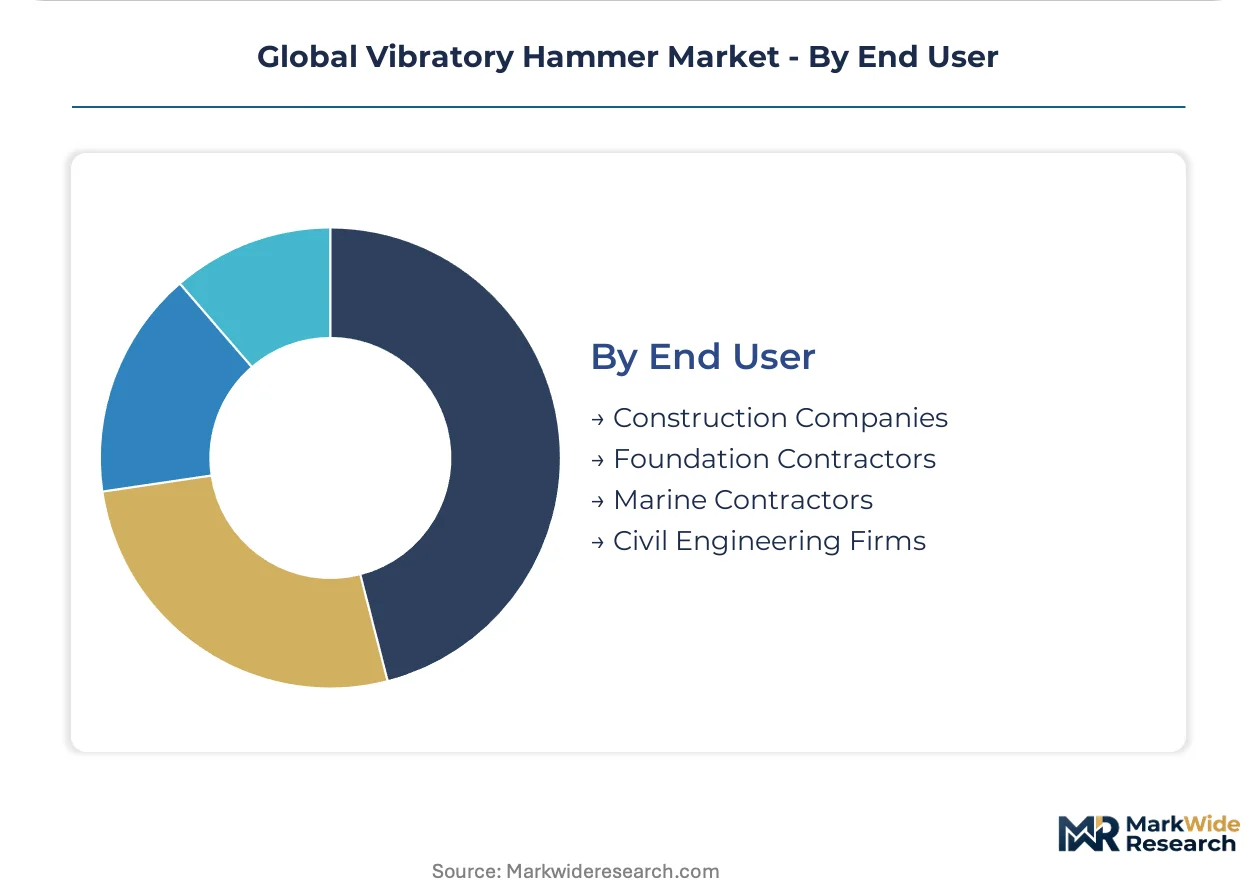
- Foundation Contractors:These specialized firms focus exclusively on deep foundation solutions, driving demand for high-performance, technologically advanced vibratory hammers. They often require compliant equipment for complex geotechnical challenges.
- Construction Companies:General construction firms utilize vibratory hammers for a wide range of projects, from commercial buildings to infrastructure. Their procurement often balances versatility with cost-effectiveness for diverse site requirements.
- Marine Contractors:Companies specializing in offshore and coastal projects are key users, requiring robust hammers for demanding underwater and near-shore foundation work.
- Civil Engineering Firms:While not direct equipment operators, these firms influence equipment selection through project specifications and design recommendations, particularly for public works.
Foundation Contractors are the primary drivers of advanced technology adoption. Construction Companies represent the largest customer base by volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Concentration in the vibratory hammer market is shifting towards regions with significant infrastructure development and stringent environmental regulations. Demand drivers include offshore wind projects, port expansions, and urban construction, particularly in Europe and Asia. These regions prioritize advanced equipment that meets evolving emissions and noise standards.
Germany
Offshore wind farm development and port modernization projects drive demand for large hydraulic vibratory hammers in Germany. The EU Green Deal initiatives accelerate investment in marine energy infrastructure across the North Sea. Berlin's municipal authorities enforce strict noise and vibration regulations, favoring electric and variable frequency drive models for urban construction.
Vietnam
Rapid urbanization and economic expansion fuel significant public and private investment in new bridges, ports, and high-rise buildings in Vietnam. The national infrastructure development plan mandates efficient construction methods for large-scale projects. Major coastal cities like Ho Chi Minh City and Da Nang are seeing increased demand for pile driving equipment for port upgrades and new commercial developments.
United States
Infrastructure modernization and offshore wind projects along the East Coast are boosting demand for vibratory hammers in the United States. The EPA's Tier 4 Final emission standards dictate the power packs used with hydraulic units. Construction in major metropolitan areas such as New York City and Los Angeles increasingly specifies lower-impact vibratory models to comply with local noise ordinances.
Japan
Urban redevelopment and coastal protection projects are key demand drivers for vibratory hammers in Japan. Tokyo's environmental regulations place strict limits on noise and ground vibration, promoting the adoption of high-frequency, variable moment hammers. Investment in resilient infrastructure following natural disasters also sustains demand for efficient pile installation and extraction.
Indonesia
Extensive port development and inter-island connectivity projects are driving substantial demand for vibratory hammers across Indonesia. The government's focus on infrastructure development includes new bridges and industrial parks. Jakarta and Surabaya are experiencing significant construction activity, requiring robust piling solutions for commercial and residential high-rises.
Global Vibratory Hammer Market Key Industry Players
Concentration sits with specialized manufacturers offering advanced hydraulic and variable frequency drive vibratory hammers. The market structure exhibits a tiered landscape, with a few large global players dominating the premium segment and numerous regional manufacturers competing on cost and localized service. Strategic competitive moves include technology licensing and continuous product innovation to meet evolving regulatory requirements.
Within the specialized equipment tier, Dieseko Group, leveraging its PVE and ICE brands, offers a wide hydraulic range for complex foundation work. BAUER Maschinen integrates its vibratory units into comprehensive foundation systems, providing end-to-end solutions for large-scale projects. MOVAX Oy differentiates through its advanced side-grip pile driving technology, enhancing operational flexibility on constrained sites for various contractors.
| Leading Market Players |
|---|
| BAUER Maschinen |
| Dieseko Group |
| Atlas Copco |
| Liebherr |
| ThyssenKrupp Infrastructure |
| MOVAX Oy |
| Junttan |
| American Piledriving Equipment |
| ABI Equipment Limited |
| Others |
Cost & Logistics Intelligence
Operational scale in vibratory hammer manufacturing dictates both supply concentration and establishes price floors for equipment. High fixed costs associated with specialized engineering and compliant power pack production limit the number of global players, influencing overall market pricing structures.
Pricing Analysis
EU Stage V and EPA Tier 4 emission standards dictate the pricing tier structure for vibratory hammers, especially for hydraulic units. Project-based pricing dominates for complex foundation work, reflecting customization and long-term support. Price differentiation stems from the integration of Variable Frequency Drive technology and the after-sales service packages offered by manufacturers. Pricing pressure intensifies for basic fixed-frequency models due to broader competition. Small to mid-sized contractors demonstrate the highest price sensitivity for initial capital expenditure.
Supply Chain Analysis
Germany, the Netherlands, and Finland anchor vibratory hammer manufacturing, producing specialized hydraulic and electric units. The supply chain draws from high-grade steel for hammer bodies, precision hydraulic components, and advanced electronic controls for VFD systems. Regulatory changes impacting engine emission standards represent a significant supply chain risk, requiring costly redesigns from power pack suppliers. Distribution runs through a dual model of direct sales to large foundation contractors and specialized equipment rental companies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Global infrastructure spending cycles, particularly in marine energy and urban development, are driving a cyclical recovery in the vibratory hammer market.
For Market Incumbents:
Consolidate market share by acquiring specialized technology developers in automation or electric hammer solutions. Expand rental fleet offerings for advanced, compliant equipment to counter the high capital expenditure barrier for smaller contractors. Invest heavily in R&D for next-generation VFD technology and integrated control systems to maintain a competitive edge against emerging specialized firms. Emphasize comprehensive after-sales support and operator training to mitigate skilled operator scarcity.
For New Entrants and Emerging Players:
Certification fast-tracks for noise-compliant electric hammers in urban centers offer a clear entry point. Target niche applications in noise-sensitive environments or regions with underdeveloped coastal infrastructure, such as African port expansion projects. Develop integrated sensor-based solutions for optimized pile driving, offering a distinct go-to-market angle. Focus on modular designs that simplify maintenance and reduce the total cost of ownership for regional contractors.
For Investors and Strategic Acquirers:
Specialized technology developers in VFD and automation represent attractive acquisition targets over the long term, driven by sustained demand for efficient and compliant solutions. The market benefits from ongoing global infrastructure development and the energy transition, ensuring viability for the next 5-10 years. A specific signal to watch is the volume of new offshore wind farm project announcements and the associated demand for large hydraulic hammers.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion for Electric Models | Increased production addresses rising demand in noise-sensitive urban construction projects. |
| Technology Licensing for VFD Systems | Accelerates market penetration of advanced control features across diverse equipment manufacturers. |
| Green Manufacturing Transition | Reduces the environmental footprint of production, aligning with global sustainability mandates. |
| Strategic Partnership with Rental Companies | Expands market access for high-cost compliant equipment, benefiting small and mid-sized contractors. |
| Product Launch of Automated Extractors | Addresses the growing need for efficient pile extraction in decommissioning services and urban redevelopment. |
Research Approach
A spread of perspectives from foundation contractors, marine contractors, equipment rental fleet managers, and vibratory hammer design engineers converged on the working assumptions for this study. Primary interviews with industry stakeholders were validated against secondary data sources, including government infrastructure spending reports, offshore wind project databases, construction equipment trade publications, and regulatory body reports, using bottom-up and top-down triangulation.
Product type (hydraulic, electric), technology (VFD, fixed frequency), application (marine, pile driving), end-user (foundation contractors, construction companies), and regional regulatory environment were the segmentation dimensions modeled. The analytical framework projects market growth across the analysis window, deriving Compound Annual Growth Rates through regression analysis and market share projections. Planned infrastructure project pipelines and regulatory compliance adoption rates served as key industry-specific forecast inputs.
Underlying assumptions cover stable economic growth and consistent infrastructure investment, with deviation risk concentrated in unforeseen geopolitical instability or rapid shifts in environmental regulations. Recalibration cycles align with material shifts in named drivers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Trash Rack Cleaning Machine Market
Construction Equipment
Shot Peening Machine Market
Construction Equipment
Walform Machines Market
Construction Equipment
Boring Bar Market
Construction Equipment
4-Wheel Sit-Down Counterbalance Forklift Market
Construction Equipment
Tunnel Boring Machines Market
Construction Equipment
Brazil Construction Equipment Market
Construction Equipment
Static and Rotating Equipment Market
Construction Equipment
Middle East and Africa Construction Equipment Market
Construction Equipment
Hydraulic Breaker for Excavator Market
Construction Equipment
Laser Cladding Systems Market
Construction Equipment
Vibratory Plate Compactors Market
Construction Equipment
Australia Concrete Pump Market
Construction Equipment
Derinding Machines Market
Construction Equipment
North America Mobile Crane Market
Construction Equipment
Excavator Wheels Market