
 Derinding Machines Market | 2026-2036
Derinding Machines Market Size, Share, and Industry Trends Forecast 2026-2036
Derinding Machines Market Analytics
Preventive maintenance contracts and blade-wear subscription analytics is repositioning how OEMs capture lifetime value from derinding equipment. Marel leverages its integrated software platform to lock in recurring revenue across installed bases. GEA Group sustains engineering leadership through in-house servo-motor development for precision blade control. NOCK Maschinenbau GmbH anchors its competitive stance with specialized knife geometries optimized for pork and beef hide removal.
A derinding machine is industrial equipment that mechanically separates skin, membrane, or fat layers from meat cuts using rotating knives, rollers, or automated blade arrays operating at controlled speeds and pressures. The primary purpose is to standardize yield rates and surface quality for downstream portioning, curing, or further processing. Automated Systems command the largest installed base due to labor-cost pressures in high-volume pork and beef operations, while Roller Machines represent the fastest-growing category as processors seek gentler handling for delicate seafood and poultry applications. Small Scale units retain margin pools in artisanal and specialty meat segments where batch flexibility outweighs throughput metrics.
FDA hazard analysis requirements and EFSA material-contact standards shape blade metallurgy, sanitation access, and clean-in-place protocols across export-oriented equipment lines. The EU Machinery Directive and CE marking mandate interlock systems and noise-emission controls that add engineering cost but filter out low-spec competitors. ISO 14159 hygiene design standards increasingly determine eligibility for tenders from multinational protein processors. Stakeholders must weigh retrofit compatibility against full-system replacement as electrical servo technology displaces legacy pneumatic and hydraulic actuation architectures.
Market Dynamics
Electrical servo actuation is displacing legacy pneumatic and hydraulic systems across meat processing lines, forcing OEMs to redesign blade control architectures and recalibrate maintenance revenue models around predictive analytics rather than scheduled part replacement.
Growth Catalysts
- FDA Hazard Analysis Mandates:US pork and beef processors must deploy automated derinding with documented blade-wear logs to satisfy hazard analysis requirements, accelerating capital expenditure cycles for compliant equipment.
- EFSA Material-Contact Standards:Blade metallurgy and sanitation-access designs must meet EFSA specifications for export eligibility into European markets, creating specification lock-in for certified OEMs.
- German Precision Engineering Clusters:Concentrated pork processing operations in Bavaria and Lower Saxony require high-throughput automated systems, anchoring regional demand for integrated blade-wear monitoring technology.
Market Restraints
- Specialized Servo-Motor Supply Concentration:Precision motion control components for blade arrays concentrate among a handful of European and Japanese suppliers, exposing OEMs to input cost volatility and extended lead times.
- EU Machinery Directive Compliance Burden:CE marking mandates for interlock systems and noise-emission controls add engineering cost layers that filter out low-spec competitors but also compress margin pools for mid-tier manufacturers.
- Manual Processing Substitution in Artisanal Segments:Small-scale specialty meat operations retain hand-derinding for batch flexibility, limiting addressable market expansion in premium niche categories.
Strategic Opportunities
- Seafood and Poultry Roller Machine Expansion:Gentler handling requirements for delicate species create white space for roller-based systems, with Nordic salmon processors and Dutch poultry cooperatives piloting lower-shear alternatives to blade arrays.
- ISO 14159 Hygiene Certification as Tender Gatekeeper:Multinational protein processors increasingly require ISO 14159-compliant equipment designs, creating regulatory tailwind for OEMs with validated clean-in-place protocols.
- Preventive Maintenance Subscription Models:Blade-wear analytics platforms enable recurring revenue capture from installed bases, shifting OEM economics from equipment margin to lifetime value extraction.
Industry Challenges
- Servo-Electrical Retrofit Integration Complexity:Legacy pneumatic and hydraulic actuation architectures in existing processing lines require costly electrical infrastructure upgrades, slowing replacement cycles and demanding hybrid engineering capabilities from service teams.
- CE Marking Certification Timeline Compression:Accelerated product development cycles strain notified body capacity, extending time-to-market for new blade-control architectures and compressing competitive response windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Derinding Machines Market |
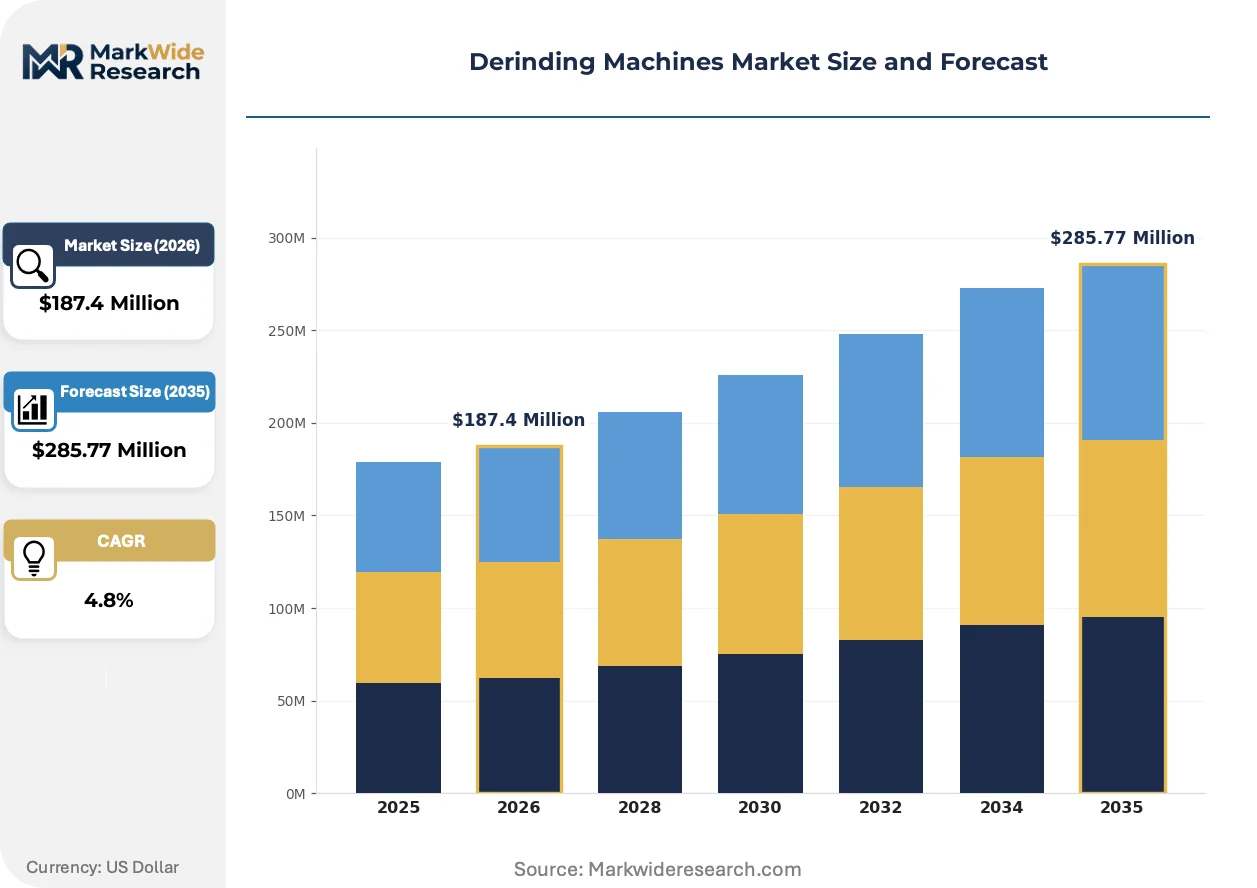
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $285.77 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Knife Machines, Roller Machines, Automated Systems, Manual Systems Technology: Mechanical, Pneumatic, Hydraulic, Electrical End User: Food Processing, Meat Processing, Seafood Processing, Industrial Applications Machine Size: Small Scale, Medium Scale, Large Scale, Custom Size |
| Companies Covered | Marel, GEA Group, NOCK Maschinenbau GmbH, Windsor Food Machinery, BAADER, JBT Corporation, Bühler, The Middleby Corporation, Bettcher Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Derinding Machines Market Evolving Landscape
Sensor-integrated blade monitoring and cloud-connected maintenance platforms are redefining how processing equipment generates value beyond the initial sale, shifting competitive advantage toward software-embedded hardware ecosystems.
Servo-electric blade positioning systems is absorbing the precision-control function previously handled by hydraulic actuators in high-volume pork operations. German and Danish beef processors are adopting these architectures at accelerating rates to meet yield-consistency targets. The technology is absorbing maintenance budget allocations as predictive algorithms replace scheduled blade replacement intervals.
EFSA material-contact standards are tightening specifications for blade metallurgy and surface finish in equipment destined for European protein processing facilities. Manufacturers must now document traceability for all food-contact components through the supply chain. Roller machine suppliers targeting Nordic seafood exports are responding with specialized knife geometries and enhanced sanitation access panels.
After-sales service unbundling is fragmenting traditional OEM revenue models as processors demand à-la-carte blade-wear analytics separate from full maintenance contracts. Independent software vendors are inserting themselves between equipment makers and end-users in Germany and the Netherlands. This pattern is most visible among mid-scale beef operations seeking to optimize maintenance spend across mixed-vendor processing lines.
Derinding Machines Market Segmentation
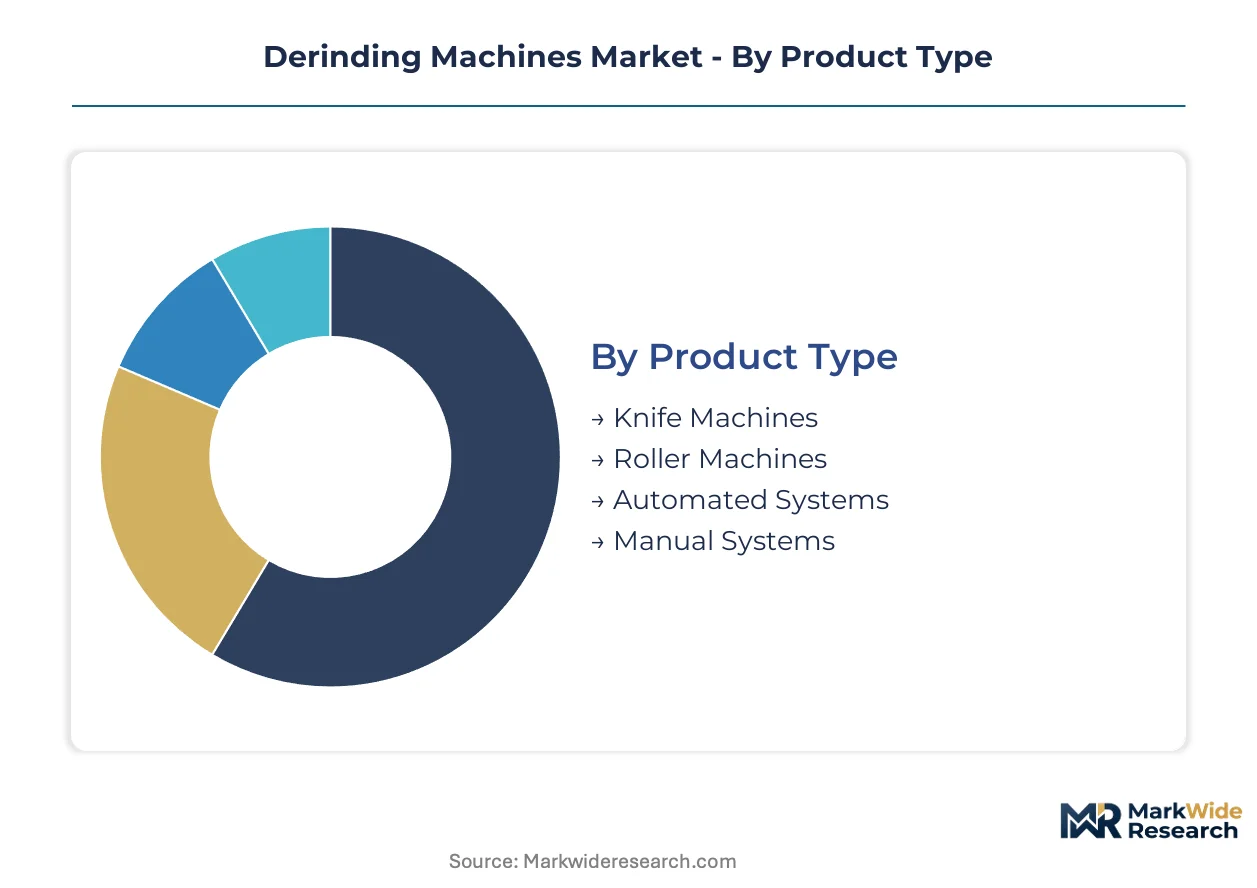
Segmentation in derinding equipment reveals how certification burdens, throughput requirements, and automation intensity reshape procurement patterns across protein processing verticals. Equipment buyers prioritize compliance-ready configurations that satisfy FDA hazard analysis mandates or EFSA material-contact standards depending on their export destination.
Product Type:
FDA hazard analysis requirements apply most stringently to Automated Systems and Knife Machines, where blade-wear documentation is mandatory for US pork and beef operations. Roller Machines face lighter regulatory scrutiny but must still satisfy EFSA material-contact standards for European seafood exports. Manual Systems fall outside automated compliance frameworks entirely, leaving artisanal processors to navigate basic sanitation protocols without continuous monitoring obligations.
- Automated Systems:Integrated blade arrays with servo-electric positioning and real-time wear monitoring dominate high-volume pork operations in Germany and Denmark. FDA-mandated hazard analysis documentation drives capital expenditure cycles among US processors seeking compliant yield-standardization.
- Roller Machines:Lower-shear mechanical separation using textured rollers preserves tissue integrity for delicate Nordic salmon and Dutch poultry applications. Seafood processors in Norway and Iceland pilot these systems to reduce product damage during skin removal.
- Knife Machines:Rotating blade configurations with adjustable cutting depths serve mid-scale beef operations requiring flexibility across carcass sizes.
- Manual Systems:Hand-operated tools retain relevance in specialty meat segments where batch variability outweighs throughput optimization.
Automated Systems sits at the top of the volume ranking, with Roller Machines climbing the fastest.
Technology:
Cost tiering separates legacy hydraulic installations from premium servo-electric architectures, with pneumatic systems occupying a narrowing middle ground as maintenance economics shift.
- Electrical:Servo-motor blade positioning delivers precision control for yield-consistency targets in German beef processing. Predictive maintenance algorithms replace scheduled blade replacement intervals, absorbing capital budgets previously allocated to hydraulic infrastructure.
- Hydraulic:Legacy actuation architectures persist in installed bases but face displacement as electrical servo systems demonstrate superior repeatability and reduced contamination risk.
- Pneumatic:Compressed-air systems retain footholds in mid-tier pork operations where upgrade capital is constrained but performance demands are moderate.
- Mechanical:Direct-drive configurations without fluid power suit small-scale facilities with limited technical support capabilities.
Electrical technology commands the highest capital allocation per installation, while Mechanical systems face steepest share erosion.
End User:
Application intensity varies dramatically across protein categories, with red meat operations demanding the most rigorous automation and seafood processors prioritizing gentle handling.
- Meat Processing:High-throughput pork and beef facilities in Bavaria and Lower Saxony require integrated blade-wear monitoring and documented compliance with EU Machinery Directive interlock mandates.
- Seafood Processing:Nordic salmon processors and Dutch cooperatives drive demand for roller-based alternatives that minimize shear damage to delicate fillet structures.
- Food Processing:Diversified protein handlers seek modular equipment capable of switching between species with minimal reconfiguration downtime.
- Industrial Applications:Non-food hide processing and rendering operations utilize derinding technology for byproduct valorization outside regulated food-contact frameworks.
Meat Processing generates the largest equipment volume, with Seafood Processing expanding most quickly as roller technology matures.
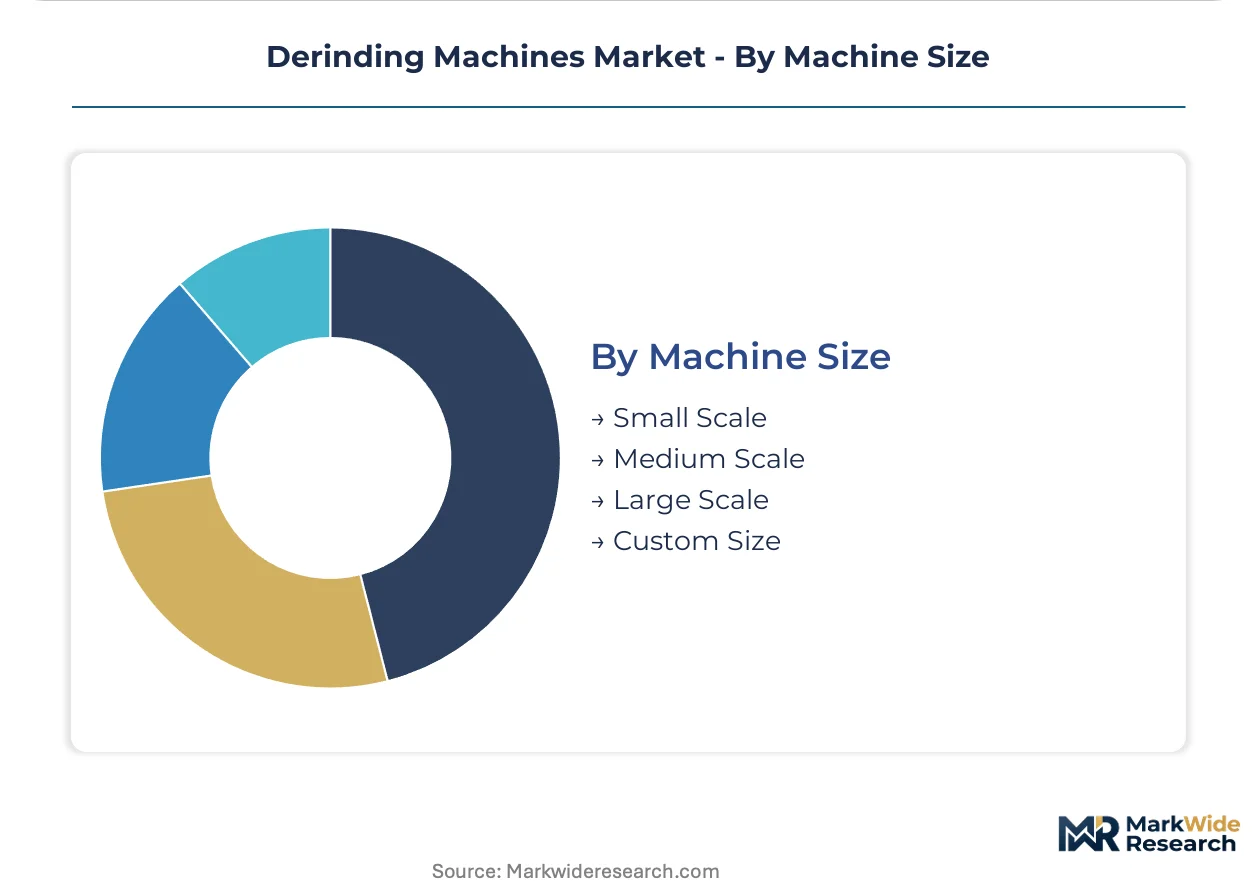
Machine Size:
Customer scale determines whether procurement prioritizes throughput maximization or batch flexibility, with multinational processors and artisanal operators occupying opposite ends of the specification spectrum.
- Large Scale:Continuous-feed systems with automated blade arrays and clean-in-place protocols serve multinational protein processors requiring ISO 14159 hygiene certification for tender eligibility.
- Small Scale:Batch-operated units with manual loading and tool-free sanitation access retain margin pools in specialty meat segments where product variety outweighs line speed.
- Medium Scale:Semi-automated configurations bridge the gap between artisanal flexibility and industrial throughput for regional cooperatives.
- Custom Size:Engineered-to-order dimensions accommodate non-standard facility layouts or specialized species handling requirements.
Large Scale installations dominate capital deployment, with Small Scale units showing resilient niche persistence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany deploys automated derinding systems at triple the density of Spain, while Danish pork processors outpace Italian beef operators in servo-electric adoption rates. National regulatory frameworks and cluster economics explain these divergent equipment penetration patterns.
Germany
Bavarian and Lower Saxony pork processors drive demand for high-throughput automated systems with integrated blade-wear monitoring. The EU Machinery Directive mandates interlock systems and noise-emission controls that filter out low-spec competitors. Precision engineering clusters around Stuttgart and Nuremberg anchor servo-motor supply relationships for blade control architectures.
United States
US pork and beef processors accelerate capital expenditure cycles to satisfy FDA hazard analysis requirements for documented blade-wear logs. The FDA mandates automated derinding with continuous monitoring for large-scale operations. Midwest processing corridors in Iowa and Illinois concentrate deployment of compliance-ready equipment configurations.
Denmark
Danish beef processors adopt servo-electric blade positioning at accelerating rates to meet yield-consistency targets for export markets. EFSA material-contact standards shape blade metallurgy specifications for European market access. Copenhagen-region engineering firms supply predictive maintenance platforms to regional protein processors.
Netherlands
Dutch poultry cooperatives pilot roller-based derinding systems to reduce shear damage in delicate fillet processing. EFSA sanitation-access requirements determine clean-in-place protocol designs for equipment tenders. Food Valley clusters around Wageningen drive innovation in gentler handling technologies for white meat applications.
Spain
Spanish pork processors lag Northern European counterparts in automation intensity but expand medium-scale semi-automated installations. CE marking compliance adds engineering cost layers that compress margin pools for domestic equipment purchasers. Catalonian meat processing hubs around Barcelona concentrate regional demand for retrofit-compatible systems.
Derinding Machines Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated OEMs capturing premium tiers and regional fabricators serving price-sensitive niches. The vendor base concentrates among European engineering houses and diversified food equipment conglomerates with protein processing portfolios. Three archetypes dominate: precision-engineering specialists with proprietary blade geometries, diversified industrial groups leveraging cross-product service networks, and regional machinery builders competing on customization agility. Consolidation through strategic technology licensing and geographic expansion into seafood processing verticals represents the primary competitive trajectory.
Among European precision-engineering specialists, NOCK Maschinenbau GmbH exemplifies the blade-geometry-focused archetype with specialized knife configurations for pork and beef hide removal. Marel and GEA Group occupy positions within the diversified industrial tier, with the former representing software-integrated platform strategies and the latter exemplifying in-house servo-motor development capabilities for precision blade control. These three anchors illustrate how competitive positioning fragments across engineering depth, vertical integration choices, and service model architecture.
| Leading Market Players |
|---|
| Marel |
| GEA Group |
| NOCK Maschinenbau GmbH |
| Windsor Food Machinery |
| BAADER |
| JBT Corporation |
| Bühler |
| The Middleby Corporation |
| Bettcher Industries |
| Others |
Value Network & Pricing Analysis
Electrical servo actuation displacing legacy pneumatic systems simultaneously compresses maintenance revenue pools and concentrates component sourcing among German and Japanese precision motor suppliers. This technology transition reshapes cost economics for OEMs while locking in supply dependencies that amplify pricing power at the input tier.
Pricing Analysis
Capacity additions in Denmark and the Netherlands are reshaping price floors for mid-tier automated systems as regional cooperatives expand servo-electric installations. Pricing stratifies across premium, standard, and economy tiers based on ISO 14159 certification status and bundled predictive maintenance analytics. Cost compression in standard-tier equipment is intensifying because independent software vendors unbundle blade-wear monitoring from full service contracts. Small-scale artisanal processors exhibit highest price sensitivity, while multinational protein processors in Germany demonstrate lowest sensitivity due to compliance-driven procurement mandates.
Supply Chain Analysis
Precision servo-motor supply rests on German, Japanese, and Swiss specialty electromechanical producers with limited second-source alternatives. Blade metallurgy draws from Swedish and Austrian specialty steel mills, while control system electronics feed from Taiwanese and South Korean semiconductor fabricators. Single-source vulnerability concentrates in high-torque servo drives for blade positioning arrays. Distribution runs through OEM-direct channels for large-scale installations and regional equipment distributors serving mid-tier meat processing cooperatives.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where FDA hazard analysis mandates and EFSA material-contact standards continuously refresh equipment replacement cycles. The EU Machinery Directive's CE marking requirements anchor demand durability for compliant OEMs.
For Market Incumbents:Cement recurring revenue capture by deepening predictive maintenance platform penetration across installed bases before independent software vendors fragment analytics access. Invest in backward integration into servo-motor development to offset supply concentration risk from Japanese and German component suppliers. Defend against regional machinery builders in Spain and Italy by accelerating ISO 14159 certification timelines that filter out low-spec competitors.
For New Entrants and Emerging Players:Independent software vendors represent the most penetrable channel archetype for blade-wear analytics unbundling, particularly among Dutch and German mid-scale beef operations seeking à-la-carte optimization tools. Target Nordic seafood processing cooperatives with roller-based system alternatives that address shear-damage sensitivity in salmon fillet applications. Pursue co-development partnerships with Wageningen-region Food Valley clusters to validate gentler handling protocols for white meat processors.
For Investors and Strategic Acquirers:Valuations sit cheapest among regional machinery builders in Southern Europe lacking CE marking certification depth and predictive maintenance software capabilities. Long-term viability across the analysis window favors OEMs with demonstrated FDA and EFSA compliance track records that lock in tender eligibility for multinational protein processors. Watch for inflection signals in servo-motor supply lead times that would compress margin pools for non-integrated equipment manufacturers.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Servo-Motor Development | GEA Group's in-house production of precision blade control components reduces exposure to Japanese and German supplier concentration. |
| Predictive Maintenance Platform Launch | Marel's software-embedded hardware ecosystems shift economics from equipment margin toward lifetime value extraction from installed bases. |
| ISO 14159 Hygiene Certification Investment | Compliance with international hygiene design standards determines tender eligibility from multinational protein processors in Germany and Denmark. |
| Seafood Roller Machine Geographic Expansion | Nordic salmon processors in Norway and Iceland pilot lower-shear alternatives to blade arrays for delicate fillet handling. |
| Blade Metallurgy Supply Agreement | Documentation of food-contact component traceability satisfies EFSA specifications for European market access and export eligibility. |
Research Methodology
Coverage spans Germany, the United States, Denmark, the Netherlands, and Spain, with primary inputs from each market cluster. The research combines structured interviews with maintenance directors at pork and beef processing facilities, OEM procurement teams, and aftermarket service heads with secondary validation from FDA 483 inspection observations, EFSA scientific opinions on material-contact standards, and EU Machinery Directive compliance databases. Customs records for servo-motor and specialty steel imports, SEC filings from diversified food equipment conglomerates, and ISO certification registries provided additional triangulation anchors. Bottom-up equipment shipment tallies and top-down protein processing capacity estimates were cross-referenced for consistency.
Segmentation granularity was modeled at the product-type, technology, end-user, and machine-size dimensions, with additional disaggregation by regulatory compliance tier across the projection horizon. CAGRs were derived from installed base growth rates, replacement cycle compression from FDA mandates, and technology transition assumptions for servo-electric displacement. Forecast inputs incorporated blade-wear monitoring adoption curves, EFSA material-contact specification timelines, and regional pork and beef processing capacity expansion plans from industry associations.
Revisions become necessary when FDA enforcement intensity shifts, EFSA tightens material-contact standards, or servo-motor supply disruptions extend lead times beyond hybrid engineering adaptation capacity. A small set of named triggers warrants ongoing watch: CE marking notified body capacity constraints, independent software vendor market share gains in analytics unbundling, and German precision engineering cluster labor availability.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Oxy-Fuel Welding Equipment Market
Construction Equipment
Canada Construction Equipment Market
Construction Equipment
Electric Shovel Market
Construction Equipment
Malaysia Plastic Injection Molding Machine Market
Construction Equipment
Earthmoving Equipment Tyres Market
Construction Equipment
Assembly Machine Market
Construction Equipment
Broaching Machine Market
Construction Equipment
Cold Heading Machine Market
Construction Equipment
CNC Machine Market
Construction Equipment
Mexico Flexible Concrete Vibrator Market
Construction Equipment
Australia Mobile Cranes Rental Market
Construction Equipment
Europe Construction Equipment Market
Construction Equipment
Cold Planers Market
Construction Equipment
Felling Heads Market
Construction Equipment
Global PDC Drill Bits Market
Construction Equipment
Industrial Grout Pumps Market