
 Brazil Construction Equipment Market | 2026-2036
Brazil Construction Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Brazil Construction Equipment Market Insights
Tier-4 Final emission-compliant machinery is rotating through Brazilian rental and contractor fleets as the dominant procurement standard. Caterpillar Inc. leverages its parts distribution network across Minas Gerais and Paraná to sustain aftermarket revenue. Komatsu Ltd. anchors its position through localized assembly and technical training centers. Volvo Construction Equipment differentiates via connected fleet management platforms.
Brazil construction equipment encompasses earthmoving, lifting, and material handling machinery engineered to hydraulic pressure ratings and payload specifications for tropical operating conditions. These machines execute grading, excavation, and vertical transport across residential, commercial, and extractive sites where soil composition and humidity demand reinforced undercarriages and corrosion-resistant finishes. Excavators command the largest installed base among product types, though autonomous machinery represents the fastest-expanding technology category as labor costs and site safety protocols intensify. Infrastructure Development absorbs the deepest equipment deployment among applications, while mining contractors generate the highest margin pools per machine-hour.
ANVISA oversees operator safety certification standards, while the Brazilian Institute of Environment and Renewable Natural Resources enforces noise and emission thresholds for worksites near protected areas. The Central Bank of Brazil's credit directives through BNDES shape equipment financing availability for mid-sized contractors. Stakeholders must track how the National Land Transport Agency's weight-bridge enforcement and pending CONAMA resolutions on diesel particulate limits will reshape fleet composition decisions.
Market Dynamics
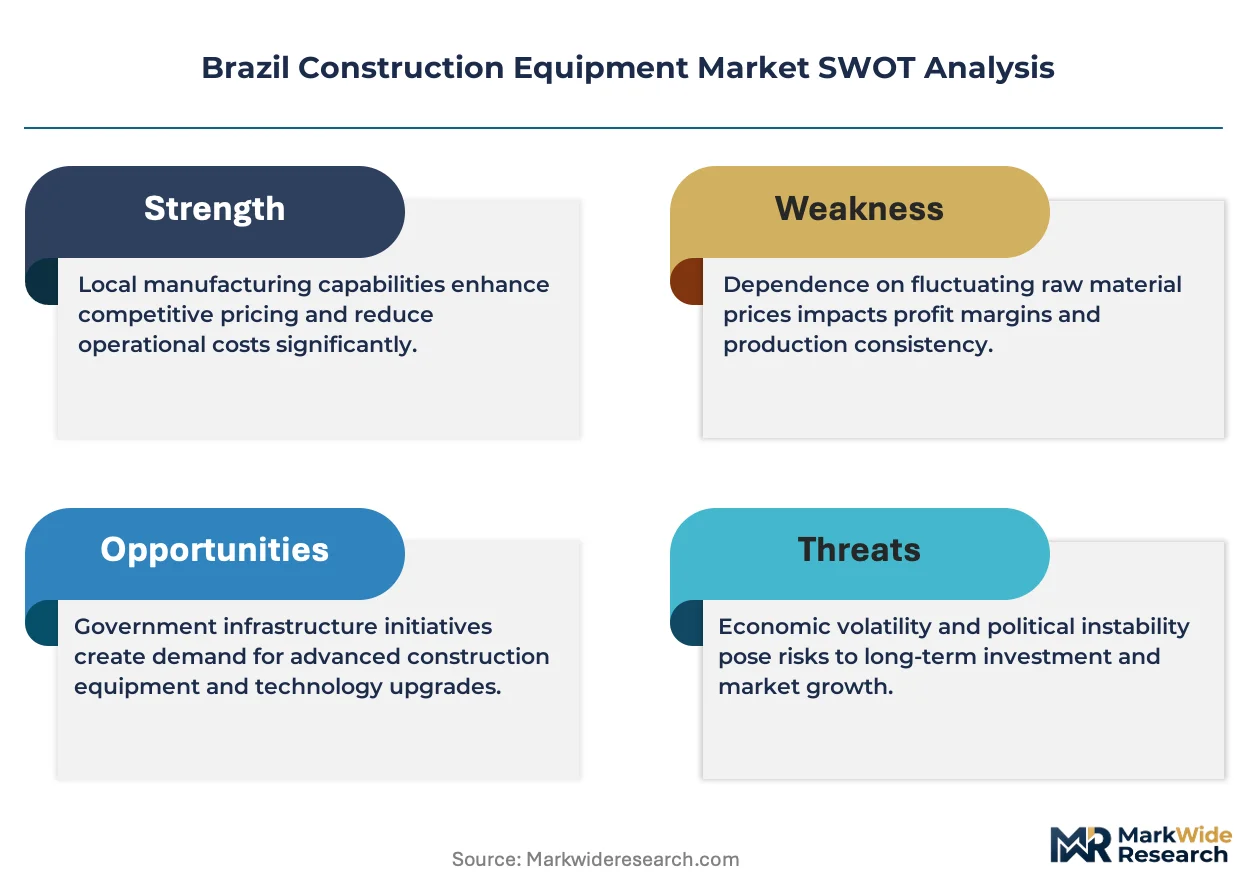
Federal infrastructure disbursements through PAC are compressing equipment replacement cycles while Tier-4 Final emission mandates force simultaneous fleet upgrades across Brazilian contractors and rental houses.
Growth Catalysts
- PAC Infrastructure Acceleration:Federal disbursements for highways, ports, and urban transit are pulling forward demand for excavators and motor graders among state contractors in Minas Gerais and Paraná.
- Telematics Integration:Connected fleet management platforms are enabling real-time fuel monitoring and predictive maintenance, reducing downtime for São Paulo-based earthmoving fleets.
- Extractive Sector Expansion:Iron ore and copper mining operations in the Carajás Basin are sustaining premium equipment utilization rates and multi-year service contracts.
Market Restraints
- Import Tariff Burden:Industrialized machinery components face heavy taxation at Brazilian ports, elevating landed costs for hydraulic systems and precision electronics.
- Credit Access Compression:BNDES financing directives have tightened collateral requirements, constraining mid-sized contractors in Northeast states from securing equipment loans.
- Skilled Operator Scarcity:ANVISA certification bottlenecks are extending workforce deployment timelines, limiting fleet utilization rates during peak construction seasons.
Strategic Opportunities
- Amazon Basin Infrastructure:BR-319 highway paving and river port modernization in Amazonas and Roraima are opening greenfield demand for amphibious excavators and specialized undercarriages.
- Retrofit Emission Compliance:CONAMA diesel particulate thresholds are creating aftermarket demand for engine rebuild kits and exhaust treatment systems among legacy fleet operators.
- Rental Fleet Digitization:Equipment-as-a-service platforms are penetrating São Paulo and Rio de Janeiro contractor markets, unbundling ownership from utilization.
Industry Challenges
- Parts Distribution Latency:Minas Gerais and Paraná service depots struggle with inventory synchronization, extending repair turnaround times for critical hydraulic components.
- Legacy Fleet Integration:Telematics retrofits on pre-2015 machines encounter CAN bus incompatibility, fragmenting fleet data visibility for mixed-age operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brazil Construction Equipment Market |
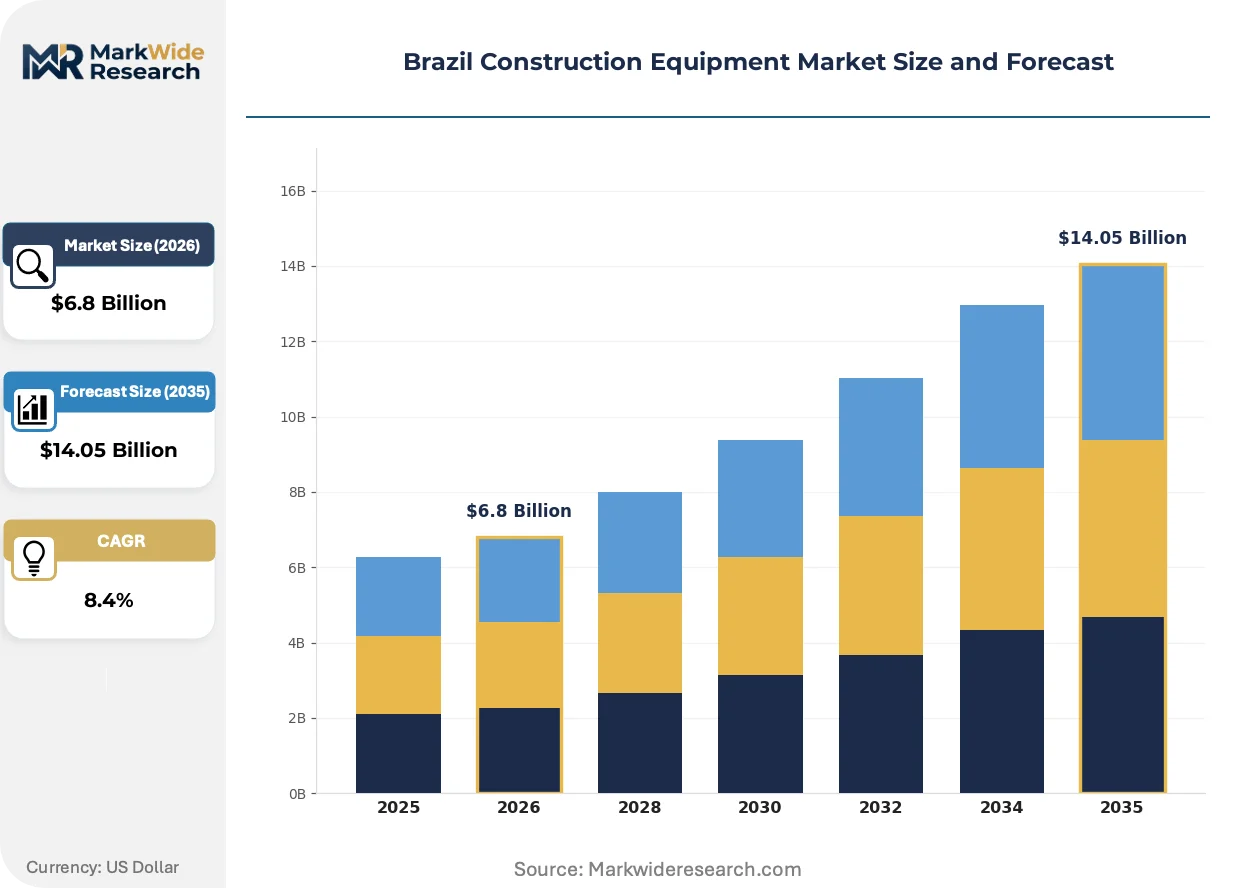
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.05 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Excavators, Loaders, Cranes, Bulldozers Application: Residential Construction, Commercial Projects, Infrastructure Development, Mining Operations End User: Construction Companies, Government Agencies, Real Estate Developers, Contractors Technology: Telematics, Electric Equipment, Manual Equipment, Autonomous Machinery |
| Companies Covered | Caterpillar Inc., Komatsu Ltd., Volvo Construction Equipment, Hitachi Construction Machinery, Liebherr Group, XCMG, JCB, CNH Industrial, Doosan Infracore, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brazil Construction Equipment Market Trends and Innovations
Electrification architectures and autonomous control systems are restructuring equipment value chains while regulatory enforcement tightens emission accountability across Brazilian worksites.
Autonomous haulage and excavation control systems are decomposing traditional operator-centric workflows in open-pit mining and large-scale earthmoving. Vale and other extractive operators in Minas Gerais are piloting remote-operated dozers and drill rigs at select iron ore sites. This capability decomposition is compressing labor cost structures and reshaping site safety protocols while demanding new technical training curricula.
ANVISA operator certification standards and pending CONAMA resolutions on diesel particulate limits are tightening equipment eligibility for government contracts. Contractors must now document emission compliance and operator qualification records to bid on federal infrastructure projects. Mining and heavy civil segments are responding fastest, pre-positioning Tier-4 Final machines and certified workforces ahead of enforcement deadlines.
Rental houses and contractor fleets are unbundling ownership from utilization through multi-year service agreements and guaranteed availability contracts. São Paulo state earthmoving specialists are shifting capital expenditure toward operational expenditure models, transferring residual value risk to OEM captive finance arms. This pattern concentrates most visibly among mid-tier contractors executing PAC-funded municipal works.
Brazil Construction Equipment Market Segmentation
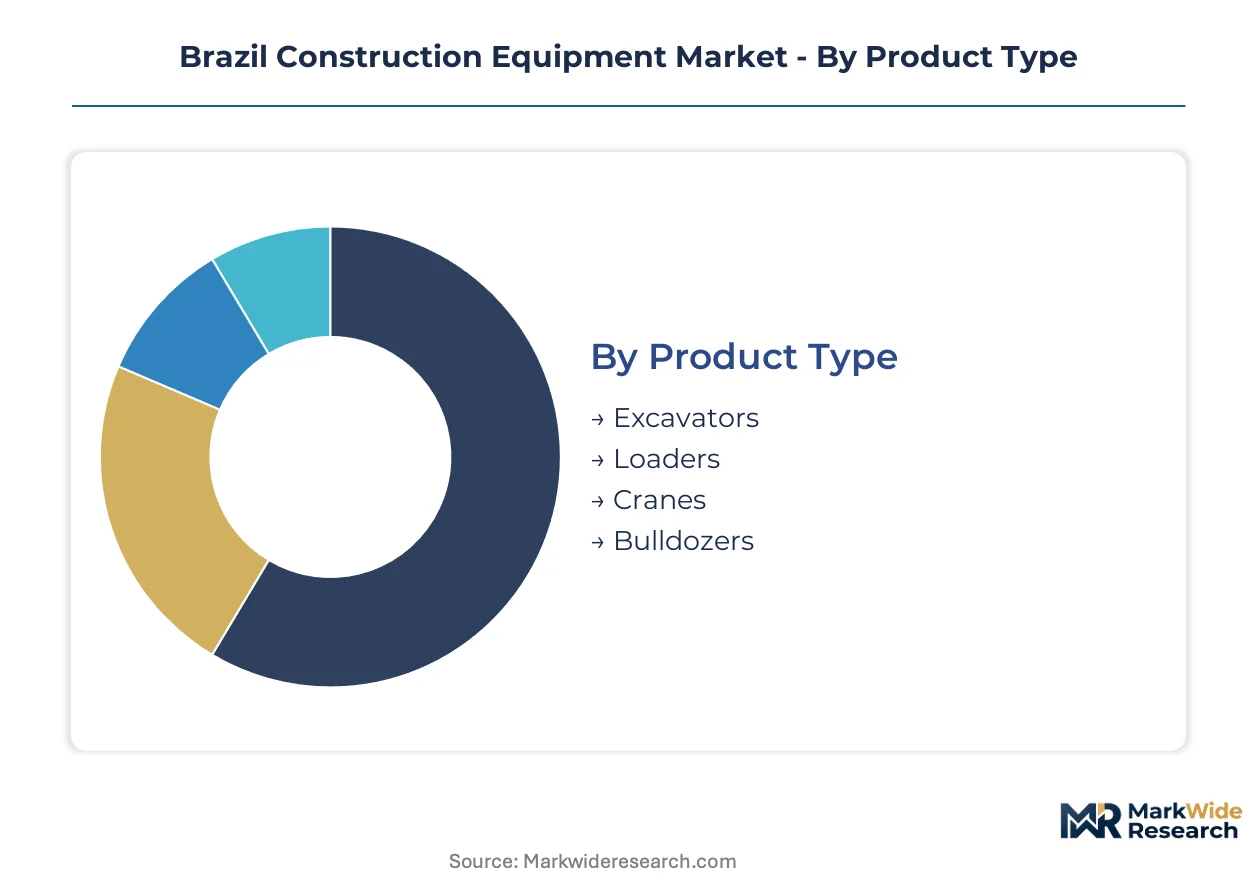
Brazil's construction equipment segmentation reveals how federal procurement standards and regional soil conditions concentrate demand across distinct machinery categories. Fleet composition decisions increasingly hinge on emission compliance tiers and telematics compatibility rather than upfront capital cost alone.
Product Type:
Substitution pressure intensifies most acutely in earthmoving categories where rental fleets and used equipment imports compete aggressively against new machine sales.
- Excavators:Hydraulic machines with reinforced undercarriages engineered for tropical humidity and clay-heavy soil profiles dominate fleet rosters. São Paulo state contractors and Minas Gerais mining operations absorb the deepest deployment volumes as PAC-funded highway widening accelerates trenching and foundation work.
- Loaders:Articulated and wheel loader variants equipped with telematics modules are rotating through rental houses as the dominant procurement specification. Real estate developers in Rio de Janeiro metropolitan zones concentrate demand for material handling cycles at commercial project sites.
- Cranes:Mobile and tower configurations serve vertical transport requirements at infrastructure and high-rise developments.
- Bulldozers:Tracked dozers with corrosion-resistant finishes execute grading and clearing operations across Amazon Basin frontier projects.
Excavators anchor the volume base while autonomous-capable loaders gain share at the steepest rate.
Application:
Cost tier stratification separates premium-specification machines deployed at mining and heavy civil sites from standard configurations serving municipal contracting.
- Infrastructure Development:Federal PAC disbursements for highways, ports, and urban transit pull forward demand for motor graders and large excavators. ANVISA certification requirements and Tier-4 Final emission mandates filter equipment eligibility for government contracts.
- Mining Operations:Iron ore and copper extraction in the Carajás Basin sustains premium utilization rates and multi-year service agreements. Vale and extractive operators pilot remote-operated drill rigs and autonomous haulage systems at select Minas Gerais sites.
- Residential Construction:Compact excavators and mini-loaders serve foundation and earthmoving cycles at housing developments.
- Commercial Projects:Tower cranes and material handlers support high-rise vertical transport in São Paulo and Rio de Janeiro metropolitan corridors.
Infrastructure Development commands the largest equipment deployment while Mining Operations generates the highest margin pools per machine-hour.
End User:
Customer type determines financing structure and ownership model, with government agencies accessing BNDES credit lines unavailable to private contractors.
- Government Agencies:Federal and state entities executing PAC-funded works maintain accelerated replacement cycles and mandate Tier-4 Final compliance. Procurement concentrates through centralized bidding platforms with ANVISA certification and emission documentation requirements.
- Contractors:Mid-sized earthmoving specialists in São Paulo and Paraná are unbundling ownership from utilization through equipment-as-a-service agreements. BNDES financing tightening has compressed credit access for Northeast state operators.
- Construction Companies:Large integrated builders maintain captive fleets for multi-year project pipelines.
- Real Estate Developers:Rio de Janeiro and São Paulo metropolitan developers concentrate demand for compact loaders and excavators at commercial and residential sites.
Government Agencies anchor procurement volume while Contractors are expanding most quickly through rental and service-based models.
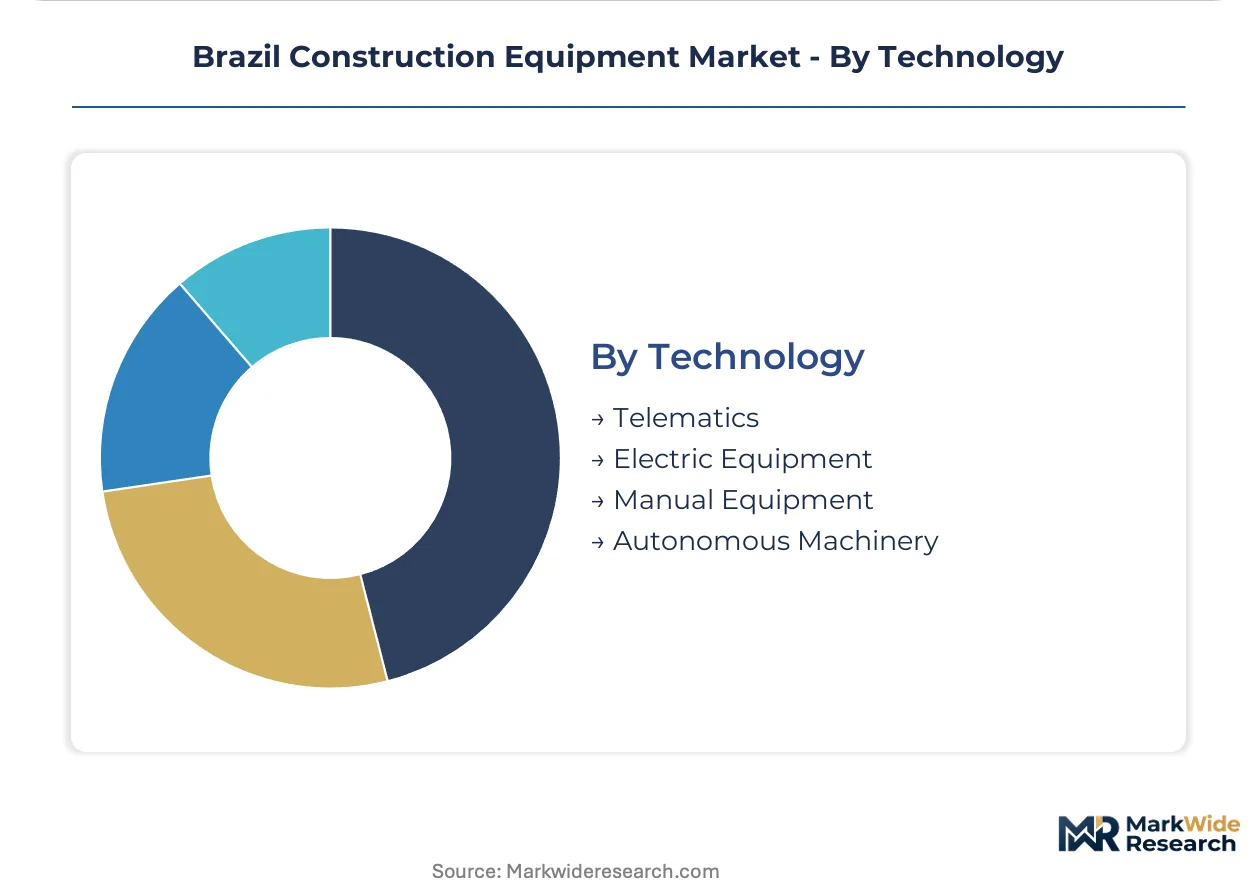
Technology:
Maturity gradients separate established telematics platforms from emerging electric and autonomous architectures still scaling through pilot deployments.
- Telematics:Connected fleet management platforms with real-time fuel monitoring and predictive maintenance modules are penetrating São Paulo rental houses. CAN bus retrofits on pre-2015 machines encounter compatibility fragmentation.
- Autonomous Machinery:Remote-operated dozers and drill rigs decompose traditional operator-centric workflows at Vale iron ore sites in Minas Gerais. Technical training curricula and site safety protocols are restructuring around capability decomposition.
- Electric Equipment:Battery-electric excavators and loaders remain limited to pilot programs near urban centers with charging infrastructure.
- Manual Equipment:Legacy hydraulic machines without connectivity modules persist in Northeast contractor fleets with constrained capital access.
Telematics anchors installed connectivity while Autonomous Machinery climbs the fastest as labor costs and safety protocols intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across Brazilian states, with São Paulo contractors absorbing premium pricing for telematics-equipped fleets while Northeast operators face credit constraints that compress procurement budgets.
São Paulo
Metropolitan contractors concentrate demand for compact excavators and connected loaders at commercial and residential sites. ANVISA certification requirements filter equipment eligibility for municipal contracts. Real estate developers in Greater São Paulo deploy mid-size earthmoving fleets for high-rise foundation work.
Minas Gerais
Iron ore extraction in the Iron Quadrangle sustains premium utilization rates for large excavators and autonomous-capable haul trucks. Vale pilots remote-operated drill rigs at select open-pit sites. Belo Horizonte-based service depots struggle with hydraulic parts inventory synchronization.
Paraná
Agricultural frontier expansion and highway paving under PAC disbursements pull demand for motor graders and articulated loaders. Federal infrastructure bidding platforms mandate Tier-4 Final emission documentation. Curitiba metropolitan contractors rotate rental fleets through equipment-as-a-service agreements.
Rio de Janeiro
Port modernization and offshore logistics infrastructure concentrate demand for tower cranes and material handlers. State environmental regulators enforce noise thresholds near protected coastal zones. Niterói and Duque de Caxias industrial corridors host specialized undercarriage service facilities.
Amazonas
BR-319 highway paving and river port development generate greenfield demand for amphibious excavators and corrosion-resistant finishes. IBAMA enforcement of diesel particulate limits near protected areas shapes fleet composition decisions. Manaus-based contractors face extended parts distribution lead times for specialized components.
Brazil Construction Equipment Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the Brazilian market. The vendor base organizes around three strategic tiers: integrated multinationals with captive finance arms, regional assemblers with localized production, and rental-focused service platforms. Consolidation pressure intensifies as emission mandates and telematics requirements raise capital barriers for mid-tier participants. Dominant competitive moves include portfolio diversification into aftermarket services and strategic partnerships with BNDES-accredited financing channels.
Among North American and European multinationals, Caterpillar Inc. and Volvo Construction Equipment exemplify the integrated service archetype, anchoring positions through parts distribution density and connected fleet platforms. Komatsu Ltd. occupies a parallel position within the Japanese industrial machinery tradition, representing localized assembly and technical training center strategies. These three names illustrate how geographic origin and corporate structure shape competitive positioning without determining specific market outcomes.
| Leading Market Players |
|---|
| Caterpillar Inc. |
| Komatsu Ltd. |
| Volvo Construction Equipment |
| Hitachi Construction Machinery |
| Liebherr Group |
| XCMG |
| JCB |
| CNH Industrial |
| Doosan Infracore |
| Others |
Pricing and Supply Chain Analysis
ANVISA operator certification standards and CONAMA emission tiers simultaneously gate supplier qualification and stratify price levels across Brazilian equipment procurement. Contractors bidding on PAC-funded infrastructure must document compliance with both regimes, forcing price differentiation between certified and non-certified fleet tiers.
Pricing Analysis
Aftermarket service contracts and parts revenue anchor lifetime value calculations for OEMs serving Brazilian contractors. Three-tier pricing structure across premium, standard, and economy levels separates Tier-4 Final compliant machines with telematics bundles from legacy hydraulic units without connectivity. Cost compression in the economy tier is intensifying because used equipment imports from North American fleets compete aggressively against domestic rental house offerings. Mid-sized contractors in Northeast states exhibit highest price sensitivity due to BNDES financing constraints, while mining operators in Minas Gerais demonstrate lowest sensitivity given utilization rate premiums.
Supply Chain Analysis
Port congestion at Santos and Paranaguá elevates inbound logistics costs for hydraulic systems and precision electronics sourced from Japan, Germany, and the United States. Brazilian assembly operations draw from imported engines, electronic control modules, and high-grade steel components. Single-source vulnerability concentrates in Tier-4 Final emission control systems where limited qualified suppliers serve Latin American markets. Distribution runs through Caterpillar and Komatsu parts depots in Belo Horizonte and Curitiba, with satellite facilities reaching Amazonas contractors via extended lead times.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated rental houses and government procurement platforms that unbundle ownership from utilization. This consolidation compresses pricing leverage for fragmented mid-tier contractors while elevating volume concentration among platform operators.
For Market Incumbents: Compound aftermarket revenue density by expanding hydraulic parts inventory synchronization across Minas Gerais and Paraná service depots. Extend captive finance arms into equipment-as-a-service agreements to capture recurring revenue streams from São Paulo contractors shifting capital expenditure to operational expenditure models. Defend against emerging Chinese OEM entrants by anchoring positions through ANVISA-certified technical training centers. For New Entrants and Emerging Players: ANVISA certification fast-tracks for autonomous machinery operators create entry pathways into mining service contracts. White-space concentrates in amphibious excavator segments serving Amazon Basin infrastructure where specialized undercarriage demand outstrips incumbent supply. Target BR-319 highway contractors in Amazonas and Roraima with corrosion-resistant equipment configurations unavailable through standard rental channels. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across telematics-enabled fleet platforms as software development costs displace pure manufacturing scale. Long-term viability favors asset-light service platforms over captive fleet ownership models. Acquisition target archetypes include regional rental houses with established BNDES financing relationships and specialized undercarriage service facilities in frontier states. Monitor CONAMA diesel particulate enforcement timelines as inflection indicator for retrofit aftermarket demand.| Strategic Initiative | Industry Significance |
|---|---|
| Telematics Platform Integration | Connected fleet management enables predictive maintenance contracts with São Paulo earthmoving specialists. |
| Regional Service Depot Expansion | Minas Gerais hydraulic parts inventory reduces repair turnaround times for Vale mining operations. |
| Equipment-as-a-Service Launch | Multi-year availability contracts transfer residual value risk from contractors to OEM captive finance. |
| Autonomous Machinery Certification | ANVISA-compliant remote operation protocols open bidding eligibility for federal infrastructure contracts. |
| Amazon Basin Product Line Extension | Amphibious excavator configurations address BR-319 highway and river port modernization demand. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of BNDES credit directive filings, ANVISA certification databases, and CONAMA regulatory drafts. Primary interviews engaged equipment fleet managers at Vale mining operations, procurement leads at São Paulo-based rental houses, aftermarket service directors at Minas Gerais depots, and PAC program officers at federal infrastructure agencies. Secondary sources included Central Bank of Brazil financing statistics, customs import records for industrialized machinery components, and SEC filings from listed OEMs with Brazilian operations. Bottom-up equipment deployment estimates triangulate against top-down infrastructure spending allocations.
Segmentation dimensions modeled span product type, application, end user, technology tier, and state-level regional cluster across the analysis window. Earthmoving machinery volume splits by excavator, loader, and dozer categories; application segmentation separates Infrastructure Development, Mining Operations, Residential Construction, and Commercial Projects; technology tiers distinguish telematics-equipped, autonomous-capable, electric, and manual configurations. CAGRs derive from equipment replacement cycle compression under PAC acceleration and emission mandate phase-in schedules. Forecast inputs incorporate BNDES credit availability indices and iron ore production forecasts from Carajás Basin operators.
Decision-makers should treat outputs as directional under assumptions of sustained federal infrastructure disbursement and CONAMA enforcement timelines; material deviation would warrant model refresh. Specific risks include credit access compression for Northeast contractors, IBAMA enforcement variability near protected areas, and import tariff volatility affecting hydraulic component landed costs. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Vertical Mill Market
Construction Equipment
Cutting and Bending Machine Market
Construction Equipment
Global Cone Crusher Market
Construction Equipment
Demolition Equipment Market
Construction Equipment
North America Construction Equipment Market
Construction Equipment
Jackhammer Market
Construction Equipment
Extrusion Equipment Market
Construction Equipment
Rockbreakers Market
Construction Equipment
Europe Crane Market
Construction Equipment
Foundry Sand Cleaning Machine Market
Construction Equipment
Metal Rollforming System Market
Construction Equipment
Amphibious Excavator Market
Construction Equipment
Friction Stir Welding Market
Construction Equipment
Concrete Testers Market
Construction Equipment
Sandblasting Machines Market
Construction Equipment
Wood Chipping Machinery Market