

4-Wheel Sit-Down Counterbalance Forklift Market Size, Share, and Industry Trends Forecast 2026-2036
4-Wheel Sit-Down Counterbalance Forklift Market Insights
Chinese electric motor production capacity is realigning global supply chains for industrial motive equipment. Toyota Material Handling leverages its vertical integration in battery systems to control cost curves across Asian distribution networks. KION Group anchors its European manufacturing base while extending automation software into fleet management services. Hyster-Yale competes through specialized internal combustion platforms for outdoor construction applications.
A 4-wheel sit-down counterbalance forklift is a powered industrial truck with a seated operator position, four-point wheel configuration, and a counterweighted rear chassis that offsets front-loaded cargo without outrigger supports; units typically lift 3,000 to 15,000 pounds to heights of 15 to 25 feet for horizontal transport and vertical stacking in confined aisles. Electric product types dominate indoor warehousing contracts where lithium-ion battery technology displaces lead-acid systems due to opportunity charging protocols and reduced maintenance intervals. Distribution center applications generate the densest order volumes, while construction end users sustain diesel and dual-fuel demand for rough-terrain duty cycles.
OSHA enforces operator certification and workplace design standards that mandate training programs and pedestrian separation systems, directly influencing fleet procurement specifications. EPA Tier 4 Final emissions regulations constrain diesel engine configurations and accelerate electric platform adoption in regulated jurisdictions. The EU Green Deal and F-Gas Regulation add parallel carbon-accounting pressures for multinationals operating across North American and European facilities. Stakeholders must monitor battery chemistry sourcing constraints and charging infrastructure deployment timelines as fleet electrification commitments outpace grid readiness in key logistics corridors.
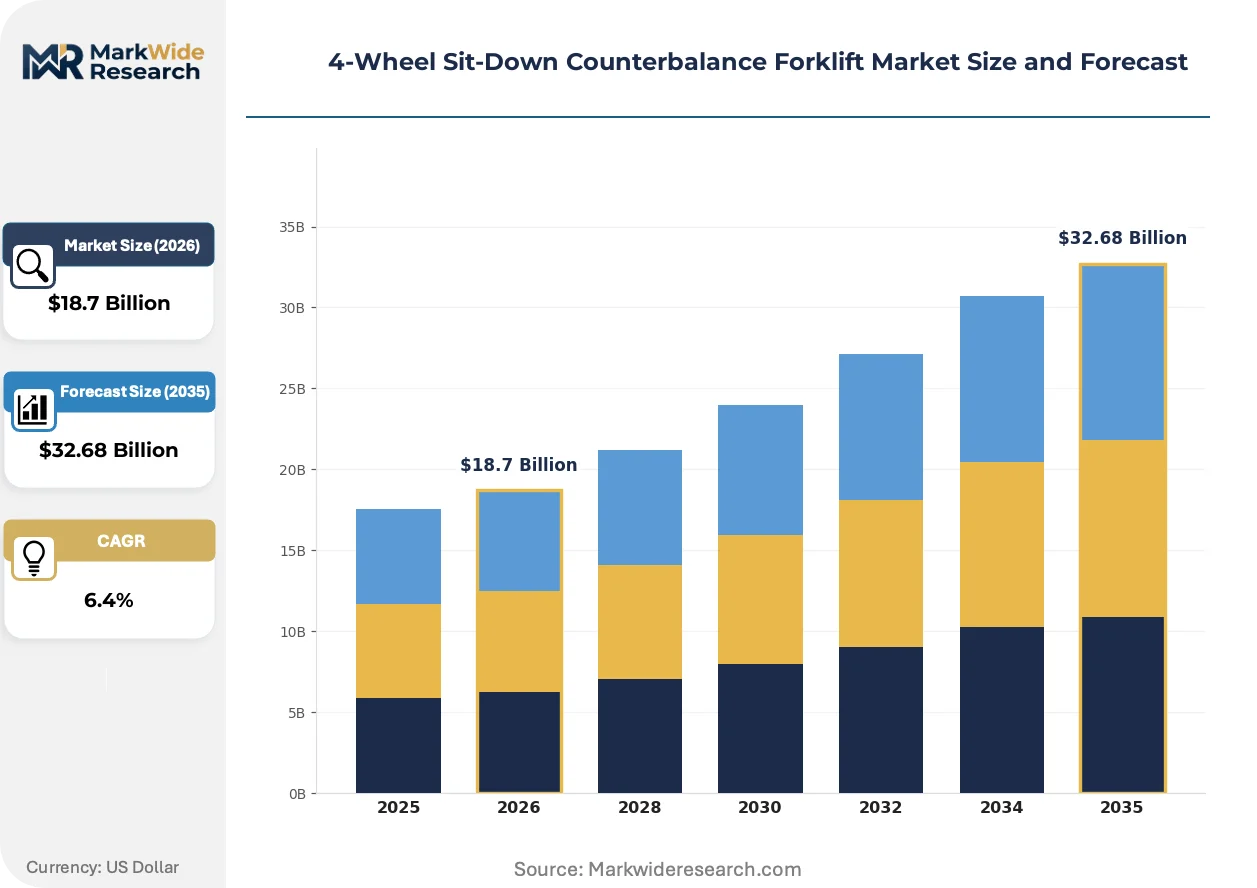
Market Dynamics
Lithium-ion battery chemistry is converging with opportunity charging infrastructure to compress fleet downtime economics and displace lead-acid dominance in multi-shift warehousing contracts.
Growth Catalysts
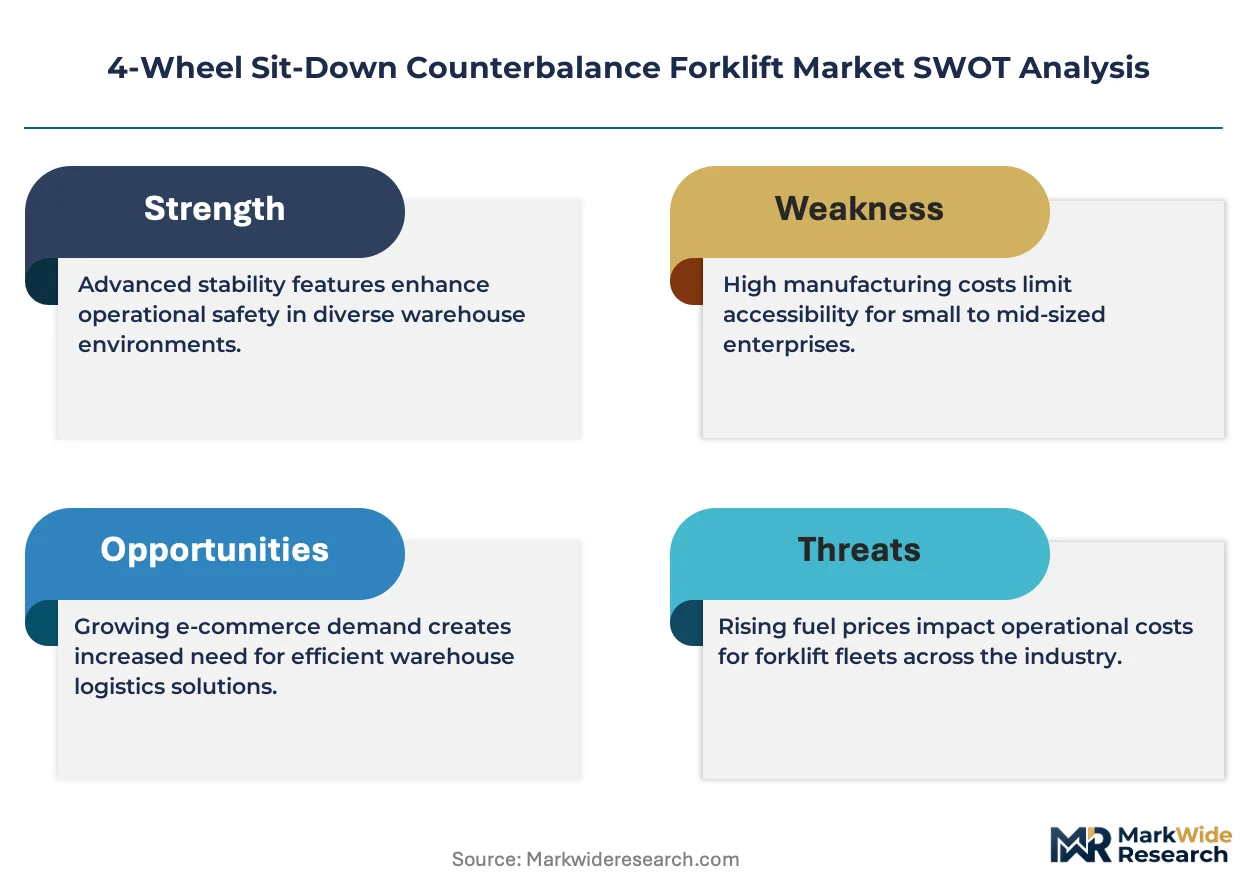
- EPA Tier 4 Final:Stringent particulate emissions limits on diesel engines accelerate electric platform procurement in regulated US logistics corridors.
- E-commerce fulfillment density:Three-shift operations at automated distribution centers multiply unit utilization rates and shorten replacement cycles.
- OSHA pedestrian separation mandates:Warehouse redesign specifications incorporate sensor-equipped forklifts, expanding attachment and safety system attach rates.
Market Restraints
- Lithium carbonate volatility:Battery pack cost curves remain exposed to South American and Australian mining concentration, pressuring electric unit margins.
- Grid readiness gaps:Charging infrastructure deployment lags fleet electrification commitments in key logistics corridors, constraining rapid scaling.
- Lead-acid installed base inertia:Existing fleet amortization schedules and maintenance technician familiarity slow technology substitution timelines.
Strategic Opportunities
- India logistics modernization:Cold chain expansion and organized retail penetration create first-mover positioning for lithium-ion platforms in temperature-controlled warehousing.
- Fleet management software convergence:Telematics integration with warehouse management systems enables outcome-based uptime contracts and recurring revenue streams.
- EU Green Deal carbon accounting:Multinational operators face Scope 3 pressure to electrify material handling across European distribution networks.
Industry Challenges
- High-voltage technician scarcity:Lithium-ion maintenance and thermal runaway response protocols outpace vocational training program throughput.
- Interoperability fragmentation:Proprietary charging connectors and battery management protocols complicate multi-brand fleet standardization.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
4-Wheel Sit-Down Counterbalance Forklift Market Trends and Innovations
Electrification architecture is rewriting competitive advantage around energy density and charging speed rather than engine displacement. Three developments are compressing traditional equipment lifecycles and reshaping supplier-customer relationships.
Lithium iron phosphate battery packs are converging with modular fast-charging stations to eliminate battery swap requirements. Third-party logistics operators in Germany and the Netherlands are adopting these configurations for 24-hour fulfillment cycles. The technology is converging with warehouse automation investments to enable continuous operation without dedicated battery rooms.
The EU F-Gas Regulation constrains hydrofluorocarbon use in operator cabin climate systems, forcing redesigns of HVAC components in outdoor diesel units. Manufacturers serving European construction and port terminal segments must certify alternative refrigerant architectures. This regulatory pressure is concentrating R&D expenditure on electric thermal management systems that bypass combustion-engine waste heat recovery.
Leasing structures are displacing outright purchase for mid-sized warehousing operations seeking to transfer battery degradation risk. Equipment finance providers in the United States are bundling telematics subscriptions and preventive maintenance into per-hour rate cards. This shift is most pronounced among food and beverage distributors with seasonal volume volatility seeking balance sheet flexibility.
4-Wheel Sit-Down Counterbalance Forklift Market Segmentation
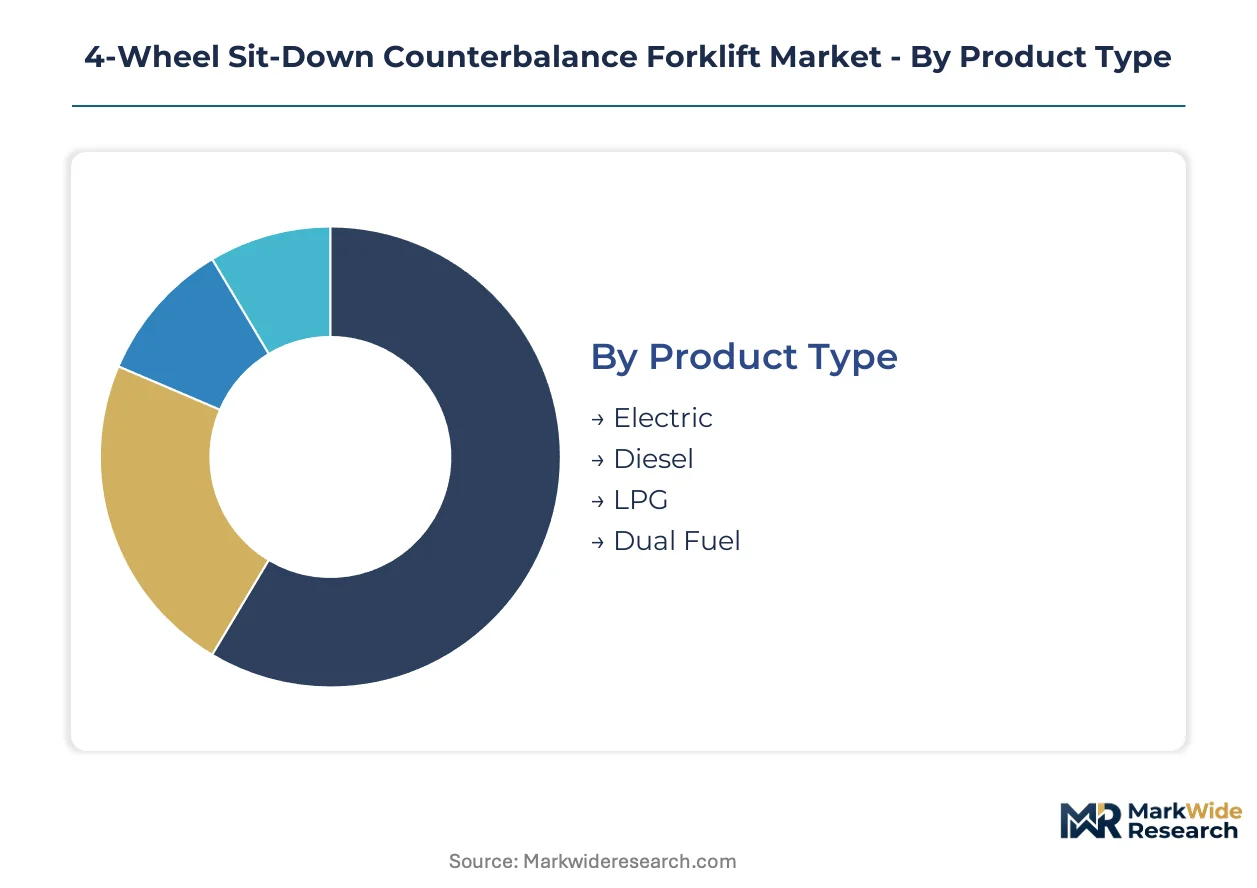
Procurement specifications diverge sharply across operating environments. Battery chemistry choices, duty cycle intensity, and facility infrastructure constraints each reshape fleet composition and supplier relationships.
Product Type:
Supply concentration for powertrain components determines regional availability and lead time differentials across procurement channels.
- Electric:Lithium-ion battery packs with opportunity charging capability dominate indoor warehousing contracts. Demand concentrates at automated distribution centers in Germany and the United States where EPA Tier 4 Final compliance costs disadvantage diesel alternatives.
- Diesel:Internal combustion engines with particulate after-treatment systems serve outdoor construction and port terminal applications. Procurement persists in markets with limited grid infrastructure or extreme temperature operating envelopes.
- LPG:Liquid petroleum gas configurations offer indoor/outdoor flexibility for mid-sized manufacturing facilities without heavy electrical infrastructure investment.
- Dual Fuel:Bi-fuel diesel-natural gas systems address carbon reduction mandates in European logistics corridors while preserving range security.
Today's leader: Electric. Tomorrow's challenger: Dual Fuel.
Technology:
Cost tier stratification separates established installed base maintenance from next-generation platform procurement.
- Lithium-Ion Battery:Energy density above 150 Wh/kg enables single-battery multi-shift operation without dedicated battery rooms. Demand concentrates at cold chain facilities in the Netherlands where reduced heat generation preserves temperature integrity.
- Lead Acid Battery:Flooded-cell and sealed AGM configurations retain installed base dominance in price-sensitive single-shift operations. Replacement parts availability and technician familiarity sustain residual procurement.
- Hydrogen Fuel Cell:Proton exchange membrane systems with three-minute refueling target continuous-duty port terminals and automotive supplier just-in-sequence operations.
- AC Motor:Brushless permanent magnet drives with regenerative braking reduce maintenance intervals versus DC motor predecessors in high-cycle warehousing applications.
Current procurement tilts toward Lithium-Ion Battery. Hydrogen Fuel Cell offers the steepest expansion trajectory where refueling infrastructure materializes.
Application:
Volume concentration varies by shift density and vertical stacking height requirements across facility types.
- Distribution Centers:Three-shift e-commerce fulfillment operations with 25-foot lift heights drive highest unit utilization and shortest replacement cycles. OSHA pedestrian separation mandates accelerate sensor-equipped fleet refresh.
- Warehousing:General storage facilities with intermittent duty cycles sustain lead-acid dominance and longer equipment lifespans.
- Construction:Rough-terrain duty cycles with pneumatic tires and high ground clearance preserve diesel and dual-fuel demand.
- Manufacturing:Just-in-time component delivery within assembly plants favors electric units with precision maneuvering and zero emissions.
- Ports:Container handling and intermodal transfer operations with continuous duty requirements test durability limits and fuel cell viability.
Distribution Centers command current procurement volume. Manufacturing offers the fastest-growing trajectory as automotive suppliers electrify material handling.
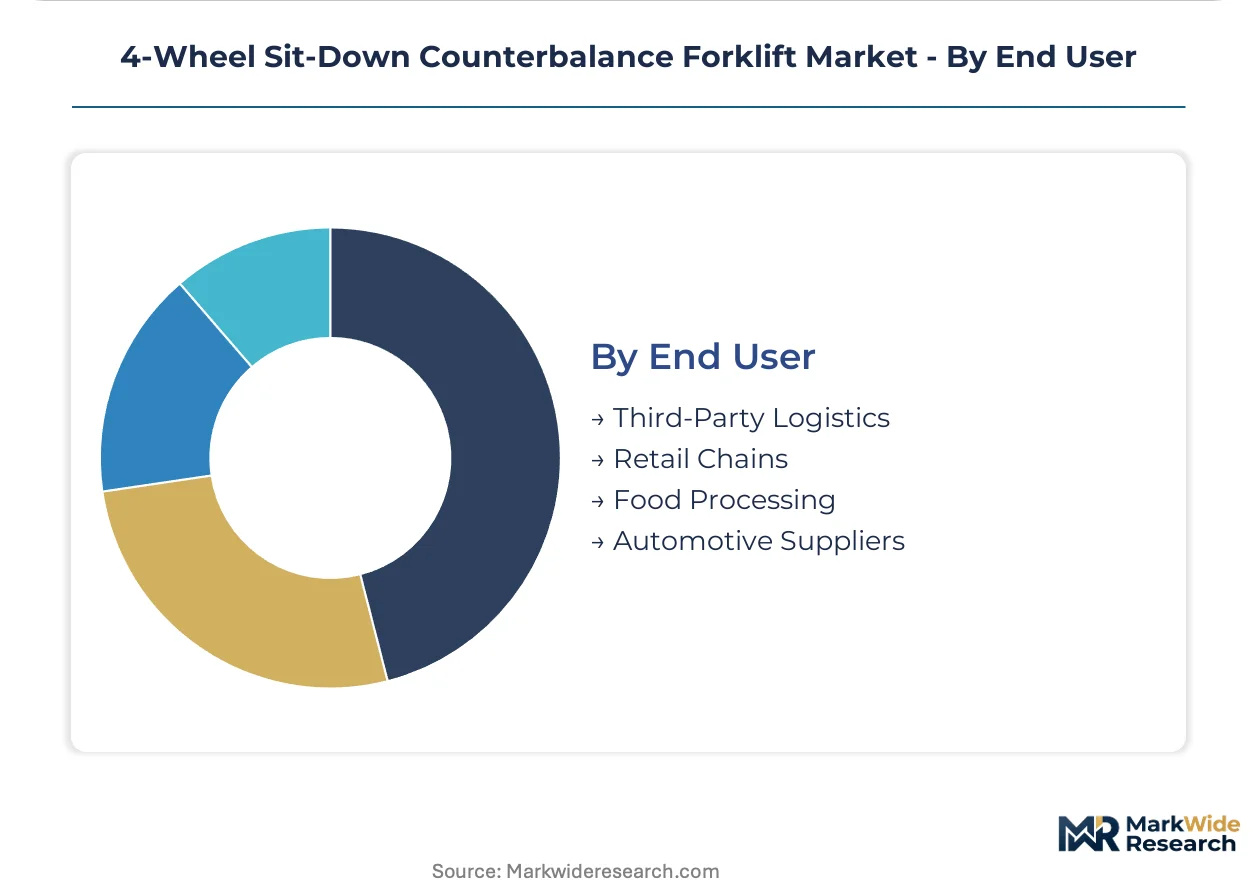
End User:
Customer type determines financing structure preference and telematics attach rate sensitivity.
- Third-Party Logistics:Asset-light operators with seasonal volume volatility favor per-hour leasing with bundled maintenance and battery risk transfer.
- Retail Chains:Private fleet operators with predictable demand patterns amortize electric platform premiums through energy cost savings and reduced downtime.
- Food Processing:Cold storage operators prioritize lithium-ion thermal stability and opportunity charging to maintain continuous throughput in temperature-controlled environments.
- Automotive Suppliers:Tier-1 and Tier-2 manufacturers with just-in-sequence delivery requirements specify high-availability configurations with redundant charging infrastructure.
Third-Party Logistics shapes current contract structures. Food Processing offers the fastest-growing trajectory as cold chain expansion accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting manufacturing investment toward jurisdictions with favorable emissions compliance costs. Production capacity is migrating to markets where battery supply chains cluster near end-user demand centers.
United States
E-commerce fulfillment densification around Chicago, Dallas, and Atlanta is accelerating fleet turnover. EPA Tier 4 Final enforcement constrains diesel procurement in California and Northeast logistics corridors. The Inland Empire warehouse cluster east of Los Angeles now hosts the densest concentration of lithium-ion forklift deployments.
Germany
Automotive supplier just-in-sequence operations around Stuttgart and Wolfsburg sustain premium electric platform demand. The EU Green Deal carbon accounting rules pressure multinationals to electrify material handling across Bavarian and North Rhine-Westphalian distribution networks. The Port of Hamburg is piloting hydrogen fuel cell configurations for continuous-duty container handling.
China
Domestic battery cell manufacturing scale in Fujian and Jiangsu provinces is compressing electric forklift cost curves. MIIT industrial equipment standards mandate energy efficiency benchmarks that disadvantage imported internal combustion units. The Yangtze River Delta logistics corridor around Shanghai now concentrates the world's largest deployed base of lithium-ion motive equipment.
India
Cold chain expansion in Maharashtra and Gujarat is creating first-mover openings for temperature-stable battery platforms. The PLI scheme for advanced chemistry cell manufacturing is localizing lithium-ion supply chains near Mumbai-Pune industrial zones. Organized retail penetration in the Delhi-NCR corridor is driving multi-shift warehousing contracts with opportunity charging requirements.
Japan
Precision manufacturing clusters in Aichi Prefecture and the Kansai region sustain demand for high-maneuverability electric units. METI carbon neutrality roadmaps for industrial equipment accelerate replacement cycles in Osaka-Kobe port logistics. Toyota City remains the global benchmark for vertically integrated battery-forklift production systems.
4-Wheel Sit-Down Counterbalance Forklift Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue automation-software adjacencies and battery chemistry specialization. The vendor base stratifies across three maturity tiers: legacy internal combustion specialists, electric platform incumbents with captive battery supply, and regional challengers leveraging Chinese cell manufacturing proximity. Three strategic archetypes dominate: vertically integrated industrial conglomerates, pure-play motive equipment specialists, and automation-software integrators. Competitive moves concentrate on M&A for telematics capabilities and strategic partnerships for charging infrastructure deployment.
Within the premium-tier vector, Toyota Material Handling and KION Group anchor the established producer category. Hyster-Yale occupies a position exemplifying the internal combustion-to-electric transition archetype. These three entities represent the dominant competitive anchors around which mid-tier specialists and regional assemblers position their alternative platform offerings.
| Leading Market Players |
|---|
| Crown Equipment |
| Toyota Material Handling |
| KION Group |
| Jungheinrich |
| Mitsubishi Logisnext |
| Hyster-Yale |
| Raymond |
| Anhui Heli |
| CLARK Material Handling |
| Others |
Pricing and Supply Chain Analysis
Lithium-ion battery pack standardization is compressing cost curves while concentrating supply leverage among cell manufacturers in Fujian and Jiangsu provinces, simultaneously reshaping procurement economics and vendor bargaining power across material handling equipment markets.
Pricing Analysis
Distributor margins on electric units absorb the steepest compression as OEMs bypass traditional channel layers for direct fleet contracts with third-party logistics operators. Three-tier pricing structure across premium lithium-ion configurations, standard lead-acid platforms, and economy refurbished units stratifies buyer segments. Pricing pressure stems from Chinese cell oversupply feeding into aggressive Asian assembler pricing. Single-shift warehousing operators exhibit highest price sensitivity; automated distribution centers with uptime penalties show lowest.
Supply Chain Analysis
Container freight rates from Shanghai to Hamburg and Los Angeles directly determine landed cost differentials for European and North American procurement managers. Cell manufacturing concentrates in China, South Korea, and Japan; steel chassis fabrication draws from Turkey, Mexico, and Poland. Lithium carbonate and nickel sulfate dependencies create exposure to South American and Indonesian mining concentration. Single-source vulnerability sits with proprietary battery management system firmware. Distribution runs through regional equipment dealers with captive service networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The 4-wheel sit-down counterbalance forklift market functions as a stable compounder anchored by e-commerce fulfillment infrastructure buildouts that sustain replacement-cycle visibility across multi-year logistics contracts.
For Market Incumbents: Deepen captive battery supply arrangements to defend margin structures against Chinese assemblers with direct cell procurement advantages. Expand certified technician training pipelines to address high-voltage maintenance scarcity that constrains fleet uptime guarantees. Prioritize telematics platform integration with warehouse management systems to lock in switching costs against automation-software entrants. For New Entrants and Emerging Players: Direct-to-fleet digital sales channels bypass dealer networks to capture price-transparent procurement from mid-sized warehousing operators in India and Southeast Asia. Target cold chain logistics in Maharashtra and Gujarat where temperature-stable lithium-ion platforms face limited incumbent penetration. Lead with outcome-based uptime contracting that transfers battery degradation risk from capital-constrained buyers. For Investors and Strategic Acquirers: Valuations sit cheapest among regional assemblers with Chinese cell supply agreements but limited brand recognition in European and North American markets. Long-term viability hinges on electrification transition completion and software-services attach rate expansion. Monitor hydrogen fuel cell pilot deployments at Hamburg and Los Angeles ports as inflection indicators for alternative powertrain viability.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Captive lithium-ion cell access from CATL or BYD insulates margin structures against commodity volatility. |
| Telematics Platform Integration | API connectivity with SAP EWM and Blue Yonder creates recurring SaaS revenue from fleet optimization. |
| Certified Technician Network Expansion | OSHA-aligned training programs address high-voltage scarcity that constrains electric fleet scaling. |
| Opportunity Charging Infrastructure | Modular fast-charging stations eliminate battery rooms and enable 24-hour continuous fulfillment cycles. |
| Outcome-Based Leasing Structure | Per-hour rate cards with bundled maintenance transfer battery risk from seasonal-volume distributors. |
Research Methodology
Bottom-up distribution center and manufacturing facility modeling reconciled against top-down OEM production and trade flow tracking forms the analytical core. Primary interviews with fleet managers, maintenance directors, OEM procurement teams, and aftermarket service heads combine with secondary validation from MIIT industrial equipment registrations, EPA certification databases, customs trade data, and SEC equipment manufacturer filings. Triangulation across stakeholder inputs and documentary sources anchors volume and value estimates.
Input-output matrices map powertrain configuration, battery chemistry, and application intensity against facility type and regional regulatory cluster across the analysis window. Segmentation dimensions include product type, technology tier, end-use application, and customer archetype. CAGRs derive from replacement cycle compression rates and electrification transition velocity. Forecast inputs incorporate charging infrastructure deployment timelines and lithium carbonate supply elasticity assumptions.
The model assumes a particular technology adoption path; alternative pathways for hydrogen fuel cell or solid-state battery commercialization would alter the outlook. Forecasts reflect documented assumptions about grid readiness, regulatory enforcement intensity, and mining supply expansion. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.