
 Vibratory Plate Compactors Market | 2026-2036
Vibratory Plate Compactors Market Size, Share, and Industry Trends Forecast 2026-2036
Vibratory Plate Compactors Market Analysis
Plate compaction performance ratings above 5,000 vpm is rotating demand toward premium-class machines. Wacker Neuson SE leverages its German engineering heritage to dominate European specification tiers. Caterpillar Inc. anchors North American rental channel supply through its dealer network. Mikasa Sangyo Co. Ltd. specializes in lightweight units for Japanese landscaping contractors.
Vibratory plate compactors are unidirectional or reversible machines that use eccentrically mounted weights to generate high-frequency vertical vibration, typically operating between 3,500 and 6,000 vibrations per minute to densify granular soils and asphalt layers. Reversible units command the highest margin pools due to their dual-direction utility on confined job sites. Electric power source variants are gaining fastest among urban construction fleets facing noise ordinances and indoor slab work requirements. Rental services as an end user segment sustains volume throughput by cycling mid-size diesel units through seasonal demand peaks.
EPA Tier 4 Final standards in the United States and EU Stage V regulations enforced by national type-approval authorities limit diesel engine particulate emissions, compelling manufacturers to integrate after-treatment systems or pivot to electric drivetrains. OSHA noise exposure limits in construction zones shape operator cabin specifications and influence electric model uptake. Stakeholders must monitor battery energy density trajectories and charging infrastructure buildout to time capital commitments across power source platforms.
Market Dynamics
EPA Tier 4 Final emission standards are compressing diesel engine margins while accelerating electric drivetrain adoption across municipal fleet procurement. Equipment managers now face platform selection decisions that lock in operational costs for decade-long depreciation cycles.
Growth Catalysts
- Urban Noise Ordinances:Municipalities in the United States are tightening construction decibel limits. Electric plate compactors bypass curfew restrictions that idle diesel units.
- Rental Channel Expansion:Independent equipment rental firms are cycling mid-size reversible units through seasonal demand peaks. This sustains volume throughput without capital burden on contractors.
- REACH Compliance Deadlines:EU Stage V enforcement is compelling fleet operators to replace pre-2019 diesel inventory. After-treatment retrofit costs make electric alternatives economically competitive.
Market Restraints
- Battery Cell Supply Concentration:Lithium-ion cell production clusters in China and South Korea. Geographic concentration creates vulnerability for electric compactor manufacturers dependent on cylindrical cell formats.
- Steel Input Volatility:Plate compaction base plates require high-grade carbon steel. Mill pricing swings directly compress gross margins on standard-class machines.
- OSHA Permissible Exposure Limits:Whole-body vibration thresholds constrain operating hours per shift. Hand-arm vibration regulations add certification overhead for manual guidance models.
Strategic Opportunities
- Indoor Slab Preparation:Zero-emission electric units access enclosed commercial construction sites. This application was previously inaccessible to diesel-powered equipment.
- India Smart Cities Mission:Urban infrastructure densification is creating demand for compact reversible plates. Localized assembly partnerships can bypass import duty structures.
- Battery Swapping Infrastructure:Converging battery standardization across construction equipment categories enables shared charging assets. Fleet operators can amortize infrastructure across multiple machine types.
Industry Challenges
- Power Electronics Integration:Variable frequency drive programming for soil-specific vibration optimization requires embedded systems expertise scarce among traditional mechanical engineering teams.
- Dual Certification Burden:Manufacturers must simultaneously satisfy EPA certification for diesel variants and UL 2580 for battery systems. Parallel testing timelines extend product launch cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vibratory Plate Compactors Market |
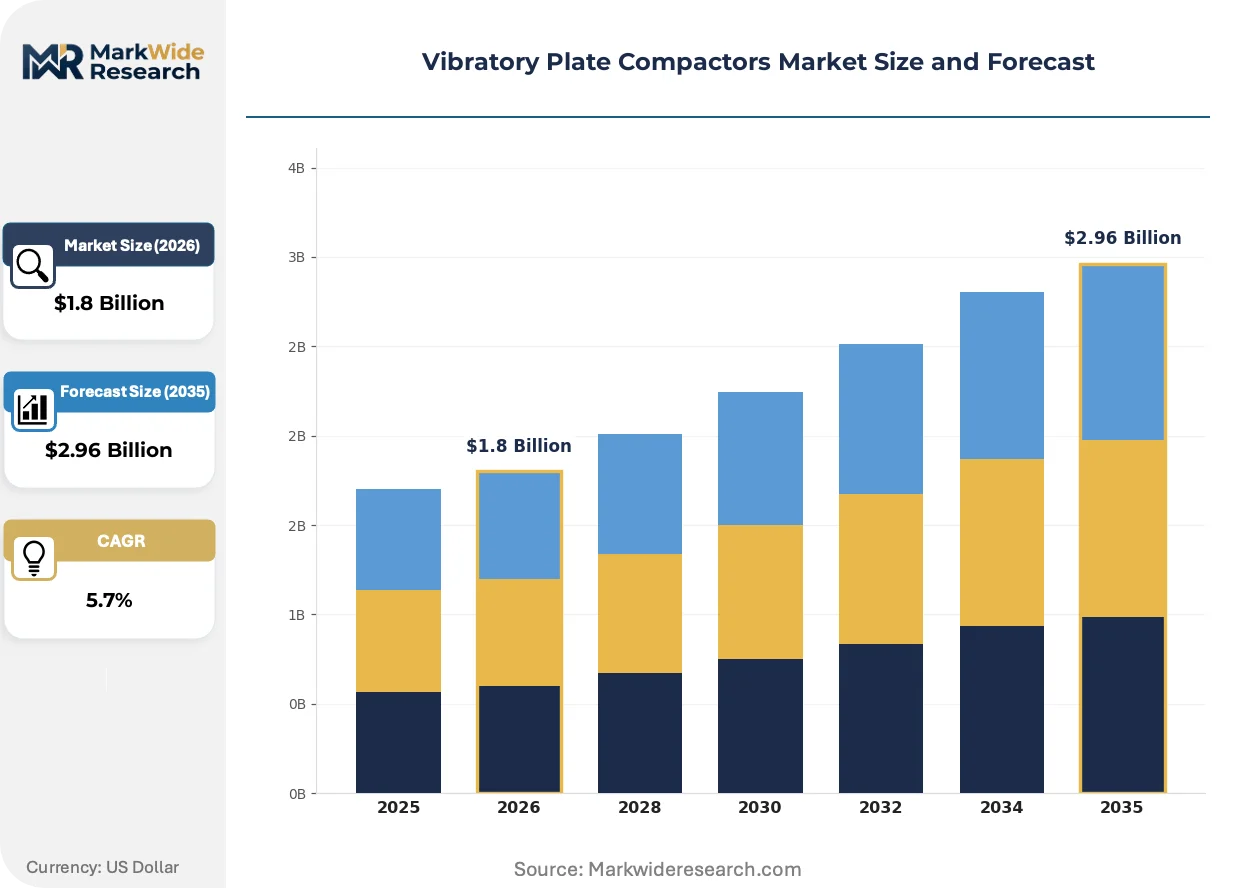
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reversible, Forward, Single-Directional, Heavy-Duty End User: Construction, Landscaping, Road Maintenance, Rental Services Power Source: Diesel, Electric, Gasoline, Hybrid Size: Compact, Medium, Large, Extra Large |
| Companies Covered | Ammann Group, Weber Maschinentechnik GmbH, Wacker Neuson SE, Mikasa Sangyo Co. Ltd., Doosan Corporation, Caterpillar Inc., Atlas Copco AB, Multiquip Inc., Bomag GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vibratory Plate Compactors Market Emerging Trajectories
Electrification is fragmenting the established power source hierarchy while connectivity modules enable usage-based service models. These shifts are compressing traditional equipment lifecycle economics.
Lithium-iron-phosphate battery chemistry is fragmenting the incumbent diesel-normative product architecture. Municipal fleet operators in Germany and California are specifying electric plate compactors for urban road maintenance contracts. This chemistry choice is fragmenting supplier relationships as cell procurement decouples from engine sourcing networks.
EU Stage V emission standards enforced by national type-approval authorities are mandating diesel particulate filters and selective catalytic reduction on all new machines. After-treatment hardware adds weight and maintenance burden to compact equipment categories. Rental fleets in France and Italy are responding by accelerating electric model trials for sub-500 kg weight classes.
Telematics-enabled condition monitoring is altering ownership economics for contractor segments. Real-time vibration analytics and hour-meter data allow rental houses to unbundle maintenance from base rates. Equipment lessors in Texas and Florida are piloting usage-indexed pricing structures that shift operating risk to operators.
Vibratory Plate Compactors Market Segmentation
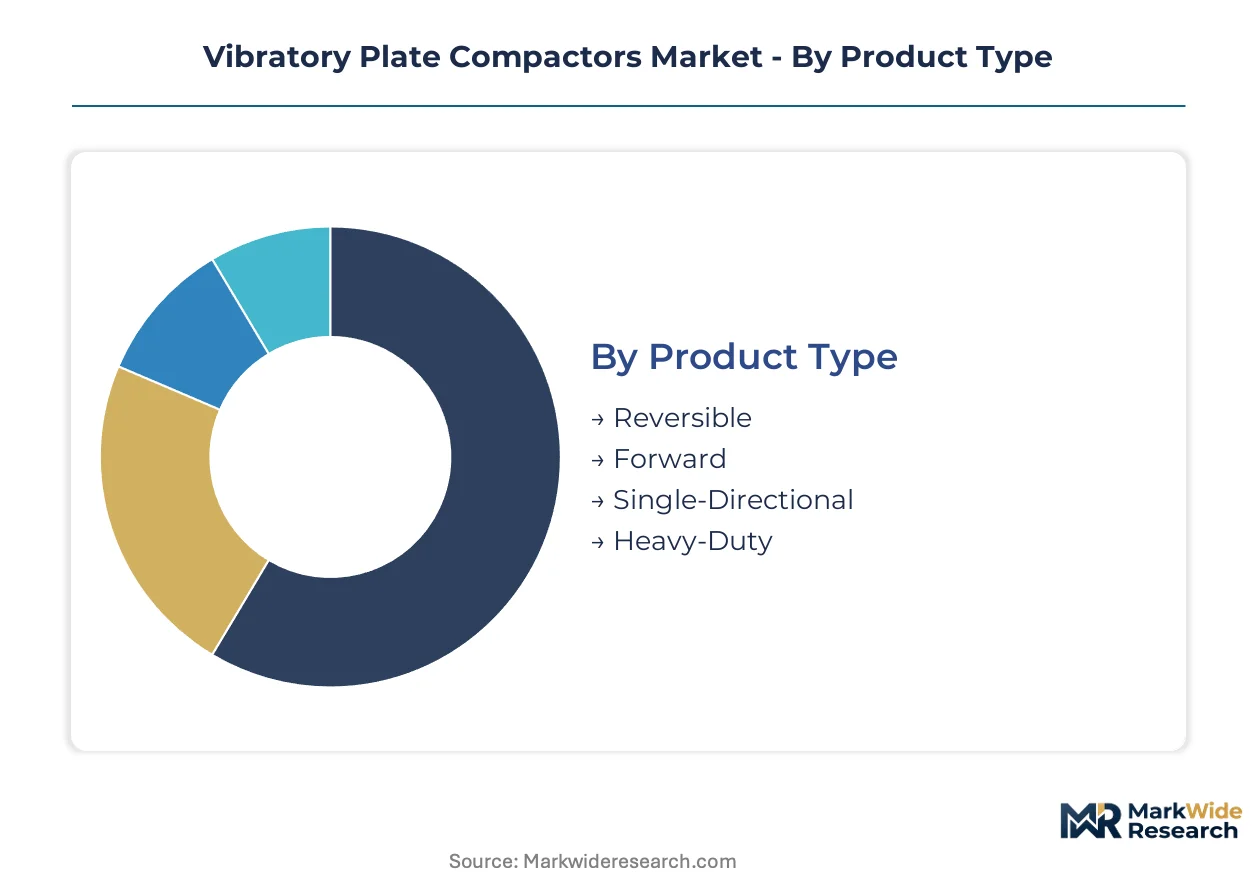
Segmentation in vibratory plate compactors reveals how equipment specifications align with distinct operational economics. Product architecture, power systems, and size classes each map to different customer procurement patterns and margin structures.
Product Type:
Reversible units dominate export flows to European municipal fleets, while single-directional models concentrate in domestic North American contractor purchases.
- Reversible:Dual-direction operation enables compaction against walls and obstacles without repositioning. German road maintenance agencies specify these for urban reconstruction contracts facing confined site geometries. EU Stage V compliance costs push rental fleets toward electric variants in this class.
- Forward:Unidirectional travel suits open-area soil preparation with simpler mechanical systems. Demand concentrates among United States residential contractors completing foundation backfill work. Lower acquisition costs sustain volume in price-sensitive developing markets.
- Single-Directional:Fixed-path operation serves linear trench compaction and narrow utility installations. Japanese landscaping specialists favor lightweight gasoline-powered configurations.
- Heavy-Duty:Reinforced base plates and eccentric mass systems handle cohesive clay soils and deep lift depths. Infrastructure projects in China deploy these for dam and airport runway construction.
Reversible holds the largest share; momentum sits with Heavy-Duty as infrastructure scale increases.
End User:
Cost tier segmentation separates capital-owning contractors from asset-light operators cycling equipment through rental channels.
- Construction:General contractors deploy mixed fleets across soil and asphalt applications. United States commercial building permits drive seasonal procurement spikes.
- Landscaping:Lightweight electric units access noise-restricted residential zones. California municipalities specify zero-emission equipment for public park renovations.
- Road Maintenance:Municipal fleets face decade-long depreciation cycles locked by procurement rules. EPA Tier 4 Final standards force replacement decisions toward electric alternatives.
- Rental Services:Asset utilization rates determine profitability; telematics track vibration hours for predictive maintenance. Independent rental firms in Texas cycle mid-size diesel units through oil-patch construction seasons.
Rental Services commands the highest volume throughput; Road Maintenance shows the steepest electrification pivot.
Power Source:
Application context dictates power selection — indoor slab work eliminates combustion options entirely.
- Diesel:High torque density suits continuous heavy compaction cycles. After-treatment hardware adds weight and maintenance burden compressing margins on sub-500 kg machines.
- Electric:Zero emissions and reduced noise unlock indoor commercial construction and nighttime urban work. Battery energy density trajectories and charging infrastructure buildout determine capital commitment timing.
- Gasoline:Lower first cost serves intermittent-use landscaping contractors. OSHA noise exposure limits constrain operating hours per shift.
- Hybrid:Combustion-electric architectures balance runtime flexibility with emission reductions. Limited commercial deployment pending power electronics integration maturation.
Diesel retains installed base dominance; Electric gains share fastest where noise ordinances tighten.
Size:
Volume concentration sits with medium units, while margin pools concentrate at size extremes.
- Compact:Sub-100 kg designs enable manual transport and stair access. Japanese equipment rental chains stock these for residential sidewalk repairs.
- Medium:Balanced centrifugal force and maneuverability serve general construction. United States independent rental firms maintain highest fleet counts in this class.
- Large:Extended base plates and higher amplitude target highway subgrade preparation. Chinese state-owned construction enterprises deploy these for belt-and-road infrastructure.
- Extra Large:Specialized dam and landfill compaction requires dedicated transport trailers. Limited unit volumes with project-specific procurement cycles.
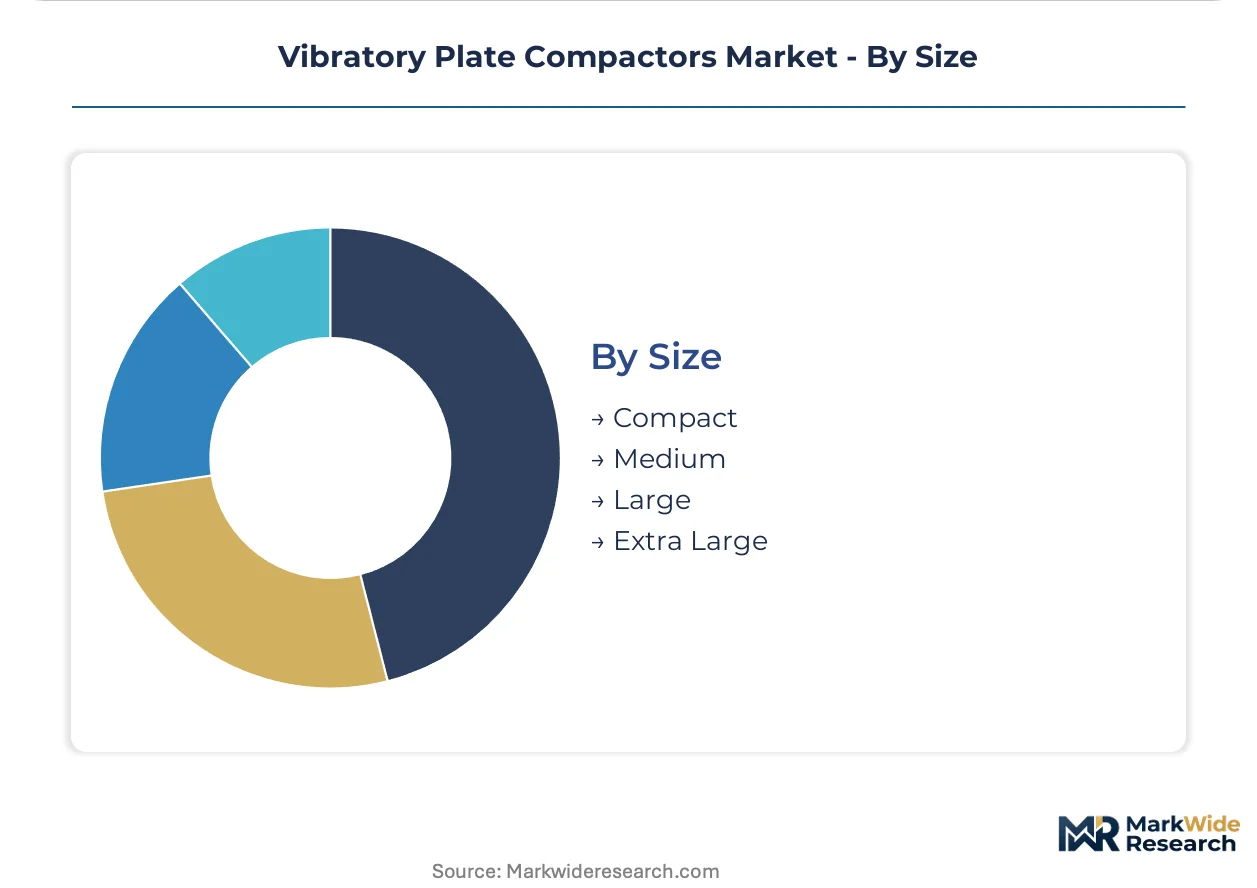
Medium holds the largest share; momentum sits with Compact as urban densification constrains site access.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German engineering specifications and Chinese infrastructure deployment anchor manufacturing concentration, while municipal procurement patterns in the United States and India reshape regional demand trajectories.
United States
Municipal road maintenance agencies in Texas and Florida are expanding fleet purchases ahead of federal infrastructure disbursement timelines. EPA Tier 4 Final emission standards compel diesel engine upgrades or electric platform pivots. Equipment rental firms in Houston cycle mid-size reversible units through oil-patch construction seasons.
Germany
Bavarian road maintenance authorities specify premium-class reversible plates for urban reconstruction contracts with confined site geometries. EU Stage V regulations enforced by KBA mandate diesel particulate filters and selective catalytic reduction systems. Stuttgart-based engineering clusters drive specification standards across European municipal procurement.
China
State-owned construction enterprises deploy heavy-duty units for belt-and-road infrastructure including dam and airport runway construction. MIIT emission standards and dual carbon goals accelerate electric drivetrain trials in coastal provinces. Manufacturing concentration in Shandong and Jiangsu provinces supplies domestic and export markets.
India
Smart Cities Mission urban infrastructure densification creates demand for compact reversible plates in Maharashtra and Karnataka. BIS certification requirements and DGFT import duty structures favor localized assembly partnerships. Mumbai and Bangalore municipal corporations specify mid-size electric units for nighttime road maintenance.
Japan
Landscaping contractors in Tokyo and Osaka prefectures favor lightweight gasoline-powered configurations for residential sidewalk repairs. METI energy efficiency guidelines and JIS standards shape product specifications. Kanto region equipment rental chains stock sub-100 kg designs for manual transport applications.
Vibratory Plate Compactors Market Vendor Landscape
Concentration sits with diversified industrial equipment conglomerates and specialized compaction machinery manufacturers. The vendor base spans three tiers: premium engineering-led specialists, scale-driven rental channel suppliers, and regional fabrication houses serving price-sensitive developing markets. Strategic moves center on electrification platform development and telematics integration for usage-based service models.
Among German engineering-led specialists, Wacker Neuson SE and Bomag GmbH exemplify specification-driven positioning anchored in European municipal procurement standards. Weber Maschinentechnik GmbH occupies a position within the precision fabrication tier. Caterpillar Inc. anchors North American rental channel supply through its dealer network infrastructure. Mikasa Sangyo Co. Ltd. represents the lightweight specialization archetype serving Japanese landscaping contractors.
| Leading Market Players |
|---|
| Ammann Group |
| Weber Maschinentechnik GmbH |
| Wacker Neuson SE |
| Mikasa Sangyo Co. Ltd. |
| Doosan Corporation |
| Caterpillar Inc. |
| Atlas Copco AB |
| Multiquip Inc. |
| Bomag GmbH |
| Others |
Supply Flow & Price Mechanics
EPA Tier 4 Final certification gates both supplier qualification and price differentiation simultaneously, forcing manufacturers to absorb after-treatment hardware costs on sub-500 kg machines while enabling premium positioning for electric variants that bypass compliance burden entirely.
Pricing Analysis
EPA Tier 4 Final dictates the pricing tier structure across the vibratory plate compactor landscape. Three-tier pricing structure across premium, standard, and economy levels separates EU Stage V-compliant reversible units from Tier 4 Final diesel workhorses and uncertified gasoline configurations. Price differentiation centers on certification grade and after-sales service bundling. Cost compression in standard-class diesel machines is intensifying because after-treatment hardware adds weight without performance gain. Municipal fleet operators show lowest price sensitivity; independent rental firms in developing markets exhibit highest.
Supply Chain Analysis
Lithium-ion cell production concentration in China and South Korea underwrites electric variant cost structures. High-grade carbon steel plate sourcing draws from Shandong and Jiangsu provinces alongside German and Japanese mill networks. Supply chain risk concentrates in single-source vulnerability for cylindrical cell formats. Distribution runs through Caterpillar dealer networks in North America, Wacker Neuson direct specification channels in Europe, and localized assembly partnerships in India.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Telematics-enabled condition monitoring represents a service-attach opportunity expanding faster than hardware sales, allowing rental houses to unbundle predictive maintenance from base equipment rates.
For Market Incumbents: Fortify electric platform development through backward integration into battery pack assembly, insulating margin pools from cell supply volatility. Secure UL 2580 certification ahead of competitors to lock municipal procurement specifications. Channel control through dealer network exclusivity agreements defends against emerging Chinese manufacturers targeting price-sensitive segments. For New Entrants and Emerging Players: Battery swapping infrastructure deployment gaps in urban construction fleets offer white-space entry where incumbents under-serve. Target compact electric units for indoor slab preparation applications previously inaccessible to diesel equipment. Go-to-market through equipment rental consortium partnerships bypasses direct sales force buildout requirements. For Investors and Strategic Acquirers: EU Stage V enforcement reshapes the acquisition landscape toward electric drivetrain capability holders. Long-term viability favors vertically integrated specialists with captive battery sourcing and embedded systems expertise. Watch charging infrastructure buildout velocity in Germany and California as inflection indicator for platform commitment timing.| Strategic Initiative | Industry Significance |
|---|---|
| Electric Platform Development | Battery energy density trajectories in China and South Korea determine capital commitment timing for fleet operators. |
| Telematics Integration | Real-time vibration analytics enable usage-indexed pricing models that shift operating risk to equipment operators. |
| Backward Integration | In-house production of battery packs insulates gross margins from lithium-ion cell supply concentration vulnerability. |
| Certification Investment | Dual EPA and UL 2580 approval accelerates product launch cycles for municipal procurement windows. |
| Localized Assembly Partnerships | Joint ventures in Maharashtra and Karnataka bypass BIS certification delays and DGFT import duty structures. |
Methodological Framework
Two parallel data streams informed the analysis: primary interviews with equipment fleet managers, rental house operations directors, municipal procurement officers, and aftermarket service heads; and secondary validation through EPA certification filings, EU type-approval databases, customs trade records, and OEM SEC disclosures. Bottom-up unit shipment estimates triangulated against top-down infrastructure spending allocations across the analysis window.
Across the projection horizon, the analytical framework modeled segmentation dimensions spanning product type, power source architecture, size class, and end-use vertical. CAGRs derived from regression against historical replacement cycles and regulatory compliance deadlines. Forecast inputs incorporated battery cost curves and charging infrastructure deployment schedules.
Underlying assumptions cover steady emission standard enforcement timelines and stable steel input pricing, with deviation risk concentrated in battery cell supply disruptions and municipal budget allocation shifts. Practitioners should keep alternative scenarios live as EU Stage V implementation pace and lithium mining expansion trajectories evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Press Brakes Market
Construction Equipment
Portable Rebar Bending Machine Market
Construction Equipment
Crossover Ladder Market
Construction Equipment
Europe Used Construction Machinery Market
Construction Equipment
CNC Lathe Machine Market
Construction Equipment
Welding Equipment Market
Construction Equipment
Hybrid Construction Equipment Market
Construction Equipment
Stick Welding Electrode Market
Construction Equipment
Rough Terrain Crane Market
Construction Equipment
Cementing Accessories Market
Construction Equipment
Piling Machine Market
Construction Equipment
Baler Market
Construction Equipment
Bulldozer Rental Market
Construction Equipment
Mobile Elevating Work Platform (MEWP) Market
Construction Equipment
Global Skid Steer Attachments Market
Construction Equipment
Rotational Moulding Machines Market