
 Tunnel Boring Machines Market | 2026-2036
Tunnel Boring Machines Market Size, Share, and Industry Trends Forecast 2026-2036
Tunnel Boring Machines Market Analysis
Municipal transit authorities are bifurcating from mining conglomerates as the dominant buyer archetype for new tunnel boring machines. Herrenknecht AG leverages its deep specialization in slurry shield systems for urban water-pressure environments. Komatsu Ltd. anchors its position through captive supply of cutterhead components and in-house production of drive systems. Dalian Huarui Heavy Industry Group Co. Ltd. competes aggressively on manufacturing scale for hard rock variants serving hydroelectric developers.
A tunnel boring machine is a mechanized excavation system comprising a rotating cutterhead, thrust cylinders, segment erector, and muck removal conveyor, designed to excavate circular tunnels through soil or rock while simultaneously installing precast concrete lining segments. The equipment operates at diameters ranging from under four meters for utility tunnels to over fifteen meters for vehicular passages, with advance rates typically measured in meters per day depending on geotechnical conditions. Slurry shield and earth pressure balance machines dominate urban metro applications where groundwater control determines project viability, while hard rock systems retain stronger margins in mining and hydroelectric sectors where longer tunnel lengths amortize capital intensity. MixShield configurations represent the fastest-growing technology segment as contractors seek single-machine flexibility across variable geology.
China's SAMR enforces GB standards for structural welding and electromagnetic compatibility that constrain import eligibility for non-domestic manufacturers. The EU F-Gas Regulation and REACH framework from ECHA govern hydraulic fluid formulations and seal material composition for machines deployed in European infrastructure. Japan's METI coordinates with JIS standards bodies to certify noise and vibration thresholds for urban deployment. Stakeholders must monitor how divergent national certification regimes fragment equipment specification standards and reshape supplier qualification timelines.
Market Dynamics
Urban metro authorities now dominate procurement volumes, displacing mining conglomerates as the primary buyer archetype and forcing manufacturers to reconfigure product portfolios toward slurry shield and earth pressure balance systems optimized for water-pressure environments beneath dense city centers.
Growth Catalysts
- China's GB standards tightening:SAMR enforcement of structural welding and electromagnetic compatibility rules is accelerating domestic equipment replacement cycles and constraining import eligibility for non-compliant foreign suppliers.
- India's urban rail corridors:Subterranean alignments dominate new network extensions across Delhi, Mumbai, and Bengaluru metro systems, concentrating demand for large-diameter machines in geotechnically complex alluvial plains.
- MixShield technology maturation:Single-machine flexibility across variable geology reduces contractor fleet requirements and enables faster mobilization between projects with differing ground conditions.
Market Restraints
- Specialized steel supply concentration:High-grade cutterhead alloy production concentrates in select European and Japanese foundries, exposing manufacturers to input cost volatility and extended lead times.
- EU F-Gas Regulation compliance:Hydraulic fluid formulation restrictions and seal material composition mandates under REACH and ECHA frameworks add certification friction for equipment deployed in European infrastructure.
- Long amortization cycles:Capital intensity of hard rock systems requires project portfolios with tunnel lengths exceeding ten kilometers to justify unit economics, limiting addressable project inventory.
Strategic Opportunities
- Southeast Asian urban rail:Vietnam, Indonesia, and the Philippines are initiating first-generation metro systems where subterranean construction methods remain underpenetrated relative to elevated alternatives.
- Japan's METI noise thresholds:Stricter JIS certification for urban vibration and acoustic emissions creates premium positioning for manufacturers with advanced dampening systems and electric drive architectures.
- Digital twin integration:Convergence of real-time cutterhead telemetry with predictive maintenance software enables outcome-based service contracts and unbundled aftermarket revenue streams.
Industry Challenges
- Geotechnical specialist scarcity:Shortage of engineers capable of interpreting mixed-face conditions and adjusting machine parameters in real time extends commissioning timelines and elevates project risk.
- Multi-jurisdictional certification:Divergent national regimes across China's GB standards, EU REACH, and Japan's JIS frameworks fragment equipment specifications and reshape supplier qualification timelines.
- Legacy fleet integration:Contractors operating heterogeneous machine generations face compatibility gaps between proprietary control systems and modern segment erector automation protocols.
Report Scope
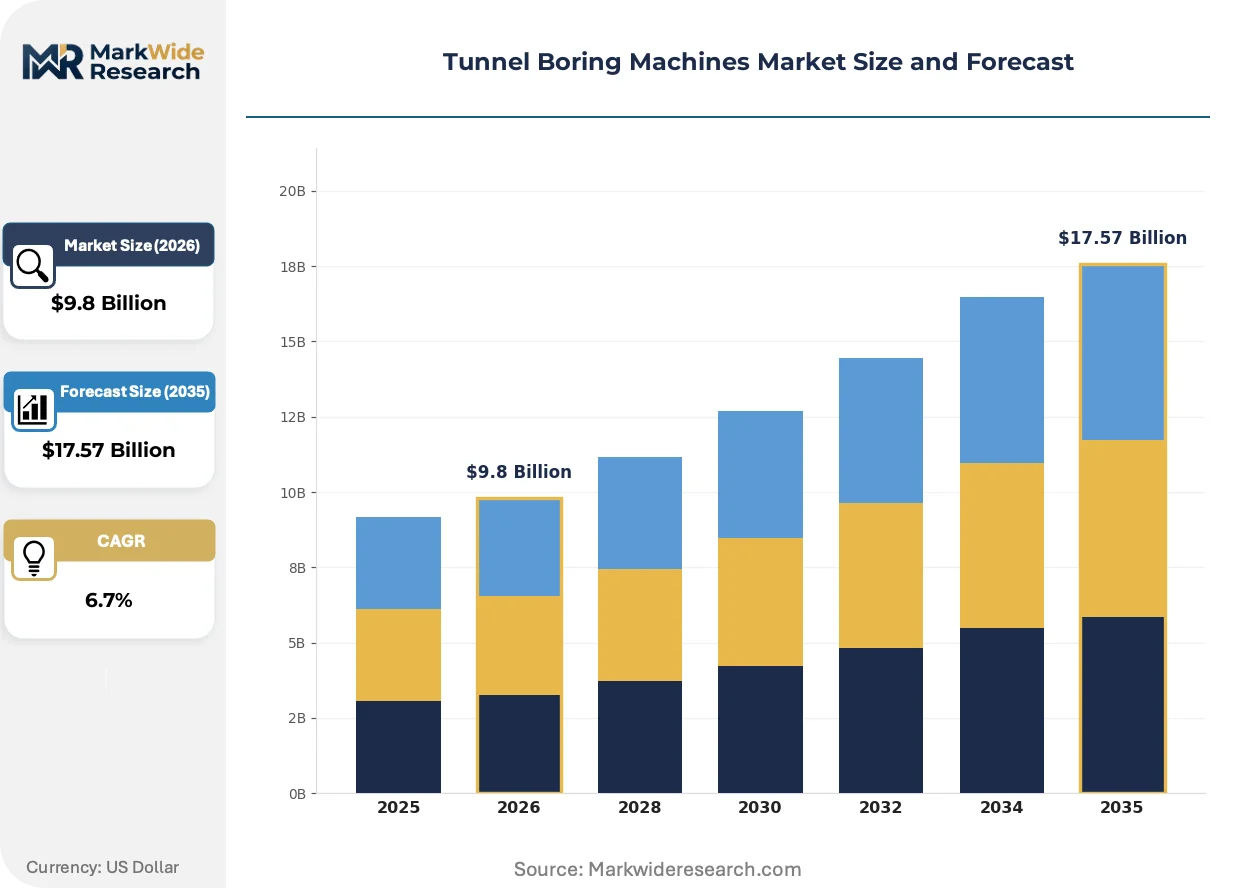
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tunnel Boring Machines Market |
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $17.57 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Earth Pressure Balance, Slurry Shield, Hard Rock, MixShield Technology: Conventional Method, EPB Technology, Slurry TBM, Open Face End User: Transportation, Water Infrastructure, Mining, Utilities Application: Metro Systems, Road Tunnels, Sewer Tunnels, Hydroelectric Projects |
| Companies Covered | Komatsu Ltd., Hitachi Zosen Corporation, Herrenknecht AG, Dalian Huarui Heavy Industry Group Co. Ltd., IHI Corporation, China Railway Engineering Equipment Group Co. Ltd., Kawasaki Heavy Industries Ltd., Northern Heavy Industries Group Co. Ltd., China Railway Construction Heavy Industry Corporation Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tunnel Boring Machines Market Emerging Trajectories
Equipment architecture is undergoing fundamental redesign as contractors demand single-machine adaptability across projects with unpredictable geology, while regulatory pressure on emissions and noise accelerates electric drivetrain adoption and hydraulic system replacement.
Autonomous cutterhead control systems are miniaturizing sensor arrays and embedded computing power to enable real-time geological interpretation without surface intervention. Metro contractors in Japan and South Korea are deploying these configurations for overnight maintenance windows in dense urban corridors. This compression of decision latency is reducing face stability incidents and accelerating advance rates in variable ground.
REACH framework amendments from ECHA are mandating biodegradable hydraulic fluid formulations and fluorinated gas phase-outs for seal inflation systems. Manufacturers serving European infrastructure must reformulate supply chains and validate alternative chemistries under accelerated compliance deadlines. The slurry shield segment bears disproportionate impact due to its reliance on pressurized fluid circuits for face support.
Service contract unbundling is separating machine provision from operational support, with specialized contractors assuming thrust cylinder maintenance and cutterhead refurbishment responsibilities. This channel restructuring displaces traditional bundled procurement through equipment financiers and concentrates aftermarket value with regional service specialists. The shift is most visible in Australia's tunnelling sector, where project-specific joint ventures now dominate machine operation rather than ownership.
Tunnel Boring Machines Market Segmentation
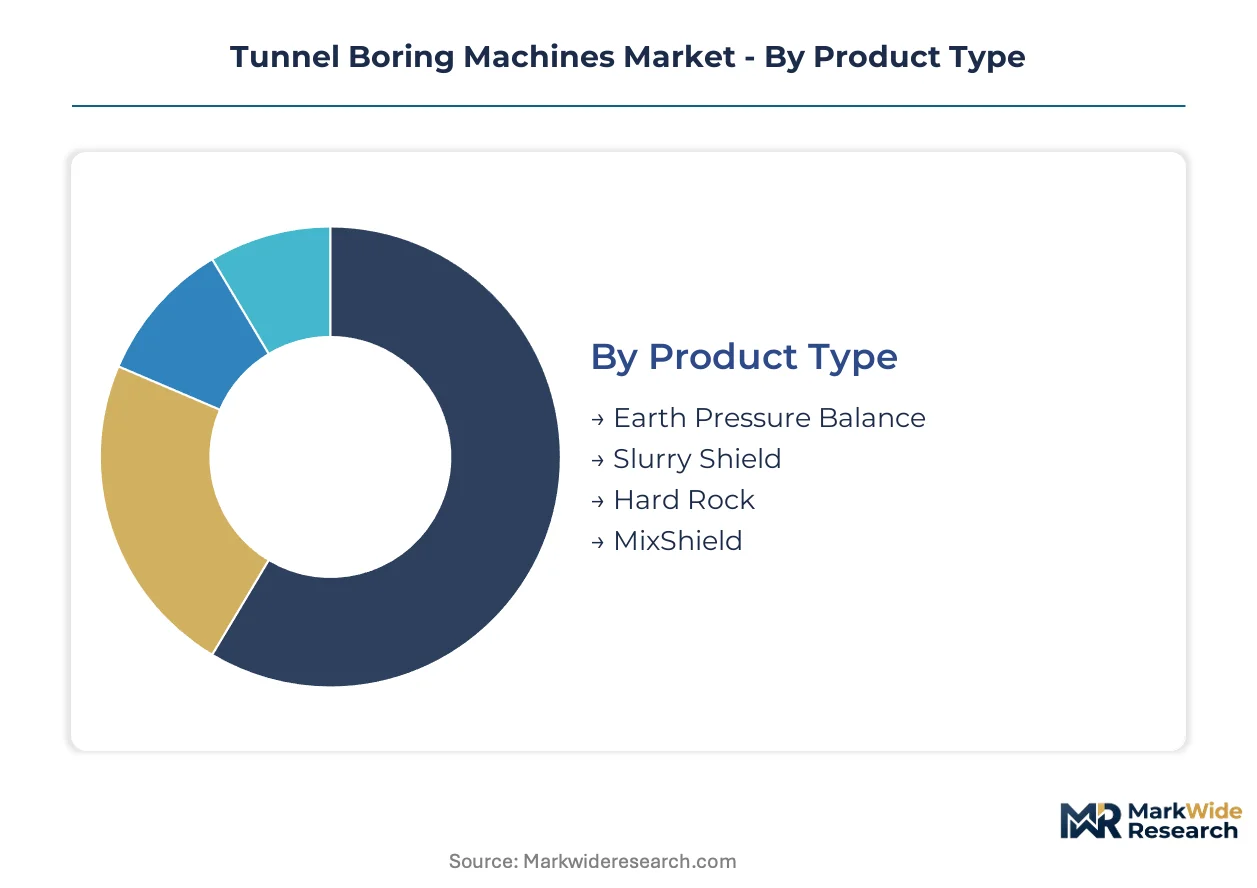
Equipment specification diverges sharply across tunneling contexts, with geology and groundwater conditions dictating machine architecture. Procurement patterns concentrate in urban metro authorities seeking slurry shield and earth pressure balance configurations, while mining and hydroelectric developers sustain demand for hard rock variants.
Product Type:
Margin pools concentrate in slurry shield and MixShield configurations where water-pressure environments beneath dense urban centers command premium pricing and specialized aftermarket service contracts.
- Slurry Shield:Pressurized bentonite slurry stabilizes the excavation face in high-water-table conditions beneath rivers and coastal cities. Demand concentrates in China's Yangtze River Delta metro corridors and India's Mumbai coastal alignments where groundwater control determines project viability.
- MixShield:Convertible face support systems toggle between slurry and earth pressure modes without machine withdrawal. Contractors in Germany's Stuttgart and Australia's Sydney deploy these configurations for projects traversing variable geology, reducing fleet requirements and mobilization delays.
- Earth Pressure Balance:Screw conveyor muck removal maintains face pressure in cohesive soils without slurry circulation. Urban rail authorities in Japan and South Korea specify these machines for dense residential corridors where slurry plant footprint is prohibitive.
- Hard Rock:Gripper or shielded configurations with disc cutter arrays penetrate abrasive quartzite and granite. Hydroelectric developers in Norway and mining conglomerates in Chile sustain this segment through projects exceeding ten kilometers in length.
Slurry Shield holds installed capacity. MixShield is rotating up the share rankings.
Technology:
Technology selection tracks groundwater risk and face stability requirements, with pressurized systems displacing open-face methods in urban applications.
- EPB Technology:Earth pressure balance systems with foam conditioning circuits dominate soft ground urban tunneling. China's SAMR GB standards for electromagnetic compatibility and structural welding accelerate domestic equipment replacement cycles for these configurations.
- Slurry TBM:Closed slurry circuits with separation plants manage high-permeability sands and gravels beneath water bodies. Contractors on the Fehmarn Belt Fixed Link between Germany and Denmark deploy these systems for subsea passages.
- Conventional Method:Open or compressed-air face support without continuous pressure control persists in stable rock with limited water ingress. Legacy procurement in developing markets sustains this tier.
- Open Face:Unshielded excavation with immediate ground support installation retains niche application in self-supporting rock masses with minimal overburden.
EPB Technology commands the largest installed base. Slurry TBM is climbing the fastest.
End User:
Customer archetypes have bifurcated, with municipal transit authorities displacing mining conglomerates as the dominant procurement volume.
- Transportation:Metro authorities and highway agencies specify large-diameter machines for vehicular and rail passages. Delhi Metro Rail Corporation and Singapore's Land Transport Authority concentrate demand for diameters exceeding twelve meters.
- Water Infrastructure:Sewerage boards and water utilities drive demand for mid-diameter utility tunnels. Thames Tideway in London and Paris's Grand Paris Express sanitation corridors deploy specialized configurations.
- Mining:Hard rock ore transport declines in procurement share as open-pit alternatives and autonomous haulage reduce underground development.
- Utilities:Power transmission and telecommunications cable tunnels sustain small-diameter demand in dense urban rights-of-way.
Transportation anchors procurement volumes. Water Infrastructure is expanding most quickly.
Application:
Application mix tracks infrastructure investment cycles, with metro systems commanding capital allocation in emerging urban rail markets.
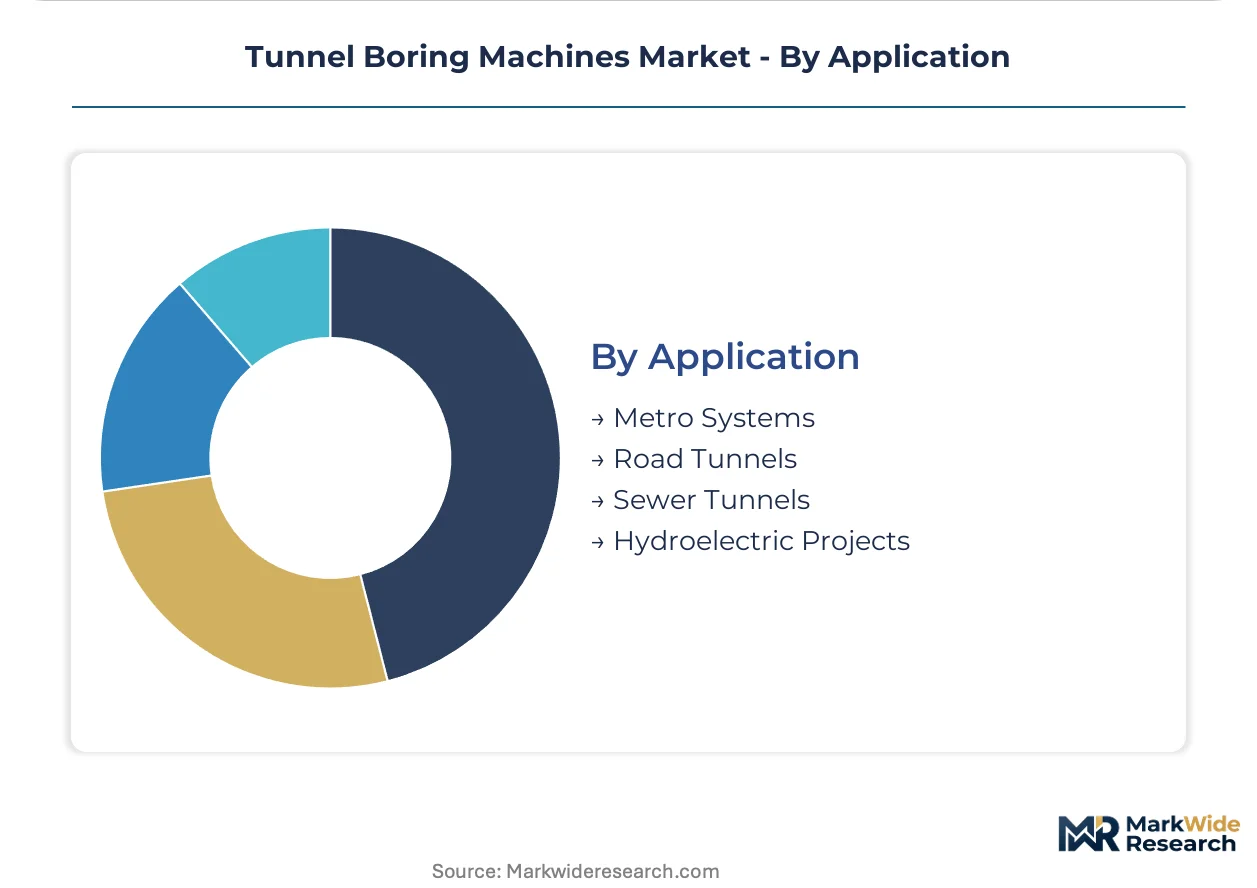
- Metro Systems:Subterranean alignments dominate network extensions in geotechnically complex alluvial plains. India's Delhi, Mumbai, and Bengaluru systems concentrate procurement for large-diameter earth pressure balance machines.
- Road Tunnels:Vehicular passages beneath urban centers and mountain crossings sustain demand for diameters exceeding fifteen meters. Norway's E39 coastal highway and China's urban expressway networks drive specifications.
- Sewer Tunnels:Deep interceptor and storage tunnels for combined sewer overflow control deploy mid-diameter slurry shield systems. EU Urban Waste Water Treatment Directive compliance sustains this segment.
- Hydroelectric Projects:Headrace and tailrace tunnels in mountainous terrain retain hard rock machine deployment. Projects in Switzerland, Austria, and the Himalayas sustain this application.
Metro Systems hold the dominant share position. Sewer Tunnels is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Municipal transit authorities in China and India now concentrate procurement volumes, displacing mining conglomerates as the dominant buyer archetype across Asia-Pacific infrastructure corridors.
China
Metro authorities in the Yangtze River Delta and Pearl River Delta drive demand for slurry shield configurations beneath high-water-table urban centers. SAMR enforcement of GB standards for structural welding and electromagnetic compatibility accelerates domestic equipment replacement cycles and constrains import eligibility for non-compliant foreign suppliers. Shanghai and Shenzhen municipal rail corporations concentrate procurement for diameters exceeding twelve meters.
India
Delhi Metro Rail Corporation and Mumbai Metro specify large-diameter earth pressure balance machines for subterranean alignments across geotechnically complex alluvial plains. The Ministry of Housing and Urban Affairs coordinates with CEA certification requirements for tunnel safety equipment deployed in public infrastructure corridors. Bengaluru and Hyderabad urban rail extensions concentrate demand for MixShield configurations traversing variable geology.
Germany
Contractors on the Fehmarn Belt Fixed Link and Stuttgart urban rail deploy slurry TBM systems for subsea passages and water-pressure environments beneath dense city centers. ECHA REACH framework amendments mandate biodegradable hydraulic fluid formulations and fluorinated gas phase-outs for seal inflation systems. Herrenknecht AG anchors specialized aftermarket service networks across the Rhine-Ruhr and Stuttgart industrial clusters.
Japan
Tokyo Metro and Osaka Municipal Subway specify earth pressure balance machines with advanced dampening systems for dense residential corridors where slurry plant footprint is prohibitive. METI coordinates with JIS standards bodies to certify stricter noise and vibration thresholds for urban deployment. Nagoya and Fukuoka rail authorities concentrate procurement for electric drive architectures meeting acoustic emissions requirements.
Australia
Sydney Metro contractors deploy MixShield configurations for projects traversing variable sandstone and shale geology beneath the harbor city. The country's national infrastructure regulator enforces tunnel safety certification aligned with ISO standards for mechanized excavation equipment. Melbourne and Brisbane urban rail extensions concentrate demand for service-contract unbundling arrangements with regional operation specialists.
Tunnel Boring Machines Market Vendor Landscape
Player mix skews toward integrated machinery conglomerates with captive component production and specialized slurry system engineers serving water-pressure environments. Market structure concentrates around three strategic archetypes: German specialists in pressurized face support systems, Japanese diversified heavy industrial groups with in-house drive system production, and Chinese state-linked fabricators scaling hard rock variants for domestic hydroelectric developers. Dominant competitive moves include backward integration into cutterhead alloy supply and technology licensing agreements for MixShield mode-conversion mechanisms.
Among German-based specialists, Herrenknecht AG exemplifies the engineering-intensive archetype focused on slurry shield and MixShield configurations. Japanese conglomerates Hitachi Zosen Corporation and Kawasaki Heavy Industries Ltd. occupy positions within the diversified industrial tier, leveraging in-house production capabilities across marine and heavy machinery segments. Chinese fabricators Dalian Huarui Heavy Industry Group Co. Ltd. and China Railway Engineering Equipment Group Co. Ltd. represent the scale-driven end, anchoring domestic procurement for large-diameter urban metro deployment.
| Leading Market Players |
|---|
| Komatsu Ltd. |
| Hitachi Zosen Corporation |
| Herrenknecht AG |
| Dalian Huarui Heavy Industry Group Co. Ltd. |
| IHI Corporation |
| China Railway Engineering Equipment Group Co. Ltd. |
| Kawasaki Heavy Industries Ltd. |
| Northern Heavy Industries Group Co. Ltd. |
| China Railway Construction Heavy Industry Corporation Limited |
| Others |
Supply Flow & Price Mechanics
Capacity utilization at European and Japanese specialty steel foundries sets effective price floors for cutterhead assemblies, concentrating margin pressure on manufacturers without captive alloy supply or long-term offtake agreements with Yangtze River Delta metal suppliers.
Pricing Analysis
Cost-plus contracts with steel price indexation dominate procurement between machine manufacturers and municipal transit authorities. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and after-sales service bundling, with EU F-Gas Regulation compliance adding certification premiums for European deployment. Cost compression in standard-tier configurations is intensifying because Chinese state-linked fabricators are scaling domestic production of earth pressure balance systems. Mining conglomerates show least price sensitivity due to long amortization cycles, while Southeast Asian first-generation metro authorities exhibit highest sensitivity to upfront capital outlays.
Supply Chain Analysis
Strait of Malacca transit underwrites just-in-time delivery schedules for high-grade cutterhead alloys sourced from German, Japanese, and South Korean foundries. Component production draws from specialized European suppliers for thrust cylinder seals, Chinese fabricators for segment erector mechanisms, and domestic Japanese producers for electric drive architectures. Single-source vulnerability concentrates in high-grade tungsten carbide cutter inserts where alternative qualified suppliers remain limited. Distribution runs through project-specific joint ventures in Australia and regional service specialists in Germany rather than traditional equipment financiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Metro authority procurement programs across Asia-Pacific are still in early-cycle expansion, with subterranean alignments in Indian urban rail corridors driving penetration rates well below saturation thresholds for mechanized tunneling equipment.
For Market Incumbents: Consolidate aftermarket service networks through acquisition of regional cutterhead refurbishment specialists, particularly in Australia's unbundled contracting environment. Deepen backward integration into high-grade alloy supply by securing long-term offtake agreements with Yangtze River Delta foundries, countering input cost volatility that threatens margin stability in slurry shield production lines. For New Entrants and Emerging Players: Fast-track GB standards certification through partnership with China's SAMR-recognized testing bodies to unlock domestic procurement eligibility. Target Vietnam's first-generation metro systems where subterranean construction methods remain underpenetrated relative to elevated alternatives, offering MixShield configurations on lease-to-operate terms that reduce upfront capital barriers for emerging transit authorities. For Investors and Strategic Acquirers: Specialized slurry system engineering boutiques with proprietary mode-conversion patents represent the most defensible acquisition targets in a consolidating supplier landscape. Long-term viability hinges on exposure to urban water-pressure environments where regulatory barriers and technical complexity sustain margin premiums. Monitor MixShield adoption rates across German and Australian projects as the inflection indicator for technology substitution cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cutterhead Alloy Supply | Captive supply from Yangtze River Delta foundries insulates margin stability against European input cost volatility. |
| MixShield Technology Licensing Agreements | Mode-conversion patents unlock single-machine flexibility across variable geology projects in Stuttgart and Sydney. |
| Digital Twin Platform Development | Real-time telemetry integration with predictive maintenance software enables outcome-based service contracts with Delhi Metro. |
| Regional Service Specialist Acquisition | Aftermarket unbundling in Australia's tunnelling sector concentrates value with operation-focused joint ventures. |
| Electric Drive Architecture Certification | METI-coordinated JIS compliance for noise thresholds secures premium positioning in Tokyo and Osaka corridors. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted across the primary research phase, including metro authority procurement directors, tunneling contractor project managers, cutterhead alloy foundry technical leads, and aftermarket service specialists. Secondary validation drew from SAMR GB standards filings, ECHA REACH amendment documentation, METI JIS certification registries, and municipal rail corporation tender announcements. Bottom-up equipment deployment tallies were triangulated against top-down infrastructure investment forecasts from national housing and urban affairs ministries.
Across the analysis window, the forecasting framework modeled equipment demand by machine type, diameter class, geology application, and regional regulatory cluster. CAGRs were derived from project pipeline analysis and replacement cycle timing for installed base units. Industry-specific inputs included groundwater table depth variations across alluvial plains and urban vibration threshold compliance requirements under METI-coordinated standards.
Decision-makers should treat outputs as directional under assumptions of continued municipal rail capital allocation and stable alloy supply from qualified foundries; material deviation in geotechnical specialist availability or GB standards enforcement stringency would warrant model refresh. Practitioners should keep alternative scenarios live as EU F-Gas Regulation amendment timelines and India's CEA certification requirement evolution unfold.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Construction Wearable Technology Market
Construction Equipment
Excavator Wheels Market
Construction Equipment
Piles Turner Market
Construction Equipment
Mini Cranes Market
Construction Equipment
Concrete Placing Booms Market
Construction Equipment
Laser Cladding Systems Market
Construction Equipment
Global CNC Tool and Cutter Grinding Machine Market
Construction Equipment
Automated Bending Machine Market
Construction Equipment
Global Portable Sawmills Market
Construction Equipment
Compaction Equipment Market
Construction Equipment
Felling Heads Market
Construction Equipment
Manhole Housing Lifter Hook Market
Construction Equipment
Rail Welding Equipment Market
Construction Equipment
Global Airport Snow Removal Vehicles and Equipment Market
Construction Equipment
Rotational Moulding Machines Market
Construction Equipment
Asia-Pacific Completion Equipment and Services Market