
 Shot Peening Machine Market | 2026-2036
Shot Peening Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Shot Peening Machine Market Analysis
Aftermarket service revenue is reshaping profit pools away from pure equipment sales toward lifecycle contracts and spare-part streams. Wheelabrator leverages its global installed base to sustain recurring revenue through maintenance protocols and consumable supply. Pangborn anchors North American aerospace demand with specialized nozzle configurations and process certification support. Rösler differentiates through robotic integration expertise, competing on programmable intensity control rather than unit price alone.
A shot peening machine propels metallic media at controlled velocity to induce compressive residual stress on component surfaces, typically operating at air pressures of 60–100 psi or wheel velocities exceeding 3,000 RPM to achieve specified Almen intensity values. The equipment serves primarily to extend fatigue life in cyclically loaded metal components across aviation, automotive, and heavy engineering sectors. Automatic systems dominate volume shipments for high-throughput automotive lines, while robotic configurations capture expanding share in aerospace where complex geometry access and repeatable path programming command premium positioning. Surface treatment applications anchor current demand, though fatigue strengthening commands the fastest trajectory as OEMs push design limits on lighter-weight structural alloys.
FAA airworthiness directives and EASA certification requirements mandate documented peening parameters for flight-critical components, forcing equipment vendors to embed data logging and process verification as standard features. OSHA noise exposure limits and EPA particulate emissions standards further constrain open-blast system designs, redirecting investment toward enclosed, media-recovery architectures. Stakeholders must weigh capital intensity against regulatory compliance trajectory when selecting between manual retrofit paths and fully integrated robotic cells.
Market Dynamics
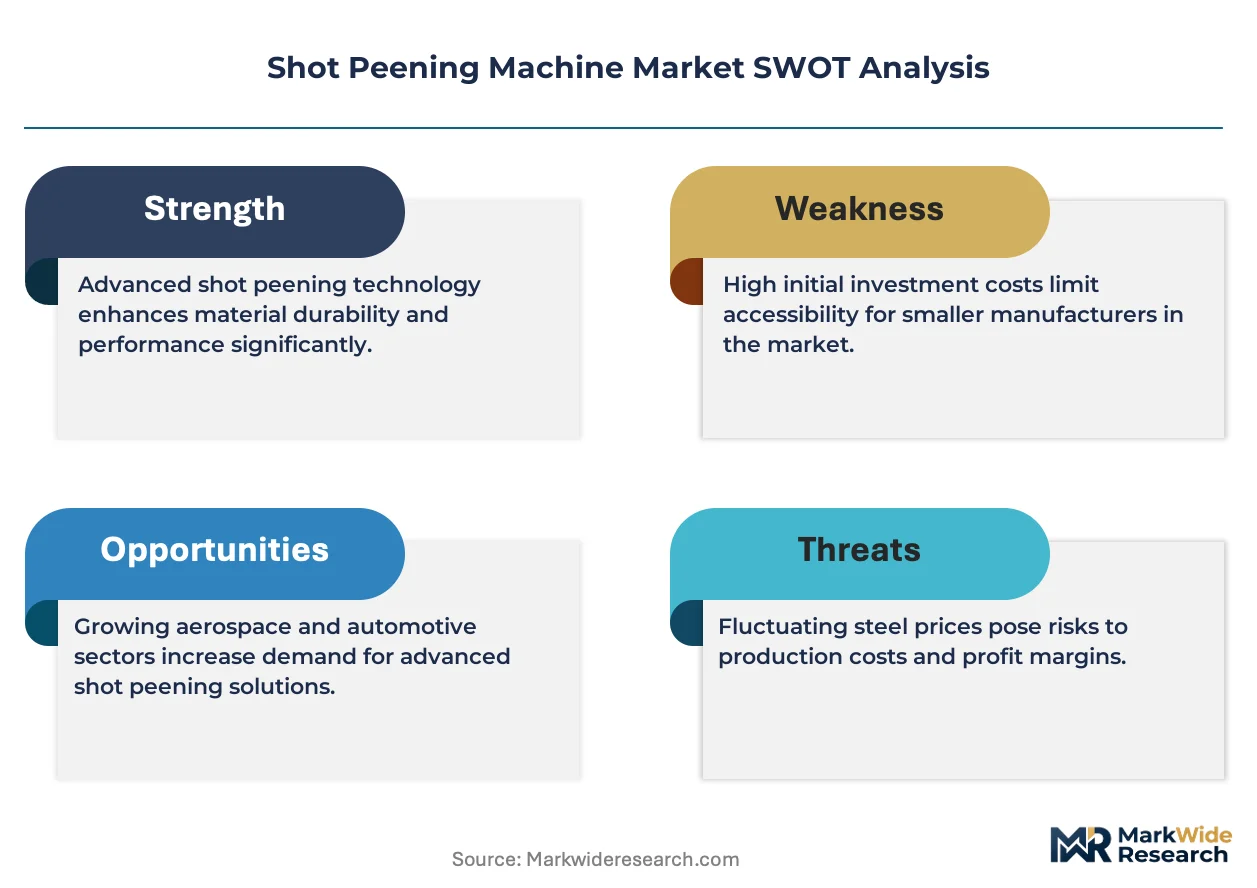
Shot peening equipment manufacturers face mounting pressure from FAA and EASA traceability mandates that now require embedded data-logging systems as standard features, fundamentally altering product architecture and customer procurement criteria.
Growth Catalysts
- FAA Airworthiness Directives:Mandated documentation of peening parameters for flight-critical components forces equipment upgrades across North American aerospace supply chains.
- Turbine blade fatigue life extension:Aerospace OEMs push design limits on lighter-weight structural alloys, expanding precision peening capacity requirements.
- Automated wheel peening systems:High-throughput automotive lines in Germany drive volume shipments of automatic configurations with programmable intensity control.
Market Restraints
- Specialized alloy media costs:Virgin steel shot and ceramic bead prices fluctuate with raw material volatility, squeezing consumable margins.
- Equipment supply concentration:Precision engineering clusters in southern Germany dominate high-end robotic system manufacturing.
- OSHA noise exposure limits:Open-blast system designs face operational constraints, requiring costly enclosure retrofits.
Strategic Opportunities
- EU Green Deal industrial decarbonization:Energy-efficient enclosed media-recovery architectures qualify for sustainability-linked capital subsidies.
- Robotic integration with additive manufacturing:Converging technologies enable post-process surface treatment of complex 3D-printed aerospace geometries.
- India defense aerospace localization:Underpenetrated demand for indigenous peening capacity supports equipment import substitution.
Industry Challenges
- Almen intensity calibration expertise:Shortage of certified process engineers delays commissioning and qualification timelines.
- Legacy PLC integration complexity:Retrofitting data-logging modules onto installed wheel and air-blast systems strains maintenance budgets.
- EASA certification documentation:Extended validation cycles for new equipment configurations freeze capital deployment decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Shot Peening Machine Market |
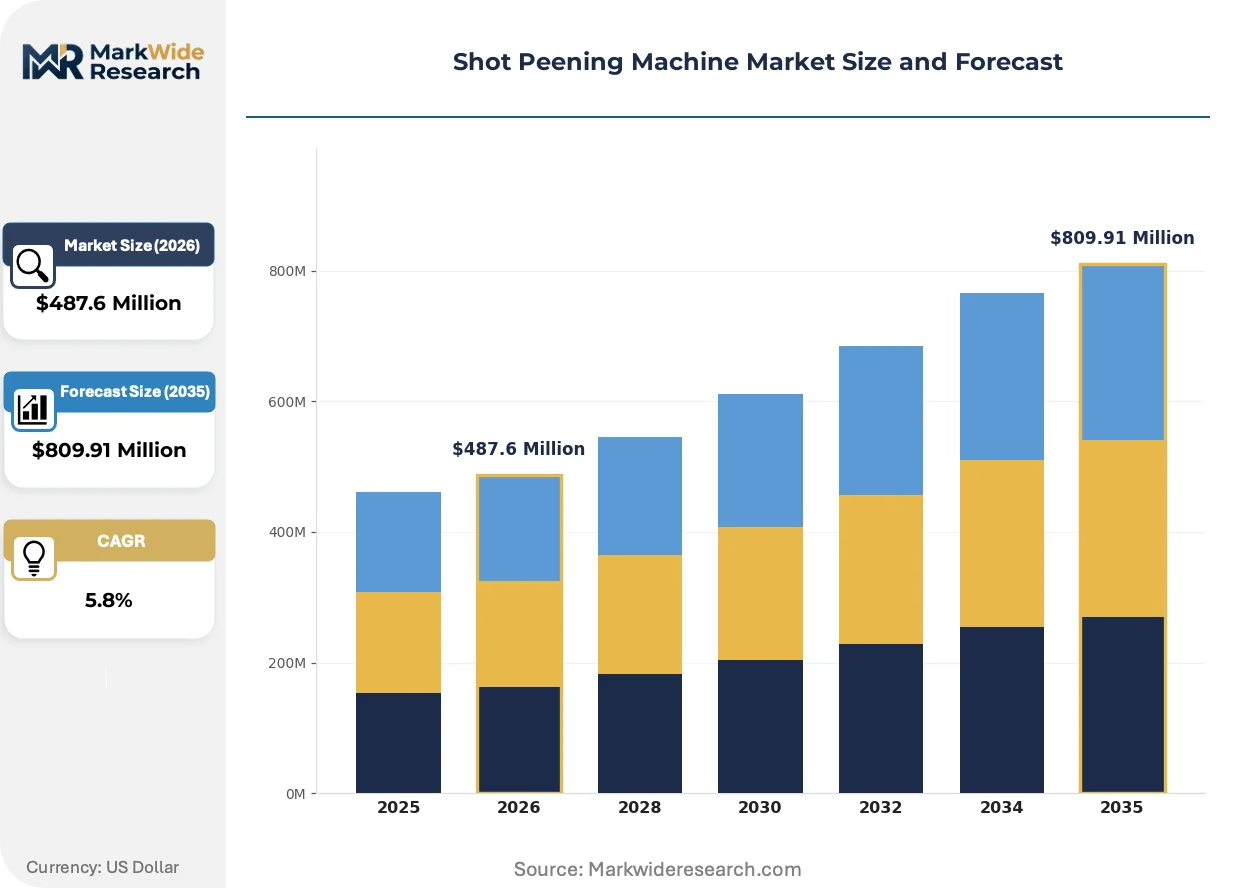
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $809.91 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual, Automatic, Semi-Automatic, Robotic End User: Aerospace, Automotive, Defense, Manufacturing Application: Surface Treatment, Stress Relief, Fatigue Strengthening, Coating Preparation Material Type: Aluminum, Steel, Titanium, Copper |
| Companies Covered | Pangborn, Goff, Wheelabrator, Qingdao Huanghe, Kaitai, Sinto, Agtos, Surfex, Rösler, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Shot Peening Machine Market Emerging Trajectories
Equipment architecture is pivoting toward closed-loop process control as regulatory traceability requirements merge with operational efficiency imperatives, reshaping vendor R&D priorities and customer upgrade cycles.
Real-time Almen strip monitoring is digitizing quality assurance workflows in aerospace peening cells. Tier-one suppliers in France and the United States deploy sensor-integrated nozzle arrays that stream intensity data directly to MES platforms. This connectivity is digitizing the handoff between equipment operators and quality engineers, compressing deviation response times from hours to minutes.
REACH restrictions on metallic particulate emissions are accelerating enclosed cabinet designs across European installations. The regulation forces open-blast operators toward media-recovery systems with HEPA filtration. Automotive stamping plants in Germany and aerospace MRO facilities in the United Kingdom absorb the highest compliance costs, redirecting capex toward integrated dust collection.
Lifecycle service contracts are displacing transactional equipment sales in buyer-vendor relationships. Airlines and automotive OEMs in Japan and South Korea now specify multi-year maintenance and consumable supply agreements in initial tenders. This preference concentrates procurement authority with vendors capable of global spare-part logistics and remote diagnostics support.
Shot Peening Machine Market Segmentation
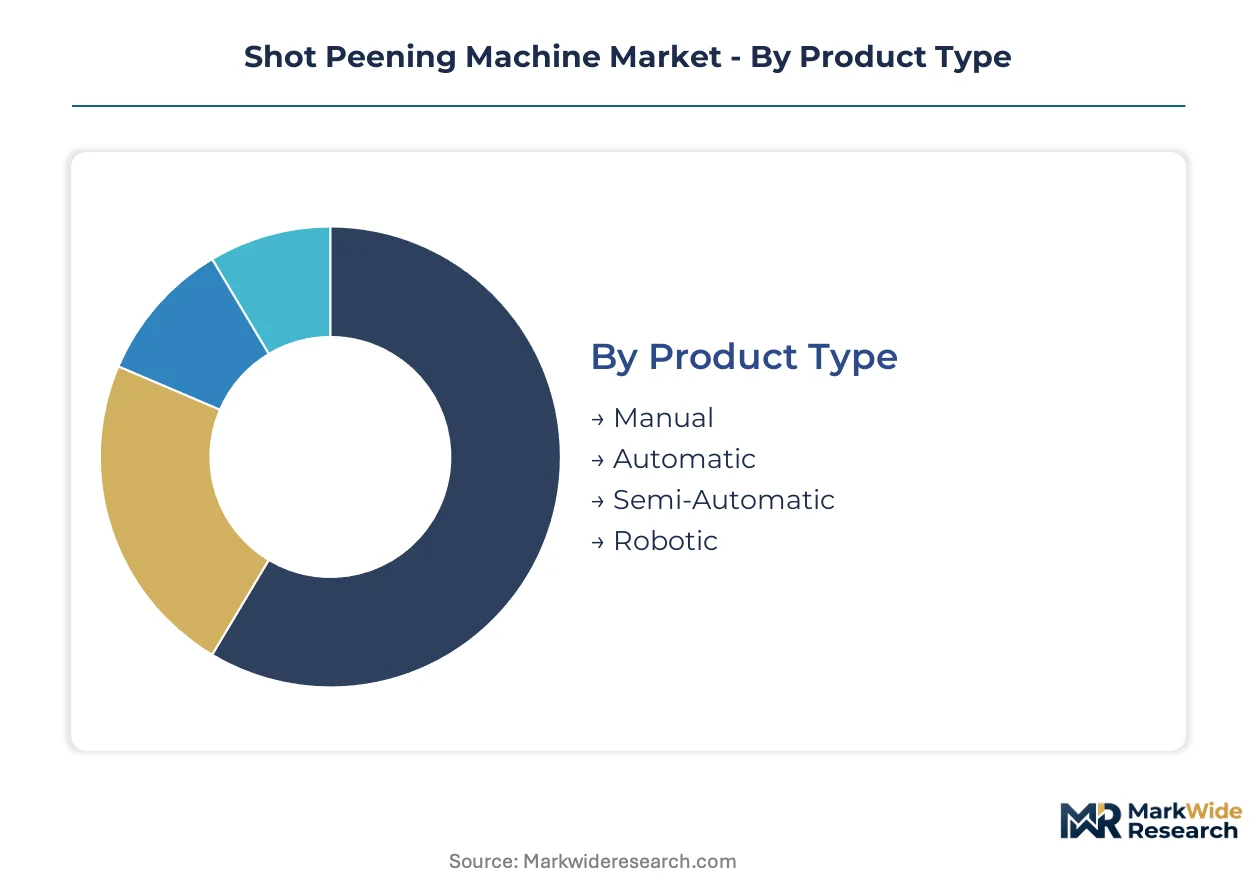
Shot peening equipment selection hinges on throughput requirements, component geometry complexity, and regulatory compliance burdens. Distinct operational profiles across aerospace MRO shops and automotive stamping plants drive divergent procurement patterns within each segment category.
Product Type:
Mature wheel-based systems dominate high-volume automotive lines, while emerging robotic configurations capture share in precision aerospace applications.
- Automatic:Wheel-driven systems with programmable intensity control process crankshafts and suspension components at cycle times under 30 seconds. German automotive OEMs specify these configurations for integrated production lines, prioritizing throughput consistency over flexibility.
- Robotic:Six-axis manipulators with specialized nozzle arrays navigate complex turbine blade geometries and additive-manufactured aerospace structures. FAA traceability mandates accelerate adoption as embedded data-logging becomes standard architecture.
- Manual:Operator-directed air-blast cabinets serve low-volume job shops and prototype workshops where part variety exceeds automation economics.
- Semi-Automatic:Hybrid configurations blend operator loading with automated peening cycles, bridging cost gaps for mid-tier suppliers in defense and general manufacturing.
Automatic systems handle the majority of throughput; robotic configurations are expanding most quickly on share as aerospace qualification requirements tighten.
End User:
Customer procurement authority concentrates with tier-one suppliers possessing in-house process engineering capabilities.
- Aerospace:Turbine blade fatigue life extension and landing gear component treatment drive precision peening demand. EASA certification requirements and FAA airworthiness directives mandate documented Almen intensity parameters, elevating equipment specification complexity.
- Automotive:High-volume powertrain and suspension component treatment favors wheel peening economics. German and Japanese OEMs specify automatic systems with integrated media recovery for enclosed-cell operation.
- Defense:Indigenous aerospace programs in India and regional MRO networks sustain demand for flexible, multi-material capable systems.
- Manufacturing:General industrial applications span tooling refurbishment and structural steel preparation, price-sensitive segments favoring manual and semi-automatic configurations.
Automotive absorbs the highest equipment volume; aerospace climbs the fastest as OEMs push design limits on lighter-weight structural alloys.
Application:
Functional requirements separate commodity surface preparation from engineered fatigue life extension.
- Fatigue Strengthening:Compressive residual stress induction extends service life in cyclically loaded aluminum and titanium aerospace structures. Precision intensity control and real-time Almen monitoring differentiate qualified suppliers.
- Surface Treatment:General cleaning, deburring, and cosmetic finishing of castings and forgings serves broad industrial demand with lower technical barriers.
- Stress Relief:Post-machining and post-weld stress redistribution in precision components supports tool and die manufacturing clusters.
- Coating Preparation:Anchor pattern generation for thermal spray and paint adhesion serves automotive body-in-white and industrial equipment refurbishment.
Surface treatment commands current volume leadership; fatigue strengthening gains share fastest as structural alloy specifications advance.
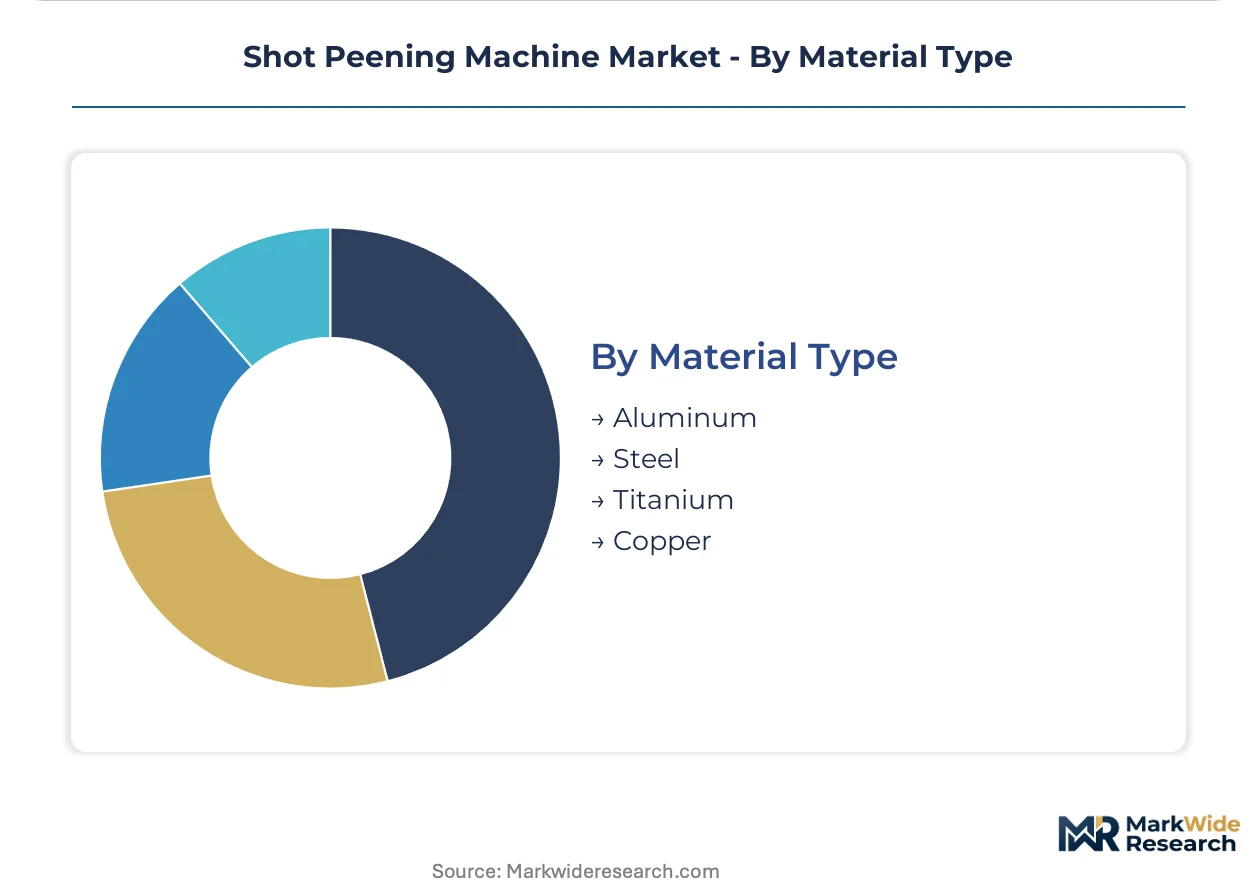
Material Type:
Workpiece metallurgy dictates media selection, intensity parameters, and equipment wear characteristics.
- Steel:Ferrous components across automotive powertrains and heavy machinery sustain the largest installed base of wheel peening systems.
- Aluminum:Lightweight structural alloys in aerospace and electric vehicle chassis require gentler intensity profiles and specialized ceramic media to avoid surface damage.
- Titanium:High-value aerospace rotating components command premium robotic cells with closed-loop process verification and full parameter traceability.
- Copper:Electrical component and heat exchanger applications represent niche demand with specialized media recovery requirements to prevent contamination.
Steel processing handles the majority of equipment utilization; titanium applications command the steepest expansion trajectory as engine OEMs optimize power-to-weight ratios.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in India and Southeast Asia exhibit acute price sensitivity, prioritizing manual and semi-automatic configurations. German and Japanese purchasers absorb premium pricing for robotic cells with embedded traceability systems.
United States
FAA airworthiness directives mandate documented peening parameters for flight-critical turbine blades, forcing equipment upgrades across aerospace supply chains. OSHA noise exposure limits constrain open-blast system designs, redirecting investment toward enclosed architectures. Connecticut and Ohio manufacturing clusters anchor precision peening capacity for landing gear and engine component treatment.
Germany
Automotive OEMs specify automatic wheel peening systems with integrated media recovery for powertrain component lines. REACH restrictions on metallic particulate emissions accelerate enclosed cabinet adoption across Bavarian and Baden-Württemberg stamping plants. Precision engineering clusters in southern Germany dominate high-end robotic system manufacturing for global tier-one suppliers.
China
Domestic electric vehicle chassis production expands demand for aluminum-compatible peening configurations with gentler intensity profiles. MIIT industrial equipment standards tighten process documentation requirements for automotive suppliers. Yangtze River Delta manufacturing hubs concentrate mid-tier automatic system fabrication for regional automotive stamping networks.
India
Defense aerospace localization programs under the PLI scheme sustain demand for flexible multi-material capable systems. BIS certification requirements for imported industrial machinery extend equipment validation timelines. Bangalore and Hyderabad defense clusters absorb imported robotic cells for indigenous turbine blade manufacturing programs.
Japan
Automotive OEMs specify multi-year maintenance and consumable supply agreements in initial equipment tenders. METI energy efficiency standards favor enclosed media-recovery architectures with integrated dust collection. Nagoya and Osaka industrial corridors concentrate high-throughput automatic system deployment for integrated powertrain lines.
Shot Peening Machine Market Vendor Landscape
Capability concentration sits with precision-engineering specialists; scale advantage sits with diversified surface-treatment conglomerates. The vendor base stratifies into three tiers: robotic integration specialists commanding aerospace premiums, automatic system fabricators serving automotive volume, and regional job-shop suppliers competing on equipment cost. Dominant competitive moves include lifecycle service contract expansion and geographic licensing partnerships for aftermarket support networks.
Among European precision-engineering specialists, Rösler and Agtos occupy positions emphasizing programmable intensity control and process certification support. Wheelabrator exemplifies the scale-driven archetype with global installed-base leverage for recurring maintenance revenue. Qingdao Huanghe represents the Chinese fabrication tier serving cost-sensitive regional demand with standardized automatic configurations.
| Leading Market Players |
|---|
| Pangborn |
| Goff |
| Wheelabrator |
| Qingdao Huanghe |
| Kaitai |
| Sinto |
| Agtos |
| Surfex |
| Rösler |
| Others |
Supply Flow & Price Mechanics
Single-source dependency on southern German precision-engineering clusters for high-end robotic systems determines both pricing tier spreads and supply chain shape, compressing margins for tier-two fabricators while elevating premium positioning for integrated vendors with captive service networks.
Pricing Analysis
After-sales revenue from lifecycle service contracts and consumable supply streams drives lifetime value more than initial equipment transactions. Three-tier pricing structure across premium, standard, and economy levels separates FAA-certified robotic cells with embedded data-logging from mid-range automatic configurations and basic manual cabinets. Cost compression in the economy tier is intensifying because Chinese fabricators are expanding standardized automatic system output. Job shops and prototype workshops exhibit the highest price sensitivity, while aerospace tier-one suppliers absorb premium pricing for traceability-compliant architectures.
Supply Chain Analysis
Tariff exposure between Germany and China dominates supply chain risk assessment for European equipment vendors sourcing control systems and servo motors. Component manufacturing concentrates in Germany, China, and Japan, with precision nozzle arrays and robotic manipulators drawing from Bavarian engineering clusters. Virgin steel shot and ceramic bead supply rests on raw material volatility in global metallurgical markets. Distribution runs through direct OEM relationships for large aerospace and automotive accounts, with regional distributors serving mid-tier job-shop demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment, where FAA and EASA certification requirements create switching costs that freeze out unqualified competitors and protect incumbent revenue streams.
For Market Incumbents: Build switching-cost moats through embedded data-logging architectures that lock customers into proprietary service ecosystems. Deepen backward integration into consumable media supply to capture recurring revenue streams and defend against commodity margin erosion. Expand certification support capabilities to accelerate customer qualification timelines and preempt emerging entrants lacking process engineering depth. For New Entrants and Emerging Players: Mid-market semi-automatic configurations for defense and general manufacturing in India represent the most penetrable entry point, given underdeveloped indigenous capacity and extended import validation timelines. Robotic integration partnerships with additive manufacturing service bureaus offer a second white-space channel for post-process surface treatment of complex 3D-printed geometries. Lead with flexible multi-material system architectures rather than competing head-to-head on aerospace certification speed. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors precision-engineering specialists with established regulatory relationships over diversified conglomerates lacking vertical process expertise. Acquisition targets should display certified Almen intensity calibration capabilities and existing FAA/EASA equipment approvals. Watch for inflection signals in India defense localization program contract awards, which would validate import substitution thesis and trigger capital deployment into regional fabrication capacity.| Strategic Initiative | Industry Significance |
|---|---|
| Lifecycle Service Contract Expansion | Recurring revenue streams from Wheelabrator's global installed base stabilize cash flow volatility. |
| Robotic Integration Partnership | Rösler's programmable intensity control expertise captures aerospace premium positioning. |
| Geographic Licensing Partnership | Aftermarket support networks in India reduce validation timeline friction for imported equipment. |
| Consumable Supply Integration | Captive virgin steel shot and ceramic bead sourcing defends margin against raw material volatility. |
| Certification Investment Acceleration | EASA documentation capabilities compress customer qualification cycles and preempt competitor entry. |
Methodological Framework
A standing panel of maintenance directors, plant engineers, OEM procurement teams, and aftermarket service heads provided ongoing calibration across primary fieldwork and secondary validation. Equipment vendor SEC filings, customs trade data for shot peening machinery imports, FAA airworthiness directive documentation, and automotive production databases supplied foundational quantitative anchors. Bottom-up sizing of installed base units and top-down triangulation against capital expenditure disclosures reinforced segment-level precision.
Scenario-bracketing around regulatory compliance trajectory and raw material cost volatility shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, end-user industry, application function, workpiece material, and regional regulatory cluster. CAGRs were derived from intensity-of-use assumptions tied to aerospace fleet expansion and automotive powertrain output. Forecast inputs incorporated Almen strip monitoring adoption curves and enclosed media-recovery architecture penetration rates.
Macroeconomic conditions sit as an overlay; deviation in defense procurement budgets, automotive capital expenditure cycles, or steel alloy commodity indices would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and equipment replacement cycle timing. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Hammer Unions Market
Construction Equipment
Induction Furnace Market
Construction Equipment
Europe Ground Penetrating Radar Market
Construction Equipment
Jackhammer Market
Construction Equipment
Electrofusion Welding Machines Market
Construction Equipment
CNC Router Market
Construction Equipment
Truck Mounted Knuckle Boom Cranes Market
Construction Equipment
Electric Hot Chamber Die Casting Machines Market
Construction Equipment
Hydraulic Breaker for Excavator Market
Construction Equipment
Hydroforming Press Market
Construction Equipment
Truck Mounted Concrete Pump Market
Construction Equipment
North America Mini and Midi Horizontal Directional Drilling Market
Construction Equipment
Used Backhoe Market
Construction Equipment
Rockbreakers Market
Construction Equipment
Global Portable Light Towers Market
Construction Equipment
Mini Cranes Market