
 Middle East and Africa Construction Equipment Market | 2026-2036
Middle East and Africa Construction Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Construction Equipment Market Foresight
The EU Green Deal's extraterritorial carbon-border pressure is recalibrating procurement criteria for contractors sourcing European-branded machinery across North African ports. Caterpillar Inc. leverages its regional parts distribution network to sustain uptime guarantees for mining fleets in Zambia and the Democratic Republic of Congo. Komatsu Ltd. anchors its position through integrated ICT construction solutions that dominate smart-city earthworks in the Gulf. JCB Ltd. competes aggressively on total cost of ownership for mid-scale contractors in Nigeria's residential building sector.
Middle East and Africa construction equipment encompasses self-propelled and towed machinery engineered for earthmoving, material handling, and vertical lifting operations, typically powered by diesel engines rated between 75 and 500 horsepower and governed by regional emissions protocols. Its primary commercial purpose centers on enabling capital-intensive infrastructure delivery, mineral extraction, and urban densification across climates ranging from arid Gulf conditions to tropical West African rainfall zones. Excavators command the largest product-type position owing to versatility across trenching, demolition, and mining benching applications. Hybrid technology represents the fastest-expanding technology category as Dubai's mandatory green building codes and Saudi Vision 2030 sustainability mandates filter down to contractor fleet specifications. Mining applications concentrate margin pools in premium-tier articulated haulers and large-class hydraulic shovels serving copper and gold operations in Southern Africa.
Egypt's Ministry of Environment enforces heavy-duty vehicle emission standards that restrict diesel-only imports, while South Africa's National Regulator for Compulsory Specifications mandates rollover protective structures and operator visibility protocols. The UAE's MOHAP-aligned occupational safety frameworks extend to construction site machinery certification, creating compliance costs that favor established distributors with in-house testing laboratories. Stakeholders must monitor how Gulf sovereign wealth fund project pipelines synchronize with local content requirements that increasingly specify assembly or component manufacturing within Saudi Arabia or the UAE.
Market Dynamics
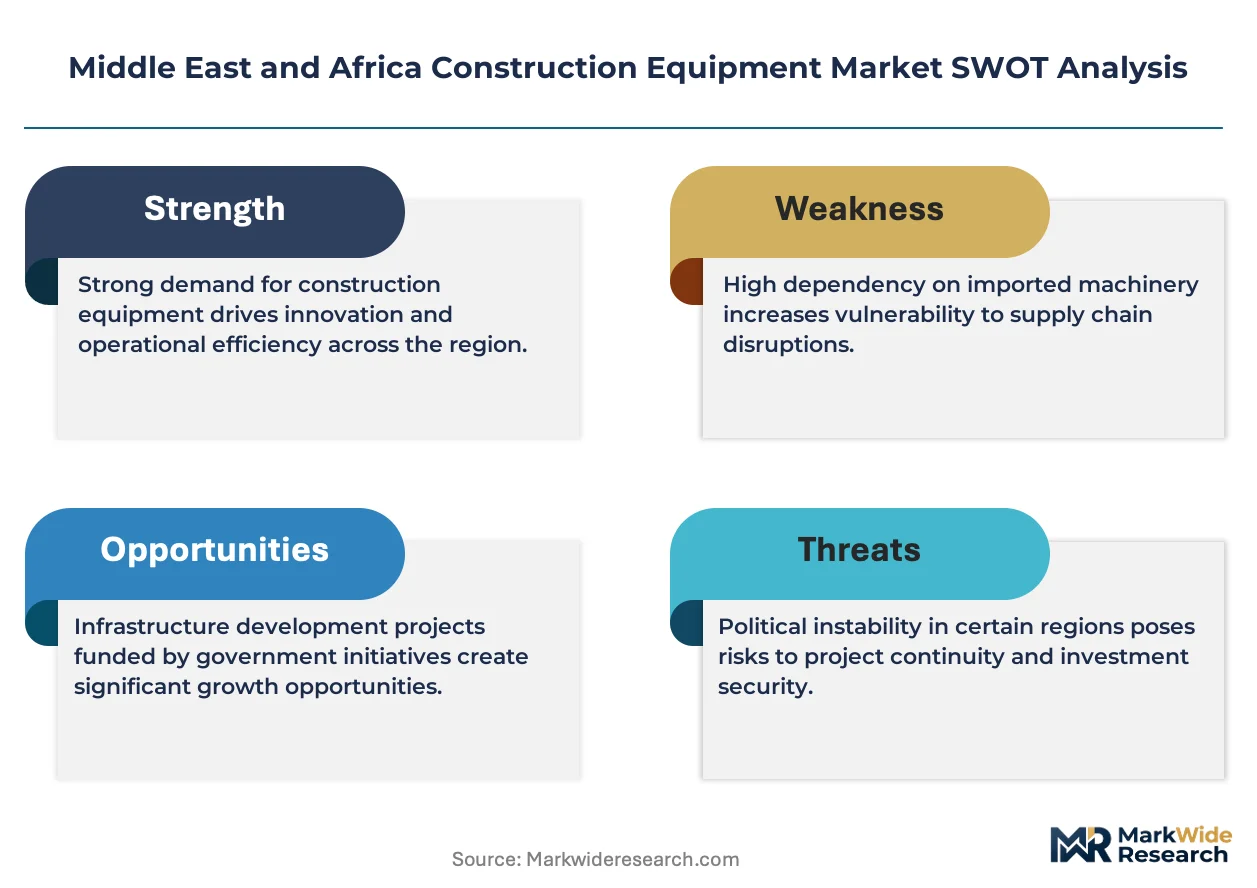
Gulf sovereign wealth fund infrastructure pipelines are compressing equipment procurement cycles while Egypt's Euro V-equivalent emissions mandates force fleet electrification decisions on contractors operating across North African ports.
Growth Catalysts
- NEOM and Al Dhafra megaprojects:Saudi Arabia's linear city and UAE's solar complex are pulling excavator and crane orders from international construction firms ahead of 2030 completion targets.
- Euro V-equivalent standards:Egypt's Ministry of Environment restrictions on diesel-only imports are accelerating hybrid technology adoption among contractors serving Mediterranean port expansions.
- Copper belt mining:Articulated hauler demand concentrates in Zambia and the Democratic Republic of Congo where benching operations require premium-tier hydraulic shovels.
Market Restraints
- Steel and semiconductor input volatility:Hydraulic system components face supply concentration from East Asian foundries, exposing African distributors to currency mismatch risks.
- Sub-Saharan rental fleet decay:Nigeria and Kenya lack secondary market liquidity for used equipment, trapping capital in depreciating assets.
- MOHAP certification bottlenecks:UAE occupational safety frameworks create testing backlogs that delay site deployment for non-distributor service networks.
Strategic Opportunities
- Ethiopian dam and logistics corridors:The Grand Ethiopian Renaissance Dam and Djibouti rail links represent underpenetrated demand for mid-size excavators outside Gulf procurement networks.
- ICT-integrated earthworks:Komatsu's machine control systems and telematics platforms enable precision grading contracts for Gulf smart-city developers seeking productivity guarantees.
- Saudi local content mandates:Vision 2030 domestic assembly requirements create joint-venture openings for component manufacturers establishing presence in Jubail industrial zones.
Industry Challenges
- Operator certification gaps:South Africa's National Regulator for Compulsory Specifications mandates rollover protective structures and visibility protocols that training institutes struggle to deliver at scale.
- Legacy fleet integration:Contractors in Morocco and Tunisia face retrofit complexity when connecting older diesel units to telematics platforms required for Dubai green building code compliance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Construction Equipment Market |
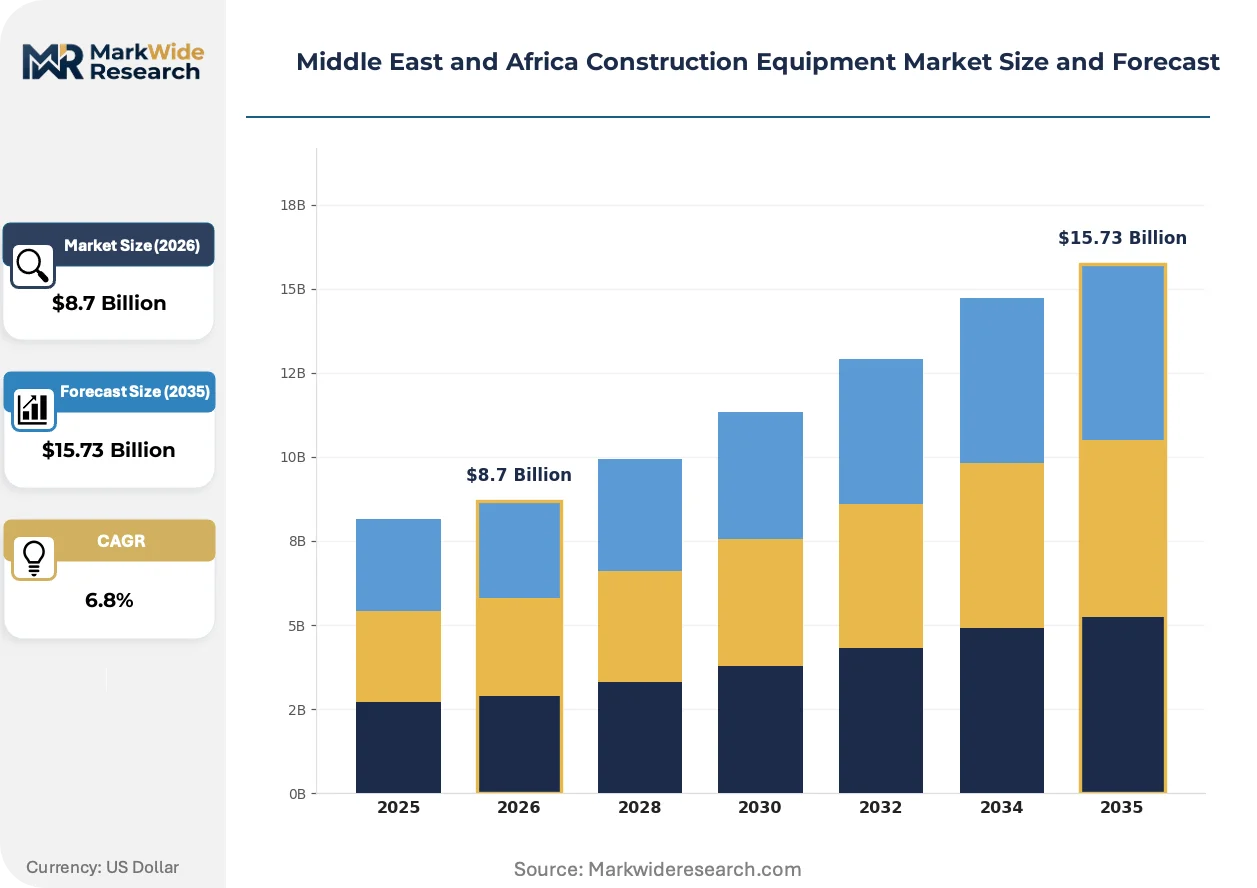
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Excavators, Loaders, Cranes, Bulldozers Application: Infrastructure, Commercial, Residential, Mining Technology: Electric, Hybrid, Diesel, Gas End User: Construction Companies, Government Agencies, Real Estate Developers, Contractors |
| Companies Covered | Liebherr Group, Hitachi Construction Machinery, Caterpillar Inc., Doosan Corporation, JCB Ltd., Komatsu Ltd., CNH Industrial, SANY Heavy Industry, Volvo AB, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Construction Equipment Market Shifts & Advancements
Electrification architectures and digital fleet management are compressing equipment lifecycle economics while reshaping contractor-distributor relationships across arid and tropical operating environments.
Battery-electric powertrains are modularizing construction equipment architectures by separating energy storage from hydraulic drive systems. Saudi smart-city developers are specifying swappable battery packs for excavators to maintain uptime during desert heat conditions. This modularity is enabling regional distributors to offer energy-as-a-service contracts rather than capital sales.
Egypt's Ministry of Environment enforcement of heavy-duty vehicle emission standards is restricting diesel-only import licenses for equipment above 75 horsepower. Contractors serving Mediterranean port expansions must now source hybrid or electric alternatives from European or Asian manufacturers with certified powertrain technology. The compliance burden concentrates procurement among established distributors with in-house testing laboratories.
After-sales service unbundling is fragmenting traditional distributor revenue models. Nigerian residential contractors are sourcing parts directly from Caterpillar's regional distribution network while using third-party mechanics for field repairs. This disintermediation is most visible in Lagos and Abuja where independent service providers undercut authorized dealer labor rates by forty percent.
Middle East and Africa Construction Equipment Market Segmentation
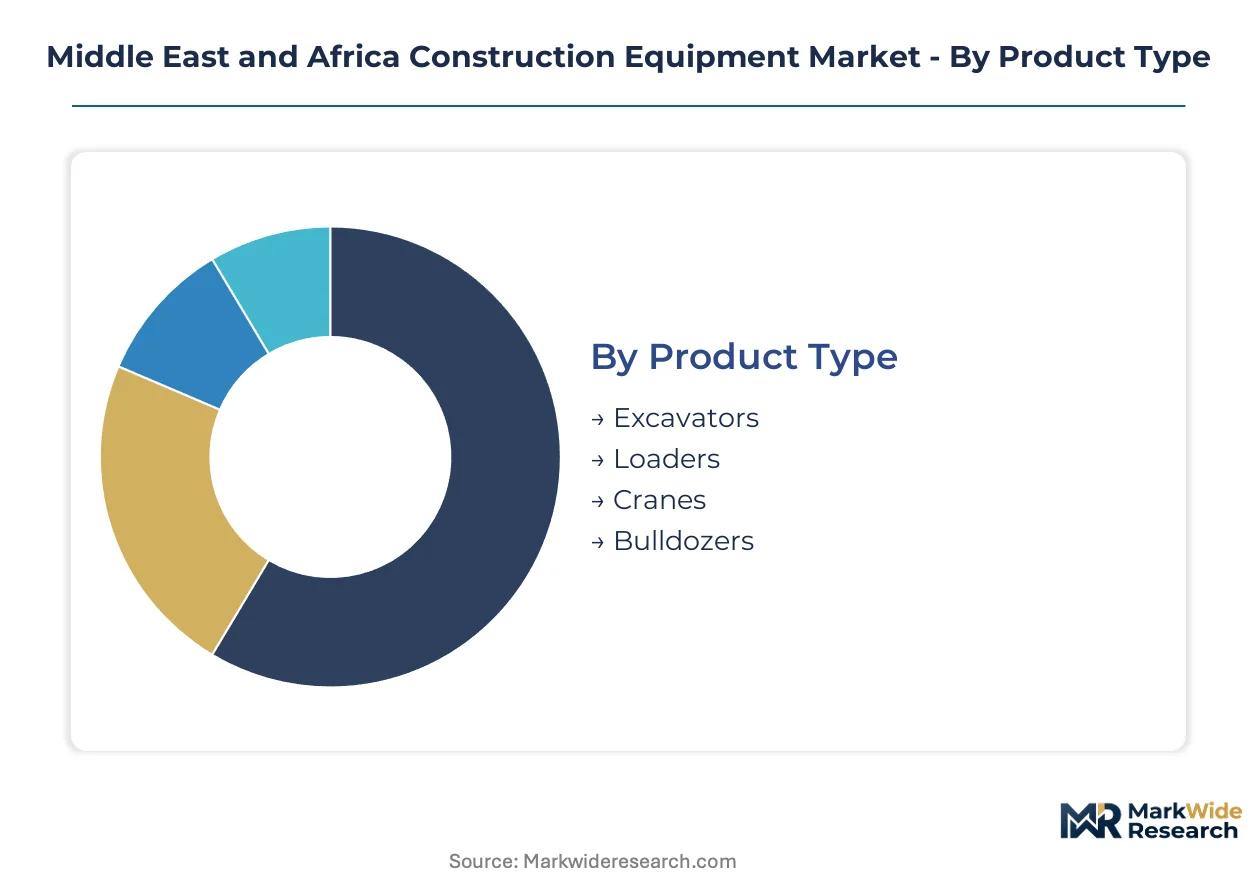
Procurement patterns across the Middle East and Africa diverge sharply between Gulf sovereign wealth fund pipelines and Sub-Saharan rental-dependent markets. Understanding how contractors prioritize versatility, compliance, and total cost of ownership across equipment categories reveals where margin pools concentrate and technology shifts accelerate.
Product Type:
Contractors weigh versatility against specialization when matching equipment to project scale and duration.
- Excavators:Hydraulic systems rated 20-50 tonnes dominate trenching, demolition, and mining benching applications across Saudi NEOM and UAE Al Dhafra sites. Demand concentrates in Gulf Cooperation Council states where linear city earthworks and port expansions require rapid cycle times and precision grading capabilities.
- Loaders:Articulated and wheel-mounted variants handle material stockpiling and site logistics in Zambia and Democratic Republic of Congo copper operations. Fleet managers prioritize breakout force and fuel efficiency for benching operations where haul road maintenance determines productivity.
- Cranes:Tower and mobile units serve vertical construction in Dubai and Riyadh high-rise clusters.
- Bulldozers:Track-type tractors clear rights-of-way for Ethiopian dam logistics corridors and Djibouti rail links.
Excavators lead on scale; hybrid-configured loaders lead on momentum.
Application:
Project funding sources dictate equipment specification tiers and technology adoption timelines.
- Infrastructure:Roads, bridges, and utilities deployment across Egypt's Mediterranean port expansions and Saudi Vision 2030 corridors. Egypt's Ministry of Environment Euro V-equivalent standards restrict diesel-only imports above 75 horsepower, forcing hybrid procurement for contractors serving government-backed projects.
- Mining:Open-pit extraction in Southern Africa's copper belt demands premium-tier articulated haulers and large-class hydraulic shovels. Bench heights and haul distances in Zambian operations favor equipment with reinforced undercarriages and extended warranty coverage.
- Commercial:Office and retail developments in Lagos and Abuja drive mid-scale excavator demand.
- Residential:Urban densification in Nigeria and Kenya concentrates compact equipment needs for confined site access.
Infrastructure leads on scale; mining leads on momentum.
Technology:
Regulatory enforcement and operating cost structures determine powertrain selection across climates from arid Gulf conditions to tropical West African rainfall zones.
- Hybrid:Diesel-electric architectures separate energy storage from hydraulic drive systems, enabling swappable battery configurations for Saudi smart-city developers. Dubai's mandatory green building codes filter down to contractor fleet specifications, accelerating adoption where uptime guarantees during desert heat conditions are non-negotiable.
- Electric:Battery-electric powertrains with modular energy packs are gaining traction in UAE urban construction zones where emissions restrictions and noise ordinances intersect. Regional distributors are piloting energy-as-a-service contracts rather than capital sales for municipal projects.
- Diesel:Conventional powertrains retain dominance in Sub-Saharan rental fleets where secondary market liquidity constraints trap capital in depreciating assets.
- Gas:Compressed natural gas alternatives serve select Nigerian and Algerian operations with proximity to domestic fuel infrastructure.
Diesel leads on scale; hybrid leads on momentum.
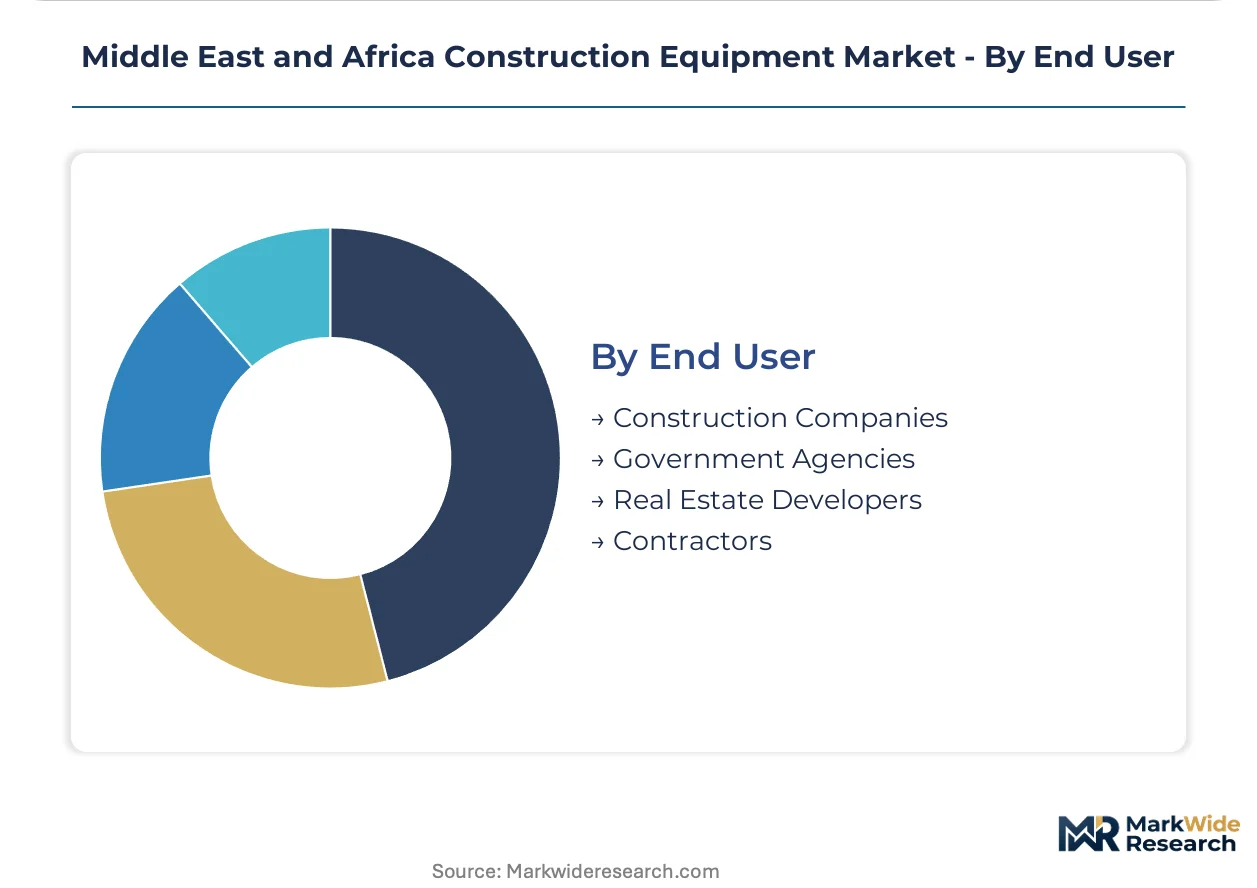
End User:
Balance sheet capacity and project pipeline visibility shape procurement modality and service expectations.
- Construction Companies:International firms operating across Saudi Arabia and UAE megaprojects leverage fleet standardization to minimize training and parts inventory costs. These entities specify integrated ICT construction solutions for precision earthworks where productivity guarantees determine contract awards.
- Government Agencies:State-backed infrastructure authorities in Egypt and Gulf Cooperation Council states mandate emissions compliance and local content requirements that favor established distributors with in-house testing laboratories.
- Real Estate Developers:Private developers in Lagos and Nairobi prioritize total cost of ownership calculations for mid-scale residential projects.
- Contractors:Sub-Saharan rental-dependent operators face working capital constraints that limit technology upgrades and extend legacy fleet utilization.
Construction companies lead on scale; government agencies lead on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized equipment operators and maintenance technicians concentrate in Gulf Cooperation Council urban corridors, anchoring regional deployment capacity for megaproject construction and mining operations across diverse climate zones.
Saudi Arabia
NEOM's linear city and Red Sea coastal developments are pulling excavator and crane orders from international construction firms. The Saudi Standards, Metrology and Quality Organization enforces local content requirements that increasingly specify assembly within Jubail industrial zones. Riyadh's high-rise cluster concentrates tower crane deployment for vertical construction timelines.
United Arab Emirates
Al Dhafra solar complex and Dubai smart-city earthworks are accelerating hybrid equipment procurement cycles. MOHAP-aligned occupational safety frameworks create certification bottlenecks that favor established distributors with in-house testing laboratories. Abu Dhabi's procurement networks dominate premium-tier articulated hauler specifications for desert operating conditions.
Egypt
Mediterranean port expansions and Suez Canal logistics corridors are driving mid-size excavator demand among contractors serving government-backed infrastructure. The Ministry of Environment enforces Euro V-equivalent emissions standards that restrict diesel-only imports above 75 horsepower, forcing hybrid technology adoption. Cairo-Alexandria construction clusters concentrate fleet electrification decisions for contractors with European export exposure.
South Africa
Platinum and gold mining operations in the Bushveld Complex sustain demand for large-class hydraulic shovels and premium-tier haulers. The National Regulator for Compulsory Specifications mandates rollover protective structures and operator visibility protocols that training institutes struggle to deliver at scale. Johannesburg-Pretoria industrial corridors concentrate distributor service networks for mining fleet uptime guarantees.
Nigeria
Lagos and Abuja residential densification is driving compact equipment needs for confined site access among mid-scale contractors. Secondary market liquidity constraints trap capital in depreciating rental fleet assets, limiting technology upgrade cycles. Independent service providers in Lagos undercut authorized dealer labor rates, fragmenting after-sales revenue models.
Middle East and Africa Construction Equipment Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across equipment architecture decisions, creating tiered competitive dynamics. The vendor base concentrates around integrated full-line manufacturers, regional assembly specialists, and component technology licensors. Three archetypes dominate: Gulf-focused smart-city solution providers, mining-centric premium-tier suppliers, and cost-optimized mid-market fabricators. M&A activity targets ICT construction technology capabilities, while strategic partnerships secure battery-electric powertrain supply for emissions-compliant fleets.
Among Japanese-headquartered full-line manufacturers, Komatsu Ltd. and Hitachi Construction Machinery occupy positions exemplifying integrated machine control and telematics platforms. Liebherr Group represents the European premium-tier archetype for large-class mining and lifting equipment. These three anchors illustrate how competitive positioning separates on precision earthworks productivity guarantees versus raw lifting capacity specifications.
| Leading Market Players |
|---|
| Liebherr Group |
| Hitachi Construction Machinery |
| Caterpillar Inc. |
| Doosan Corporation |
| JCB Ltd. |
| Komatsu Ltd. |
| CNH Industrial |
| SANY Heavy Industry |
| Volvo AB |
| Others |
Supply & Pricing Matrix
Gulf sovereign wealth fund procurement clusters anchor pricing power for premium-tier equipment, compressing negotiation cycles through consolidated megaproject tenders that favor full-line manufacturers with integrated service networks.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments the market by certification grade and after-sales bundling intensity. Premium tiers capture Euro V-equivalent compliance costs and ICT-integrated telematics, while economy tiers serve Sub-Saharan rental fleets with stripped specifications. Cost compression in mid-scale excavator categories is intensifying because Nigerian contractors source parts directly from regional distribution networks, bypassing authorized dealer markups. Government agencies exhibit lowest price sensitivity due to local content mandates, whereas independent Sub-Saharan contractors face working capital constraints that extend legacy fleet utilization.
Supply Chain Analysis
Authorized distributor networks with in-house testing laboratories handle compliance-intensive Gulf demand, while fragmented independent service providers capture Nigerian residential repair work. Hydraulic system components draw from East Asian foundries in China, South Korea, and Japan, exposing African distributors to currency mismatch risks. Steel and semiconductor input volatility rests on single-source vulnerability for precision electronic control modules. Distribution runs through established OEM dealer networks in Saudi Arabia and UAE, with direct-to-contractor parts sales accelerating in Lagos and Abuja.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Middle East and Africa construction equipment market represents a late-cycle quality story where Egyptian emissions enforcement and Saudi local content mandates are filtering procurement toward premium-tier hybrid configurations with integrated ICT platforms.
For Market Incumbents: To counter direct parts sourcing by Nigerian contractors, deepen captive supply of critical hydraulic components through backward integration into Jubail industrial zone assembly partnerships. Channel control represents the essential lever: expand in-house testing laboratory capacity to capture MOHAP certification bottlenecks that delay competitor deployment timelines. For New Entrants and Emerging Players: Independent service providers in Lagos and Abuja offer the most penetrable channel entry point for mid-scale residential contractors seeking forty percent labor rate savings against authorized dealers. Ethiopian dam logistics corridors and Djibouti rail links present underpenetrated white-space demand for mid-size excavators outside established Gulf procurement networks. A component manufacturing joint-venture strategy aligned with Saudi Vision 2030 domestic assembly requirements secures preferential access to sovereign wealth fund pipelines. For Investors and Strategic Acquirers: Construction technology specialists with machine control and telematics capabilities are the most active acquirer targets in this space, as Komatsu's integrated ICT construction solutions demonstrate. Long-term viability hinges on electrification architecture IP and battery-electric powertrain supply agreements. The signal to watch is Dubai green building code enforcement velocity, which determines hybrid fleet specification timelines across contractor tiers.| Strategic Initiative | Industry Significance |
|---|---|
| Local Content Joint Venture | Saudi assembly requirements in Jubail industrial zones secure sovereign wealth fund access. |
| Battery-Electric Powertrain Licensing | Swappable battery architectures address desert heat uptime guarantees for NEOM developers. |
| ICT Construction Platform Integration | Precision grading telematics capture smart-city earthwork contracts in Dubai and Riyadh. |
| Independent Service Network Expansion | Third-party repair capacity undercuts authorized dealer rates in Lagos residential clusters. |
| In-House Testing Laboratory Investment | MOHAP certification capabilities compress deployment timelines for UAE megaproject tenders. |
Research Methodology
Direct dialogue with fleet managers at Gulf construction companies, procurement officers at Zambian copper operations, aftermarket service heads in Nigerian distributor networks, and regulatory compliance leads at Egypt's Ministry of Environment grounded qualitative assessments. Secondary validation drew from customs trade data for equipment imports, SEC filings of listed manufacturers, Saudi Vision 2030 project disclosure databases, and EU Green Deal extraterritorial compliance documentation. Bottom-up equipment shipment analysis and top-down infrastructure spending projections were triangulated to cross-verify market sizing.
Segmentation outputs across product type, application, technology, and end user were modeled over the projection horizon, with powertrain transition timelines calibrated to Egyptian emissions enforcement phases and Dubai green building code adoption curves. CAGRs were derived from equipment replacement cycle analysis and megaproject procurement pipeline visibility. Copper belt mining activity and Mediterranean port expansion capex served as demand-side anchors for forecast sensitivity testing.
Revisions become necessary when Gulf sovereign wealth fund project cancellations, semiconductor supply disruptions, or Sub-Saharan currency devaluations materialize beyond modeled scenarios. Forecasts reflect assumptions regarding emissions standard harmonization timelines and local content mandate enforcement intensity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Global Wheel Trenchers Market
Construction Equipment
Cement Consistometer Market
Construction Equipment
Saudi Arabia Construction Equipment Market
Construction Equipment
Autonomous Construction Equipment Market
Construction Equipment
Vertical Mill Market
Construction Equipment
Sandblasting Machines Market
Construction Equipment
Skid Steer Loader Market
Construction Equipment
Down-The-Hole (DTH) Hammer Bits Market
Construction Equipment
Global Portable Light Towers Market
Construction Equipment
Industrial Hydraulic Equipment Market
Construction Equipment
Pile Cage Welding Machine Market
Construction Equipment
Earthmoving Equipment Tyres Market
Construction Equipment
Shotcrete Sprayer Market
Construction Equipment
Earthing Equipment Market
Construction Equipment
Compact Loaders Market
Construction Equipment
GCC Mini Cranes Market