
 GCC Advanced Buildings Materials Market | 2026-2036
GCC Advanced Buildings Materials Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Advanced Buildings Materials Market Insights
Modular panel bundling is recalibrating procurement patterns across GCC construction supply chains. Saint Gobain Group leverages its integrated glass and insulation portfolio to anchor specification in high-performance envelope packages. Kingspan Group competes through prefabricated insulated panel systems that reduce on-site labor exposure in extreme Gulf climates. CEMEX sustains its position by extending specialty concrete and lightweight aggregate capabilities into structural component supply.
Advanced building materials encompass engineered products with specified thermal conductivity below 0.035 W/m·K, compressive strength exceeding 20 MPa, or integrated smart-monitoring functionality, manufactured through extrusion, vacuum forming, or additive deposition to deliver energy efficiency, structural optimization, or environmental compliance in built environments. Prefabrication technology leads segment momentum as Gulf contractors adopt factory-built volumetric modules to compress project schedules amid labor scarcity. Facade systems concentrate margin pools where specification-driven architects in Dubai and Riyadh prioritize U-value performance over first-cost comparisons. Smart materials represent the fastest-growing technology category, though from a smaller installed base, as developers embed sensing capabilities for predictive maintenance in premium commercial assets.
Saudi Building Code and Abu Dhabi International Building Code shape product certification requirements, while Dubai Municipality's Green Building Regulations mandate material disclosure for embodied carbon tracking. The UAE's MOHAP and Saudi Standards, Metrology and Quality Organization enforce conformity assessment protocols that filter non-compliant imports from Asian supply sources. Stakeholders must monitor evolving mandatory energy labeling timelines and pre-qualification changes for giga-project material suppliers.
Market Dynamics
Mega-project construction in Saudi Arabia's NEOM and Qiddiya developments is compressing procurement cycles and forcing specification of high-performance envelope systems that exceed baseline thermal standards.
Growth Catalysts
- Saudi Building Code thermal mandates:Enhanced U-value requirements for commercial facades are disqualifying conventional cladding from giga-project tenders.
- Qiddiya entertainment district construction:Developers specify vacuum-insulated panels and smart-monitoring facades to meet aggressive sustainability certifications.
- Modular prefabrication adoption:Factory-built volumetric modules reduce on-site labor exposure in extreme Gulf climates while compressing project schedules.
Market Restraints
- Specialty polymer feedstock volatility:Polyisocyanurate and phenolic resin prices fluctuate with global petrochemical supply, squeezing margin on insulated panel systems.
- Asian import concentration:Non-compliant material flows from unvetted overseas suppliers strain Saudi Standards, Metrology and Quality Organization enforcement capacity.
- Embodied carbon disclosure gaps:Dubai Municipality's Green Building Regulations lack standardized measurement protocols, creating certification friction for suppliers.
Strategic Opportunities
- Kuwait residential retrofit pipeline:Aging building stock and new energy efficiency targets create demand for lightweight facade overcladding systems.
- Integrated sensing-convergence:Embedding IoT monitoring within structural insulated panels enables predictive maintenance contracts in premium commercial assets.
- Direct-to-developer digital channels:Procurement platforms bypass traditional distributor layers, allowing manufacturers to capture specification data earlier in design phases.
Industry Challenges
- Façade engineering talent scarcity:Gulf contractors face shortages of specialists capable of integrating high-performance envelope design with local climatic load calculations.
- Multi-certification timeline compression:Suppliers must navigate concurrent Saudi Building Code, Abu Dhabi International Building Code, and project-specific giga-project pre-qualification reviews.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Advanced Buildings Materials Market |
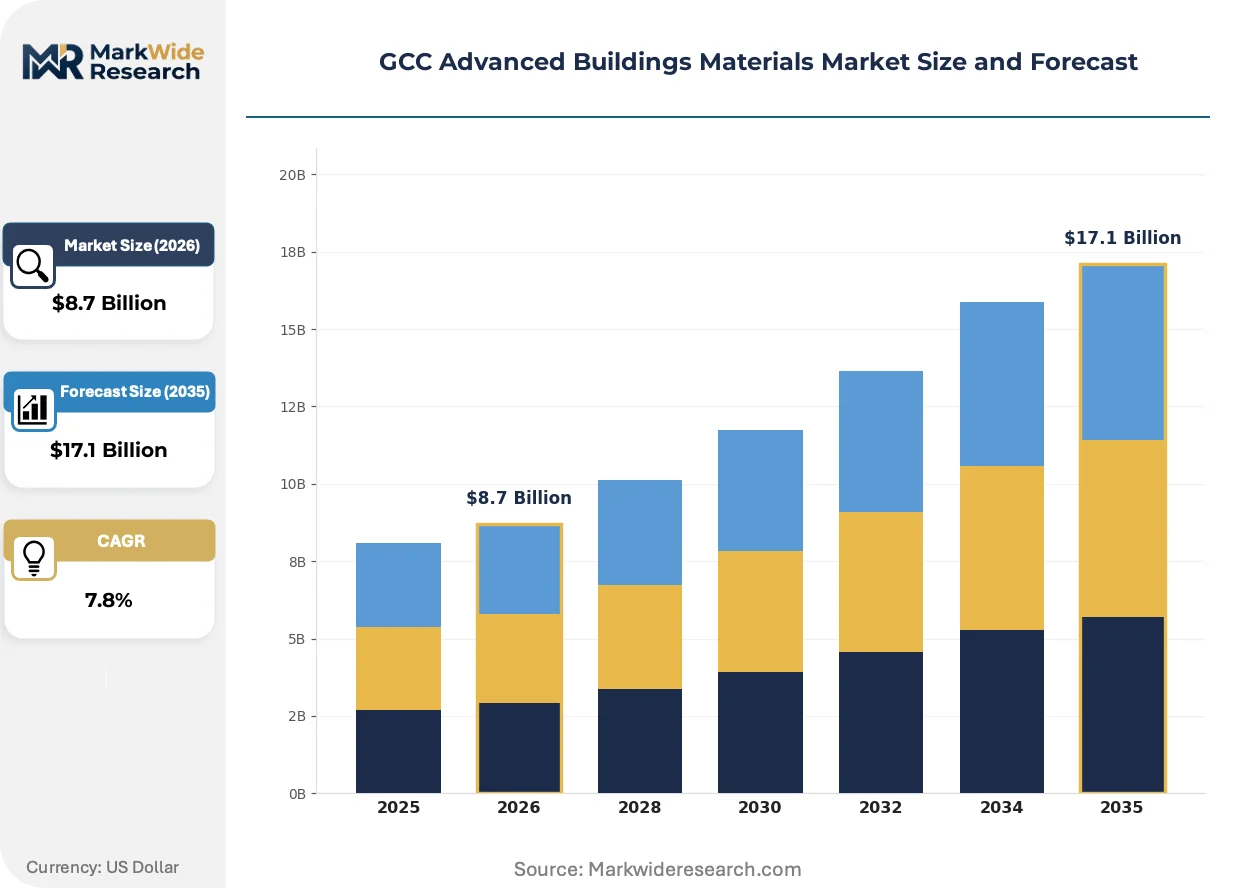
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $17.1 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Insulation Materials, Structural Components, Facade Systems, Flooring Solutions Application: Commercial Buildings, Residential Projects, Industrial Facilities, Infrastructure Developments Technology: 3D Printing, Prefabrication, Smart Materials, Eco-Friendly Technologies End User: Contractors, Architects, Builders, Property Developers |
| Companies Covered | Saint Gobain Group, Kingspan Group, PPG Industries LLC, CEMEX, Knauf Gips, Sherwin Williams Company, 3M Co., Daikin Industries Ltd, Huntsman International LLC, Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Advanced Buildings Materials Market Trends and Innovations
Specification architects in Dubai and Riyadh are prioritizing thermal performance metrics over first-cost comparisons, reshaping competitive positioning around U-value guarantees and embodied carbon transparency.
Aerogel-enhanced insulation is absorbing specification share in curtain wall applications where space constraints prohibit conventional thick-panel solutions. Premium commercial developers in Abu Dhabi specify these materials for their sub-0.020 W/m·K thermal conductivity. The technology is absorbing margin pools that previously accrued to standard mineral wool suppliers.
Abu Dhabi International Building Code amendments now mandate pre-construction thermal bridging analysis for envelope assemblies above 50 meters height. This requirement forces design-phase collaboration between facade consultants and material suppliers that previously operated in sequential handoffs. High-rise residential towers in Al Reem Island represent the most affected segment, with developers accelerating specialist consultant procurement.
Developer procurement teams are consolidating vendor relationships around envelope-package suppliers capable of warranting integrated thermal and structural performance. Single-source accountability replaces fragmented subcontractor bidding for cladding, insulation, and air barrier scopes. This concentration is most visible in Saudi Arabia's giga-project pipeline, where developers pre-qualify panel system providers before schematic design completion.
GCC Advanced Buildings Materials Market Segmentation
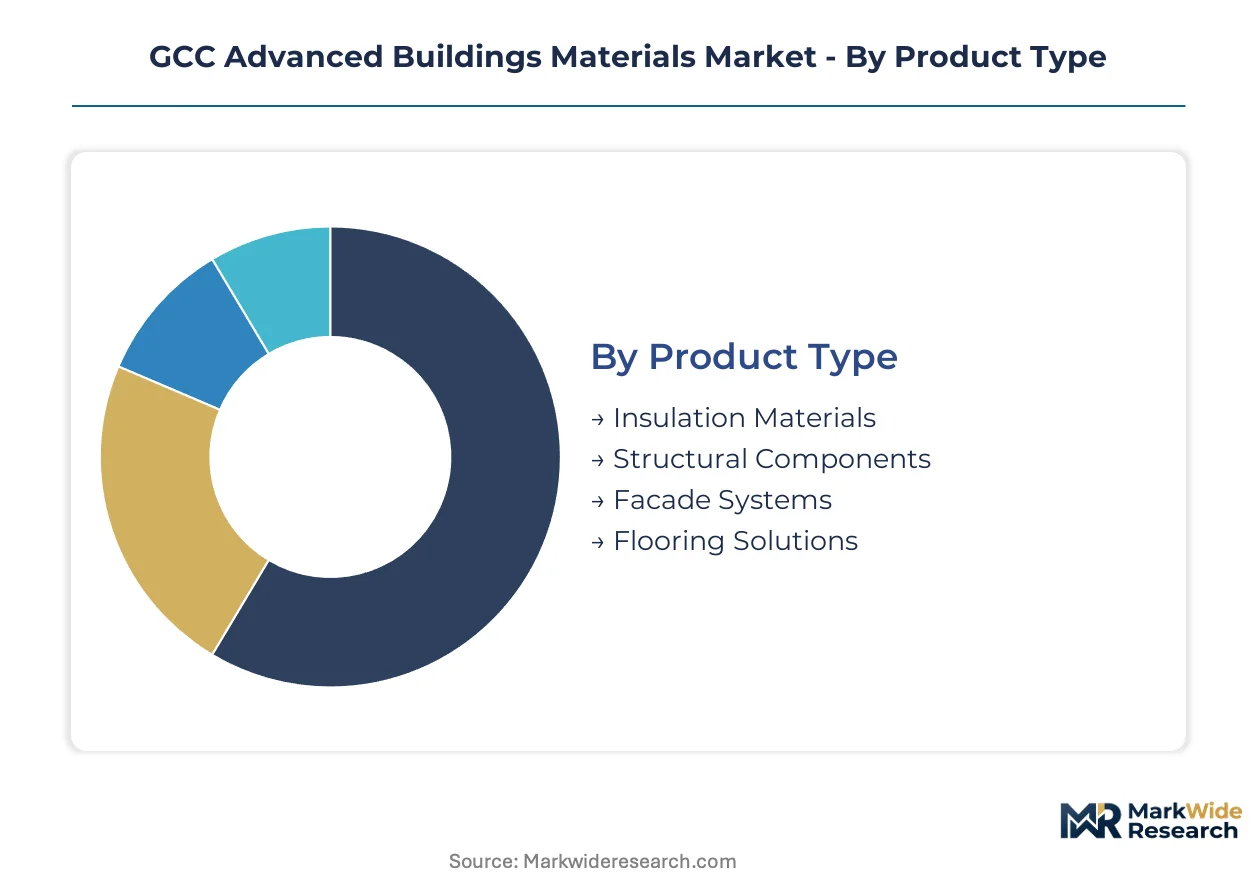
Segmentation in GCC advanced building materials reveals how certification requirements and project scale reshape procurement priorities. Saudi Building Code thermal mandates and Abu Dhabi International Building Code amendments filter supplier eligibility differently across product categories and end-use applications.
Product Type:
Saudi Standards, Metrology and Quality Organization conformity assessment and Dubai Municipality Green Building Regulations apply varying stringency to thermal performance claims by material category.
- Insulation Materials:Vacuum-insulated panels and aerogel-enhanced systems achieve sub-0.020 W/m·K thermal conductivity for curtain wall applications where space constraints prohibit thick-panel solutions. Demand concentrates in NEOM and Qiddiya giga-projects where developers specify these materials to meet aggressive sustainability certifications amid compressed procurement cycles.
- Facade Systems:Integrated envelope packages combine cladding, insulation, and air barrier functions under single-source warranty. Dubai and Riyadh specification architects prioritize U-value guarantees over first-cost comparisons, concentrating procurement around suppliers capable of warranting integrated thermal and structural performance.
- Structural Components:Lightweight aggregate concrete and specialty mixes deliver compressive strength exceeding 20 MPa for modular volumetric construction.
- Flooring Solutions:Engineered systems with embedded sensing capabilities serve predictive maintenance contracts in premium commercial assets.
Leading the category by volume: Facade Systems. Growing fastest: Insulation Materials.
Application:
Project scale and regulatory exposure segment demand by construction type, with mega-developments facing distinct pre-qualification timelines.
- Commercial Buildings:High-rise towers above 50 meters height in Abu Dhabi now require pre-construction thermal bridging analysis under amended building code provisions. Al Reem Island residential-commercial mixed towers represent the most affected segment, with developers accelerating specialist facade consultant procurement to comply.
- Infrastructure Developments:NEOM linear city and Qiddiya entertainment district construction compress schedules and force specification of high-performance envelope systems exceeding baseline thermal standards. These projects disqualify conventional materials through giga-project tender pre-qualification gates.
- Residential Projects:Kuwait aging building stock and new energy efficiency targets create retrofit demand for lightweight facade overcladding.
- Industrial Facilities:Factory-built volumetric modules reduce on-site labor exposure in extreme Gulf climates while meeting aggressive project timelines.
Highest certification burden: Infrastructure Developments. Steepest expansion trajectory: Commercial Buildings.
Technology:
Manufacturing method determines which conformity assessment protocols apply, with additive deposition and smart functionality triggering additional disclosure requirements.
- Prefabrication:Factory-built volumetric modules integrate structural, envelope, and MEP systems off-site for delivery to Saudi giga-project sites. This technology compresses project schedules amid regional labor scarcity while reducing on-site exposure to extreme Gulf climates.
- Smart Materials:Structural insulated panels with embedded IoT monitoring enable predictive maintenance contracts in premium commercial assets across Dubai and Abu Dhabi. These systems represent the technology category gaining share fastest from a smaller installed base.
- 3D Printing:Additive deposition of cementitious and polymer composites for complex geometric components.
- Eco-Friendly Technologies:Low-carbon binders and recycled aggregate systems face embodied carbon disclosure gaps under Dubai Municipality regulations.
Widest adoption: Prefabrication. Climbing the fastest: Smart Materials.
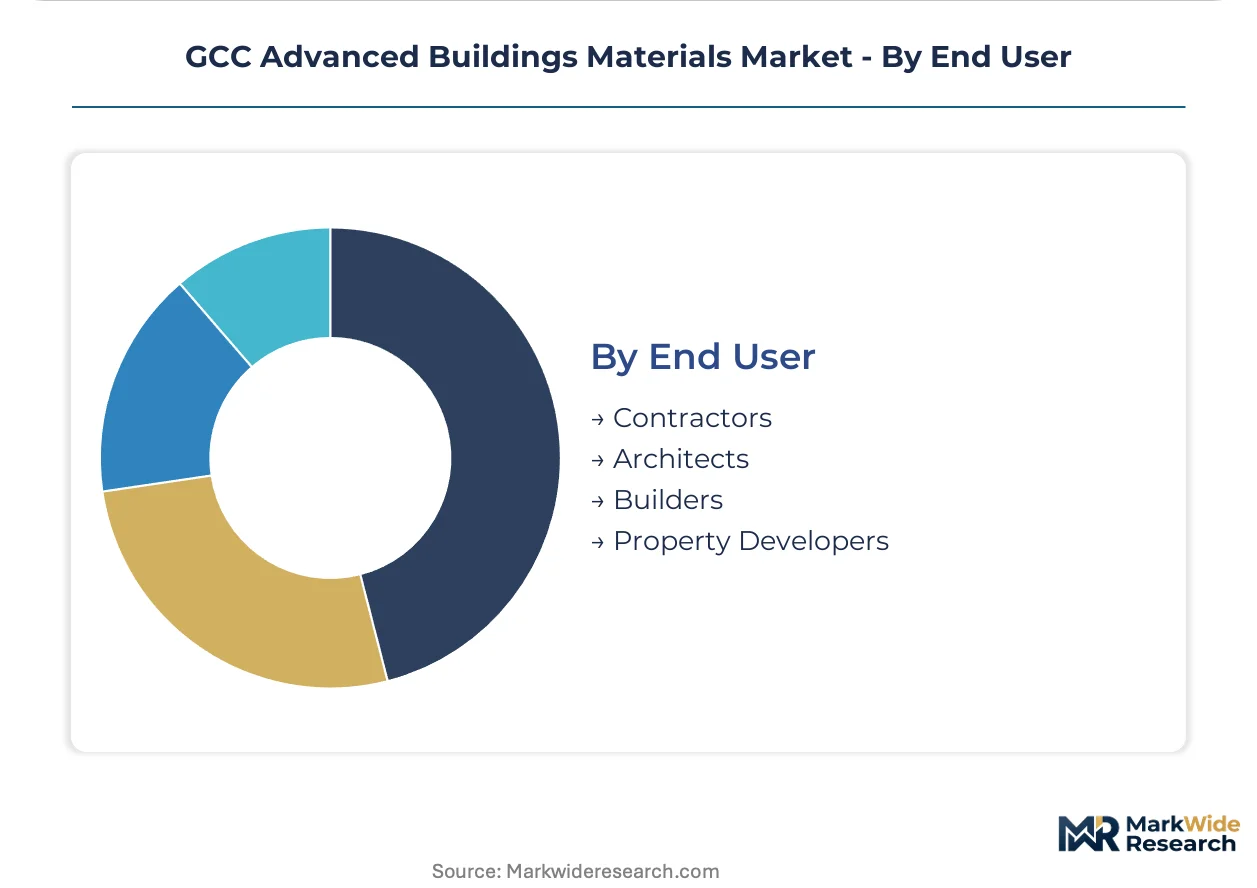
End User:
Procurement authority and design-phase influence segment stakeholders by their position in specification timing.
- Property Developers:Saudi giga-project developers pre-qualify panel system providers before schematic design completion, consolidating vendor relationships around envelope-package suppliers. Direct-to-developer digital procurement platforms bypass traditional distributor layers, capturing specification data earlier.
- Architects:Dubai and Riyadh specification architects prioritize thermal performance metrics and embodied carbon transparency over first-cost comparisons. These professionals drive demand for U-value guarantees and material disclosure documentation.
- Contractors:Gulf contractors face shortages of facade engineering specialists capable of integrating high-performance envelope design with local climatic load calculations.
- Builders:On-site assembly crews for prefabricated modules require reduced labor exposure in extreme climates.
Greatest procurement consolidation: Property Developers. Fastest-growing influence: Architects.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
NEOM and Qiddiya special economic zones concentrate procurement authority for high-performance envelope systems, compressing supplier qualification timelines and reshaping material flows across the Gulf.
Saudi Arabia
NEOM linear city and Qiddiya entertainment district construction drives specification of vacuum-insulated panels and smart-monitoring facades. Saudi Building Code thermal mandates disqualify conventional cladding from giga-project tenders. Riyadh and the Eastern Province anchor fabrication capacity for modular volumetric systems serving these developments.
United Arab Emirates
Abu Dhabi International Building Code amendments mandate pre-construction thermal bridging analysis for towers above 50 meters. Dubai Municipality Green Building Regulations enforce material disclosure for embodied carbon tracking. Al Reem Island and Dubai Marina clusters accelerate specialist facade consultant procurement to comply with amended provisions.
Kuwait
Aging residential building stock and new energy efficiency targets generate retrofit demand for lightweight facade overcladding systems. The country's national building regulator enforces updated thermal performance standards for commercial renovations. Kuwait City concentrates specification activity for envelope upgrade projects.
Qatar
Post-World Cup infrastructure repurposing creates demand for adaptive reuse of sports and hospitality assets. The national standards body mandates conformity assessment for imported high-performance insulation. Doha and Lusail City drive procurement of integrated envelope packages for commercial conversion projects.
GCC Advanced Buildings Materials Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across the GCC advanced building materials landscape. The market exhibits tiered concentration where envelope-package suppliers capture premium procurement relationships through single-source warranty capabilities. Three archetypes dominate: integrated material-science conglomerates, prefabricated system specialists, and regional distribution platforms. Competitive dynamics center on backward integration into polymer feedstocks and strategic partnerships with giga-project developers to secure pre-qualification status.
Within the integrated conglomerate tier, Saint Gobain Group and CEMEX exemplify diversified players leveraging cross-product portfolios to anchor specification in high-performance envelope packages. Kingspan Group occupies a position among prefabricated system specialists competing through factory-built volumetric modules. These three companies represent distinct strategic postures—materials integration, manufacturing scale, and modular delivery—that define competitive positioning across Saudi giga-projects and UAE high-rise developments.
| Leading Market Players |
|---|
| Saint Gobain Group |
| Kingspan Group |
| PPG Industries LLC |
| CEMEX |
| Knauf Gips |
| Sherwin Williams Company |
| 3M Co. |
| Daikin Industries Ltd |
| Huntsman International LLC |
| Others |
Pricing and Supply Chain Analysis
Giga-project developers in Saudi Arabia consolidating procurement around pre-qualified envelope-package suppliers are forcing specialty polymer feedstock producers to secure long-term offtake agreements, compressing margin pools for non-integrated panel system providers.
Pricing Analysis
Short-lead-time premiums for vacuum-insulated panels and aerogel-enhanced systems command substantial markups over standard mineral wool alternatives in NEOM and Qiddiya tenders. Project-based contract pricing stratifies across performance tiers, with U-value guarantees below 0.020 W/m·K attracting premium positioning while conventional insulated panels face cost compression from Asian import competition. Price differentiation hinges on Saudi Standards, Metrology and Quality Organization certification status and embodied carbon disclosure completeness. Contractors represent the most price-sensitive buyer segment, prioritizing first-cost comparisons, whereas specification architects in Dubai demonstrate lowest sensitivity, emphasizing thermal performance metrics.
Supply Chain Analysis
Pre-qualification gating under Saudi Building Code and Abu Dhabi International Building Code amendments filters supplier eligibility before tender participation, concentrating approved vendor lists around integrated material-science conglomerates. Manufacturing capacity clusters in Saudi Arabia, the United Arab Emirates, and Germany supply high-performance envelope systems to Gulf markets. Raw material dependencies rest on polyisocyanurate resins, phenolic precursors, and specialty glass fiber reinforcements. Single-source vulnerability in vacuum-insulated panel core production presents structural risk amid geopolitical feedstock disruptions. Distribution runs through project-specific direct procurement channels and specialist facade consultant networks rather than traditional distributor layers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialist facade engineering talent scarcity across the Gulf is constraining installation capacity for high-performance envelope systems, propping pricing power for qualified panel system providers through the analysis window.
For Market Incumbents: Cement specification relationships with Saudi giga-project developers before schematic design completion to lock out modular prefabrication competitors. Secure backward integration into polyisocyanurate feedstocks to defend margin position against petrochemical price volatility. Prioritize investment in Saudi Standards, Metrology and Quality Organization pre-qualification status as the primary competitive moat against Asian import challengers. For New Entrants and Emerging Players: Launch via direct-to-developer digital procurement platforms to bypass entrenched distributor relationships and capture specification data earlier in design phases. Target Kuwait's residential retrofit pipeline for lightweight facade overcladding systems, the most penetrable geography given aging building stock and new energy efficiency mandates. Pursue integrated sensing-convergence partnerships with premium commercial developers in Dubai and Abu Dhabi as the optimal go-to-market angle. For Investors and Strategic Acquirers: The window for entry favors envelope-package specialists with single-source warranty capabilities and established giga-project pre-qualification status. Acquisition targets should demonstrate proven thermal bridging analysis integration with facade engineering services. Monitor Saudi Building Code amendment timelines for mandatory energy labeling as the critical inflection signal warranting portfolio rebalancing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Feedstocks | Captive resin supply insulates margin from petrochemical volatility affecting Kingspan and Saint Gobain competitors. |
| Giga-Project Pre-Qualification Investment | Saudi Standards certification unlocks NEOM and Qiddiya tender participation before design completion. |
| Direct-to-Developer Digital Channel Launch | Procurement platforms capture specification data earlier, displacing traditional distributor intermediaries. |
| Integrated Sensing-Convergence Partnership | IoT-enabled structural insulated panels enable predictive maintenance contracts in Dubai premium assets. |
| Facade Engineering Talent Acquisition | Specialist consultant capacity addresses Gulf contractor shortages for high-performance envelope integration. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with facade engineering consultants, giga-project procurement directors, panel system manufacturing executives, and Saudi Standards conformity assessment officers. Secondary sources included Dubai Municipality Green Building Regulations disclosure databases, Abu Dhabi International Building Code amendment trackers, and GCC customs import manifests for high-performance insulation categories. Bottom-up project pipeline enumeration triangulated against top-down construction spend forecasts to validate market sizing.
Data-stream reconciliation across material shipment volumes, tender award values, and certification registration counts informed the analytical framework. Segmentation modeling incorporated product type, application scale, manufacturing technology, and end-user procurement authority dimensions across the projection horizon. CAGRs derived from regression analysis of historical specification penetration rates and announced giga-project construction timelines. Industry-specific inputs included thermal conductivity performance tier adoption curves and embodied carbon disclosure compliance trajectories.
Feedstock price volatility, regulatory pre-qualification timeline shifts, and giga-project construction schedule accelerations are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions regarding Saudi Building Code enforcement intensity and Dubai Municipality disclosure protocol finalization. A model refresh is warranted upon material change in giga-project procurement consolidation patterns or Saudi Standards conformity assessment capacity expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Construction
Mezzanine Floor Market
Building Construction
France Prefab Wood Building Market
Building Construction
Australia Construction Market
Building Construction
Early Production Facility Market
Building Construction
Prefabricated Buildings Market
Building Construction
US Modular Construction Market
Building Construction
Saudi Arabia Prefabricated Buildings Market
Building Construction
Swiss Prefabricated Buildings Market
Building Construction
Qatar Construction Market
Building Construction
Malaysia Construction Market
Building Construction
Japan Construction Market
Building Construction
Russia Prefabricated Buildings Market
Building Construction
North America Modular Construction Market
Building Construction
Japan Commercial Construction Market
Building Construction
Spain Prefabricated Buildings Market
Building Construction
India Prefabricated Buildings Market