
 Hydraulic Packers Market | 2026-2036
Hydraulic Packers Market Size, Share, and Industry Trends Forecast 2026-2036
Hydraulic Packers Market Intelligence
Multi-source procurement for high-pressure sealing assemblies is shifting toward vertically integrated domestic suppliers across North American shale plays. Schlumberger leverages in-house metallurgy capabilities to control elastomer compound supply for sour-service packers. Halliburton anchors its position through captive manufacturing of expandable sealing elements in Houston. Baker Hughes differentiates via proprietary slip-system designs that reduce trip time in extended-reach laterals.
Hydraulic packers are downhole mechanical devices that use applied fluid pressure to expand elastomeric or metallic sealing elements against casing walls, typically rated for differential pressures exceeding 10,000 psi and temperatures above 350°F, to isolate zones within wellbores during completion, stimulation, or production operations. Permanent packers retain dominant placement in deepwater and high-pressure high-temperature applications where mechanical reliability overrides retrievability concerns. Retrievable packers represent the fastest-growing product category as operators prioritize plug-and-perf flexibility in unconventional horizontal wells. Among end users, service providers command disproportionate purchasing volume due to their role as intermediaries between tool manufacturers and independent operators.
API 11D1 and ISO 14310 govern validation testing for packer sealing integrity and mechanical hold under simulated downhole conditions, while EPA methane emissions rules indirectly tighten requirements for zonal isolation that prevents fugitive gas migration. OSHA and BSEE enforcement of wellbore barrier standards shapes operator specifications for redundant packer configurations in critical sour-gas environments. Stakeholders must monitor how evolving EPA greenhouse gas reporting obligations for abandoned well integrity reshape demand for permanent versus retrievable isolation strategies.
Market Dynamics
Multi-stage completion intensity in unconventional shale basins is compressing replacement cycles for downhole isolation equipment, while API 11D1 and ISO 14310 certification requirements reshape supplier qualification thresholds across North American upstream operations.
Growth Catalysts
- Retrievable packer flexibility:Operators in the Permian Basin prioritize plug-and-perf adaptability as reservoir complexity rises, driving demand for tools that enable rapid zonal reconfiguration without milling operations.
- EPA methane emissions rules:Fugitive gas migration prevention mandates tighten zonal isolation specifications, compelling operators to upgrade packer configurations in critical sour-gas environments.
- Halliburton's captive manufacturing:In-house production of expandable sealing elements in Houston demonstrates how backward integration into elastomer supply secures sour-service material availability.
Market Restraints
- Specialized alloy input costs:Chromium-molybdenum steel price volatility directly impacts high-pressure packer manufacturing margins, with sour-service grades commanding premium surcharges.
- Metallurgy capability concentration:Advanced elastomer compound formulation for HPHT applications clusters among vertically integrated suppliers with in-house R&D facilities.
- Permanent packer lock-in:Deepwater operators face switching costs from established mechanical-set permanent systems, slowing retrievable technology penetration in ultra-deepwater basins.
Strategic Opportunities
- Extended-reach laterals:Proprietary slip-system designs that reduce trip time are capturing share in West Texas multi-mile horizontals where rig time economics dominate tool selection.
- Abandoned well integrity:Evolving EPA greenhouse gas reporting obligations for plugged wells reshape demand toward permanent isolation strategies in mature basin retirement programs.
- Digital-twin integration:Real-time packer performance monitoring converges with predictive maintenance platforms, enabling service providers to unbundle after-sales support from hardware sales.
Industry Challenges
- API 11D1 V1-V3 certification timelines:Extended validation testing for high-temperature sealing integrity creates backlog bottlenecks for new product introductions.
- HPHT simulation capacity:Finite laboratory infrastructure for simultaneous pressure-temperature cycling limits concurrent product qualification throughput.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydraulic Packers Market |
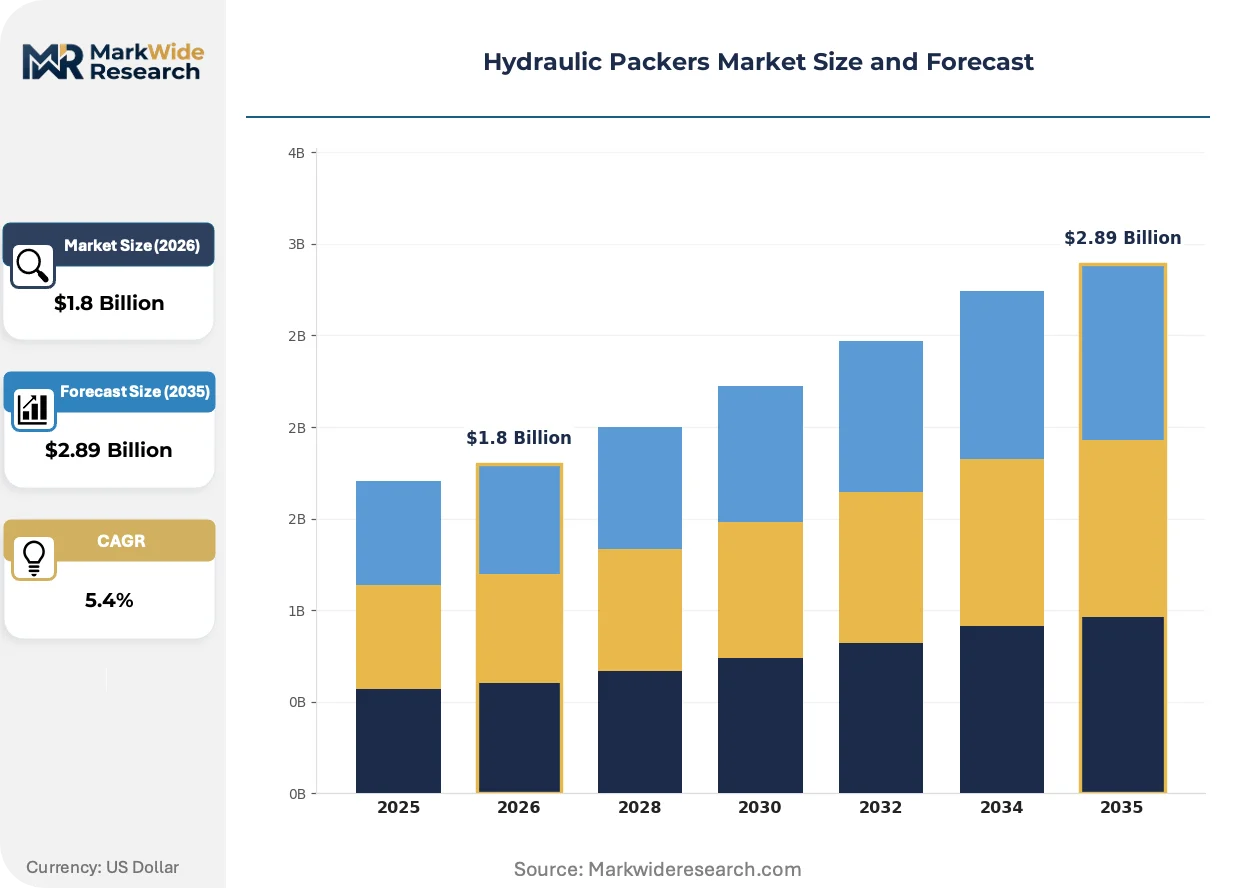
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.89 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Retrievable Packers, Permanent Packers, Multi-Stage Packers, Single-Trip Packers Application: Oil & Gas Exploration, Water Injection, Geothermal Wells, Acidizing End User: Upstream Oil Producers, Service Providers, Independent Operators, Government Agencies Installation: Top-Down Installation, Bottom-Up Installation, Horizontal Installation, Combining Techniques |
| Companies Covered | Weatherford International, American Completion Tools, Schlumberger, Tendeka, D&L Oil Tools, Halliburton, National Oilwell Varco, TAM International, Baker Hughes, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydraulic Packers Market Strategic Shifts & Innovations
Downhole isolation technology is bifurcating between permanent mechanical reliability and retrievable operational flexibility, with digital integration and materials science advancing in parallel across both product architectures.
Metallic-to-metallic sealing systems are expanding into ultra-high-pressure geothermal and HPHT gas applications where elastomer degradation risks exclude conventional rubber compounds. Geothermal developers in Iceland and Turkey adopt these systems for 400°F-plus reservoir conditions. The technology is expanding into markets previously reserved for permanent packer installations, compressing the performance gap between retrievable and permanent isolation solutions.
OSHA and BSEE enforcement of wellbore barrier standards in US Gulf of Mexico operations mandates redundant packer configurations for sour-gas completions. This regulatory pressure elevates specification requirements for mechanical hold and sealing integrity under simulated downhole conditions. Deepwater service providers respond by pre-qualifying dual-packer assemblies to accelerate permitting timelines.
Buyer concentration among integrated service providers is consolidating procurement leverage, compressing pricing power for independent tool manufacturers. Direct sourcing agreements between operators and specialized packer suppliers bypass traditional distribution channels in the Permian Basin. This channel disintermediation is most visible among independent operators with sufficient drilling density to justify direct vendor relationships.
Hydraulic Packers Market Segmentation
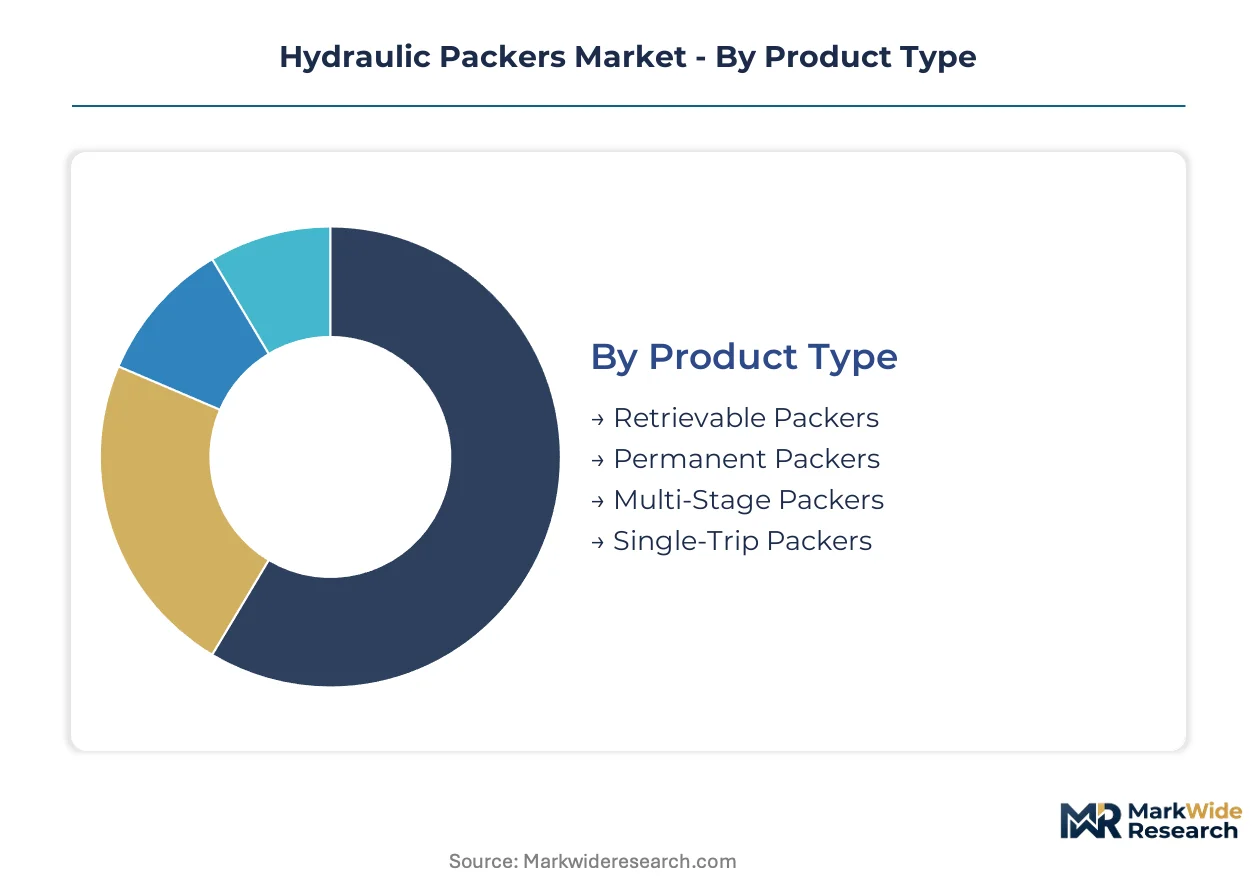
Segmentation in the hydraulic packers market reveals how tool selection criteria diverge sharply between unconventional shale operators prioritizing operational flexibility and deepwater developers demanding mechanical permanence. Understanding these fault lines enables suppliers to align R&D investment with the specific performance thresholds that dominate purchasing decisions across distinct well construction environments.
Product Type:
Buyer selection pivots on the trade-off between retrievability and pressure integrity, with reservoir depth and completion strategy dictating which sealing architecture earns placement.
- Retrievable Packers:Mechanical or hydraulic setting mechanisms enable full bore-through retrieval without milling, preserving casing integrity for recompletion. Permian Basin operators deploy these tools in plug-and-perf sequences where zonal reconfiguration frequency justifies premium pricing over permanent alternatives.
- Permanent Packers:Slip-and-seal assemblies rated for 15,000-plus psi differential pressure anchor production tubing in deepwater Gulf of Mexico completions where mechanical reliability overrides future access requirements. These systems dominate HPHT gas developments where elastomer degradation risks mandate metallic backup sealing.
- Multi-Stage Packers:Isolation tools designed for simultaneous zonal separation during single-trip fracturing operations in extended-reach laterals.
- Single-Trip Packers:Integrated completion systems reducing rig time through combined setting and stimulation functions.
Permanent packers lead on scale; retrievable packers lead on momentum.
Application:
Operating environment severity determines material specification tiers, with geothermal and sour-gas applications commanding specialized metallurgy and compound formulations unavailable in standard catalog offerings.
- Oil & Gas Exploration:Zonal isolation during drilling and completion phases in conventional and unconventional reservoirs, spanning primary production through enhanced recovery. West Texas shale basins drive replacement cycle compression as multi-stage completion intensity accelerates tool consumption rates.
- Geothermal Wells:Metallic-to-metallic sealing systems address elastomer degradation above 350°F in Iceland and Turkey developments, where thermal cycling resistance separates qualified suppliers from catalog vendors.
- Water Injection:Packers maintaining injection profile integrity in secondary recovery operations.
- Acidizing:Corrosion-resistant sealing elements for stimulation chemistry exposure.
Oil and gas exploration anchors volume procurement; geothermal applications expand most quickly.
End User:
Purchasing concentration among integrated service providers reshapes channel economics, with direct sourcing agreements bypassing traditional distribution in high-density drilling corridors.
- Service Providers:Schlumberger, Halliburton, and Baker Hughes command disproportionate procurement volume as intermediaries between tool manufacturers and independent operators. These firms leverage captive manufacturing and in-house metallurgy to secure sour-service material availability while compressing margins for independent packer suppliers.
- Upstream Oil Producers:Supermajors and shale-focused independents specify packer configurations directly in deepwater and critical sour-gas environments where internal engineering teams override service provider recommendations.
- Independent Operators:Permian-focused drillers with sufficient rig density justify direct vendor relationships.
- Government Agencies:State-owned enterprises in resource-nationalist jurisdictions mandating local content quotas.
Service providers dominate procurement scale; independent operators gain purchasing momentum through channel disintermediation.
Installation:
Wellbore geometry and rig configuration dictate deployment methodology, with horizontal installation complexity driving differentiation among suppliers serving extended-reach laterals.
- Horizontal Installation:Specialized running tools and slip-system designs address drag forces and differential sticking risks in multi-mile laterals where conventional top-down methods fail. West Texas operators prioritize proprietary trip-time reduction features that compress rig day rates.
- Top-Down Installation:Standard deployment from surface through vertical wellbore sections, dominant in conventional and shallow unconventional completions.
- Bottom-Up Installation:Deployment from lower completion upward in selective zonal isolation scenarios.
- Combining Techniques:Hybrid approaches for complex well architectures.
Top-down installation retains scale leadership; horizontal installation climbs fastest as lateral lengths extend.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Permian Basin of West Texas anchors demand concentration for hydraulic packers, with multi-stage completion intensity driving replacement cycles for downhole isolation equipment across North American shale plays.
United States
Upstream operators in the Permian Basin and Bakken formation deploy retrievable packers for plug-and-perf flexibility as lateral lengths extend beyond three miles. EPA methane emissions rules tighten zonal isolation specifications for sour-gas environments, compelling upgrades to dual-packer configurations. Houston hosts captive manufacturing facilities for expandable sealing elements, securing material availability for high-pressure applications.
Canada
Montney and Duvernay shale operators prioritize metallic-to-metallic sealing systems for thermal cycling resistance in steam-assisted gravity drainage operations. The country's national energy regulator enforces wellbore barrier standards that mandate redundant isolation in critical sour-gas completions. Calgary-based engineering teams specify API 11D1 V3-certified tools for thermal recovery projects in Alberta's oil sands corridors.
Saudi Arabia
Saudi Aramco's gas development programs in the Jafurah Basin drive demand for HPHT-rated permanent packers in high-sulfur reservoir conditions. The national oil company mandates local content quotas that reshape procurement toward domestic fabrication partnerships. Dhahran's technology centers collaborate with international suppliers on sour-service metallurgy qualification for 15,000 psi differential pressure ratings.
Norway
Equinor's Johan Sverdrup and Northern Lights projects specify permanent packer systems for subsea tiebacks where mechanical reliability overrides retrieval requirements. The Norwegian Petroleum Safety Authority enforces well integrity regulations that elevate specification thresholds for deepwater barrier elements. Stavanger's supplier cluster concentrates engineering expertise for North Sea high-pressure gas developments.
Brazil
Pre-salt carbonate developments in the Santos Basin require packer assemblies rated for 400°F-plus temperatures and corrosive CO2-rich production fluids. Petrobras mandates local content requirements that channel procurement toward domestic manufacturing partnerships. Rio de Janeiro's subsea technology corridor hosts qualification facilities for metallic sealing systems in ultra-deepwater applications.
Hydraulic Packers Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue specialty metallurgy and digital integration as differentiation vectors. The supplier base concentrates around integrated oilfield service conglomerates with captive manufacturing capabilities, while independent tool manufacturers defend position through niche specialization in sour-service or geothermal applications. Three archetypes dominate: vertically integrated service providers controlling elastomer supply chains; independent packer specialists with proprietary slip-system designs; and regional fabricators serving local content mandates. Capacity expansion in Houston and consolidation of testing facilities represent the dominant competitive moves.
Among US-based integrated providers, Schlumberger, Halliburton, and Baker Hughes exemplify the vertically integrated archetype, each occupying positions shaped by in-house metallurgy capabilities and captive supply of critical sealing components. These entities anchor procurement scale through direct relationships with supermajors and shale-focused independents, compressing margin structures for non-integrated competitors. Weatherford International and National Oilwell Varco represent alternative structural approaches, with the former emphasizing retrievable tool portfolios and the latter leveraging manufacturing scale across complementary downhole product lines.
| Leading Market Players |
|---|
| Weatherford International |
| American Completion Tools |
| Schlumberger |
| Tendeka |
| D&L Oil Tools |
| Halliburton |
| National Oilwell Varco |
| TAM International |
| Baker Hughes |
| Others |
Cost & Logistics Intelligence
Integrated service providers commanding procurement scale compress margin structures for independent packer manufacturers across North American shale corridors. Three-tier pricing structure across premium, standard, and economy levels reflects divergent certification grades and metallurgy capabilities rather than brand positioning alone.
Pricing Analysis
Chromium-molybdenum steel price volatility passes through directly to high-pressure packer manufacturing margins, with sour-service alloy grades commanding premium surcharges that widen spreads between API 11D1 V3-certified and uncertified alternatives. Cost compression in the standard tier intensifies as Halliburton and Schlumberger leverage captive elastomer supply to undercut independent vendors. Independent operators in the Permian Basin exhibit acute price sensitivity for retrievable tools, while deepwater supermajors prioritize mechanical reliability over unit economics.
Supply Chain Analysis
Freight costs for oversized downhole equipment from Houston fabrication clusters to West Texas well sites add meaningful landed cost premiums versus regional Mexican or Canadian supply alternatives. Manufacturing concentration in the United States, Norway, and Saudi Arabia draws from specialized alloy feedstocks and elastomer compound formulations. Single-source vulnerability clusters around in-house metallurgy capabilities for HPHT applications. Distribution runs through integrated service provider procurement arms that bypass traditional tool distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds regulatory demand through EPA methane emissions enforcement and evolving abandoned well integrity obligations that mandate upgraded zonal isolation specifications.
For Market Incumbents: Extend API 11D1 V3 certification coverage across retrievable product lines to preempt emerging entrants from capturing plug-and-perf share in the Permian Basin. Deepen backward integration into sour-service elastomer supply chains before commodity alloy volatility erodes captive manufacturing advantages. For New Entrants and Emerging Players: The price-point gap between premium Halliburton/Schlumberger offerings and economy-tier regional fabricators creates white-space for metallic-to-metallic sealing specialists targeting geothermal developers in Iceland and Turkey. Target direct sourcing relationships with independent operators in West Texas bypassing service provider intermediaries. For Investors and Strategic Acquirers: Integrated oilfield service conglomerates are the most active acquirers in this space, consolidating niche metallurgy capabilities to fill HPHT qualification gaps. Long-term viability hinges on exposure to regulatory-driven replacement cycles rather than drilling activity sensitivity alone. Monitor EPA greenhouse gas reporting rulemaking for plugged wells as the signal indicating permanent packer demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| API 11D1 V3 Certification Investment | Accelerates permitting timelines for deepwater Gulf of Mexico completions under BSEE enforcement. |
| Captive Elastomer Manufacturing | Secures sour-service compound availability independent of specialty chemical supplier pricing. |
| Metallic-to-Metallic Sealing Development | Opens geothermal and ultra-HPHT gas applications above 400°F where rubber degrades. |
| Digital-Twin Integration | Enables service providers to unbundle predictive maintenance from hardware sales revenue. |
| Direct Operator Sourcing Agreements | Bypasses integrated service provider procurement leverage in high-density Permian drilling corridors. |
Research Approach
Multiple input streams — primary interviews with completion engineers, procurement leads at independent operators, and aftermarket service heads; secondary validation through API certification databases, SEC 10-K filings, and EPA regulatory dockets; plus customs records for alloy import flows — were reconciled through bottom-up and top-down triangulation. Conversations with Schlumberger, Halliburton, and Baker Hughes product line managers anchored demand-side assumptions, while supplier interviews with Weatherford and National Oilwell Varco informed capacity and pricing dynamics.
Data-stream reconciliation across product type, application severity, end-user procurement tier, and regional regulatory framework shaped the analytical framework over the projection horizon. CAGRs were derived from replacement cycle modeling in multi-stage completion environments and thermal recovery project pipelines. Forecast inputs incorporated EPA methane rule compliance timelines and Saudi Aramco Jafurah Basin development schedules.
Caveats apply where commodity alloy price spikes or regulatory enforcement delays could materially shift the outlook for high-pressure packer procurement. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Ultrasonic Welding Machine Market
Construction Equipment
Dozer Tire Market
Construction Equipment
CNC Machine Tools Market
Construction Equipment
LAMEA Mini Excavators Market
Construction Equipment
Concrete NDT Testing Equipment Market
Construction Equipment
Press Fit Machines Market
Construction Equipment
Europe Crane Market
Construction Equipment
Sandblasting Machines Market
Construction Equipment
Industrial Grout Pumps Market
Construction Equipment
Concrete Mixer Market
Construction Equipment
Concrete Pumps Market
Construction Equipment
Concrete Spreader Market
Construction Equipment
Welding Fume Extraction Equipment Market
Construction Equipment
Construction Camera [Time Lapse Camera] Market
Construction Equipment
Europe Construction Equipment Rental Market
Construction Equipment
Static Crane Market