
 Hydraulic Breaker for Excavator Market | 2026-2036
Hydraulic Breaker for Excavator Market Size, Share, and Industry Trends Forecast 2026-2036
Hydraulic Breaker for Excavator Market Insights
Tier-4 Final and Stage V emissions-compliant breaker specifications is redrawing procurement criteria across the hydraulic breaker for excavator market. Caterpillar leverages its integrated excavator-breaker bundling strategy to sustain fleet renewal cycles in North American quarrying. Komatsu anchors its position through advanced hydraulic percussive systems optimized for mining contractors in Australia and Indonesia. SANY Group competes aggressively on manufacturing scale, occupying dominant share in China's domestic infrastructure build-out.
A hydraulic breaker for excavator is a percussive attachment mounted to carrier machines via quick-coupler systems, typically delivering impact energy from 500 to 15,000 joules through nitrogen-gas-assisted piston reciprocation to fracture rock, concrete, or asphalt substrates. Medium-duty breakers command the largest installed base among utility installation and road construction contractors, while heavy-duty breakers generate concentrated margin pools in mining operations where downtime costs dominate total cost of ownership. Electro-hydraulic technology is gaining fastest penetration in European urban demolition, where self-adjusting impact systems reduce structural vibration complaints and permit compliance costs.
OSHA noise exposure limits in the United States and EU machinery directives under CE marking constrain breaker operating specifications, forcing redesigns of housing insulation and damping systems. India's BIS certification requirements for construction equipment imports create non-tariff barriers that favor localized assembly by domestic firms such as Yantai Ligong Machinery and Beilite. Equipment rental firms and infrastructure developers must monitor how regulatory divergence across these jurisdictions fragments spare parts logistics and recalibrates aftermarket service networks.
Market Dynamics
Electro-hydraulic breaker technology is decomposing traditional nitrogen-gas piston architectures as urban demolition contractors face tightening vibration limits and noise ordinances. This shift forces manufacturers to redesign damping systems and recalibrate aftermarket service networks around electronic diagnostics rather than mechanical rebuild cycles.
Growth Catalysts
- India's PLI scheme for construction equipment:Domestic rental firms and highway contractors are accelerating fleet deployment under production-linked incentive structures that favor localized assembly.
- Self-adjusting impact systems:European urban demolition specialists are retrofitting carriers with automated stroke modulation to preempt structural damage claims and permit delays.
- Quarrying expansion in Southeast Asia:Infrastructure developers in Indonesia, Vietnam, and the Philippines are standardizing medium-duty breaker specifications across road construction and aggregate extraction contracts.
Market Restraints
- Specialized steel alloy supply concentration:High-wear piston and chisel production depends on Swedish and Japanese specialty steel mills with limited surge capacity.
- F-Gas Regulation compliance costs:EU nitrogen charging protocols face refrigerant gas handling restrictions that extend service turnaround times and raise technician certification requirements.
- Electric excavator compatibility gaps:Battery-powered carrier voltages and hydraulic flow rates mismatch legacy breaker control systems, forcing adapter development delays.
Strategic Opportunities
- CE marking as competitive filter:Manufacturers with certified low-vibration housings can capture premium positioning in German and French municipal demolition tenders.
- Remote diagnostic integration:Telematics-enabled breakers allow rental fleets to shift from time-based maintenance to condition-based service intervals, improving utilization rates.
- Australian mining contractor consolidation:Large-scale iron ore and lithium operations are standardizing heavy-duty breaker fleets, creating volume contracts for impact energy ratings above 10,000 joules.
Industry Challenges
- Electro-hydraulic technician scarcity:Field service networks lack personnel trained in electronic control module troubleshooting and sensor calibration protocols.
- Dual certification timelines:Simultaneous OSHA noise exposure and CE machinery directive approvals extend product launch cycles by 8-14 months for North Atlantic suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydraulic Breaker for Excavator Market |
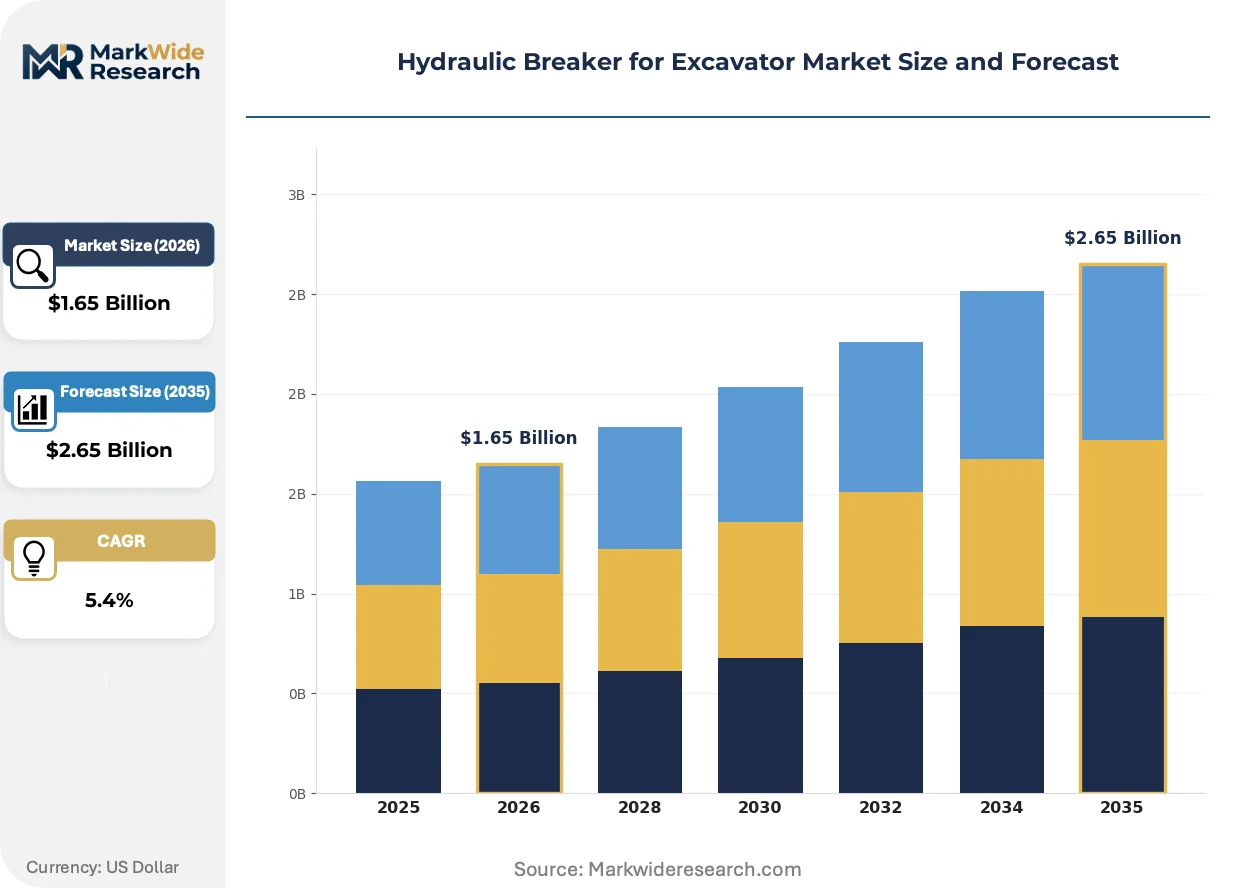
| Market Size in 2026 | $1.65 Billion |
| Market Size in 2035 | $2.65 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Heavy-Duty Breaker, Medium-Duty Breaker, Compact Breaker, Multi-Purpose Breaker, Demolition Breaker Technology: Pneumatic Hydraulic, Electro-Hydraulic, Hydraulic Direct Impact, Hydraulic Percussive, Self-Adjusting Impact Application: Quarrying, Road Construction, Mining Operations, Building Demolition, Utility Installation End User: Construction Companies, Mining Contractors, Infrastructure Developers, Utility Service Providers, Equipment Rental Firms |
| Companies Covered | Doosan Infracore, Yantai Ligong Machinery, Caterpillar, Astec, Komatsu, Atlas Copco, Beilite, Allied/Rammer, SANY Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydraulic Breaker for Excavator Market Trends and Innovations
Breaker technology trajectories center on intelligent energy management, regulatory pre-compliance as product strategy, and rental fleet digitization reshaping ownership economics across construction verticals.
Variable-frequency drive systems are decomposing fixed-stroke hydraulic breakers by enabling real-time impact energy modulation based on substrate density feedback. Tunneling contractors in Switzerland and Austria are specifying these units for mixed-face excavation where rock hardness shifts unpredictably. The technology is compressing demand for single-purpose medium-duty models as versatile units cover broader application ranges.
The EU F-Gas Regulation and Machinery Directive are forcing nitrogen-assisted systems toward sealed charging architectures with leak-detection monitoring. Manufacturers must redesign accumulator housings to eliminate service-port emissions during routine maintenance. German demolition specialists now require CE-marked breakers with documented vibration emission values below 5 m/s² for inner-city structural dismantling.
Rental fleet operators are unbundling after-sales service from equipment procurement, selecting breakers based on telematics interoperability and third-party service network density rather than OEM captive support. This pattern concentrates in the United States where United Rentals and Sunbelt are standardizing API-accessible diagnostic protocols across attachment portfolios. Independent service providers in Texas and Florida are capturing maintenance revenue previously retained by manufacturer dealers.
Hydraulic Breaker for Excavator Market Segmentation
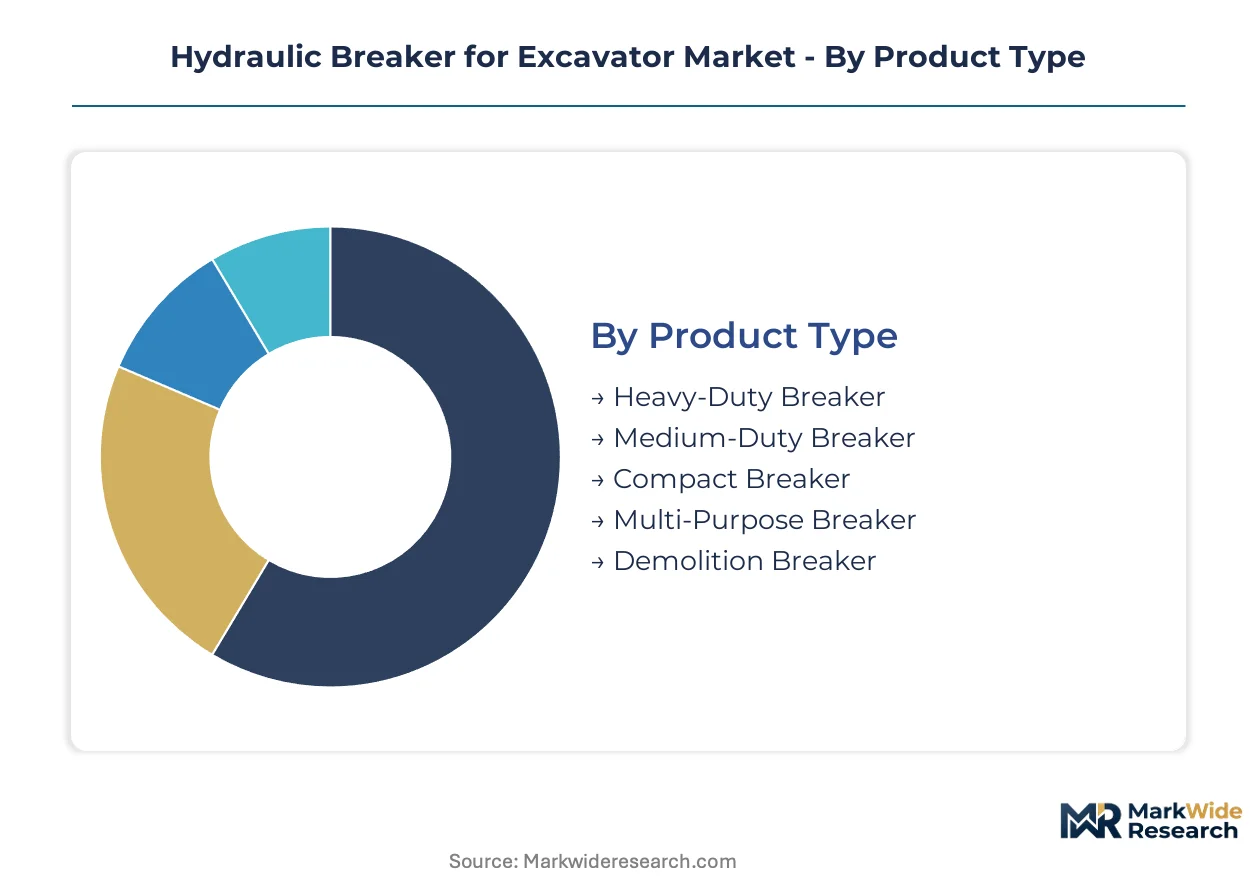
Breaker procurement patterns diverge sharply across duty ratings and technology architectures. Equipment buyers in India and Southeast Asia prioritize acquisition cost and parts availability, while European and Australian contractors specify compliance-grade specifications that filter vendor pools.
Product Type:
Domestic assembly dominates compact and medium-duty categories in India under PLI incentives, while heavy-duty units remain import-dependent across most markets.
- Heavy-Duty Breaker:Nitrogen-gas-assisted piston systems deliver impact energy above 10,000 joules for hard rock fracturing in Australian iron ore and lithium extraction. Mining contractors standardize these units under fleet consolidation programs that prioritize mean time between failures over upfront capital cost.
- Medium-Duty Breaker:Specifications from 2,000 to 8,000 joules cover utility trenching and secondary quarrying tasks. Indonesian and Vietnamese road contractors are standardizing this class across aggregate extraction and asphalt recycling contracts to reduce fleet complexity.
- Compact Breaker:Urban renovation contractors in German and French city centers deploy sub-2,000 joule units for interior structural dismantling where transport weight limits apply.
- Multi-Purpose Breaker:Quick-coupler compatibility allows carrier sharing between demolition and utility crews.
- Demolition Breaker:Reinforced housing designs withstand continuous vertical breaking of reinforced concrete bridge decks.
Medium-duty breakers command the established base. The steepest expansion runs through heavy-duty units in Australian mining standardization programs.
Technology:
Cost tiers separate mature nitrogen-assisted architectures from premium electro-hydraulic systems with sensor feedback loops.
- Electro-Hydraulic:Real-time stroke modulation via variable-frequency drives enables substrate-density adaptation without operator intervention. Swiss and Austrian tunneling contractors specify these for mixed-face excavation where rock hardness shifts unpredictably within single bore sections.
- Self-Adjusting Impact:Automated energy modulation preempts structural damage claims in European urban demolition. German municipal tender specifications now require documented vibration emission values below 5 m/s² for inner-city dismantling permits.
- Pneumatic Hydraulic:Legacy nitrogen-gas piston architectures dominate replacement part markets and technician training programs.
- Hydraulic Direct Impact:Simplified valving reduces maintenance intervals for rental fleet operators prioritizing uptime over precision.
- Hydraulic Percussive:Komatsu's optimized systems anchor market position in Indonesian and Australian mining contractor relationships.
Pneumatic hydraulic systems retain the largest installed base. Electro-hydraulic technology is climbing the fastest as CE marking and F-Gas Regulation compliance reshape procurement filters.
Application:
Volume concentration varies by infrastructure investment cycles, with quarrying and road construction showing countercyclical patterns to building demolition.
- Quarrying:Medium-duty breakers fracture limestone and granite for aggregate supply to concrete batching plants. Philippine and Vietnamese infrastructure developers are expanding fleet purchases to support national highway expansion programs.
- Road Construction:Cold planing and asphalt recycling applications demand breaker-to-milling machine compatibility for surface preparation crews.
- Mining Operations:Heavy-duty units generate concentrated margin pools where downtime costs dominate total cost of ownership calculations.
- Building Demolition:Selective dismantling of reinforced concrete structures requires precision impact control to preserve adjacent properties.
- Utility Installation:Trenching for water, gas, and fiber optic lines drives consistent replacement demand for compact breaker wear components.
Road construction and quarrying together anchor volume demand. Building demolition is gaining share fastest as European urban renewal accelerates and vibration ordinances tighten.
End User:
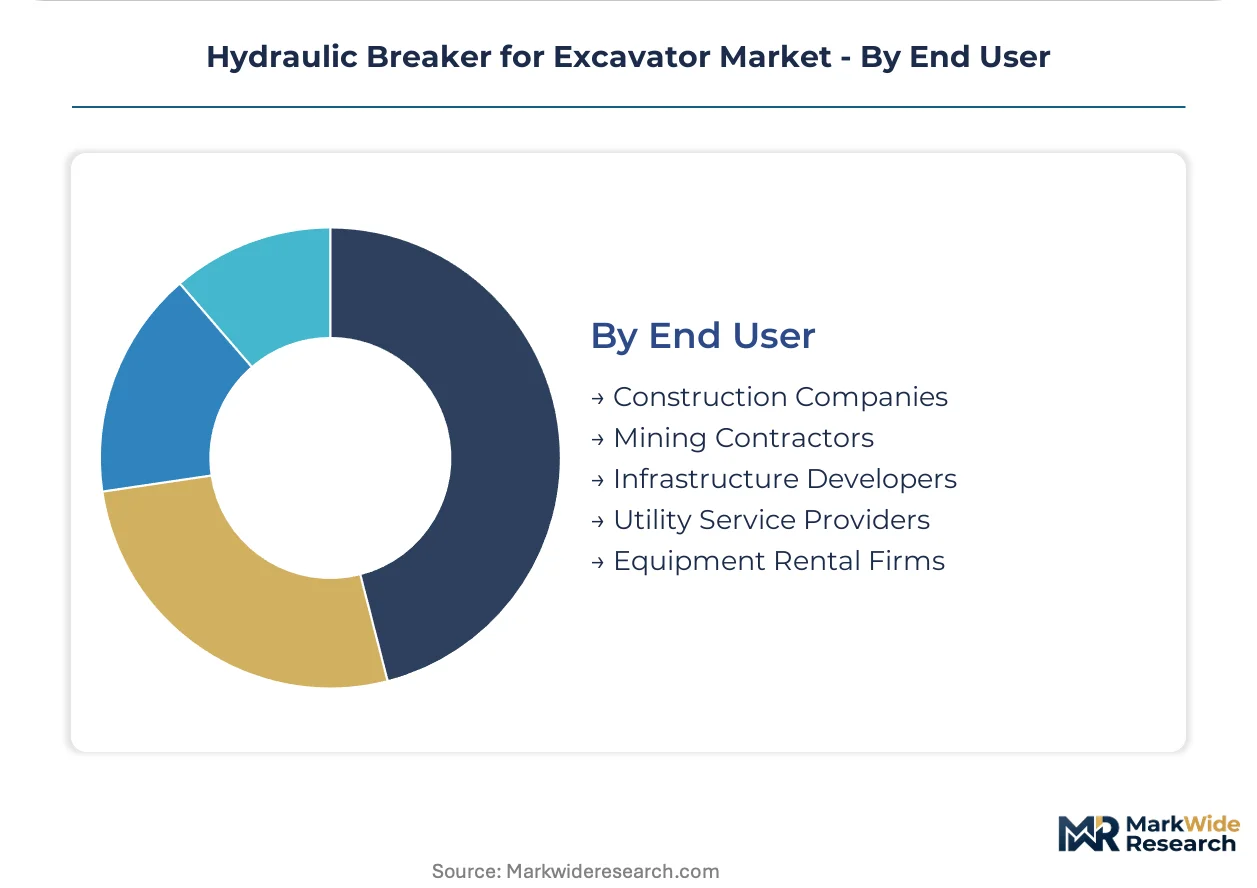
Customer type determines ownership economics, with rental firms prioritizing telematics interoperability and mining contractors demanding captive service networks.
- Equipment Rental Firms:United Rentals and Sunbelt in the United States are standardizing API-accessible diagnostic protocols across attachment portfolios. These operators select breakers based on third-party service network density rather than OEM captive support, shifting maintenance revenue to independent providers in Texas and Florida.
- Mining Contractors:Large-scale iron ore and lithium operations in Australia standardize heavy-duty fleets above 10,000 joules under volume contracts that specify impact energy ratings and guaranteed spare parts availability.
- Construction Companies:General contractors balance acquisition cost against depreciation schedules for tax-advantaged fleet planning.
- Infrastructure Developers:Indian national highway programs are accelerating breaker deployment through domestic rental firm partnerships under PLI scheme structures.
- Utility Service Providers:Municipal water and gas authorities maintain compact breaker inventories for emergency pipeline repair mobilization.
Construction companies hold the broadest installed base. Equipment rental firms are expanding most quickly as telematics-enabled condition-based maintenance reshapes utilization economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import dependence for heavy-duty breakers concentrates in Australia and Indonesia, while export-oriented manufacturing clusters in China and South Korea supply medium-duty units across Southeast Asian infrastructure markets. Trade flows reflect divergent regulatory compliance burdens, with CE-marked European specifications commanding premium positioning against OSHA-compliant North American variants.
United States
Quarrying contractors in Texas and Florida drive replacement demand for nitrogen-gas-assisted systems. OSHA noise exposure limits constrain housing insulation specifications, forcing redesigns of damping architectures for domestic rental fleets. The Permian Basin and Appalachian shale regions concentrate heavy-duty breaker deployment for aggregate extraction serving oilfield infrastructure.
Germany
Municipal demolition tenders in Berlin and Hamburg specify CE-marked breakers with vibration emission values below 5 m/s². The F-Gas Regulation mandates sealed nitrogen charging architectures with leak-detection monitoring, extending service turnaround times. The Ruhr industrial corridor anchors aftermarket service networks for electro-hydraulic retrofit programs.
India
National highway expansion programs accelerate breaker deployment through domestic rental firm partnerships. The PLI scheme for construction equipment favors localized assembly by Yantai Ligong Machinery and Beilite, reducing import dependence for compact and medium-duty categories. Maharashtra and Gujarat host assembly operations serving western infrastructure corridors.
Australia
Iron ore and lithium mining contractors in Western Australia standardize heavy-duty fleets above 10,000 joules under volume contracts specifying guaranteed spare parts availability. Import dependence persists for nitrogen-gas-assisted piston systems, with Perth and Kalgoorlie forming maintenance hubs for remote site support.
Indonesia
Road construction and aggregate extraction contracts in Java and Sumatra standardize medium-duty breaker specifications to reduce fleet complexity. Infrastructure developers expand fleet purchases as national connectivity programs accelerate. Jakarta-based rental firms source predominantly from Chinese and South Korean export channels.
Hydraulic Breaker for Excavator Market Competitive Landscape
Concentration sits with diversified heavy equipment manufacturers and specialized attachment fabricators competing across distinct technology tiers. Market structure fragments between premium electro-hydraulic specialists serving European compliance markets and scale-driven manufacturers dominating Asian infrastructure procurement. Two strategic archetypes define competitive positioning: integrated excavator-breaker bundlers leveraging fleet renewal cycles, and standalone attachment specialists capturing rental fleet standardization programs. Competitive moves center on telematics interoperability certification and third-party service network density expansion.
Among diversified equipment manufacturers, Caterpillar exemplifies the integrated bundling archetype through excavator-breaker fleet positioning, while Komatsu anchors hydraulic percussive system optimization for mining contractor relationships. SANY Group occupies the scale-driven manufacturing tier, competing on production capacity for domestic Chinese infrastructure build-out and Southeast Asian export channels. These three manufacturers represent divergent competitive vectors: captive ecosystem integration, mining-specific performance engineering, and cost-optimized volume production.
| Leading Market Players |
|---|
| Doosan Infracore |
| Yantai Ligong Machinery |
| Caterpillar |
| Astec |
| Komatsu |
| Atlas Copco |
| Beilite |
| Allied/Rammer |
| SANY Group |
| Others |
Pricing and Supply Chain Analysis
Ninety-day inventory cycles for Swedish specialty steel mill orders compress pricing power toward piston and chisel fabricators while forcing rental fleet operators toward longer-term procurement contracts. This lead-time structure concentrates margin capture with alloy suppliers and fragments negotiation leverage across breaker assemblers in India and Southeast Asia.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation centers on CE marking compliance grade and guaranteed mean time between failures for mining contractor volume contracts. Cost compression in economy-tier compact breakers is intensifying because domestic assembly under India's PLI scheme expands supply-side capacity. Equipment rental firms exhibit highest price sensitivity, while Australian mining contractors prioritize performance guarantees over acquisition cost.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes extend inbound logistics costs for nitrogen-gas charging equipment and electronic control modules. Manufacturing concentrates in China, South Korea, and Germany for complete breaker assemblies, while specialty steel for high-wear components draws from Sweden and Japan. Supply chain risk rests on single-source vulnerability for electro-hydraulic sensor arrays. Distribution runs through OEM captive dealer networks in mining corridors and independent service providers in US rental markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated rental fleet operators as United Rentals and Sunbelt standardize telematics protocols across attachment portfolios, fragmenting aftermarket revenue capture for incumbent manufacturers.
For Market Incumbents: Compound service network density in Australian mining corridors and German municipal demolition markets to preempt independent provider capture. Invest in CE marking pre-compliance for electro-hydraulic architectures before F-Gas Regulation tightening accelerates. Backward integration into sealed nitrogen charging systems reduces technician certification bottlenecks. For New Entrants and Emerging Players: CE marking fast-track programs for low-vibration housing designs open municipal tender access in Berlin and Hamburg. Target Indian domestic rental firm partnerships under PLI scheme structures where localized assembly requirements filter import competition. Pursue telematics API certification as primary go-to-market wedge against OEM captive diagnostics. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-arbitrage play because divergence between OSHA noise exposure limits and EU Machinery Directive compliance timelines creates 8-14 month product launch gaps for North Atlantic suppliers. Acquisition targets should demonstrate electro-hydraulic technician training infrastructure or certified low-vibration housing IP. Watch Australian iron ore and lithium mining contractor fleet standardization announcements as volume contract inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| Electro-Hydraulic Technology Migration | Variable-frequency drive adoption enables CE marking compliance for German municipal demolition tenders. |
| Telematics Interoperability Certification | API-accessible diagnostic protocols shift rental fleet maintenance revenue toward independent service providers. |
| Sealed Nitrogen Charging Architecture | F-Gas Regulation compliance eliminates service-port emissions during routine accumulator maintenance. |
| Domestic Assembly Under PLI Incentives | Localized production in Maharashtra and Gujarat reduces BIS certification barriers for Indian highway contractors. |
| Heavy-Duty Fleet Volume Contracts | Western Australian mining standardization programs above 10,000 joules lock in spare parts availability guarantees. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with quarrying contractors, equipment rental fleet managers, mining maintenance directors, and aftermarket service technicians. Secondary validation drew from customs trade data, SEC filings of diversified equipment manufacturers, BIS certification registries, and EU Machinery Directive compliance databases. Bottom-up triangulation against top-down production capacity estimates anchored volume and value outputs.
Across the analysis window, projections integrate duty rating segmentation by impact energy tier, technology architecture by control system type, and end-user category by ownership economics. CAGRs were derived from equipment replacement cycle modeling and infrastructure investment correlation analysis. Forecast inputs include national highway program appropriations in India, Australian mining capital expenditure announcements, and EU urban demolition permit issuance trends.
Decision-makers should treat outputs as directional under assumptions of sustained PLI scheme funding and stable specialty steel alloy pricing; material deviation would warrant model refresh. Forecasts reflect base-case infrastructure investment trajectories and regulatory enforcement intensity. Supply chain disruption or emissions standard acceleration outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Concrete Mixer Market
Construction Equipment
Hydraulic Packers Market
Construction Equipment
Electric and Hybrid Construction Equipment Market
Construction Equipment
Rotomolding Market
Construction Equipment
Concrete Grinder Market
Construction Equipment
Pressure Washer Market
Construction Equipment
Europe Used Construction Machinery Market
Construction Equipment
Construction Equipment Rental Market
Construction Equipment
Saudi Arabia Completion Equipment and Services Market
Construction Equipment
Grout Bags Market
Construction Equipment
Vietnam Crane Market
Construction Equipment
Yard Crane Market
Construction Equipment
India Heavy Construction Equipment Rental Market
Construction Equipment
Sandblasting Machines Market
Construction Equipment
Stick Welding Electrode Market
Construction Equipment
Stud Welding Machine Market