
 Global Hydraulic Hammer Market | 2026-2036
Global Hydraulic Hammer Market Size, Share, and Industry Trends Forecast 2026-2036
Global Hydraulic Hammer Market Analysis
The EU Green Deal is decoupling diesel-only hammer demand from European public procurement contracts, forcing fleet operators to evaluate hybrid and electric alternatives. Atlas Copco leverages its electrification roadmap to anchor premium positioning in Scandinavian infrastructure tenders. Sandvik competes through captive alloy supply chains that sustain breaker tool longevity under abrasive conditions. Rammer dominates Nordic mining aftermarket channels where equipment uptime commands premium service contracts.
A hydraulic hammer is a percussive attachment powered by pressurized fluid, typically operating at oil pressures of 160–220 bar with impact energies ranging from 150 joules to 20,000 joules depending on carrier weight class. It fractures rock, concrete, and compacted earth through repeated piston strikes transmitted via a tool bit, serving demolition, quarrying, tunneling, and foundation work. Demolition hammers lead product type revenue due to urban renewal cycles in mature economies, while pile drivers represent the fastest-growing segment as offshore wind farm installation accelerates. Hydraulic technology occupies the dominant share over pneumatic and electric alternatives in heavy excavation applications, though electric variants are gaining share in noise-sensitive utility maintenance work.
The EPA enforces Tier 4 Final emissions standards on diesel-powered carriers in the United States, indirectly constraining hydraulic hammer specifications through engine-downsizing trends. China's MEE implements GB standards on construction machinery noise and exhaust that shape export compliance requirements for manufacturers serving Belt and Road projects. ISO 18752 and ISO 4413 govern hydraulic hose and system safety, influencing breaker integration protocols and maintenance intervals. Stakeholders must monitor how carbon border adjustments and local content rules reshape equipment sourcing decisions across multi-jurisdiction project portfolios.
Market Dynamics
The EU Green Deal's machinery emissions standards are forcing a technology transition across the hydraulic hammer value chain, decoupling diesel-only specifications from public procurement and redirecting R&D investment toward electrified powertrains and bio-hydraulic fluids.
Growth Catalysts
- Underground Mining Intensification:Declining ore grades in Australian hard-rock operations are extending mine life through deeper extraction, expanding fleet purchases of heavy-duty breakers for overburden removal and stope development.
- EU Green Deal Procurement Mandates:European public infrastructure tenders now require electrified or hybrid equipment, redirecting fleet operator capital toward compliant hammer variants and accelerating manufacturer electrification roadmaps.
- Western China Infrastructure Buildout:Rail tunneling and hydropower dam construction across Sichuan and Yunnan provinces are concentrating demand for high-impact rock-breaking equipment in geologically challenging terrain.
Market Restraints
- Specialized Alloy Supply Concentration:Premium breaker tool steels depend on tungsten and molybdenum processing concentrated in limited smelting jurisdictions, exposing manufacturers to raw material availability shocks.
- EPA Tier 4 Final Compliance Costs:Diesel carrier engine-downsizing requirements in the United States indirectly constrain hammer power-to-weight specifications, limiting performance in weight-class-constrained applications.
- Electric Alternative Performance Gap:Battery-powered carriers currently deliver insufficient sustained hydraulic flow for continuous high-cycle hammer operation in quarrying and mining, restricting electrification to intermittent demolition tasks.
Strategic Opportunities
- Offshore Wind Foundation Installation:Monopile and jacket foundation driving for North Sea and Baltic wind farms is creating specialized pile driver demand that commands premium pricing and long-term service contracts.
- India National Infrastructure Pipeline:The country's tunneling and highway expansion programs remain underpenetrated by premium hydraulic breaker suppliers, offering first-mover positioning in price-sensitive but volume-intensive procurement.
- Digital Telematics Integration:Convergence of hammer-mounted vibration sensors with cloud-based predictive maintenance platforms is enabling outcome-based service models that capture aftermarket revenue streams.
Industry Challenges
- Certification Timeline Compression:China's GB standards on construction machinery noise and exhaust are evolving faster than traditional product validation cycles, forcing parallel regulatory submissions across multiple jurisdictions.
- Hydraulic System Integration Complexity:Electrified carrier architectures require redesigned valve blocks and accumulator configurations that conflict with legacy breaker mounting interfaces, complicating fleet standardization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Hydraulic Hammer Market |
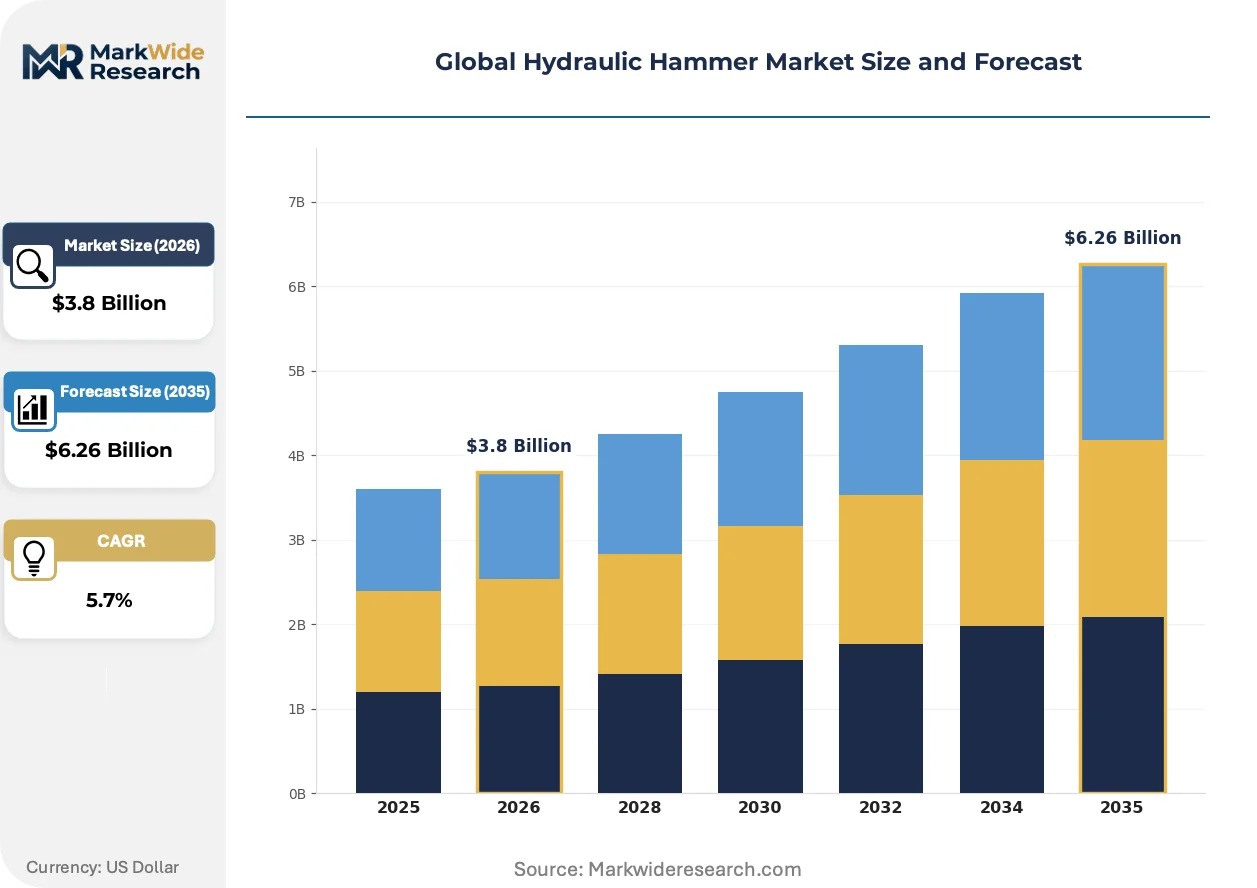
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Demolition Hammers, Concrete Breakers, Pile Drivers, Post Drivers End User: Construction, Mining, Oil & Gas, Infrastructure Application: Road Construction, Excavation, Building Renovation, Utility Maintenance Technology: Pneumatic, Hydraulic, Electric, Mechanical |
| Companies Covered | Soosan, Rammer, Atlas Copco, Montabert, Furukawa, Indeco, Sandvik, NPK, EVERDIGM, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Hydraulic Hammer Market Emerging Trajectories
Electrification, digital integration, and regulatory compliance are converging to reshape product architectures and competitive positioning across the hydraulic hammer market, compressing traditional technology lifecycles and redrawing supplier-customer relationships.
Variable displacement piston pumps with integrated load-sensing controls are unifying power delivery and impact modulation in a single hydraulic circuit. Tunneling contractors in Alpine regions are adopting these systems to reduce energy consumption during intermittent rock-breaking cycles. This unification is compressing the performance gap between fixed and variable geometry hammers, enabling standardized fleet configurations across mixed demolition and excavation applications.
REACH restrictions on mineral oil-based hydraulic fluids are mandating bio-based synthetic alternatives with higher oxidation stability requirements. European manufacturers are reformulating seal compounds and reservoir coatings to accommodate these fluid chemistries without degrading service intervals. Demolition contractors in German urban centers face the tightest compliance timelines, driving accelerated retrofit programs for existing carrier fleets.
Aftermarket parts procurement is fragmenting from dealer-centric models toward direct manufacturer portals and third-party platform aggregators. Mining operators in Western Australia are bypassing traditional distribution to source breaker tools and bushings through integrated supply chain platforms that consolidate multi-site fleet purchasing. This channel disintermediation is most pronounced in mature markets where equipment density supports predictive inventory positioning and same-day fulfillment expectations.
Global Hydraulic Hammer Market Segmentation
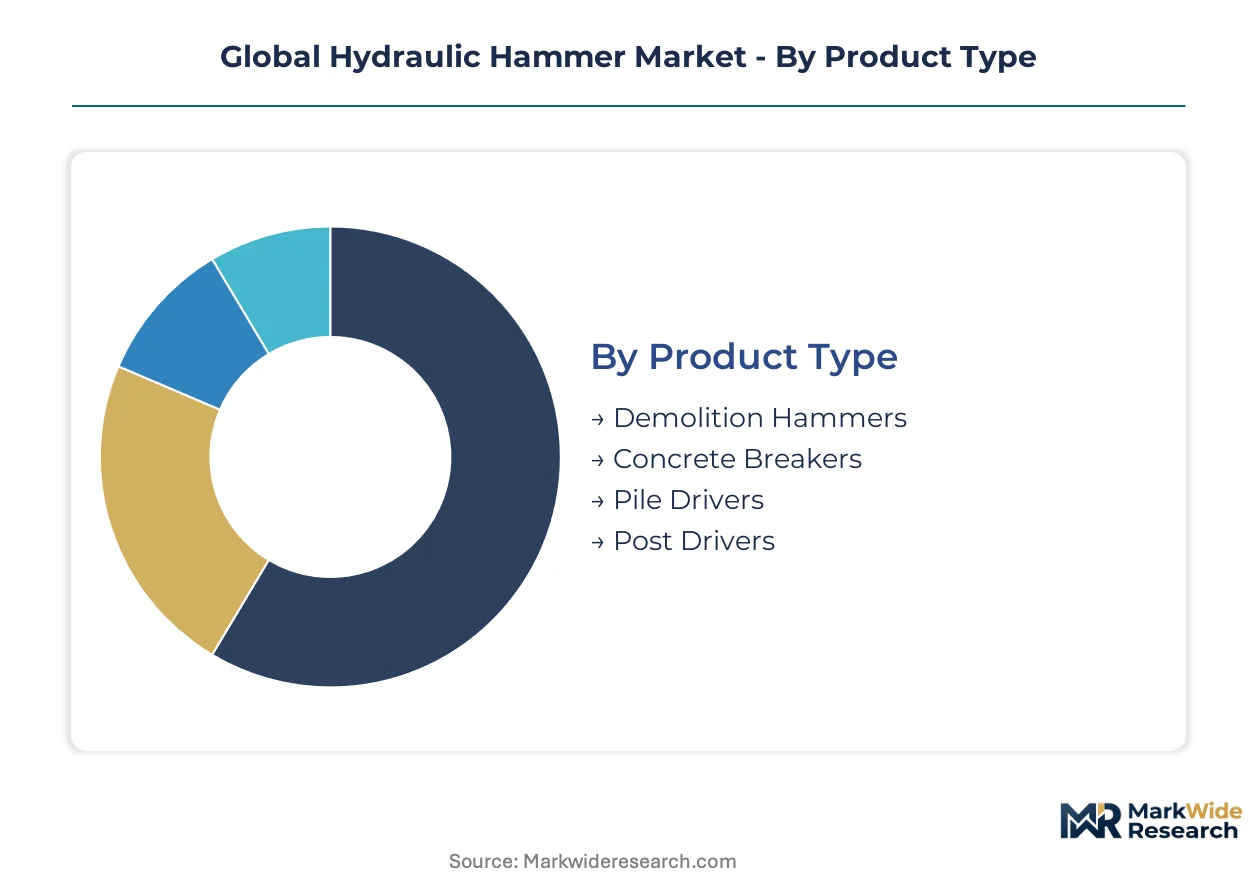
Segmentation in hydraulic hammers reflects divergent engineering requirements across impact energy classes, carrier compatibility, and duty-cycle intensity. Specification mismatches between breaker and carrier hydraulics drive premature failures and warranty disputes. Fleet operators increasingly standardize procurement around unified technology platforms to simplify maintenance and spare parts logistics.
Product Type:
Impact energy density and tool geometry differentiate commercial positioning across product categories, with urban noise constraints and mining duty cycles pulling designs in opposite directions.
- Demolition Hammers:These units operate at 1,000–10,000 joule impact energies with silenced housing configurations for urban compliance. European demolition contractors in German cities prioritize these variants where REACH-mandated bio-hydraulic fluids and noise limits below 85 dB apply. Revenue concentration reflects mature economies' urban renewal cycles and decommissioning of post-war infrastructure.
- Pile Drivers:Specialized monopile and jacket foundation driving equipment delivers sustained high-frequency impacts for offshore wind installation. North Sea and Baltic projects command premium pricing and long-term service contracts due to salt-air corrosion exposure and remote maintenance logistics.
- Concrete Breakers:Compact units under 1,500 joules serve building renovation and selective demolition where precision outweighs raw throughput. Tool steel longevity under reinforced concrete abrasion determines total cost of ownership.
- Post Drivers:Agricultural and fencing applications utilize lighter pneumatic-mechanical hybrids with minimal hydraulic infrastructure requirements. Seasonal demand patterns in North American ranching and Australian pastoral regions create inventory management challenges.
Demolition hammers lead on scale; pile drivers lead on momentum.
End User:
Capital intensity and equipment utilization rates create distinct procurement behaviors across customer categories, with mining operators prioritizing uptime guarantees over acquisition cost.
- Construction:General contractors demand versatile breaker specifications compatible with mixed fleet carriers. Urban projects in China's western provinces and India's National Infrastructure Pipeline concentrate volume, though price sensitivity limits premium attachment penetration.
- Mining:Underground hard-rock operations in Australia and Nordic countries require heavy-duty breakers rated for continuous duty cycles. Declining ore grades extend mine life through deeper extraction, expanding fleet purchases for overburden removal and stope development.
- Oil & Gas:Pipeline construction and decommissioning drive seasonal demand in North American shale regions and North Sea mature fields. Explosion-proof specifications for Zone 1 hazardous areas constrain supplier qualification.
- Infrastructure:Government procurement mandates in the EU Green Deal framework now require electrified or hybrid equipment, redirecting capital toward compliant hammer variants.
Mining commands the highest attachment values per unit; infrastructure procurement is expanding most quickly under decarbonization mandates.
Application:
Geological conditions and substrate hardness dictate breaker selection, with abrasive quartzite formations in Western China and Scandinavian granite requiring premium tool steels.
- Road Construction:Highway expansion and tunneling through mountainous terrain in Sichuan and Yunnan provinces concentrates demand for high-impact rock-breaking equipment. Drill-and-blast restrictions in populated valleys push mechanical breaking adoption.
- Excavation:Foundation work and earthmoving applications prioritize hydraulic flow efficiency over peak impact energy. Load-sensing pump integration reduces fuel consumption during intermittent duty cycles.
- Building Renovation:Interior demolition and selective structural modification require compact breakers with vibration damping to protect adjacent structures. Noise-sensitive utility maintenance in Japanese and European urban centers favors electric alternatives.
- Utility Maintenance:Trenching and pipe repair operations demand rapid carrier attachment changes. Telematics integration enables predictive maintenance scheduling across dispersed municipal fleets.
Road construction anchors current volume; building renovation is gaining share fastest on urban densification trends.
Technology:
Power density and portability trade-offs position each technology for distinct duty-cycle and environmental constraints, with electrification compressing traditional hydraulic dominance in select niches.
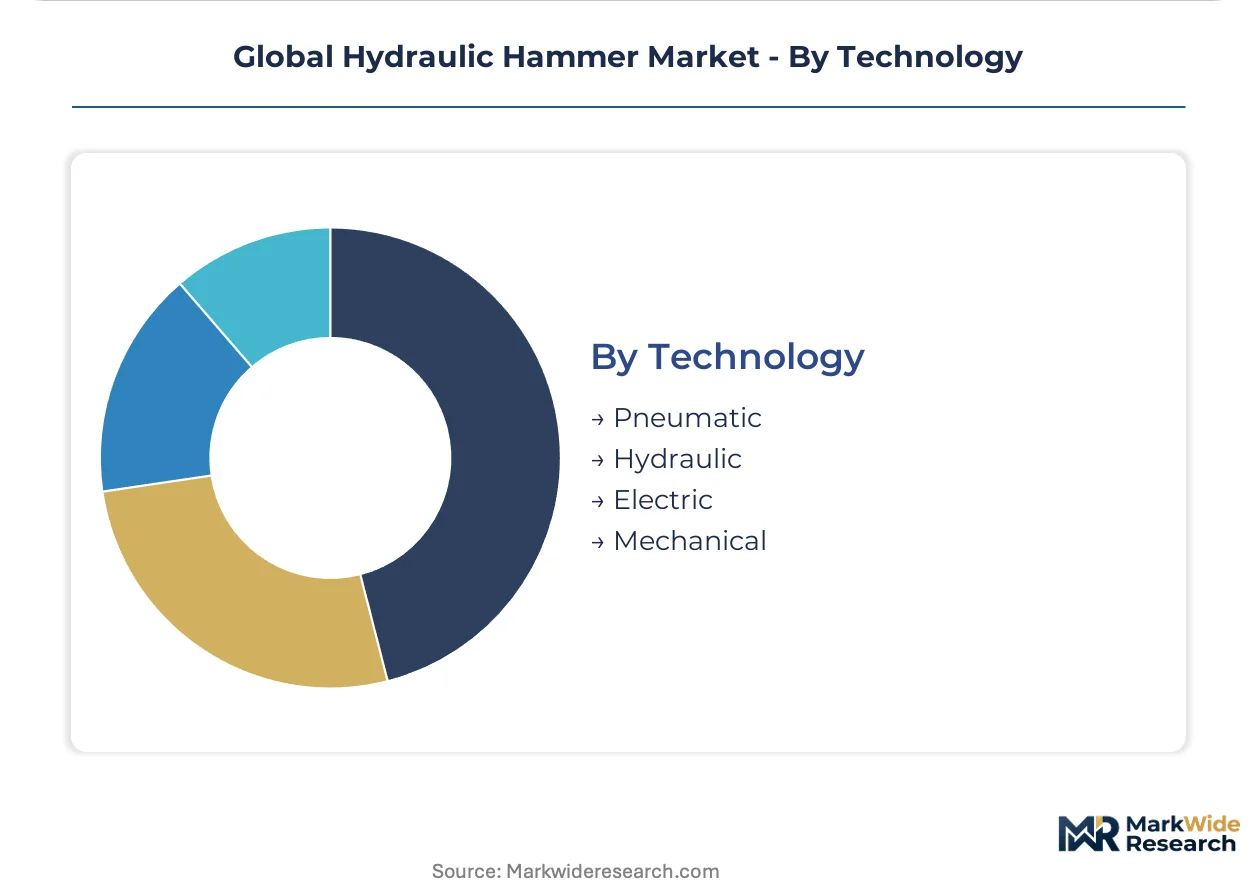
- Hydraulic:Dominant technology for heavy excavation delivers 160–220 bar operating pressures with impact energies spanning 150–20,000 joules. Piston-accumulator configurations transmit force through tool bits for rock, concrete, and compacted earth fracturing.
- Electric:Battery-powered variants serve noise-sensitive utility maintenance in German urban centers and Japanese infrastructure corridors. Current energy density limits restrict continuous high-cycle quarrying and mining applications to intermittent demolition tasks.
- Pneumatic:Compressed-air systems persist in underground mining where spark suppression overrides efficiency concerns. Limited portability and compressor logistics constrain surface construction adoption.
- Mechanical:Direct-drive cam and flywheel mechanisms serve agricultural post-driving with minimal maintenance infrastructure. Low capital cost appeals to seasonal users in price-sensitive developing markets.
Hydraulic systems retain scale leadership; electric variants show the steepest expansion trajectory on emissions compliance pressure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled equipment operators and maintenance technicians concentrate in Australia's Pilbara region, Germany's industrial heartland, and China's western construction corridors, anchoring demand clusters for specialized hydraulic breaker applications.
United States
Pipeline construction and shale field decommissioning drive seasonal hammer demand across Texas and North Dakota. EPA Tier 4 Final emissions standards constrain diesel carrier specifications, indirectly limiting breaker power-to-weight ratios. Houston's oilfield services cluster sources explosion-proof breakers for Zone 1 hazardous area work.
Germany
Urban demolition contractors in Berlin and Hamburg prioritize silenced housing configurations under REACH-mandated bio-hydraulic fluid requirements. The EU Green Deal's machinery emissions standards redirect public procurement toward electrified carrier compatibility. Bavaria's equipment manufacturers reformulate seal compounds for synthetic fluid chemistries.
China
Rail tunneling through Sichuan's mountainous terrain and hydropower dam construction in Yunnan concentrate demand for high-impact rock-breaking equipment. MEE's GB standards on construction machinery noise and exhaust shape export compliance for Belt and Road projects. Chengdu's machinery dealers stock heavy-duty breakers for geologically challenging western provinces.
Australia
Underground hard-rock mining in Western Australia's Pilbara region extends mine life through deeper extraction, expanding fleet purchases for overburden removal. Declining ore grades at Rio Tinto and BHP operations drive continuous-duty breaker specifications. Perth's mining equipment distributors prioritize uptime guarantees and premium service contracts.
India
The National Infrastructure Pipeline's tunneling and highway expansion programs create volume-intensive procurement opportunities across Maharashtra and Karnataka. Price-sensitive contractors favor versatile breaker specifications compatible with mixed fleet carriers. Mumbai's construction equipment importers source mid-range attachments for urban renewal projects.
Global Hydraulic Hammer Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across the hydraulic hammer value chain, with integrated foundry operations facing pressure from specialized assembly houses that outsource tool steel forging. The vendor base stratifies into three tiers: premium European manufacturers with captive alloy supply chains, mid-scale Asian fabricators serving price-sensitive developing markets, and regional specialists dominating aftermarket service corridors. Consolidation pressure intensifies as electrification R&D costs rise and certification timelines compress across multiple jurisdictions. Strategic moves center on backward integration into tungsten processing and geographic expansion through distributor acquisition in underpenetrated infrastructure markets.
Among European-based manufacturers, Atlas Copco and Sandvik occupy positions within the premium-tier archetype, leveraging integrated supply chains and electrification roadmaps to anchor Scandinavian infrastructure tenders. Rammer exemplifies the regional specialist model through aftermarket channel dominance in Nordic mining corridors where equipment uptime commands premium service contracts. These three entities represent contrasting strategic postures—technology-led premium positioning, captive materials control, and service-intensive regional anchoring—without implying specific market share claims or operational details beyond their visible industry positioning.
| Leading Market Players |
|---|
| Soosan |
| Rammer |
| Atlas Copco |
| Montabert |
| Furukawa |
| Indeco |
| Sandvik |
| NPK |
| EVERDIGM |
| Others |
Supply Flow & Price Mechanics
Tungsten price volatility cascades through breaker tool steel costs into three distinct pricing tiers, compressing margins for European manufacturers while amplifying procurement leverage for Australian mining operators with captive service contracts. The EU Green Deal's bio-hydraulic fluid mandates add formulation premiums that stratify final equipment quotations across compliance-bound and exempt geographies.
Pricing Analysis
The bundled-versus-unbundled service split separates premium European manufacturers from Asian fabricators, with Atlas Copco and Sandvik anchoring long-term service contracts that embed predictive maintenance telemetry while mid-scale competitors transact on per-unit spot terms. Price differentiation hinges on captive alloy supply chain control and ISO 18752 hydraulic hose certification tier, with Tier 4 Final compliance costs in the United States forcing diesel carrier downsizing that constrains breaker power specifications. Cost compression in the standard tier intensifies as Chinese manufacturers scale variable-displacement pump integration. Construction contractors in India's National Infrastructure Pipeline exhibit highest price sensitivity, while Australian underground mining operators prioritize uptime guarantees over acquisition cost.
Supply Chain Analysis
China's GB standards on construction machinery noise and exhaust function as de facto local-content rules, redirecting component sourcing toward domestic valve block and accumulator manufacturers serving Belt and Road project exporters. Tungsten processing concentrates in China and Vietnam, with molybdenum smelting anchored in Chile and the United States, creating dual-hemisphere raw material dependencies for premium tool steel production. Single-source vulnerability in tungsten carbide powder supply exposes European manufacturers to export quota disruptions. Distribution runs through mining equipment distributors in Perth and Houston, aftermarket platform aggregators in Western Australia, and direct manufacturer portals consolidating multi-site fleet purchasing for German urban demolition contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The hydraulic hammer market functions as a regulatory compounder, with the EU Green Deal's machinery emissions standards forcing fleet replacement cycles that expand electrified attachment demand across European public procurement.
For Market Incumbents: Deploy captive alloy supply chain control to anchor premium positioning against emerging Asian fabricators scaling variable-displacement pump integration. Deepen backward integration into tungsten carbide processing to buffer raw material availability shocks from Chinese export quota volatility. Expand predictive maintenance telemetry deployment to capture outcome-based service revenue streams from Australian mining operators prioritizing equipment uptime guarantees over acquisition cost. For New Entrants and Emerging Players: The EU Green Deal in Europe opens a window for electrified hammer variants compatible with battery-powered carriers serving German urban demolition contractors under REACH-mandated bio-hydraulic fluid requirements. India's National Infrastructure Pipeline presents the most penetrable geography, with price-sensitive but volume-intensive tunneling and highway expansion procurement favoring versatile breaker specifications compatible with mixed fleet carriers. Pursue distributor acquisition in underpenetrated infrastructure corridors to establish aftermarket service anchoring before incumbent platform consolidation accelerates. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized assembly houses outsourcing tool steel forging while integrating digital telematics platforms for predictive maintenance monetization. Long-term viability favors entities controlling backward integration into critical mineral processing or commanding regional aftermarket density in mining corridors where equipment uptime commands premium service contracts. Watch for inflection signals in battery energy density improvements that close the performance gap for continuous high-cycle quarrying and mining applications, displacing diesel-hydraulic dominance in heavy-duty segments.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Tungsten Processing | Captive carbide supply secures tool steel margins against Chinese export quota volatility. |
| Electrification Roadmap Acceleration | EU Green Deal compliance anchors Scandinavian infrastructure tender participation. |
| Digital Telematics Platform Deployment | Hammer-mounted vibration sensors enable predictive maintenance revenue from Australian mining fleets. |
| Distributor Acquisition in India | First-mover positioning in National Infrastructure Pipeline tunneling procurement concentrates volume. |
| Bio-Hydraulic Fluid Compatibility Investment | REACH-mandated synthetic fluid reformulation secures German urban demolition contractor loyalty. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with maintenance directors at Australian underground mining operations, OEM procurement teams at European construction equipment manufacturers, aftermarket service heads in Nordic mining corridors, and plant engineers at Chinese hydropower construction sites with secondary validation against customs trade data, SEC 10-K filings from listed equipment manufacturers, ISO certification registries, and EU public procurement contract databases. Bottom-up carrier fleet sizing and top-down infrastructure investment flow estimates were triangulated to anchor demand projections.
Segment-weighting across the projection horizon applied differential growth assumptions to demolition hammers, pile drivers, concrete breakers, and post drivers by carrier weight class, duty-cycle intensity, and electrification compatibility tier. CAGRs were derived from fitted logistic adoption curves for electrified variants overlaid on linear extrapolation of hydraulic equipment replacement cycles. Industry-specific forecast inputs included ore grade decline trajectories at Australian hard-rock operations and offshore wind foundation installation schedules in the North Sea and Baltic regions.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt battery energy density breakthroughs or Chinese tungsten export quota disruptions. The analytical envelope assumes stable regulatory enforcement timelines for EU Green Deal machinery standards and GB standards compliance pathways for Belt and Road equipment exporters. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Concrete NDT Testing Equipment Market
Construction Equipment
LAMEA Mini Excavators Market
Construction Equipment
Plasma Cutting Machine Market
Construction Equipment
Europe Construction Equipment Rental Market
Construction Equipment
Europe Road Marking Machine Market
Construction Equipment
Japan Waterjet Cutting Machines Market
Construction Equipment
Drone-Based Solutions in Construction Market
Construction Equipment
Cold Heading Machine Market
Construction Equipment
Europe Multi Attachment Loaders Market
Construction Equipment
Solar Pile Driving Equipment Market
Construction Equipment
Stick Welding Electrode Market
Construction Equipment
Electric Excavators Market
Construction Equipment
Latin America Heavy Construction Equipment Market
Construction Equipment
Welding Equipment Market
Construction Equipment
Crossover Ladder Market
Construction Equipment
Drilling Machine Market