
 Australia Concrete Pump Market | 2026-2036
Australia Concrete Pump Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Concrete Pump Market Outlook
Skilled concrete pump operator shortages across Queensland and Western Australia is unwinding project timelines and elevating equipment utilization rates. Meales Concrete Pumping leverages its national fleet network to sustain coverage in remote mining infrastructure corridors. CPE Machinery Pty Ltd anchors its position through Putzmeister's technical service density in capital cities. Zoomlion Australia competes on cost-adjusted specifications for mid-tier contractors in Melbourne's commercial build-to-rent pipeline.
An Australia concrete pump is a hydraulically powered machine designed to transport liquid concrete through pipeline systems at pressures typically ranging from 1,000 to 2,500 psi, enabling precise placement in structurally complex or vertically extended environments. Its primary industrial purpose is to eliminate manual wheelbarrow distribution, reduce pour times, and ensure consistent concrete quality in large-scale construction. Truck-mounted boom pumps dominate capital city commercial work where reach height and setup speed determine contract awards. Trailer-mounted units occupy the residential and regional infrastructure tier where mobility constraints and lower pour volumes favor towable configurations. Line pumps specialize in foundations and slab work across Sydney's detached housing estates where access clearance limits boom deployment.
The Australian Building Codes Board enforces structural performance standards that mandate concrete placement integrity documentation, directly shaping pump calibration and operator certification requirements. Safe Work Australia protocols govern elevated work platforms and pressurized equipment, compelling fleet operators to maintain rigorous maintenance schedules and incident reporting systems. The National Construction Code's evolving energy provisions influence diesel engine specifications and electric hybrid adoption timelines. Stakeholders must weigh capital deployment between boom pump capacity expansion and line pump flexibility as residential density shifts alter pour profiles across state planning zones.
Market Dynamics
The National Construction Code's energy efficiency provisions are compressing diesel pump deployment timelines while elevating electric-hybrid procurement premiums across Australian fleet operators.
Growth Catalysts
- Infrastructure Megaprojects:New South Wales and Victoria transport corridors are absorbing boom pump capacity at volumes that sustain manufacturer order backlogs through extended construction windows.
- Building Code Stringency:Australian Building Codes Board structural performance standards mandate placement integrity documentation, forcing pump calibration upgrades and certified operator deployment.
- High-Rise Residential Density:Sydney's vertical construction corridor compresses pour schedules, creating demand for rapid-setup boom configurations with extended reach specifications.
Market Restraints
- Diesel Engine Cost Volatility:Tier 4 Final emission compliance hardware adds capital burden to fleet replacement cycles, squeezing mid-tier contractor margins.
- Operator Supply Concentration:Queensland and Western Australia skilled concrete pump operator shortages limit equipment utilization expansion regardless of machine availability.
- Electric Infrastructure Gap:Remote mining corridors lack grid capacity for hybrid pump charging, tethering zero-emission adoption to capital city perimeters.
Strategic Opportunities
- Western Australia Mining Revival:Iron ore and lithium infrastructure corridors outside Perth metro present underpenetrated demand for trailer-mounted units with desert-rated specifications.
- Telematics-Converged Fleet Management:Real-time pressure monitoring integrated with predictive maintenance algorithms enables outcome-based service contracting for risk-averse contractors.
- Safe Work Australia Protocol Alignment:Elevated work platform certification expansion creates regulatory tailwind for operators investing in incident reporting automation and maintenance documentation systems.
Industry Challenges
- Certification Pipeline Bottleneck:Concrete pump operator licensing through state-based high-risk work frameworks faces training facility capacity constraints, extending workforce onboarding timelines.
- Capex Intensity for Hybrid Transition:Electric boom pump procurement requires parallel charging infrastructure investment that strains regional contractor balance sheets.
- Legacy Fleet Integration Friction:Older diesel units lack CAN bus compatibility for telematics retrofits, fragmenting fleet data visibility across mixed-vintage deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Concrete Pump Market |
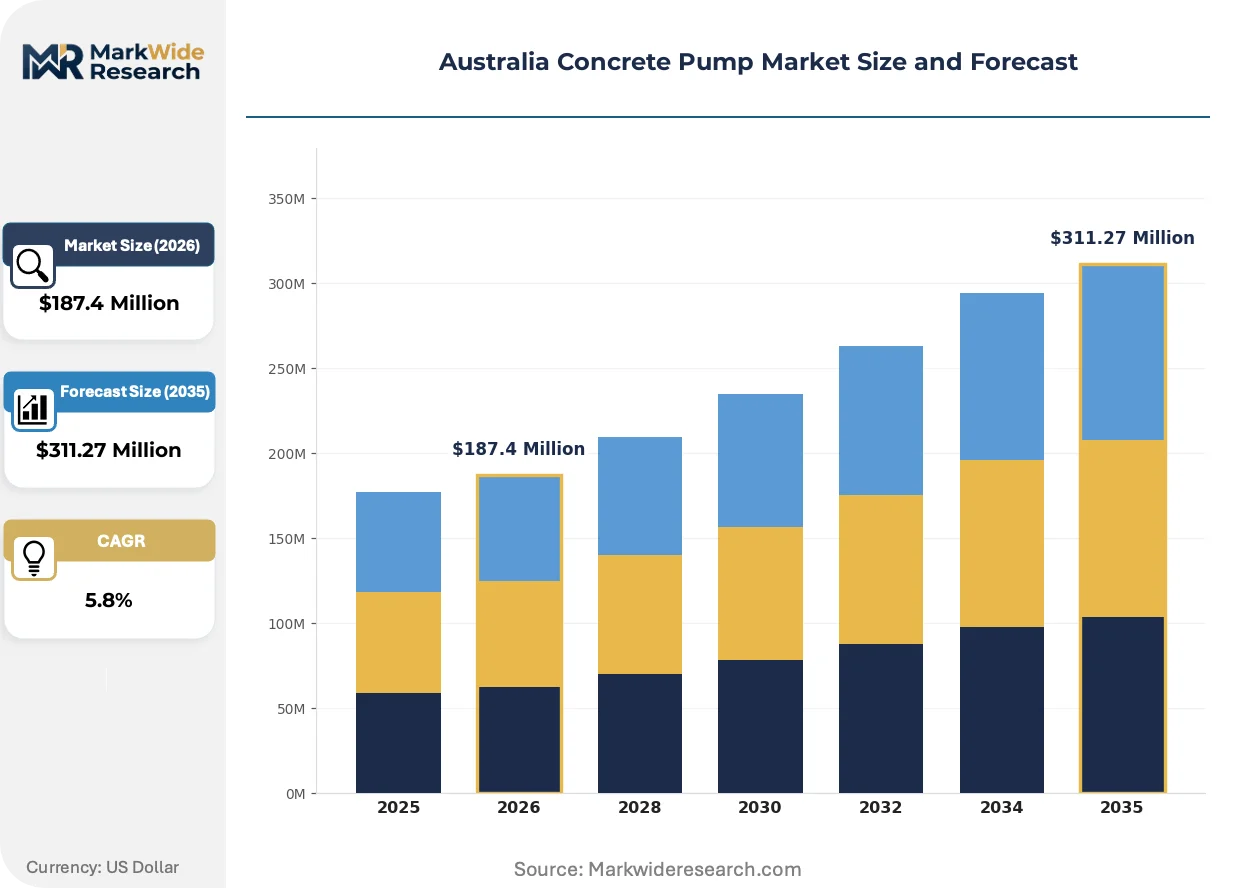
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
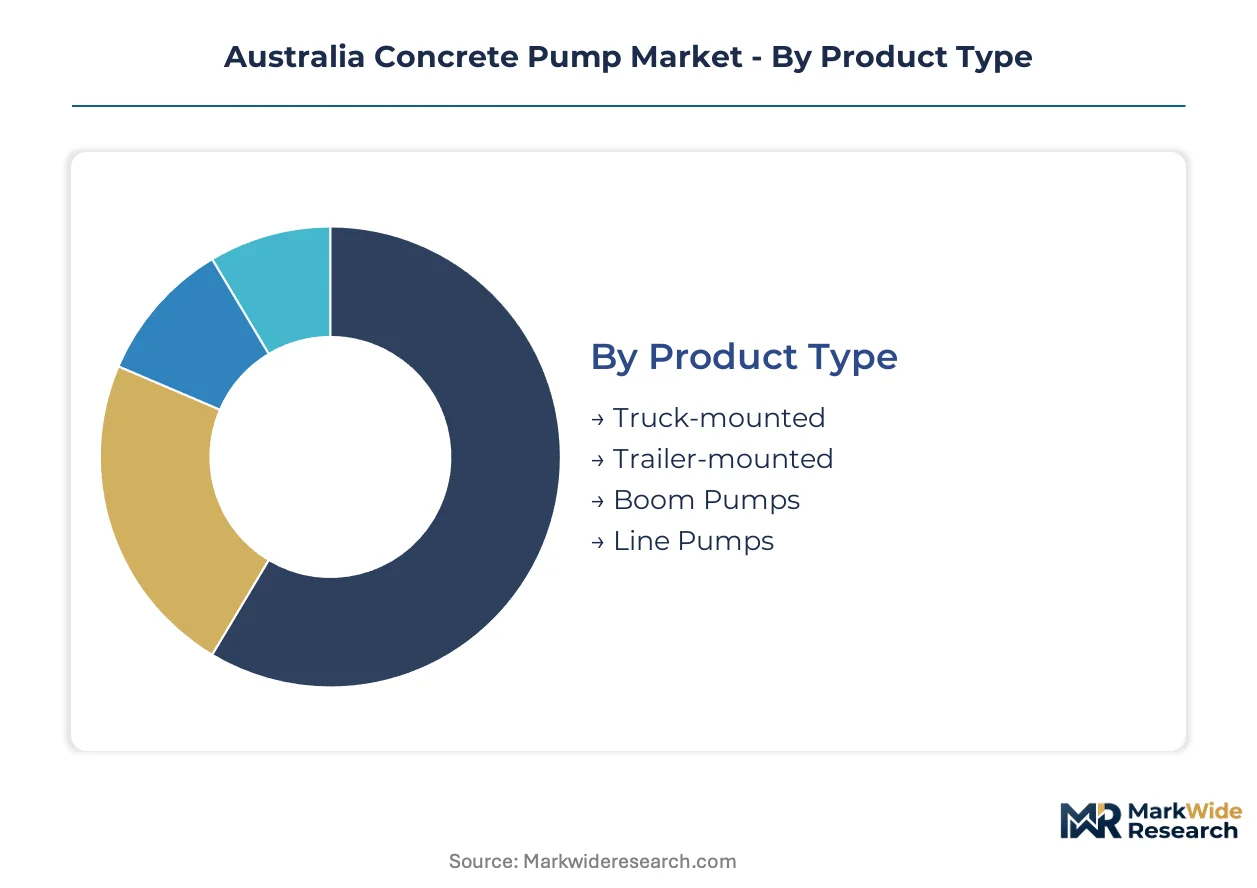
| Segmentation | Product Type: Truck-mounted, Trailer-mounted, Boom Pumps, Line Pumps End User: Construction, Infrastructure, Residential, Commercial Size: Small, Medium, Large, Enterprise Application: High-rise Buildings, Bridges, Roads, Foundations |
| Companies Covered | Meales Concrete Pumping, CPE Machinery Pty Ltd (Putzmeister AU), Flowcrete Australia, Alliance Concrete Pumps Australia, DY Concrete Pumps Australia, Zoomlion Australia, Premier Concrete Pumping, Jacon Equipment Pty Ltd, Callaghan Concrete Pumps Pty Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Concrete Pump Market Strategic Shifts
Equipment intelligence and emission compliance are restructuring competitive advantage around data capture capability and energy transition readiness rather than brute hydraulic specification.
Telematics-integrated pump control systems are supplanting manual pressure gauges and analog flow meters in capital city commercial fleets. Tier-one contractors in Melbourne's build-to-rent pipeline are specifying factory-installed remote monitoring as a contract precondition. This capability compression is collapsing reactive maintenance intervals and enabling usage-based equipment financing structures.
The National Construction Code's evolving energy provisions are mandating documented carbon intensity for construction equipment procurement above threshold contract values. Fleet operators must now submit diesel consumption baselines and electrification transition roadmaps for public infrastructure tenders. Sydney and Brisbane municipal authorities are piloting zero-emission equipment mandates for projects within designated airshed zones.
Service unbundling is fragmenting traditional full-maintenance lease structures. Contractors in high-rise residential corridors are separating equipment rental from operator provision and maintenance execution, sourcing each component through specialized vendors. This procurement decomposition is most visible in Victoria where project labor agreements specify union-certified operators independent of fleet ownership.
Australia Concrete Pump Market Segmentation
Pump configuration and deployment scale determine contractor bidding power across Australia's state-tier procurement systems. Segment boundaries align with project risk profiles, operator certification tiers, and fleet financing structures that shape equipment procurement decisions.
Product Type:
Margin pools concentrate in boom pump configurations where reach specifications command rental premiums and longer contract tenures.
- Truck-mounted:Self-propelled chassis integrate hydraulic boom articulation with on-board pumping systems, enabling rapid site repositioning. Sydney's high-rise residential corridor absorbs these units where vertical pour schedules compress setup windows and mobility constraints eliminate trailer alternatives.
- Trailer-mounted:Towable platforms separate pumping hardware from transport vehicles, reducing capital outlay for regional contractors. Western Australia mining infrastructure corridors outside Perth metro deploy these units where desert-rated specifications and lower utilization rates favor flexible ownership models.
- Boom Pumps:Articulated arm configurations extend horizontal and vertical reach for complex placement geometries. Melbourne's build-to-rent pipeline specifies extended-reach variants for podium-level pours.
- Line Pumps:Flexible hose systems navigate confined access corridors for foundation and slab work. Sydney's detached housing estates favor these units where clearance limits preclude boom deployment.
Truck-mounted configurations hold installed capacity. Trailer-mounted units are rotating up the share rankings.
End User:
Application risk profiles segment procurement behavior across public infrastructure mandates and private development timelines.
- Construction:General contracting tier spans commercial and residential verticals with mixed fleet requirements. Tier-one operators in New South Wales and Victoria maintain diversified pump portfolios to capture cross-sector opportunities.
- Infrastructure:Transport corridor megaprojects absorb boom pump capacity at volumes sustaining manufacturer order backlogs. Safe Work Australia protocols govern elevated work platforms, compelling fleet operators to maintain rigorous maintenance schedules.
- Residential:Detached housing and low-rise multi-unit developments favor line pumps and trailer-mounted units. Queensland's skilled operator shortages limit utilization expansion regardless of machine availability.
- Commercial:Build-to-rent and speculative office developments specify rapid-setup configurations. Municipal zero-emission equipment mandates in Sydney and Brisbane airshed zones filter procurement toward hybrid-capable fleets.
Infrastructure commands the steepest expansion trajectory. Residential is gaining share fastest.
Size:
Fleet scale determines financing access and service contract eligibility across Australia's equipment leasing networks.
- Small:Owner-operator configurations with 1-3 units serve regional residential markets. These operators face capital constraints for Tier 4 Final emission compliance hardware.
- Medium:Multi-unit fleets spanning 4-10 pumps capture mid-tier commercial contracts. Victorian project labor agreements specify union-certified operators independent of fleet ownership.
- Large:11-25 unit deployments sustain national coverage networks. Meales Concrete Pumping leverages this scale for remote mining corridor penetration.
- Enterprise:25+ unit fleets integrate telematics-converged management systems. Real-time pressure monitoring enables outcome-based service contracting for risk-averse contractors.
Enterprise-scale operators hold installed capacity. Medium-tier fleets are climbing the fastest.
Application:
Structural complexity and access constraints determine pump specification requirements across project types.
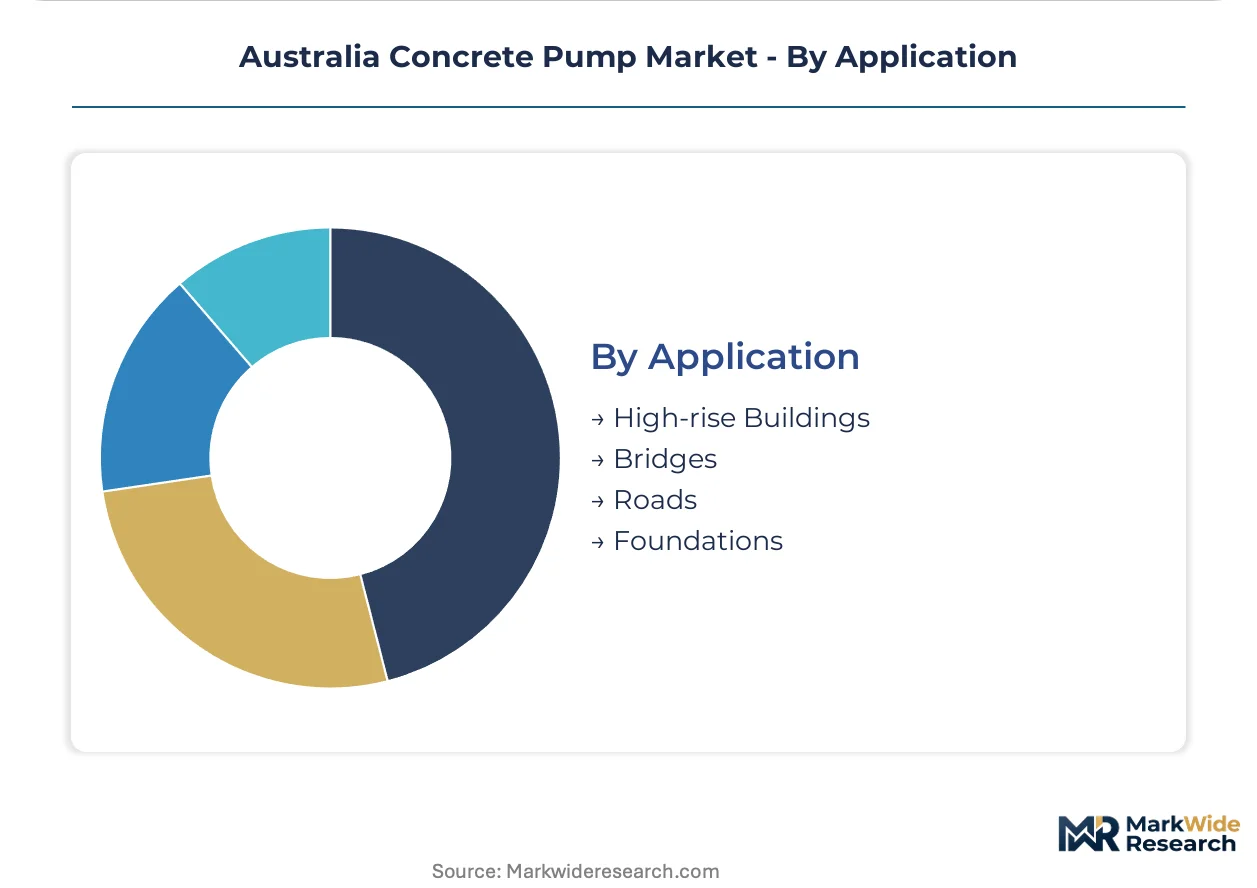
- High-rise Buildings:Vertical construction demands extended-reach boom pumps with rapid-setup configurations. Australian Building Codes Board structural performance standards mandate placement integrity documentation.
- Bridges:Span construction requires specialized boom articulation for pier and deck placement. Remote locations tether deployment to trailer-mounted support units.
- Roads:Linear infrastructure favors line pumps for barrier and drainage pours. Regional road maintenance contracts absorb smaller fleet operators.
- Foundations:Slab and footing work across Sydney's housing estates deploys line pumps where access clearance limits boom deployment.
High-rise applications hold installed capacity. Foundation work is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
New South Wales and Victoria deploy truck-mounted boom pumps for high-rise compression schedules, while Western Australia and Queensland favor trailer-mounted flexibility for mining corridors and regional infrastructure gaps.
New South Wales
Sydney's vertical residential corridor drives demand for rapid-setup boom configurations with extended reach specifications. The Australian Building Codes Board mandates placement integrity documentation for structural performance compliance. Parramatta and Chatswood high-rise clusters absorb the densest boom pump deployment in the national market.
Victoria
Melbourne's build-to-rent pipeline specifies telematics-integrated pumps as contract preconditions for tier-one contractors. Safe Work Australia protocols govern elevated work platforms across commercial developments. The Docklands and Southbank precincts concentrate enterprise-scale fleet operations serving dense urban pours.
Queensland
Skilled concrete pump operator shortages constrain utilization expansion regardless of machine availability across Brisbane and Gold Coast corridors. The state's high-risk work licensing framework faces training facility capacity bottlenecks. Regional road maintenance contracts absorb smaller trailer-mounted fleets outside metropolitan perimeters.
Western Australia
Iron ore and lithium infrastructure corridors outside Perth metro present underpenetrated demand for desert-rated trailer-mounted specifications. Remote mining sites lack grid capacity for hybrid pump charging, tethering zero-emission adoption to capital city boundaries. The Pilbara region sustains specialized fleet requirements for extreme climate durability.
Australia Concrete Pump Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with national fleet networks commanding premium positioning against regional owner-operators. The market structure reflects capital intensity barriers and operator certification requirements that favor scale. Three archetypes dominate: enterprise-scale fleet operators with telematics-converged management, manufacturer-anchored distributors with technical service density, and cost-positioned challengers competing on adjusted specifications. Competitive moves concentrate on geographic coverage expansion and service unbundling strategies that separate equipment rental from operator provision.
Among national-scale fleet operators, Meales Concrete Pumping and Premier Concrete Pumping occupy positions sustained by remote corridor penetration capabilities. CPE Machinery Pty Ltd anchors the manufacturer-linked distribution tier through Putzmeister's technical service density in capital cities. Zoomlion Australia exemplifies the specification-adjusted challenger archetype competing for mid-tier contractor contracts in Melbourne's commercial pipeline.
| Leading Market Players |
|---|
| Meales Concrete Pumping |
| CPE Machinery Pty Ltd (Putzmeister AU) |
| Flowcrete Australia |
| Alliance Concrete Pumps Australia |
| DY Concrete Pumps Australia |
| Zoomlion Australia |
| Premier Concrete Pumping |
| Jacon Equipment Pty Ltd |
| Callaghan Concrete Pumps Pty Limited |
| Others |
Value Chain & Pricing Dynamics
Project-based rental contracts with embedded operator provision lock in supply access for tier-one contractors while compressing price visibility across Australia's concrete pump market. This structure concentrates procurement power with enterprise-scale fleet operators who bundle telematics-enabled maintenance into multi-year agreements.
Pricing Analysis
Long-term offtake agreements dominate infrastructure megaprojects where transport corridor contractors secure boom pump capacity across extended construction windows. Price differentiation separates premium-tier telematics-integrated fleets from standard diesel configurations and economy-grade trailer-mounted units without remote monitoring. Cost compression in the mid-tier segment is intensifying because Tier 4 Final emission compliance hardware adds capital burden to fleet replacement cycles. Residential contractors exhibit the highest price sensitivity, while infrastructure developers prioritize uptime guarantees over per-hour rental rates.
Supply Chain Analysis
Germany and China anchor hydraulic system manufacturing for Australian concrete pump imports, with boom articulation components sourced from specialized European fabricators. Australian fleet assembly draws from Japanese diesel engines, Korean hydraulic pumps, and Chinese steel chassis components. Single-source vulnerability concentrates in advanced telematics control modules where European suppliers dominate firmware development. Distribution runs through manufacturer-anchored distributors in capital cities, with regional penetration dependent on third-party logistics partnerships for remote mining corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
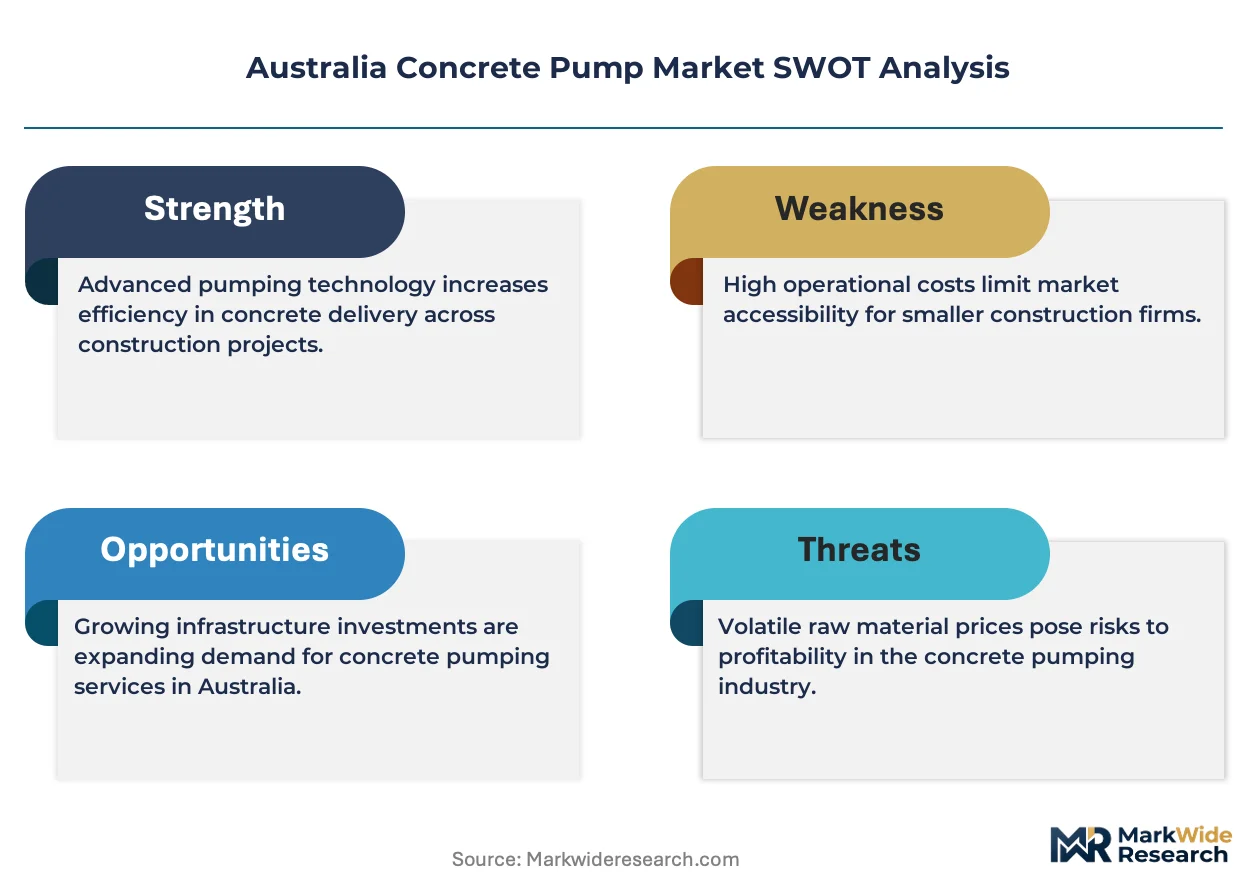
Australia's concrete pump market sits in early-cycle expansion as infrastructure megaprojects across New South Wales and Victoria absorb capacity at volumes sustaining manufacturer order backlogs through extended construction windows.
For Market Incumbents: Consolidate fleet scale advantages through telematics-converged management systems that enable outcome-based service contracting. Acquire specialized operators in Western Australia mining corridors to preempt challenger entry. Operator certification pipeline bottlenecks present a defensive moat against mid-tier expansion. For New Entrants and Emerging Players: Anchor in Queensland's skilled operator shortage gap by establishing training facility partnerships with state high-risk work licensing frameworks. Target trailer-mounted deployments in regional road maintenance contracts outside Brisbane metro where incumbent coverage thins. Lead with desert-rated specifications for Pilbara lithium infrastructure corridors. For Investors and Strategic Acquirers: Capital is best deployed toward enterprise-scale fleet operators with proven remote corridor penetration and telematics integration capabilities across the medium-term horizon. Monitor Safe Work Australia protocol expansions around elevated work platform certification as an inflection signal for regulatory-compliant fleet premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Telematics Fleet Integration | Real-time pressure monitoring enables predictive maintenance contracts with tier-one infrastructure contractors. |
| Operator Certification Expansion | Training facility partnerships with Queensland's high-risk work framework address supply-constrained utilization growth. |
| Hybrid Pump Procurement | Electric-hybrid adoption aligns with National Construction Code energy provisions and Sydney municipal zero-emission mandates. |
| Regional Coverage Network Buildout | Desert-rated trailer-mounted fleets penetrate Western Australia mining corridors outside Perth metro perimeter. |
| Service Unbundling | Separating equipment rental from operator provision captures Victorian project labor agreement procurement flows. |
Study Parameters
The analysis maps truck-mounted boom pumps, trailer-mounted units, line pumps, and telematics-integrated configurations, each validated through fleet operations directors, concrete pump operators, construction procurement managers, and equipment financing specialists. Primary interviews with maintenance heads at national-scale fleet operators and regional owner-operators combined with secondary validation through Australian Bureau of Statistics construction activity data, Safe Work Australia incident reporting databases, National Construction Code amendment registers, and state-based high-risk work licensing records. Bottom-up equipment deployment counts triangulated against top-down construction output forecasts.
Consistency checks validated volume and value outputs against Australian construction equipment import data and diesel engine displacement trends across the projection horizon. The analytical framework modeled pump configuration type, fleet scale tier, end-use application, and geographic deployment density. CAGRs derived from equipment replacement cycle analysis and infrastructure project pipeline tracking, with inputs including Australian Building Codes Board structural performance standard amendments and state-level transport corridor investment commitments.
Decision-makers should treat outputs as directional under assumptions of continued infrastructure megaproject execution and stable diesel emission compliance timelines; material deviation in public investment cycles or rapid electric infrastructure buildout would warrant model refresh. Recalibration cycles align with material shifts in National Construction Code energy provisions and state high-risk work licensing framework amendments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Fully Automatic Metal Band Saw Machine Market
Construction Equipment
Static Crane Market
Construction Equipment
China Construction Equipment Market
Construction Equipment
Pressure Vessel Market
Construction Equipment
North America and Europe Snow Blowers Market
Construction Equipment
Mexico Flexible Concrete Vibrator Market
Construction Equipment
India Construction Equipment Market
Construction Equipment
Pre-Owned Construction Equipment Market
Construction Equipment
Global Asphalt Crushers Market
Construction Equipment
Shot Peening Machine Market
Construction Equipment
Construction Site Preparation Equipment Market
Construction Equipment
Middle-East and Africa Anchors and Grouts Market
Construction Equipment
Industrial and Commercial Floor Scrubbers Market
Construction Equipment
Global Pile Driving Equipment Market
Construction Equipment
Europe Excavator and Loaders Market
Construction Equipment
Press Brakes Market