
 Excavator Wheels Market | 2026-2036
Excavator Wheels Market Size, Share, and Industry Trends Forecast 2026-2036
Excavator Wheels Market Analysis
Dealer networks serving mid-size contractors is fragmenting across North America and Europe as direct OEM procurement portals and regional parts distributors compete for aftermarket volume. Caterpillar Inc. leverages its captive dealer system to control replacement wheel flows and service bundling. Komatsu Ltd. anchors its position through integrated supply agreements with mining fleet operators. Sany Group competes aggressively on price through centralized manufacturing in China and direct export channels into Southeast Asia and Africa.
Excavator wheels are load-bearing rotating assemblies mounted to excavator undercarriages or wheeled excavator axles, typically fabricated from forged steel rims with rubber or polyurethane tread compounds vulcanized or bonded to withstand terrain abrasion and static loads exceeding 2000 kg; their primary purpose is to mobilize excavation equipment across finished surfaces, soft ground, or demolition debris without track damage. Steel wheels dominate mining and quarry applications where puncture resistance outweighs surface protection concerns, while polyurethane wheels capture premium share in urban construction zones where floor surface preservation commands higher pricing. Rubber wheels occupy the broad middle across general earthmoving as OEMs balance cost and versatility in standard equipment configurations.
EPA Tier 4 Final emissions rules and the EU F-Gas Regulation shape equipment design standards that cascade into wheel specifications, particularly weight constraints affecting axle loading and fuel efficiency calculations. OSHA workplace safety mandates in the US and REACH chemical compliance in Europe govern tread compound formulations and worker exposure limits during wheel servicing. China's GB standards and MIIT equipment certification requirements dictate domestic manufacturing tolerances that export-oriented suppliers must harmonize for dual-market access. Stakeholders must monitor regulatory divergence between emission-focused jurisdictions and chemical-compliance markets when standardizing wheel platforms across production footprints.
Market Dynamics
Wheel specification decisions now cascade from axle load calculations driven by EPA Tier 4 Final and EU F-Gas weight-constraint mandates, forcing polyurethane and steel variant trade-offs earlier in equipment design cycles than legacy procurement patterns allowed.
Growth Catalysts
- Urban tunneling infrastructure:Polyurethane wheel adoption accelerates among contractors operating in China's metro expansion corridors and European city-center projects where surface preservation commands specification priority.
- EPA Tier 4 Final compliance:Emissions-driven weight reduction targets push OEMs toward lighter wheel assemblies, expanding addressable volume for advanced tread compounds that maintain durability at reduced mass.
- Xuzhou manufacturing clustering:Proximity sourcing between wheel fabricators and final assembly plants compresses logistics costs and inventory carrying requirements for export-oriented equipment builders.
Market Restraints
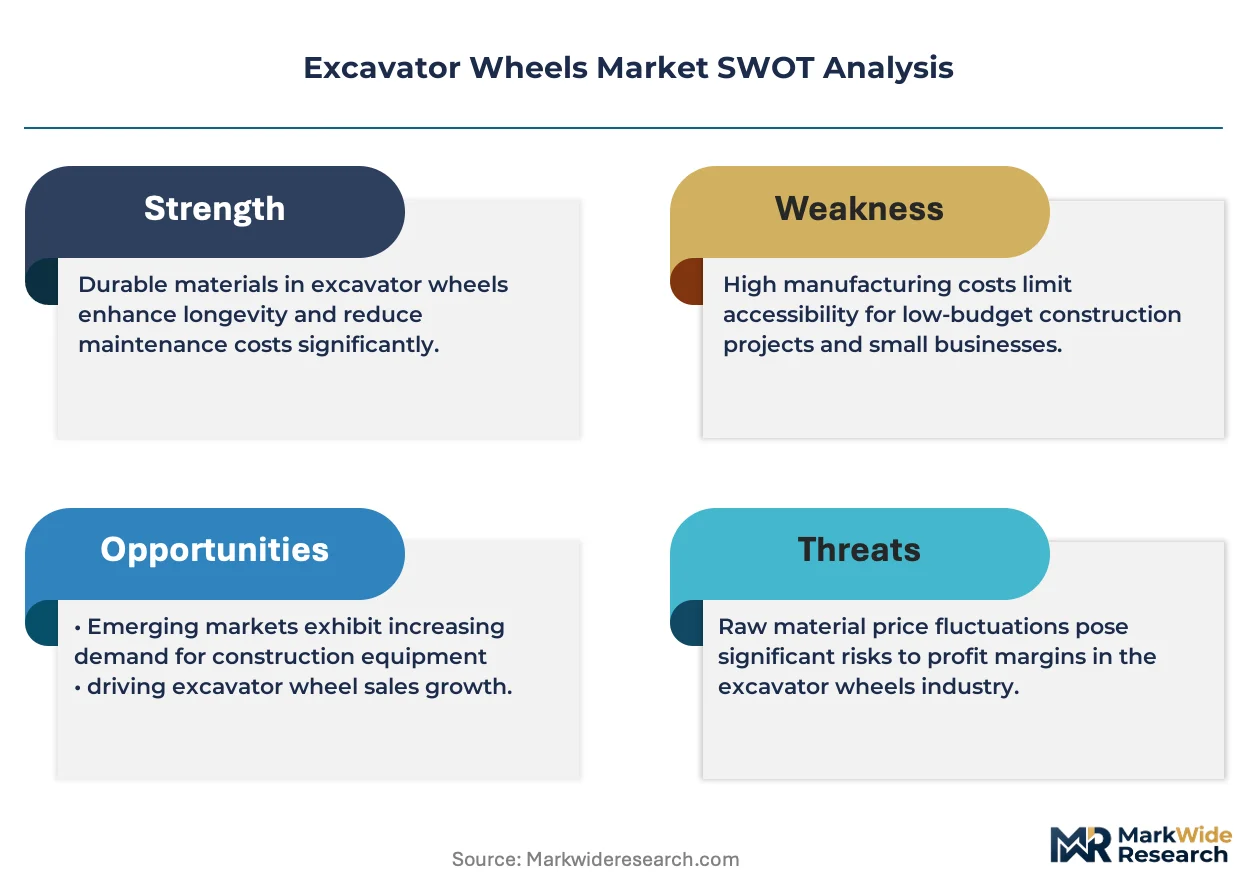
- Steel input cost volatility:Forged rim material prices fluctuate with scrap metal and energy indices, compressing margin predictability for standard-grade wheel producers serving price-sensitive earthmoving segments.
- Polyurethane formulation complexity:REACH chemical compliance in Europe and OSHA exposure limits in the US constrain vulcanization process chemistry, extending qualification timelines for new compound variants.
- Track conversion substitution:Mining fleet operators in quarry applications increasingly specify steel-track undercarriages over steel-wheel configurations for extreme abrasion environments.
Strategic Opportunities
- Remanufacturing service integration:Wheel retreading and rim refurbishment programs capture aftermarket value from mining and demolition fleets seeking to extend asset life beyond single-use replacement cycles.
- Dual-certification harmonization:Suppliers aligning China's GB standards with EU F-Gas and EPA requirements unlock simultaneous access to domestic and export markets without parallel production lines.
- Telematics-enabled predictive replacement:IoT load monitoring and wear-pattern sensors allow wheel suppliers to displace scheduled maintenance with condition-based service contracts.
Industry Challenges
- Vulcanization technician scarcity:Specialized bonding process expertise concentrates among aging workforces in traditional manufacturing regions, constraining capacity expansion for polyurethane wheel output.
- Cross-border certification synchronization:Divergent testing protocols between EPA, EU F-Gas, and China's MIIT create redundant validation burdens for suppliers serving multiple regulatory jurisdictions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Excavator Wheels Market |
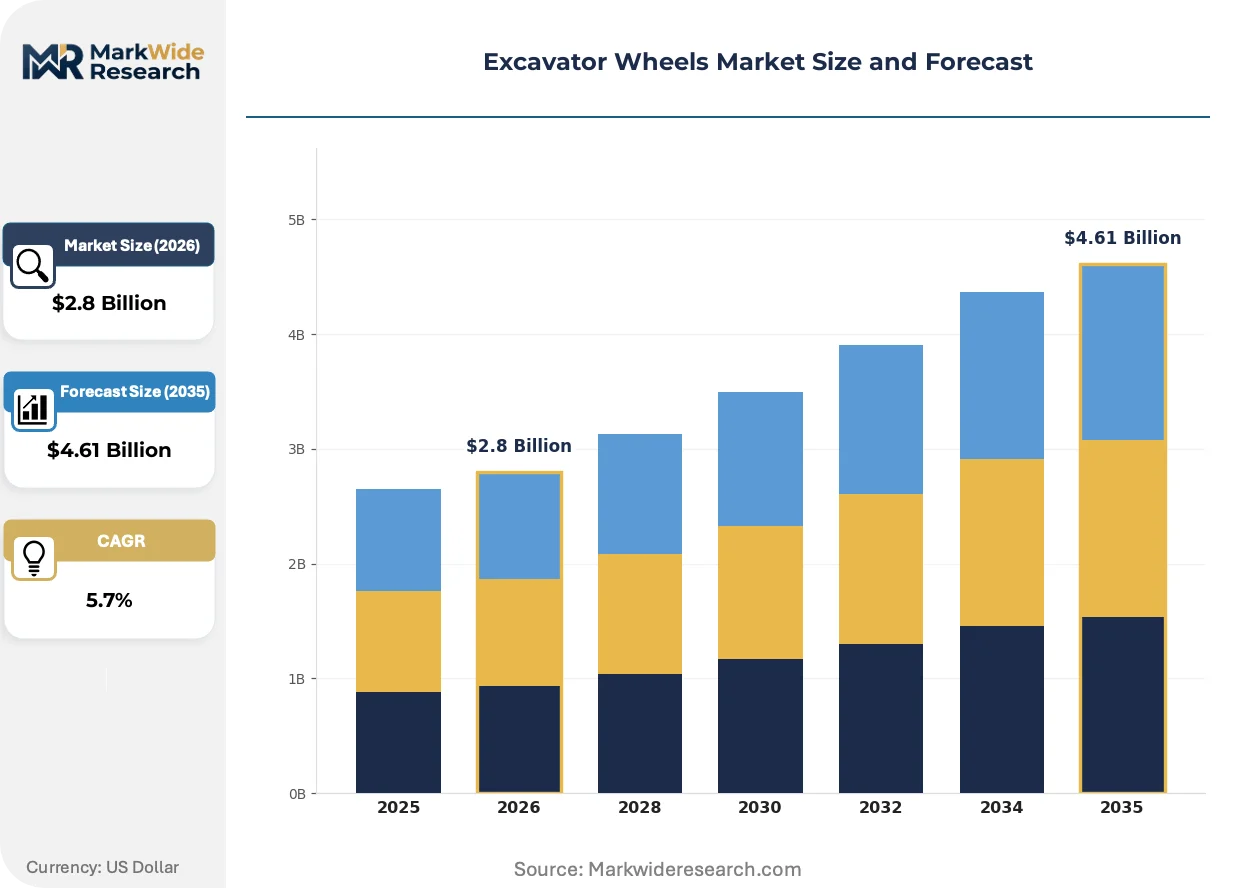
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.61 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rubber Wheels, Steel Wheels, Polyurethane Wheels, Solid Wheels Diameter: 10 Inch, 12 Inch, 14 Inch, 16 Inch Load Capacity: 500 kg, 1000 kg, 1500 kg, 2000 kg Manufacturing Process: Injection Molding, Die Casting, CNC Machining, Metal Stamping |
| Companies Covered | Caterpillar Inc., Komatsu Ltd., Hitachi Construction Machinery Co., Ltd., Volvo Construction Equipment, Liebherr Group, J C Bamford Excavators Ltd., Sany Group, Guangxi LiuGong Machinery Co. Ltd., Xuzhou Construction Machinery Group Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Excavator Wheels Market Emerging Trajectories
Material science advances and connected equipment architectures are compressing replacement cycles while elevating performance specifications across urban construction and resource extraction applications.
Embedded load sensors and tread-wear telemetry is digitizing wheel fleet management for mining operators and large-scale earthmoving contractors. Komatsu and Caterpillar equipment divisions integrate these systems into proprietary service platforms. Real-time axle stress data is digitizing procurement from reactive replacement toward predictive inventory positioning.
EU F-Gas Regulation phase-down schedules now constrain refrigerant choices in wheeled excavator climate systems, indirectly tightening weight budgets that flow through to wheel assembly specifications. Equipment designers respond with lighter rim geometries and denser tread compounds. Urban construction fleets in Germany and France face the steepest compliance ramps.
Rental fleet operators now unbundle wheel replacement from full-service maintenance agreements, shifting specification authority toward procurement departments and away from field mechanics. This compresses supplier relationships toward price-transparent catalog purchasing. The pattern is most visible in North American equipment rental chains serving mid-size contractor customers.
Excavator Wheels Market Segmentation
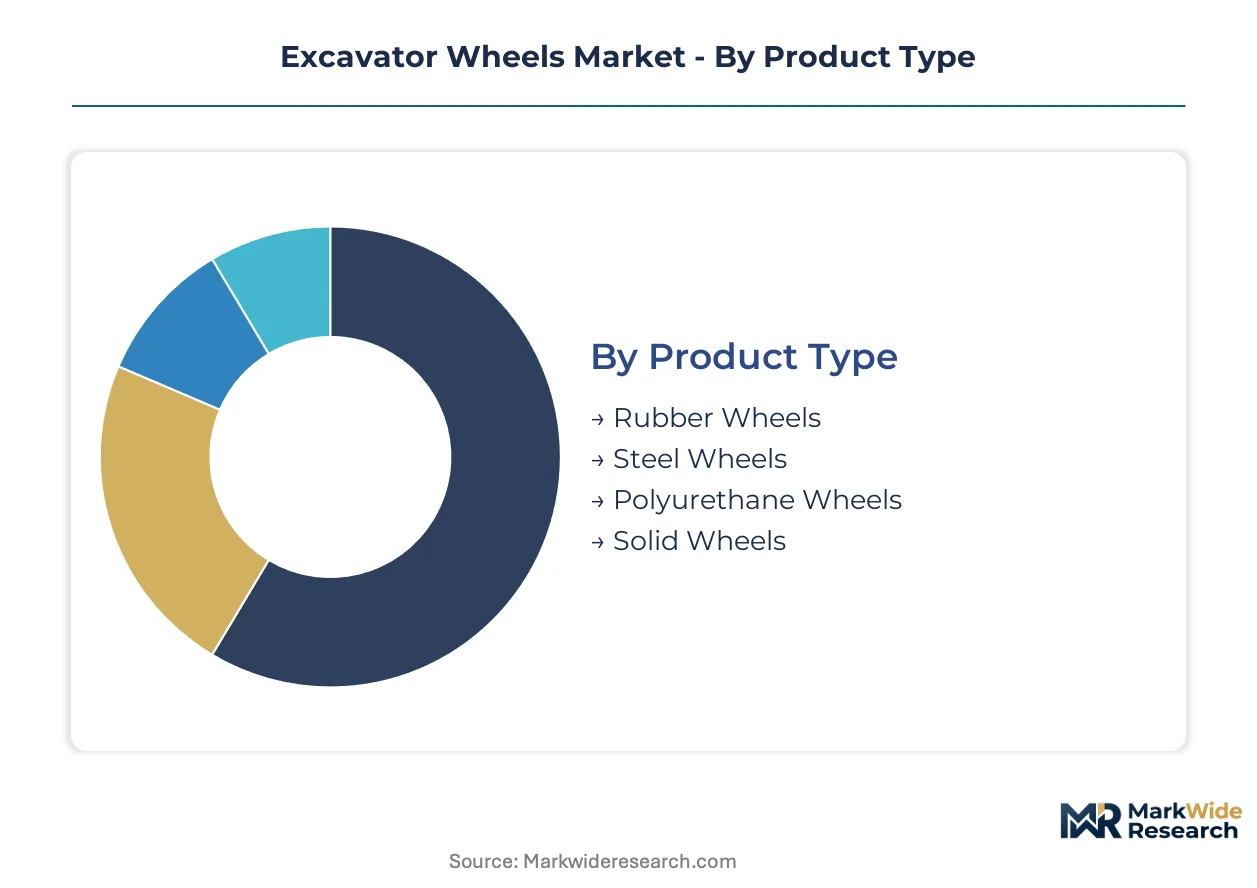
Excavator wheel procurement cycles vary dramatically by material chemistry and application severity, with mining fleets replacing steel wheels on accelerated schedules while urban construction stretches polyurethane service intervals. Specification authority sits with distinct stakeholders across each segment, fragmenting vendor relationships and pricing transparency. Understanding these replacement rhythms and decision hierarchies exposes where suppliers can capture recurring revenue versus one-time specification wins.
Product Type:
Replacement frequency separates these segments sharply, with abrasion-intensive mining applications demanding steel wheel swaps every 18-24 months while polyurethane wheels in tunneling projects often exceed 48-month service lives.
- Rubber Wheels:Vulcanized rubber tread bonded to forged steel rims delivers balanced cost-performance across general earthmoving. Demand clusters with mid-size contractors in North American rental fleets where versatility outweighs specialization.
- Steel Wheels:Solid forged construction eliminates puncture risk in quarry and demolition environments. Mining operators in Australia's Pilbara region and Brazil's Carajás basin specify these for extreme abrasion, accepting surface damage trade-offs.
- Polyurethane Wheels:Cast polyurethane tread compounds preserve finished concrete and epoxy flooring in urban infrastructure. Metro expansion projects in China's Guangzhou and Germany's Munich specify these despite 40-60% cost premiums over rubber.
- Solid Wheels:Monolithic rubber or composite construction eliminates air pressure maintenance for waste handling and scrap yard applications. Demand concentrates with municipal fleets prioritizing uptime over ride quality.
Steel wheels dominate installed base volume in resource extraction. Polyurethane wheels are where expansion concentrates as urban tunneling specifications tighten surface protection mandates.
Diameter:
Cost tiers stratify sharply across diameter classes, with 16-inch wheels commanding premium positioning for heavy-class excavators while 10-inch variants serve compact equipment price sensitivity.
- 10 Inch:Compact utility excavators and skid-steer attachments specify these for tight access jobs. Landscaping contractors and utility maintenance fleets in Japan's dense urban corridors drive specification volume.
- 12 Inch:Mid-size wheeled excavators in the 8-14 ton class standardize this diameter. European rental chains serving municipal infrastructure favor 12-inch configurations for fleet standardization.
- 14 Inch:Heavy construction and road building equipment specifies 14-inch wheels for load distribution. India's National Highways Authority equipment procurement increasingly mandates this diameter class.
- 16 Inch:Large wheeled excavators exceeding 20 tons require 16-inch wheels for axle load compliance. Mining support equipment in South Africa's platinum belt and Chile's copper operations specify these for stability.
12-inch wheels capture the broadest addressable fleet. 16-inch wheels are climbing the fastest as heavy-class equipment penetration expands in resource extraction.
Load Capacity:
Application severity and regulatory weight constraints push specification toward higher load ratings, with 2000 kg wheels displacing lighter alternatives in emission-compliant equipment designs.
- 500 kg:Mini-excavators and compact loaders specify these for light material handling. Japan's equipment manufacturers dominate specification authority for this capacity tier.
- 1000 kg:Standard mid-size excavators in the 10-15 ton operating weight class use 1000 kg rated wheels. China's Xuzhou manufacturing cluster sources these for domestic and Southeast Asian export equipment.
- 1500 kg:Heavy construction applications and material handlers specify 1500 kg wheels for dynamic loading. German OEMs integrate these into wheeled excavator platforms for EU F-Gas weight compliance.
- 2000 kg:Mining support equipment and large demolition machines require 2000 kg static load ratings. Australia's Fortescue Metals Group and BHP specify these for iron ore site preparation fleets.
1000 kg wheels anchor general construction fleet specifications. 2000 kg wheels are gaining share fastest as mining fleet operators upgrade to heavier-class equipment.
Manufacturing Process:
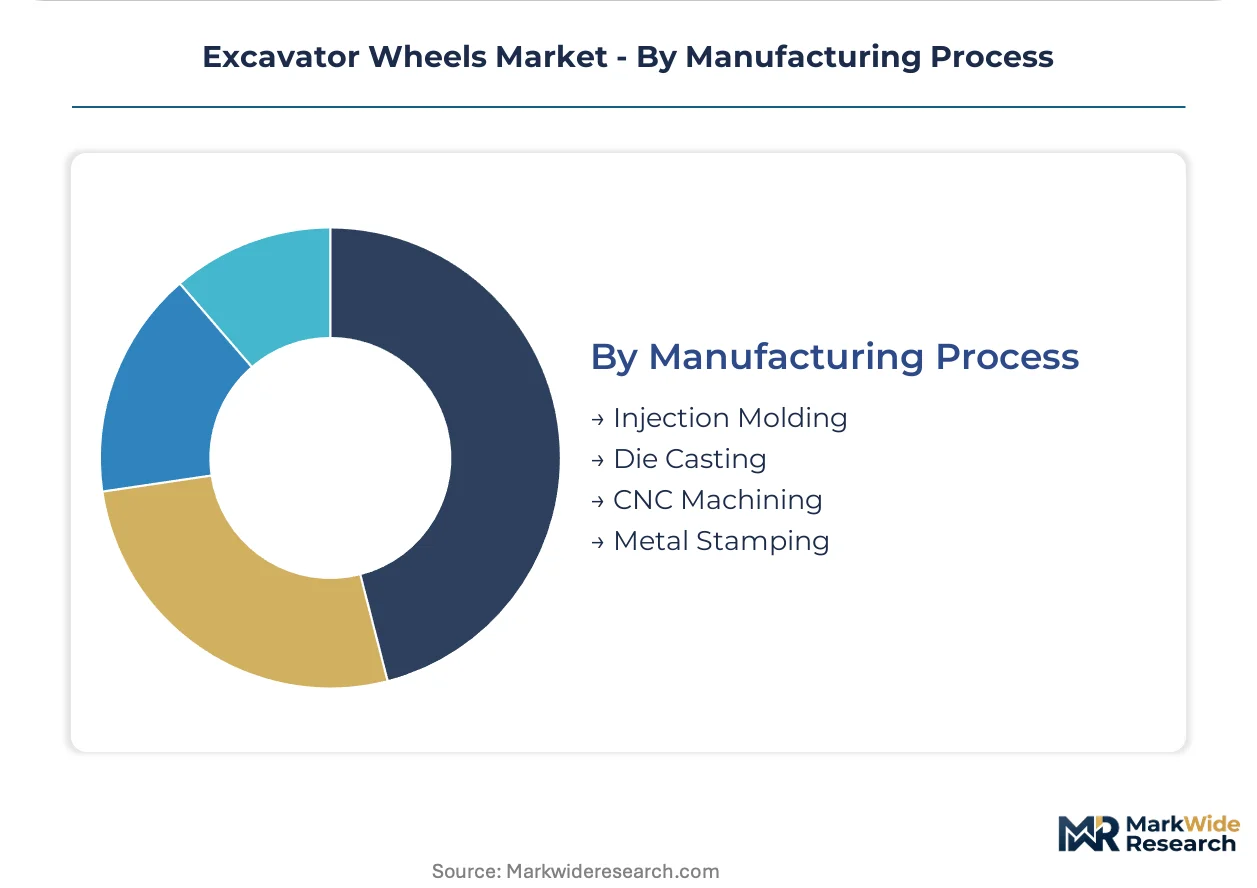
Supply concentration and margin structure diverge across fabrication methods, with injection molding capturing polyurethane wheel volume while CNC machining serves precision rim requirements.
- Injection Molding:Polyurethane wheel tread formation uses liquid casting injection for complex geometries. Suppliers in China's Zhejiang province cluster capacity to serve Xuzhou OEM demand.
- Die Casting:Aluminum rim production for lighter wheel assemblies employs high-pressure die casting. EPA Tier 4 Final weight targets are accelerating die casting adoption for forged rim alternatives.
- CNC Machining:Precision steel rim finishing and bore tolerancing relies on CNC centers. German and Italian equipment suppliers dominate high-precision machining for European OEM qualification.
- Metal Stamping:Rim blanks and structural components use progressive stamping for cost-sensitive volume production. India's Pune and Chennai manufacturing corridors specialize in stamping for domestic and export supply.
Metal stamping commands the highest production volume across cost-sensitive segments. CNC machining is expanding most quickly as precision requirements tighten for telematics-integrated wheel assemblies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in Germany commands 40-60% premiums over Chinese domestic benchmarks, reflecting divergent regulatory compliance burdens and specification stringency. This asymmetry shapes procurement patterns across construction equipment value chains.
United States
EPA Tier 4 Final enforcement tightens axle weight budgets for wheeled excavators deployed in urban demolition. OSHA workplace safety mandates govern tread compound handling protocols during wheel servicing operations. Equipment rental chains in Texas and Florida unbundle wheel replacement from full-service agreements, shifting purchasing authority toward procurement departments.
Germany
EU F-Gas Regulation phase-down schedules constrain climate system refrigerant choices, cascading into lighter wheel assembly specifications for compliance. REACH chemical restrictions limit vulcanization process chemistry for polyurethane tread production. Munich metro expansion projects specify premium polyurethane wheels for tunneling surface preservation.
China
MIIT equipment certification requirements and GB standards dictate domestic manufacturing tolerances for export-oriented suppliers. Xuzhou manufacturing clusters concentrate wheel fabricators adjacent to final assembly plants, compressing logistics costs. Guangzhou metro corridors drive polyurethane wheel specification volume for urban infrastructure.
Australia
Mining fleet operators in Western Australia's Pilbara region specify steel wheels for iron ore site preparation amid extreme abrasion environments. The country's national equipment safety regulator enforces load rating compliance for heavy-class excavator deployments. Perth-based procurement hubs coordinate replacement cycles for remote mining operations.
Brazil
Carajás basin mining operations anchor steel wheel demand for quarry and extraction applications. ANVISA chemical compliance governs imported tread compound formulations for wheel refurbishment programs. São Paulo construction equipment distributors serve as regional stocking points for South American aftermarket volume.
Excavator Wheels Market Vendor Landscape
Integrated equipment OEMs and specialized component fabricators split the market along captive-versus-independent supply lines. Consolidation pressure concentrates among mid-tier wheel suppliers serving price-sensitive earthmoving segments. Three archetypes dominate: full-line construction equipment manufacturers with captive wheel production, regional stamping specialists supplying rim blanks, and polyurethane compounders focused on urban infrastructure specifications. Geographic expansion and backward integration into rim forging represent the dominant competitive vectors.
Among Asia-Pacific-based equipment manufacturers, Sany Group and Xuzhou Construction Machinery Group Co. Ltd. occupy positions reflecting scale-driven export strategies. Caterpillar Inc. exemplifies the integrated OEM archetype through captive dealer network control. These three anchors illustrate divergent pathways: Chinese manufacturers compete on centralized production economics, while US-based players leverage service bundling and replacement part flow management.
| Leading Market Players |
|---|
| Caterpillar Inc. |
| Komatsu Ltd. |
| Hitachi Construction Machinery Co., Ltd. |
| Volvo Construction Equipment |
| Liebherr Group |
| J C Bamford Excavators Ltd. |
| Sany Group |
| Guangxi LiuGong Machinery Co. Ltd. |
| Xuzhou Construction Machinery Group Co. Ltd. |
| Others |
Supply Flow & Price Mechanics
Tariff exposure on Chinese steel rim imports determines both pricing tier spreads and supply chain shape across excavator wheel procurement, compressing margin buffers for standard-grade producers while pushing premium polyurethane variants toward regionalized sourcing footprints.
Pricing Analysis
Configured-to-order pricing for custom polyurethane formulations commands 40-60% premiums over standard rubber wheel catalog pricing. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and after-sales bundling intensity. Cost compression in economy-grade steel wheels intensifies because scrap metal volatility feeds directly into forged rim input costs. Mid-size rental fleet operators in North America exhibit highest price sensitivity, while mining fleet procurement in Australia prioritizes durability metrics over unit cost.
Supply Chain Analysis
Supplier-financing facilities extended by Xuzhou-based wheel fabricators compress payment cycles for Southeast Asian export customers. Manufacturing concentrates in China, Germany, and India, with rim forging drawing from scrap steel and virgin alloy feedstocks. Single-source vulnerability concentrates in polyurethane prepolymer supply from specialized chemical compounders. Distribution runs through captive OEM dealer networks and independent aftermarket distributors serving remote mining operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Excavator wheel procurement fragmentation creates entry niches as rental fleet operators disaggregate specification authority from field mechanics toward centralized procurement departments.
For Market Incumbents: Pre-empt track conversion substitution in mining applications by integrating remanufacturing service contracts that extend wheel asset life beyond single-use replacement cycles. Backward integration into rim forging secures margin control against steel input volatility. Anchor dealer network relationships through telematics-enabled predictive replacement platforms that displace scheduled maintenance.
For New Entrants and Emerging Players: Brazil's Carajás basin mining corridor offers underpenetrated steel wheel refurbishment demand as ANVISA chemical compliance constrains imported compound formulations. Target municipal waste handling fleets specifying solid wheels for uptime-critical applications. Pursue direct export channels into Southeast Asia bypassing established distributor markups.
For Investors and Strategic Acquirers: EU F-Gas Regulation phase-down schedules reshape the acquisition landscape toward lighter wheel assembly specialists with REACH-compliant polyurethane chemistry. Five-to-ten-year viability favors compounders with dual-certification alignment across China's GB standards and EPA requirements. Monitor vulcanization technician workforce aging as capacity constraint signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Remanufacturing Service Integration | Captures aftermarket value from Fortescue Metals Group and BHP fleet operators seeking extended asset life. |
| Dual-Certification Harmonization | Unlocks simultaneous access to China's MIIT-regulated domestic market and EU F-Gas export requirements. |
| Telematics-Enabled Predictive Replacement | Positions wheel suppliers to displace scheduled maintenance with condition-based service contracts for mining operators. |
| Backward Integration into Rim Forging | Insulates margin structure from scrap steel volatility affecting standard-grade wheel producers. |
| Polyurethane Compound R&D Investment | Addresses REACH chemical restrictions constraining vulcanization process chemistry in European production. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with maintenance directors, OEM procurement teams, aftermarket service heads, and plant engineers; and secondary validation through customs/trade data, SEC 10-K filings, equipment production databases, and MIIT certification registries. Bottom-up volume triangulation across material type, diameter class, and load capacity segments was cross-checked against top-down market sizing derived from OEM shipment disclosures and rental fleet operator procurement patterns.
Forecast inputs considered replacement cycle dynamics across mining, urban construction, and municipal waste handling applications over the projection horizon. Segmentation dimensions modeled include wheel material chemistry, diameter class, load rating tier, manufacturing process, and regional regulatory cluster. CAGRs were derived from regression analysis against construction equipment production indices and mining capital expenditure trajectories, with specific weighting applied to EPA Tier 4 Final compliance-driven equipment refresh cycles and China's metro expansion procurement timelines.
The forecast holds incumbent behavior within observed patterns; aggressive backward integration moves by mid-tier stamping specialists would shift outcomes. Macroeconomic deviation in steel scrap pricing, regulatory acceleration in EU F-Gas phase-down schedules, or breakthrough advances in track-undercarriage durability would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Construction Equipment Attachments Market
Construction Equipment
Earthmoving Equipment Undercarriage Market
Construction Equipment
Rotary Blasthole Drilling Rig Market
Construction Equipment
Construction Camera [Time Lapse Camera] Market
Construction Equipment
Manhole Housing Lifter Hook Market
Construction Equipment
Industrial and Commercial Floor Scrubbers Market
Construction Equipment
Pre-Owned Construction Equipment Market
Construction Equipment
Tray Dryers Market
Construction Equipment
Ground Engaging Tools (GET) Market
Construction Equipment
Shield Machines Market
Construction Equipment
Vibratory Plate Compactors Market
Construction Equipment
Piling Machine Market
Construction Equipment
Yard Crane Market
Construction Equipment
Brazil Metal Fabrication Equipment Market
Construction Equipment
Hydraulic Breaker for Excavator Market
Construction Equipment
Mexico Flexible Concrete Vibrator Market