
 Laser Cladding Systems Market | 2026-2036
Laser Cladding Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Laser Cladding Systems Market Analytics
ISO 9001 and AS9100 certification cycles are bifurcating the competitive landscape into qualified aerospace suppliers and general industrial providers. TRUMPF leverages its vertical integration across laser sources and beam delivery systems to command premium positioning in high-precision applications. IPG Photonics Corporation sustains technology leadership through in-house fiber laser manufacturing, while Coherent Corp competes via broad wavelength portfolio coverage across diode and solid-state architectures.
Laser cladding systems deposit metallurgically bonded surface layers using concentrated laser energy to melt feedstock powder or wire onto substrates, typically achieving bond strengths exceeding those of thermal spray coatings and enabling precise dilution control below five percent. The equipment serves primarily to restore dimensional tolerances on worn components and engineer functional surfaces for extreme operating environments. Fiber laser product types dominate installed capacity due to superior wall-plug efficiency and beam quality, while powder feeding technology leads revenue generation because it supports complex geometries and graded material transitions that wire processes cannot replicate. Additive manufacturing applications represent the fastest-expanding segment as machine tool builders integrate cladding heads into hybrid manufacturing platforms.
REACH registration requirements from ECHA constrain powder alloy formulations available to European operators, while FAA airworthiness directives and AS9100D quality mandates govern repair procedure qualifications in the United States. EPA hazardous air pollutant standards under NESHAP affect thermal spray shops considering laser cladding conversions. Stakeholders must monitor evolving qualification protocols for nickel-based superalloys and cobalt-chrome compositions as regulatory thresholds for respirable particulates tighten across multiple jurisdictions.
Market Dynamics
Aerospace engine remanufacturing requirements are compressing qualification timelines for laser cladding repair procedures, forcing equipment suppliers to synchronize R&D cycles with FAA airworthiness directive schedules and AS9100D audit windows.
Growth Catalysts
- REACH powder registration:ECHA compliance mandates in Europe are filtering out non-qualified alloy suppliers, concentrating procurement among certified powder producers with full toxicological dossiers.
- Fiber laser efficiency gains:Wall-plug efficiency improvements above forty percent are reducing operating costs for high-volume remanufacturing operations in automotive powertrain restoration.
- Germany precision clusters:Stuttgart and Munich supplier networks are creating captive demand for multi-axis cladding centers integrated into hybrid manufacturing platforms.
Market Restraints
- Nickel superalloy powder concentration:Over seventy percent of aerospace-grade feedstock originates from a limited set of gas atomization facilities in Germany and the United States.
- CAPEX intensity for fiber laser sources:Kilowatt-class systems require capital commitments that exclude smaller thermal spray conversion candidates.
- Plasma transferred arc competition:PTA welding retains cost advantages for cylindrical component restoration in oil and gas valve remanufacturing.
Strategic Opportunities
- India defense aerospace:Indigenous combat aircraft programs are creating first-mover advantage for cladding system vendors establishing local service infrastructure.
- Wire feed technology convergence:Closed-loop wire positioning systems are opening geometries previously exclusive to powder processes in turbine blade repair.
- EU Green Deal remanufacturing incentives:Circular economy funding mechanisms are subsidizing equipment purchases for component life extension services.
Industry Challenges
- Multi-physics simulation expertise:Process modeling for dilution control requires rare combinations of thermal-fluid dynamics and metallurgical training.
- AS9100D certification timelines:Aerospace repair procedure qualification cycles extend eighteen to thirty-six months, delaying revenue recognition for new market entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Laser Cladding Systems Market |
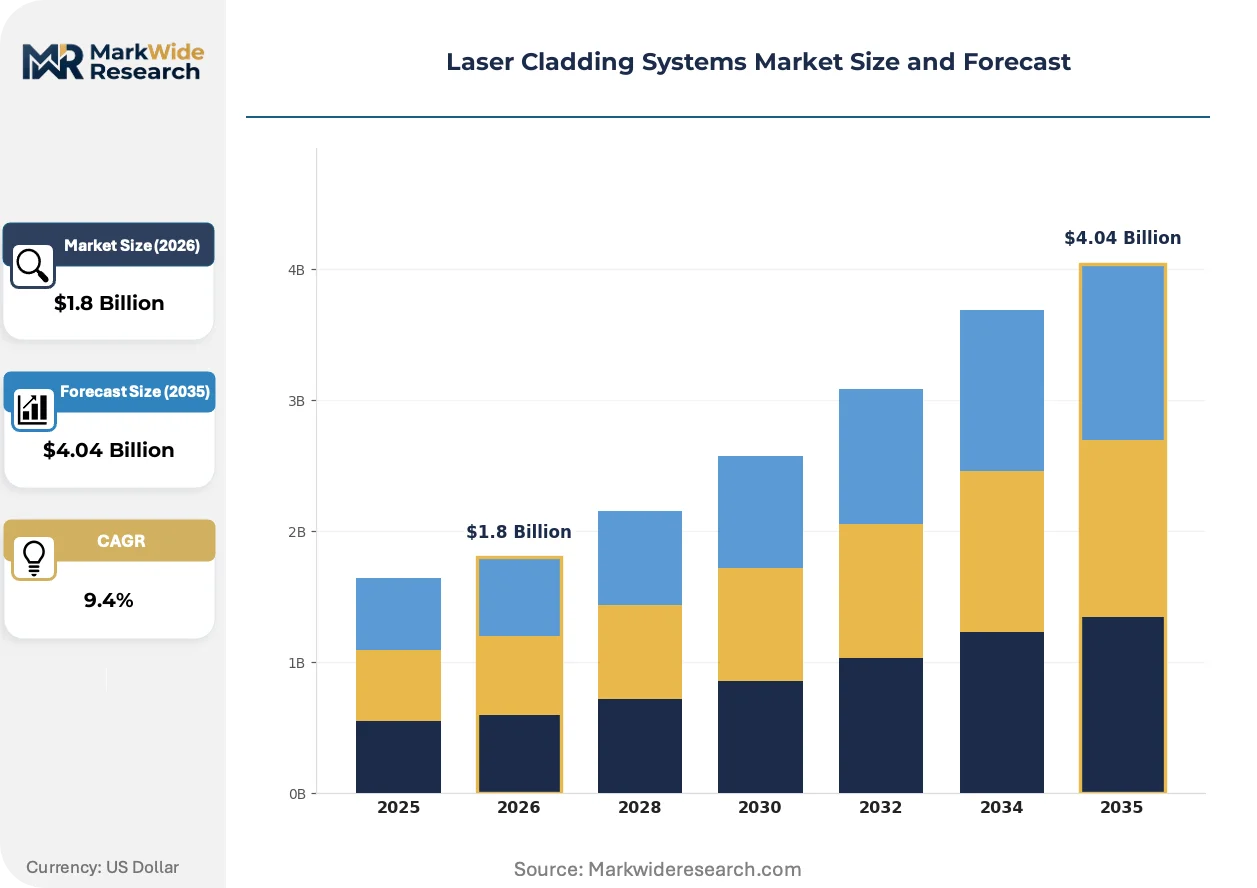
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.04 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fiber Laser, Solid-State Laser, CO2 Laser, Diode Laser End User: Aerospace, Automotive, Marine, Energy Technology: Hybrid Laser Cladding, Powder Feeding, Wire Feeding, Multi-Layer Cladding Application: Surface Repair, Wear Resistance, Functional Coatings, Additive Manufacturing |
| Companies Covered | TRUMPF, OC Oerlikon Management AG, IPG Photonics Corporation, Coherent Corp, Alpha Laser GmbH, Laserline GmbH, Höganäs AB, O.R. Lasertechnologie GmbH, TLM Laser, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Laser Cladding Systems Market Evolving Landscape
Real-time melt pool monitoring systems are displacing post-process inspection regimes, enabling closed-loop parameter adjustment during deposition and compressing quality assurance cycles for safety-critical aerospace repairs.
Hyperspectral imaging integrated with machine vision is bifurcating the equipment base between premium systems with in-situ metallurgical verification and standard platforms relying on offline destructive testing. Tier-one aerospace MROs in Germany and the United States are mandating the premium tier for engine component repairs, while general industrial restoration tolerates conventional architectures.
EPA NESHAP hazardous air pollutant standards are accelerating thermal spray shop conversions to laser cladding across the United States. Shops operating chromium carbide spray processes face particulate emission thresholds that favor laser-based alternatives with closed powder handling systems. Surface engineering contractors in Ohio and Texas are prioritizing equipment purchases to preempt enforcement actions.
Service contract unbundling is fragmenting procurement relationships between equipment OEMs and end-users. Aerospace MROs in France and the United Kingdom are separating hardware acquisition from process development support, engaging specialized engineering consultancies for application-specific parameter qualification rather than captive supplier programs. This pattern concentrates margin in technical services while pressuring equipment pricing transparency.
Laser Cladding Systems Market Segmentation
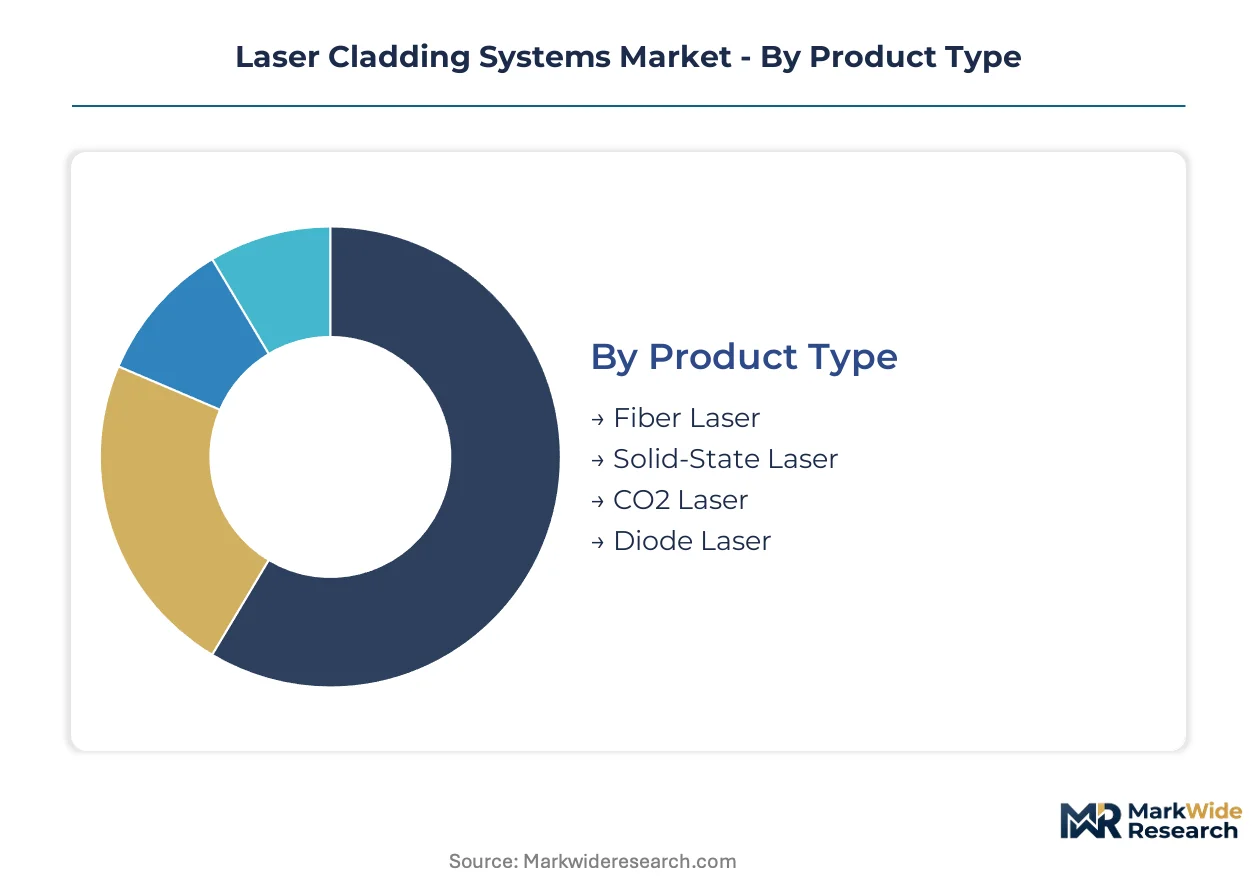
Laser cladding equipment segments by laser source, end-use sector, deposition method, and functional application. Each dimension carries distinct qualification requirements and margin structures that shape procurement patterns across aerospace MROs and industrial remanufacturing facilities.
Product Type:
Fiber laser systems dominate domestic procurement in Germany and Japan where precision engineering clusters anchor demand, while solid-state and CO2 architectures retain export-led traction in cost-sensitive Asian markets.
- Fiber Laser:Wall-plug efficiency exceeding forty percent enables high-duty-cycle operations in automotive powertrain restoration. Stuttgart and Munich supplier networks concentrate procurement for hybrid manufacturing platforms integrating cladding heads with CNC machining centers.
- Solid-State Laser:Nd:YAG and disk laser architectures deliver pulse-controlled energy deposition for aerospace nickel superalloy repairs. FAA airworthiness directive schedules in the United States and EASA certification timelines in France compress equipment qualification windows for this segment.
- CO2 Laser:Longer wavelength absorption characteristics suit polymer matrix composite substrates in marine propeller restoration.
- Diode Laser:Direct diode arrays offer compact footprints for field-deployable repair units in offshore energy infrastructure.
Fiber laser systems hold the largest share; momentum sits with diode laser configurations for mobile repair applications.
End User:
Cost tier differentiation separates aerospace qualification-intensive procurement from general industrial volume purchasing, with marine and energy sectors occupying intermediate positions on certification stringency.
- Aerospace:AS9100D mandates govern repair procedure qualifications for turbine blade restoration and engine casing remanufacturing. United States-based MROs in Ohio and Texas concentrate demand for closed-loop melt pool monitoring systems.
- Automotive:Powertrain component life extension drives fiber laser adoption for crankshaft and camshaft resurfacing. German OEM supplier networks in Baden-Württemberg integrate cladding centers into just-in-sequence remanufacturing lines.
- Marine:Propeller blade cavitation repair and stern tube bearing restoration utilize powder feeding systems for graded material transitions.
- Energy:Gas turbine hot section component repair and nuclear valve remanufacturing require cobalt-chrome alloy deposition under NRC oversight in the United States.
Aerospace commands premium pricing tiers; automotive generates the steepest expansion trajectory through circular economy remanufacturing incentives.
Technology:
Volume concentration favors powder feeding installations, while wire feeding systems gain application scope through closed-loop positioning advances.
- Powder Feeding:Gas atomized alloy delivery enables complex geometry reconstruction and functionally graded material transitions. German gas atomization facilities in North Rhine-Westphalia supply seventy percent of aerospace-grade nickel superalloy feedstock.
- Wire Feeding:Solid wire deposition achieves higher deposition rates for cylindrical component restoration in oil and gas valve repair. Advanced wire positioning systems now access turbine blade geometries previously exclusive to powder processes.
- Hybrid Laser Cladding:Machine tool builders integrate cladding heads with subtractive machining centers for sequential additive-subtractive processing.
- Multi-Layer Cladding:Sequential material deposition builds engineered surface architectures with property gradients through thickness.
Powder feeding retains the dominant installed base; hybrid laser cladding gains share fastest through machine tool OEM platform integration.
Application:
Customer type bifurcation separates safety-critical aerospace repairs from general industrial restoration, with functional coatings bridging qualification regimes.
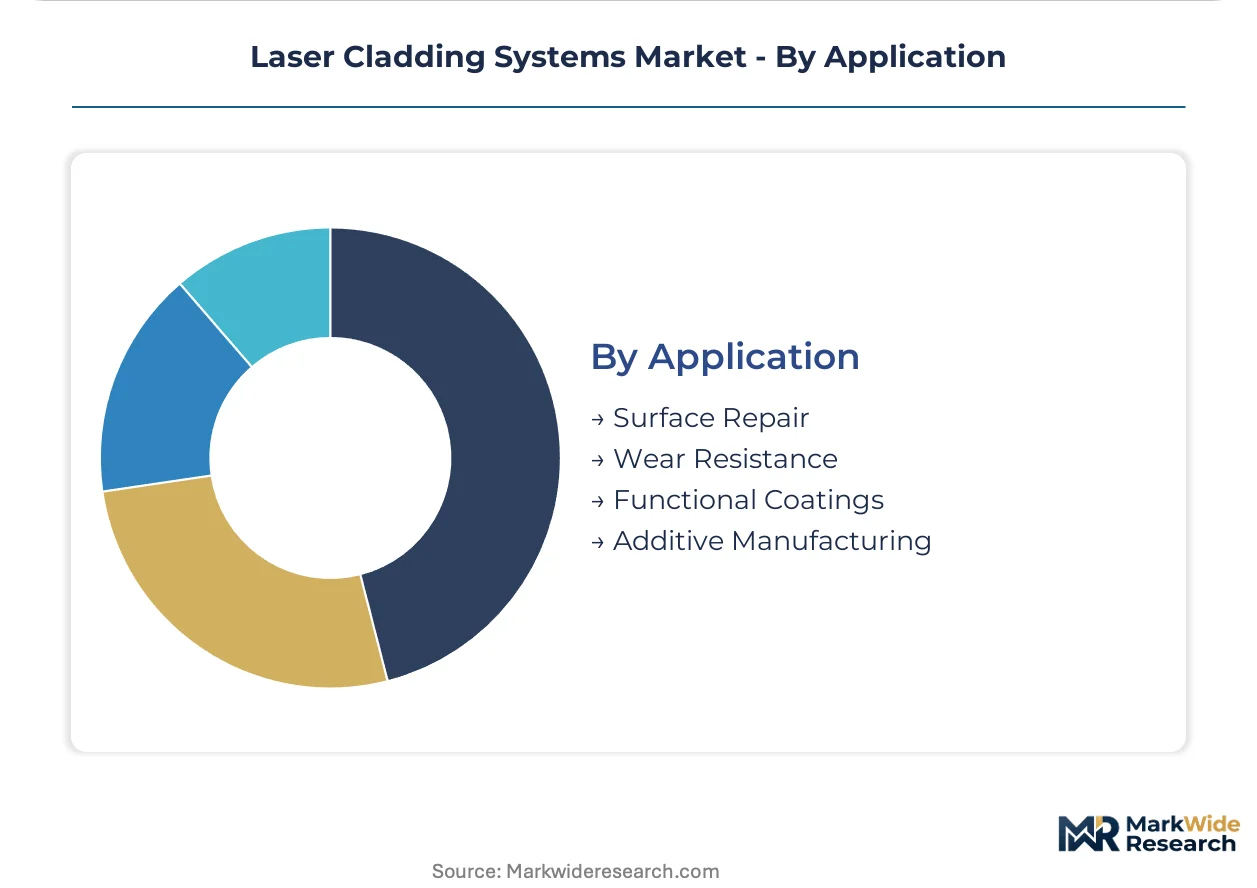
- Surface Repair:Dimensional restoration of worn components achieves metallurgical bond strengths exceeding thermal spray alternatives. United States thermal spray shops in Ohio and Texas convert to laser cladding under EPA NESHAP hazardous air pollutant enforcement pressure.
- Additive Manufacturing:Near-net-shape component fabrication and feature addition onto existing substrates represent the expanding application frontier. Germany's EU Green Deal circular economy funding subsidizes equipment purchases for component life extension services.
- Wear Resistance:Hardfacing deposits of tungsten carbide and chromium carbide compositions protect mining and agricultural equipment.
- Functional Coatings:Corrosion-resistant and thermal barrier coatings extend service intervals in chemical processing and power generation.
Surface repair maintains the largest revenue contribution; additive manufacturing climbs the fastest through hybrid platform adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Procurement concentrates among aerospace MROs and precision engineering clusters in Germany, the United States, Japan, China, and India. Each geography exhibits distinct regulatory drivers and industrial concentration patterns that shape equipment specification and supplier relationships.
Germany
Stuttgart and Munich precision engineering clusters generate captive demand for multi-axis cladding centers integrated into hybrid manufacturing platforms. ECHA REACH registration requirements filter alloy formulations, concentrating powder procurement among certified producers with full toxicological dossiers. Baden-Württemberg automotive OEM supplier networks drive fiber laser adoption for powertrain remanufacturing lines.
United States
Ohio and Texas thermal spray shops convert to laser cladding systems under EPA NESHAP hazardous air pollutant enforcement pressure. FAA airworthiness directives govern repair procedure qualifications for turbine blade restoration, compressing equipment supplier R&D cycles. Cleveland and Houston aerospace MROs mandate closed-loop melt pool monitoring for engine component repairs.
Japan
Chubu region machine tool builders integrate cladding heads into hybrid manufacturing platforms for automotive and precision component sectors. METI industrial technology roadmaps prioritize additive manufacturing process development. Nagoya supplier networks emphasize fiber laser systems for high-duty-cycle production environments.
China
Yangtze River Delta industrial machinery manufacturers adopt laser cladding for mining equipment restoration and mold repair applications. MIIT equipment upgrade programs subsidize advanced manufacturing technology adoption. Shanghai and Suzhou precision engineering clusters drive demand for mid-power fiber laser configurations.
India
Indigenous combat aircraft programs in Bangalore and Hyderabad create first-mover advantage for cladding system vendors establishing local service infrastructure. Defense procurement policies prioritize domestic manufacturing partnerships for aerospace repair technology. Tamil Nadu and Karnataka automotive component remanufacturing facilities evaluate wire feed technology for cylindrical part restoration.
Laser Cladding Systems Market Competitive Landscape
Player mix skews toward diversified industrial laser manufacturers with captive beam source production. Market structure exhibits tiered concentration, with premium positioning held by vertically integrated suppliers and mid-tier competition among specialized cladding equipment fabricators. Strategic archetypes include laser source OEMs extending into deposition systems, machine tool builders integrating cladding modules, and dedicated cladding system specialists. Dominant competitive moves encompass backward integration into powder alloy supply and geographic expansion through local service infrastructure partnerships.
Among Germany-based precision equipment specialists, TRUMPF and Alpha Laser GmbH exemplify the vertically integrated archetype controlling laser source and beam delivery manufacturing. IPG Photonics Corporation represents the fiber laser source specialist extending downstream into cladding applications. These three anchors illustrate divergent strategic positions: full-stack integration versus component specialization versus platform diversification.
| Leading Market Players |
|---|
| TRUMPF |
| OC Oerlikon Management AG |
| IPG Photonics Corporation |
| Coherent Corp |
| Alpha Laser GmbH |
| Laserline GmbH |
| Höganäs AB |
| O.R. Lasertechnologie GmbH |
| TLM Laser |
| Others |
Value Network & Pricing Analysis
Gas atomization capacity utilization above eighty percent in German and United States powder facilities anchors price floors for aerospace-grade nickel superalloy feedstock, compressing margin buffers for equipment OEMs while elevating procurement leverage among certified alloy producers with full ECHA REACH dossiers.
Pricing Analysis
Cost-plus contracts with nickel and cobalt LME indexation dominate long-term powder supply agreements, insulating certified producers from commodity volatility while exposing non-integrated cladding system vendors to margin compression. Three-tier pricing structure across premium, standard, and economy levels separates AS9100D-qualified aerospace systems from general industrial configurations and entry-level thermal spray conversions. Cost compression in the mid-tier is intensifying because automotive OEMs in Baden-Württemberg negotiate bundled service contracts. General industrial remanufacturing facilities exhibit highest price sensitivity; aerospace MROs in Ohio and Texas tolerate premium positioning for closed-loop melt pool monitoring capabilities.
Supply Chain Analysis
Port congestion on Hamburg-Rotterdam trade lanes elevates inbound logistics costs for German precision engineering clusters sourcing fiber laser diodes from Asian component fabs. Supply concentrates in Germany, the United States, and Japan for gas atomized superalloy powders, fiber laser resonators, and precision motion stages. Raw material dependencies rest on cobalt-chrome feedstock, ytterbium-doped fiber, and high-purity argon shielding gas. Single-source vulnerability characterizes ytterbium supply concentration among three dominant fiber laser manufacturers. Distribution runs through direct OEM sales for aerospace qualification-intensive procurement and specialized industrial distributors for general remanufacturing applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics inflection in this market centers on machine tool OEMs integrating cladding heads into hybrid manufacturing ecosystems, creating interoperability standards that privilege early movers with established CNC controller partnerships.
For Market Incumbents: Fortify captive powder alloy supply through backward integration into gas atomization capacity or exclusive offtake agreements with REACH-certified producers in North Rhine-Westphalia. Deepen AS9100D audit preparation services to compress eighteen-month qualification timelines for aerospace MROs facing FAA airworthiness directive pressure. Priority lever rests on controlling toxicological dossier submission workflows that ECHA mandates increasingly filter. For New Entrants and Emerging Players: Application engineering services for wire feed parameter development represent the most under-served layer where incumbents bundle hardware with restrictive process support contracts. Target India's indigenous combat aircraft programs in Bangalore and Hyderabad before established vendors complete local service infrastructure deployment. Go-to-market angle emphasizes closed-loop wire positioning systems for turbine blade geometries previously exclusive to powder processes. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors hybrid platform specialists with established CNC controller partnerships and proven multi-axis deposition software stacks. Long-term viability over the coming decade hinges on capturing machine tool OEM integration sockets before platform standards crystallize. Acquisition target archetype: regional cladding system fabricators with AS9100D repair procedure libraries and established aerospace MRO relationships. Signal to monitor: FAA publication of streamlined qualification pathways for wire-based engine component repairs.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Gas Atomization | Captive superalloy powder supply secures ECHA REACH compliance and procurement leverage against certified competitors. |
| Hybrid Platform Controller Partnership | Machine tool OEM integration sockets in Stuttgart and Nagoya determine long-term equipment placement trajectories. |
| AS9100D Repair Procedure Library Expansion | Pre-qualified parameter sets compress eighteen-month aerospace qualification cycles for nickel superalloy deposition. |
| Local Service Infrastructure in India | Bangalore and Hyderabad defense aerospace clusters create first-mover advantage before indigenous programs mature. |
| Closed-Loop Wire Positioning Development | Advanced wire feed systems access turbine blade geometries previously exclusive to powder processes in MRO applications. |
Research Methodology
A spread of perspectives from equipment OEM product managers, aerospace MRO engineering directors, powder alloy procurement leads, and machine tool platform engineers converged on the working assumptions underlying demand projections. Primary interviews combined with secondary validation against ECHA REACH registration databases, FAA airworthiness directive filings, EPA NESHAP enforcement records, and SEC 10-K disclosures from listed laser manufacturers. Bottom-up triangulation across installed base estimates and top-down cross-checks against capital equipment spending patterns anchored value projections.
Segmentation dimensions modeled encompass laser source architecture, deposition method technology, end-use sector qualification intensity, and functional application type across the projection horizon. CAGRs derived from regression analysis of historical equipment procurement cycles against regulatory compliance deadlines and circular economy subsidy program schedules. Industry-specific forecast inputs include fiber laser wall-plug efficiency improvement trajectories and gas atomization capacity expansion timelines in German production hubs.
Forecasts assume regulatory continuity in ECHA REACH registration requirements, FAA AS9100D certification protocols, and EPA NESHAP enforcement patterns; material policy shifts would require re-modeling of powder formulation availability and thermal spray conversion timelines. Specific risks encompass nickel superalloy supply concentration among limited gas atomization facilities and potential relaxation of EU Green Deal remanufacturing subsidies. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Crane Buffer Market
Construction Equipment
Street Washer Machine Market
Construction Equipment
Saudi Arabia Completion Equipment and Services Market
Construction Equipment
Global Asphalt Crushers Market
Construction Equipment
Wood Milling Machine Market
Construction Equipment
Sandblasting Machines Market
Construction Equipment
Autonomous Construction Equipment Market
Construction Equipment
Portable Rebar Bending Machine Market
Construction Equipment
Cold Heading Machine Market
Construction Equipment
Global Light Towers Market
Construction Equipment
Crawler Dozers Market
Construction Equipment
Fogging Machine Market
Construction Equipment
Road Marking Equipment Market
Construction Equipment
Global Compact Construction Equipment Market
Construction Equipment
GCC Crane Market
Construction Equipment
US Rental Equipment Market