
 Global UV Curable Resins Market | 2026-2036
Global UV Curable Resins Market Size, Share, and Industry Trends Forecast 2026-2036
Global UV Curable Resins Market Intelligence
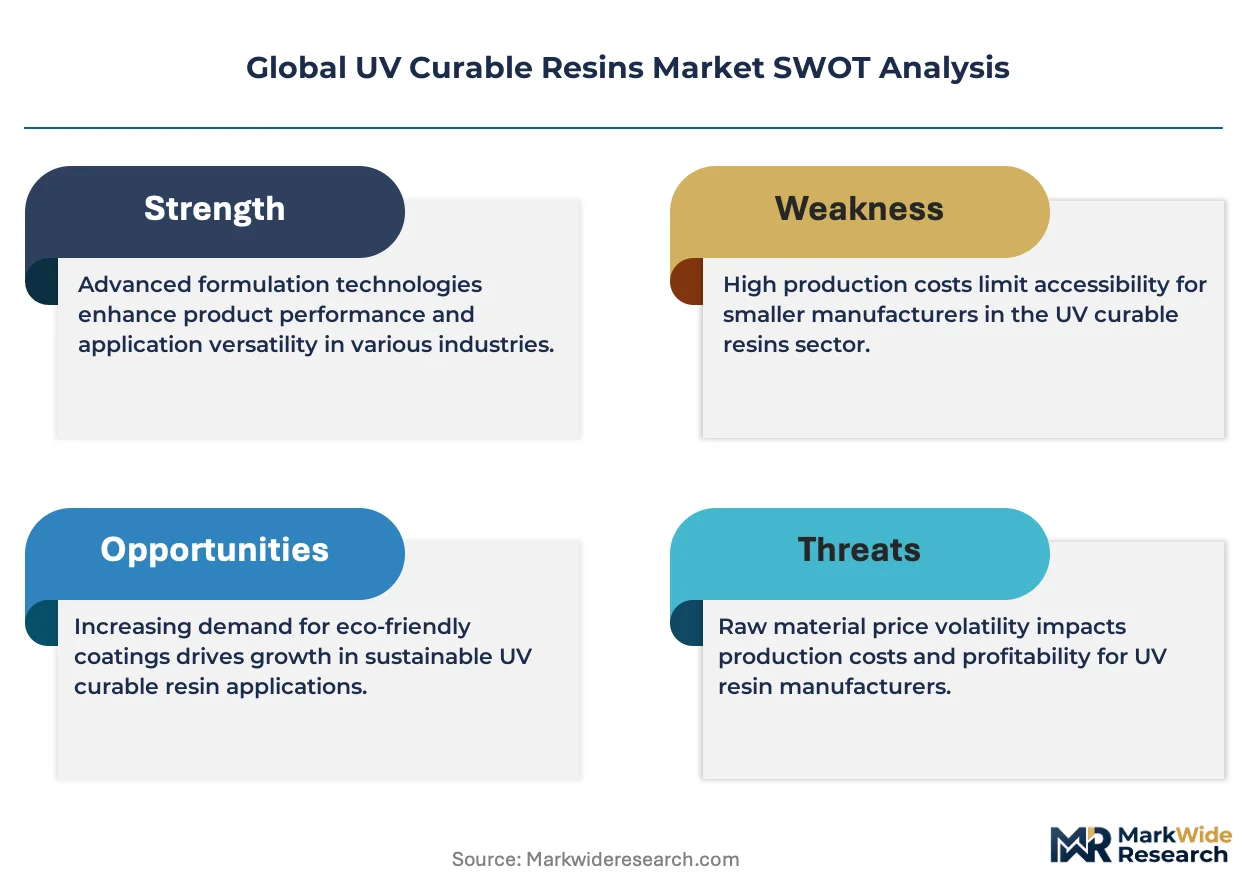
Subscription-based technical service and formulation support is consolidating around resin producers that bundle application engineering with raw material supply. Arkema Group leverages its Sartomer acrylate platform to anchor high-performance electronics coatings in Asia. BASF SE competes through backward integration into photoinitiator chemistry and captive supply of specialty monomers. Allnex differentiates via waterborne UV resin technology for furniture producers seeking low-VOC finishes.
UV curable resins comprise oligomers, monomers, and photoinitiators that polymerize within seconds under ultraviolet light, typically achieving full cure at 200-400 nm wavelength with solvent-free processing. These materials serve industrial coating, adhesive, and ink applications where throughput speed and environmental compliance override conventional thermal curing economics. Acrylates dominate product type volume due to their versatility across free radical systems, though cationic epoxy formulations capture margin pools in electronics encapsulation where moisture resistance is paramount. Hybrid technology combining radical and cationic mechanisms represents the fastest-growing technology segment as formulators seek to bridge adhesion gaps on difficult substrates.
FDA regulates UV-cured coatings for food-contact packaging through 21 CFR 175.105 adhesive provisions, while EPA oversight of VOC emissions under Clean Air Act Title I shapes reformulation priorities for domestic coatings producers. ECHA REACH restrictions on isocyanates and certain photoinitiators force European suppliers toward safer-by-design monomer architectures. Stakeholders must monitor pending EU PFAS restrictions that could eliminate fluorinated surfactants used in UV coating wetting agents, requiring alternative substrate preparation chemistries.
Market Dynamics
Mercury-free photoinitiator reformulation is compressing incumbent supply chains as European REACH restrictions force immediate chemistry transitions across coating and adhesive formulators.
Growth Catalysts
- Electronics encapsulation demand:Moisture-resistant cationic epoxy systems capture specification wins in semiconductor packaging as thermal curing yields to UV throughput advantages.
- China coastal manufacturing concentration:Shenzhen and Guangzhou industrial clusters absorb half of Asia-Pacific resin volume through integrated PCB and display coating operations.
- RoHS compliance mandates:European electronics assemblers specify mercury-free photoinitiator packages, accelerating supplier qualification cycles for compliant resin systems.
Market Restraints
- Photoinitiator supply concentration:Specialty photoinitiator synthesis clusters in German and Chinese chemical parks, creating single-source vulnerability for formulators.
- Acrylate monomer cost volatility:Propylene oxide feedstock exposure ties UV resin margins to petrochemical cycle swings without hedge mechanisms.
- Cationic epoxy technical ceiling:Oxygen inhibition sensitivity limits cationic systems to thin-film applications, blocking thick-section composite markets.
Strategic Opportunities
- India industrial coating penetration:Automotive and furniture producers in Pune and Chennai remain sub-15% UV-adopted, offering first-mover formulation partnerships.
- Hybrid radical-cationic convergence:Dual-cure mechanisms bridge adhesion gaps on polyolefin substrates previously excluded from UV finishing.
- Waterborne UV regulatory tailwind:Allnex-style low-VOC technology aligns with EU Green Deal industrial emissions targets for wood furniture clusters.
Industry Challenges
- Formulation chemistry talent scarcity:Photochemistry and radiation curing expertise concentrates among retiring European specialists, constraining Asian technical service expansion.
- Dual-cure equipment capex burden:Hybrid radical-cationic systems require sequential LED and microwave investment, extending payback periods for mid-tier coaters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global UV Curable Resins Market |
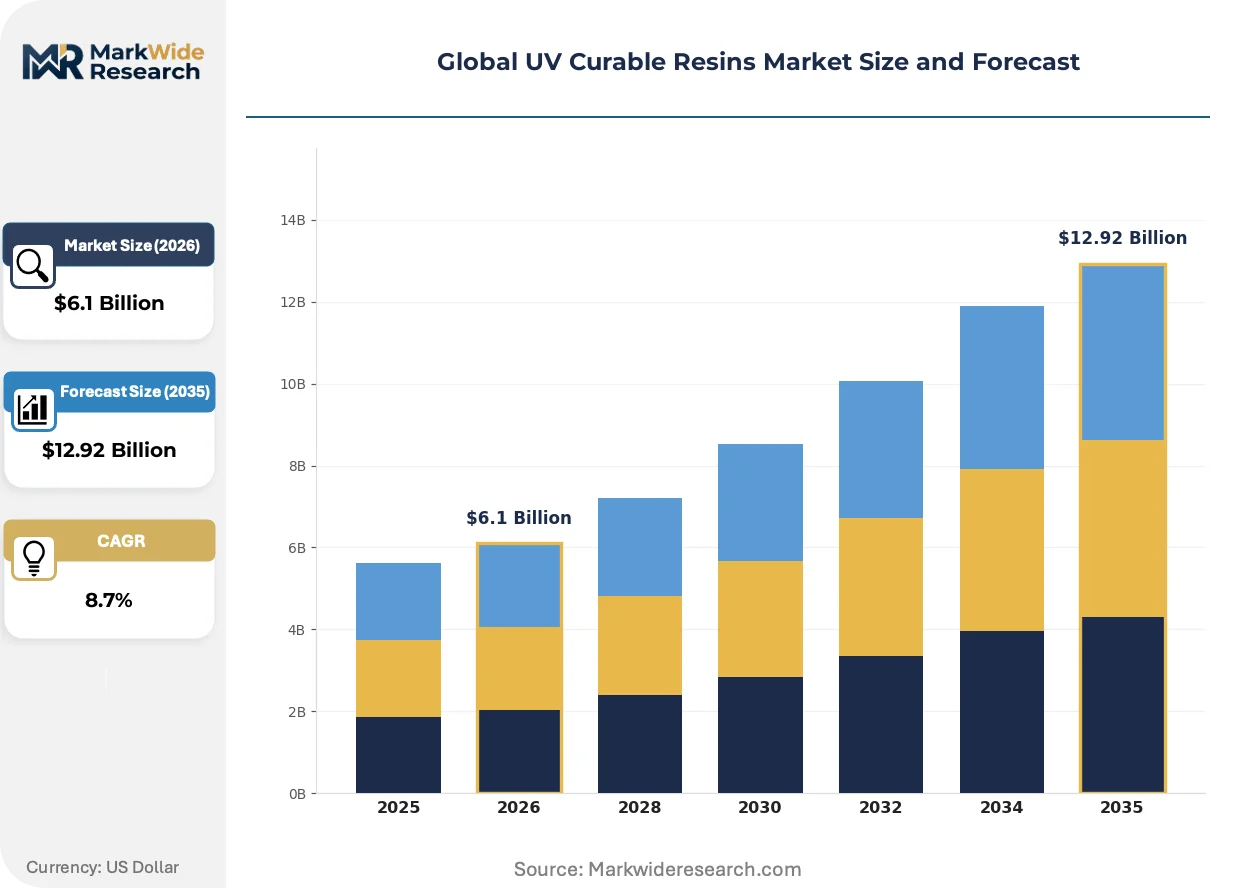
| Market Size in 2026 | $6.1 Billion |
| Market Size in 2035 | $12.92 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
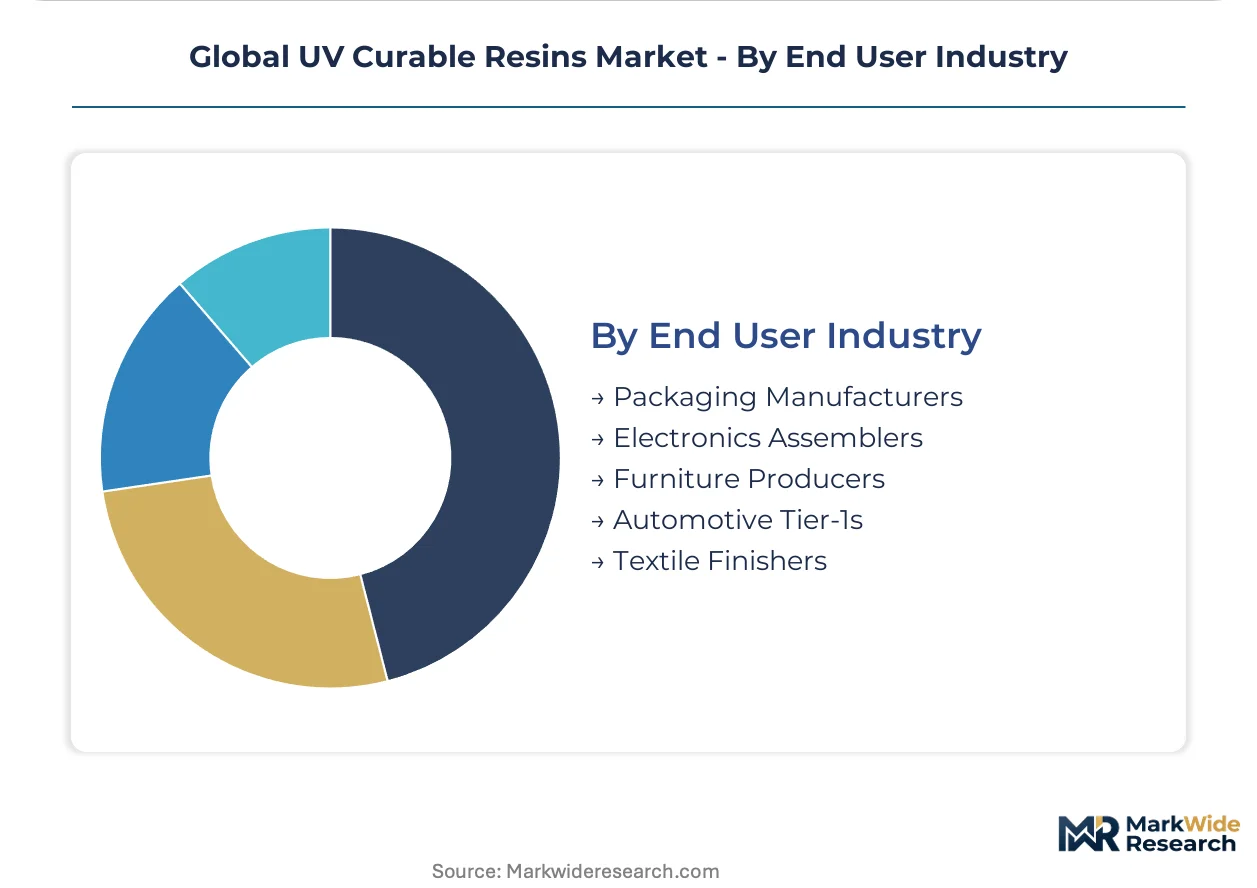
| Segmentation | Product Type: Acrylates, Epoxy, Polyurethane, Polyester, Vinyl Ether Technology: Free Radical Polymerization, Cationic Polymerization, Hybrid Technology, Photoinitiator Types Application: Printing Inks, Coatings, Adhesives, Electronics, Optical Fibers End User Industry: Packaging Manufacturers, Electronics Assemblers, Furniture Producers, Automotive Tier-1s, Textile Finishers |
| Companies Covered | Arkema Group, DIC Corporation, BASF SE, Alberdingk Boley GmbH, Resonac Holdings Corporation, Covestro AG, IGM Resins, Miwon Specialty Chemical, Allnex, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global UV Curable Resins Market Strategic Shifts & Innovations
LED UV curing wavelengths below 365 nm are compressing mercury arc dominance while bio-based acrylate feedstocks and waterborne dilution technologies reshape formulation architecture.
LED UV systems operating at 395 nm and 405 nm are absorbing mercury vapor lamp installations in flatbed printing and wood coating lines. Packaging converters in Germany and Italy specify LED-compatible photoinitiator packages to eliminate mercury handling protocols. The technology is absorbing capital allocation from thermal drying tunnels, shrinking floor space requirements by two-thirds in greenfield coating facilities.
ECHA REACH restrictions on isocyanate-containing oligomers are forcing urethane acrylate reformulation toward aliphatic epoxy and polyester backbones. European automotive refinish and industrial maintenance coatings suppliers face 2025 re-registration deadlines. Electronics encapsulation formulators pivot fastest, leveraging existing cationic epoxy expertise to bypass urethane dependency entirely.
Technical service bundling is displacing raw material spot purchasing among mid-tier coating houses. Resin producers embed application engineers at customer formulation labs, converting supply relationships into annual service contracts. This pattern concentrates in China's Yangtze River Delta, where furniture and electronics coaters lack in-house photochemistry capability.
Global UV Curable Resins Market Segmentation
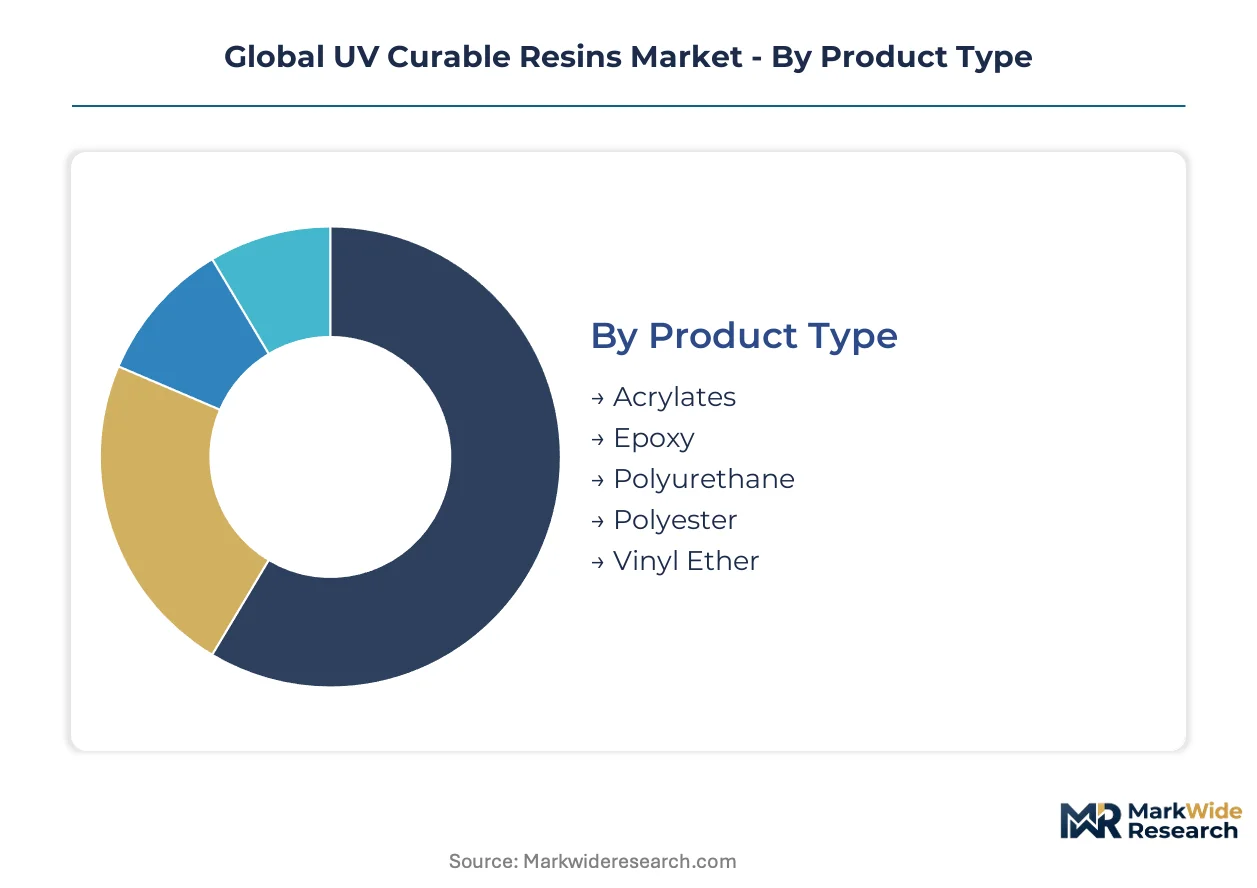
UV curable resin procurement patterns diverge sharply across end-use contexts, with electronics assemblers prioritizing moisture resistance specifications while furniture producers optimize for VOC compliance thresholds. Formulation architecture must reconcile these competing performance mandates through precise oligomer and photoinitiator selection.
Product Type:
Buyers in this category segment by cure speed requirements, substrate compatibility demands, and regulatory compliance burdens rather than price alone.
- Acrylates:Free-radical systems built from multifunctional monomers and oligomers deliver sub-second cure speeds across coating and ink applications. Shenzhen PCB fabricators consume substantial volumes for solder mask and conformal coating layers where throughput velocity determines line economics.
- Epoxy:Cationic ring-opening polymerization yields dense crosslinked networks with superior moisture barrier properties. Semiconductor packaging houses in South Korea and Taiwan specify these systems for flip-chip underfill and wafer-level encapsulation where thermal cycling resistance is non-negotiable.
- Polyurethane:Urethane acrylate hybrids balance flexibility with abrasion resistance in automotive refinish and wood flooring topcoats.
- Polyester:Lower-cost backbone structures serve commodity wood furniture primers and paper overprint varnishes where premium performance is unnecessary.
- Vinyl Ether:Rapid cationic cure kinetics suit high-speed flexographic printing on non-porous films.
Volume sits with Acrylates; growth tilts toward Epoxy as electronics encapsulation specifications tighten.
Technology:
Technology selection hinges on oxygen sensitivity tolerance, substrate surface energy, and available capital equipment for sequential or single-stage cure.
- Free Radical Polymerization:Acrylate-based systems dominate installed base with mature photoinitiator packages and broad hardware compatibility. German packaging converters leverage these chemistries for high-speed label printing where atmospheric oxygen inhibition is manageable through nitrogen inerting or high-intensity lamps.
- Cationic Polymerization:Epoxy and vinyl ether systems polymerize through acid-catalyzed mechanisms without oxygen inhibition, enabling thick-section cure. Japanese electronics material suppliers are expanding cationic capacity for automotive sensor encapsulation where dimensional stability under thermal shock is critical.
- Hybrid Technology:Dual radical-cationic mechanisms address adhesion failures on untreated polyolefins and engineering thermoplastics.
- Photoinitiator Types:Mercury-free Type I cleavage and Type II hydrogen abstraction systems are displacing legacy benzophenone and HMPP packages under REACH restrictions.
Installed base favors Free Radical Polymerization; Hybrid Technology is gaining share fastest as substrate diversity expands.
Application:
Application segmentation reflects divergent regulatory exposure, with food-contact packaging facing FDA scrutiny and industrial coatings subject to EPA VOC enforcement.
- Coatings:Wood furniture, automotive refinish, and industrial maintenance segments drive formulation complexity for scratch resistance and weatherability. Italian furniture clusters in Brianza specify low-VOC UV coatings to satisfy EU Green Deal industrial emissions protocols.
- Printing Inks:Flexographic and offset lithographic systems for food packaging require low-migration photoinitiator packages compliant with Swiss Ordinance and EU Printing Ink Regulation frameworks.
- Adhesives:Pressure-sensitive and structural bonding applications in medical device assembly demand biocompatibility certification.
- Electronics:PCB solder masks, display edge seals, and semiconductor encapsulation represent specification-intensive segments.
- Optical Fibers:Primary and secondary coating layers for telecommunications cable require precise refractive index control and microbending resistance.
Revenue concentrates in Coatings; specification intensity peaks in Electronics.
End User Industry:
End user procurement sophistication varies from commodity spot purchasing among furniture producers to integrated annual service contracts among electronics assemblers.
- Electronics Assemblers:Vertically integrated PCB and display manufacturers in China's Pearl River Delta specify resin systems through captive formulation partnerships. These buyers bundle technical service, application engineering, and raw material supply into multi-year agreements with penalty clauses for specification drift.
- Packaging Manufacturers:Converters in Germany, Italy, and the US Midwest prioritize LED-compatible photoinitiator packages to eliminate mercury handling protocols and reduce energy intensity.
- Furniture Producers:Wood coating houses in Vietnam and Poland remain price-sensitive spot purchasers with limited in-house photochemistry capability.
- Automotive Tier-1s:Interior trim and refinish coaters face OEM mandates for aliphatic polyurethane acrylates with low-yellowing performance.
- Textile Finishers:Narrow web and industrial fabric coaters in Turkey and India apply UV curable binders for technical textiles and synthetic leather.
Contract value concentrates with Electronics Assemblers; penetration headroom sits with Furniture Producers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China manufactures half of Asia-Pacific resin volume while European formulators absorb reformulation costs from REACH deadlines. German and Chinese chemical parks concentrate photoinitiator synthesis, creating supply vulnerability for coaters elsewhere.
China
Shenzhen and Guangzhou industrial clusters consume the bulk of regional acrylate volumes for PCB solder masks and display edge seals. MEE enforcement of dual carbon goals accelerates mercury-free photoinitiator transitions in coastal facilities. The Pearl River Delta houses integrated electronics assemblers that bundle multi-year resin supply contracts with captive technical service.
Germany
Automotive refinish and packaging converters in Bavaria and North Rhine-Westphalia specify LED-compatible photoinitiator packages to eliminate mercury handling. ECHA REACH restrictions on isocyanate-containing oligomers force 2025 re-registration deadlines for urethane acrylate formulators. The Eindhoven-Randstad corridor absorbs German resin exports for furniture coating lines seeking low-VOC compliance.
United States
EPA Clean Air Act Title I enforcement shapes reformulation priorities for domestic coatings producers facing VOC emission thresholds. FDA 21 CFR 175.105 provisions regulate food-contact packaging adhesives, constraining photoinitiator selection for label converters in the Midwest. Michigan and Ohio automotive tier-1s specify aliphatic polyurethane acrylates for interior trim applications.
South Korea
Semiconductor packaging houses in Suwon and Yongin drive cationic epoxy demand for flip-chip underfill and wafer-level encapsulation. K-REACH alignment with EU chemical safety protocols accelerates mercury-free photoinitiator qualification cycles. The Seoul Capital Area concentrates electronics material suppliers expanding cationic capacity for automotive sensor applications.
India
Automotive and furniture producers in Pune and Chennai remain sub-15% UV-adopted, offering penetration headroom for formulation partnerships. BIS standards for industrial coatings lack UV-specific provisions, creating regulatory ambiguity for domestic formulators. The Maharashtra-Gujarat corridor hosts price-sensitive spot purchasers with limited in-house photochemistry capability.
Global UV Curable Resins Market Key Industry Players
Capital-heavy producers compete with asset-light designers across formulation and photoinitiator supply. The market structures around three tiers: integrated resin-photoinitiator houses, oligomer specialists with captive monomer supply, and regional formulators dependent on spot purchasing. Strategic moves concentrate on backward integration into photoinitiator chemistry and bundling technical service with raw material contracts.
Within the integrated tier, Arkema Group and BASF SE occupy positions that span acrylate oligomers through photoinitiator synthesis. Allnex exemplifies the waterborne UV specialization vector for furniture coating compliance. Among Asian chemical conglomerates, DIC Corporation and Resonac Holdings Corporation anchor regional supply relationships through diversified material portfolios. Covestro AG and IGM Resins sit within the mid-cap specialist category, serving formulators seeking application-specific performance packages without full integration burdens.
| Leading Market Players |
|---|
| Arkema Group |
| DIC Corporation |
| BASF SE |
| Alberdingk Boley GmbH |
| Resonac Holdings Corporation |
| Covestro AG |
| IGM Resins |
| Miwon Specialty Chemical |
| Allnex |
| Others |
Cost & Logistics Intelligence
LED UV curing wavelength compression below 365 nm simultaneously reduces energy input costs and concentrates photoinitiator purchasing power among German and Chinese specialty chemical houses. This technology transition reshapes procurement economics as formulators abandon mercury arc legacy systems and absorb reformulation qualification expenses.
Pricing Analysis
Margin tightening in standard acrylate tiers reflects propylene oxide feedstock volatility without hedge mechanisms. Three-tier pricing structure across electronics-grade, industrial-performance, and commodity furniture segments separates specification-intensive buyers from spot purchasers. Electronics assemblers in Shenzhen show lowest price sensitivity due to captive technical service bundling, while Vietnamese wood coaters drive aggressive spot-market negotiation.
Supply Chain Analysis
Specialized photochemistry workforce scarcity in China's Yangtze River Delta and Germany's North Rhine-Westphalia constrains technical service expansion for resin producers. Photoinitiator synthesis clusters in Ludwigshafen and Shanghai chemical parks create single-source vulnerability for formulators dependent on Type I cleavage packages. Distribution runs through regional distributors serving mid-tier coating houses lacking in-house formulation capability.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Photoinitiator supply concentration props pricing power for integrated resin houses, with mercury-free reformulation cycles locking in multi-year contract structures.
For Market Incumbents: Anticipate REACH-aligned regulatory expansion into Asian jurisdictions by securing captive photoinitiator supply through backward integration or long-term offtake agreements. Consolidate technical service teams in China's Pearl River Delta to defend against emerging Korean electronics material suppliers. Prioritize hybrid radical-cationic R&D investment to capture adhesion-gap applications previously excluded from UV finishing. For New Entrants and Emerging Players: Capture underpenetrated furniture coating demand in India's Maharashtra-Gujarat corridor through waterborne UV formulation partnerships with price-sensitive spot purchasers. Target automotive sensor encapsulation specifications in South Korea's Seoul Capital Area where cationic epoxy expertise concentrates. Lead with application engineering deployment rather than raw material spot supply to differentiate from established distributors. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to Asian chemical conglomerates seeking European photoinitiator technology and formulation expertise. Mid-cap specialists with captive monomer supply and LED-compatible photoinitiator portfolios represent priority acquisition archetypes over asset-light formulators. Monitor ECHA PFAS restriction timelines as inflection indicators for surfactant-dependent coating wetting agent demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Photoinitiator Chemistry | Arkema and BASF secure supply continuity as REACH restrictions eliminate mercury-containing packages. |
| Waterborne UV Technology Expansion | Allnex-style low-VOC formulations align with EU Green Deal emissions targets for Italian furniture clusters. |
| Hybrid Radical-Cationic Capacity Buildout | Dual-cure systems bridge adhesion gaps on polyolefin substrates for automotive interior trim applications. |
| Technical Service Bundling Contracts | Annual service agreements with penalty clauses lock in electronics assemblers across China's Pearl River Delta. |
| LED-Compatible Photoinitiator Qualification | Mercury-free packages eliminate handling protocols for German packaging converters in Bavaria. |
Research Approach
Document review covered customs and trade flow data, SEC and TSE corporate filings, ECHA substance registration databases, and industry association technical reports, complemented by interviews with resin plant managers, downstream coating procurement leads, photoinitiator R&D directors, and distribution channel partners across Germany, China, and the United States. Bottom-up volume modeling triangulated against top-down demand aggregation across end-use segments.
Segment-level projections incorporated oligomer grade tier, cure technology type, end-use industry vertical, and regional manufacturing hub clustering across the analysis window. CAGRs derived from elasticity-adjusted demand curves incorporating electronics fabrication capacity expansion, furniture coating regulatory compliance deadlines, and automotive lightweighting material substitution rates.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to REACH regulatory expansion timelines, propylene oxide feedstock cycle positioning, and LED curing equipment capital allocation patterns. Material deviation in these triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Polymer Binders Market
Polymers & Resins
Thermosetting Plastics Market
Polymers & Resins
BMI Resins Market
Polymers & Resins
Polystyrene and Expandable Polystyrene (EPS) Market
Polymers & Resins
Saudi Arabia Engineering Plastics Market
Polymers & Resins
Cyclic Olefin Polymers (COP) Polymer Syringes Market
Polymers & Resins
Polymers for Electric Vehicle (EV) Market
Polymers & Resins
Antiviral Polymers for Packaging Market
Polymers & Resins
Petroleum Resins Market
Polymers & Resins
Gel Polymer Electrolytes Market
Polymers & Resins
Flame Retardant Thermoplastics Market
Polymers & Resins
Dispersant Polymer Market
Polymers & Resins
Polypropylene Powder Market
Polymers & Resins
Europe Polyurethane Market
Polymers & Resins
China Engineering Plastics Market
Polymers & Resins
Bio-Based Polycarbonate Market