
 Europe Polyurethane Market | 2026-2036
Europe Polyurethane Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Polyurethane Market Insights
Market Dynamics
Maintenance contracts for foam reconditioning and performance monitoring is consolidating as a discrete revenue layer alongside bulk chemical sales. BASF SE leverages its Ludwigshafen hub to sustain integrated polyol-isocyanate supply chains across Central Europe. Covestro AG anchors its competitive stance through specialized aliphatic systems for light-stable coatings. Huntsman Corporation differentiates via MDI capacity positioned to serve Mediterranean construction markets.
Product Landscape
Polyurethane denotes a class of polymers formed by reacting a di- or poly-isocyanate with a polyol, yielding carbamate linkages that enable tunable density from 10 kg/m³ flexible foam to 200 kg/m³ structural rigid systems for thermal insulation and impact absorption. Flexible foam dominates volume through automotive seating and furniture cushioning applications where comfort-density specifications command stable margin pools. Rigid foam represents the fastest-expanding category as EU building energy codes drive insulation retrofits across residential and commercial envelopes. Coatings and adhesives occupy specialized niches where abrasion resistance and substrate bonding performance justify premium positioning.
Regulatory Environment
REACH restricts certain isocyanate concentrations in consumer-facing products while the EU Green Deal's renovation wave targets mandate minimum thermal performance standards that elevate rigid foam specification rates. ECHA's ongoing evaluation of diisocyanate respiratory sensitization risks is reshaping occupational handling protocols and accelerating investment in low-monomer formulations. Stakeholders must monitor how the F-Gas Regulation's phase-down of blowing agents redirects formulation chemistry toward hydrofluoroolefin and hydrocarbon alternatives without compromising lambda values.
Market Dynamics
The EU Green Deal's renovation wave is compressing specification cycles for rigid foam insulation across residential and commercial building envelopes, forcing formulators to accelerate low-lambda product development while managing diisocyanate handling restrictions.
Growth Catalysts
- Building energy codes:REACH-compliant rigid foam systems are capturing retrofit demand as Germany and Poland enforce stricter thermal transmittance limits on aging housing stock.
- Automotive lightweighting:Flexible foam seating specifications are expanding as manufacturers reduce vehicle mass to meet fleet emission targets.
- Cold chain logistics:Refrigerated transport insulation demand is concentrating along Rhine-Alpine corridor distribution hubs serving temperature-sensitive pharmaceutical distribution.
Market Restraints
- Feedstock volatility:Propylene oxide and MDI precursor costs fluctuate with naphtha-cracker margins, compressing formulation margins for mid-tier suppliers.
- Supply concentration:Merchant polyol availability depends on integrated producers along Ludwigshafen-Antwerp chemical corridor, creating geographic single-source exposure.
- Substitution pressure:Mineral wool and extruded polystyrene compete for envelope insulation specifications where fire rating requirements exceed polyurethane foam capabilities.
Strategic Opportunities
- Eastern Europe retrofit gap:Bulgaria and Romania hold underpenetrated building stock with limited insulation coverage, creating specification runway as EU cohesion funds flow toward energy efficiency.
- Aliphatic coating systems:Light-stable automotive refinish and flooring topcoat applications are absorbing specialized isocyanate derivatives at premium price positions.
- Circular feedstocks:Chemolysis and glycolysis recycling pathways for end-of-life foam are qualifying for EU taxonomy-aligned investment under Green Deal industrial policy.
Industry Challenges
- Diisocyanate handling certification:ECHA's respiratory sensitization evaluation mandates retraining thousands of applicators across construction and manufacturing sectors by mandated deadlines.
- Blowing agent transitions:F-Gas Regulation phase-down forces simultaneous reformulation of lambda performance and foam dimensional stability without grandfathered product lines.
Report Scope
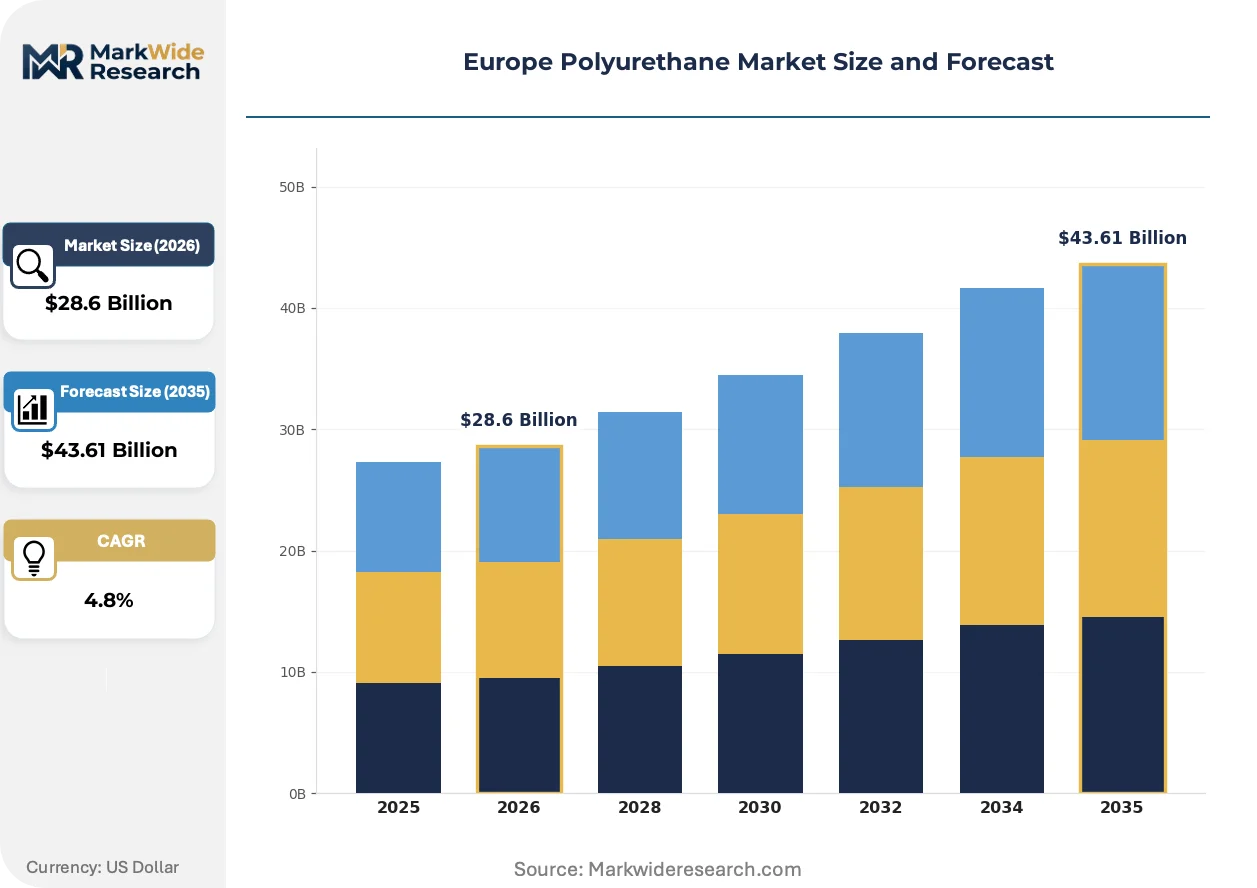
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Polyurethane Market |
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $43.61 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible Foam, Rigid Foam, Coatings, Adhesives Application: Furniture, Automotive, Construction, Insulation End User: Manufacturers, Contractors, Retailers, OEMs Form: Slabs, Blocks, Powder, Liquid |
| Companies Covered | BASF SE, Covestro AG, Huntsman Corporation, Dow Inc., Recticel NV/SA, Wanhua Chemical Group, LANXESS AG, Evonik Industries AG, Paul Bauder GmbH & Co. KG, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Polyurethane Market Trends and Innovations
Formulation chemistry and application methods are converging around sustainability metrics and occupational safety requirements, compressing development timelines while expanding addressable specification spaces.
Bio-based polyol feedstocks derived from rapeseed oil and lignin residues are unifying performance parity with petrochemical benchmarks in rigid insulation applications. Construction specifiers in Nordic markets are qualifying these systems for passive house certification. The technology is unifying cost structures between conventional and renewable feedstock pathways within three formulation generations.
REACH restrictions on diisocyanate monomer concentrations in consumer products are forcing downstream handling protocol overhauls. Industrial coating and adhesive manufacturers are investing in low-monomer prepolymer production to maintain market access. Automotive seating suppliers face the steepest compliance curve given high-volume flexible foam throughput and workforce exposure profiles.
Asset-light toll manufacturing is displacing captive production for mid-scale polyurethane converters. Regional compounders in Benelux and northern Italy are capturing formulation business from integrated producers by offering rapid batch customization and reduced minimum order quantities. Construction contractors in France and Spain are consolidating procurement through these channels to manage project-specific density and reactivity requirements without inventory risk.
Europe Polyurethane Market Segmentation
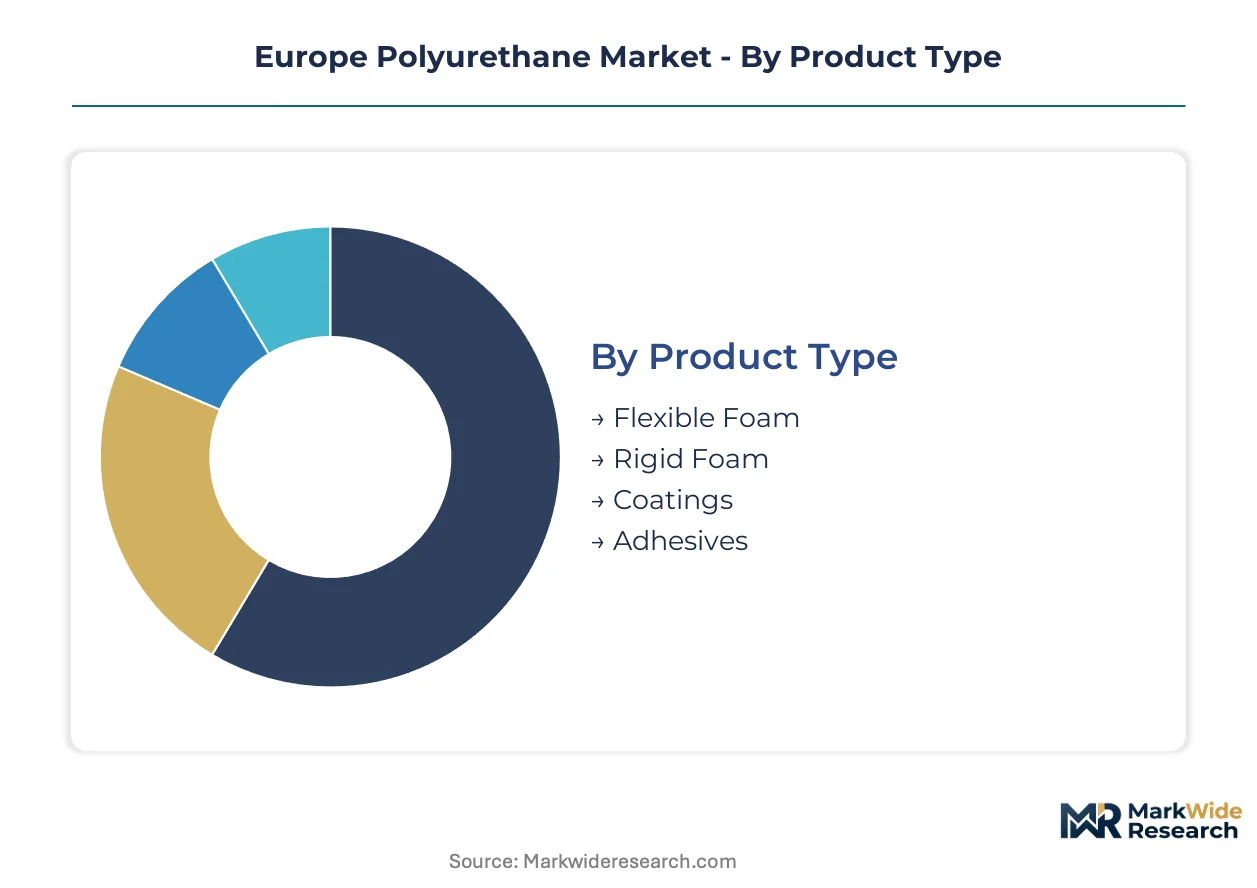
Polyurethane chemistry spans radically different performance envelopes—from 10 kg/m³ comfort foam to 200 kg/m³ structural insulation—making granular segmentation essential for matching formulation investment to specification cycles. Each category reveals distinct margin pools and regulatory exposure profiles across European end-use markets.
Product Type:
Standalone material systems dominate bulk chemical sales, while embedded formulations integrate into customer manufacturing processes with tighter co-development ties.
- Flexible Foam:Open-cell polymers tuned for resilience and compression set recovery. Automotive seating specifications in Germany's industrial corridor absorb high-volume offtake as fleet lightweighting targets intensify comfort-density requirements.
- Rigid Foam:Closed-cell structures with lambda values below 0.025 W/m·K for thermal barrier applications. Building envelope retrofits across Poland and Germany are compressing specification cycles as EU Green Deal renovation mandates tighten energy transmittance limits.
- Coatings:Abrasion-resistant film formers for substrate protection. Light-stable aliphatic systems command premium positioning in automotive refinish and flooring topcoat niches.
- Adhesives:Structural bonding formulations with tunable cure profiles. Industrial assembly applications in Benelux manufacturing clusters absorb specialized isocyanate derivatives.
Volume placements concentrate in Flexible Foam; the faster expansion belongs to Rigid Foam.
Application:
Specification authority varies sharply—architects and automotive OEMs wield direct formulation influence, while construction contractors delegate to tier-two compounders.
- Furniture:Comfort-layer specifications for residential and contract seating. Italian and Polish upholstery manufacturers maintain steady flexible foam demand through direct mill relationships.
- Automotive:Seating, interior trim, and NVH applications. German OEMs are expanding molded foam specifications to reduce vehicle mass against fleet emission compliance deadlines.
- Construction:Spray and pour-in-place systems for structural elements. French and Spanish contractors are consolidating procurement through toll manufacturers to manage project-specific density requirements.
- Insulation:Boardstock and cavity-fill systems for thermal envelopes. Nordic passive house certification programs are qualifying bio-based polyol formulations from rapeseed oil feedstocks.
Automotive commands the densest specification relationships; Insulation shows the steepest upward trajectory as building codes tighten.
End User:
Technical sophistication and volume scale determine whether procurement flows through merchant distribution or direct mill supply agreements.
- Manufacturers:Captive foam production for integrated finished goods. Major furniture and automotive seating producers in Germany maintain in-house mixing operations for quality control.
- Contractors:Site-applied insulation and adhesive systems. REACH diisocyanate handling certifications are forcing retraining investments across construction applicator networks.
- Retailers:Consumer-facing mattresses and cushioning products. Low-monomer formulation requirements are reshaping supply agreements with foam converters.
- OEMs:Original equipment specifications with embedded foam components. Cold chain logistics providers along the Rhine-Alpine corridor specify rigid foam for refrigerated transport units.
Manufacturers anchor volume commitments; Contractors present the most volatile compliance burden as ECHA protocols phase in.
Form:
Physical state dictates supply chain configuration—bulk liquid systems integrate with continuous production, while discrete units enable inventory positioning at distribution nodes.
- Slabs:Continuous-cast bun stock for fabrication into cushions and insulation boards. Central European converters slice bulk supply for just-in-time furniture component delivery.
- Blocks:Molded or cut-to-shape structural elements. Construction specifiers in Eastern Europe source block insulation for masonry cavity retrofits.
- Powder:Thermoplastic polyurethane for coating and adhesive reconstitution. Specialized compounding operations in northern Italy process powder feedstocks for niche applications.
- Liquid:Two-component systems for on-site reaction and cure. Spray foam contractors in France deploy liquid MDI-polyol combinations for building envelope air sealing.
Liquid systems capture the broadest geographic reach; Slabs retain the highest throughput density in established manufacturing corridors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity clusters along the Ludwigshafen-Antwerp chemical corridor while consumption disperses across retrofit construction sites and automotive assembly plants. This geographic split shapes logistics costs and inventory positioning for formulators serving dispersed end-use markets.
Germany
Automotive seating specifications from BMW, Mercedes-Benz, and Volkswagen absorb flexible foam volumes as fleet emission deadlines intensify lightweighting mandates. REACH diisocyanate handling certifications are forcing retraining investments across Baden-Württemberg and Bavaria manufacturing clusters. BASF SE's Ludwigshafen hub anchors integrated polyol-isocyanate supply chains serving Central European converters.
Poland
Building envelope retrofits are accelerating as EU cohesion funds flow toward residential energy efficiency programs targeting aging housing stock. The EU Green Deal's renovation wave mandates are tightening thermal transmittance limits on multi-family residential buildings. Construction contractors in Warsaw and Kraków are consolidating procurement through toll manufacturers to manage project-specific density requirements.
France
Spray foam insulation demand is concentrating in Île-de-France and Auvergne-Rhône-Alpes as commercial building retrofits advance toward carbon neutrality targets. ECHA's respiratory sensitization protocols are reshaping applicator certification requirements across construction networks. Regional compounders in northern Italy are capturing formulation business from French contractors seeking rapid batch customization.
Italy
Furniture upholstery manufacturers in Lombardy and Veneto maintain steady flexible foam demand through direct mill relationships with foam converters. The F-Gas Regulation's blowing agent phase-down is redirecting formulation chemistry toward hydrofluoroolefin alternatives. Specialized powder compounding operations in Piedmont process thermoplastic polyurethane feedstocks for niche coating applications.
Spain
Construction insulation specifications are expanding in Madrid and Catalonia as building energy codes tighten envelope performance standards. Asset-light toll manufacturing is displacing captive production for mid-scale polyurethane converters serving regional contractors. Mediterranean climate conditions are driving demand for light-stable aliphatic coating systems in automotive refinish applications.
Europe Polyurethane Market Competitive Landscape
Capital-heavy integrated producers compete with asset-light regional compounders across formulation and distribution layers. The market structure concentrates upstream polyol and isocyanate production among three chemical majors while fragmenting downstream through toll manufacturers and specialized converters. Strategic archetypes span integrated petrochemical giants, regional formulation specialists, and circular feedstock innovators. Dominant competitive moves include backward integration into bio-based polyol feedstocks and geographic expansion into Eastern European retrofit markets.
Among Germany-based chemical conglomerates, BASF SE and Covestro AG exemplify the integrated producer archetype with captive polyol-isocyanate capabilities. Huntsman Corporation represents the transatlantic specialist model with MDI capacity positioned to serve Mediterranean construction markets. These three anchors demonstrate how scale chemistry and application expertise stratify competitive positioning across rigid insulation, flexible foam, and specialized coating segments.
| Leading Market Players |
|---|
| BASF SE |
| Covestro AG |
| Huntsman Corporation |
| Dow Inc. |
| Recticel NV/SA |
| Wanhua Chemical Group |
| LANXESS AG |
| Evonik Industries AG |
| Paul Bauder GmbH & Co. KG |
| Others |
Pricing and Supply Chain Analysis
EU Green Deal renovation mandates are compressing specification cycles for rigid foam insulation, forcing formulators to absorb reformulation costs while managing diisocyanate handling certification expenses that cascade through contractor pricing. This demand-side pressure concentrates procurement leverage among toll manufacturers offering rapid batch customization, fragmenting volume discounts that once flowed to integrated producers.
Pricing Analysis
Cost compression in mid-tier flexible foam traces to propylene oxide and MDI precursor volatility that erodes formulation margins when naphtha-cracker spreads widen. Three-tier pricing structure across premium, standard, and economy levels separates REACH-compliant low-monomer systems from conventional formulations and unbranded commodity grades. Price differentiation rests on certification tier and volume scale, with automotive seating suppliers least sensitive due to embedded specification authority while construction contractors face acute pressure from project-based procurement consolidation.
Supply Chain Analysis
Dual-sourcing requirements from German automotive OEMs and French construction contractors are forcing qualification of secondary polyol suppliers beyond the Ludwigshafen-Antwerp corridor. Merchant availability draws from Germany, Belgium, and the Netherlands, with propylene oxide, MDI, and specialty isocyanates as critical inputs. Single-source vulnerability concentrates around integrated producers' captive supply chains, while distribution runs through regional compounders in Benelux and northern Italy offering reduced minimum order quantities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe polyurethane market sits in a blowing agent transition phase, with hydrofluoroolefin and hydrocarbon alternatives displacing F-Gas-regulated legacy systems. This chemistry shift rewards formulators who qualify low-lambda formulations ahead of mandated phase-down deadlines.
For Market Incumbents: Hedge margin exposure by securing captive bio-based polyol supply from rapeseed oil and lignin feedstock partnerships before cost parity closes. Expand toll manufacturing capacity in Poland and Romania to capture EU cohesion fund flows toward Eastern European retrofit markets. Mineral wool substitution in fire-critical specifications threatens rigid foam share; counter with enhanced lambda performance certification for passive house programs. For New Entrants and Emerging Players: Launch via asset-light toll manufacturing models serving French and Spanish construction contractors seeking project-specific density customization without inventory risk. Bulgaria and Romania present the most penetrable geographies, with underinsulated building stock and accelerating EU renovation fund disbursement. Target cold chain logistics providers along the Rhine-Alpine corridor with specialized rigid foam formulations for refrigerated pharmaceutical transport. For Investors and Strategic Acquirers: The window for entry favors regional compounders with REACH-compliant low-monomer capabilities and established contractor networks. Long-term viability hinges on qualification for EU taxonomy-aligned circular feedstock investments under chemolysis and glycolysis recycling pathways. Watch ECHA's final diisocyanate respiratory sensitization ruling as the inflection signal that would accelerate consolidation among non-compliant mid-scale converters.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-based Polyols | Rapeseed oil and lignin feedstock partnerships secure cost parity with petrochemical benchmarks within three formulation generations. |
| Capacity Expansion in Eastern Europe | Poland and Romania toll manufacturing positions capture EU cohesion fund flows toward underpenetrated building stock retrofits. |
| Low-monomer Formulation Certification | REACH-compliant prepolymer production maintains market access as ECHA respiratory sensitization protocols phase in. |
| Long-term Supply Agreement with Automotive OEMs | German OEM flexible foam specifications intensify as fleet lightweighting deadlines compress sourcing cycles. |
| Joint Venture for Circular Feedstock Recycling | Chemolysis and glycolysis pathways qualify for EU taxonomy-aligned investment under Green Deal industrial policy. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews across plant managers at integrated producers, procurement leads at automotive seating suppliers, distribution channel partners in Benelux and northern Italy, and technical R&D directors at formulation specialists. Cefic sector reports, ECHA regulatory submissions, SEC 10-K disclosures from listed chemical conglomerates, and EU customs trade databases provided validation layers. Bottom-up volume modeling and top-down value reconciliation triangulated outputs across the analysis window.
Segment-level granularity modeled product type splits across flexible foam, rigid foam, coatings, and adhesives; application dimensions spanning furniture, automotive, construction, and insulation; and form factors including slabs, blocks, powder, and liquid systems. CAGRs derived from historical trajectory analysis adjusted for regulatory inflection points and feedstock cost correlation models. Blowing agent transition timelines and EU Green Deal renovation fund disbursement schedules served as industry-specific forecast inputs.
Feedstock volatility, regulatory ruling delays, and substitution acceleration are the dominant revision risks to the outlook. Deviation in ECHA's final diisocyanate handling certification deadlines would shift contractor compliance costs and demand timing materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Global Fluoropolymer Market
Polymers & Resins
Redispersible Polymer Powder Market
Polymers & Resins
Global Emulsion Polymer Market
Polymers & Resins
Phenolic Resin Market
Polymers & Resins
Europe Polyolefin Market
Polymers & Resins
Polyurethanes (PU) Market
Polymers & Resins
Polyacrylate Market
Polymers & Resins
Hydrocarbon Resins Market
Polymers & Resins
PET Foam Core Market
Polymers & Resins
Styrene-Butadiene-Styrene Block Copolymer Market
Polymers & Resins
Expanded Thermoplastic Polyurethane Market
Polymers & Resins
Methyl Methacrylate Acrylonitrile Butadiene Styrene (MABS) Market
Polymers & Resins
North America Epoxy Resins Market
Polymers & Resins
Polycarbonate Glazing Market
Polymers & Resins
Flame Retardant Polyester Resins Market
Polymers & Resins
CO2-Based Polycarbonate Polyols for Flexible PU Foam Market