
 Cyclic Olefin Polymers (COP) Polymer Syringes Market | 2026-2036
Cyclic Olefin Polymers (COP) Polymer Syringes Market Size, Share, and Industry Trends Forecast 2026-2036
Cyclic Olefin Polymers (COP) Polymer Syringes Market Outlook
Pre-filled syringe bundling with safety devices and needle-stick protection is recalibrating procurement criteria across hospital and home healthcare channels. SCHOTT leverages its glass-to-polymer technology crossover to anchor high-barrier COP syringe output for mRNA and protein-based therapies. Gerresheimer differentiates through integrated contract development and manufacturing services that extend from primary packaging to fill-finish operations. Nipro Corporation competes on manufacturing scale across Asian pharmaceutical supply chains.
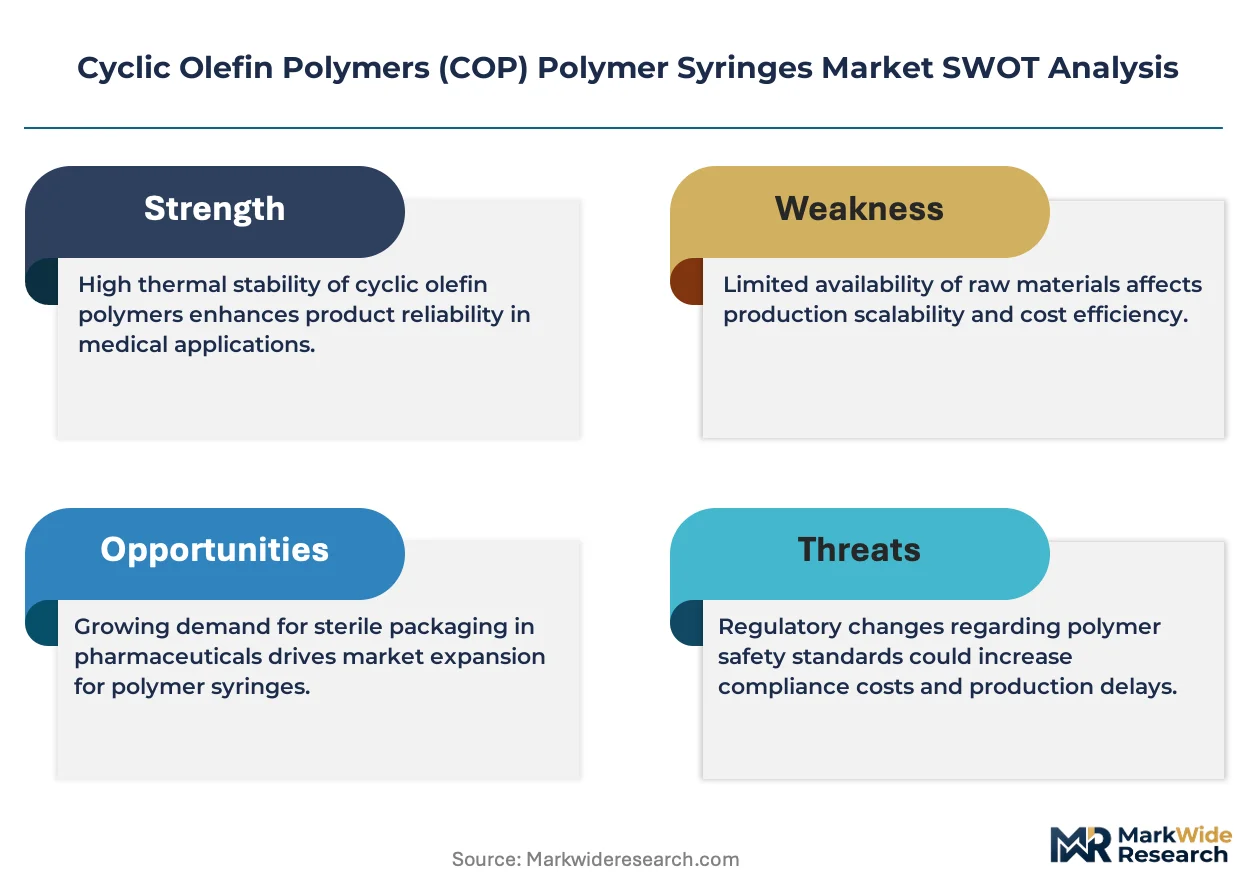
Cyclic olefin polymer syringes are thermoplastic containers molded from amorphous hydrocarbon resins with glass-like clarity, low moisture permeation, and extractables profiles superior to conventional polypropylene, serving primarily as primary packaging for parenteral drug delivery where silicone-free or tungsten-free interiors reduce protein aggregation risk. Pre-filled syringes command the dominant volume position as biologics manufacturers prioritize ready-to-administer formats that minimize contamination exposure and dosing error. Dual-chamber syringes represent the fastest-growing configuration, driven by lyophilized drug reconstitution needs in oncology and autoimmune therapy segments where stability demands separation of active and diluent components until point of use.
The FDA's combination product regulations and the EMA's Annex 1 revision on sterile manufacturing are converging to mandate enhanced container closure integrity verification and particulate control, directly elevating COP syringe qualification requirements for new drug applications. ISO 11040 prefilled syringe standards and USP Chapter 661.1 plastic packaging system testing create layered compliance thresholds that filter supplier bases toward vertically integrated manufacturers with in-house polymerization and molding capabilities. Stakeholders must monitor evolving pharmacopeial extractables testing protocols and polymer recycling mandates as sustainability criteria increasingly penetrate pharmaceutical packaging procurement specifications.
Market Dynamics
FDA combination product guidance and EMA Annex 1 sterile manufacturing revisions are forcing biologics manufacturers to requalify primary packaging systems, compressing supplier bases toward polymer syringe specialists with integrated extractables testing capabilities.
Growth Catalysts
- EMA Annex 1 Revision:Sterile manufacturing mandates for enhanced container closure integrity verification are disqualifying conventional polypropylene syringes from European biologics filings.
- Silicone-free interior demand:Protein-based therapy manufacturers specify tungsten-free COP barrels to minimize aggregation risk in monoclonal antibody formulations.
- Germany production clustering:Gerresheimer and SCHOTT anchor advanced polymer syringe output for European biotech supply chains, creating regional captive demand.
Market Restraints
- Zeoner resin supply concentration:Mitsui Chemicals and JSR control global COP polymer feedstock, exposing converters to single-source dependency risk.
- ISO 11040 certification timelines:Prefilled syringe standard compliance requires 18-24 month qualification cycles that delay new entrant market entry.
- Glass-to-polymer switching friction:Established fill-finish lines optimized for borosilicate barrels resist capital reconfiguration for thermoplastic handling systems.
Strategic Opportunities
- Home healthcare self-administration:Rheumatoid arthritis and multiple sclerosis patients in the United States are driving demand for prefilled autoinjector-compatible COP syringes with integrated needle shields.
- Dual-chamber lyophilized reconstitution:Oncology drug developers are separating active powder from diluent in single-unit COP systems for point-of-use mixing.
- EU Green Deal packaging mandates:Pharmaceutical procurement specifications are beginning to incorporate polymer recycling content thresholds that favor COP over multilayer barrier plastics.
Industry Challenges
- Extractables chemist scarcity:Specialized analytical toxicology expertise for USP Chapter 661.1 compliance testing is concentrated among legacy glass-to-polymer crossover firms.
- Silicone oil alternative validation:Eliminating baked-on silicone for plunger lubrication requires extensive functional equivalence studies that extend development timelines.
- Cross-border polymer lot traceability:Multi-site molding operations struggle to maintain batch-level documentation for FDA drug master file submissions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cyclic Olefin Polymers (COP) Polymer Syringes Market |
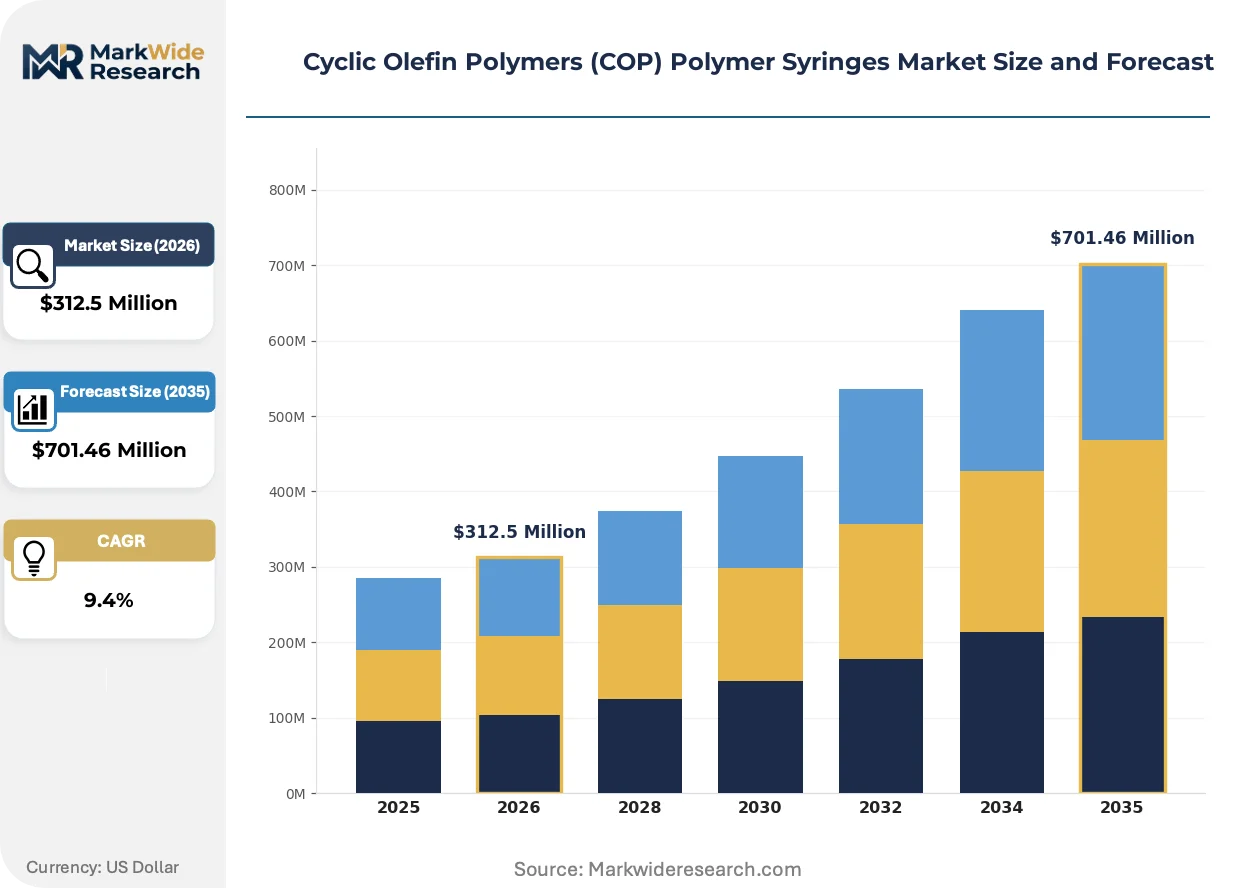
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $701.46 Million |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pre-filled Syringes, Standalone Syringes, Dual-chamber Syringes, Disposable Syringes Application: Vaccines, Biologics, Hormones, Injectable Drugs End User: Hospitals, Clinics, Pharmacies, Home Healthcare Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesalers |
| Companies Covered | SCHOTT, Gerresheimer, West Pharmaceutical Services, Nipro Corporation, Stevanato Group, Catalent, Becton, Dickinson and Co, Vetter Pharma International GmbH, Terumo Corp, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cyclic Olefin Polymers (COP) Polymer Syringes Market Strategic Shifts
Container closure integrity verification technologies and polymer barrier engineering are converging to redefine qualification protocols for parenteral packaging, shifting competitive advantage toward vertically integrated manufacturers with captive polymerization capabilities.
Plasma-enhanced chemical vapor deposition barrier coatings are absorbing moisture ingress protection functions previously addressed through multilayer coextrusion, enabling thinner-wall COP syringes that reduce resin consumption per unit. Biologics manufacturers in Switzerland and Germany are piloting these coated single-layer systems for peptide formulations with intermediate stability requirements. The technology is absorbing market share from cyclic olefin copolymer (COC) blends by matching their oxygen transmission rates at lower material cost.
REACH restriction proposals on per- and polyfluoroalkyl substances are accelerating fluoropolymer liner replacement programs in high-barrier syringe applications. European converters are qualifying hydrocarbon-based alternatives for sensitive biologics where metal-catalyzed oxidation presents stability risks. The regulatory pressure is most acute in France and Germany, where ANSM and BfArM inspections now scrutinize fluorinated material declarations in combination product submissions.
Home infusion therapy distributors are consolidating prefilled syringe procurement through direct manufacturer agreements that bypass traditional wholesale channels. Hospital systems in the United States are compressing supplier panels to three-to-five preferred vendors with integrated safety device bundling capabilities. This concentration is most visible in rheumatology and endocrinology clinics where self-administration training programs create sticky relationships between device manufacturers and specialty pharmacies.
Cyclic Olefin Polymers (COP) Polymer Syringes Market Segmentation
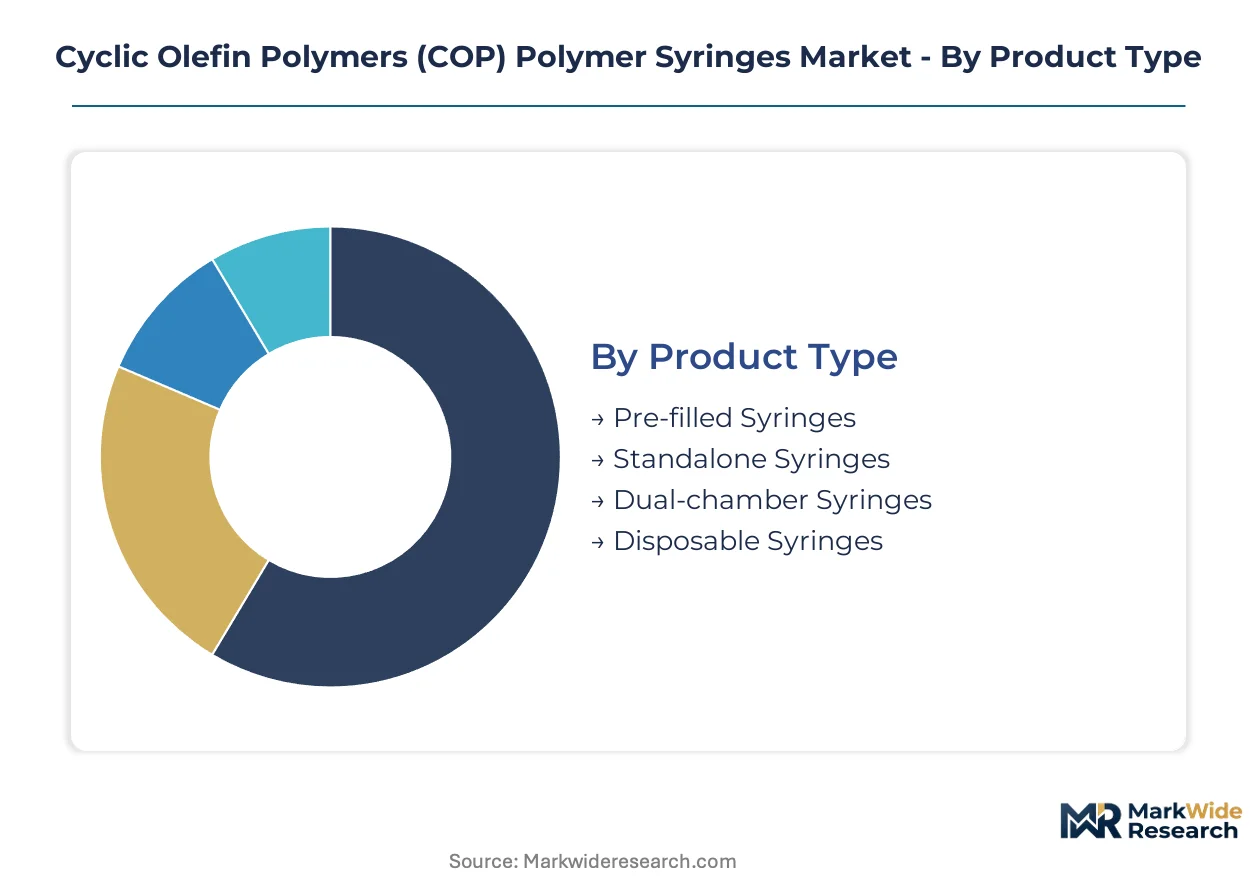
COP syringe procurement decisions hinge on ISO 11040 compliance tiers and USP Chapter 661.1 extractables profiles, with each segment carrying distinct qualification burdens that filter supplier eligibility. Pharmaceutical manufacturers map product configurations directly to therapy stability requirements and administration settings, creating rigid segment boundaries that resist cross-selling.
Product Type:
ISO 11040-4 certification requirements vary sharply across barrel configurations, with pre-filled formats demanding the most extensive extractables documentation and dual-chamber systems requiring separate chamber validation protocols.
- Pre-filled Syringes:Ready-to-administer COP barrels with integrated stoppers and needle shields undergo 18-24 month USP Chapter 661.1 qualification cycles. Demand concentrates in German biologics manufacturing where EMA Annex 1 sterile manufacturing mandates disqualify polypropylene alternatives for monoclonal antibody filings.
- Dual-chamber Syringes:Two-compartment COP systems separate lyophilized active from diluent via breakable seals or movable partitions. Swiss oncology developers are piloting these for point-of-use reconstitution of peptide therapies where stability demands pre-dose separation.
- Standalone Syringes:Empty COP barrels for compounding pharmacies and clinical trial supply chains.
- Disposable Syringes:Single-use COP systems for emergency medicine and field vaccination campaigns.
Leading the category by volume: Pre-filled Syringes. Growing fastest: Dual-chamber Syringes.
Application:
Biologics manufacturers drive premium COP specifications, while vaccine producers prioritize cost-scalable formats that accommodate high-volume pandemic response manufacturing.
- Biologics:Protein-based therapies including monoclonal antibodies and fusion proteins require tungsten-free, silicone-minimized COP interiors to prevent aggregation. FDA combination product regulations for these therapies mandate container closure integrity verification that elevates barrier specification requirements above other application segments.
- Vaccines:mRNA and viral vector formulations utilize COP's moisture barrier properties for cold chain stability, with fill-finish lines in Belgium and the Netherlands scaling output for European immunization programs.
- Hormones:Peptide and steroid injectables where oxygen sensitivity drives barrier selection.
- Injectable Drugs:Small-molecule parenterals with intermediate stability requirements.
Biologics command the highest specification tier. Vaccines scale the largest absolute volume.
End User:
Procurement authority and safety device bundling requirements diverge sharply between institutional buyers with centralized contracting and direct-to-patient channels with training-dependent adherence protocols.
- Hospitals:Acute care systems in the United States consolidate COP syringe procurement through group purchasing organizations that mandate integrated needle-stick protection and autoinjector compatibility for biologics administration.
- Home Healthcare:Self-administration of rheumatoid arthritis and multiple sclerosis therapies drives demand for prefilled COP syringes with ergonomic plunger rods and audible dose-completion indicators, with specialty pharmacies managing patient training programs.
- Clinics:Outpatient infusion centers with mixed biologics and vaccine portfolios.
- Pharmacies:Retail and compounding channels with lower barrier specification requirements.
Hospitals dominate contract value. Home Healthcare expands most quickly on self-injection trends.
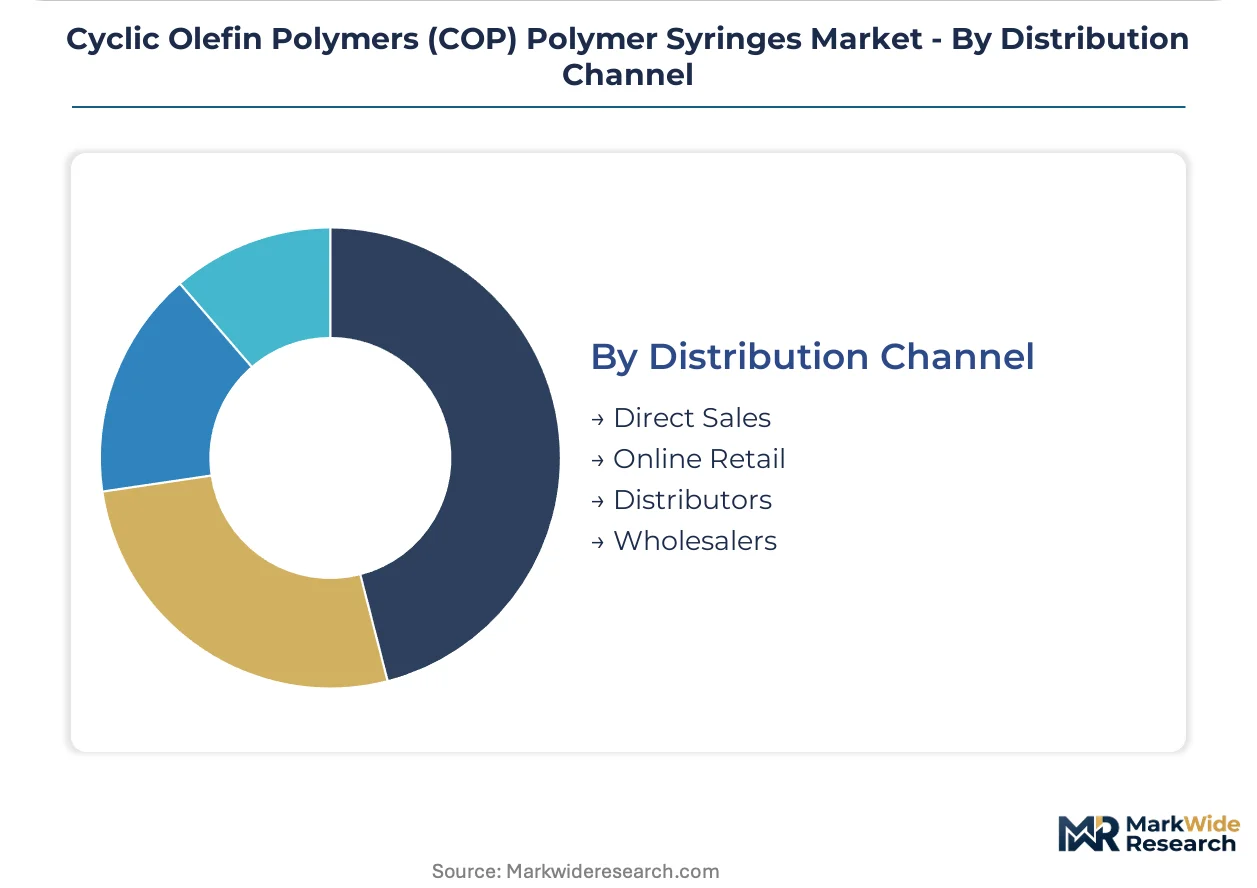
Distribution Channel:
Channel selection reflects shipment integrity requirements and lot traceability burdens, with direct sales carrying FDA drug master file documentation obligations that distributors cannot assume.
- Direct Sales:Manufacturer-to-pharma relationships for prefilled COP syringes where batch-level polymer lot traceability and extractables certificates of analysis accompany every shipment. German fill-finish contractors prefer this channel for EMA compliance documentation.
- Distributors:Regional medical supply intermediaries serving hospital systems with consolidated safety device and syringe bundling.
- Online Retail:Direct-to-consumer channels for home healthcare patients with established therapy prescriptions.
- Wholesalers:High-volume vaccine supply chains with standardized product configurations.
Direct Sales captures the highest-margin transactions. Distributors handle the broadest SKU breadth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany manufactures the majority of advanced COP syringes for European biologics supply chains, while the United States consumes the largest absolute volume through its hospital systems and specialty pharmacy networks. Japan and Switzerland anchor precision polymer processing for high-barrier applications. China is scaling domestic converter capacity to reduce import dependency for vaccine packaging.
United States
Hospital systems in the United States consolidate COP syringe procurement through group purchasing organizations that mandate integrated needle-stick protection for biologics administration. FDA combination product regulations for monoclonal antibodies require container closure integrity verification that elevates barrier specifications above other markets. The Northeast Corridor hosts specialty pharmacy networks managing patient training programs for rheumatoid arthritis self-injection therapies.
Germany
German fill-finish contractors drive premium COP specifications for European biologics manufacturing where EMA Annex 1 sterile manufacturing mandates disqualify polypropylene alternatives. The country's national pharmaceutical regulator enforces enhanced extractables documentation for combination product submissions. Bavaria and North Rhine-Westphalia anchor integrated polymer syringe production with captive molding and safety device assembly operations.
Switzerland
Swiss oncology developers pilot dual-chamber COP systems for point-of-use reconstitution of peptide therapies requiring pre-dose separation of active and diluent. Swissmedic inspections scrutinize fluorinated material declarations in combination product submissions following REACH restriction proposals. The Basel region concentrates biologics packaging innovation with proximity to major pharmaceutical headquarters.
Japan
Japanese pharmaceutical manufacturers specify tungsten-free, silicone-minimized COP interiors for protein-based therapies to prevent aggregation. The country's national pharmaceutical regulator aligns with ISO 11040 prefilled syringe standards that filter supplier bases toward vertically integrated manufacturers. The Kanto region around Tokyo hosts precision polymer processing for high-barrier parenteral packaging applications.
China
Domestic vaccine producers in China scale COP syringe adoption for mRNA and viral vector formulations requiring moisture barrier properties for cold chain stability. The country's national pharmaceutical regulator strengthens extractables testing protocols for imported polymer packaging systems. The Yangtze River Delta concentrates converter capacity expansion to reduce dependency on Japanese and German polymer feedstock suppliers.
Cyclic Olefin Polymers (COP) Polymer Syringes Market Competitive Environment
The competitive structure tilts toward vertically integrated polymer specialists with captive resin conversion and fill-finish service capabilities. Three archetypes dominate: glass-to-polymer crossover firms leveraging existing pharmaceutical relationships, pure-play polymer converters with ISO 11040 certification depth, and contract development and manufacturing organizations bundling primary packaging with drug product services. Capacity expansion in Germany and strategic partnerships for dual-chamber technology access represent the dominant competitive moves.
Among German-based integrated packaging specialists, Gerresheimer and SCHOTT exemplify the glass-to-polymer crossover archetype with established pharmaceutical customer relationships. West Pharmaceutical Services occupies a position within the North American safety device bundling tier. Nipro Corporation represents the Asian manufacturing scale archetype serving regional vaccine supply chains. These three anchors illustrate how geographic proximity to major biologics manufacturing clusters shapes competitive positioning.
| Leading Market Players |
|---|
| SCHOTT |
| Gerresheimer |
| West Pharmaceutical Services |
| Nipro Corporation |
| Stevanato Group |
| Catalent |
| Becton, Dickinson and Co |
| Vetter Pharma International GmbH |
| Terumo Corp |
| Others |
Value Chain & Pricing Dynamics
Captive polymerization by German and Japanese converters anchors supply security and pricing power for high-barrier COP syringe grades, insulating qualified manufacturers from Zeoner resin spot market volatility while commanding ISO 11040 certification premiums over outsourced molding competitors.
Pricing Analysis
Cost compression in standard-grade COP barrels accelerates as Chinese converters expand capacity for vaccine packaging applications, eroding margin buffers established by legacy European suppliers. Three-tier pricing structure across premium ISO 11040-certified, standard medical-grade, and economy vaccine-grade levels separates qualification-intensive biologics specifications from high-volume pandemic response contracts. Price differentiation traces to extractables documentation depth and EMA Annex 1 compliance verification, with biologics manufacturers least sensitive to unit cost and vaccine procurement officers most responsive to volume discounts.
Supply Chain Analysis
Single-source vulnerability sits with Mitsui Chemicals and JSR for Zeoner resin feedstock, exposing global COP syringe output to Japanese petrochemical scheduling disruptions. Manufacturing concentrates in Germany, Japan, and emerging Chinese converter facilities near Yangtze River Delta vaccine fill-finish clusters. Raw material dependencies encompass amorphous hydrocarbon resins, tungsten-free plunger components, and plasma-enhanced barrier coatings. Tariff exposure on Japanese resin imports into European molding operations threatens cost structures. Distribution runs through direct manufacturer-to-pharma relationships for prefilled formats, with regional distributors handling standardized disposable syringe volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
COP syringe technology is displacing borosilicate glass in protein-based therapy packaging, creating transition-phase positioning opportunities for stakeholders with extractables testing capabilities and EMA Annex 1 compliance infrastructure.
For Market Incumbents: Deepen backward integration into Zeoner resin conversion or secure long-term offtake agreements with Mitsui Chemicals and JSR to defend against supply disruption threats from Asian competitors. Anchor capacity expansion in Bavaria and North Rhine-Westphalia to maintain proximity to German biologics fill-finish contractors. Prioritize dual-chamber molding technology R&D to capture lyophilized reconstitution growth in Swiss oncology pipelines. For New Entrants and Emerging Players: Direct-to-specialty-pharmacy digital channels bypass consolidated hospital GPO procurement panels for rheumatoid arthritis and multiple sclerosis self-injection therapies. Target home healthcare autoinjector-compatible formats where patient training programs create sticky relationships absent in institutional contracting. Penetrate through integrated safety device bundling rather than commodity barrel supply. For Investors and Strategic Acquirers: Exit pathways concentrate in contract development and manufacturing organizations with captive COP syringe molding and fill-finish service bundling. Long-term viability favors vertically integrated packaging specialists with in-house polymerization capabilities over pure-play converters exposed to resin price volatility. Watch FDA combination product submission volumes for monoclonal antibodies as inflection indicator for premium barrier demand.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Chamber Molding Technology Investment | Captures lyophilized reconstitution demand from Swiss and German oncology developers. |
| EMA Annex 1 Compliance Certification | Qualifies suppliers for European biologics filings that disqualify polypropylene alternatives. |
| Backward Integration into Zeoner Resin Conversion | Insulates margin structure from Mitsui Chemicals and JSR supply concentration risk. |
| Direct Specialty Pharmacy Channel Development | Bypasses hospital GPO consolidation for rheumatoid arthritis self-injection therapies. |
| Plasma-Enhanced Barrier Coating Qualification | Enables thinner-wall COP syringes that reduce resin consumption per unit for peptide formulations. |
Study Parameters
Document review covered FDA combination product filings, EMA Annex 1 revision drafts, ISO 11040 certification registries, and USP Chapter 661.1 testing protocols, complemented by interviews with biologics packaging procurement managers, regulatory affairs directors at German fill-finish contractors, extractables testing laboratory heads, and specialty pharmacy network operators. Secondary validation drew from pharmaceutical packaging trade customs data, polymer resin import records, and hospital GPO contract disclosures. Bottom-up volume modeling triangulated against top-down therapy demand projections.
Historical shipment patterns cross-referenced against panel input from converter capacity planners and resin procurement officers anchored volume and value outputs across the analysis window. Segmentation dimensions encompassed product configuration, application stability tier, end-user procurement authority, and regional regulatory cluster. CAGRs derived from therapy pipeline analysis and fill-finish capacity expansion schedules. Forecast inputs included monoclonal antibody filing volumes and mRNA vaccine cold chain packaging requirements.
The model holds under stable EMA Annex 1 implementation timelines and continued Zeoner resin supply from Japanese petrochemical producers; deviation in REACH restriction enforcement or fluoropolymer substitution mandates would shift barrier coating technology adoption curves. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Fluorinated Polyimide Market
Polymers & Resins
Asia-Pacific Polyethylene Wax Market
Polymers & Resins
Construction Polymer Market
Polymers & Resins
Low Density Polyethylene Market
Polymers & Resins
Global Cyanate Ester Resins Market
Polymers & Resins
Polymer Modifiers Market
Polymers & Resins
India Polyacrylamide Copolymer Market
Polymers & Resins
Polyether Amine Market
Polymers & Resins
Soft PVC Sealing Strip Market
Polymers & Resins
Bio-Based Emulsion Polymers Market
Polymers & Resins
Global Polymer Dispersion Market
Polymers & Resins
TPEE in Automotive Industry Market
Polymers & Resins
Water Soluble Polymers Market
Polymers & Resins
Polyglycerol Market
Polymers & Resins
C9 Resin Market
Polymers & Resins
Poly(P-Phenylene Ether) (PPE) Market