
 Global UV-Cured Coatings Market | 2026-2036
Global UV-Cured Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Global UV-Cured Coatings Market Foresight
Software-defined formulation management is decoupling coating performance from fixed resin recipes, letting manufacturers reconfigure curing parameters without reformulating base chemistry. AkzoNobel NV leverages digital tinting and spectral matching platforms to shorten custom color development cycles for automotive component clients. PPG Industries anchors its UV-cured portfolio around proprietary oligomer architectures that reduce mercury vapor lamp energy intensity by one-third. Dymax Corp. specializes in light-curable adhesives and conformal coatings for electronics, occupying a defensible niche in medical device and circuit board assembly.
UV-cured coatings are liquid or powder formulations that polymerize through free-radical or cationic crosslinking when exposed to ultraviolet radiation in the 200–400 nanometer range, typically achieving full cure in seconds without thermal drying. Their primary purpose is to deliver hard, chemically resistant surface finishes with near-zero volatile organic compound emissions for substrates that cannot tolerate heat exposure. Acrylic formulations lead volume consumption due to their balanced adhesion, weatherability, and cost structure across wood finishing and packaging applications. UV-LED technology is displacing mercury vapor lamp installations fastest in electronics coating lines where substrate heat sensitivity and mercury disposal liability concentrate buyer preference. Epoxy segments command premium positioning in protective films and industrial maintenance where chemical resistance requirements justify higher formulation costs.
EPA regulations under the National Emission Standards for Hazardous Air Pollutants restrict solvent-based coating use in wood furniture manufacturing, directly expanding UV-cured substitution eligibility across Midwestern and Southeastern US production clusters. ECHA REACH Annex XVII substance restrictions and RoHS substance limits shape European formulator R&D priorities by phasing out certain photoinitiators and restricting heavy metal pigments in electronics-facing coatings. China's MEE enforces increasingly stringent VOC emission caps for industrial coating operations in the Yangtze River Delta and Pearl River Delta manufacturing belts. Stakeholders must monitor photoinitiator supply security and UV-LED equipment capex trajectories as these variables determine conversion economics for mid-size coating operations.
Market Dynamics
UV-LED curing hardware is automating production line reconfiguration across electronics and automotive component manufacturing, compressing the capital payback window for mercury lamp replacement and reshaping equipment procurement priorities for coating operations worldwide.
Growth Catalysts
- EPA NESHAP enforcement:Wood furniture manufacturers in the US Midwest and Southeast face mandatory solvent-based coating phaseouts, expanding UV-cured substitution eligibility across cabinetry and millwork production clusters.
- Photoinitiator chemistry advances:Formulators now deploy TPO and BAPO variants with broader spectral sensitivity, enabling faster line speeds in packaging and label printing without mercury lamp heat damage.
- China's Yangtze River Delta concentration:Industrial coating infrastructure density in Jiangsu and Zhejiang provinces supports rapid UV-LED adoption among electronics contract manufacturers serving medical device and consumer appliance brands.
Market Restraints
- Photoinitiator supply concentration:European and Chinese specialty chemical producers control 80% of TPO-L and acylphosphine oxide manufacturing, creating input cost volatility and security-of-supply exposure for formulators.
- Substrate adhesion limitations:Low-surface-energy plastics and oily woods require proprietary oligomer modifications that raise per-liter formulation costs 15-40% above standard acrylic systems.
- Mercury lamp disposal liability:RoHS substance restrictions and national hazardous waste frameworks impose end-of-life compliance burdens that slow full UV-LED conversion for capital-constrained mid-size operations.
Strategic Opportunities
- India's industrial coating modernization:BIS standards alignment with REACH substance limits and PLI scheme incentives for domestic electronics manufacturing create first-mover advantage for UV-LED equipment suppliers.
- 3D printing post-processing:Photopolymer resin printing expansion in dental, hearing aid, and prototyping applications generates demand for compatible UV-cured finishing systems with biocompatibility certification.
- Software-defined formulation platforms:Digital tinting and spectral matching convergence with IoT-enabled curing parameter control enables mass customization without base chemistry reformulation.
Industry Challenges
- Photochemistry expertise scarcity:Formulation chemists with combined free-radical and cationic curing knowledge command premium compensation, constraining R&D expansion at mid-size coating houses.
- UV-LED capex intensity:Full production line conversion requires $2-4 million per installation for optical systems, nitrogen inerting, and conveyor modifications, stretching payback periods for sub-$50 million revenue operations.
- Multi-jurisdictional certification timelines:ECHA REACH Annex XVII substance notifications, FDA 510(k) medical device coatings clearance, and China's MEE environmental compliance documentation create 18-36 month product launch cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global UV-Cured Coatings Market |
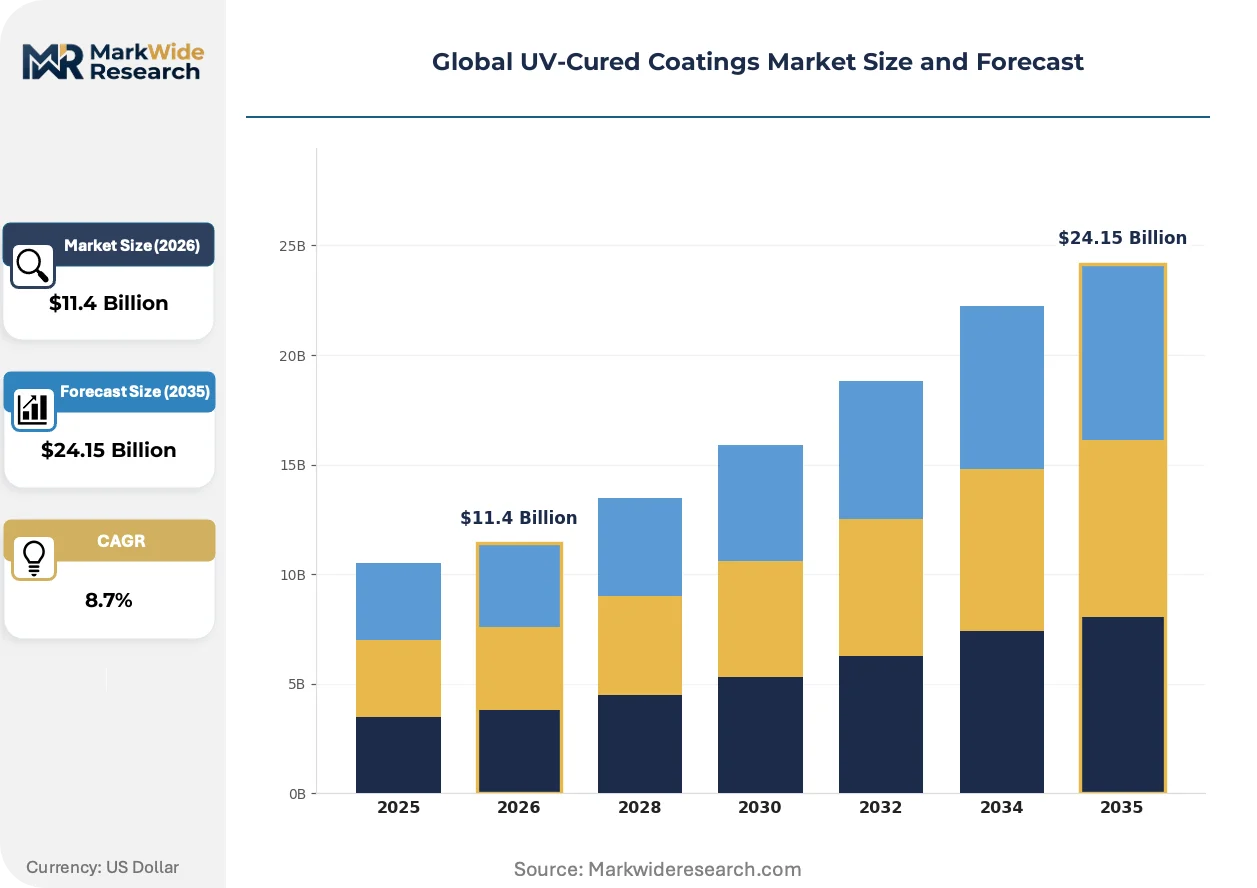
| Market Size in 2026 | $11.4 Billion |
| Market Size in 2035 | $24.15 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Acrylic, Epoxy, Polyester, Polyurethane, Silicone, Fluoropolymer Technology: UV-LED, Mercury Vapor Lamps, Excimer Lamps, Pulsed Xenon Lamps, Metal Halide Lamps Application: Wood Finishing, Automotive Components, Electronics Coating, Packaging, Textiles, Protective Films End User Industry: Furniture Manufacturers, Vehicle Assemblers, Consumer Electronics, Food Packaging, Apparel Producers |
| Companies Covered | AkzoNobel NV, PPG Industries, The Sherwin-Williams Company, Dymax Corp., Nippon Paints, BASF SE, Axalta Coating Systems, Allnex GmbH, Arkema, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global UV-Cured Coatings Market Shifts & Advancements
Formulation science and hardware engineering are converging to eliminate the thermal curing bottleneck, with digital control systems now enabling real-time adjustment of polymerization parameters without stopping production lines.
UV-LED array technology is automating wavelength-specific curing protocols that previously required manual lamp configuration. Electronics manufacturers in Germany and South Korea are deploying 395 nanometer and 365 nanometer dual-source systems for multi-layer conformal coatings on heat-sensitive circuit boards. This hardware flexibility is compressing the minimum economic order quantity for custom formulation runs from thousands of liters to hundreds.
ECHA REACH Annex XVII restrictions on certain photoinitiators are forcing formulators to validate TPO alternatives across wood finishing and packaging applications. The regulatory friction is most acute for food-contact coatings, where migration testing protocols add 12-18 months to reformulation timelines. European packaging converters are consolidating supplier relationships to share compliance documentation burdens.
Specification authority is migrating from coating applicators to brand-owner sustainability procurement teams. Automotive OEMs and furniture retailers now mandate VOC emission disclosures and carbon footprint documentation upstream, bypassing traditional distributor channels. This buyer concentration is most visible in the US and German automotive supply chains, where tier-one component suppliers face audit requirements that previously applied only to direct coating operations.
Global UV-Cured Coatings Market Segmentation
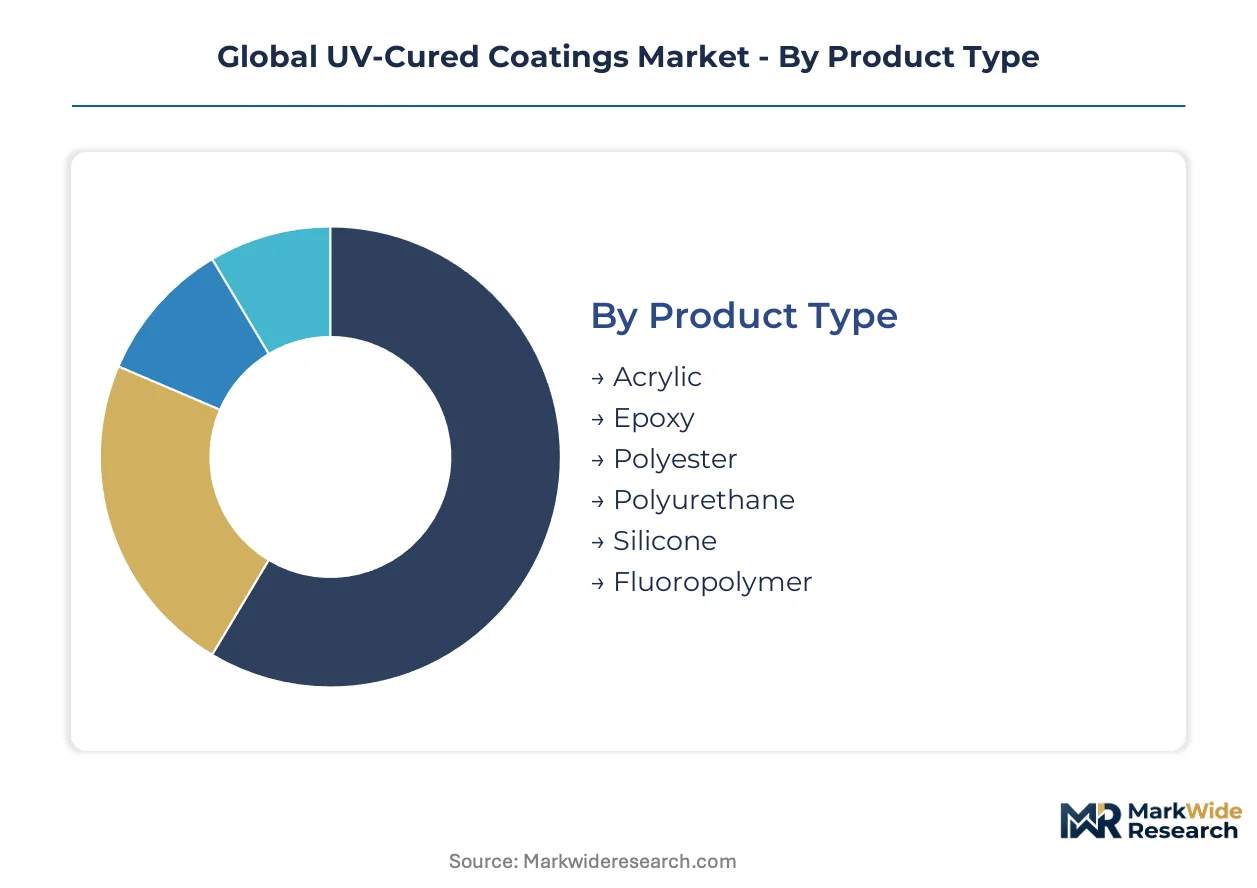
UV-cured coatings span multiple chemistries, curing technologies, and end-use specifications that determine formulation priorities and equipment procurement decisions. Buyers select segments based on substrate compatibility, regulatory compliance requirements, and total applied cost rather than resin price alone. Each segmentation dimension carries distinct margin structures and switching costs that shape competitive positioning.
Product Type:
Formulation cost tiers drive buyer selection, with standard acrylic systems competing against premium chemistries for specialized performance requirements.
- Acrylic:Balanced adhesion, weatherability, and cost structure make this the default choice for wood finishing and packaging lines. Furniture manufacturers in Germany and the United States specify acrylic systems for cabinetry and millwork where VOC compliance under EPA NESHAP and REACH frameworks is mandatory.
- Epoxy:Superior chemical resistance and hardness justify premium positioning in protective films and industrial maintenance coatings. Demand concentrates in electronics conformal coatings and automotive underhood components where thermal cycling and solvent exposure are severe.
- Polyester:High crosslink density delivers scratch resistance for flooring and decorative laminates.
- Polyurethane:Flexibility and abrasion resistance serve textile coatings and flexible packaging applications.
- Silicone:Heat stability and release properties target specialized electronics and medical device applications.
- Fluoropolymer:Extreme chemical inertness commands niche positioning in semiconductor processing equipment and architectural coatings.
Acrylic leads on scale; epoxy leads on momentum as electronics and automotive specifications tighten.
Technology:
Capital expenditure intensity and operating cost trajectories separate buyer preferences across curing hardware categories.
- UV-LED:Solid-state arrays at 365-395 nanometers eliminate mercury disposal liability and reduce energy consumption by one-third versus vapor lamp systems. Electronics contract manufacturers in South Korea and Germany deploy dual-source configurations for multi-layer conformal coatings on heat-sensitive circuit boards.
- Mercury Vapor Lamps:Established installed base and broad spectral output maintain relevance in wood finishing and packaging where substrate heat tolerance is higher. Midwestern US furniture producers face compliance burdens from RoHS substance restrictions and hazardous waste frameworks that slow full conversion.
- Excimer Lamps:Monochromatic output at 172 nanometers enables surface modification without thermal damage for ultra-thin film applications.
- Pulsed Xenon Lamps:High peak intensity supports rapid curing of pigmented and filled formulations.
- Metal Halide Lamps:Doped arc tubes provide tailored spectral output for specialized photoinitiator systems.
Mercury vapor retains installed base dominance; UV-LED gains share fastest as payback periods compress below three years.
Application:
Substrate sensitivity to thermal exposure and chemical resistance requirements determine formulation and equipment pairing decisions.
- Wood Finishing:Flat-line and roll-coat systems for furniture, flooring, and millwork demand fast cure without solvent retention. EPA NESHAP enforcement across US Midwest and Southeast production clusters is accelerating substitution away from solvent-based lacquers.
- Electronics Coating:Conformal coatings and adhesives for circuit boards and medical devices require precision wavelength control and minimal heat transfer. Yangtze River Delta contract manufacturers specify UV-LED systems to meet MEE emission caps and brand-owner sustainability audits.
- Automotive Components:Interior trim, lighting lenses, and underhood parts require weathering resistance and thermal stability.
- Packaging:Food-contact regulations and migration testing protocols favor low-extractable formulations.
- Textiles:Flexible substrates demand low-modulus polyurethane and silicone chemistries.
- Protective Films:Optical clarity and scratch resistance specifications serve display and automotive glazing applications.
Wood finishing leads on scale; electronics coating leads on momentum as miniaturization intensifies heat sensitivity.
End User Industry:
Procurement authority migration from applicators to brand-owner sustainability teams is reshaping supplier relationships and certification requirements.
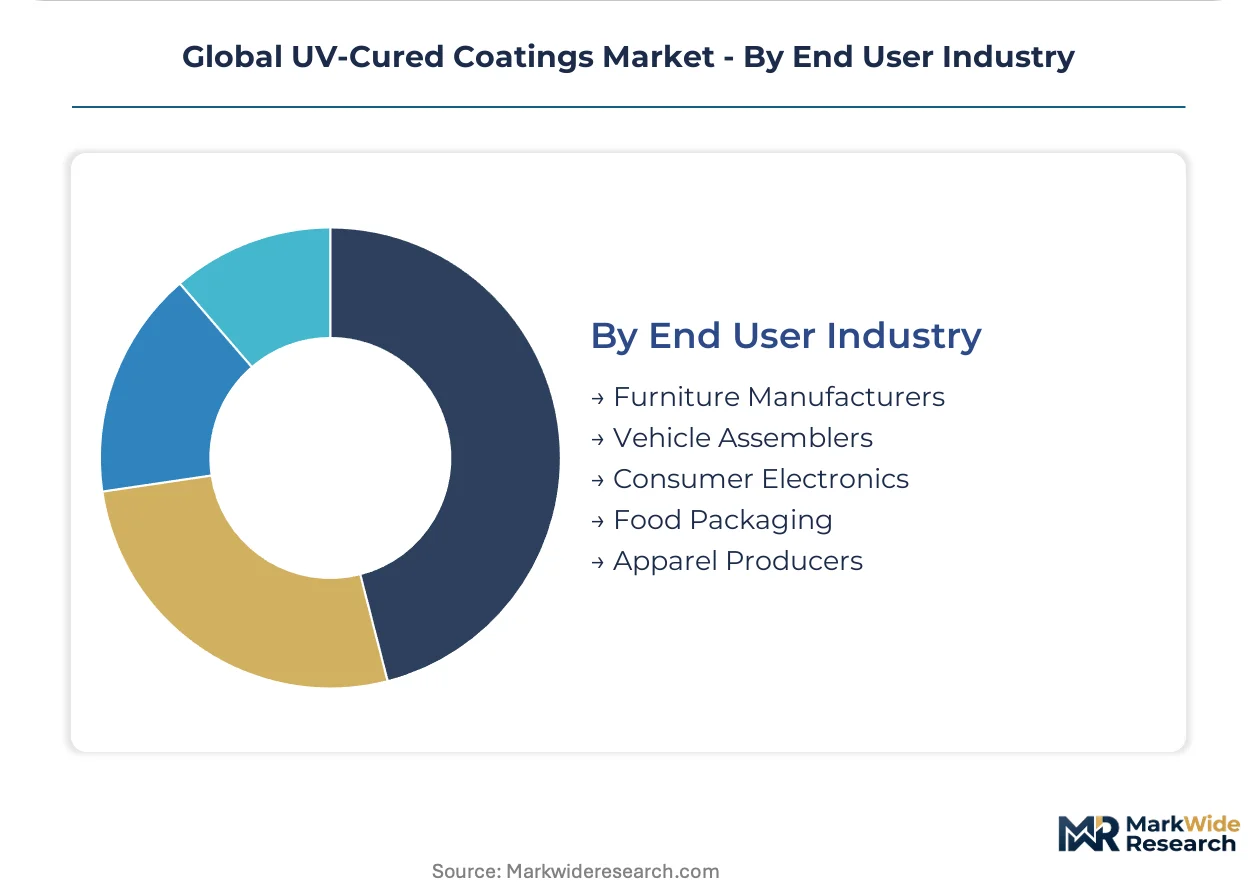
- Furniture Manufacturers:Cabinetry, millwork, and flooring producers face mandatory VOC phaseouts under EPA NESHAP in the United States and REACH restrictions in Europe. German and US retailers now mandate emission disclosures upstream, bypassing traditional distributor channels.
- Consumer Electronics:Medical devices, smartphones, and appliances require biocompatibility certification and RoHS compliance. FDA 510(k) clearance and ECHA Annex XVII substance notifications create 18-36 month product launch cycles that favor consolidated supplier relationships.
- Vehicle Assemblers:Tier-one component suppliers face audit requirements for carbon footprint documentation and VOC disclosures.
- Food Packaging:Migration testing protocols and FSSAI standards in India add compliance layers to formulation development.
- Apparel Producers:Textile coating lines value flexibility and rapid color change capabilities.
Furniture manufacturers lead on scale; consumer electronics leads on momentum as specification authority concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany and China operate divergent enforcement frameworks that reshape formulator priorities. While German regulators emphasize REACH Annex XVII substance restrictions, Chinese authorities prioritize MEE emission caps in manufacturing belts. These jurisdictional differences concentrate UV-LED adoption in distinct industrial clusters.
United States
Wood furniture manufacturers across the Midwest and Southeast face mandatory solvent-based coating phaseouts under EPA NESHAP enforcement. Retailers now mandate VOC emission disclosures upstream from tier-one suppliers. Production clusters in North Carolina and Michigan accelerate UV-cured substitution for cabinetry and millwork lines.
Germany
REACH substance restrictions and RoHS compliance requirements drive formulator R&D toward TPO photoinitiator alternatives. Automotive OEMs audit carbon footprint documentation across supplier tiers. The Baden-Württemberg automotive corridor concentrates demand for conformal coatings on heat-sensitive electronics.
China
MEE enforces stringent VOC emission caps across the Yangtze River Delta and Pearl River Delta manufacturing belts. Electronics contract manufacturers in Jiangsu and Zhejiang provinces deploy UV-LED systems to meet brand-owner sustainability audits. Medical device and consumer appliance production lines drive fastest equipment conversion rates.
India
BIS standards alignment with REACH substance limits and PLI scheme incentives for domestic electronics manufacturing create first-mover opportunities. Formulators navigate FSSAI migration testing protocols for food-contact coatings. Gujarat and Maharashtra industrial corridors attract UV-LED equipment suppliers targeting packaging modernization.
South Korea
Electronics manufacturers deploy dual-source 365-395 nanometer UV-LED configurations for multi-layer conformal coatings on circuit boards. METI-aligned efficiency standards accelerate mercury lamp replacement in display and semiconductor fabrication facilities. The Gyeonggi-do cluster anchors regional demand for precision wavelength control systems.
Global UV-Cured Coatings Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments. The market structures around three tiers: integrated chemical conglomerates with captive resin production, focused coating formulators with proprietary oligomer architectures, and regional applicators serving single-industry customers. Consolidation pressures concentrate among mid-size formulators lacking photoinitiator supply security. Dominant competitive moves include portfolio diversification into adjacent light-curable chemistries and backward integration into oligomer synthesis.
Within the integrated chemical tier, BASF SE and Arkema occupy positions defined by captive raw material access and multi-jurisdictional regulatory compliance infrastructure. Among focused coating specialists, AkzoNobel NV exemplifies the digital tinting and spectral matching archetype, while PPG Industries anchors the proprietary oligomer development segment. Dymax Corp. represents the defensible niche strategy in medical device and electronics assembly applications. These three archetypes—integrated chemical, digital-enabled formulator, and application-specific specialist—capture distinct margin pools across end-use specifications.
| Leading Market Players |
|---|
| AkzoNobel NV |
| PPG Industries |
| The Sherwin-Williams Company |
| Dymax Corp. |
| Nippon Paints |
| BASF SE |
| Axalta Coating Systems |
| Allnex GmbH |
| Arkema |
| Others |
Supply & Pricing Matrix
TPO and acylphosphine oxide photoinitiator price indices cascade through UV-cured coating supply chains, compressing margins for standard acrylic formulations while amplifying premium capture for epoxy systems with proprietary oligomer architectures. Buyers in wood finishing and electronics coating segments face divergent cost pass-through dynamics based on formulation complexity and certification requirements.
Pricing Analysis
Capacity additions in China's Jiangsu and Zhejiang provinces are reshaping price floors for standard acrylic UV-cured coatings, forcing European and North American formulators toward premium-mid-economy pricing differentiation based on REACH compliance tiers and FDA 510(k) certification status. Price differentiation hinges on photoinitiator security-of-supply contracts and UV-LED equipment bundling arrangements. Pricing pressure stems from mercury lamp disposal liability conversion costs. Mid-size furniture manufacturers exhibit highest price sensitivity; medical device coating buyers prioritize biocompatibility certification over per-liter cost.
Supply Chain Analysis
Photoinitiator supply rests on German and Chinese specialty chemical producers, with TPO-L and acylphosphine oxide manufacturing concentrated among European and Asian suppliers. Raw material dependencies span acrylic and epoxy resin feedstocks, oligomer architectures, and nitrogen inerting gases for oxygen-scavenging cure environments. Supply chain risk centers on single-source vulnerability for acylphosphine oxide variants under ECHA REACH Annex XVII substance review. Distribution runs through direct technical sales to tier-one automotive and electronics OEMs, with consolidated distributor relationships in wood finishing segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
UV-cured coating margins expand through UV-LED equipment bundling and software-defined formulation platforms that reduce base chemistry reformulation costs. Premium-tier shift toward medical device and automotive electronics specifications justifies oligomer architecture investments.
For Market Incumbents: Deploy proprietary oligomer synthesis capabilities to secure photoinitiator supply alternatives ahead of ECHA REACH Annex XVII restrictions on legacy photoinitiators. Consolidate distributor relationships in German and US wood finishing clusters to capture EPA NESHAP-driven substitution demand. Counter emerging Asian formulators through FDA 510(k) clearance acceleration and carbon footprint documentation for automotive OEM audits. For New Entrants and Emerging Players: Digital tinting platforms offer the lowest-friction entry path for mid-size coating houses seeking custom color development without captive resin production. India's Gujarat and Maharashtra industrial corridors present the most penetrable geography, with BIS standards alignment creating regulatory parity with REACH frameworks. Target electronics contract manufacturers in the Yangtze River Delta through UV-LED equipment leasing models that compress capital barriers. For Investors and Strategic Acquirers: Asymmetric upside sits with application-specific specialists holding biocompatibility certification and RoHS-compliant formulation libraries for medical device and consumer electronics segments. Long-term viability favors targets with backward integration into oligomer synthesis and established ECHA notification infrastructure. Watch photoinitiator supply disruption signals and UV-LED payback period compression below thirty-six months as inflection indicators.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Oligomer Synthesis | Captive supply of proprietary resin architectures reduces photoinitiator reformulation costs for REACH compliance. |
| UV-LED Equipment Bundling | Combined hardware-formulation offerings compress customer payback periods and lock in recurring chemical offtake. |
| FDA 510(k) Clearance Acceleration | Medical device coating specifications command premium positioning and defensible customer relationships. |
| Software-Defined Formulation Platforms | Digital tinting and spectral matching enable mass customization without base chemistry inventory proliferation. |
| Long-term Supply Agreements | Photoinitiator security contracts with German and Chinese specialty chemical producers mitigate input cost volatility. |
Research Methodology
Coverage spans Germany, China, the United States, India, and South Korea, with primary inputs from each market cluster combining formulation chemist interviews, coating applicator procurement leads, and UV-LED equipment manufacturer technical directors with secondary validation. Secondary sources include ECHA REACH Annex XVII substance notifications, EPA NESHAP enforcement records, MEE emission cap disclosures, and SEC filings from listed chemical conglomerates. Bottom-up triangulation across resin consumption volumes and top-down cross-check against end-use industry production data anchor value estimates.
Rate-of-change decomposition separates volume growth from price-mix effects across the projection horizon. Segmentation dimensions modeled include chemistry type, curing technology, application substrate, and end-use industry procurement authority. CAGRs derive from regression against industrial coating output, regulatory substitution elasticity, and UV-LED equipment installation trajectories. Forecast inputs incorporate photoinitiator supply security indices and mercury lamp disposal liability cost curves.
The model assumes a particular technology adoption path; alternative pathways for UV-LED wavelength optimization or excimer lamp surface modification would alter the outlook. Forecasts reflect stated assumptions regarding ECHA substance restriction timelines and MEE enforcement intensity. Regulatory acceleration or photoinitiator supply disruption would revise projections. A small set of triggers—photoinitiator supply concentration events, UV-LED capex compression thresholds, and REACH Annex XVII expansion—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Electron Beam Curable Coating Market
Coatings
Germany Automotive OEM Coatings Market
Coatings
Water-Based Alkyd Coatings Market
Coatings
Japan Architectural Coatings Market
Coatings
Global Anti-Smudge Coatings Market
Coatings
Can Coatings Market
Coatings
Middle East and Africa Super Hydrophobic Coatings Market
Coatings
Bio-Based Coatings Market
Coatings
Phosphate Conversion Coatings Market
Coatings
Canada Protective Coatings Market
Coatings
Spain Automotive OEM Coatings Market
Coatings
Coating Agents for Synthetic Leather Market
Coatings
Food Grade Ceramic Coatings Market
Coatings
FEVE Fluoropolymer Coatings Market
Coatings
Tablet Coatings Market
Coatings
Asia-Pacific Radiation Curable Coatings Market