
 Gel Polymer Electrolytes Market | 2026-2036
Gel Polymer Electrolytes Market Size, Share, and Industry Trends Forecast 2026-2036
Gel Polymer Electrolytes Market Foresight
South Korea's polymer synthesis corridor is fragmenting as domestic battery material suppliers expand gel electrolyte capacity to serve LG Chem's pouch cell demand. Solvay leverages its fluoropolymer expertise to anchor European supply chains for high-voltage gel formulations. BASF SE competes through integrated PEO precursor production, while Arkema specializes in PVDF-based gel membranes for aerospace-grade cells.
Gel polymer electrolytes are semi-solid ionic conductors comprising a polymer matrix swollen with liquid electrolyte, typically achieving ionic conductivity between 10⁻⁴ and 10⁻³ S/cm at room temperature through controlled cross-linking of PEO, PAN, or PVDF host structures. These materials eliminate free liquid leakage while maintaining electrode interfacial contact, serving primarily as drop-in replacements for liquid electrolytes in lithium-ion and emerging sodium-ion battery architectures. PEO-based formulations dominate current manufacturing volumes due to established roll-to-roll coating compatibility, though PVDF-based variants command premium positioning in aerospace and defense applications where thermal runaway suppression is non-negotiable. Sodium-ion technology represents the fastest-expanding technology segment, as gel architectures solve the dendrite penetration risks that plague hard carbon anodes in liquid systems.
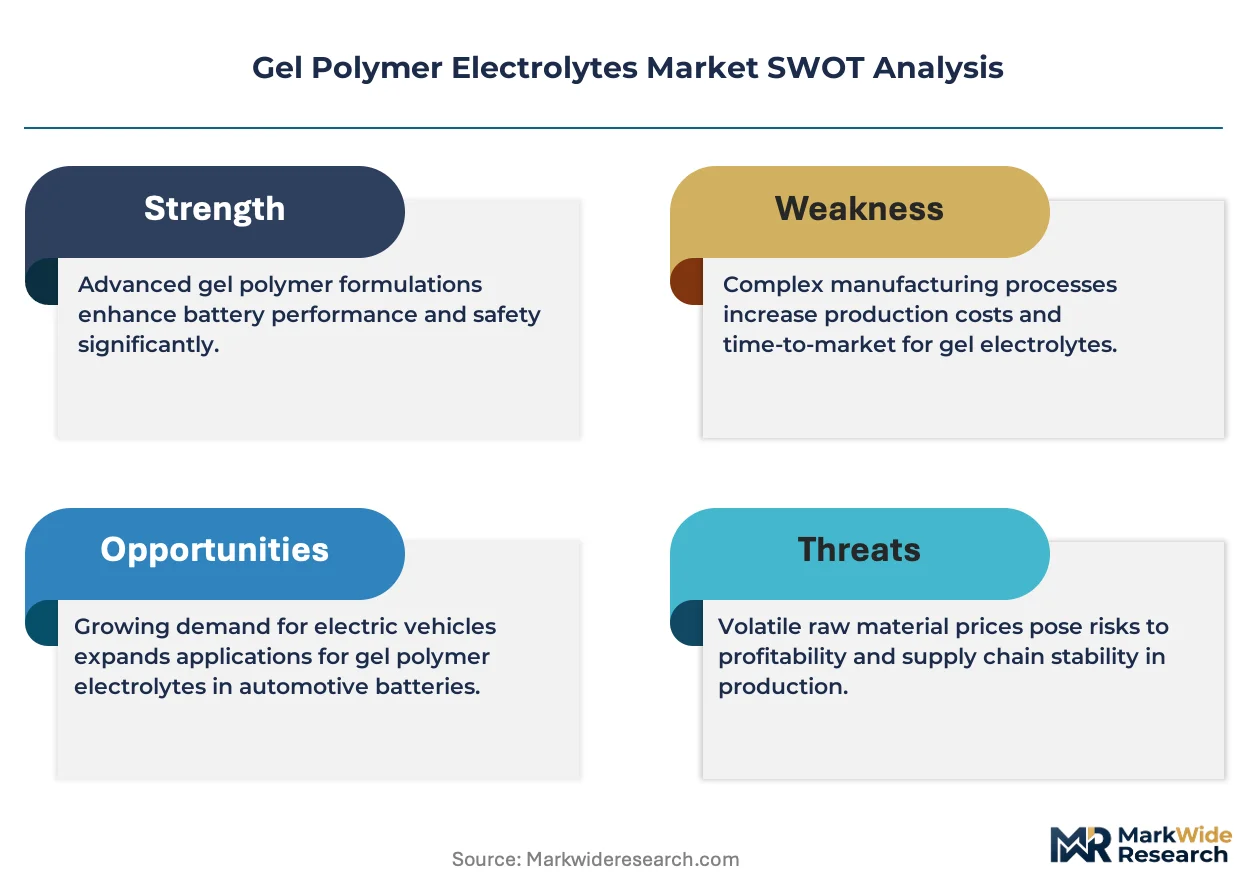
REACH compliance in Europe and China's GB/T standards for lithium-ion battery safety dictate gel electrolyte composition disclosures and flammability testing protocols, creating compliance moats for suppliers with in-house toxicology databases. The EU Battery Regulation's carbon footprint declarations are forcing polymer producers to document solvent recovery rates in gel casting processes. Stakeholders must monitor how solid-state battery pilot lines in Japan and South Korea allocate capital between true ceramic solid electrolytes and gel polymer intermediates, as this technology choice will determine which polymer chemistry platforms survive the next manufacturing transition.
Market Dynamics
Pouch cell architectures in electric vehicle battery packs are displacing cylindrical formats, forcing electrolyte suppliers to retool for gel-based separator compatibility and high-volume polymer synthesis.
Growth Catalysts
- EU Battery Regulation:Carbon footprint declarations and recyclability mandates are accelerating certification demand for gel electrolytes that eliminate liquid leakage risks in transport applications.
- Sodium-ion battery chemistry:Hard carbon anodes in sodium-ion systems require gel architectures to suppress dendrite penetration, opening parallel demand streams beyond lithium-ion.
- South Korea's polymer corridor:Domestic capacity expansion around LG Chem and Samsung SDI suppliers is creating concentrated procurement clusters with shorter qualification cycles.
Market Restraints
- Fluoropolymer feedstock volatility:PVDF and PVDF-HFP resin prices swing with semiconductor and construction demand, compressing margins for high-voltage gel formulations.
- Solvent recovery capital intensity:REACH compliance and EU Green Deal solvent emission limits require casting line retrofits that smaller polymer compounders cannot finance.
- Ceramic solid-state substitution:Pilot lines in Japan and South Korea are diverting R&D capital toward sulfide and oxide electrolytes that promise true elimination of liquid components.
Strategic Opportunities
- India's PLI scheme for battery manufacturing:Domestic cell production incentives are creating first-mover openings for gel electrolyte suppliers to establish local compounding operations ahead of demand maturation.
- Aerospace-grade thermal runaway suppression:Defense and satellite applications are specifying PVDF-based gel membranes at premium pricing for non-negotiable safety margins.
- Cross-linked PEO-PAN hybrid architectures:Converging polymer platforms are enabling single-supplier solutions that span consumer electronics through electric vehicle voltage ranges.
Industry Challenges
- Electrochemist talent scarcity:Polymer synthesis expertise for ionic conductivity optimization competes with semiconductor and pharmaceutical sectors for limited PhD-level labor pools.
- Dual certification timelines:Simultaneous GB/T safety testing in China and UN 38.3 transport certification creates six-to-nine month product launch delays.
- Roll-to-roll coating IP thickets:Thickness uniformity patents held by film processing equipment vendors complicate process development for new market entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gel Polymer Electrolytes Market |
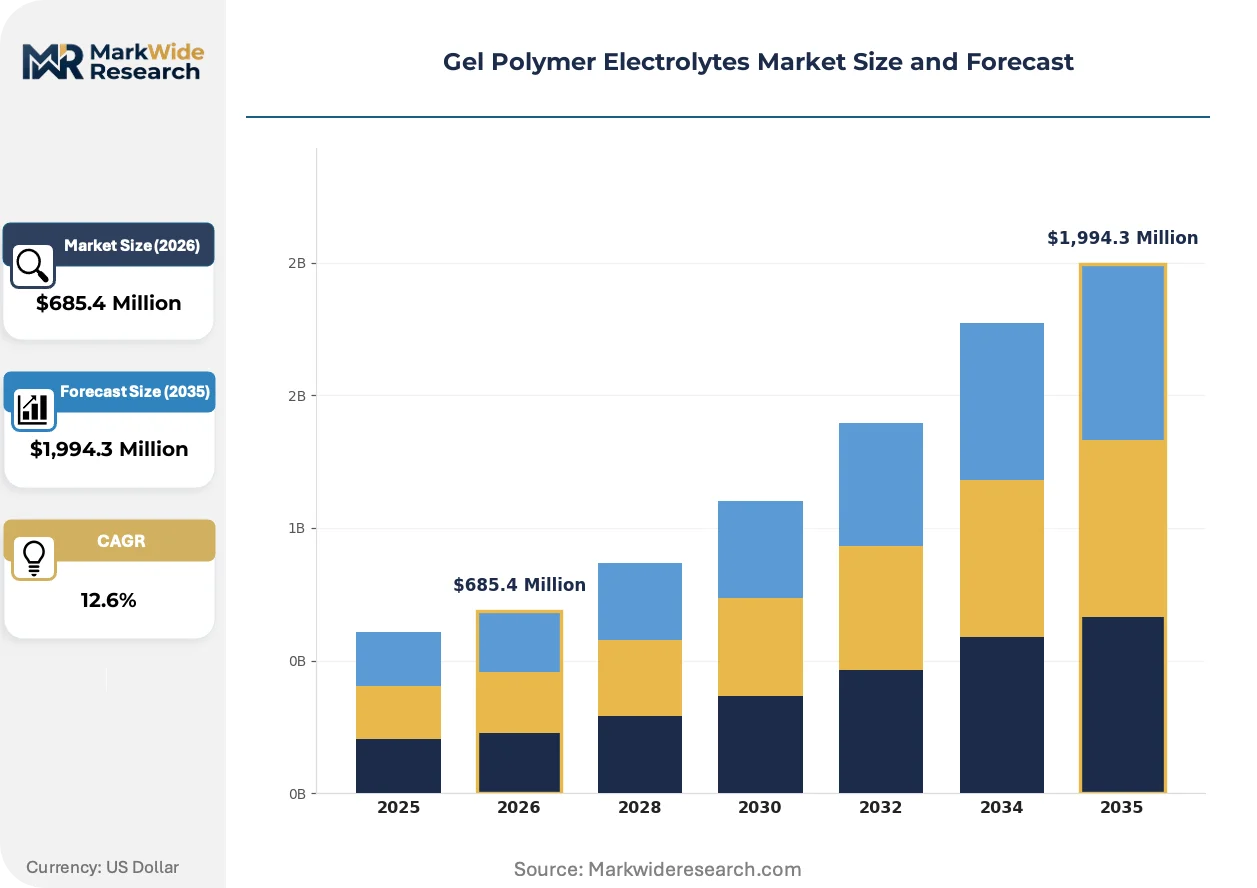
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,994.3 Million |
| CAGR (2026 – 2036) | 12.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PEO-based, PAN-based, PMMA-based, PVDF-based, Others Technology: Lithium-ion, Sodium-ion, Magnesium-ion, Proton-conducting, Dual-ion Application: Consumer Electronics, Aerospace, Electric Vehicles, Grid Energy Storage, Wearable Devices End User: Battery Manufacturers, Research Institutions, Industrial Equipment Producers, Defense Sector |
| Companies Covered | Solvay, Ashland, 3M Company, Arkema, Nippon Shokubai Co. Ltd, LG Chem, BASF SE, Zhejiang Fluorine, EVONIK Industries AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gel Polymer Electrolytes Market Shifts & Advancements
Electrolyte formulation is fragmenting across polymer chemistry platforms as end-users trade off manufacturing compatibility against performance specifications in high-voltage applications.
Cross-linked polyethylene oxide networks with controlled swelling ratios are virtualizing the interface between liquid and solid electrolyte categories. Battery pack producers in the electric vehicle segment are adopting these architectures for pouch cell production at scale. The technology is virtualizing traditional procurement boundaries between liquid electrolyte suppliers and solid-state material developers, compressing vendor consolidation timelines.
REACH Article 33 disclosure requirements for Substances of Very High Concern are forcing gel electrolyte producers to document plasticizer and cross-linker chemistries in customer safety data sheets. European compounders are reformulating away from certain phthalate-based plasticizers to preempt authorization list restrictions. High-voltage formulations for electric vehicle applications are most affected, with suppliers accelerating fluorinated solvent substitutions ahead of sunset dates.
Direct long-term contracting between automotive OEMs and polymer compounders is bypassing traditional electrolyte blenders in procurement hierarchies. Tier-one battery producers are losing margin capture to upstream material specialists with captive synthesis capabilities. South Korea and China's domestic supply chains exhibit this pattern most visibly, where vertical integration incentives align with national battery sovereignty policies.
Gel Polymer Electrolytes Market Segmentation
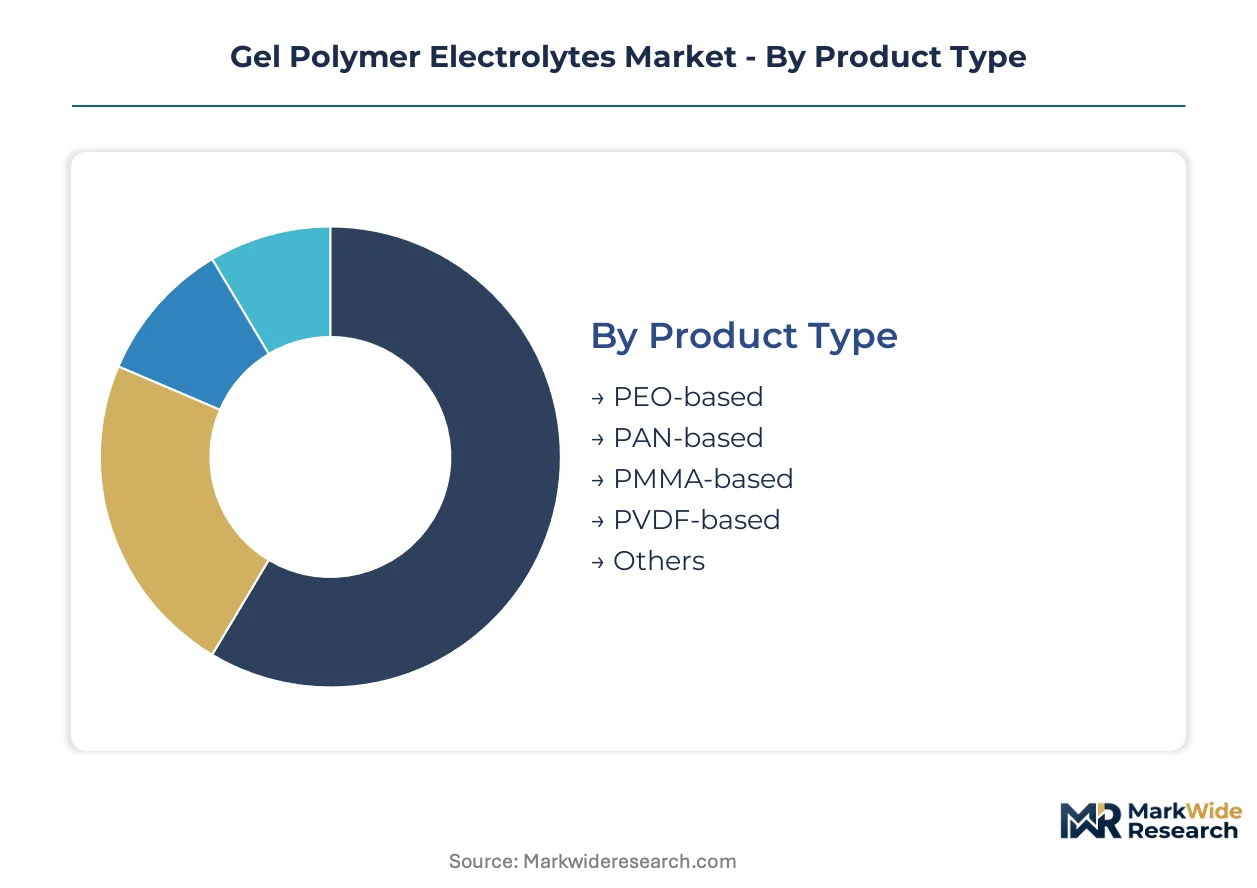
Gel polymer electrolyte procurement patterns diverge sharply across chemistry platforms, with PEO formulations dominating roll-to-roll manufacturing while PVDF variants command aerospace premiums. End-use segmentation reveals how electric vehicle pouch cell demand is restructuring supply chain priorities away from consumer electronics.
Product Type:
Polymer host selection spans laboratory-scale specialty synthesis through commodity coating operations, with each chemistry presenting distinct trade-offs between ionic conductivity and mechanical stability.
- PEO-based:Polyethylene oxide networks achieve 10⁻⁴ to 10⁻³ S/cm conductivity through controlled cross-linking density, dominating current manufacturing volumes due to established solvent casting compatibility with South Korean pouch cell producers.
- PVDF-based:Fluoropolymer gel membranes deliver superior thermal runaway suppression through PVDF-HFP copolymer architectures, with defense and satellite applications specifying these formulations at substantial premiums for non-negotiable safety margins.
- PAN-based:Polyacrylonitrile hosts exhibit excellent oxidative stability in high-voltage cells.
- PMMA-based:Polymethyl methacrylate matrices offer cost advantages in consumer electronics applications.
- Others:Experimental polymer platforms including polyphosphazenes and single-ion conductors serve niche research applications.
The dominant share belongs to PEO-based formulations, while PVDF-based variants are closing the gap fastest through aerospace certification pipelines.
Technology:
Electrochemistry selection determines dendrite suppression requirements, with alkali metal anodes demanding gel architectures that liquid systems cannot safely accommodate.
- Sodium-ion:Hard carbon anodes in sodium-ion systems require gel electrolytes to suppress dendrite penetration risks that plague liquid electrolyte alternatives, opening parallel demand streams beyond lithium-ion supply chains as Chinese and Indian cell producers scale sodium chemistry pilot lines.
- Lithium-ion:Mature lithium-ion technology maintains volume leadership through pouch cell adoption in electric vehicle battery packs, where gel formulations eliminate leakage risks during thermal cycling.
- Magnesium-ion:Multivalent ion transport challenges favor dense polymer matrices with chelating functionalities.
- Proton-conducting:Fuel cell crossover applications specify sulfonated polymer gel architectures.
- Dual-ion:Graphite anode dual-ion systems benefit from gel electrolyte interfacial stability.
Lithium-ion retains the largest installed base, though sodium-ion exhibits the steepest expansion trajectory as cell producers diversify beyond lithium supply constraints.
Application:
End-use requirements fragment across voltage windows, with electric vehicle applications demanding high-voltage stability that consumer electronics specifications do not require.
- Electric Vehicles:Pouch cell architectures in EV battery packs are displacing cylindrical formats, with automotive OEMs establishing direct procurement relationships with polymer compounders to secure gel electrolyte supply chains under EU Battery Regulation carbon footprint disclosure requirements.
- Aerospace:Satellite and defense applications specify PVDF-based gel membranes with rigorous thermal runaway testing protocols, creating certification moats for suppliers with in-house flammability databases.
- Consumer Electronics:Smartphone and laptop manufacturers prioritize thin-film coating compatibility and cost minimization.
- Grid Energy Storage:Utility-scale installations emphasize cycle life and fire safety in containerized systems.
- Wearable Devices:Flexible form factors demand low-modulus gel formulations with stretchable electrode interfaces.
Electric Vehicles command the largest revenue share, while Grid Energy Storage is gaining share fastest through utility procurement of sodium-ion systems.
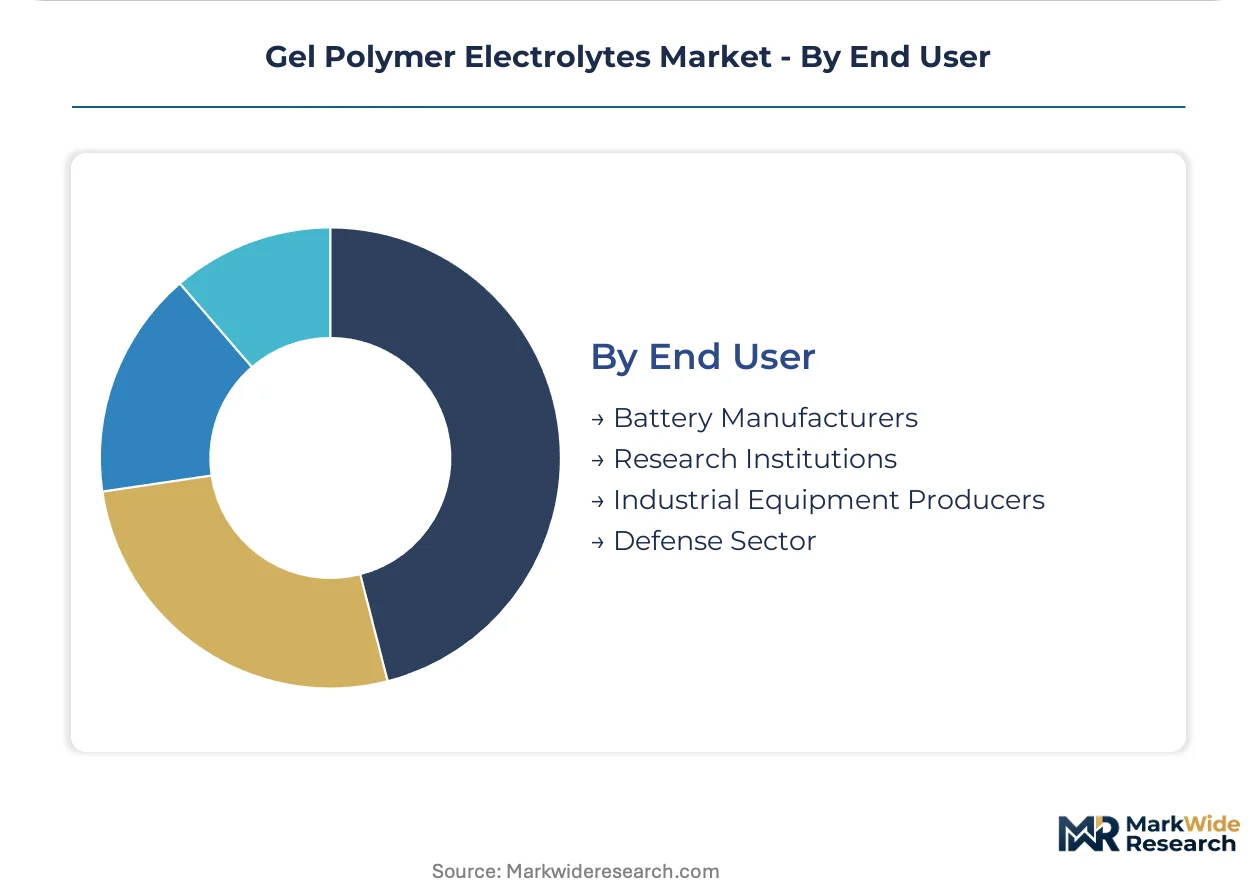
End User:
Customer type determines qualification timelines, with defense and automotive sectors imposing extended certification protocols that research institutions bypass.
- Battery Manufacturers:Tier-one cell producers in South Korea and China are consolidating procurement around domestic polymer synthesis capacity, with LG Chem and Samsung SDI suppliers expanding captive gel electrolyte compounding operations to shorten qualification cycles.
- Defense Sector:Military specifications for thermal runaway suppression mandate PVDF-based gel membranes with documented traceability under ITAR and comparable national security frameworks.
- Research Institutions:Academic and national laboratory users drive experimental polymer platform development.
- Industrial Equipment Producers:Forklift and stationary power applications prioritize cost-optimized PEO formulations.
Battery Manufacturers represent the largest procurement volume, while the Defense Sector is expanding fastest through aerospace electrification programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Korea consumes gel polymer electrolytes primarily for pouch cell EV batteries, whereas China deploys equivalent volumes across sodium-ion pilot lines and grid storage systems. Germany's demand clusters around high-voltage aerospace specifications. India's procurement remains nascent, concentrated in PLI-linked cell manufacturing zones.
China
Sodium-ion battery chemistry drives gel electrolyte consumption in Jiangsu and Anhui provinces, where CATL and BYD suppliers operate hard carbon anode production lines. GB/T lithium-ion safety standards and dual carbon goals mandate flammability testing for gel-based separators. The Yangtze River Delta hosts polymer compounding facilities serving both domestic cell producers and export markets.
South Korea
LG Chem and Samsung SDI procurement dominates regional demand, with gel electrolytes specified for high-nickel pouch cell architectures in premium EV segments. The national battery sovereignty policy accelerates domestic polymer synthesis capacity expansion. Ulsan and Gwangju industrial corridors concentrate fluoropolymer resin production and electrode coating operations.
Germany
Automotive OEM direct contracting with polymer compounders bypasses traditional electrolyte blenders in Baden-Württemberg and Bavaria. REACH Article 33 disclosure requirements and EU Battery Regulation carbon footprint declarations reshape procurement specifications. The Stuttgart-Munich corridor anchors European high-voltage gel formulation development for next-generation cell architectures.
United States
Defense and aerospace applications in California and Texas specify PVDF-based gel membranes with ITAR traceability requirements. NHTSA battery safety investigations and FAA satellite power system certifications create dual compliance pathways. The Silicon Valley-Boston corridor concentrates solid-state battery R&D investments that compete with gel polymer intermediate solutions.
India
PLI scheme incentives for domestic cell manufacturing attract gel electrolyte suppliers to Gujarat and Tamil Nadu industrial zones. BIS battery safety standards and CEA grid storage mandates create parallel certification requirements. The Delhi-Mumbai industrial corridor hosts first-mover compounding operations ahead of demand maturation in sodium-ion and lithium-ion segments.
Gel Polymer Electrolytes Market Competitive Landscape
Capability concentration sits with fluoropolymer specialists and integrated polymer producers; scale advantage sits with diversified chemical conglomerates with captive electrolyte precursor supply. The vendor base stratifies across three tiers: European and Japanese specialty polymer houses with aerospace certification databases, South Korean and Chinese integrated battery material suppliers with domestic synthesis scale, and regional compounders dependent on toll manufacturing arrangements. Strategic moves center on backward integration into polymer resin production and direct long-term contracting with automotive OEMs to bypass tier-one battery producers.
Among European specialty polymer houses, Solvay anchors the fluoropolymer expertise tier for high-voltage gel formulations, while Arkema occupies a position exemplifying PVDF-based membrane specialization. BASF SE represents the integrated chemical conglomerate archetype with captive PEO precursor production. South Korean suppliers including LG Chem sit within the battery-integrated material tier, leveraging domestic polymer corridor expansion to shorten qualification cycles with cell producers.
| Leading Market Players |
|---|
| Solvay |
| Ashland |
| 3M Company |
| Arkema |
| Nippon Shokubai Co. Ltd |
| LG Chem |
| BASF SE |
| Zhejiang Fluorine |
| EVONIK Industries AG |
| Others |
Supply & Pricing Matrix
Overcapacity in Chinese fluoropolymer resin production is compressing margins for PVDF-HFP suppliers while simultaneously enabling aggressive pricing postures in high-voltage gel formulations. This utilization imbalance feeds directly into contract negotiation leverage for automotive OEMs sourcing pouch cell electrolytes.
Pricing Analysis
Long-term offtake agreements between South Korean battery producers and domestic polymer compounders dominate procurement, locking in volume commitments that insulate against PVDF feedstock volatility. Price differentiation hinges on aerospace certification grade and REACH-compliant solvent recovery documentation, with defense buyers exhibiting minimal sensitivity compared to consumer electronics manufacturers seeking cost-optimized PEO alternatives. Cost compression in standard-grade formulations is intensifying as Chinese sodium-ion cell producers scale pilot lines and demand volume discounts.
Supply Chain Analysis
Contract manufacturing concentration rests with LG Chem and Samsung SDI captive operations in South Korea, supplemented by toll compounding arrangements through Zhejiang Fluorine in China's Yangtze River Delta. Raw material sourcing draws from Australian lithium chemical feedstock, Japanese fluoropolymer resin, and German PEO precursor supply. Single-source vulnerability in semiconductor-grade PVDF resin creates structural exposure when electronics demand spikes. Distribution runs through direct OEM contracting that bypasses traditional electrolyte blender intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Gel polymer electrolyte procurement is evolving into a service-attach opportunity as certification compliance and formulation customization expand faster than base polymer supply. Recurring revenue from REACH documentation updates and carbon footprint auditing now outpaces hardware margin growth for European compounders.
For Market Incumbents: Harden supply chain resilience through backward integration into PEO precursor production and captive fluoropolymer resin capacity in South Korea's Ulsan corridor. Ceramic solid-state battery pilot investments in Japan threaten long-term gel electrolyte positioning; defend through accelerated certification of hybrid gel-ceramic architectures that bridge technology transitions.
For New Entrants and Emerging Players: Pursue India's PLI-linked cell manufacturing zones in Gujarat and Tamil Nadu before domestic polymer synthesis capacity matures. Sodium-ion battery chemistry presents the most penetrable technology segment for qualification-light market entry. Establish toll manufacturing partnerships with existing Chinese compounding facilities to circumvent capital-intensive solvent recovery infrastructure.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across sodium-ion gel electrolyte production as process standardization reduces casting line retrofit costs. Long-term viability favors integrated suppliers with in-house toxicology databases and aerospace certification pipelines. Monitor Japan's sulfide solid-state pilot line yield rates as the critical signal for gel polymer demand inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into PEO Precursor Production | BASF SE's captive supply chain anchors European high-voltage formulation cost structures against feedstock volatility. |
| Aerospace Certification Pipeline Investment | Arkema's PVDF-HFP membrane qualification under FAA satellite power protocols commands substantial pricing premiums. |
| Sodium-Ion Gel Electrolyte Scale-Up | CATL's hard carbon anode production lines in Jiangsu province drive parallel demand streams beyond lithium-ion supply chains. |
| Direct OEM Contracting Bypass | Automotive procurement in Baden-Württemberg eliminates tier-one battery producer margin capture for polymer compounders. |
| Solvent Recovery Infrastructure Retrofit | REACH Article 33 compliance investments create regulatory moats that smaller European compounders cannot finance. |
Research Methodology
Desk research of customs trade databases, ECHA substance registration filings, and SEC chemical company disclosures preceded structured interviews with polymer synthesis R&D directors, automotive OEM battery procurement managers, and electrolyte toll manufacturing operators. Primary fieldwork with South Korean pouch cell producers and Chinese sodium-ion pilot line engineers combined with secondary validation against GB/T standard documentation and EU Battery Regulation impact assessments. Bottom-up polymer resin consumption modeling triangulated against top-down electric vehicle battery pack production forecasts.
Assumption sets held regional regulatory implementation timelines and solid-state battery pilot yield rates constant while varying sodium-ion chemistry adoption curves and fluoropolymer feedstock pricing across the projection horizon. Segmentation dimensions spanned polymer host chemistry, electrochemical technology, voltage application tier, and end-user qualification intensity. CAGRs derived from exponential smoothing of annual capacity expansion announcements weighted by regulatory enforcement probability. Forecast inputs incorporated REACH sunset date schedules and India's PLI scheme disbursement pacing.
Macroeconomic conditions sit as an overlay; deviation in electric vehicle penetration rates or lithium chemical spot pricing would shift the trajectory materially. Forecasts reflect documented assumptions regarding ceramic solid-state substitution timelines and sodium-ion hard carbon anode yield improvements. Quarterly review of Japan's sulfide electrolyte pilot production data and South Korean polymer corridor utilization rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Thermoplastic Micro Molding Market
Polymers & Resins
Global Chromatography Resin Market
Polymers & Resins
Polyether Polyols Market
Polymers & Resins
Bio-Based PVC Market
Polymers & Resins
Europe Polypropylene Market
Polymers & Resins
HDPE Large Blow Molded Products Market
Polymers & Resins
Polyurethane (PU) Foam Market
Polymers & Resins
Beverage Processing Polymers Market
Polymers & Resins
Natural Oil Polyols (NOP) Market
Polymers & Resins
Polymer Microinjection Molding Market
Polymers & Resins
Polyimide Resin Market
Polymers & Resins
Thermoplastic Polyimide Market
Polymers & Resins
Bio-Based Polyvinyl Chloride Market
Polymers & Resins
Plastisols Market
Polymers & Resins
Bisphenol a Market
Polymers & Resins
Resin Cement for Luting Market