
 Polystyrene and Expandable Polystyrene (EPS) Market | 2026-2036
Polystyrene and Expandable Polystyrene (EPS) Market Size, Share, and Industry Trends Forecast 2026-2036
Polystyrene and Expandable Polystyrene (EPS) Market Analytics
REACH is expanding compliance costs for virgin polystyrene feedstock across European manufacturing bases. BASF SE leverages its integrated styrene monomer operations to absorb regulatory pass-through costs while sustaining margin stability. Alpek S.A.B. de C.V. anchors North American supply through its Texas Gulf Coast petrochemical corridor. Kaneka Corporation differentiates via high-purity EPS bead formulations for precision molding applications.
Polystyrene and Expandable Polystyrene (EPS) comprise aromatic thermoplastic polymers derived from styrene monomer polymerization, with EPS containing pentane-blown cellular structures achieving densities of 15-30 kg/m³ for thermal insulation. The material primarily serves as rigid foam insulation in building envelopes and protective packaging for temperature-sensitive goods. General Purpose Polystyrene occupies mature commodity pricing tiers in disposable consumer goods, while Expanded Polystyrene captures premium positioning in construction insulation where R-value performance drives specification. High Impact Polystyrene competes in automotive interior components requiring dimensional stability under thermal cycling.
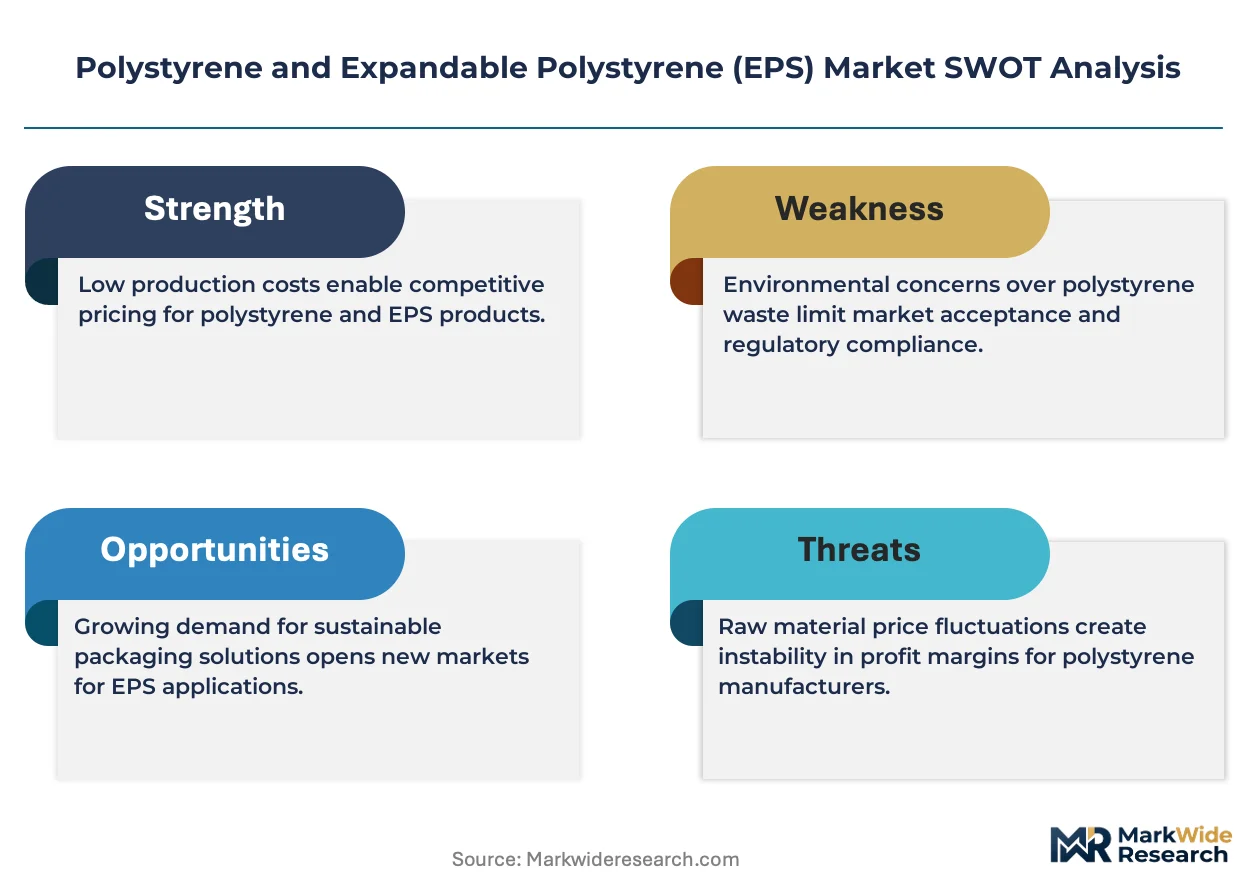
The EPA regulates styrene emissions under Clean Air Act provisions, while the EU F-Gas Regulation indirectly shapes EPS competitiveness against alternative insulation materials. China's MEE enforces stricter VOC controls on petrochemical production clusters, elevating capital requirements for new styrene capacity. India's BIS certification mandates for construction materials create non-tariff barriers for imported EPS board products. Stakeholders must monitor evolving building energy codes and recycled content mandates to anticipate substitution risks from bio-based and mineral wool alternatives.
Market Dynamics
Construction retrofit mandates across the EU Green Deal's building renovation wave are compressing specification cycles for EPS insulation boards, forcing manufacturers to align production capacity with tightening thermal performance codes rather than traditional new-build cycles.
Growth Catalysts
- EU F-Gas Regulation:Restrictions on hydrofluorocarbon blowing agents elevate EPS competitiveness against polyurethane foams in commercial roofing applications.
- China's dual carbon goals:Provincial energy efficiency mandates in Jiangsu and Zhejiang accelerate specification of high-R-value insulation in cold-chain logistics facilities.
- Mechanical recycling advances:Dissolution-based polystyrene purification is enabling food-contact rPS flake supply, opening closed-loop packaging demand from quick-service restaurant chains.
Market Restraints
- Styrene monomer concentration:Gulf Coast petrochemical corridor outages transmit immediate price volatility to North American EPS molders lacking backward integration.
- REACH compliance costs:ECHA's expanding substance evaluation obligations elevate testing burdens for virgin polystyrene feedstock across European compounding operations.
- Mineral wool substitution:Stone wool insulation captures specification share in high-rise commercial envelopes where fire-rated assemblies dominate.
Strategic Opportunities
- India's BIS certification gaps:Domestic testing infrastructure shortages delay import clearance for EPS board products, creating first-mover advantage for local manufacturing investment.
- Carbon capture integration:Styrene producers deploying CCUS at Antwerp-Rotterdam-Rhine-Ruhr cluster sites can offer mass-balanced low-carbon EPS to construction procurement frameworks.
- Digital specification platforms:BIM-embedded thermal modeling tools are compressing architect decision cycles for envelope material selection.
Industry Challenges
- Fire-safety certification timelines:Extended reaction-to-fire testing protocols under EN 13501-1 delay new product introductions by 8-14 months.
- Chemical recycling scale-up:Pyrolysis-based polystyrene depolymerization requires capital commitments exceeding $200 million per commercial unit.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polystyrene and Expandable Polystyrene (EPS) Market |
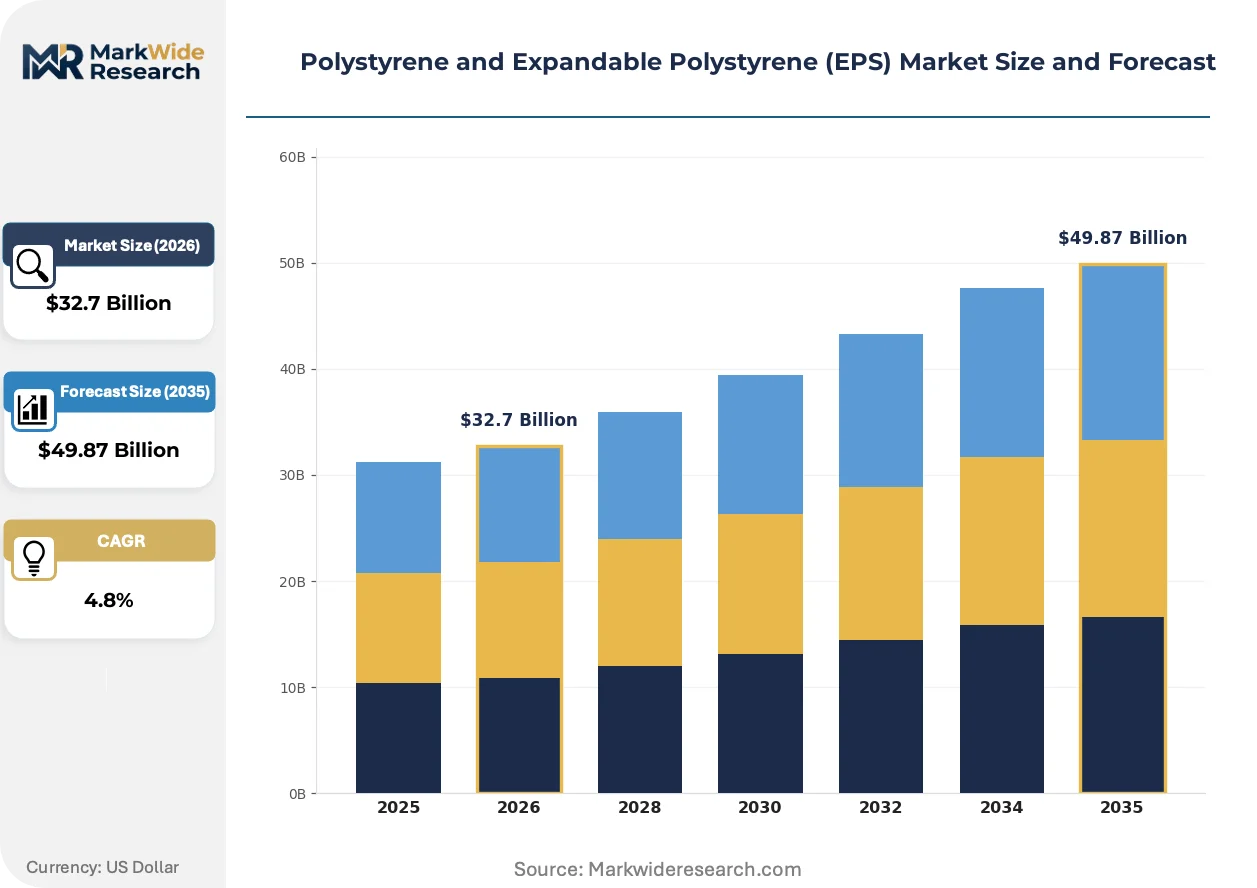
| Market Size in 2026 | $32.7 Billion |
| Market Size in 2035 | $49.87 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: General Purpose Polystyrene, High Impact Polystyrene, Expanded Polystyrene, Extruded Polystyrene Application: Packing Materials, Construction Insulation, Automotive Parts, Consumer Goods End User: Construction Industry, Electronics Sector, Food Packaging, Retail Form: Sheets, Blocks, Beads, Foam |
| Companies Covered | BASF SE, Alpek S.A.B. de C.V., Kaneka Corporation, SABIC, Synthos, TotalEnergies, LG Chem, Flint Hills Resources, NOVA Chemicals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polystyrene and Expandable Polystyrene (EPS) Market Evolving Landscape
Active reformulation of blowing agent chemistries and specification tool digitization are compressing traditional competitive moats in thermal insulation procurement.
Advanced process control systems using machine vision are automating bead expansion density uniformity in continuous pre-expander operations. European block-molding facilities with batch sizes exceeding 20 cubic meters deploy these systems to reduce thermal conductivity variation below 3%. This precision is automating quality-based supplier tiering in public procurement frameworks.
The EU Green Deal's building renovation targets are tightening thermal transmittance requirements for existing stock. Member states must renovate 3% of public building floor area annually, forcing municipal buyers to specify EPS with lambda values below 0.031 W/mK. German federal funding programs now require Environmental Product Declarations for insulation subsidies.
Consolidation among European construction distributors is compressing supplier negotiation leverage. Three buying groups now control 60% of insulation volume in France and Benelux, extracting extended payment terms and technical support commitments. This channel concentration is visible in specification-led projects where distributor-preferred brands displace architect-specified alternatives.
Polystyrene and Expandable Polystyrene (EPS) Market Segmentation
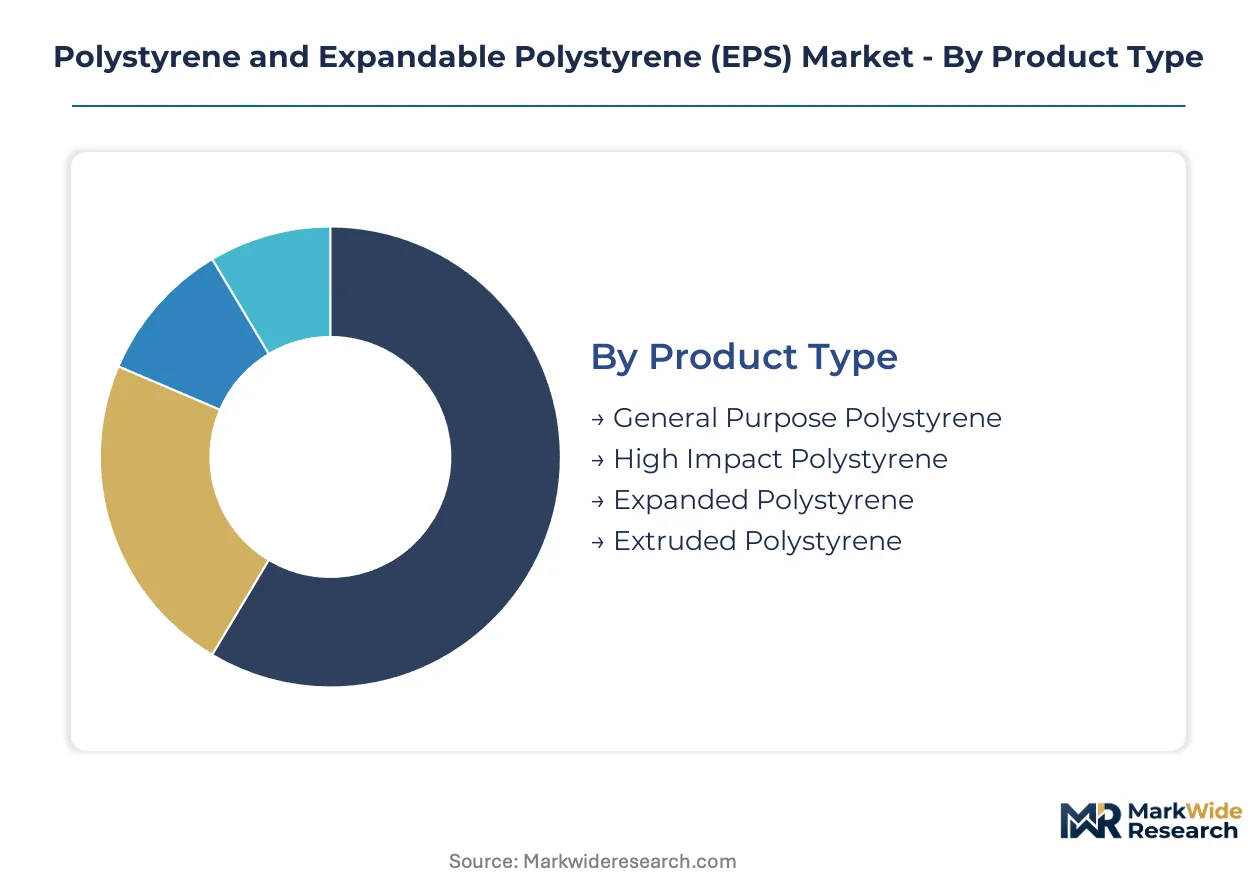
Polystyrene and EPS markets fragment across material grades, conversion forms, and end-use specifications that dictate margin structures and technical service requirements. Procurement patterns diverge sharply between commodity resin buyers seeking volume pricing and construction specifiers demanding certified thermal performance data.
Product Type:
Cost tiers separate buyers seeking commodity resin from those requiring engineered performance characteristics.
- General Purpose Polystyrene:Crystal-clear amorphous thermoplastic with high stiffness and excellent processability in injection molding. Demand concentrates in disposable cutlery and medical laboratoryware where optical clarity and dimensional precision matter more than impact resistance.
- Expanded Polystyrene:Pentane-blown cellular structure achieving densities of 15-30 kg/m³ with lambda values below 0.031 W/mK. Construction procurement in Germany, France, and China dominates volume as EU Green Deal renovation mandates compress specification cycles for thermal insulation boards.
- High Impact Polystyrene:Rubber-modified grade delivering enhanced toughness for appliance housings and automotive interior trim. Electronics manufacturers in South Korea and Japan specify HIPS for television bezels requiring gloss retention under thermal cycling.
- Extruded Polystyrene:Closed-cell rigid foam manufactured through continuous extrusion with higher compressive strength than molded EPS. Commercial roofing and foundation insulation in cold climates drives uptake where moisture resistance and long-term R-value stability justify premium positioning.
Volume sits with General Purpose Polystyrene; growth tilts toward Expanded Polystyrene.
Application:
Application selection tracks regulatory exposure and fire-safety certification burdens that reshape competitive positioning.
- Construction Insulation:Rigid foam boards and cavity-fill beads specified for building envelope thermal performance. EU member states renovating 3% of public building floor area annually under Green Deal targets are forcing municipal buyers toward lambda-certified EPS with Environmental Product Declarations.
- Packing Materials:Molded shapes and loose-fill cushioning for electronics and appliance distribution. E-commerce fulfillment centers in the United States and China are absorbing volume as damage-rate penalties from retailers compress tolerance for inadequate protection.
- Automotive Parts:Instrument panel substrates, door trim cores, and energy-absorbing bumper components. Lightweighting mandates from NHTSA fuel economy standards and China's MIIT dual carbon goals are displacing heavier polypropylene alternatives in interior applications.
- Consumer Goods:Refrigerator liners, food service containers, and CD jewel cases. Food-contact rPS flake from dissolution-based mechanical recycling is opening closed-loop demand from quick-service restaurant chains seeking circular packaging credentials.
Construction Insulation commands the steepest expansion trajectory; Packing Materials retains the largest installed demand base.
End User:
End user concentration determines whether suppliers compete on technical service or commodity logistics.
- Construction Industry:General contractors, insulation subcontractors, and building envelope specialists procuring board stock and spray-grade bead. Consolidation among French and Benelux distributors has concentrated 60% of insulation volume under three buying groups, extracting extended payment terms and specification support commitments.
- Food Packaging:Quick-service restaurants, prepared meal processors, and dairy distributors requiring food-contact compliance. Dissolution-based purification advances are enabling rPS flake supply with virgin-equivalent migration test performance.
- Electronics Sector:OEMs and contract manufacturers molding housings, trays, and component carriers. Precision molding applications in Japan and Taiwan demand high-purity EPS bead formulations with tight expansion density control.
- Retail:Big-box stores and e-commerce platforms sourcing protective packaging and display fixtures. Damage-rate penalties from Amazon and Walmart fulfillment standards are tightening density specifications for molded cushioning.
The Construction Industry anchors volume commitment; Food Packaging is gaining share fastest on circular economy procurement mandates.
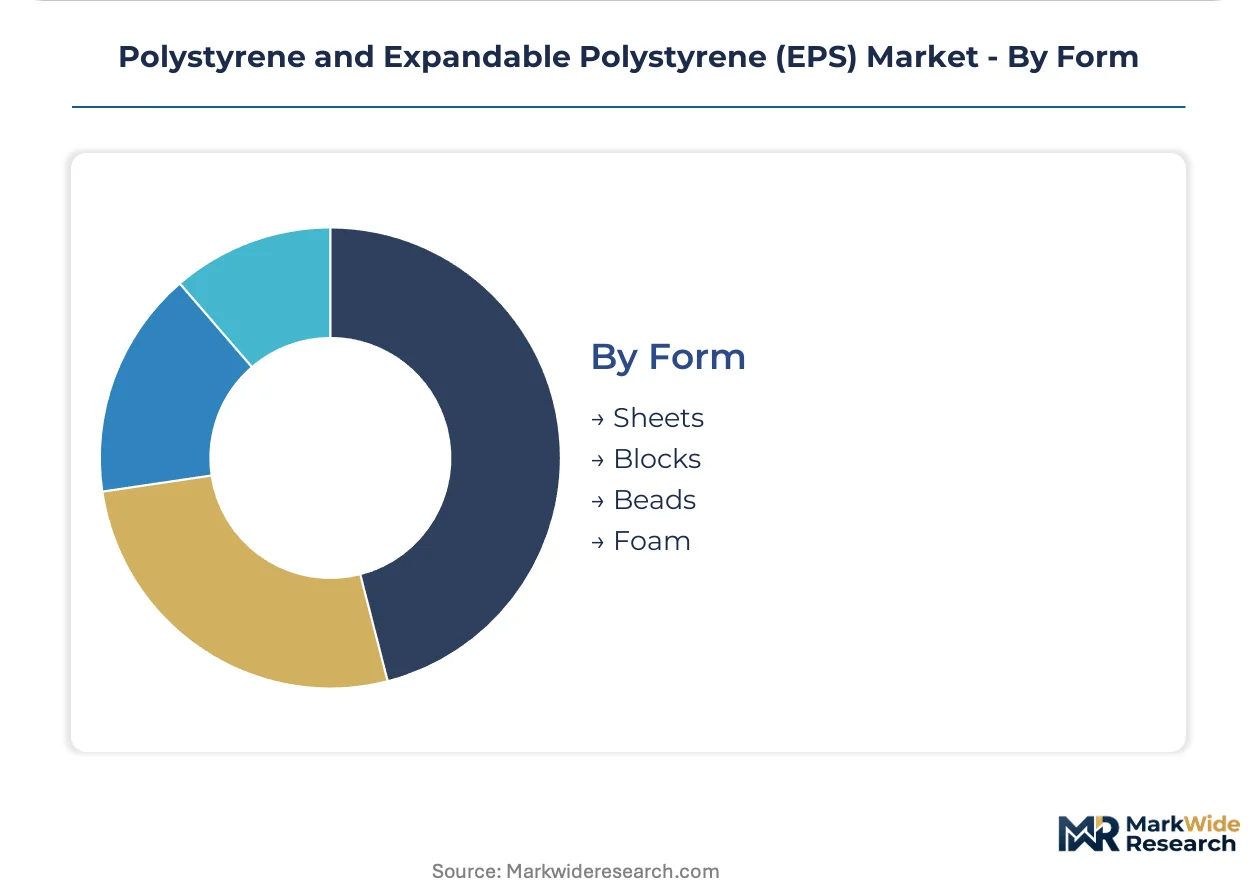
Form:
Form selection constrains processing equipment investment and logistics optimization.
- Blocks:Large-format molded buns slit into boards or fabricated into custom shapes. Block-molding facilities with batch sizes exceeding 20 cubic meters deploy machine vision systems to reduce thermal conductivity variation below 3%.
- Beads:Pre-expanded polystyrene particles for loose-fill cushioning or mold-filling operations. Precision molding in automotive and electronics applications requires bead size distribution control within narrow tolerances.
- Sheets:Extruded or thermoformed flat stock for signage, printing, and shallow-draw packaging. General Purpose Polystyrene sheet serves point-of-purchase displays where printability and gloss compete with PVC alternatives.
- Foam:Low-density cellular structures for cushioning, insulation, and flotation. Marine and geotechnical applications specify foam densities and compression characteristics outside standard construction grades.
Blocks dominate construction volume; beads are expanding most quickly on precision molding demand from automotive and electronics sectors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Antwerp-Rotterdam-Rhine-Ruhr petrochemical corridor tax incentives concentrate styrene monomer capacity and downstream EPS molding operations across northwestern Europe. This clustering pattern replicates in China's Yangtze River Delta special economic zones and the Texas Gulf Coast foreign trade zones, creating three dominant supply basins.
Germany
Federal funding programs for building renovations under the EU Green Deal are accelerating municipal procurement of lambda-certified EPS insulation boards. The country's national construction regulator mandates Environmental Product Declarations for all subsidized thermal envelope materials. Industrial concentration centers on North Rhine-Westphalia, where block-molding facilities serve Benelux distributor buying groups controlling 60% of regional insulation volume.
China
Provincial energy efficiency mandates in Jiangsu and Zhejiang provinces are driving cold-chain logistics facility construction requiring high-R-value insulation. The Ministry of Ecology and Environment enforces stricter VOC controls on petrochemical production clusters, elevating capital requirements for new styrene capacity. Yangtze River Delta special economic zones host integrated EPS bead-to-board manufacturing serving domestic construction and export packaging demand.
United States
Retrofit mandates in California and New York State building codes are compressing specification cycles for commercial roofing insulation. The Environmental Protection Agency regulates styrene emissions under Clean Air Act provisions, shaping plant siting decisions. Texas Gulf Coast petrochemical corridor outages transmit immediate price volatility to North American EPS molders lacking backward integration into monomer supply.
India
Bureau of Indian Standards certification gaps for imported EPS board products are creating clearance delays at domestic ports. The central government's PLI scheme for chemicals and petrochemicals offers production-linked incentives for local manufacturing investment. Maharashtra and Gujarat industrial corridors are attracting first-mover capacity to bypass testing infrastructure shortages and serve Delhi-NCR construction demand.
Japan
Precision molding applications in electronics and automotive sectors demand high-purity EPS bead formulations with tight expansion density control. The Ministry of Economy, Trade and Industry oversees JIS standards compliance for construction materials and packaging applications. Kansai region chemical complexes maintain specialty-grade production serving Taiwan and South Korean electronics contract manufacturers.
Polystyrene and Expandable Polystyrene (EPS) Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across distinct capability tiers in the polystyrene and EPS market. Integrated petrochemical majors leverage captive styrene monomer supply to absorb regulatory pass-through costs, while independent compounders and molders compete on formulation service and logistics responsiveness. Three strategic archetypes dominate: backward-integrated resin producers, regional conversion specialists, and precision-grade formulators. Competitive moves concentrate on capacity alignment with EU Green Deal renovation timelines and dissolution-based recycling technology partnerships.
Among European-based integrated producers, BASF SE exemplifies the petrochemical-major archetype with Antwerp-Rotterdam-Rhine-Ruhr cluster positioning. Alpek S.A.B. de C.V. anchors North American supply through its Mexico-incorporated structure. Kaneka Corporation occupies the precision-formulator tier, representing Japanese specialty-grade capability in high-purity bead formulations.
| Leading Market Players |
|---|
| BASF SE |
| Alpek S.A.B. de C.V. |
| Kaneka Corporation |
| SABIC |
| Synthos |
| TotalEnergies |
| LG Chem |
| Flint Hills Resources |
| NOVA Chemicals |
| Others |
Value Network & Pricing Analysis
Captive styrene monomer production at Antwerp-Rotterdam-Rhine-Ruhr cluster sites anchors supply position and pricing power for integrated European producers facing REACH compliance pass-through costs. This backward integration into virgin feedstock insulates margin stability against Gulf Coast petrochemical corridor volatility that immediately transmits to North American molders lacking upstream control.
Pricing Analysis
Short lead-time premiums for lambda-certified EPS boards with Environmental Product Declarations command pricing separation from spot inventory in construction procurement. Three-tier pricing structure across premium certified, standard grade, and economy resin tiers tracks thermal performance certification and volume scale. Pricing pressure stems from mineral wool substitution in high-rise commercial envelopes. Municipal buyers under EU Green Deal mandates show least price sensitivity; commodity resin purchasers in disposable goods show most.
Supply Chain Analysis
Direct-to-construction-distributor channels handle volume demand from Benelux buying groups controlling regional insulation procurement. Geographic supply concentrates in Germany, China, and the United States where integrated petrochemical corridors feed downstream molding operations. Raw material dependencies rest on styrene monomer, pentane blowing agents, and flame retardant additives. Single-source vulnerability runs through Gulf Coast petrochemical outages. Distribution runs through consolidated construction distributor networks extracting extended payment terms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The polystyrene and EPS market sits in a technology-transition phase as dissolution-based mechanical recycling replaces legacy pyrolysis depolymerization for food-contact rPS flake supply.
For Market Incumbents: To counter mineral wool substitution in fire-rated commercial envelopes, BASF SE and integrated majors should deepen backward integration into low-carbon styrene via CCUS deployment at Antwerp-Rotterdam-Rhine-Ruhr sites. Certification investment in EN 13501-1 reaction-to-fire testing acceleration compresses new product introduction timelines against stone wool competitors. For New Entrants and Emerging Players: Launch via domestic manufacturing partnerships in Maharashtra and Gujarat industrial corridors to bypass India's BIS certification gaps for imported EPS board products. Precision molding applications in Japanese electronics and automotive sectors offer penetrable white-space for high-purity bead formulations with tight expansion density control. Target quick-service restaurant chains seeking circular packaging credentials through food-contact rPS flake supply agreements. For Investors and Strategic Acquirers: Exit pathways concentrate in specialty-grade formulators with precision bead capabilities serving Taiwan and South Korean electronics contract manufacturers. Long-term viability over the analysis window favors targets with dissolution-based recycling technology partnerships and carbon capture integration at production sites. Monitor EU F-Gas Regulation enforcement intensity as inflection indicator for EPS competitiveness against polyurethane foams.| Strategic Initiative | Industry Significance |
|---|---|
| Carbon Capture Integration | CCUS deployment at Antwerp-Rotterdam-Rhine-Ruhr sites enables mass-balanced low-carbon EPS supply for Green Deal procurement frameworks. |
| Dissolution-Based Recycling Scale-Up | Mechanical purification technology opens closed-loop food-contact rPS flake demand from quick-service restaurant chains. |
| Precision Bead Formulation Investment | High-purity EPS bead production serves Japanese automotive and Taiwanese electronics contract manufacturers. |
| Domestic Manufacturing in India | Maharashtra and Gujarat capacity bypasses BIS certification delays and captures Delhi-NCR construction demand. |
| Digital Specification Platform Partnership | BIM-embedded thermal modeling tools compress architect decision cycles for envelope material selection. |
Research Methodology
Multi-period observation of EU Green Deal renovation mandates, REACH compliance cost trajectories, and styrene monomer price volatility anchored the trend analysis, supplemented by interviews with plant managers at European block-molding facilities, procurement leads at Benelux construction distributor buying groups, technical R&D directors at Japanese precision formulators, and channel partners in India's Maharashtra industrial corridor. Secondary validation drew from ECHA substance evaluation databases, Cefic chemical industry reports, SEC 10-K filings of listed petrochemical majors, and customs trade data for EPS board imports. Bottom-up volume modeling triangulated against top-down macroeconomic indicators across the analysis window.
Input-output matrices mapped styrene monomer supply through downstream conversion tiers across grade tier, end-use industry, and regional production hub dimensions. CAGRs were derived from regression analysis of historical price-volume relationships and projected specification cycle compression under tightening thermal performance codes. Industry-specific forecast inputs included EU member state renovation rate compliance trajectories and China's provincial dual carbon goal enforcement intensity.
Feedstock price spikes, regulatory timeline slippage, and substitution acceleration are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions regarding REACH compliance cost pass-through rates and mechanical recycling technology yield improvements. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
North America Fluoropolymer Market
Polymers & Resins
Vinyl Acetate Emulsion Polymers Market
Polymers & Resins
Polyelectrolyte Market
Polymers & Resins
Packaging Resins Market
Polymers & Resins
Polyurethane (PU) Foam Market
Polymers & Resins
Europe Polyamide Market
Polymers & Resins
Global UV Curable Resins Market
Polymers & Resins
North America Plastic Compounding Market
Polymers & Resins
Polybutene-1 Market
Polymers & Resins
C9 Resin Market
Polymers & Resins
Concrete Containing Polymer Market
Polymers & Resins
Hydrogenated Styrene Block Copolymers Market
Polymers & Resins
Polyphenylene Sulfide (PPS) Resin Market
Polymers & Resins
Bakelite Market
Polymers & Resins
Epoxy Resin Reactive Diluent Market
Polymers & Resins
Medical Polyoxymethylene (POM) Market